
 Hip Tendinitis Market | 2026-2036
Hip Tendinitis Market Size, Share, and Industry Trends Forecast 2026-2036
Hip Tendinitis Market Analytics
Modular treatment bundling is shifting how orthopedic practices package physical therapy sessions with pain relievers and support braces into single episode-of-care contracts. Pfizer leverages its manufacturing scale to supply nonsteroidal anti-inflammatory formulations across outpatient networks. Bayer AG anchors its position through topical analgesic lines distributed through sports medicine channels. Abbott differentiates with device-portfolio breadth spanning therapeutic devices and rehabilitation monitoring tools.
Hip tendinitis denotes inflammatory degeneration of the tendons anchoring muscles to the proximal femur and pelvic girdle, typically involving the iliopsoas, gluteus medius, or hamstring origin under repetitive mechanical loading. The condition impedes gait mechanics and athletic performance, driving clinical intervention across physical therapy, pharmacological, and surgical modalities. Medications and physical therapy dominate current care patterns, while therapeutic devices within product-type classifications are capturing expanding margin pools as home-based rehabilitation protocols gain protocol acceptance. Athletes and rehabilitation centers represent the most structurally dynamic end-user categories, with sports facilities emerging as a concentrated channel for premium-brace and device placement.
The FDA governs injectable corticosteroid formulations and therapeutic device clearances, while HIPAA mandates structure patient-data handling across rehabilitation platforms and telehealth follow-up systems. State-level scope-of-practice regulations further determine whether physical therapists in jurisdictions like Texas or Florida may administer modalities independently or require physician oversight. Stakeholders must monitor evolving reimbursement thresholds for conservative versus surgical management as payors recalibrate episode-based payment models.
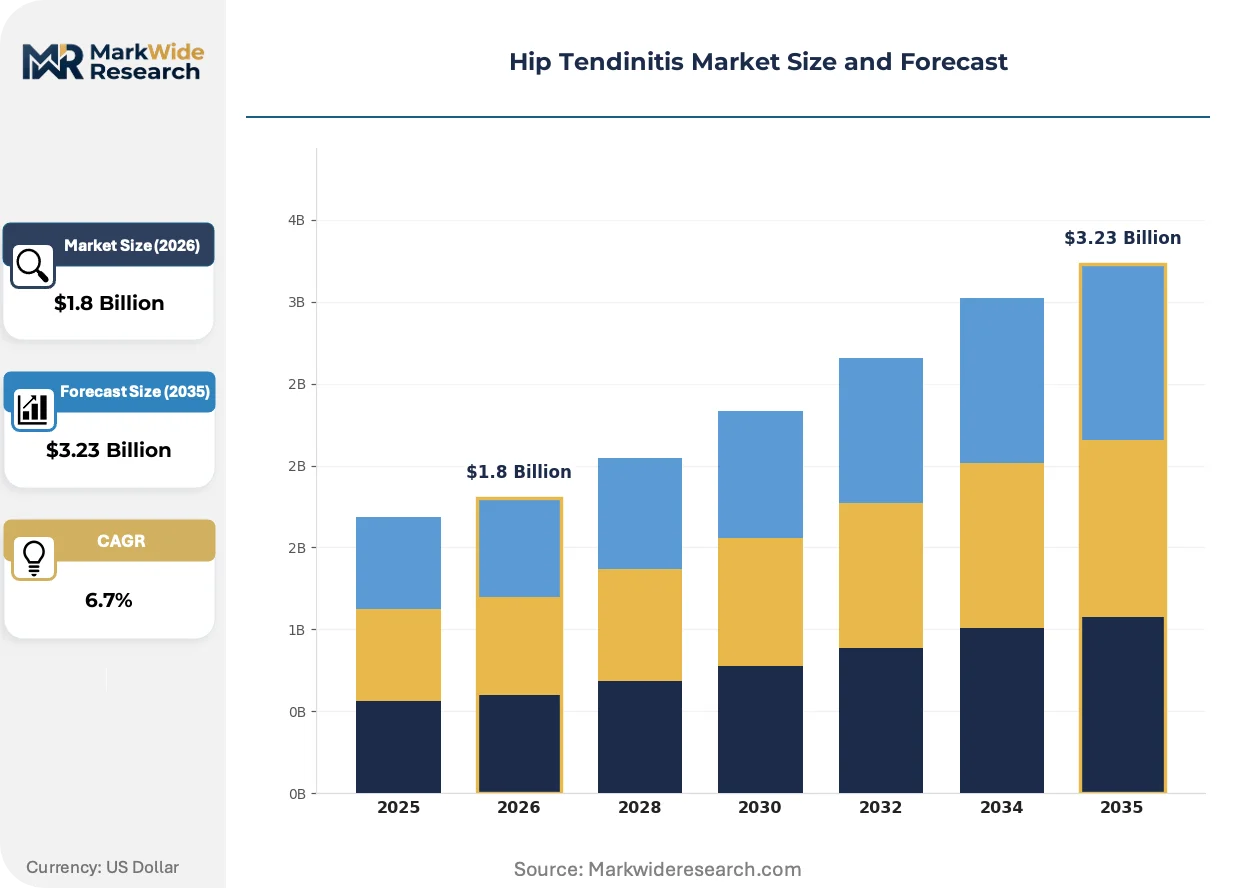
Market Dynamics
FDA's evolving corticosteroid injection guidelines are compressing reimbursement windows and forcing orthopedic practices toward bundled episode-of-care contracts that integrate physical therapy, pharmacological intervention, and home-based rehabilitation monitoring.
Growth Catalysts
- Episode-based payment mandates:CMS bundled payment pilots for musculoskeletal episodes are accelerating provider consolidation around integrated hip preservation protocols across United States metropolitan markets.
- Home rehabilitation technology:Wearable motion-tracking systems and connected resistance bands are extending therapeutic device utility beyond clinic walls into patient residences.
- Athlete population expansion:Youth sports specialization and masters-level competitive participation are elevating hip tendinitis incidence rates among active demographics seeking rapid return-to-play protocols.
Market Restraints
- Injectable corticosteroid scrutiny:FDA safety communications regarding tendon rupture risks are restricting repeat injection frequency and compressing pharmaceutical revenue per patient episode.
- Physical therapist scope limitations:State-level practice acts in Texas, Florida, and comparable jurisdictions mandate physician oversight for advanced modalities, creating access bottlenecks and cost layering.
- Conservative management ceiling:Structural tendon degeneration in refractory cases eventually exhausts non-surgical options, forcing costly surgical referral and limiting lifetime value per patient.
Strategic Opportunities
- Telehealth rehabilitation platforms:HIPAA-compliant remote monitoring systems enable asynchronous physical therapy oversight, capturing rural and suburban patient populations distant from specialized hip preservation centers.
- Biologic injection alternatives:Platelet-rich plasma and mesenchymal stem cell therapies are carving reimbursement pathways through orthopedic bundled payment carve-outs for regenerative modalities.
- Sports facility direct contracting:Professional and collegiate athletic programs are establishing preferred provider networks for expedited tendinitis management, bypassing traditional payer intermediaries.
Industry Challenges
- Interoperability fragmentation:Electronic health record systems from Epic, Cerner, and specialized orthopedic platforms resist seamless data exchange, complicating episode-of-care tracking across physical therapy, imaging, and surgical handoffs.
- Rehabilitation specialist scarcity:Certified hip preservation physical therapists concentrate in major United States urban corridors, leaving secondary markets underserved and extending patient travel burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hip Tendinitis Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Physical Therapy, Corticosteroid Injections, Surgery, Medications End User: Athletes, Elderly Patients, Fitness Enthusiasts, Rehabilitation Centers Product Type: Support Braces, Pain Relievers, Therapeutic Devices, Anti-Inflammatory Creams Care Setting: Outpatient Clinics, Hospitals, Home Care, Sports Facilities |
| Companies Covered | Boehringer Ingelheim Pharmaceuticals, Inc., Pfizer, Merck and Co., Inc., Almatica Pharma, Inc., GlaxoSmithKline plc, Bayer AG, Abbott, Teva Pharmaceuticals, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hip Tendinitis Market Evolving Landscape
Three interconnected developments are restructuring how hip tendinitis is diagnosed, managed, and reimbursed: connected rehabilitation hardware, regulatory pressure on invasive interventions, and direct-to-patient service models that compress traditional referral hierarchies.
Portable motion-capture sensors and AI-powered gait analysis applications are decentralizing functional assessment from specialized biomechanics laboratories into outpatient clinics and patient homes. Sports medicine practices in the United States are deploying these systems to quantify hip kinematics during dynamic movement, enabling objective progression criteria for return-to-sport clearance. This capability is compressing the timeline between symptom resolution and competitive reintegration while reducing reliance on expensive imaging modalities.
EMA's Medical Device Regulation and FDA's evolving Software as a Medical Device framework are tightening validation requirements for rehabilitation monitoring technologies entering European and United States markets. Manufacturers must now demonstrate clinical equivalence against predicate devices through prospective studies, extending time-to-market for innovative therapeutic hardware. European orthopedic distributors are responding by consolidating supplier relationships toward established CE-marked portfolios with robust technical documentation.
Direct-pay concierge rehabilitation models are displacing traditional insurance-reimbursed physical therapy for affluent athletic populations seeking expedited access. United States-based hip preservation centers in markets like Austin, Denver, and Scottsdale are offering cash-based packages combining diagnostic imaging, injection therapy, and supervised rehabilitation under single-practice coordination. This behavioral shift is most visible among masters athletes and recreational runners prioritizing timeline certainty over cost minimization.
Hip Tendinitis Market Segmentation
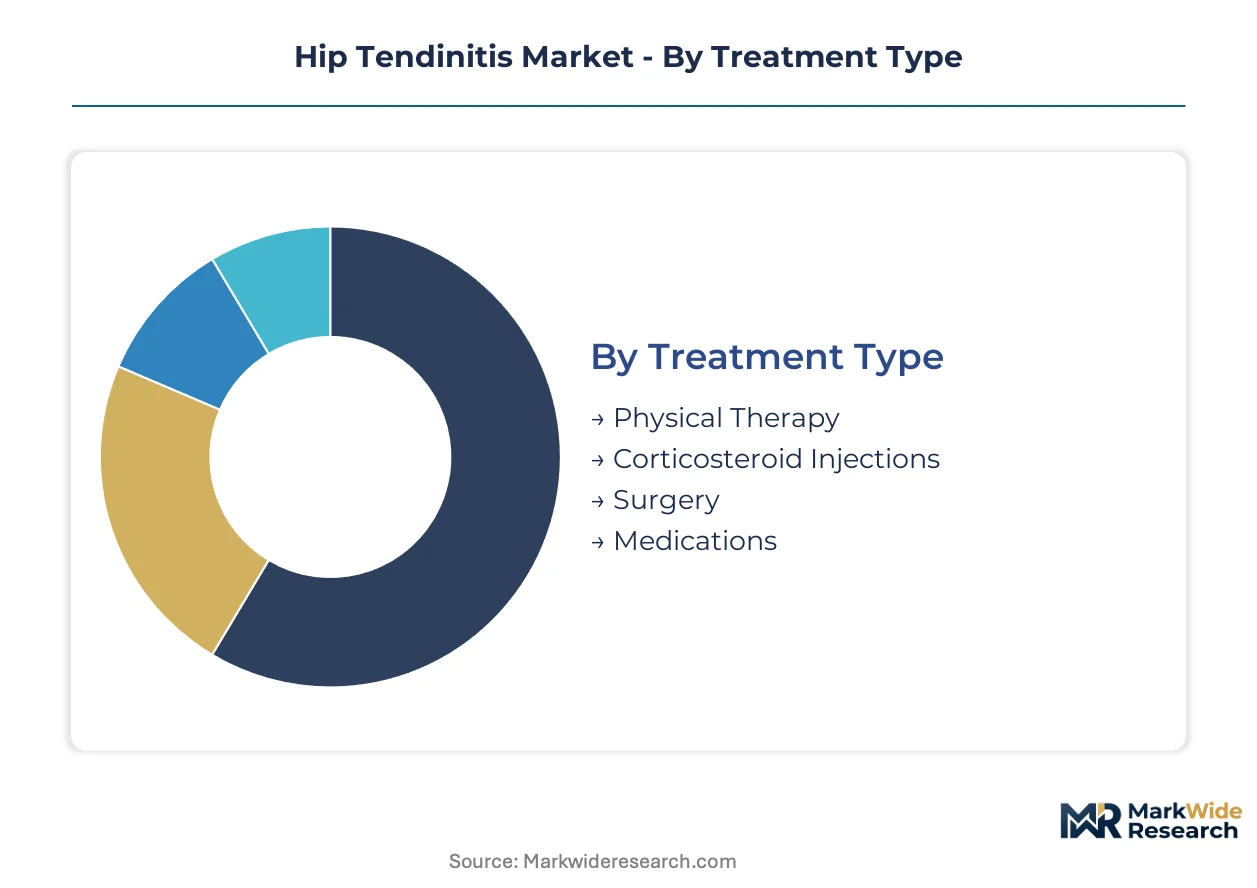
Hip tendinitis care pathways fragment across intervention intensity, patient functional demands, and care delivery location. Segmentation reveals where pharmaceutical margins concentrate versus where device and service revenues expand.
Treatment Type:
Standalone interventions dominate episodic care, while embedded combinations within bundled protocols capture longer patient relationships.
- Physical Therapy:Supervised exercise protocols targeting iliopsoas and gluteus medius tendon loading patterns. Demand clusters in United States metropolitan sports medicine corridors where CMS bundled payment pilots incentivize conservative-first pathways. Texas and Florida scope-of-practice constraints create physician-oversight bottlenecks that limit autonomous expansion.
- Corticosteroid Injections:Injectable formulations targeting peritendinous inflammation, typically triamcinolone or methylprednisolone suspensions. FDA safety communications regarding tendon rupture risks are compressing repeat injection frequency and forcing orthopedic practices toward alternative modalities. Volume placements concentrate in interventional sports medicine suites adjacent to imaging capabilities.
- Surgery:Tendon debridement, tenotomy, or repair procedures for refractory cases with structural degeneration. Reserved for patients exhausting conservative options, creating referral handoffs from physical therapy and injection protocols.
- Medications:Oral NSAIDs and topical analgesics managing symptomatic inflammation during activity modification. Widely distributed through retail pharmacy and direct-to-patient channels with minimal clinical oversight requirements.
Volume placements concentrate in Physical Therapy; the faster expansion belongs to Surgery as refractory case recognition improves.
End User:
Functional demand intensity and timeline urgency separate price-insensitive athletic populations from cost-conscious chronic management segments.
- Athletes:Competitive and recreational participants requiring rapid return-to-play protocols. Youth sports specialization and masters-level participation are elevating incidence rates among active demographics seeking expedited access. United States sports facilities and collegiate athletic programs are establishing preferred provider networks that bypass traditional payer intermediaries.
- Elderly Patients:Degenerative tendinopathy cases complicating mobility and fall risk. Medicare reimbursement thresholds for conservative versus surgical management determine access patterns across United States markets.
- Fitness Enthusiasts:Recreational runners and cross-training participants with moderate functional demands. Direct-pay concierge rehabilitation models are displacing insurance-reimbursed pathways for this segment in Austin, Denver, and Scottsdale markets.
- Rehabilitation Centers:Institutional purchasers integrating therapeutic devices and support braces into protocol-driven care. Sports medicine clinics are expanding orthopedic rehabilitation programs to serve rising athlete populations with standardized equipment procurement.
Revenue per episode peaks with Athletes; volume scale belongs to Elderly Patients as demographic aging expands the addressable pool.
Product Type:
Margin structure separates disposable consumables from durable hardware with recurring software or monitoring components.
- Support Braces:Compression and stabilization garments limiting dynamic tendon loading during activity. Sports facilities are emerging as a concentrated channel for premium-brace placement among competitive populations.
- Pain Relievers:Oral and topical analgesic formulations for symptomatic management. Bayer AG anchors distribution through sports medicine channels with topical analgesic lines requiring minimal clinical training for recommendation.
- Therapeutic Devices:Wearable motion-tracking systems, connected resistance bands, and portable stimulation units extending rehabilitation beyond clinic walls. Home-based rehabilitation protocols are gaining protocol acceptance, expanding device utility into patient residences with recurring monitoring revenue potential.
- Anti-Inflammatory Creams:Topical NSAID formulations for localized symptom control. Standardized retail distribution with limited differentiation beyond brand recognition and formulary placement.
Hardware margins concentrate in Therapeutic Devices; prescription volume leadership sits with Pain Relievers.
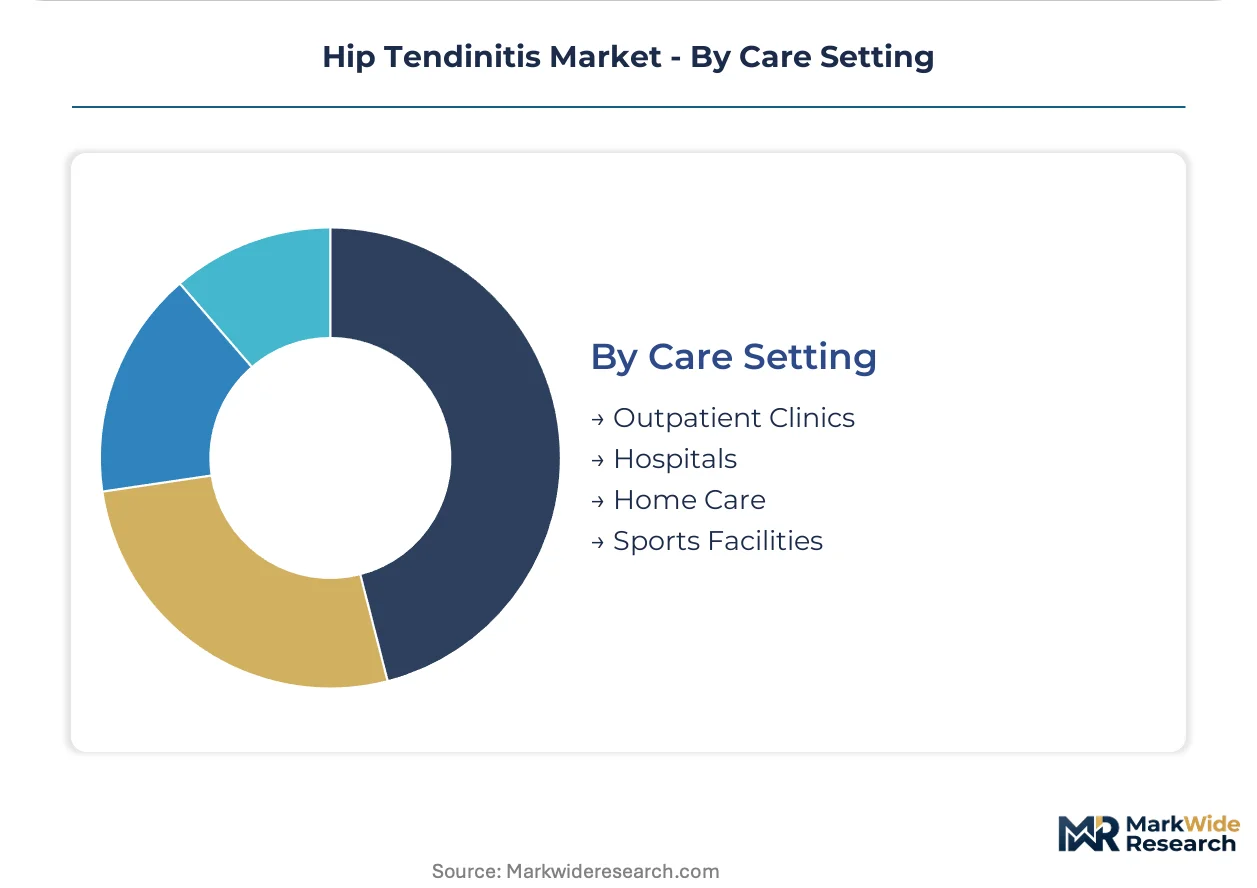
Care Setting:
Site-of-service economics and reimbursement differentials are compressing hospital-based episodes toward outpatient alternatives.
- Outpatient Clinics:Physician-supervised injection and evaluation services with adjacent physical therapy. Specialized hip preservation centers are proliferating across United States major metropolitan areas, concentrating advanced diagnostic and interventional capabilities.
- Hospitals:Surgical episodes and complex comorbid cases requiring inpatient infrastructure. Conservative management ceilings eventually force surgical referral, though bundled payment incentives are delaying this transition.
- Home Care:Remote rehabilitation monitoring and patient-directed exercise protocols. HIPAA-compliant telehealth platforms are enabling asynchronous physical therapy oversight for rural and suburban populations distant from specialized centers.
- Sports Facilities:On-site evaluation and expedited return-to-play management for affiliated athletic programs. Direct contracting relationships are bypassing traditional payer intermediaries for premium service tiers.
Episode volume concentrates in Outpatient Clinics; the steepest expansion trajectory belongs to Home Care as connected rehabilitation hardware matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones and healthcare innovation districts across the United States are concentrating hip preservation infrastructure and specialized rehabilitation capacity. These tax-advantaged development areas attract orthopedic practices, device manufacturers, and sports medicine clinics into geographic clusters that accelerate patient access and technology adoption.
United States
Specialized hip preservation centers are proliferating across Austin, Denver, and Scottsdale metropolitan markets. FDA evolving guidelines for corticosteroid injections are reshaping treatment protocols and forcing practices toward bundled episode-of-care contracts. CMS bundled payment pilots for musculoskeletal episodes are accelerating provider consolidation around integrated hip preservation protocols.
Germany
EMA Medical Device Regulation is tightening validation requirements for rehabilitation monitoring technologies entering European markets. German orthopedic distributors are consolidating supplier relationships toward established CE-marked portfolios with robust technical documentation. Munich and Berlin clusters concentrate sports medicine research institutions driving protocol innovation.
United Kingdom
NHS England musculoskeletal pathway reforms are redirecting hip tendinitis cases toward community-based physiotherapy hubs. MHRA regulatory frameworks govern therapeutic device clearances and software-as-medical-device classifications. London's Harley Street medical district anchors private-pay concierge rehabilitation models for athletic populations.
Japan
PMDA accelerated review pathways for digital therapeutics are enabling faster market entry for connected rehabilitation hardware. METI industrial policy supports domestic manufacturing of wearable motion-tracking systems. Tokyo and Osaka metropolitan corridors concentrate aging fitness enthusiasts seeking conservative management options.
Australia
TGA therapeutic goods administration structures medical device approval timelines for rehabilitation technologies entering Australian markets. Medicare reimbursement thresholds for conservative versus surgical management determine access patterns across state health systems. Sydney and Melbourne sports medicine institutes are expanding athlete-focused tendinitis programs.
Hip Tendinitis Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the hip tendinitis treatment ecosystem. Pharmaceutical manufacturers with broad analgesic portfolios face pressure from device-makers embedding software monitoring into rehabilitation hardware. Three strategic archetypes dominate: multinational drug manufacturers supplying oral NSAIDs and topical formulations, diversified medtech conglomerates spanning therapeutic devices and diagnostic tools, and emerging connected-health specialists monetizing remote patient monitoring. Competitive dynamics center on backward integration into distribution networks and strategic partnerships with sports medicine clinic chains.
Among pharmaceutical manufacturers, Pfizer leverages manufacturing scale across outpatient networks, while Bayer AG anchors distribution through sports medicine channels with topical analgesic lines. Abbott represents the diversified medtech archetype, occupying a position spanning therapeutic devices and rehabilitation monitoring tools. These three companies exemplify the strategic segmentation between drug-centric, device-centric, and integrated platform approaches reshaping competitive positioning.
| Leading Market Players |
|---|
| Boehringer Ingelheim Pharmaceuticals, Inc. |
| Pfizer |
| Merck and Co., Inc. |
| Almatica Pharma, Inc. |
| GlaxoSmithKline plc |
| Bayer AG |
| Abbott |
| Teva Pharmaceuticals |
| AstraZeneca |
| Others |
Value Network & Pricing Analysis
Raw corticosteroid APIs and medical-grade polymers flow from upstream chemical manufacturers through formulation houses and device fabricators into tiered pricing structures that separate premium-brace sports channels from economy retail pharmacy tiers. This input-cost cascade shapes margin distribution across pharmaceutical, device, and service segments.
Pricing Analysis
Margin tightening in injectable corticosteroid formulations reflects FDA safety scrutiny compressing repeat-dose frequency and per-patient revenue. Three-tier pricing structure across premium, standard, and economy levels separates concierge sports-medicine bundles from insurance-reimbursed physical therapy and over-the-counter analgesic retail. Price differentiation traces to certification grade and channel control. Cost-down pressure on therapeutic devices accelerates as home-rehabilitation hardware commoditizes. Elderly patients on Medicare demonstrate highest price sensitivity; athletes in direct-pay concierge models show lowest.
Supply Chain Analysis
Dual-sourcing requirements from United States orthopedic distributors mandate qualified backup suppliers for injectable formulations and CE-marked rehabilitation hardware. Active pharmaceutical ingredients draw from India, China, and Ireland; therapeutic device electronics source from Taiwan, South Korea, and Japan. Raw material dependencies include corticosteroid APIs, medical-grade silicones, and motion-sensor components. Single-source vulnerability concentrates in specialized hip-preservation physical therapist certification programs. Distribution runs through hospital system GPOs, sports-medicine clinic chains, and direct-to-patient e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards vertical-integration races into home-rehabilitation monitoring software and direct-contracting relationships with collegiate athletic programs.
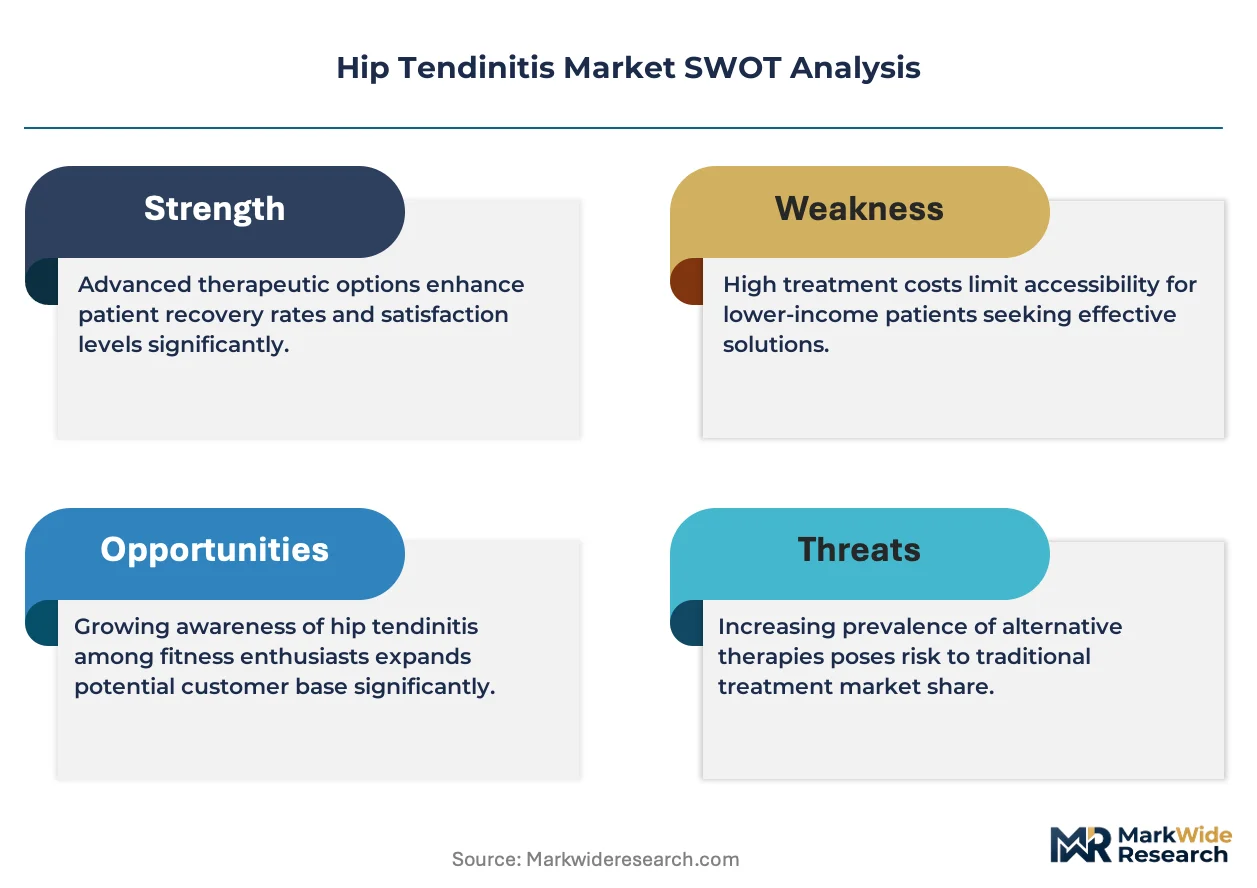
For Market Incumbents: Anticipate biologic injection alternatives displacing corticosteroid volume by securing platelet-rich plasma and stem-cell therapy supply partnerships. Consolidate position through backward integration into wearable motion-tracking hardware manufacturing. FDA evolving guidelines on tendon rupture risks threaten repeat-injection revenue streams. Channel control through sports-facility direct contracting offers defensive leverage. For New Entrants and Emerging Players: Enter via telehealth rehabilitation platforms serving rural and suburban populations distant from specialized hip preservation centers. Target fitness enthusiasts in Austin, Denver, and Scottsdale metropolitan corridors with cash-based diagnostic-imaging-plus-rehabilitation packages. Home-based connected resistance bands represent the most penetrable device segment. Go-to-market through asynchronous physical therapy oversight models bypasses state-level scope-of-practice constraints. For Investors and Strategic Acquirers: CMS bundled payment pilot expansion into additional musculoskeletal episodes is the leading indicator that episode-of-care platform consolidation will accelerate. Long-term viability favors integrated hip preservation centers combining injection, imaging, and supervised rehabilitation under single-practice coordination. Acquisition target archetype: connected-health specialists with HIPAA-compliant remote monitoring software and established orthopedic clinic partnerships. Signal to watch: state-level physical therapist scope-of-practice liberalization permitting autonomous advanced modality administration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Biologic Injection Alternative | Accelerates market entry for platelet-rich plasma therapies under orthopedic bundled payment carve-outs. |
| CE Marking Pathway for Rehabilitation Hardware | Unlocks European distribution through German orthopedic distributor consolidation toward established technical documentation portfolios. |
| Hospital System Partnership for Episode-of-Care Contracts | Captures CMS bundled payment pilot volume across United States metropolitan markets. |
| Software Companion Development for Motion-Tracking Devices | Enables recurring monitoring revenue from home-based rehabilitation protocols extending beyond clinic walls. |
| Reimbursement Strategy for Telehealth Physical Therapy | Secures asynchronous oversight payment codes for rural and suburban patient populations distant from specialized centers. |
Research Methodology
FDA filings, CMS Medicare claims data, and ClinicalTrials.gov formed the secondary backbone, cross-referenced with primary interviews involving hip preservation surgeons, sports medicine clinic operators, physical therapy practice owners, and GPO contracts managers. Bottom-up and top-down triangulation validated patient-volume estimates against pharmaceutical shipment data and therapeutic device import records.
Bottom-up modeling anchored projections in treatment-type segmentation and end-user demand intensity across the analysis window. Segmentation dimensions included intervention intensity, patient functional demands, care delivery location, and product margin structure. CAGRs derived from fitted growth curves applied to base-year estimates, incorporating FDA regulatory timeline assumptions and CMS reimbursement policy trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated biologic injection adoption or state-level physical therapist scope liberalization. Deviation in FDA corticosteroid safety communication severity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
High Frequency Vibrator Market
Others
Internet of Things Testing Market
Others
Binoculars Market
Others
Badminton Apparel Market
Others
Video Conferencing Hardware Market
Others
Space Cables Market
Others
Cat Dry Food Market
Others
Europe Flow Battery Market
Others
Eye Balm Market
Others
Europe Travel Retail Market
Others
DIY Smart Home Market
Others
Global Wireless Asset Management Market
Others
Reduced-Risk Products (Rrps) Market
Others
Global Learning Analytics Market
Others
Performance Testing Tools Market
Others
North America Printed Signage Market