
 Thermal Insulation Solution for LNG and LPG Market | 2026-2036
Thermal Insulation Solution for LNG and LPG Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Insulation Solution for LNG and LPG Market Insights
The gap between premium aerogel systems and commodity mineral wool is rebalancing as cryogenic performance thresholds split procurement tiers. Hankuk Carbon leverages its Korean manufacturing base to dominate marine LNG carrier insulation contracts. Owens Corning sustains broad fiberglass supply across storage and pipeline applications. GTT differentiates through proprietary membrane containment technology that demands ultra-low thermal conductivity specifications.
Thermal insulation solutions for LNG and LPG encompass engineered materials designed to maintain cryogenic temperatures below minus 161 degrees Celsius for natural gas and minus 42 degrees Celsius for liquefied petroleum gas, utilizing multi-layer composites with thermal conductivity ratings below 0.020 W/m·K to prevent boil-off and ensure structural integrity of containment systems. Aerogel commands the highest margin pool in cryogenic applications where space constraints and extreme thermal performance justify premium positioning. Rigid foam occupies volume leadership in pipeline insulation due to cost-efficient fabrication and established installation protocols. Fiberglass retains maturity in storage facility applications where moderate thermal loads and fire resistance requirements align with its proven performance profile.
FERC pipeline safety standards, the EU F-Gas Regulation, and South Korea's KSA shipbuilding codes collectively shape material selection, emission limits, and certification requirements for insulation systems deployed in energy infrastructure. The EU F-Gas Regulation specifically restricts high-global-warming-potential blowing agents used in polyurethane foam production, redirecting formulation investments toward hydrofluoroolefin and hydrocarbon alternatives. Stakeholders must monitor evolving IMO maritime decarbonization rules and their cascading impact on insulation weight and thermal efficiency specifications for new LNG vessel orders.
Market Dynamics
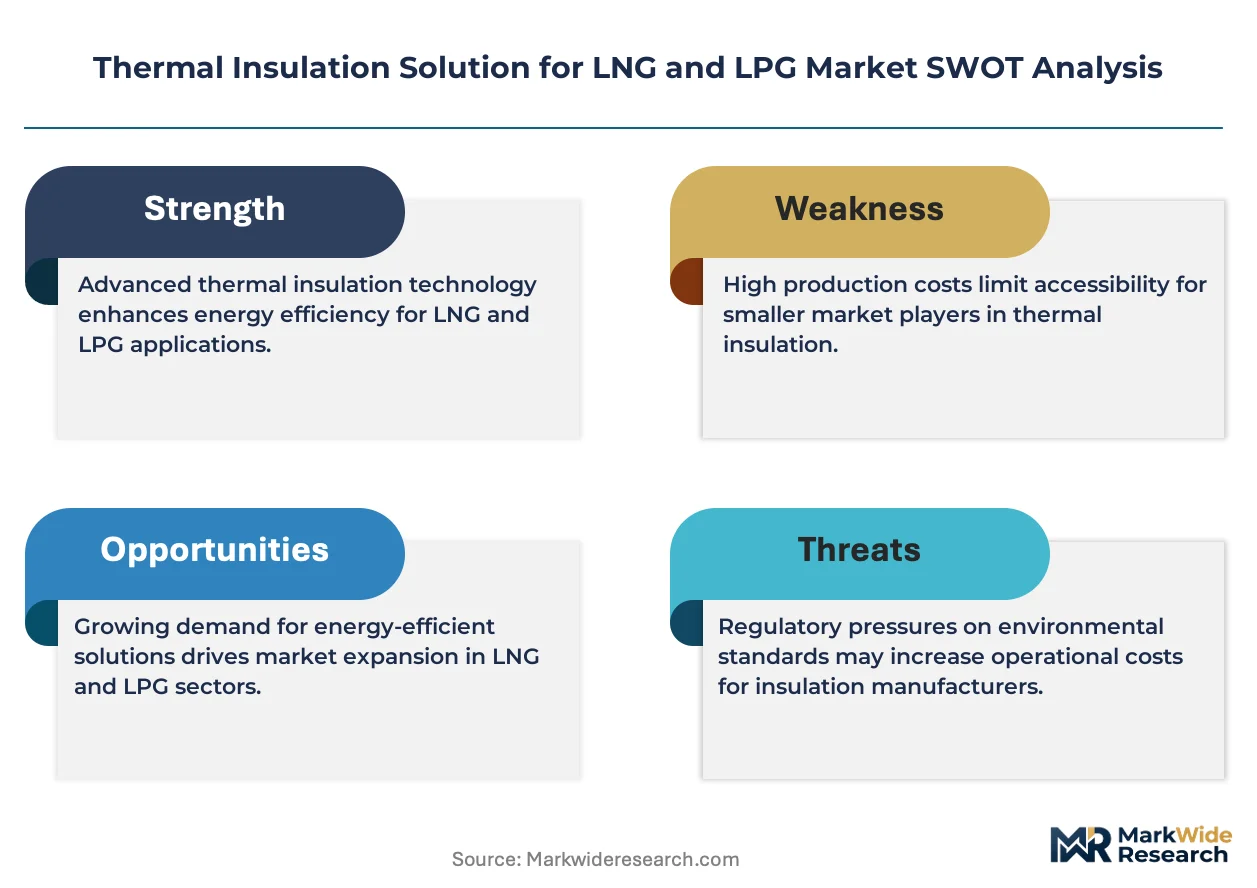
The EU F-Gas Regulation is compressing permissible thermal conductivity thresholds for polyurethane foams, forcing reformulation investments toward hydrofluoroolefin and hydrocarbon blowing agents while reshaping competitive positioning between aerogel and rigid foam suppliers.
Growth Catalysts
- Marine carrier demand:South Korean shipyards are scaling LNG vessel construction, concentrating procurement of cryogenic insulation systems for membrane containment technology.
- F-Gas Regulation:The EU framework restricts high-global-warming-potential blowing agents, redirecting polyurethane foam investments toward compliant formulations.
- IMO decarbonization rules:Maritime efficiency mandates are tightening thermal performance specifications for new LNG vessel orders, elevating specification thresholds.
Market Restraints
- Aerogel cost structure:Silica precursor volatility and complex supercritical drying requirements constrain price competitiveness against mineral wool in large-scale storage applications.
- South Korean supply concentration:Dominance of Hankuk Carbon and GTT partnerships in marine contracts creates procurement bottlenecks for non-integrated buyers.
- Fiberglass thermal limitation:Thermal conductivity above 0.030 W/m·K disqualifies traditional fiberglass from ultra-cryogenic membrane systems, restricting addressable market scope.
Strategic Opportunities
- Small-scale LNG infrastructure:Bunkering terminals and satellite storage facilities in Germany and Poland present underpenetrated demand for modular insulation systems.
- Pipeline rehabilitation:FERC safety standards are mandating thermal integrity upgrades across US interstate natural gas networks, opening replacement cycles.
- Aerogel-rigid foam hybrids:Convergence of nanoporous blankets with polyurethane substrates enables space-optimized solutions for offshore platform retrofits.
Industry Challenges
- Cryogenic installation certification:Specialized welding and vacuum-sealing competencies required for membrane containment systems face acute talent scarcity in European shipyards.
- Multi-layer integration complexity:Synchronization of primary barrier, secondary membrane, and insulation layers demands precise thermal expansion matching across temperature cycling regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Insulation Solution for LNG and LPG Market |
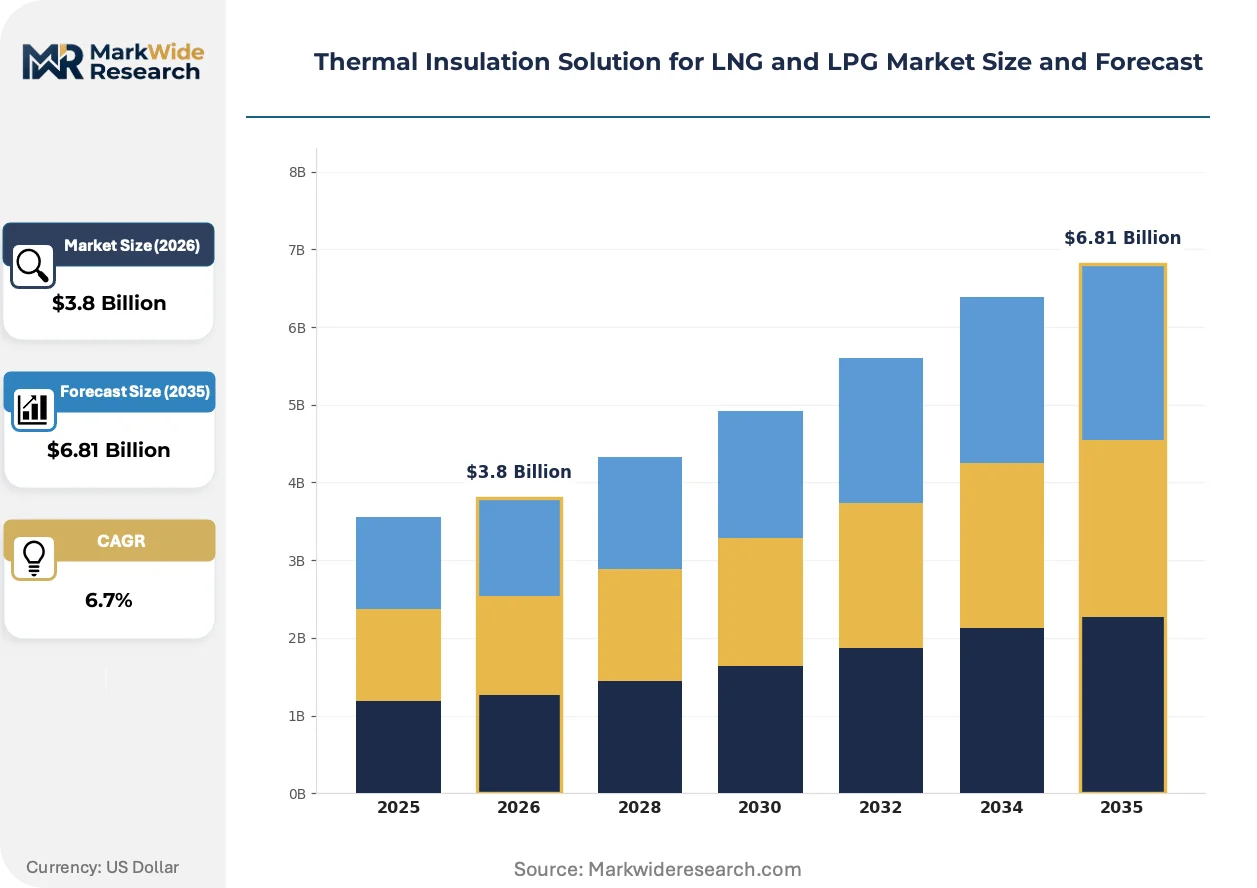
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Foam, Fiberglass, Aerogel, Mineral Wool End User: Energy Sector, Marine Industry, Storage Facilities, Transportation Companies Application: Tank Insulation, Pipeline Insulation, Equipment Insulation, Cryogenic Applications Material: Polyurethane, Polystyrene, Ceramic, Composite |
| Companies Covered | Hankuk Carbon, Dongsung FineTec, BASF, Owens Corning, GTT (Gaztransport & Technigaz), Cabot Corporation, Johns Manville, Armacell, Röchling Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Insulation Solution for LNG and LPG Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are converging to reshape formulation priorities, with performance thresholds now dictating procurement tiers rather than cost alone.
Vacuum-insulated panel technology is expanding into onshore LNG storage tanks where space constraints and boil-off reduction targets justify premium positioning. Japanese utilities and German terminal operators are piloting VIP systems for peak-shaving facilities. This expansion is compressing the addressable market for conventional multi-layer perlite systems in urban deployment scenarios.
The EU F-Gas Regulation's phasedown schedule for hydrofluorocarbons is forcing polyurethane foam producers toward hydrofluoroolefin and hydrocarbon alternatives. Reformulation costs are elevating working capital requirements for mid-tier suppliers. Marine insulation contracts are experiencing the most acute specification pressure, with South Korean yards demanding pre-certified low-GWP formulations.
Buyers are consolidating specification authority within centralized engineering teams, displacing decentralized procurement at individual terminal or vessel project levels. EPC contractors and shipyard engineering departments now dictate material selection through master service agreements. This concentration is most visible in South Korea, where Hyundai Heavy Industries and Samsung Heavy Industries have standardized approved vendor lists for cryogenic insulation.
Thermal Insulation Solution for LNG and LPG Market Segmentation
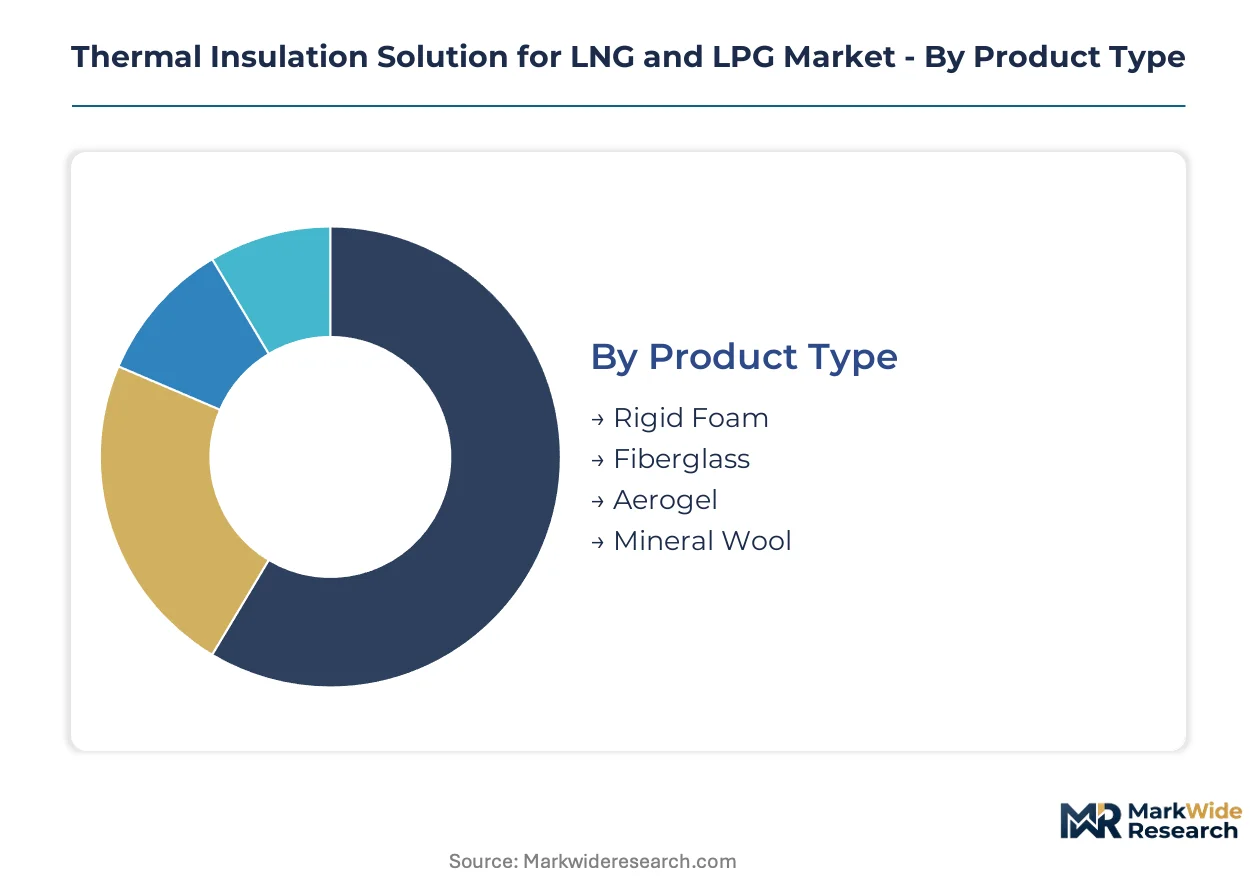
Cryogenic insulation procurement splits between standalone material supply and integrated containment systems. Specification authority concentrates in engineering departments that prioritize thermal performance thresholds over commodity sourcing.
Product Type:
Standalone insulation materials serve retrofit and maintenance demand, while composite systems dominate new-build LNG infrastructure.
- Rigid Foam:Polyurethane and polystyrene formulations deliver thermal conductivity below 0.020 W/m·K through closed-cell structures. Pipeline contractors in the US specify rigid foam for FERC-mandated rehabilitation projects where installation speed outweighs premium material costs.
- Aerogel:Silica-based nanoporous blankets achieve thermal conductivity ratings near 0.015 W/m·K with minimal thickness. Space-constrained membrane containment systems in South Korean shipyards absorb aerogel premiums to meet IMO thermal efficiency mandates.
- Fiberglass:Woven glass fiber mats provide fire resistance and moderate thermal protection for above-ground storage tanks.
- Mineral Wool:Basalt and slag-based insulation offers cost-efficient thermal management for non-cryogenic LPG storage applications.
Rigid foam leads volumes today; aerogel is gaining share fastest.
End User:
Procurement scale varies dramatically between project-based marine contracts and recurring maintenance spend at terrestrial facilities.
- Energy Sector:Upstream producers and midstream operators specify multi-layer insulation for liquefaction trains and regasification terminals. German and Polish utilities are commissioning small-scale LNG infrastructure that demands modular cryogenic systems.
- Marine Industry:Shipyards in South Korea concentrate global demand for membrane containment insulation. Hyundai Heavy Industries and Samsung Heavy Industries maintain approved vendor lists that lock out non-integrated suppliers.
- Storage Facilities:Peak-shaving terminals and satellite depots prioritize boil-off reduction through vacuum-insulated panel retrofits.
- Transportation Companies:LNG bunkering vessel operators and tanker fleets face cascading IMO decarbonization rules that elevate thermal performance specifications.
Marine Industry contracts command the highest unit values; Storage Facilities represent the most fragmented demand base.
Application:
Installation environment dictates material selection more than thermal rating alone, with accessibility and seismic loading driving specification divergence.
- Tank Insulation:Double-walled storage vessels require synchronized primary barrier, secondary membrane, and insulation layers. Japanese utilities pilot vacuum-insulated panels for urban peak-shaving tanks where space constraints justify premium positioning.
- Pipeline Insulation:Pre-insulated pipe systems with polyurethane foam cores dominate interstate natural gas networks. FERC safety standards are mandating thermal integrity upgrades that open replacement cycles across US infrastructure.
- Equipment Insulation:Compressor stations and pump skids demand flexible insulation jackets for maintenance access.
- Cryogenic Applications:Minus 161 degrees Celsius LNG and minus 42 degrees Celsius LPG containment requires ultra-low thermal conductivity specifications achievable only through aerogel or advanced foam formulations.
Pipeline Insulation generates the most recurring revenue; Cryogenic Applications carry the steepest technical barriers.
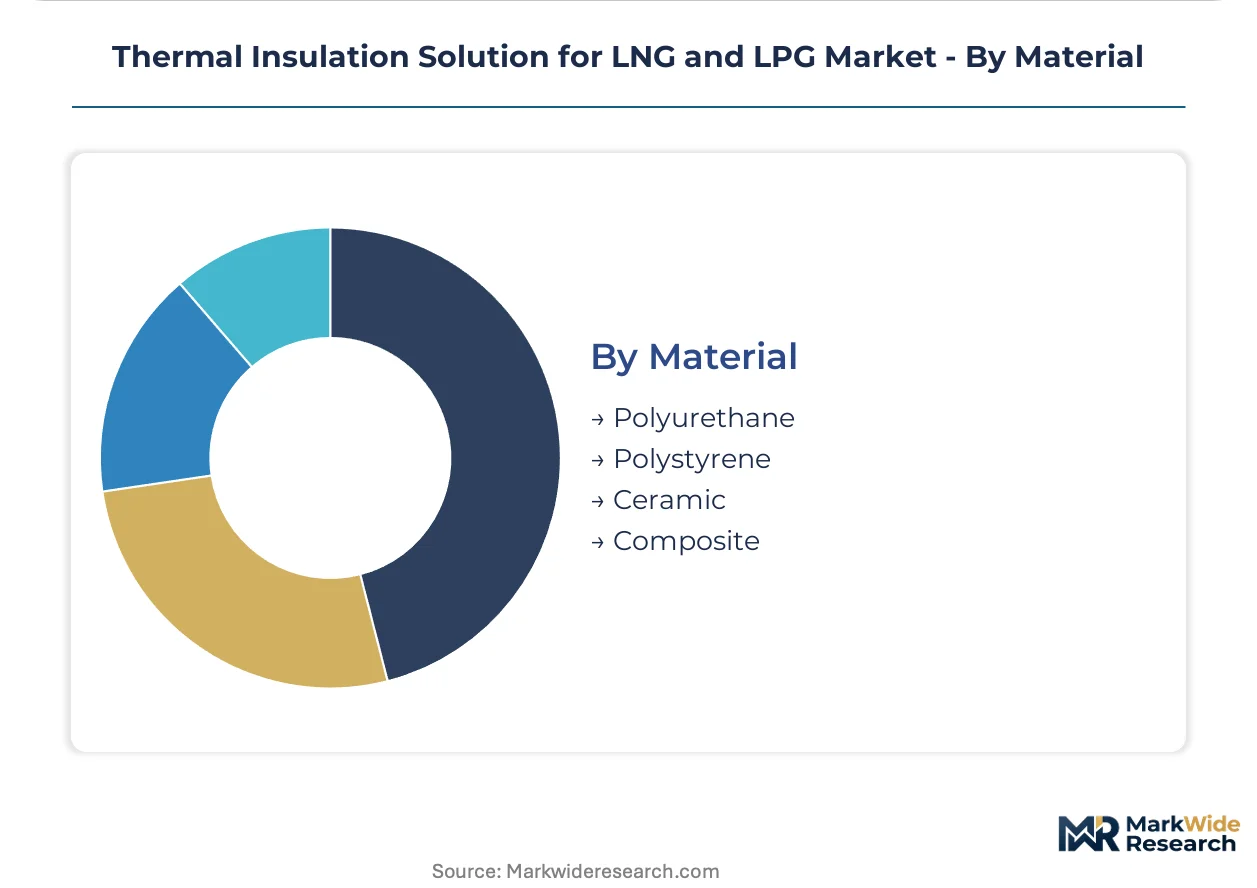
Material:
Feedstock chemistry and blowing agent selection now determine regulatory compliance as much as thermal performance.
- Polyurethane:Reformulation toward hydrofluoroolefin and hydrocarbon blowing agents is elevating working capital requirements. EU F-Gas Regulation restrictions on high-GWP agents are compressing permissible thermal conductivity thresholds and reshaping competitive positioning.
- Polystyrene:Expanded and extruded forms provide cost-efficient insulation for moderate-temperature LPG handling.
- Ceramic:Alumina-silicate fibers withstand extreme temperatures in liquefaction plant flare systems and exhaust handling.
- Composite:Multi-layer sandwiches combining nanoporous aerogel with structural substrates enable space-optimized solutions for offshore platform retrofits.
Polyurethane dominates tonnage today; Composite formulations are climbing the fastest as hybrid designs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cryogenic insulation talent clusters in South Korean shipyards and German chemical engineering hubs anchor regional production capacity for LNG containment systems.
South Korea
Marine LNG carrier construction concentrates procurement demand at Hyundai Heavy Industries and Samsung Heavy Industries shipyards. The MFDS and KSA shipbuilding codes mandate pre-certified low-GWP insulation formulations for membrane containment systems. Ulsan and Geoje host the dominant fabrication clusters where Hankuk Carbon and GTT partnerships control approved vendor lists.
United States
FERC pipeline rehabilitation mandates drive recurring demand for pre-insulated polyurethane systems across interstate natural gas networks. The EPA and FERC jointly enforce thermal integrity standards that accelerate replacement cycles in legacy infrastructure. Gulf Coast liquefaction terminals in Texas and Louisiana anchor onshore storage insulation procurement.
Germany
Small-scale LNG bunkering terminals and peak-shaving facilities in Hamburg and Wilhelmshaven create modular insulation demand. The EU F-Gas Regulation restricts high-GWP blowing agents, redirecting polyurethane investments toward hydrofluoroolefin alternatives. Industrial engineering expertise in North Rhine-Westphalia supports vacuum-insulated panel pilot programs.
Japan
Urban LNG storage constraints push Tokyo Gas and Osaka Gas toward vacuum-insulated panel retrofits for peak-shaving tanks. METI efficiency standards elevate thermal performance specifications for new terminal construction. Chubu and Kansai industrial corridors concentrate cryogenic engineering competencies.
China
State-backed LNG import terminal expansion along the Yangtze River Delta and Pearl River Delta sustains rigid foam and aerogel procurement. The MEE and GB standards enforce dual carbon compliance in insulation manufacturing. Shanghai and Ningbo shipyards are developing indigenous membrane containment capabilities.
Thermal Insulation Solution for LNG and LPG Market Competitive Landscape
Top-tier vendors anchor marine LNG carrier contracts, while mid-tier suppliers compete for pipeline and storage facility procurement. The vendor base stratifies across three functional tiers: integrated containment system providers, standalone material specialists, and regional fabrication contractors. Two dominant competitive moves are reshaping positioning: strategic partnerships between foam producers and shipyards, and backward integration into blowing agent chemistry to secure F-Gas compliance.
Within the integrated containment tier, GTT exemplifies proprietary membrane technology licensing. Among Korean material specialists, Hankuk Carbon and Dongsung FineTec occupy positions tied to shipyard engineering departments. Owens Corning and Johns Manville represent established fiberglass and mineral wool archetypes serving storage and industrial applications. BASF anchors the chemical formulation vector through polyurethane precursor supply.
| Leading Market Players |
|---|
| Hankuk Carbon |
| Dongsung FineTec |
| BASF |
| Owens Corning |
| GTT (Gaztransport & Technigaz) |
| Cabot Corporation |
| Johns Manville |
| Armacell |
| Röchling Group |
| Others |
Pricing and Supply Chain Analysis
Backward integration into blowing agent chemistry anchors supply security and pricing power for polyurethane foam producers navigating EU F-Gas Regulation compliance. Captive production of hydrofluoroolefin alternatives insulates Korean and German manufacturers from raw material volatility while supporting premium positioning in marine LNG carrier contracts.
Pricing Analysis
Bundled containment system supply commands substantial premiums over standalone insulation material sales. Three-tier pricing structure across membrane-integrated, pre-certified foam, and commodity mineral wool separates procurement tiers by certification grade and thermal performance threshold. Cost compression in rigid foam formulations is intensifying because reformulation investments toward low-GWP blowing agents elevate working capital requirements. Pipeline contractors exhibit highest price sensitivity due to standardized FERC specifications, while South Korean shipyards absorb aerogel premiums for IMO-compliant membrane systems.
Supply Chain Analysis
Workforce scarcity for cryogenic welding and vacuum-sealing competencies constrains output expansion in Ulsan and Geoje shipyard clusters. Manufacturing gravity centers on South Korea, Germany, and the United States for membrane containment systems, rigid foam precursors, and pipeline rehabilitation materials respectively. Feedstock supply draws from petrochemical complexes in the US Gulf Coast and North Rhine-Westphalia for polyurethane polyols and isocyanates. Single-source vulnerability in silica aerogel precursor supply creates concentration risk for nanoporous blanket producers. Distribution runs through EPC contractor master service agreements and shipyard-approved vendor lists rather than open market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in aerogel-rigid foam hybrid formulations where space-optimized performance justifies premium capture above commodity insulation tiers. Reformulation cost recovery through low-GWP certification premiums supports pricing power for compliant suppliers.
For Market Incumbents: Extend membrane containment technology licensing partnerships to lock out non-integrated competitors from South Korean shipyard procurement. Deepen captive supply of hydrofluoroolefin blowing agents to secure EU F-Gas Regulation compliance ahead of mid-tier suppliers facing working capital constraints. Anchor position through pre-certification investments that satisfy Hyundai Heavy Industries and Samsung Heavy Industries approved vendor requirements. For New Entrants and Emerging Players: Begin with modular insulation system supply for small-scale LNG bunkering terminals in Germany and Poland where specification authority remains fragmented across municipal utility procurement. Target pipeline rehabilitation contractors in the US interstate natural gas network where FERC-mandated thermal integrity upgrades open replacement cycles. Pursue joint development agreements with regional EPC contractors to bypass centralized shipyard vendor lists. For Investors and Strategic Acquirers: Roll-up economics work for regional fabrication contractors with cryogenic installation certifications because talent scarcity in European shipyards creates captive revenue visibility. Target mid-tier polyurethane foam producers with backward integration potential into low-GWP blowing agent chemistry. Watch for IMO maritime decarbonization rule finalization as inflection signal accelerating specification tier separation between aerogel and conventional foam systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-GWP Blowing Agents | Secures EU F-Gas Regulation compliance for polyurethane foam producers ahead of phasedown deadlines. |
| Membrane Containment Technology Licensing | GTT partnerships lock in proprietary specification authority at South Korean shipyard engineering departments. |
| Aerogel-Rigid Foam Hybrid Development | Space-optimized solutions capture premium positioning for offshore platform retrofit applications. |
| Cryogenic Installation Certification Investment | Specialized welding competencies address acute talent scarcity in European LNG vessel construction. |
| Small-Scale LNG Infrastructure Partnership | German and Polish bunkering terminals present underpenetrated demand for modular insulation systems. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to triangulate market sizing and growth trajectory estimates. Primary engagement incorporated cryogenic insulation procurement managers at South Korean shipyards, EPC contractor engineering directors, polyurethane formulation chemists, and LNG terminal project developers. Secondary validation drew from FERC pipeline safety filings, EU ECHA regulatory submissions under F-Gas Regulation, Korean KSA shipbuilding code updates, and customs trade data for insulation material flows. Bottom-up project pipeline aggregation and top-down energy infrastructure investment tracking converged on segment-level demand estimates.
Historical reference periods anchored volume and value projections across the analysis window through comparable project completion rates and contract award patterns. Segmentation modeling incorporated product type, end user industry, application environment, and material chemistry dimensions. CAGRs were derived from regression-adjusted build-out rates for LNG carrier orders, liquefaction terminal capacity additions, and pipeline rehabilitation mandates. Industry-specific inputs included IMO maritime efficiency rule adoption timelines and EU F-Gas Regulation phasedown schedules for high-GWP substances.
Several conditions sit outside the modeled scope, including unannounced regulatory acceleration, breakthrough aerogel manufacturing cost reductions, and geopolitical disruption of South Korean shipyard output. Forecasts reflect assumptions regarding continued South Korean dominance in LNG carrier construction and stable EU F-Gas Regulation enforcement trajectory. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Fluid Dispensing Systems Market
Others
Cremation Furnace Market
Others
Triathlon Clothing Market
Others
Communication Base Station Body Market
Others
Nanomedicine for Drug Delivery Market
Others
Versatile Video Coding Market
Others
Global Hydraulics Market
Others
China Packaging Primers Market
Others
Global Surface Analysis Market
Others
Global Process Equipment Market
Others
Construction Wearables Market
Others
Asia Pacific Video Conferencing Hardware Market
Others
Bimodal Identity Management Solutions Market
Others
Spain Automotive LED Lighting Market
Others
Interference Mitigation Filters Market
Others
Synthetic Leather Market