
 Spinner Flask Market | 2026-2036
Spinner Flask Market Size, Share, and Industry Trends Forecast 2026-2036
Spinner Flask Market Analytics
Buyer concentration in contract development and manufacturing organizations is restructuring procurement volumes for spinner flask suppliers. Corning leverages its materials science heritage to sustain premium positioning in glass spinner flasks across North American bioprocessing accounts. Thermo Fisher Scientific anchors global distribution through integrated laboratory supply chains, while Merck KGaA competes via life science reagent bundling with cell culture hardware.
A spinner flask is a cylindrical culture vessel with an internal magnetic or overhead-driven impeller designed to maintain suspension cells in homogeneous solution through controlled agitation, typically operating at 60 to 120 RPM with working volumes from 125 mL to 20 liters. The device serves bioprocessing laboratories by enabling scalable mammalian and insect cell propagation for monoclonal antibody and viral vector production. Glass spinner flasks retain dominance in GMP-compliant pharmaceutical workflows where autoclavability and optical clarity command margin premiums, while polycarbonate variants capture fastest expansion in academic settings prioritizing disposability and breakage resistance. Single spinner flask configurations lead research lab procurement, though multi-flask systems are gaining traction in high-throughput screening applications where parallel processing reduces manual handling.
FDA current Good Manufacturing Practice guidelines and EMA quality standards shape material validation requirements for spinner flasks entering commercial biologics workflows, with ISO 10993 biocompatibility testing increasingly mandatory for plastic-contact components. The EPA regulates disposal pathways for single-use polycarbonate vessels, adding lifecycle cost complexity to material selection decisions. Stakeholders must monitor evolving pharmacopeial extractables and leachables standards as polymer formulations proliferate.
Market Dynamics
Contract development and manufacturing organizations are consolidating procurement volumes, forcing spinner flask suppliers to restructure pricing and qualification protocols around single-use material platforms.
Growth Catalysts
- Biologics capacity expansion:Mammalian cell culture demand for monoclonal antibody production is pulling spinner flask volumes into GMP-certified manufacturing suites across the United States, Germany, and China.
- FDA quality guideline alignment:Current Good Manufacturing Practice standards are mandating autoclavable glass configurations for commercial workflows, validating premium material specifications.
- Polycarbonate formulation advances:Breakage-resistant polymer variants are capturing academic laboratory procurement previously served by reusable glass, opening volume tiers below pharmaceutical grade.
Market Restraints
- Petrochemical input volatility:Polycarbonate resin prices fluctuate with benzene and propylene feedstock markets, compressing margin stability for disposable vessel manufacturers.
- Autoclave infrastructure concentration:Glass spinner flask reuse depends on centralized sterilization capacity concentrated in legacy biopharma clusters, limiting geographic deployment flexibility.
- Extractables testing burden:ISO 10993 biocompatibility validation for polymer contact surfaces adds 12-18 month qualification timelines before commercial adoption.
Strategic Opportunities
- India bioprocessing buildout:CDSCO regulatory harmonization with ICH standards is enabling contract manufacturing investments in Hyderabad and Bengaluru, creating demand for scalable culture vessels.
- High-throughput screening convergence:Multi-flask parallel processing systems integrated with automated liquid handling are displacing manual single-vessel workflows in discovery biology.
- EU Green Deal alignment:REACH chemical safety registration for novel polymer formulations is creating first-mover advantage for vendors with validated sustainable material pathways.
Industry Challenges
- Cell culture scientist scarcity:Specialized expertise in aseptic technique and contamination control for suspension systems remains concentrated in Boston, Basel, and Singapore hubs.
- Legacy equipment integration:Magnetic drive impeller specifications vary across incumbent vessel formats, complicating fleet standardization for multi-site biopharma operators.
- Pharmacopeial certification lag:USP Class VI plastic certification timelines for new polymer grades delay product launches by 8-14 months versus glass alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spinner Flask Market |
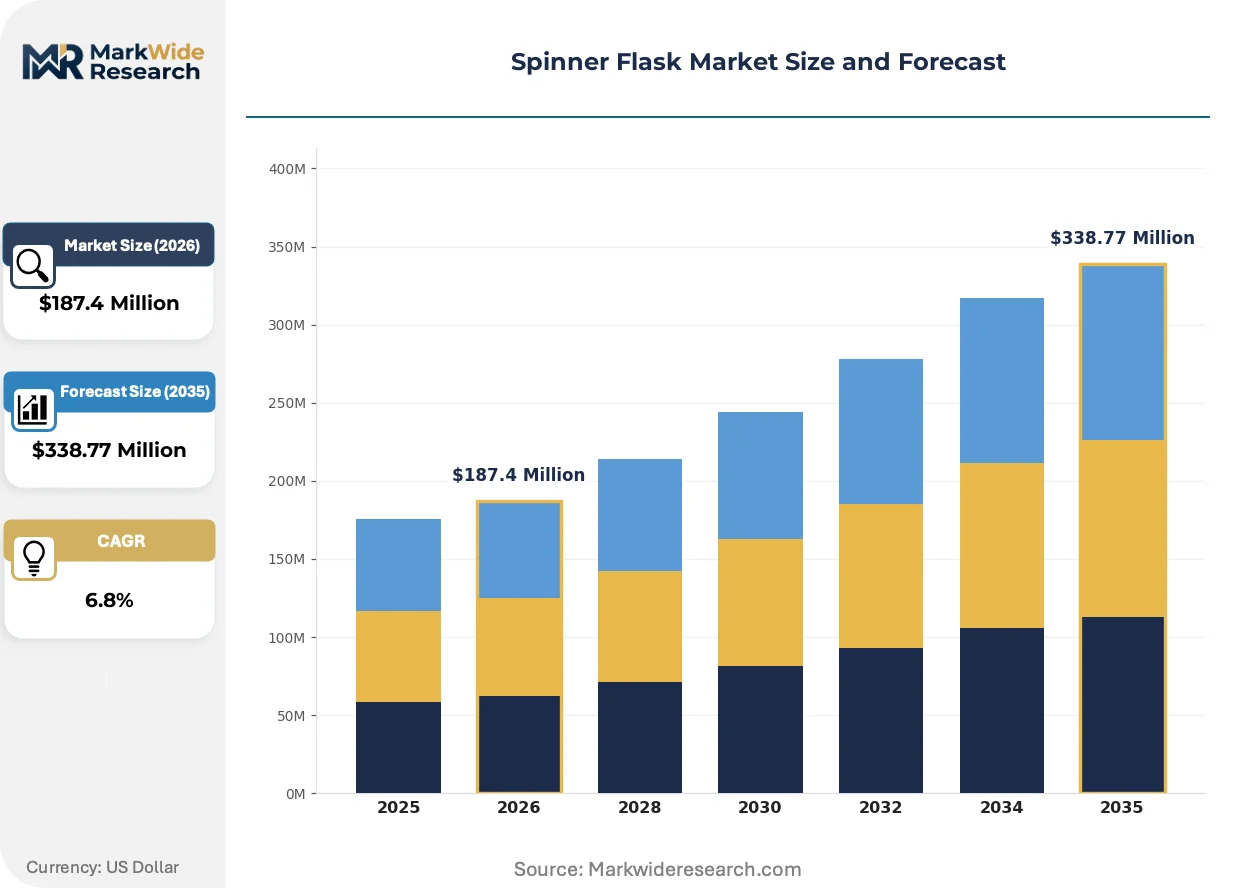
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Spinner Flask, Multi Spinner Flask, High-Density Spinner Flask, Low-Density Spinner Flask Material: Glass, Polypropylene, Polycarbonate, Stainless Steel Application: Cell Culture, Bioprocessing, Sample Mixing, Chemical Reactions End User: Pharmaceuticals, Biotechnology, Academic Institutions, Research Labs |
| Companies Covered | Corning, WHEATON, Stemcell Technologies, SCILOGEX, Bellco Glass, Chemglass Life Sciences, Thermo Fisher Scientific, Merck KGaA, Greiner Bio-One, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spinner Flask Market Evolving Landscape
Single-use technologies are fragmenting the installed base of reusable glass systems while regulatory pressure on extractables documentation intensifies material science investment.
Sensor-integrated spinner flasks with dissolved oxygen and pH monitoring capability are decentralizing process analytical technology from centralized bioreactors into small-scale development vessels. Early-phase biopharma groups in Cambridge and South San Francisco are adopting these configurations for design-of-experiment campaigns. The technology is decentralizing analytical workload from quality control laboratories into real-time vessel-level monitoring, compressing cycle times for cell line development.
EMA's revised Annex 1 guidelines on sterile manufacturing are mandating closed-system architecture for all cell culture operations, including spinner flask manipulations. This regulatory pressure is accelerating hard-shell polycarbonate vessel adoption over open-cap glass formats in European contract manufacturing. German and Swiss bioprocessing facilities are responding by retrofitting isolator-compatible impeller drive systems to maintain glass optical clarity within containment boundaries.
Academic procurement committees are unbundling spinner flask purchases from bundled reagent contracts previously dominated by full-service distributors. Direct vendor relationships are displacing laboratory supply intermediaries in university cell culture core facilities. This pattern is most visible in United States research institutions where NIH funding pressure is forcing procurement cost transparency and competitive bidding for capital equipment categories previously absorbed into consumables budgets.
Spinner Flask Market Segmentation
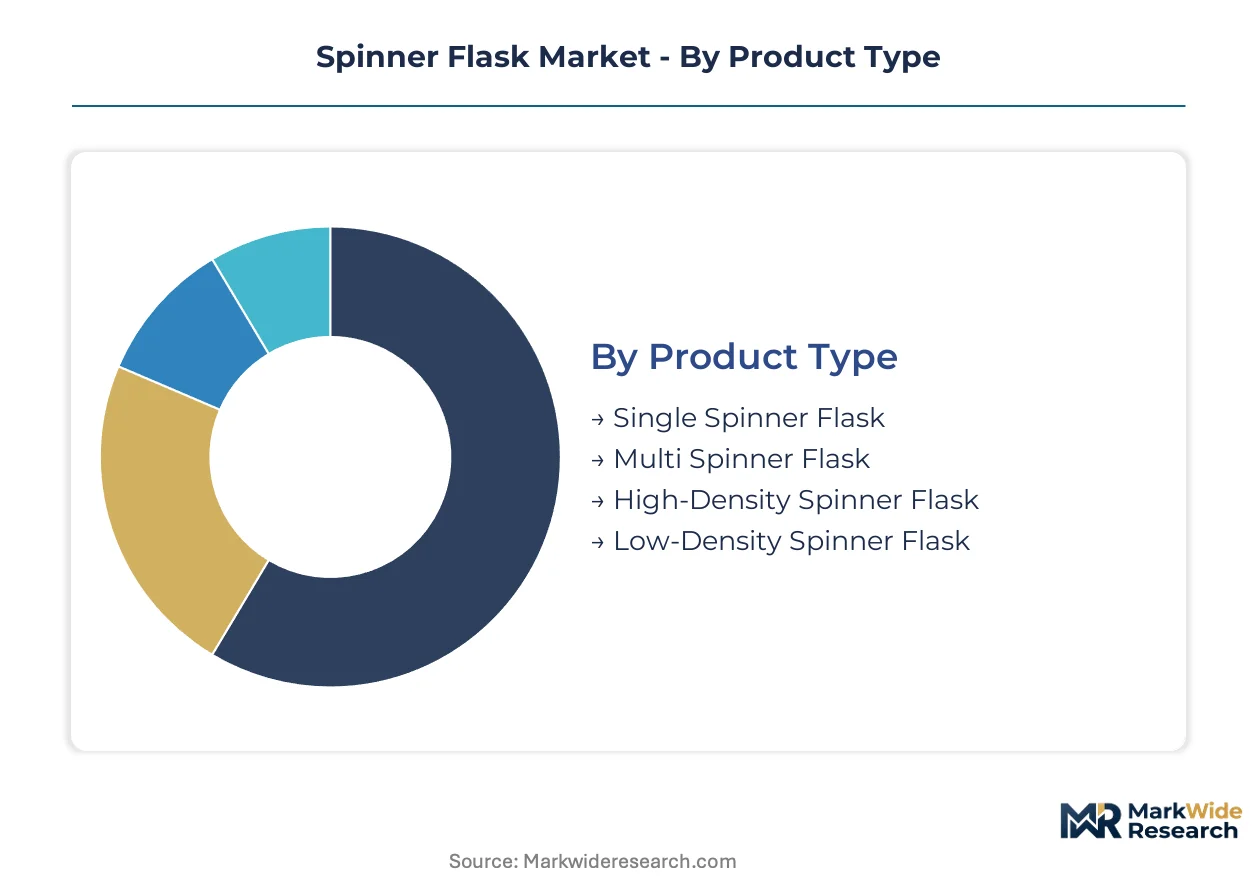
Segmentation in spinner flask procurement reveals how material science, vessel architecture, and end-use compliance requirements fragment purchasing authority across biopharma supply chains. Suppliers must navigate divergent qualification protocols between GMP-certified manufacturing and academic research environments.
Product Type:
Supply concentration in single-vessel formats dominates manufacturing procurement, while parallel processing architectures reshape research laboratory purchasing patterns.
- Single Spinner Flask:Cylindrical vessels with individual magnetic or overhead-driven impellers serve as the workhorse configuration for cell line development and seed train expansion. Demand concentrates in United States contract development organizations where FDA current Good Manufacturing Practice guidelines mandate vessel-level traceability for commercial biologics workflows.
- Multi Spinner Flask:Parallel processing systems with 4 to 12 integrated vessels enable high-throughput screening and design-of-experiment campaigns. Academic institutions in Germany and China are displacing manual single-vessel workflows as NIH and equivalent funding agencies pressure cost efficiency in discovery biology operations.
- High-Density Spinner Flask:Optimized impeller geometries and baffled architectures support cell concentrations exceeding 10 million cells per milliliter for viral vector manufacturing.
- Low-Density Spinner Flask:Standard hydrodynamic profiles suit routine subculture and master cell bank expansion with minimal shear stress.
Today's leader: Single Spinner Flask. Tomorrow's challenger: Multi Spinner Flask.
Material:
Autoclavability requirements in commercial bioprocessing sustain glass dominance, while polymer formulation advances capture volume tiers below pharmaceutical grade.
- Glass:Borosilicate constructions deliver optical clarity, thermal stability, and unlimited autoclave cycles for GMP-certified workflows. United States and German biopharma clusters specify glass for monoclonal antibody production where EMA Annex 1 sterile manufacturing guidelines mandate closed-system architecture and extractables documentation.
- Polycarbonate:Breakage-resistant polymer variants with USP Class VI certification are gaining fastest expansion in academic settings prioritizing disposability and operator safety. Chinese research institutions are adopting polycarbonate as NIH-style funding pressures force procurement cost transparency and competitive bidding.
- Polypropylene:Lower-cost thermoplastic alternatives serve non-critical mixing and buffer preparation with limited cell culture contact.
- Stainless Steel:Industrial-grade configurations support pilot-scale bioprocessing and clean-in-place operations in legacy manufacturing infrastructure.
Glass commands pharmaceutical premiums. Polycarbonate climbs fastest in research substitution.
Application:
Cell culture specificity determines material validation burden and pricing power across customer segments.
- Cell Culture:Mammalian and insect cell propagation for biologics production demands ISO 10993 biocompatibility testing and pharmacopeial extractables documentation. Contract manufacturers in Boston, Basel, and Singapore clusters drive specification intensity.
- Bioprocessing:Upstream seed train and downstream buffer operations require scalable vessel formats with validated sterilization protocols.
- Sample Mixing:General laboratory agitation applications tolerate broader material specifications and lower unit pricing.
- Chemical Reactions:Solvent compatibility and temperature resistance prioritize glass and stainless steel over polymer alternatives.
Cell culture extracts maximum margin. Sample Mixing competes on unit economics.
End User:
Purchasing authority fragments between centralized procurement in multinational biopharma and decentralized committee decisions in academic core facilities.
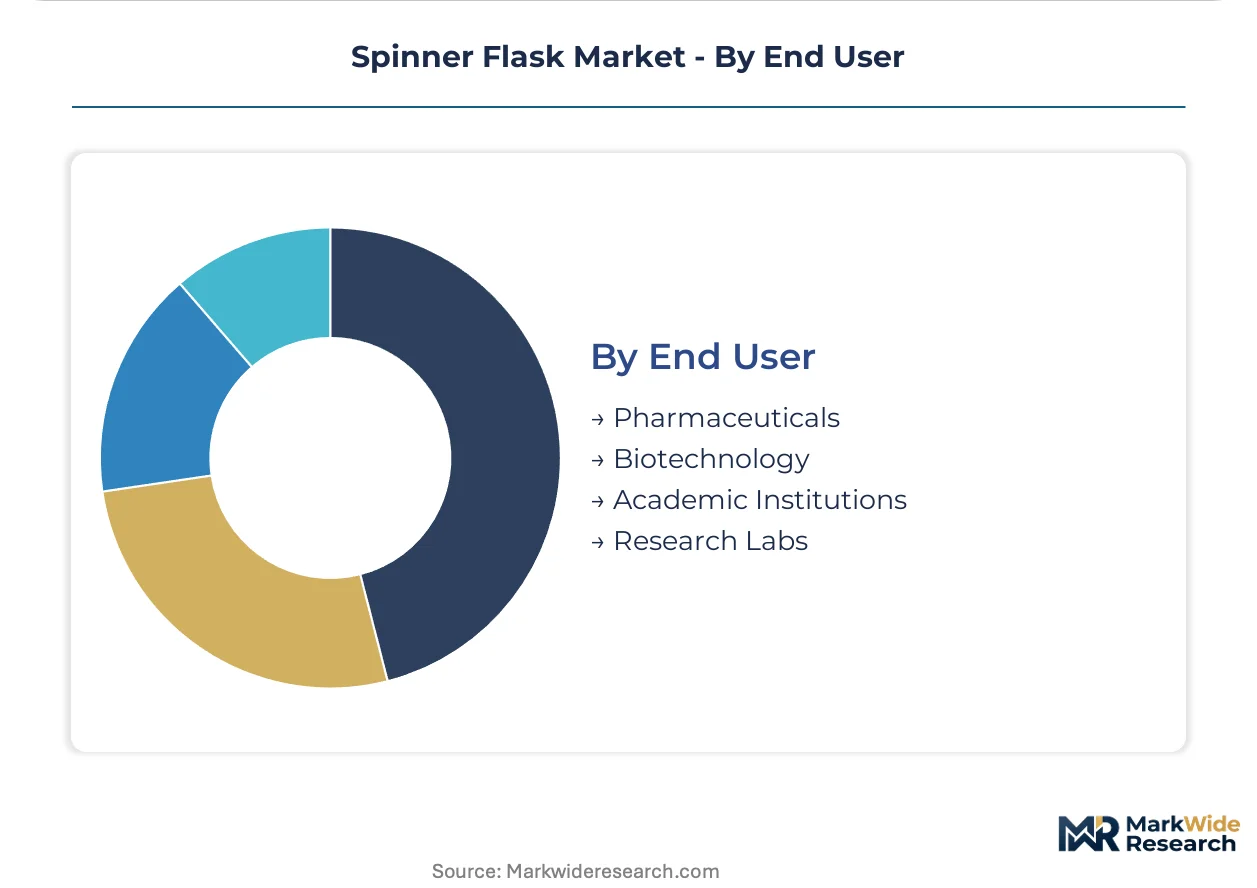
- Pharmaceuticals:Integrated biologics manufacturers specify autoclavable glass with full extractables documentation and supplier quality agreements. FDA and EMA quality guidelines mandate material validation timelines of 12 to 18 months before commercial adoption.
- Biotechnology:Venture-funded development-stage companies prioritize single-use polycarbonate for speed-to-clinic despite higher per-unit costs.
- Academic Institutions:University core facilities are unbundling spinner flask purchases from bundled reagent contracts, forcing direct vendor relationships and competitive bidding.
- Research Labs:Individual investigator grants support lower-volume procurement with price sensitivity and rapid delivery requirements.
Pharmaceuticals sustain premium positioning. Academic Institutions drive procurement restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States biopharma clusters outspend German equivalents on GMP-compliant glass vessels, while Chinese research institutions drive fastest polycarbonate volume expansion through NIH-style funding pressures.
United States
FDA current Good Manufacturing Practice guidelines mandate autoclavable glass configurations for commercial biologics workflows, sustaining premium procurement from Boston and San Francisco contract development organizations. The EPA regulates disposal pathways for single-use polycarbonate vessels, adding lifecycle cost complexity to material selection decisions. Cambridge and South San Francisco early-phase biopharma groups adopt sensor-integrated configurations for design-of-experiment campaigns.
Germany
EMA revised Annex 1 guidelines on sterile manufacturing mandate closed-system architecture for spinner flask manipulations, accelerating hard-shell polycarbonate adoption over open-cap glass formats. The EU Green Deal REACH chemical safety registration creates first-mover advantage for vendors with validated sustainable material pathways. Swiss and German bioprocessing facilities retrofit isolator-compatible impeller drive systems to maintain glass optical clarity within containment boundaries.
China
NMPA regulatory harmonization with ICH standards enables contract manufacturing investments, creating demand for scalable culture vessels across mammalian cell culture applications. The country's national pharmaceutical regulator aligns quality standards with international benchmarks for monoclonal antibody production. Beijing and Shanghai bioprocessing clusters expand GMP-certified manufacturing suites to serve domestic and export biologics markets.
India
CDSCO regulatory harmonization with ICH standards enables contract manufacturing investments in Hyderabad and Bengaluru, creating demand for scalable culture vessels. The country's national pharmaceutical regulator accelerates approval timelines for biologics manufacturing infrastructure. Hyderabad and Bengaluru CDMO clusters build out bioprocessing capacity to capture outsourced production from Western biopharma sponsors.
Switzerland
Swissmedic quality standards shape material validation requirements for spinner flasks entering commercial biologics workflows, with ISO 10993 biocompatibility testing mandatory for plastic-contact components. The country's national pharmaceutical regulator maintains stringent extractables documentation requirements for polymer formulations. Basel bioprocessing facilities concentrate specialized expertise in aseptic technique and contamination control for suspension systems.
Spinner Flask Market Competitive Landscape
United States producers anchor one tier; German and Swiss specialists hold premium positioning through materials science heritage. The vendor base structures around three tiers: integrated laboratory supply conglomerates, life science reagent bundlers, and dedicated cell culture hardware fabricators. Strategic archetypes include glass heritage specialists, single-use polymer innovators, and full-service distributors. Competitive moves concentrate on strategic partnerships for distribution reach and portfolio diversification into adjacent bioprocessing consumables.
Among United States-based fabricators, Corning and Thermo Fisher Scientific exemplify contrasting archetypes. Corning occupies a position representing glass heritage specialists leveraging materials science pedigree. Thermo Fisher Scientific anchors the integrated laboratory supply tier through global distribution infrastructure. Merck KGaA sits within the life science reagent bundling archetype, competing via hardware-reagent combination strategies. WHEATON and Bellco Glass represent dedicated cell culture hardware fabricators with focused positioning. Greiner Bio-One exemplifies European single-use polymer innovation, while Stemcell Technologies and SCILOGEX occupy research-market specialist positions. Chemglass Life Sciences represents diversified laboratory glassware fabrication with bioprocessing extension.
| Leading Market Players |
|---|
| Corning |
| WHEATON |
| Stemcell Technologies |
| SCILOGEX |
| Bellco Glass |
| Chemglass Life Sciences |
| Thermo Fisher Scientific |
| Merck KGaA |
| Greiner Bio-One |
| Others |
Value Network & Pricing Analysis
Glass-polycarbonate bifurcation between GMP-certified pharmaceutical workflows and academic research environments manifests in divergent pricing architectures and procurement channel structures. FDA autoclavability mandates sustain premium glass positioning through validated sterilization protocols, while polycarbonate commoditization in university settings channels volume through competitive bidding platforms.
Pricing Analysis
Capacity additions in Chinese polycarbonate resin production are reshaping price floors for disposable vessel tiers while glass heritage suppliers defend pharmaceutical premiums through extractables documentation. Three-tier pricing structure across premium, standard, and economy levels separates GMP-validated glass from USP Class VI polycarbonate and uncertified polymer alternatives. Cost compression in academic procurement intensifies because NIH funding transparency mandates force competitive bidding for previously bundled equipment. Biotechnology startups exhibit least price sensitivity due to speed-to-clinic priorities, while university core facilities maximize cost efficiency.
Supply Chain Analysis
Borosilicate glass supply rests on German and United States specialty ceramic producers with limited alternative sourcing for pharmaceutical-grade optical clarity. Polycarbonate resin draws from Chinese petrochemical complexes, United States Gulf Coast producers, and German chemical manufacturers. Single-source vulnerability concentrates in magnetic drive impeller assemblies sourced from Swiss precision engineering clusters. Distribution runs through integrated laboratory supply conglomerates for multinational accounts and direct vendor relationships for academic institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory ratcheting, with EMA Annex 1 sterile manufacturing revisions forcing closed-system architecture investments across European contract manufacturing.
For Market Incumbents: Deploy extractables documentation capabilities as a defensive moat against polymer innovators seeking pharmaceutical qualification. Incumbent glass specialists should deepen backward integration into borosilicate formulation to control input quality for FDA submission packages. Threat from sensor-integrated vessel startups demands accelerated R&D in real-time monitoring compatibility. For New Entrants and Emerging Players: Enter via high-throughput multi-flask configurations in German and Chinese academic markets where manual workflow displacement creates immediate procurement windows. Most penetrable segment lies in research core facilities unbundling from bundled reagent contracts. Go-to-market angle centers on competitive bidding platform partnerships with university procurement committees. For Investors and Strategic Acquirers: Consolidation pressure builds where CDSCO regulatory harmonization enables Indian contract manufacturing scale-up requiring validated vessel supply. Long-term viability frames around biologics capacity expansion durability rather than cyclical research funding. Acquisition target archetype: single-use polymer innovators with USP Class VI certification progress. Signal to watch: NMPA ICH alignment accelerating Chinese GMP-certified manufacturing suite construction.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | FDA current Good Manufacturing Practice alignment validates premium glass configurations for commercial biologics workflows. |
| Sensor Integration Partnership | Dissolved oxygen and pH monitoring capability compresses cell line development cycle times for Cambridge development groups. |
| Academic Procurement Channel Restructuring | Direct vendor relationships displace laboratory supply intermediaries under NIH funding transparency mandates. |
| Single-Use Polymer Formulation Advancement | Breakage-resistant polycarbonate variants capture fastest expansion in Chinese research institutions prioritizing disposability. |
| Isolator-Compatible Drive System Retrofit | EMA Annex 1 closed-system mandates force German and Swiss facilities to maintain glass optical clarity within containment boundaries. |
Research Methodology
Bottom-up cell culture application modeling reconciled against top-down bioprocessing capacity tracking forms the analytical core of this study. Primary interviews with bioprocess development executives, regulatory affairs leads at contract manufacturers, university core facility directors, and laboratory procurement managers combined with secondary validation from FDA filings, EMA submission databases, ISO certification registries, and pharmacopeial extractables documentation. Top-down supply-side assessment triangulated against demand-side procurement pattern analysis across pharmaceutical, biotechnology, and academic segments.
Historical trendline analysis of vessel procurement volumes and material mix shifts informed projection modeling across the analysis window. Segmentation dimensions include product architecture, material grade tier, application specificity, and end-user procurement authority structure. CAGRs were derived from regression analysis of capacity expansion announcements and funding flow patterns into biologics manufacturing infrastructure. Industry-specific forecast inputs incorporated CDSCO regulatory harmonization timelines and NMPA ICH alignment progress.
Inputs from pharmacopeial certification databases and contract manufacturing investment announcements were available through the study window; gaps in real-time academic procurement transaction data introduce uncertainty bands around research segment projections. Forecasts reflect assumptions regarding regulatory timeline adherence and biologics capacity utilization rates. A small set of triggers—EMA Annex 1 enforcement intensity, NIH funding allocation shifts, and polycarbonate resin price volatility—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
5G Tester Market
Others
Global Electronic Filters Market
Others
Europe Postal Services Market
Others
Digital Signage Media Player Market
Others
Surgical Simulation Market
Others
Cremation Furnace Market
Others
Turkey Health and Medical Insurance Market
Others
Gas Holders Market
Others
North America Enterprise Video Market
Others
Japan 3D Printing Construction Market
Others
Asia-Pacific IVD Regulatory Affairs Outsourcing Market
Others
Exosome Technologies Market
Others
Internet Protocol Television (IPTV) Market
Others
Free Space Optics (FSO) Market
Others
Asia Pacific Foodservice Paper Packaging Market
Others
Global Surface Analysis Market