
 Small Scale LNG Terminal Market | 2026-2036
Small Scale LNG Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
Small Scale LNG Terminal Market Intelligence
Buyer concentration among shipping companies and coastal industrial off-takers is expanding as vessel fleets convert from heavy fuel oil to LNG propulsion. Chart Industries leverages its cryogenic equipment specialization to anchor floating terminal deployments across Atlantic shipping lanes. Wartsila Corporation sustains technology leadership in integrated propulsion and bunkering systems for dual-fuel vessels. Shell plc dominates LNG supply contracting, using its upstream portfolio to secure long-term offtake agreements with terminal developers.
Small scale LNG terminals are engineered facilities with storage capacity below 0.5 million tonnes per annum, utilizing cryogenic containment at minus 162 degrees Celsius to maintain methane in liquid state for efficient transport and regasification. These installations serve dispersed demand nodes unreachable by pipeline infrastructure, including island power systems and remote industrial zones. Floating LNG terminals lead capital deployment where land availability is constrained or environmental permitting is restrictive, while land-based configurations retain cost advantages for permanent industrial anchor loads. Cryogenic technology commands the highest margin pool due to specialized vessel and tank fabrication requirements, whereas distribution technology faces commoditization as modular skid packages proliferate.
The International Maritime Organization enforces sulfur content limits under Annex VI, compelling shipping companies to adopt LNG-compatible bunkering infrastructure at port terminals. The EU F-Gas Regulation and national coastal zone management frameworks in Japan and South Korea shape siting approvals and emission thresholds for new terminal investments. Stakeholders must monitor regulatory divergence between IMO carbon intensity indicators and regional methane slip standards as these frameworks determine technology selection and asset obsolescence risk.
Market Dynamics
Dual-fuel vessel conversion is compressing the window for terminal developers to capture marine bunkering contracts before competitors lock up port access. Shipping operators now demand integrated LNG supply chains that tie fuel availability directly to route economics.
Growth Catalysts
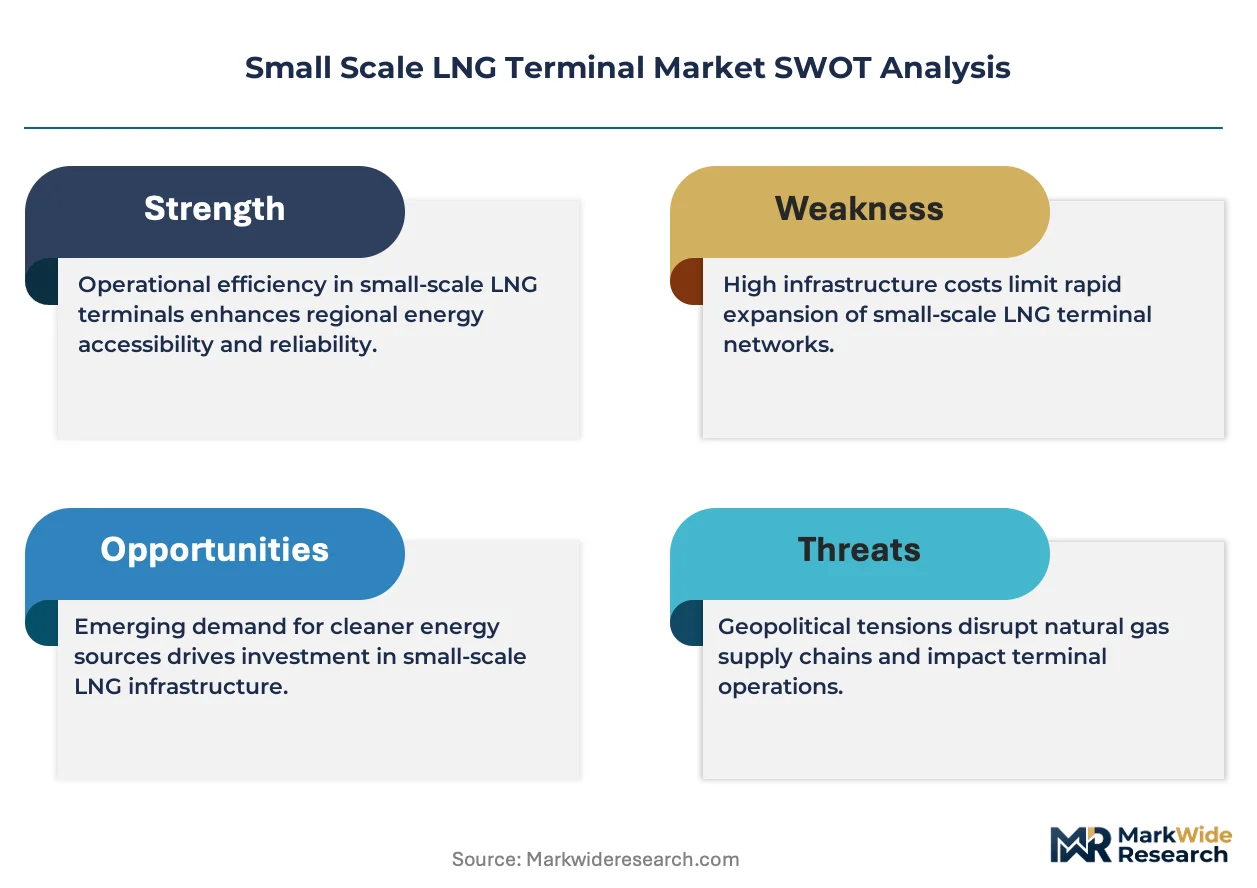
- IMO 2020 Sulfur Caps:The International Maritime Organization's Annex VI enforcement compels vessel operators to abandon heavy fuel oil, creating mandatory demand pull for LNG-compatible bunkering infrastructure at coastal terminals.
- Island Power Decarbonization:Grid operators in archipelagic jurisdictions are displacing diesel generation with LNG-to-power solutions, requiring small-scale import terminals for fuel security.
- Cryogenic Containment Advances:Vacuum-insulated tank fabrication is reducing boil-off rates below 0.1 percent daily, improving storage economics for remote industrial offtakers.
Market Restraints
- Specialized Steel Input Volatility:Nickel-alloy plate for cryogenic vessels tracks aerospace and nuclear demand cycles, creating cost unpredictability for tank fabricators.
- European Equipment Concentration:Cryogenic pump and vaporizer manufacturing clusters in Germany and France expose project timelines to single-source supply risk.
- F-Gas Regulatory Friction:The EU F-Gas Regulation's phasedown of fluorinated gases complicates insulation system selection for terminals seeking European environmental permits.
Strategic Opportunities
- Indonesian Archipelago Expansion:The national utility's 35,000 MW electrification program targets gas-fired distributed generation, creating terminal demand across Java Sea ports.
- Carbon Intensity Indicator Compliance:IMO's CII grading system rewards LNG-fueled vessels with favorable ratings, incentivizing shipping lines to contract dedicated bunkering terminals.
- Floating Storage Integration:Converting aging LNG carriers to floating storage units is enabling rapid terminal deployment without greenfield land acquisition.
Industry Challenges
- Cryogenic Welding Certification Bottlenecks:Qualified ASME Section IX welders for 9% nickel steel command premium wages, extending fabrication schedules.
- Multi-Party Interface Complexity:Terminal developers must synchronize vessel chartering, port authority permits, and offtake contracting simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Scale LNG Terminal Market |
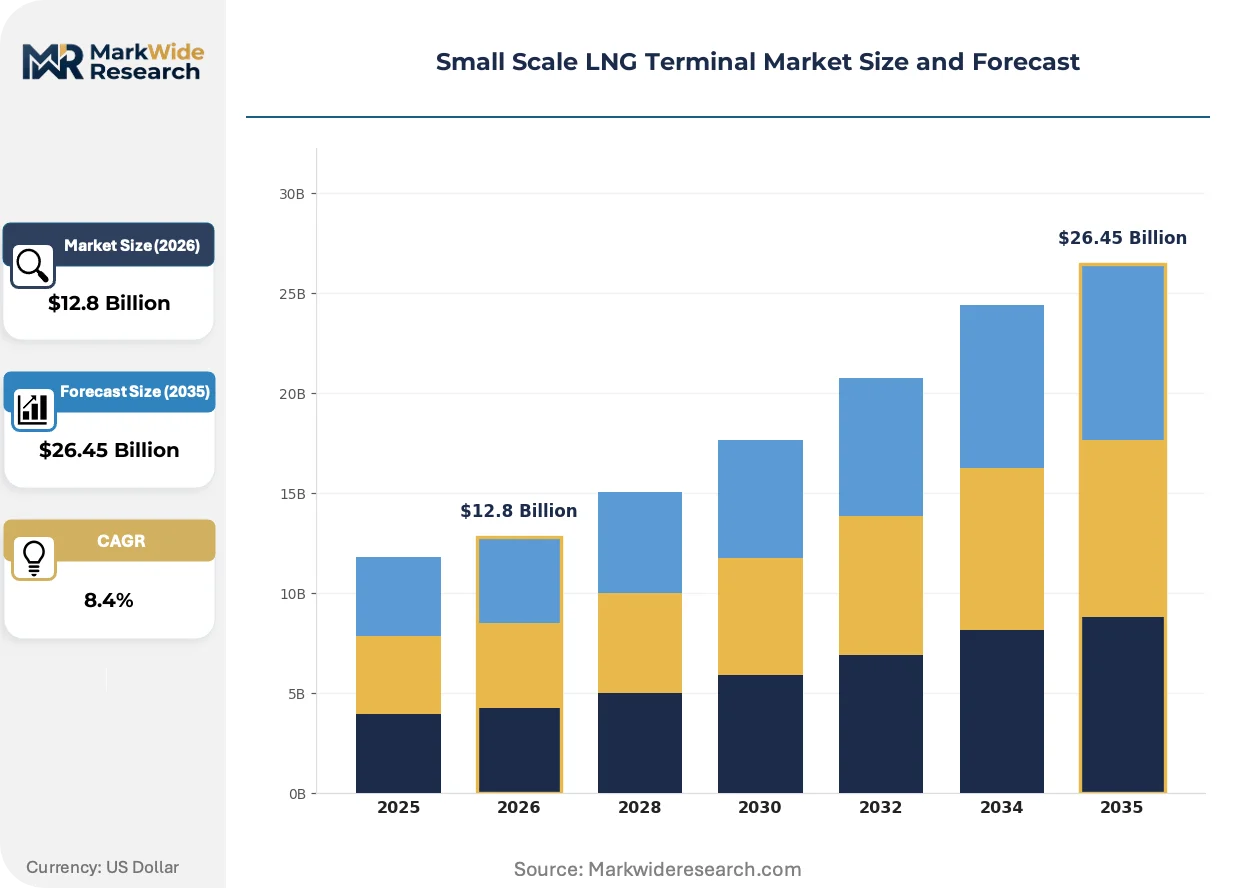
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floating LNG Terminals, Land-Based LNG Terminals, Mini LNG Terminals, Micro LNG Terminals Application: Power Generation, Industrial Usage, Transportation, Marine Applications Technology: Cryogenic Technology, Regasification Technology, Liquefaction Technology, Distribution Technology End User: Power Plants, Shipping Companies, Industrial Manufacturers, Oil & Gas Companies |
| Companies Covered | Shell plc, Chart Industries, Wartsila Corporation, Sofregaz, Gasum Oy, Linde plc, TotalEnergies, Excelerate Energy, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Scale LNG Terminal Market Strategic Shifts & Innovations
Automation of terminal operations is compressing staffing requirements while raising safety thresholds. Digital infrastructure now determines competitive positioning as much as physical storage capacity.
Integrated terminal management systems are automating custody transfer, inventory reconciliation, and berth scheduling through unified control platforms. Port operators in Rotterdam and Singapore are deploying these systems to handle simultaneous bunkering and truck loading operations. The technology is automating manual coordination tasks that previously required 24-hour control room staffing.
The EU F-Gas Regulation is tightening containment specifications for terminal insulation systems, favoring vacuum-insulated panels over polyurethane foam. Equipment suppliers must recertify product lines under revised environmental standards. Terminals in European coastal zones are responding by specifying F-gas-free alternatives in procurement tenders.
Shipping lines are consolidating fuel procurement under dedicated marine energy desks, displacing fragmented spot purchasing through vessel operators. Integrated traders like Trafigura and Vitol are capturing this volume by offering ten-year supply agreements tied to Henry Hub or TTF indexation. This concentration is most visible in the container liner segment, where CMA CGM and MSC have centralized LNG contracting authority.
Small Scale LNG Terminal Market Segmentation
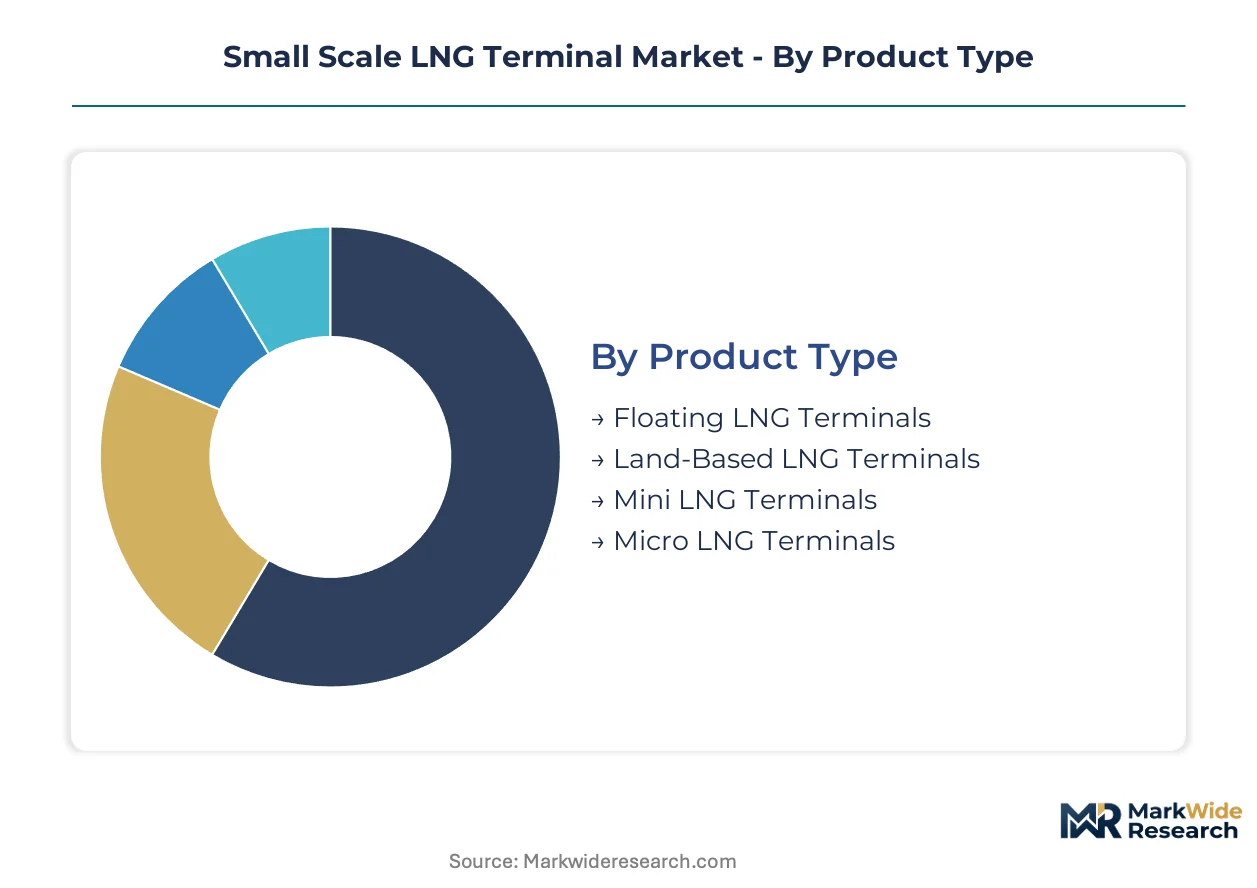
Segmentation in small scale LNG terminals reveals how capital deployment, technical complexity, and regulatory exposure vary across facility configurations. Understanding these divisions allows developers to match infrastructure investments to specific demand nodes and offtake risk profiles.
Product Type:
Floating LNG terminals command the highest upfront capital intensity due to marine-grade steel fabrication, mooring systems, and dynamic positioning equipment.
- Floating LNG Terminals:These facilities utilize converted LNG carriers or purpose-built hulls with cryogenic storage tanks, enabling deployment without land acquisition. Norwegian coastal corridors and Singapore anchorages concentrate demand as port authorities restrict greenfield construction.
- Land-Based LNG Terminals:Permanent installations with above-ground or in-ground cryogenic tanks offer lower lifecycle costs for industrial anchor loads. Japanese utilities favor these configurations for island power systems where long-term fuel security outweighs mobility requirements.
- Mini LNG Terminals:Modular designs with truck-loading capabilities serve dispersed industrial zones. South Korean port authorities are scaling these for regional manufacturing clusters.
- Micro LNG Terminals:Containerized units with sub-1,000 cubic meter capacity target remote mining camps and construction sites. Indonesian archipelago electrification programs are driving procurement.
Floating LNG terminals absorb the bulk of installed capacity; micro LNG terminals are expanding most quickly.
Application:
Application segmentation tracks how fuel delivery specifications diverge across stationary power, mobile transport, and maritime bunkering end-uses.
- Power Generation:Grid-connected facilities require continuous regasification capacity and redundancy for fuel security. Island utilities in Japan and the Philippines are displacing diesel generation with these dedicated terminals.
- Industrial Usage:Manufacturing off-takers demand scheduled delivery windows aligned with production cycles. Chemical and ceramics producers in South Korea are contracting small-scale terminals for process heat applications.
- Transportation:Truck and rail loading infrastructure enables LNG distribution to vehicle fleets. European logistics corridors are scaling these facilities under EU Green Deal transport decarbonization mandates.
- Marine Applications:Dedicated bunkering berths with simultaneous cargo and fuel operations serve dual-fuel vessel fleets. Rotterdam and Singapore port authorities are mandating these capabilities for terminal licensing.
Power generation retains the largest operational footprint; marine applications are climbing the fastest as IMO 2020 enforcement tightens.
Technology:
Technology segmentation isolates where specialized engineering commands margin premiums versus commoditized equipment procurement.
- Cryogenic Technology:Vacuum-insulated containment systems and 9% nickel steel fabrication dominate cost structures. German and French equipment suppliers concentrate manufacturing of pumps and vaporizers, creating single-source supply risk for project timelines.
- Regasification Technology:Ambient air and seawater heat exchange systems convert LNG to gaseous methane for pipeline injection. Coastal terminals in Norway favor open-rack vaporizers for their reliability in cold climates.
- Liquefaction Technology:Small-scale liquefaction units enable stranded gas monetization at production sites. North American shale plays are deploying these for regional supply integration.
- Distribution Technology:Modular skid-mounted truck loading and bunkering arms face commoditization as standardized packages proliferate. Asian fabricators are capturing volume in this segment.
Cryogenic technology absorbs the bulk of installed capacity; regasification technology is gaining share fastest as terminal utilization rates improve.
End User:
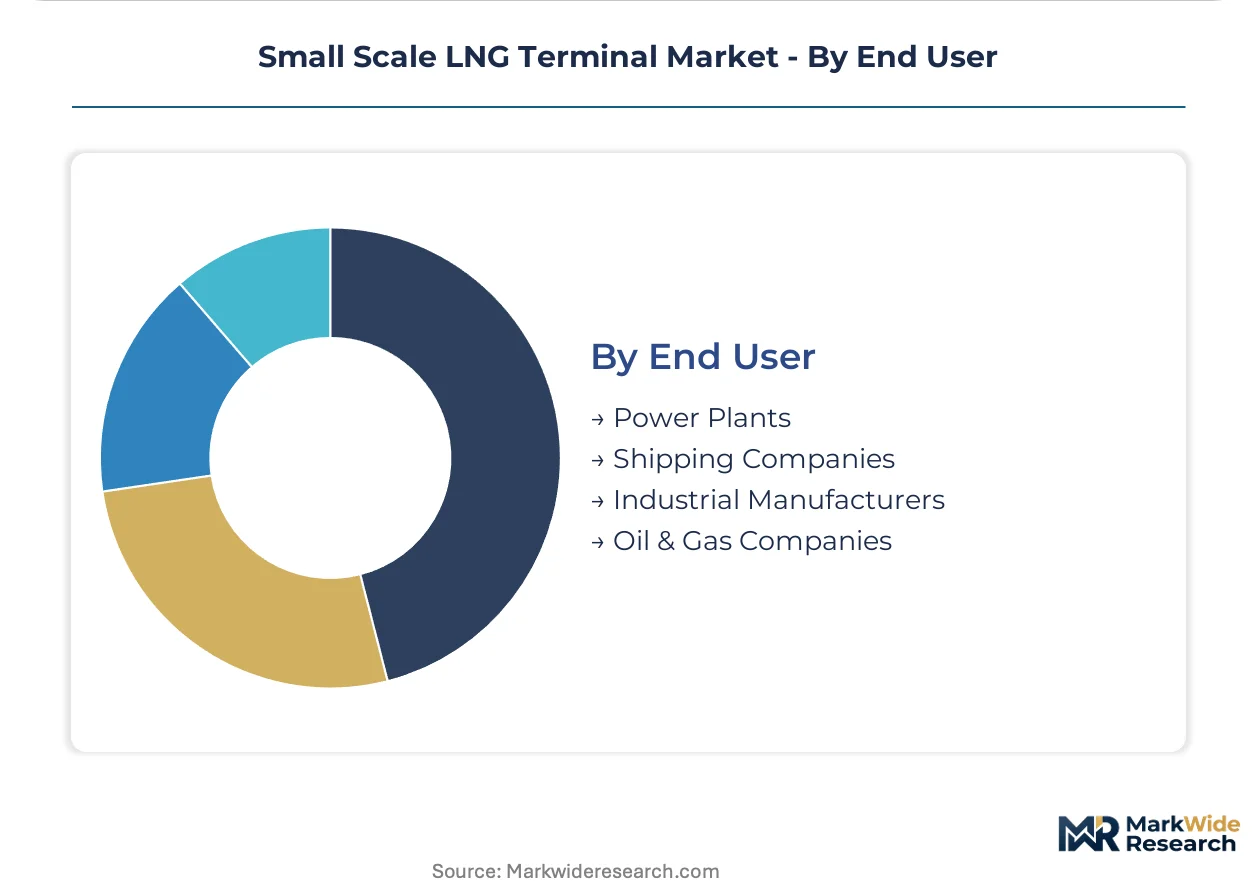
End user segmentation exposes how contracting structures and credit risk profiles differ across utility, maritime, and industrial offtakers.
- Power Plants:State-owned utilities negotiate long-term take-or-pay agreements indexed to pipeline gas benchmarks. Japanese regional utilities dominate procurement volume under national energy security frameworks.
- Shipping Companies:Container liners and tanker operators demand integrated supply chains tying bunkering availability to route economics. CMA CGM and MSC have centralized LNG contracting authority under dedicated marine energy desks.
- Industrial Manufacturers:Chemical, steel, and ceramics producers seek flexible delivery schedules aligned with production cycles. South Korean industrial parks are aggregating demand for shared terminal infrastructure.
- Oil & Gas Companies:Integrated majors use small-scale terminals for production site logistics and retail fuel networks. Shell plc secures long-term offtake agreements leveraging upstream portfolio positions.
Power plants retain the largest contracted capacity; shipping companies are expanding most quickly as dual-fuel vessel orders accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shipping operators in Norway, Japan, and South Korea are contracting small-scale LNG terminals fastest as dual-fuel vessel conversion accelerates. Port authorities across these coastal corridors are mandating bunkering infrastructure to secure maritime traffic. National energy security frameworks and sulfur emission regulations are reshaping terminal deployment priorities.
Norway
Marine bunkering demand from North Sea shipping lanes drives terminal investments along the western coast. The Norwegian Maritime Authority enforces strict emission controls under IMO Annex VI implementation guidelines. Port clusters in Bergen and Stavanger are installing simultaneous cargo-fuel operations for container liner fleets.
Japan
Island power utilities are displacing diesel generation with LNG-to-power solutions across archipelagic jurisdictions. METI coordinates national energy security frameworks that prioritize import terminal access for regional electricity providers. Terminal deployments concentrate in Kyushu and Okinawa prefectures where grid isolation necessitates dedicated fuel security infrastructure.
South Korea
Industrial manufacturers in chemical and ceramics sectors are aggregating demand for shared terminal infrastructure. The Ministry of Trade, Industry and Energy administers coastal zone permitting under national decarbonization roadmaps. Busan-Ulsan port authorities are scaling mini-terminal configurations for regional manufacturing clusters.
Singapore
The Maritime and Port Authority mandates LNG bunkering capabilities for terminal licensing in Southeast Asia's busiest transshipment hub. National regulators align port infrastructure standards with IMO carbon intensity indicator compliance requirements. Jurong Island petrochemical complexes are anchoring demand for integrated storage and regasification facilities.
Indonesia
The national utility's electrification program targets gas-fired distributed generation across Java Sea ports. PLN coordinates procurement timelines that synchronize terminal construction with grid expansion milestones. Remote mining camps and construction sites in Papua and Kalimantan are driving micro-terminal containerized unit deployment.
Small Scale LNG Terminal Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue floating storage integration and modular fabrication partnerships. The vendor base stratifies across cryogenic equipment specialists, integrated energy majors, and port infrastructure operators. Three archetypes dominate: upstream-integrated suppliers leveraging portfolio positions, technology licensors monetizing proprietary containment systems, and regional gas utilities anchoring local demand aggregation. Competitive moves concentrate on long-term offtake contracting and cryogenic welding certification capacity expansion.
Among upstream-integrated energy companies, Shell plc exemplifies the portfolio-driven archetype through supply chain control positions. Chart Industries and Wärtsilä Corporation occupy distinct specialization tiers within equipment and propulsion systems respectively. These three entities represent contrasting strategic postures: one anchored in fuel origination, another in cryogenic fabrication, and the third in marine technology integration.
| Leading Market Players |
|---|
| Shell plc |
| Chart Industries |
| Wartsila Corporation |
| Sofregaz |
| Gasum Oy |
| Linde plc |
| TotalEnergies |
| Excelerate Energy |
| Honeywell International Inc. |
| Others |
Cost & Logistics Intelligence
Shipping company fuel procurement desks concentrate demand under long-term offtake agreements, locking terminal developers into contract-based pricing indexed to Henry Hub or TTF benchmarks. This buyer consolidation shifts pricing power toward integrated energy majors with upstream portfolio positions.
Pricing Analysis
Volume concentration among container liners and state utilities splits the market between long-term contract premiums and spot-market commoditization. Cryogenic containment systems command margin premiums due to ASME Section IX certification requirements and 9% nickel steel specialization, while modular distribution skids face price erosion from Asian fabricator competition. Pricing pressure intensifies in the regasification equipment tier as standardized ambient air and seawater heat exchange systems proliferate. Industrial manufacturers in South Korean chemical parks exhibit highest price sensitivity due to production cycle alignment requirements, whereas Japanese island utilities accept premium pricing for fuel security guarantees.
Supply Chain Analysis
Regional distribution centers for cryogenic pumps and vaporizers cluster in Germany and France, creating hub-and-spoke dependency for project timelines. Germany, France, and South Korea anchor manufacturing of specialized 9% nickel steel plate and vacuum-insulated containment systems. Supply chains draw from nickel-alloy feedstocks tracking aerospace and nuclear demand cycles, specialized welding consumables for cryogenic applications, and marine-grade steel for floating hull fabrication. Single-source vulnerability concentrates in European equipment clusters where port authority permitting delays cascade through fabrication schedules. Distribution runs through EPC contractors coordinating vessel chartering, port authority interfaces, and offtake contracting simultaneously.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Terminal development economics favor consolidation as specialized welding certification bottlenecks and multi-party interface complexity force sub-scale developers toward acquisition or exit.
For Market Incumbents: Lock in cryogenic welding certification capacity expansion to capture fabrication schedule premiums before qualified ASME Section IX welder shortages worsen. Secure long-term offtake agreements with shipping company marine energy desks to anchor utilization rates against emerging floating storage competitors. Backward integration into 9% nickel steel plate sourcing mitigates aerospace demand cycle volatility threatening tank fabricator margins. For New Entrants and Emerging Players: Launch via modular micro-terminal configurations targeting Indonesian archipelago electrification programs where PLN procurement timelines synchronize with grid expansion milestones. Papua and Kalimantan remote mining camps represent the most penetrable white-space for containerized units with sub-1,000 cubic meter capacity. Partner with regional gas utilities for demand aggregation in South Korean industrial parks to bypass direct competition with integrated majors. For Investors and Strategic Acquirers: Distressed-cycle entries favor cryogenic equipment specialists with stranded fabrication capacity in Germany and France as F-Gas regulatory friction delays European environmental permits. Five-to-ten year viability hinges on IMO carbon intensity indicator compliance capabilities and methane slip technology differentiation. Watch for IMO regulatory divergence on methane slip standards as the inflection signal determining asset obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Shell plc secures ten-year offtake contracts with terminal developers leveraging upstream portfolio positions. |
| Technology Licensing | Wärtsilä Corporation monetizes integrated propulsion and bunkering system IP for dual-fuel vessel conversions. |
| Capacity Buildout | Chart Industries expands cryogenic equipment fabrication for floating terminal deployments across Atlantic shipping lanes. |
| Backward Integration | Terminal developers source 9% nickel steel plate directly to escape aerospace demand cycle cost volatility. |
| Green Certification Program | EU F-Gas Regulation compliance recertifies vacuum-insulated panels for European coastal zone procurement tenders. |
Research Approach
IMO regulatory filings, EU F-Gas Regulation documentation, and national coastal zone permitting databases formed the secondary backbone for supply-side validation. Primary interviews with EPC contractors, port authority planning officers, and shipping company marine energy desk heads combined with customs data on cryogenic equipment trade flows. Terminal developers, LNG carrier conversion specialists, and island utility procurement managers provided demand-side triangulation against bottom-up project development databases.
Bottom-up project economics modeled individual terminal configurations across floating, land-based, mini, and micro categories. Top-down energy security frameworks validated national electrification program targets in Indonesia, Japan, and South Korea. Segmentation dimensions included product type, application, technology, and end user with cryogenic welding certification capacity and F-Gas regulatory compliance status as industry-specific forecast inputs. CAGRs derived from contracted capacity pipelines and vessel fleet conversion order backlogs.
Regulatory divergence between IMO carbon intensity indicators and regional methane slip standards, nickel-alloy plate price volatility, and port authority permitting timeline extensions are the dominant revision risks. Forecasts reflect documented assumptions on vessel conversion rates and terminal utilization thresholds. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Casing Centralizer Market
Oil & Gas
North America Oil and Gas Storage Tank Market
Oil & Gas
Southeast Asia LNG Market
Oil & Gas
Open Hole Logging Services Market
Oil & Gas
Drilling Fluids Market
Oil & Gas
United States Wireline Logging Services Market
Oil & Gas
Asia-Pacific Small-Scale LNG Market
Oil & Gas
Asia-Pacific Intelligent Pigging Market
Oil & Gas
Flow Computer Oil Gas Market
Oil & Gas
Oilfield Roller Chain Market
Oil & Gas
South America Deep Water and Ultra Deep Water Exploration and Production (Eandp) Market
Oil & Gas
Downhole Motor Market
Oil & Gas
Subsea Flowlines Market
Oil & Gas
Oil and Gas Gasket Market
Oil & Gas
Asia-Pacific Well Intervention Market
Oil & Gas
Global Hydrate Inhibitors Market