
 Nigeria Oil and Gas Upstream Market | 2026-2036
Nigeria Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Oil and Gas Upstream Market Foresight
The gap between deepwater premium barrels and onshore marginal field output is shifting as capital allocation diverges sharply. TotalEnergies SE anchors its position through integrated offshore development and FPSO deployment in Nigerian waters. Seplat Energy competes aggressively in the onshore Niger Delta, leveraging its domestic operational footprint and gas monetization infrastructure. Shell PLC navigates portfolio restructuring while sustaining legacy production from its shallow-water and onshore assets.
Nigeria oil and gas upstream encompasses the exploration, drilling, and production of crude oil and natural gas from subsurface reservoirs, typically targeting formations at depths from 1,500 to over 3,000 meters with API gravities ranging from light sweet to heavy sour crude. The sector feeds domestic refineries, export terminals, and LNG liquefaction trains that supply Atlantic basin markets. Exploration and Drilling services command disproportionate capital commitment as operators target pre-salt and deepwater frontiers, while Production-phase investment dominates revenue recognition timelines for service contractors. Enhanced Oil Recovery technology attracts growing engineering spend as mature onshore fields face natural decline rates exceeding five percent annually.
The Nigerian Petroleum Industry Act and the Petroleum Industry Act fiscal framework reshape cost recovery allowances and royalty structures for new acreage awards. DPR, now NUPRC, enforces technical standards for well integrity and environmental management, while NNPC exercises participating rights and back-in provisions across joint ventures. Stakeholders must track regulatory implementation timelines and local content enforcement to calibrate capital deployment and partnership structures.
Market Dynamics
The Nigerian Petroleum Industry Act is restructuring fiscal terms and licensing frameworks, forcing operators to recalibrate joint venture economics and cost recovery structures across deepwater and onshore blocks.
Growth Catalysts
- Domestic Refinery Expansion:Dangote Refinery and rehabilitated state facilities are absorbing more crude domestically, reducing export dependency and stabilizing offtake volumes for upstream producers.
- Petroleum Industry Act Fiscal Framework:The reformed royalty structure and cost recovery allowances for new acreage awards are improving project economics for frontier exploration.
- Gas Monetization Infrastructure:LNG liquefaction trains and domestic gas-to-power networks are creating dual-revenue streams from associated gas that previously flared.
Market Restraints
- Joint Venture Funding Gaps:NNPC's cash-call arrears and constrained government budgets delay drilling programs and maintenance schedules in traditional onshore assets.
- Deepwater Capital Intensity:Pre-salt and ultra-deepwater projects require $3-5 billion per development, limiting participation to majors with balance sheet capacity.
- Security Infrastructure Costs:Pipeline surveillance, maritime security, and community engagement add 15-25% to operating expenditures in the Niger Delta corridor.
Strategic Opportunities
- Marginal Field Revitalization:Indigenous operators with lower cost structures can acquire and redevelop abandoned or underperforming onshore blocks through NUPRC licensing rounds.
- Domestic Gas-to-Industry Mandates:Federal power sector and fertilizer plant feedstock requirements are creating captive demand for non-associated gas development.
- FPSO Leasing Models:Contractor-operated floating production systems reduce upfront capex exposure and accelerate time-to-first-oil for mid-sized discoveries.
Industry Challenges
- Well Integrity Engineering Shortage:Aging well stock and limited domestic technical capacity for subsea interventions create operational bottlenecks and production deferments.
- Legacy Asset Abandonment Liabilities:Decommissioning cost estimates for decades-old platforms and pipelines exceed $15 billion, with unclear funding mechanisms and regulatory timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Oil and Gas Upstream Market |
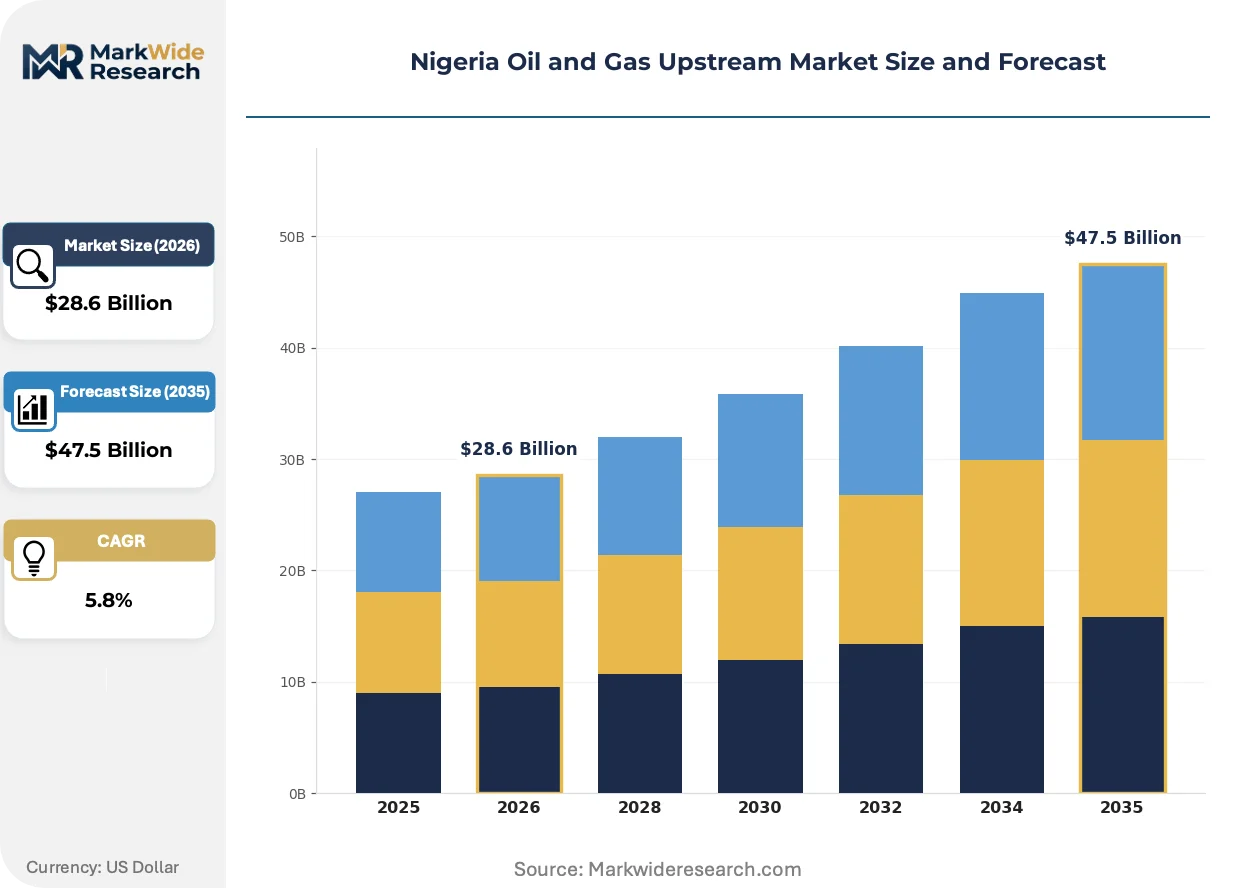
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exploration, Drilling, Production, Well Services Technology: Seismic Imaging, Enhanced Oil Recovery, Fracking, Offshore Platforms End User: Independent Producers, National Oil Companies, International Oil Companies, Service Providers Investment Stage: Pre-Funding, Exploration Phase, Development Stage, Production Phase |
| Companies Covered | TotalEnergies SE, Seplat Energy, Royal Dutch Shell PLC, Heirs Energies, Nigerian National Petroleum Development Company, Chevron Corporation, Nigerian National Petroleum Corporation, Aradel Holdings, ExxonMobil Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Oil and Gas Upstream Market Shifts & Advancements
Digital subsurface characterization and remote operations are compressing exploration timelines while Nigerian regulatory enforcement tightens environmental and local content compliance.
Subsea multiphase pumping and wet gas compression systems are automating flow assurance from deepwater wells to FPSO facilities. International operators with Nigerian deepwater portfolios are deploying these systems to maintain plateau production rates without platform shutdowns. The technology is automating intervention schedules and reducing dependency on costly workover vessels.
The Nigerian Upstream Petroleum Regulatory Commission now mandates environmental management plans and community development agreements for all new block awards. Operators must demonstrate spill response capability and local content percentages before drilling permits issue. Deepwater license holders are responding by front-loading social investment and Nigerian supplier contracts to secure regulatory clearance.
Integrated service contracts are replacing discrete procurement of seismic, drilling, and production services. National oil companies and independents are bundling exploration through abandonment under single contractor accountability. This consolidation is most visible in offshore Lagos and Bayelsa state developments where operators seek to transfer reservoir risk and cost overrun exposure.
Nigeria Oil and Gas Upstream Market Segmentation
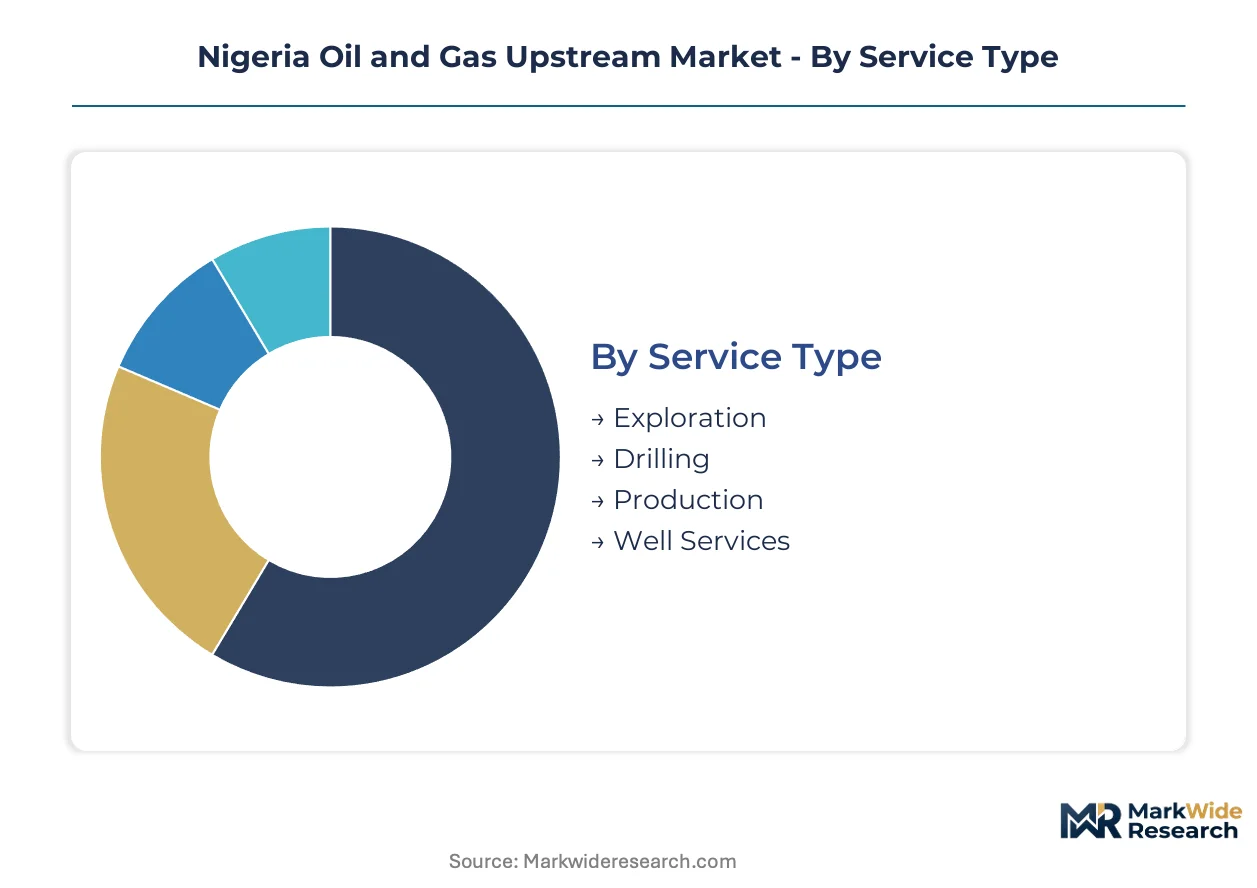
Segmentation in Nigeria's upstream market reveals how capital flows across distinct technical and commercial boundaries. Each category carries specific regulatory burdens from NUPRC that shape operator strategies and contractor selection criteria.
Service Type:
NUPRC mandates distinct technical certifications for each service tier, with exploration permits requiring environmental management plan approval before seismic operations commence.
- Exploration:Geophysical survey and subsurface characterization services targeting pre-salt and deepwater frontiers. Demand concentrates in offshore Lagos and Bayelsa blocks where TotalEnergies SE and Shell PLC deploy 3D seismic campaigns to de-risk billion-barrel prospects. NUPRC's licensing rounds tie exploration rights to minimum work program commitments.
- Drilling:Well construction, directional drilling, and completion services spanning jack-up rigs to sixth-generation drillships. The Niger Delta onshore corridor absorbs the highest rig-day volumes as indigenous operators accelerate marginal field development. DPR-to-NUPRC regulatory transition has tightened blowout preventer certification and well control training requirements.
- Production:Field development and hydrocarbon extraction operations including artificial lift and surface facility management.
- Well Services:Intervention, workover, and maintenance operations sustaining output from aging well stock.
Drilling sits at the top of the volume ranking, with Exploration climbing the fastest.
Technology:
Technology selection tracks reservoir depth and fluid characteristics, with cost tiers separating proven onshore methods from capital-intensive offshore systems.
- Seismic Imaging:2D, 3D, and 4D seismic acquisition plus advanced processing algorithms illuminating subsurface structures. Deepwater license holders in Nigerian waters prioritize wide-azimuth surveys to resolve complex salt geometries beneath the continental slope.
- Enhanced Oil Recovery:Thermal, chemical, and gas injection methods boosting recovery factors beyond primary depletion. Mature Niger Delta fields drive adoption as natural decline rates exceed five percent annually and operators face reserve replacement pressure.
- Fracking:Hydraulic fracturing for tight sandstone reservoirs and unconventional resource assessment.
- Offshore Platforms:Fixed jackets, compliant towers, and floating production systems for deepwater development.
Seismic Imaging commands the largest installed base, with Enhanced Oil Recovery expanding most quickly.
End User:
End user categories reflect capital access and risk tolerance, determining contract structures from cost-plus joint ventures to integrated service agreements.
- International Oil Companies:Majors with balance sheet capacity for multi-billion dollar deepwater developments. TotalEnergies SE anchors this segment through integrated offshore projects and FPSO deployment in Nigerian waters, leveraging technical expertise and portfolio diversification.
- National Oil Companies:NNPC and its joint venture partners exercising participating rights across concession blocks. Cash-call arrears and constrained government budgets delay drilling programs despite statutory production targets.
- Independent Producers:Indigenous operators and mid-caps targeting marginal fields and onshore redevelopment.
- Service Providers:Schlumberger, Halliburton, and local contractors delivering specialized technical services.
International Oil Companies dominate capital deployment, with Independent Producers gaining share fastest through marginal field licensing rounds.
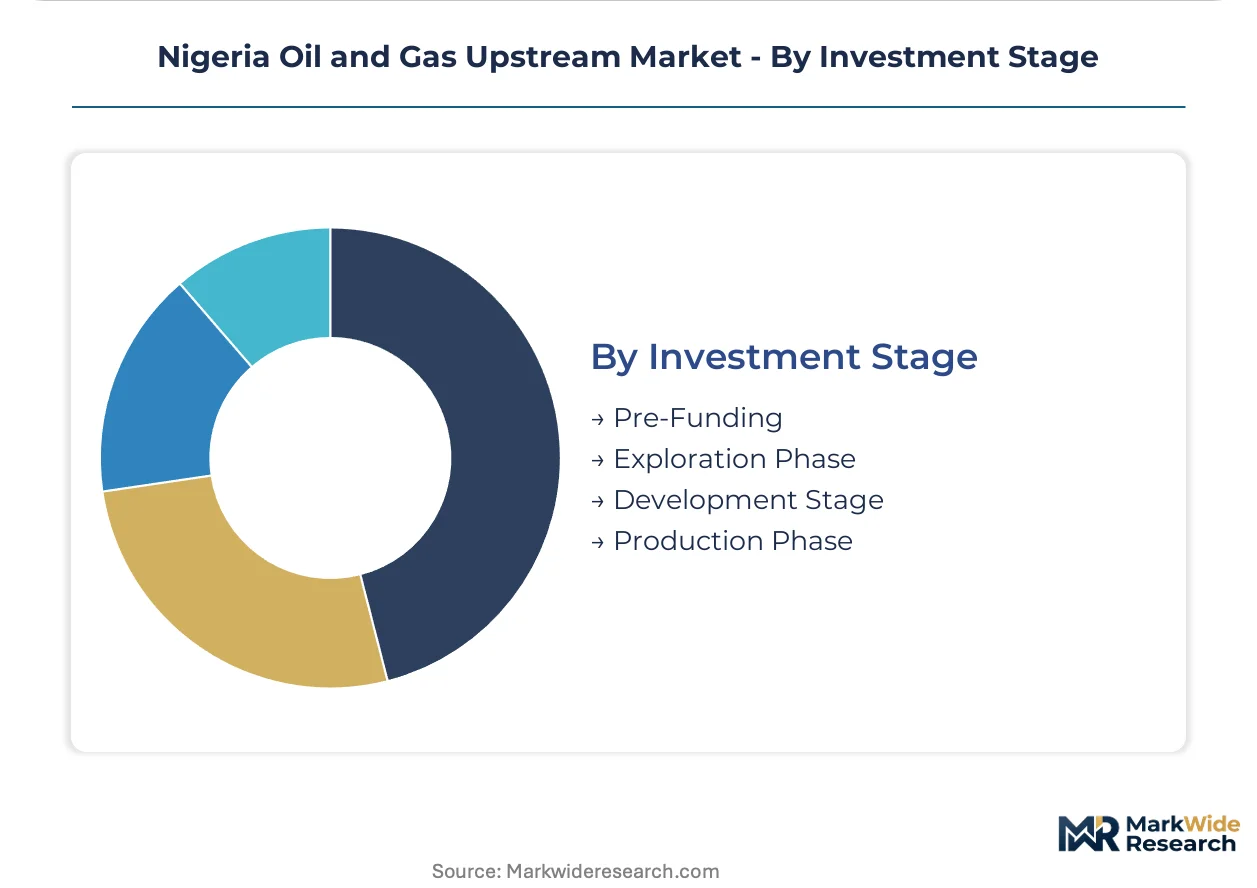
Investment Stage:
Investment stage segmentation aligns with NUPRC's block award timeline and cost recovery framework under the Petroleum Industry Act fiscal structure.
- Exploration Phase:Seismic acquisition, exploration drilling, and appraisal activities consuming capital without revenue recognition. Deepwater frontier blocks in offshore Bayelsa state concentrate this stage activity as operators test pre-salt plays.
- Production Phase:Sustaining capital, workovers, and enhanced recovery operations generating cash flows. Legacy shallow-water and onshore assets dominate this category, with operators deferring abandonment spend amid uncertain regulatory timelines.
- Pre-Funding:Farm-in negotiations, technical due diligence, and regulatory application preparation.
- Development Stage:Engineering, procurement, construction, and installation of production facilities.
Production Phase accounts for the greatest cumulative investment, with Exploration Phase showing the steepest expansion trajectory as new acreage awards accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Lagos and Port Harcourt anchor Nigeria's upstream workforce concentration. These coastal cities supply technical specialists for offshore operations and onshore field management. The Niger Delta basin and emerging deepwater provinces offshore Bayelsa and Lagos states concentrate capital deployment and production infrastructure.
Niger Delta Basin
Onshore crude extraction and marginal field redevelopment drive service demand across Rivers, Bayelsa, and Delta states. The Nigerian Upstream Petroleum Regulatory Commission enforces environmental management plans and community development agreements for all block awards. Warri and Port Harcourt host fabrication yards and logistics bases supporting drilling campaigns and pipeline maintenance.
Deepwater Offshore Lagos
Pre-salt exploration and FPSO-deployed production anchor capital intensity in blocks west of the Niger Delta. The Petroleum Industry Act fiscal framework governs cost recovery allowances and royalty structures for new deepwater acreage. Lagos serves as the commercial and technical coordination hub for integrated offshore developments.
Deepwater Offshore Bayelsa
Ultra-deepwater frontier drilling targets billion-barrel prospects beneath complex salt geometries. NUPRC mandates minimum work program commitments tied to exploration rights in these high-risk, high-reward blocks. Contractors cluster supply chain operations through Port Harcourt to support sixth-generation drillship campaigns.
Onshore Marginal Fields
Indigenous operators acquire abandoned or underperforming blocks through NUPRC licensing rounds targeting lower-cost redevelopment. Local content enforcement requires demonstrated Nigerian supplier contracts and workforce development plans. Field operations concentrate around legacy infrastructure corridors where pipeline networks and processing facilities remain operational.
Nigeria Oil and Gas Upstream Market Competitive Landscape
Top-tier vendors anchor integrated offshore developments, while mid-tier independents compete for marginal field acreage and gas monetization opportunities. The market exhibits tiered concentration with majors controlling deepwater capital deployment and indigenous firms expanding onshore market share. Two strategic archetypes dominate: balance-sheet-heavy international operators pursuing billion-dollar FPSO projects, and cost-structured domestic players leveraging operational proximity. Competitive moves center on portfolio restructuring to exit mature shallow-water assets and integrated service contracting to transfer reservoir risk.
Among international majors with Nigerian deepwater exposure, TotalEnergies SE and Shell PLC occupy positions exemplifying the integrated offshore archetype through FPSO deployment and legacy production maintenance. Seplat Energy represents the indigenous competitive vector, leveraging domestic operational footprint and gas infrastructure integration. These three entities illustrate the bifurcation between capital-intensive frontier development and onshore operational efficiency.
| Leading Market Players |
|---|
| TotalEnergies SE |
| Seplat Energy |
| Royal Dutch Shell PLC |
| Heirs Energies |
| Nigerian National Petroleum Development Company |
| Chevron Corporation |
| Nigerian National Petroleum Corporation |
| Aradel Holdings |
| ExxonMobil Corporation |
| Others |
Supply & Pricing Matrix
FPSO leasing models and integrated service contracting are compressing capital deployment timelines while redistributing cost risk between operators and contractors across Nigerian deepwater and onshore developments. This shift simultaneously lowers barriers for mid-tier players and concentrates procurement leverage among integrated service providers.
Pricing Analysis
Bundled integrated service contracts dominate deepwater developments, while unbundled discrete procurement persists in marginal field onshore operations. Price differentiation rests on certification tier under NUPRC technical standards and local content compliance percentages. Pricing pressure stems from NNPC cash-call arrears delaying joint venture drilling programs. Indigenous operators exhibit highest price sensitivity due to constrained balance sheets, while majors absorb cost volatility through portfolio diversification.
Supply Chain Analysis
Certification and qualification gating through NUPRC well control training and blowout preventer standards filters contractor eligibility for Nigerian upstream work. Equipment and technical services concentrate in the United States, United Kingdom, and Singapore. Raw material dependencies include high-grade steel for offshore platforms, subsea umbilicals, and specialized drilling consumables. Single-source vulnerability runs through sixth-generation drillship availability. Distribution feeds through Lagos and Port Harcourt logistics hubs to offshore installation sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in gas monetization infrastructure and marginal field revitalization, driven by domestic refinery offtake growth and reduced export dependency.
For Market Incumbents: Deepen integration into gas processing and LNG liquefaction chains to capture dual-revenue streams from associated gas. Acquire well intervention engineering capabilities to address aging well stock integrity shortages. Secure NUPRC environmental management plan pre-approvals to accelerate drilling permit timelines. For New Entrants and Emerging Players: Marginal field operators with sub-$50 million development budgets represent the most penetrable buyer archetype in Nigerian upstream services. Target abandoned onshore blocks in Rivers and Delta states through NUPRC licensing rounds. Deploy contractor-operated FPSO leasing models to eliminate upfront platform capex. For Investors and Strategic Acquirers: Valuations sit cheapest among indigenous service contractors with NUPRC certification and established community development agreements. Long-term viability hinges on Petroleum Industry Act implementation stability and domestic refinery absorption rates. Monitor Dangote Refinery crude offtake volumes as inflection indicator for upstream producer pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Contracting | Consolidates seismic through abandonment risk under single contractor accountability for offshore developments. |
| FPSO Leasing Deployment | Reduces upfront capex exposure and accelerates time-to-first-oil for mid-sized deepwater discoveries. |
| Gas Monetization Infrastructure | Captures dual-revenue streams from associated gas through LNG trains and domestic power sector feedstock. |
| Marginal Field Acquisition | Enables indigenous operators to redevelop abandoned blocks through NUPRC licensing with lower cost structures. |
| Enhanced Oil Recovery Investment | Offsets natural decline rates exceeding five percent annually in mature Niger Delta fields. |
Research Methodology
Coverage spans Nigeria's Niger Delta basin, deepwater offshore Lagos, and deepwater offshore Bayelsa provinces, with primary inputs from each. The approach combines structured interviews with upstream operations executives, NUPRC regulatory affairs officers, drilling contractor procurement leads, and indigenous operator finance directors with secondary validation from NUPRC licensing round disclosures, DPR historical production data, NNPC joint venture reports, and Petroleum Industry Act fiscal analysis. Bottom-up field-level production estimates and top-down sector revenue benchmarks undergo triangulation.
Granularity-level modeling disaggregates service type, technology tier, end user capital access, and investment stage across the projection horizon. CAGRs derive from production volume trajectories, capital expenditure schedules, and regulatory implementation timelines. Industry-specific inputs include well integrity intervention backlogs, FPSO deployment schedules, and domestic refinery offtake absorption curves.
Inputs from NUPRC regulatory filings and operator production disclosures were available through the study window; gaps in real-time joint venture cash-call data introduce uncertainty bands around near-term drilling activity forecasts. Forecasts reflect assumptions regarding Petroleum Industry Act enforcement consistency and security infrastructure cost stabilization. A model refresh is warranted upon material change in NNPC funding availability or domestic refinery commissioning timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Storage Market
Oil & Gas
Europe Well Intervention Market
Oil & Gas
Delayed Coker Unit Market
Oil & Gas
Europe Wireline Logging Services Market
Oil & Gas
Oil and Gas Digital Rock Analysis Market
Oil & Gas
Oil and Gas Separation Equipment Market
Oil & Gas
Saudi Arabia Liner Hanger System Market
Oil & Gas
Ecuador Wireline Logging Services Market
Oil & Gas
Uzbekistan Oil and Gas Market
Oil & Gas
Subsea Well Intervention Market
Oil & Gas
United States Wireline Logging Services Market
Oil & Gas
Kuwait Oil and Gas Market
Oil & Gas
LNG Storage Tank Market
Oil & Gas
Middle-East and Africa Frac Stack Market
Oil & Gas
GCC and North Africa Coiled Tubing Market
Oil & Gas
Nigeria Wireline Logging Services Market