
 United States Wireline Logging Services Market | 2026-2036
United States Wireline Logging Services Market Size, Share, and Industry Trends Forecast 2026-2036
United States Wireline Logging Services Market Analytics
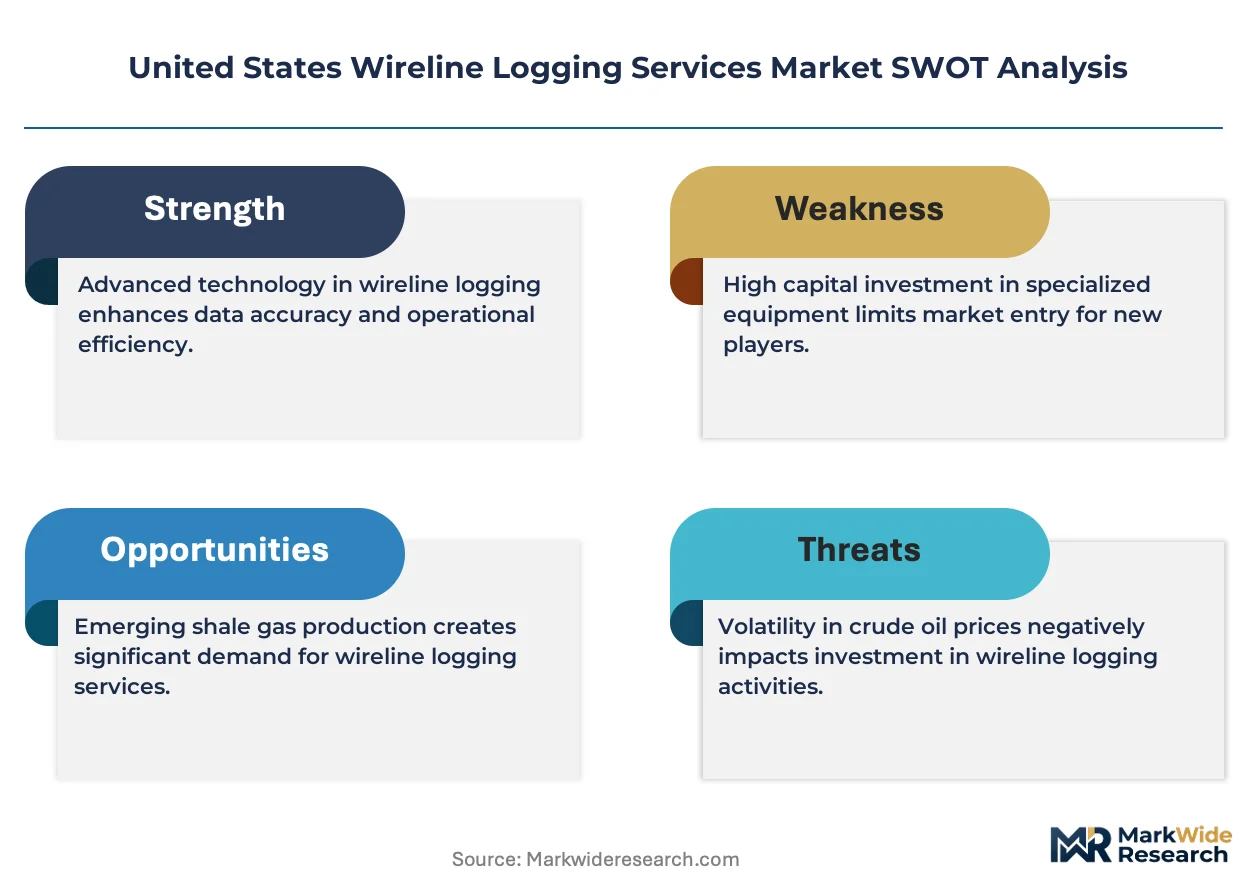
Project finance and asset-light leasing models is fragmenting competitive dynamics across the United States wireline logging sector. Schlumberger Limited leverages its integrated technology portfolio to sustain premium positioning in high-specification open-hole environments. Halliburton Company anchors its market presence through extensive Permian Basin service infrastructure and captive equipment fleets. Baker Hughes Company differentiates via advanced telemetry systems and radioactive isotope logging capabilities that command technical preference in deep unconventional wells.
Wireline logging services deploy instrumented cables to lower measurement tools into boreholes, capturing resistivity, porosity, and acoustic data through electric line or slickline conveyance at depths exceeding 30,000 feet. These measurements guide reservoir characterization, completion design, and production optimization decisions across oil and gas field development cycles. Open-hole logging retains the largest revenue share as operators require pre-completion formation evaluation to stage hydraulic fracturing programs effectively. Cased-hole services are expanding fastest as mature basins shift toward production logging and behind-casing reservoir monitoring to maximize recovery factors. Formation evaluation commands the deepest margin pools where proprietary interpretation algorithms and petrophysical expertise create defensible pricing power.
The EPA enforces methane emissions standards that mandate continuous wellbore integrity monitoring, directly expanding cased-hole logging obligations for operators across federal and tribal lands. OSHA and state-level oil and gas commissions impose radioactive materials handling protocols that shape tool deployment logistics and technician certification requirements. The Bureau of Land Management's updated drilling permit conditions are embedding environmental monitoring clauses that require baseline and periodic logging data submission. Stakeholders must monitor how evolving federal leasing rules and state groundwater protection standards alter the frequency and specification of logging interventions required for regulatory compliance.
Market Dynamics
The EPA's methane emissions standards are forcing operators to deploy continuous wellbore integrity monitoring, fundamentally expanding cased-hole logging obligations across federal and tribal lands. This regulatory pressure is compressing intervention cycles and elevating technical specifications for logging service providers.
Growth Catalysts
- Unconventional Shale Complexity:Horizontal well designs in the Permian Basin require multi-stage formation evaluation to optimize hydraulic fracturing programs. Operators demand higher-resolution resistivity and acoustic measurements at extended lateral lengths.
- EPA Methane Regulations:Continuous emissions monitoring mandates under federal standards are accelerating cased-hole logging adoption for behind-casing reservoir surveillance and leak detection.
- Production Optimization:Mature basins in Texas and North Dakota are shifting toward production logging and reservoir monitoring to maximize recovery factors from existing wellbores.
Market Restraints
- Radioactive Materials Handling:OSHA and state oil and gas commissions impose stringent certification protocols for isotope logging tools, constraining technician availability and deployment flexibility.
- Equipment Capital Intensity:Advanced telemetry systems and high-temperature rated tools require substantial capital investment, favoring providers with captive equipment fleets over asset-light entrants.
- Permitting Delays:Bureau of Land Management drilling permit conditions now embed environmental monitoring clauses that extend approval timelines and increase compliance documentation burdens.
Strategic Opportunities
- Carbon Capture Monitoring:Class VI well injection regulations are creating demand for specialized cased-hole logging to verify caprock integrity and plume migration in carbon storage projects.
- Geothermal Expansion:Enhanced geothermal systems in the western United States require formation evaluation services adapted to high-temperature crystalline rock environments.
- Real-Time Telemetry Convergence:Integration of fiber-optic distributed sensing with conventional wireline tools is enabling continuous reservoir monitoring without repeated well interventions.
Industry Challenges
- Petrophysical Talent Scarcity:Proprietary interpretation algorithms require specialized expertise that outpaces current training pipeline output, constraining service quality differentiation.
- Legacy System Integration:Operators' existing data management platforms often lack compatibility with advanced logging data formats, complicating technology adoption and value demonstration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Wireline Logging Services Market |
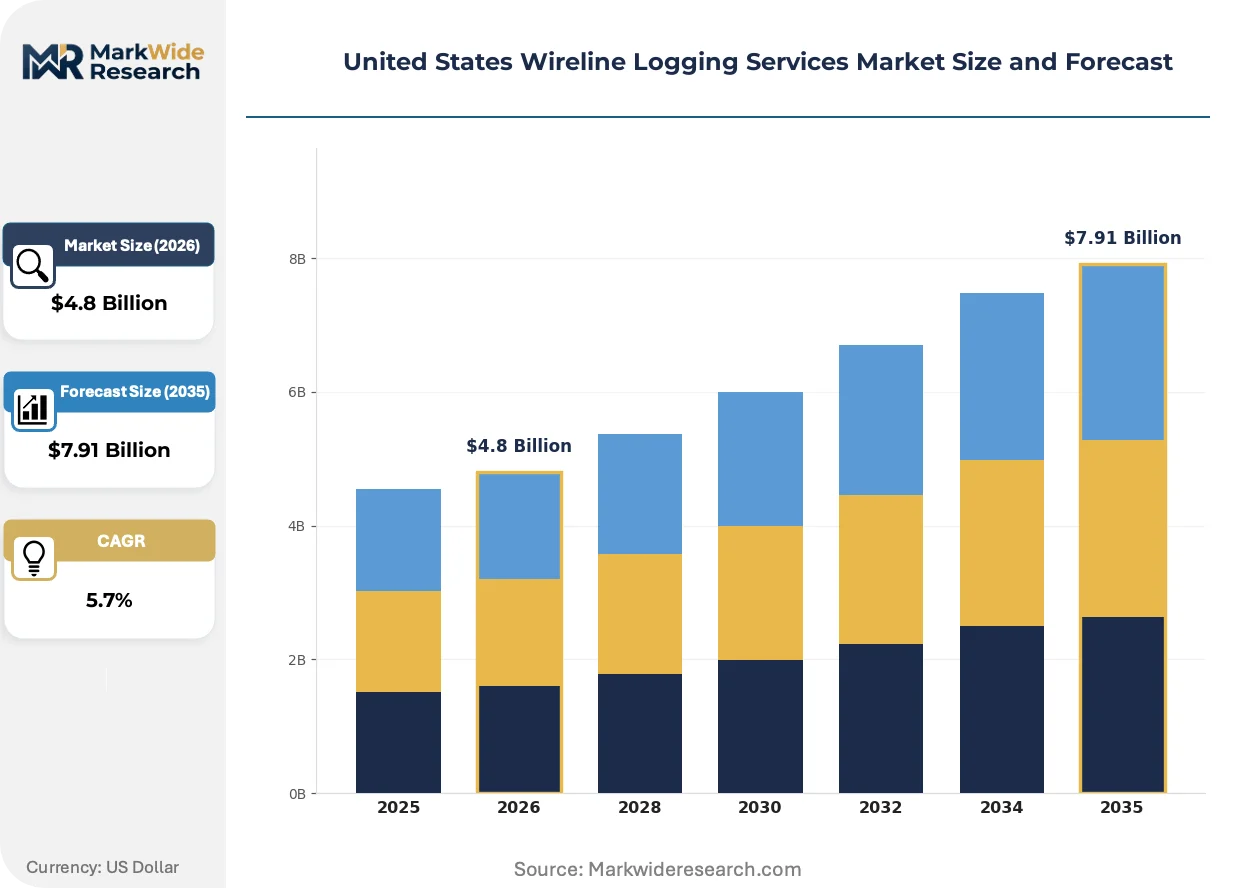
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Open Hole, Cased Hole, Production Logging, Formation Evaluation Technology: Electric Line, Slickline, Coiled Tubing, Radioactive Isotopes End User: Oil & Gas Companies, Research Institutions, Service Providers, Government Agencies Application: Reservoir Evaluation, Well Completion, Data Acquisition, Environmental Monitoring |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, Expro Group, Weatherford International, Superior Energy Services, Nabors Industries, Pioneer Energy Services Corp., NexTier Oilfield Solutions, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Wireline Logging Services Market Evolving Landscape
Digital twin architectures and real-time data transmission are compressing the timeline between subsurface measurement and operational decision-making. Service providers are racing to embed predictive analytics into logging workflows before competitors capture long-term interpretation contracts.
Cloud-based logging data platforms are virtualizing traditional interpretation workflows that previously required dedicated on-site petrophysical specialists. Permian Basin operators are adopting these systems fastest, demanding instant access to formation evaluation results across multi-well pads. This virtualization is compressing margins for conventional interpretation services while expanding addressable market for software-enabled providers.
The EPA's updated methane emissions standards are embedding continuous monitoring obligations into federal leasing agreements. Operators must now submit baseline and periodic logging data to demonstrate wellbore integrity, directly expanding cased-hole service frequency. Texas and North Dakota producers are responding by pre-negotiating multi-year logging service contracts to lock in technician availability.
Integrated service contracting is displacing discrete tool rentals as the dominant procurement model among large unconventional operators. Buyers are bundling open-hole, cased-hole, and production logging into single-source agreements that transfer interpretation risk to service providers. This consolidation is most visible in the Permian Basin, where horizontal well complexity rewards seamless data handoffs between drilling, completion, and production phases.
United States Wireline Logging Services Market Segmentation
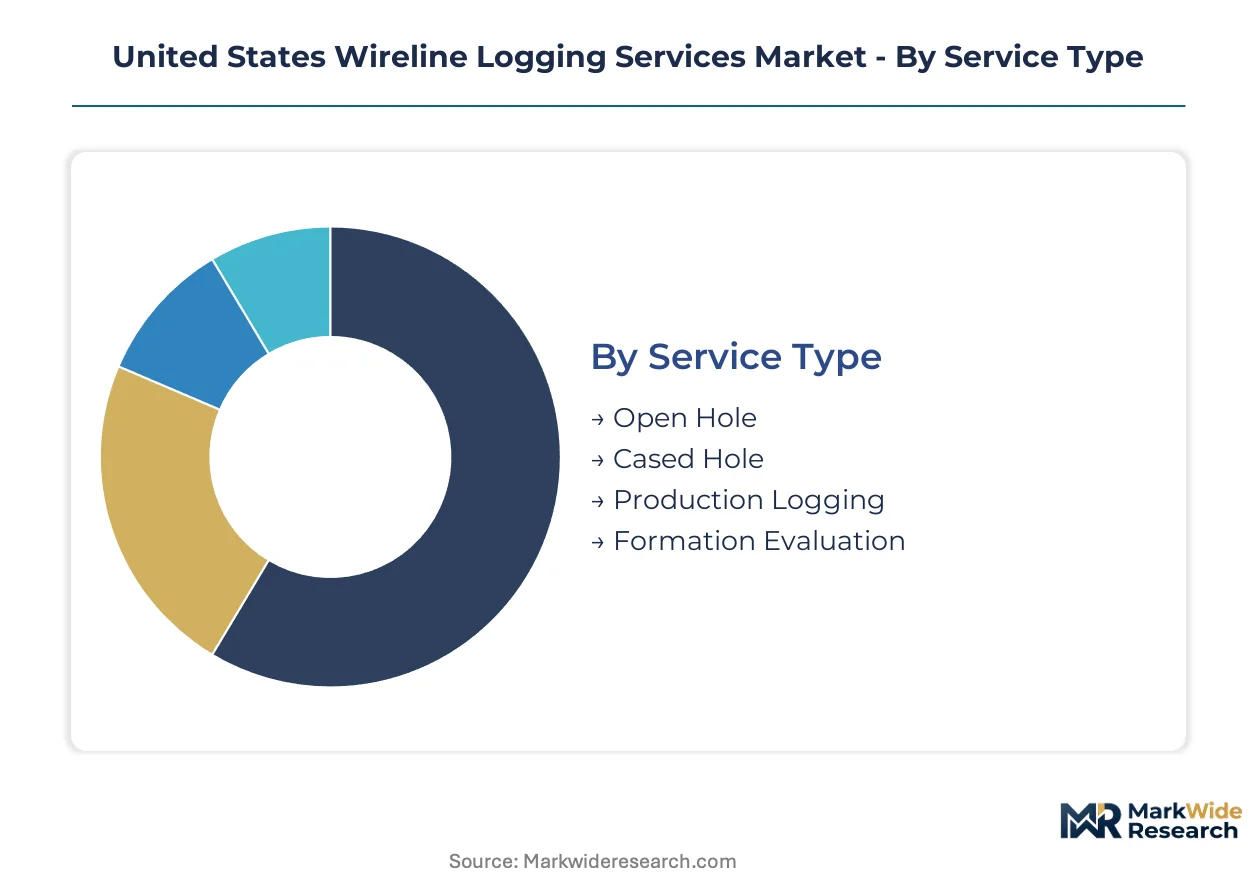
Wireline logging services fragment across four distinct dimensions that shape procurement patterns and margin structures. Each segmentation axis reveals divergent technical requirements, regulatory exposure, and customer concentration dynamics that providers must navigate.
Service Type:
Mature evaluation protocols coexist with emerging surveillance technologies across the service spectrum.
- Open Hole:Pre-completion formation evaluation captures resistivity, porosity, and acoustic measurements through uncased wellbores. Permian Basin operators demand higher-resolution tools for extended lateral characterization to stage hydraulic fracturing programs effectively.
- Cased Hole:Behind-casing reservoir monitoring and wellbore integrity surveillance uses instrumented cables in completed wells. EPA methane emissions standards are accelerating deployment frequency across federal and tribal lands in Texas and North Dakota.
- Production Logging:Flow profiling and injection diagnostics optimize recovery factors from mature basins.
- Formation Evaluation:Integrated petrophysical interpretation commands premium pricing through proprietary algorithms.
Open Hole handles the majority of throughput; Cased Hole is the fastest mover on share.
Technology:
Conveyance methods span a cost tier from standardized slickline operations to capital-intensive coiled tubing interventions.
- Electric Line:Powered cable systems transmit real-time data from high-specification measurement tools at depths exceeding 30,000 feet. Horizontal well complexity in unconventional shale drives demand for telemetry-rated electric line in the Permian Basin.
- Slickline:Mechanical wire conveyance without electrical power suits gauge ring runs, plug setting, and basic depth correlation. Cost-sensitive operators in mature Texas basins favor slickline for routine mechanical interventions.
- Coiled Tubing:Continuous pipe deployment enables logging in highly deviated or unstable wellbores where conventional cable conveyance fails.
- Radioactive Isotopes:Tracer logging for fracture diagnostics and flow profiling requires specialized handling protocols under OSHA and state oil and gas commission regulations.
Electric Line commands the largest revenue pool; Cased Hole applications are expanding most quickly for radioactive isotope deployment.
End User:
Customer concentration tilts heavily toward integrated operators with captive technical staff versus fragmented independent producers.
- Oil & Gas Companies:Exploration and production operators commission logging services across drilling, completion, and production phases. Large unconventional producers in Texas and North Dakota are consolidating procurement into multi-year integrated service contracts.
- Research Institutions:Academic and national laboratory users seek specialized formation evaluation for experimental reservoir characterization.
- Service Providers:Subcontracting relationships exist where tier-2 logging companies lease equipment or interpretation capacity from technology leaders.
- Government Agencies:Bureau of Land Management and tribal regulatory bodies mandate baseline logging data for federal drilling permits.
Oil & Gas Companies dominate contract volume; Government Agencies are tightening compliance-driven specification requirements fastest.
Application:
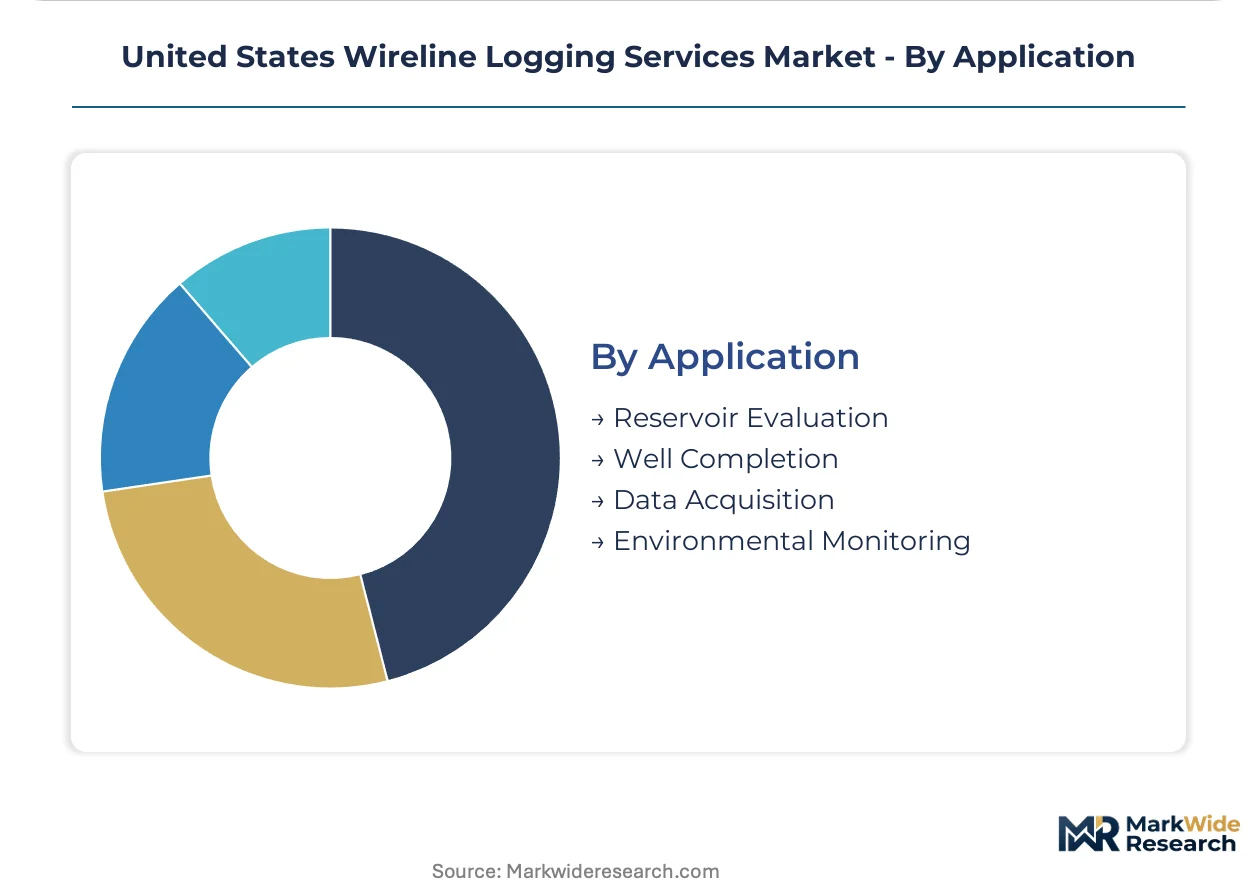
Application priorities shift from discovery-phase reservoir characterization toward production optimization and environmental assurance.
- Reservoir Evaluation:Pre-drill and post-drill formation analysis guides field development planning and reserve booking. Permian Basin operators require multi-stage evaluation across stacked pay zones to optimize horizontal landing targets.
- Well Completion:Perforation selection and stimulation design depend on open-hole logging data for fracture stage spacing. Extended lateral lengths in North Dakota's Bakken formation intensify completion logging complexity.
- Data Acquisition:Raw measurement collection spans resistivity, sonic, nuclear, and imaging tool suites.
- Environmental Monitoring:EPA-mandated wellbore integrity verification and carbon storage site characterization represent emerging specification areas.
Reservoir Evaluation anchors current revenue; Environmental Monitoring is climbing the fastest as regulatory obligations expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Texas shale corridors while North Dakota operators absorb steeper mobilization premiums for remote basin access. This asymmetry shapes contract structures across the Lower 48.
Texas
Permian Basin horizontal complexity demands multi-stage formation evaluation across stacked pay zones. EPA methane regulations under 40 CFR Part 60 Subpart OOOOb expand cased-hole logging frequency on federal leases. Midland-Odessa service clusters anchor the nation's densest wireline infrastructure.
North Dakota
Bakken formation extended laterals intensify completion logging complexity for optimized fracture stage spacing. Bureau of Land Management drilling permits embed environmental monitoring clauses extending approval timelines. Williston Basin operators pre-negotiate multi-year logging contracts to secure technician availability.
New Mexico
Delaware Basin expansion drives demand for high-temperature rated tools in deeper unconventional targets. State Oil Conservation Division rules mandate baseline logging data for groundwater protection compliance. Carlsbad-Artesia corridor concentrates radioactive isotope handling facilities serving cross-border Permian activity.
Oklahoma
SCOOP-STACK reservoir heterogeneity requires sophisticated petrophysical interpretation for landing zone selection. Oklahoma Corporation Commission protocols govern wellbore integrity verification in seismically active zones. Oklahoma City service hubs support Anadarko Basin redevelopment programs.
Louisiana
Haynesville shale gas resurgence revives production logging demand for mature horizontal well optimization. Louisiana Department of Natural Resources regulations enforce continuous wellbore surveillance in coastal restoration zones. Lake Charles-Baton Rouge logistics corridors facilitate Gulf Coast offshore mobilization.
United States Wireline Logging Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying telemetry modules and radioactive sources. The United States wireline logging sector exhibits tiered consolidation with three global service companies anchoring premium open-hole evaluation and regional independents capturing cased-hole maintenance cycles. Strategic archetypes span integrated technology platforms, basin-specific infrastructure operators, and asset-light interpretation boutiques. Dominant competitive moves include captive equipment fleet expansion and multi-year integrated service contracting that transfers interpretation risk to providers.
Among Houston-headquartered majors, Schlumberger Limited, Halliburton Company, and Baker Hughes Company exemplify the integrated platform archetype. These entities occupy positions where proprietary telemetry systems and radioactive isotope capabilities anchor premium-tier positioning. Regional specialists including Expro Group and Weatherford International sit within the basin-focused infrastructure tier, leveraging Permian and Bakken density for contract capture. The asset-light interpretation segment remains fragmented, with boutiques competing on petrophysical expertise rather than capital deployment.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| Expro Group |
| Weatherford International |
| Superior Energy Services |
| Nabors Industries |
| Pioneer Energy Services Corp. |
| NexTier Oilfield Solutions |
| Others |
Value Network & Pricing Analysis
Permian Basin overcapacity among electric line service providers is compressing day-rate spreads while elevating equipment utilization as the dominant pricing lever. This utilization pressure rewards operators with captive fleets and squeezes asset-light entrants into low-margin slickline niches.
Pricing Analysis
The customization-premium spread between configured-to-order formation evaluation packages and standard open-hole logging runs defines contract negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects tool specification tiers, with radioactive isotope capabilities and real-time telemetry commanding quality-grade premiums. Cost compression in standard electric line services is intensifying because independent producers in mature Texas basins prioritize per-foot transactional pricing over bundled interpretation. Independent shale operators exhibit highest price sensitivity; integrated majors with captive technical staff absorb premium-tier markups for proprietary algorithm access.
Supply Chain Analysis
Contract-manufacturing concentration for high-temperature rated logging tools rests on Schlumberger, Halliburton, and Baker Hughes captive production facilities in Texas, Oklahoma, and Louisiana. Raw material dependencies center on specialized cable armoring alloys, radiation-resistant scintillation crystals, and high-pressure telemetry housings. Supply chain risk hinges on single-source vulnerability for deep-unconventional rated electronics modules. Distribution runs through basin-anchored service yards in Midland-Odessa, Williston, and Carlsbad-Artesia corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireline logging services represent a service-attach opportunity where recurring cased-hole monitoring contracts expand faster than discrete open-hole hardware deployments. Interpretation software subscriptions and multi-year integrity surveillance agreements now outpace tool rental revenue growth.
For Market Incumbents: Harden defensive positioning by expanding captive radioactive materials handling infrastructure in Carlsbad-Artesia to preempt regulatory bottlenecks. Deepen backward integration into telemetry module production to isolate supply chain disruptions. Secure multi-year integrated service contracts with Permian Basin operators before asset-light interpretation boutiques capture petrophysical talent.
For New Entrants and Emerging Players: North Dakota's Bakken formation presents underpenetration for specialized high-temperature coiled tubing logging where extended lateral complexity exceeds conventional cable capabilities. Target environmental monitoring applications for carbon storage site characterization where Class VI regulations create specification gaps. Pursue direct contracting with Bureau of Land Management compliance officers for federal lease baseline logging mandates.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across radioactive isotope logging capabilities as OSHA certification requirements tighten technician scarcity. Long-term viability favors asset-light interpretation boutiques with proprietary algorithm libraries over equipment-heavy service operators. Monitor EPA methane enforcement intensity as the inflection signal for cased-hole contract frequency expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Contracting | Bundling open-hole, cased-hole, and production logging transfers interpretation risk to providers in Permian multi-well pads. |
| Radioactive Materials Infrastructure Expansion | Carlsbad-Artesia corridor concentration enables compliance advantage under OSHA and state oil and gas commission protocols. |
| Real-Time Telemetry Convergence | Fiber-optic distributed sensing integration creates continuous monitoring revenue streams without repeated well interventions. |
| Carbon Capture Monitoring Capability Buildout | Class VI well injection regulations demand specialized caprock integrity verification for carbon storage project developers. |
| Geothermal Formation Evaluation Adaptation | Enhanced geothermal systems in western states require high-temperature crystalline rock measurement tool redesign. |
Research Methodology
Operator-level perspectives from drilling engineers, completion supervisors, petrophysicists, and regulatory compliance officers anchored the qualitative base. These primary inputs combined with secondary validation from EIA drilling productivity reports, Bureau of Land Management permit databases, EPA enforcement and compliance records, and state oil and gas commission production filings. Bottom-up rig-count modeling and top-down service revenue triangulation calibrated market size estimates.
Scenario-bracketing framed analytical projections across the analysis window, with segmentation dimensions spanning service type, conveyance technology, end-user concentration, and application priority. CAGRs derived from rig activity trajectories, well complexity indices, and regulatory enforcement intensity curves. Forecast inputs incorporated horizontal lateral length expansion rates and methane monitoring mandate implementation pace.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by regional independents or accelerated EPA rulemaking would shift outcomes. Quarterly review of Bureau of Land Management permit approval timelines and radioactive materials certification backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Hydraulic Workover Units Market
Oil & Gas
Fracking Fluid Market
Oil & Gas
South-East Asia Oil and Gas Pipeline Market
Oil & Gas
North America Artificial Lift Systems Market
Oil & Gas
South America LNG Bunkering Market
Oil & Gas
Asia-Pacific Small-Scale LNG Market
Oil & Gas
Sidetracking Market
Oil & Gas
Multi-Point Ground Flares (MPGF) Market
Oil & Gas
Oman Directional Drilling Market
Oil & Gas
Mexico Wireline Services Market
Oil & Gas
Global LNG Liquefaction Equipment Market
Oil & Gas
Logging While Drilling (LWD) Market
Oil & Gas
Oil & Gas Equipment MRO Market
Oil & Gas
Asia-Pacific AI in Oil and Gas Market
Oil & Gas
Mud Mixers Market
Oil & Gas
Oil and Gas Fabrication Market