
 Casing Centralizer Market | 2026-2036
Casing Centralizer Market Size, Share, and Industry Trends Forecast 2026-2036
Casing Centralizer Market Intelligence
North American forged-steel suppliers is decoupling from legacy spot-market pricing as long-term offtake agreements with Permian operators stabilize volume commitments. Weatherford leverages its integrated manufacturing footprint across Oklahoma and Texas to sustain delivery reliability for super-spec centralizers. Halliburton anchors its position through proprietary centralizer placement software bundled with hardware offerings. Centek Group competes aggressively in the North Sea sector with aluminum-body designs rated for HPHT well conditions.
A casing centralizer is a mechanical device installed on casing strings to maintain concentric standoff between the pipe and borehole wall, typically achieving restoring forces between 20 and 50 lbf per API 10D specifications to ensure adequate cement sheath thickness during primary cementing operations. Bow spring centralizers retain dominant share in vertical and low-deviation onshore wells where cost efficiency outweighs performance premiums, while composite centralizers represent the fastest-expanding material category as operators seek weight reduction and corrosion immunity for extended-reach drilling. Rigid blade centralizers command margin pools in deepwater and high-angle applications where positive standoff tolerance of 0.125 inches or tighter is non-negotiable.
API 10D testing protocols enforced by the American Petroleum Institute govern restoring force, starting force, and running force thresholds that determine centralizer qualification for North American service company procurement. The EPA's methane emissions regulations indirectly shape centralizer specification as imperfect cement barriers become liability exposure points in gas well completions. Offshore regulators in Norway and Brazil mandate centralizer documentation within well construction dossiers submitted for drilling permit approval. Stakeholders must monitor composite material qualification timelines and API specification revision cycles to align R&D commitments with evolving procurement gate requirements.
Market Dynamics
Composite centralizer technology is expanding into extended-reach drilling applications, forcing forged-steel suppliers to defend margin pools through integrated manufacturing control and long-term offtake contracting with Permian Basin operators.
Growth Catalysts
- API 10D specification tightening:Restoring force thresholds now demand higher-performance bow spring and rigid blade designs, elevating qualification barriers that favor technically advanced manufacturers.
- Deepwater exploration intensity:Brazil and West Africa contractors are expanding composite centralizer procurement to reduce non-productive time during high-cost casing runs in saltwater environments.
- Methane emissions liability exposure:EPA regulations targeting imperfect cement barriers in gas well completions are elevating centralizer specification priority to ensure annular seal integrity.
Market Restraints
- Alloy steel price volatility:Forged-steel centralizer production faces margin compression from nickel and chromium input cost swings, squeezing spot-market suppliers without long-term material hedging.
- Composite material qualification timelines:API specification revision cycles create extended certification delays for thermoplastic and carbon-fiber designs, freezing R&D returns for 18-24 month windows.
- Offshore supply chain concentration:HPHT-rated aluminum-body centralizer capacity clusters in the North Sea, creating single-source vulnerability for North Atlantic deepwater projects.
Strategic Opportunities
- Guyana offshore expansion:ExxonMobil-operated Stabroek Block development is generating demand for premium rigid blade centralizers capable of 0.125-inch standoff tolerance in extended-reach laterals.
- Centralizer placement software bundling:Hardware-software integration models are capturing margin from standalone component suppliers by embedding predictive placement algorithms in service contracts.
- Norwegian well construction dossier mandates:Offshore regulators now require documented centralizer specification within drilling permit submissions, creating compliance-driven specification lock-in for approved vendors.
Industry Challenges
- Composite-to-metal bonding reliability:Thermoplastic centralizer end-connections face field failure risks under cyclic loading, requiring extended fatigue testing protocols that delay product release.
- Legacy inventory obsolescence:API specification revisions strand pre-qualified centralizer stockpiles, forcing distributors to absorb write-downs or negotiate retrofit certifications.
- HPHT testing infrastructure scarcity:Third-party laboratories capable of validating 350°F/20,000 psi rated designs concentrate in Oklahoma and Texas, creating bottlenecks for international qualification submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Casing Centralizer Market |
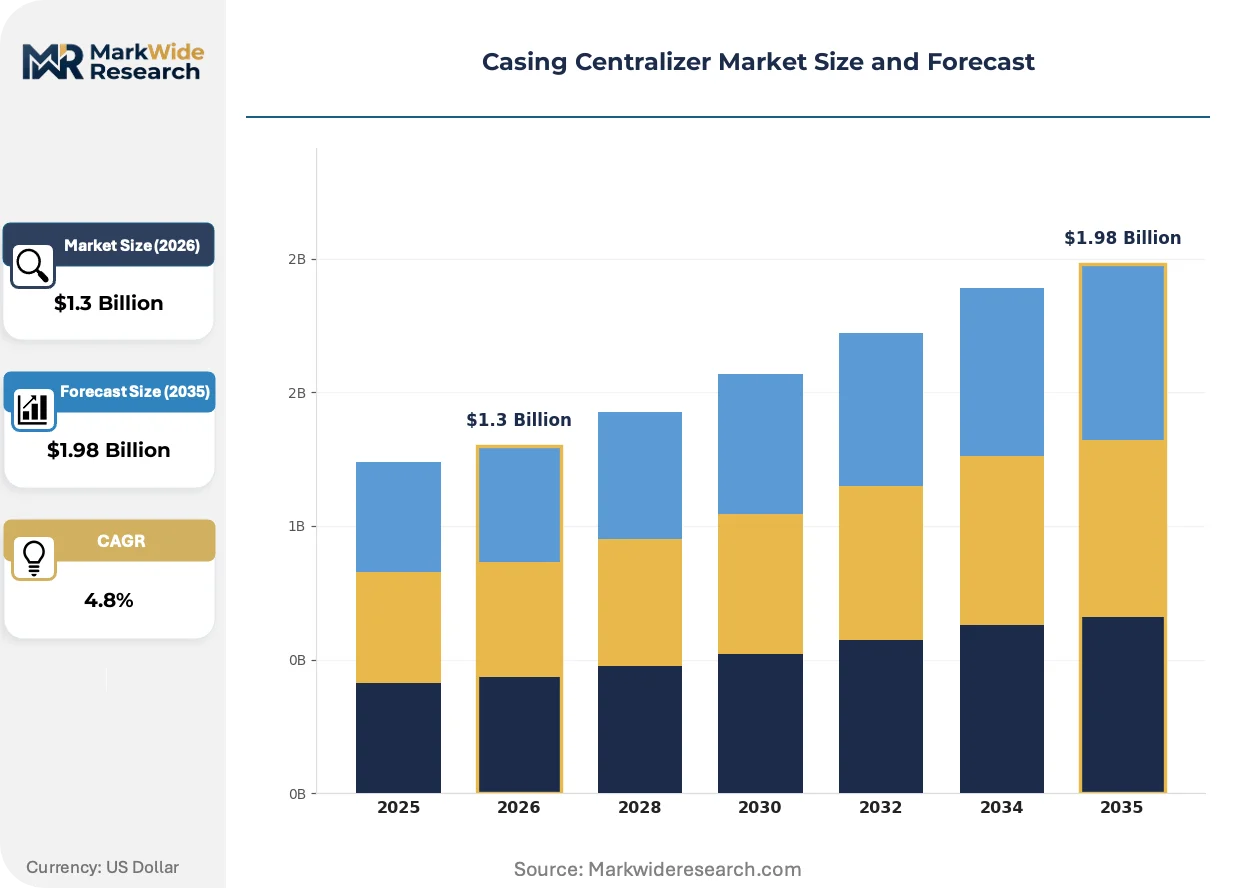
| Market Size in 2026 | $1.3 Billion |
| Market Size in 2035 | $1.98 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bow Spring Centralizers, Rigid Blade Centralizers, Composite Centralizers, Versatile Centralizers, Semi-Rigid Centralizers Material: Steel, Alloy Steel, Carbon Steel, Aluminum, Composite Materials Application: Onshore Drilling, Offshore Exploration, Directional Drilling, Production Wells, Well Completion End User: Exploration Companies, Drilling Contractors, Oilfield Service Providers, National Oil Companies, Independent Operators |
| Companies Covered | Weatherford, Summit Casing Equipment, Halliburton, Centek Group, NeOz Energy, Baker Hughes, NOV, Antelope Oil Tool, SLB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Casing Centralizer Market Strategic Shifts & Innovations
Material substitution and digital integration are compressing traditional hardware margins while elevating specification precision requirements across onshore and offshore drilling programs.
Bow spring centralizers constructed from engineered thermoplastic composites are expanding into extended-reach lateral applications previously dominated by steel designs. Permian Basin operators running 15,000-foot laterals are adopting these lightweight alternatives to reduce torque and drag during casing runs. The technology is expanding into super-spec drilling programs where corrosion immunity and weight reduction justify 40-60% unit cost premiums over forged steel.
EPA methane emissions regulations are reshaping centralizer specification priority in US gas well completions. Imperfect cement barriers now carry direct liability exposure under federal reporting requirements, elevating standoff accuracy to a compliance-critical parameter. Appalachian Basin operators are responding by mandating rigid blade centralizers with documented restoring force testing even in vertical well sections where bow springs previously dominated.
Long-term offtake agreements are displacing spot-market procurement for forged-steel centralizers in the Permian Basin. Supermajor and large independent operators are consolidating supplier relationships into 24-36 month volume commitments with price bands tied to alloy indices. This concentration is visible in West Texas and Southeast New Mexico drilling programs where delivery reliability now outweighs unit price in vendor selection criteria.
Casing Centralizer Market Segmentation
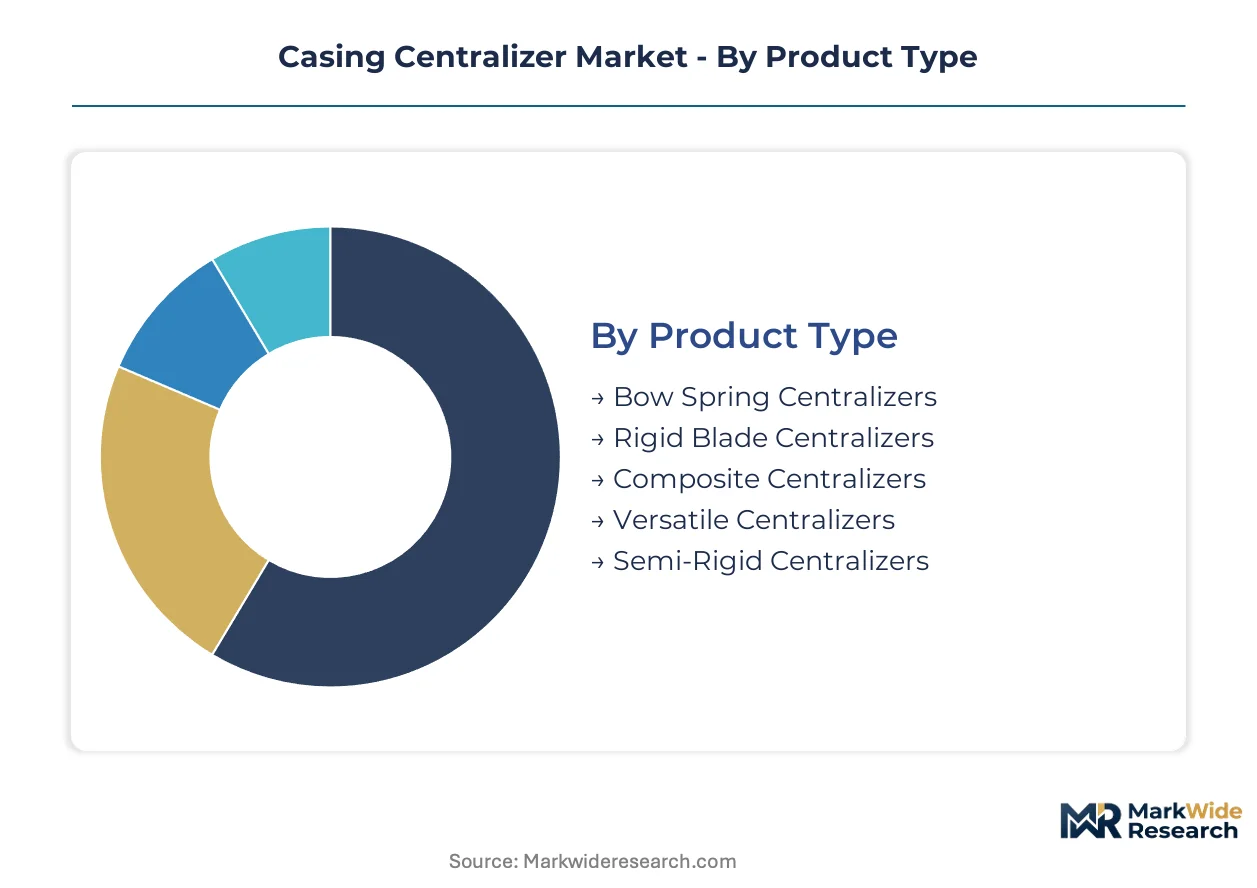
Casing centralizer procurement splits sharply between cost-driven onshore programs and precision-critical offshore developments. Material selection and product architecture determine qualification pathways across API 10D certification tiers and operator specification regimes.
Product Type:
Volume concentrates in bow spring designs for vertical wellbores, while premium margins pool in rigid and composite architectures for extended-reach applications.
- Bow Spring Centralizers:Helical steel or composite bows provide radial restoring force through elastic deformation. Permian Basin operators running standard vertical completions specify these for 20-35 lbf restoring force compliance at unit economics 40% below rigid alternatives.
- Rigid Blade Centralizers:Fixed positive standoff blades machined from solid bar stock deliver 0.125-inch tolerance or tighter. Guyana offshore contractors and North Sea HPHT programs mandate these for cement sheath integrity in high-angle wellbores where standoff variation risks zonal isolation failure.
- Composite Centralizers:Engineered thermoplastic and carbon-fiber designs achieving 60% weight reduction versus steel. Brazil pre-salt and West Africa deepwater casing runs specify these to cut torque and non-productive time.
- Versatile Centralizers:Modular designs allowing bow-spring to rigid conversion through field-adjustable blade inserts. Alaska North Slope and Sakhalin operators value configuration flexibility across seasonal drilling windows.
- Semi-Rigid Centralizers:Hybrid architectures combining flexible bow elements with fixed blade sections. Appalachian Basin gas well completions increasingly specify these for methane emissions compliance in intermediate deviation angles.
Today's leader: Bow Spring Centralizers. Tomorrow's challenger: Composite Centralizers.
Material:
Steel grades dominate procurement tonnage, but aluminum and engineered composites are climbing the fastest as HPHT and extended-reach specifications tighten.
- Steel:Standard carbon and alloy grades forged to API 10D mechanical requirements. Oklahoma and Texas manufacturing clusters supply Permian and Bakken operators under long-term offtake agreements indexed to scrap and alloy input costs.
- Alloy Steel:Chromium-nickel-molybdenum formulations rated for 350°F service temperatures. North Sea and Gulf of Mexico deepwater contractors specify these for HPHT well construction dossier compliance.
- Carbon Steel:Unalloyed grades for low-temperature, low-corrosion onshore environments. Vertical well programs in conventional US basins continue procurement despite API specification tightening on restoring force thresholds.
- Aluminum:Lightweight alloys machined for rigid blade configurations. Norwegian Continental Shelf regulators approve these for documented weight reduction in extended-reach casing strings.
- Composite Materials:Glass-fiber and carbon-fiber reinforced thermoplastics with corrosion immunity. ExxonMobil-operated Stabroek Block developments and Brazil pre-salt contractors specify these for saltwater environment durability.
Steel maintains volume dominance. Composite Materials gain specification priority fastest.
Application:
Onshore drilling absorbs centralizer volume, but offshore and directional segments command qualification premiums and software-bundled service contracts.
- Onshore Drilling:Vertical and low-deviation well construction across Permian, Eagle Ford, and DJ Basin plays. Spot-market procurement persists here, though super-spec lateral programs are shifting toward rigid blade and composite specifications.
- Offshore Exploration:Deepwater and ultra-deepwater casing runs in Brazil, Guyana, and West Africa. Contractors mandate documented centralizer specification in drilling permit submissions to national regulators.
- Directional Drilling:Extended-reach laterals exceeding 15,000 feet measured depth. Torque reduction and placement accuracy drive composite and premium rigid blade adoption.
- Production Wells:Casing repair and recompletion programs. Mature basin operators in California and West Texas specify centralizers for remedial cementing integrity.
- Well Completion:Final casing string installation and primary cementing. EPA methane emissions regulations elevate standoff accuracy to compliance-critical status in gas well completions.
Onshore Drilling anchors volume. Offshore Exploration captures margin expansion.
End User:
Procurement authority concentrates with drilling contractors and oilfield service providers, though national oil companies increasingly mandate approved vendor lists and qualification protocols.
- Exploration Companies:Independent E&P operators specifying centralizers through drilling contracts. Permian independents consolidate supplier relationships into 24-36 month volume commitments with price bands tied to alloy indices.
- Drilling Contractors:Noble, Transocean, and Seadrill specify centralizer architectures in integrated well construction services. These entities bundle hardware procurement with placement software and cementing service packages.
- Oilfield Service Providers:Halliburton, Schlumberger, and Weatherford manufacture or source centralizers for bundled service delivery. Proprietary placement algorithms differentiate hardware-software integration offerings.
- National Oil Companies:Petrobras, Equinor, and Saudi Aramco maintain approved manufacturer lists and mandate API 10D qualification documentation. Brazilian and Norwegian regulators require centralizer specification in drilling permit dossiers.
- Independent Operators:Privately held E&P companies with direct procurement authority. These entities show highest sensitivity to unit price but face EPA emissions compliance pressure in gas-weighted portfolios.
Drilling Contractors and Oilfield Service Providers control procurement flow. National Oil Companies tighten qualification gates fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting centralizer manufacturing toward jurisdictions with streamlined API certification pathways and lower alloy-input cost bases. Brazil and Norway impose the strictest documentation requirements for offshore well construction, while US Gulf Coast states leverage integrated supply chains to defend forged-steel output.
United States
Permian Basin operators in Texas and New Mexico are consolidating procurement into 24-36 month offtake agreements with Oklahoma and Texas manufacturers. EPA methane emissions regulations elevate standoff accuracy to compliance-critical status in Appalachian Basin gas completions. Houston and Oklahoma City manufacturing clusters supply super-spec centralizers for extended-reach laterals exceeding 15,000 feet.
Brazil
Pre-salt deepwater contractors specify composite centralizers to reduce torque and non-productive time during high-cost casing runs in saltwater environments. ANVISA and national petroleum regulator ANP mandate centralizer documentation within well construction dossiers submitted for drilling permit approval. Rio de Janeiro and Macaé service bases concentrate procurement authority for Petrobras-operated developments.
Norway
North Sea HPHT programs demand aluminum-body rigid blade centralizers with documented 0.125-inch standoff tolerance. Norwegian Continental Shelf regulators require centralizer specification in drilling permit submissions, creating compliance-driven specification lock-in. Stavanger and Bergen engineering clusters validate designs for 350°F/20,000 psi service conditions.
Guyana
ExxonMobil-operated Stabroek Block developments generate demand for premium rigid blade centralizers in extended-reach laterals. National petroleum regulator requires API 10D qualification documentation for all casing accessories in offshore permit applications. Georgetown logistics hubs coordinate supply chains for deepwater drilling campaigns.
China
Domestic shale gas operators in Sichuan Basin are adopting composite centralizer designs to cut torque in extended-reach horizontal wells. GB standards and MIIT regulations govern petroleum equipment certification for state-owned operator procurement. Chengdu and Chongqing manufacturing bases supply carbon-steel centralizers for onshore conventional programs.
Casing Centralizer Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue composite material qualification and placement software integration. The market structures around three tiers: integrated service providers with bundled hardware-software offerings, specialized centralizer manufacturers with API 10D certification depth, and regional fabricators competing on alloy-input cost efficiency. Strategic moves concentrate on long-term offtake contracting with Permian operators and backward integration into forged-steel production.
Among US-based integrated service providers, Weatherford and Halliburton anchor the premium tier through manufacturing footprint control across Oklahoma and Texas. Centek Group occupies a position within the specialized manufacturer archetype, with UK-based engineering credentials supporting North Sea HPHT qualification. Summit Casing Equipment and Antelope Oil Tool exemplify regional fabrication specialists competing on delivery reliability for standard bow spring designs.
| Leading Market Players |
|---|
| Weatherford |
| Summit Casing Equipment |
| Halliburton |
| Centek Group |
| NeOz Energy |
| Baker Hughes |
| NOV |
| Antelope Oil Tool |
| SLB |
| Others |
Cost & Logistics Intelligence
Composite centralizer manufacturing migration from forged-steel forging to thermoplastic molding and carbon-fiber layup simultaneously collapses alloy-input exposure and concentrates production capacity among specialized polymer processors with API 10D testing infrastructure. This dual shift fragments pricing power across material tiers while locking supply relationships to qualified testing facilities in Oklahoma, Texas, and Stavanger.
Pricing Analysis
Distributor margins on standard bow spring centralizers compress under long-term offtake agreements that Permian Basin operators negotiate directly with Oklahoma and Texas manufacturers. Three-tier pricing structure across premium rigid blade, standard forged-steel bow spring, and economy carbon-steel designs stratifies by certification depth and placement software bundling. Pricing pressure stems from nickel and chromium volatility squeezing spot-market forged-steel suppliers without alloy hedging. Independent operators in conventional US basins exhibit highest price sensitivity, while ExxonMobil-operated Stabroek Block contractors accept 40-60% premiums for documented standoff tolerance.
Supply Chain Analysis
Alloy steel feedstock for forged centralizers rests on integrated mills in the US Gulf Coast, German Ruhr Valley, and Japanese Chubu region with API-compliant melt chemistry. Chromium-nickel-molybdenum formulations, glass-fiber reinforced thermoplastics, and carbon-fiber prepregs constitute critical input dependencies. Single-source vulnerability concentrates in third-party laboratories capable of validating HPHT-rated designs, with 350°F/20,000 psi testing capacity clustering in Oklahoma and Texas. Distribution runs through drilling contractor procurement networks and oilfield service provider logistics hubs, with national oil companies increasingly mandating approved vendor lists that bypass traditional distributor channels.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The casing centralizer market reads as a late-cycle quality story where API specification tightening and EPA methane emissions liability are concentrating procurement with technically advanced manufacturers capable of documented standoff precision. Premium rigid blade and composite architectures capture expanding margin pools as extended-reach drilling specifications displace commodity bow springs.
For Market Incumbents: Deploy backward integration into forged-steel production to defend margin pools against composite substitution and alloy price volatility. Lock Permian Basin volume through 24-36 month offtake agreements with price bands tied to scrap indices, while investing in HPHT testing infrastructure to capture Norwegian and Brazilian regulatory compliance-driven specification lock-in. For New Entrants and Emerging Players: Oilfield service providers lacking proprietary placement software represent the most penetrable channel partner type for composite centralizer qualification. Target Guyana offshore contractors and Brazil pre-salt drilling programs with thermoplastic designs certified to API 10D restoring force thresholds, leveraging weight reduction and corrosion immunity as differentiated value propositions against legacy steel suppliers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional forged-steel fabricators without long-term offtake coverage or HPHT testing capabilities. Five-to-ten year viability hinges on composite material qualification timelines and API specification revision cycles. Watch ANP and Norwegian Continental Shelf regulator documentation requirements as inflection indicators for compliance-driven vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Permian operators secure volume commitments with Oklahoma-Texas manufacturers to stabilize alloy-input cost exposure. |
| Backward Integration | Forged-steel centralizer producers acquire captive melt capacity to defend margins against nickel-chromium volatility. |
| Technology Licensing | Composite material suppliers partner with established service companies to accelerate API 10D qualification timelines. |
| Joint Venture | Drilling contractors and centralizer manufacturers co-develop placement software bundled with hardware offerings. |
| Green Certification Program | Composite centralizer producers document corrosion immunity and weight reduction for EPA methane emissions compliance positioning. |
Research Approach
Bottom-up drilling program modeling reconciled against top-down manufacturer shipment tracking forms the analytical core of this study. Primary interviews with drilling contractors, oilfield service procurement directors, centralizer manufacturing plant managers, and national oil company technical standards engineers combine with secondary validation from API specification documentation, EPA regulatory filings, ANP and Norwegian Petroleum Directorate drilling permit dossiers, and customs trade data for alloy steel and composite material flows.
Historical trendline analysis of centralizer procurement patterns by product architecture, material grade, and application intensity informs the projection framework across the analysis window. Segmentation dimensions modeled include product type, material composition, application setting, and end-user procurement authority tier. CAGRs derive from fitted growth curves calibrated to drilling activity forecasts, specification revision timelines, and regulatory compliance phase-in schedules for methane emissions and well construction documentation.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to composite material fatigue reliability under cyclic loading and API specification revision cycles that could strand legacy inventory. Forecasts reflect documented assumptions regarding drilling contractor consolidation, national oil company vendor list tightening, and HPHT testing infrastructure expansion. A small set of named triggers—ANP documentation mandate enforcement, EPA methane reporting rule expansion, and composite-to-metal bonding field failure rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Iran Oil and Gas Exploration and Production Market
Oil & Gas
Rotary Steerable System Market
Oil & Gas
Japan AI in Oil and Gas Market
Oil & Gas
Oilwell Completion Tools Market
Oil & Gas
LNG Loading Skid Market
Oil & Gas
Global LNG Liquefaction Terminals Market
Oil & Gas
Global LNG Regasification Terminals Market
Oil & Gas
North America Frac Sand Market
Oil & Gas
Well Test Market
Oil & Gas
Trinidad and Tobago Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Automation and Instrumentation Market
Oil & Gas
Drilling Fluids Market
Oil & Gas
Europe Hydraulic Fracturing Fluids Market
Oil & Gas
Oman Oil and Gas Pipeline Market
Oil & Gas
Oil and Gas Hose Assemblies Market
Oil & Gas
Well Cementing Market