
 Asia-Pacific Small-Scale LNG Market | 2026-2036
Asia-Pacific Small-Scale LNG Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Small-Scale LNG Market Outlook
ISO 8217-compliant marine-grade LNG specifications is unwinding legacy fuel oil infrastructure across Southeast Asian ports. Shell PLC leverages its integrated bunkering network to dominate Singapore-Jakarta shipping lanes. Chart Industries Inc anchors cryogenic storage solutions for remote power installations. TotalEnergies SE extends its liquefaction terminal footprint across Papua New Guinea and Timor-Leste coastal zones.
Asia-Pacific small-scale LNG encompasses liquefaction, regasification, and distribution systems processing under 0.5 million tonnes per annum, typically employing modular skid-mounted units with storage pressures between 4-10 bar for off-grid industrial and marine applications. Regasification units lead installed capacity as archipelagic geographies prioritize fuel-switching flexibility over greenfield liquefaction. Small-scale vessels represent the fastest-expanding segment as dual-fuel engine retrofits multiply across intra-Asian shipping routes. Marine fuel applications command premium margins due to IMO 2020 sulfur compliance deadlines and port authority low-emission mandates.
Australia's NOPSEMA enforces offshore safety standards for floating storage and regasification units, while Japan's METI subsidizes LNG-to-hydrogen transition pilots that preserve gas infrastructure value. China's SAMR implements GB standard certification for small-scale cryogenic equipment, restricting market access for uncertified foreign suppliers. Stakeholders must monitor Indonesia's forthcoming downstream gas regulations and Vietnam's draft LNG terminal licensing framework to anticipate import monopoly relaxations.
Market Dynamics
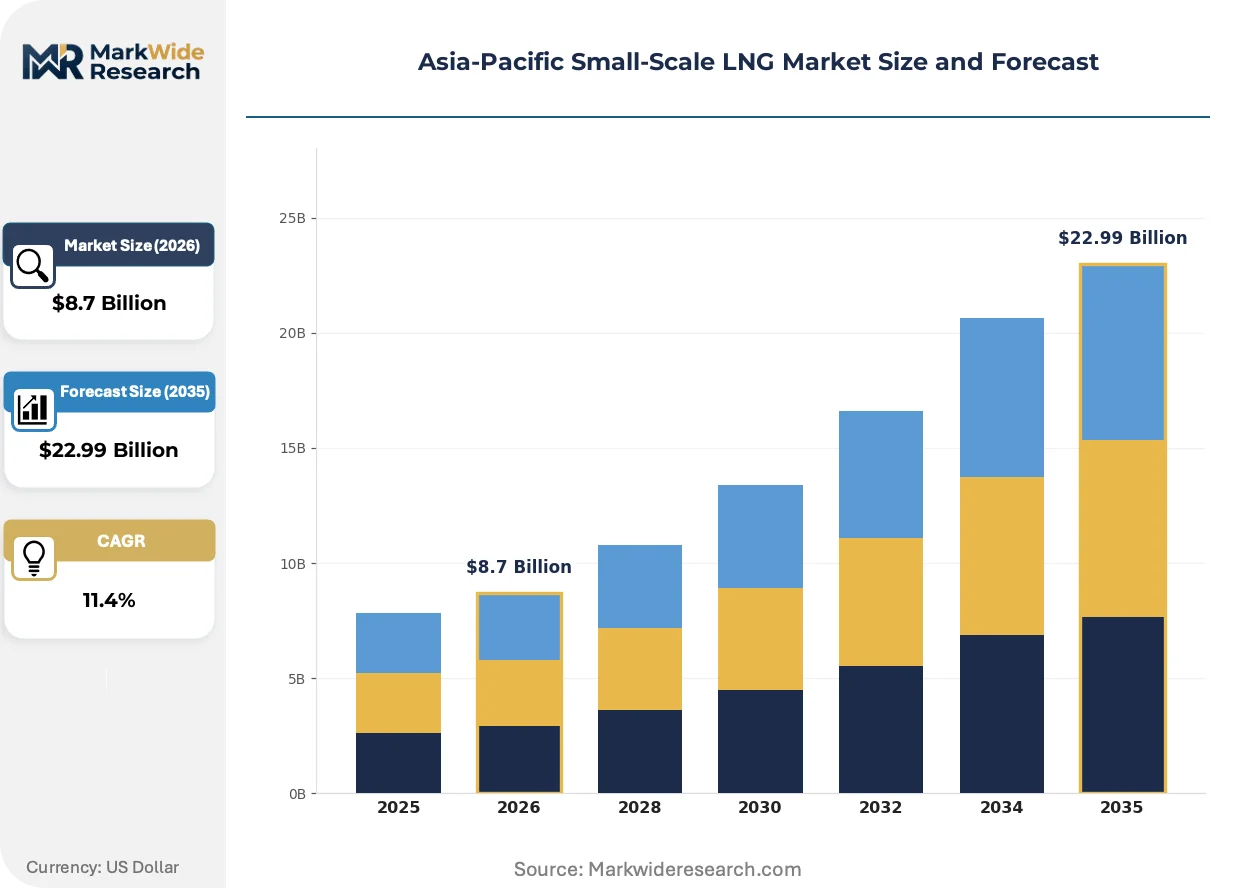
Dual-fuel marine engine retrofits across Indonesian and Philippine archipelagos are compressing payback periods for small-scale LNG infrastructure investments below five years. This hardware transition is pulling capital away from conventional diesel bunkering networks toward modular cryogenic systems.
Growth Catalysts
- IMO 2020 Sulfur Mandates:Port authorities in Singapore, Jakarta, and Ho Chi Minh City enforce low-sulfur fuel requirements that elevate LNG's cost competitiveness against scrubber-fitted heavy fuel oil.
- Japan's METI Hydrogen Co-firing Roadmap:Power utilities retrofit existing LNG receiving terminals for hydrogen blending, preserving gas infrastructure value through 2040 transition timelines.
- Remote Mining Electrification:Western Australia's Pilbara iron ore corridors and Queensland's Bowen Basin coal operations substitute diesel gensets with skid-mounted regasification units.
Market Restraints
- Cryogenic Equipment Import Dependence:China's SAMR GB standard certification restricts uncertified foreign suppliers, concentrating modular liquefaction skid sourcing within domestic manufacturing bases.
- Feedstock Price Volatility:Henry Hub-linked LNG contract structures expose small-scale offtakers to price swings that diesel contracts hedge more effectively.
- Liquefaction Scale Diseconomics:Modular units below 0.5 million tonnes per annum face thermodynamic efficiency penalties that regasification-only configurations avoid.
Strategic Opportunities
- Vietnam's Draft LNG Terminal Licensing:Proposed regulatory frameworks signal import monopoly relaxation, opening coastal power clusters to private small-scale terminal developers.
- Biogas-to-LNG Upgrading:Palm oil mill effluent capture in Malaysia and Indonesia converges with small-scale liquefaction to produce carbon-negative marine fuel.
- Floating Storage and Regasification Unit Leasing:Offshore mining camps and island grids adopt FSRU-as-a-service models that eliminate upfront terminal capex.
Industry Challenges
- Cryogenic Welding Certification Bottlenecks:Australia's NOPSEMA and Japan's ClassNK impose divergent qualification standards that delay project commissioning by 8-14 months.
- Dual-fuel Engine Technician Scarcity:Marine engineering programs across Southeast Asia lack curricula for high-pressure gas injection system maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Small-Scale LNG Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquefaction Terminals, Regasification Units, Small-Scale Vessels, Storage Solutions End User: Industrial Users, Power Plants, Transportation, Domestic Consumers Application: Power Generation, Industrial Heating, Marine Fuel, Backup Supply Distribution Channel: Direct Sales, Distributors, Online Sales, Third-Party Logistics |
| Companies Covered | Wärtsilä Oyj ABP, Gazprom PJSC, Shell PLC, Black & Veatch Corp, Chart Industries Inc, TotalEnergies SE, Eni SpA, Engie SA, Linde plc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Small-Scale LNG Market Strategic Shifts
Modular skid-mounted architecture is collapsing project development timelines from years to months. Equipment standardization and remote monitoring convergence are enabling asset-light entry strategies that reshape competitive economics.
Micro-liquefaction trains utilizing mixed refrigerant cycles are displacing trucked LNG deliveries for stranded gas fields in Papua New Guinea and Timor-Leste. Remote mining operators and island utilities adopt these sub-50 tonne per day units to capture associated gas that flaring regulations previously rendered uneconomic. The technology is displacing long-haul diesel logistics chains across archipelagic supply routes.
Japan's METI subsidizes LNG-to-hydrogen transition pilots that mandate 30% co-firing compatibility in new power plant designs. Equipment suppliers must engineer regasification infrastructure with hydrogen-ready metallurgy and burner retrofits. This regulatory pressure compresses procurement cycles for future-proofed cryogenic systems in Japanese industrial zones.
Power purchase agreements now structure LNG supply as bundled energy-as-a-service rather than commodity offtake. Australian mining houses and Indonesian nickel processors contract for delivered megawatt-hours, transferring volume risk to terminal operators. This model concentrates in Queensland's Gladstone industrial cluster where integrated logistics providers capture margin through fuel-switching optimization.
Asia-Pacific Small-Scale LNG Market Segmentation
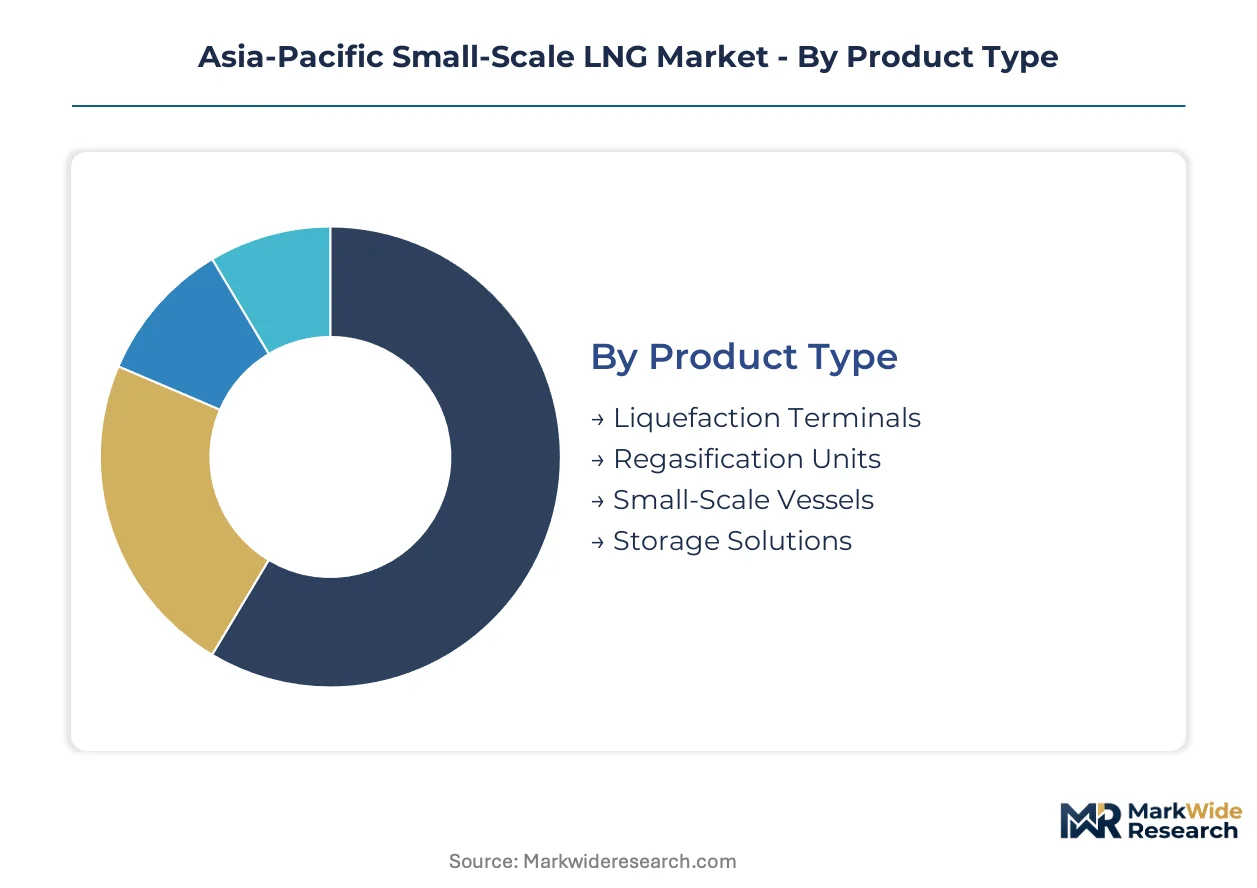
Small-scale LNG infrastructure exhibits divergent deployment patterns across archipelagic versus continental geographies. Equipment specifications and procurement channels vary sharply between Japan's hydrogen-ready retrofits and Indonesia's remote island electrification projects.
Product Type:
Domestic demand concentrates in modular regasification for Australian mining corridors and Japanese power utilities, while export-led growth flows through liquefaction terminals serving Southeast Asian bunkering hubs.
- Liquefaction Terminals:Modular skid-mounted trains below 0.5 million tonnes per annum employ mixed refrigerant cycles for stranded gas capture. Papua New Guinea and Timor-Leste coastal operators deploy these units to monetize associated gas that flaring regulations previously rendered uneconomic.
- Regasification Units:Pressure-rated systems between 4-10 bar dominate installed capacity across archipelagic geographies prioritizing fuel-switching flexibility. Australia's Pilbara iron ore corridors and Queensland's Gladstone industrial cluster substitute diesel gensets with these skid-mounted configurations.
- Small-Scale Vessels:Dual-fuel engine retrofits multiply across intra-Asian shipping routes, compressing payback periods below five years.
- Storage Solutions:Cryogenic tanks anchor remote power installations where Chart Industries Inc holds established supplier relationships.
Regasification Units hold the largest share; momentum sits with Small-Scale Vessels.
End User:
Cost-tier stratification separates premium-grade industrial offtakers from price-sensitive domestic segments, with transportation emerging as the margin-rich intermediate layer.
- Industrial Users:Nickel processors in Indonesia's Morowali corridor and Western Australia's mining houses contract for delivered megawatt-hours through energy-as-a-service structures. These agreements transfer volume risk to terminal operators while guaranteeing baseload fuel supply.
- Power Plants:Japan's METI subsidizes LNG-to-hydrogen transition pilots mandating 30% co-firing compatibility in new designs, preserving gas infrastructure value through extended transition timelines.
- Transportation:Marine fuel bunkering commands premium margins due to IMO 2020 sulfur compliance deadlines and port authority low-emission mandates.
- Domestic Consumers:Off-grid island grids adopt FSRU-as-a-service models that eliminate upfront terminal capital expenditure.
Industrial Users anchor revenue concentration; Transportation gains share fastest.
Application:
Application mix tracks the energy transition hierarchy, with hydrogen-ready power infrastructure commanding procurement priority over legacy industrial heating.
- Power Generation:LNG-to-power retrofits accelerate under Japan's METI hydrogen co-firing mandates, requiring regasification infrastructure with hydrogen-ready metallurgy and burner compatibility.
- Industrial Heating:Queensland's Gladstone industrial cluster and Indonesian nickel smelters substitute diesel and coal with direct-fired gas applications.
- Marine Fuel:ISO 8217-compliant specifications unwind legacy fuel oil infrastructure across Singapore, Jakarta, and Ho Chi Minh City ports.
- Backup Supply:Remote mining camps and island utilities maintain cryogenic storage for grid resilience during diesel supply disruptions.
Power Generation dominates capital deployment; Marine Fuel climbs the fastest.
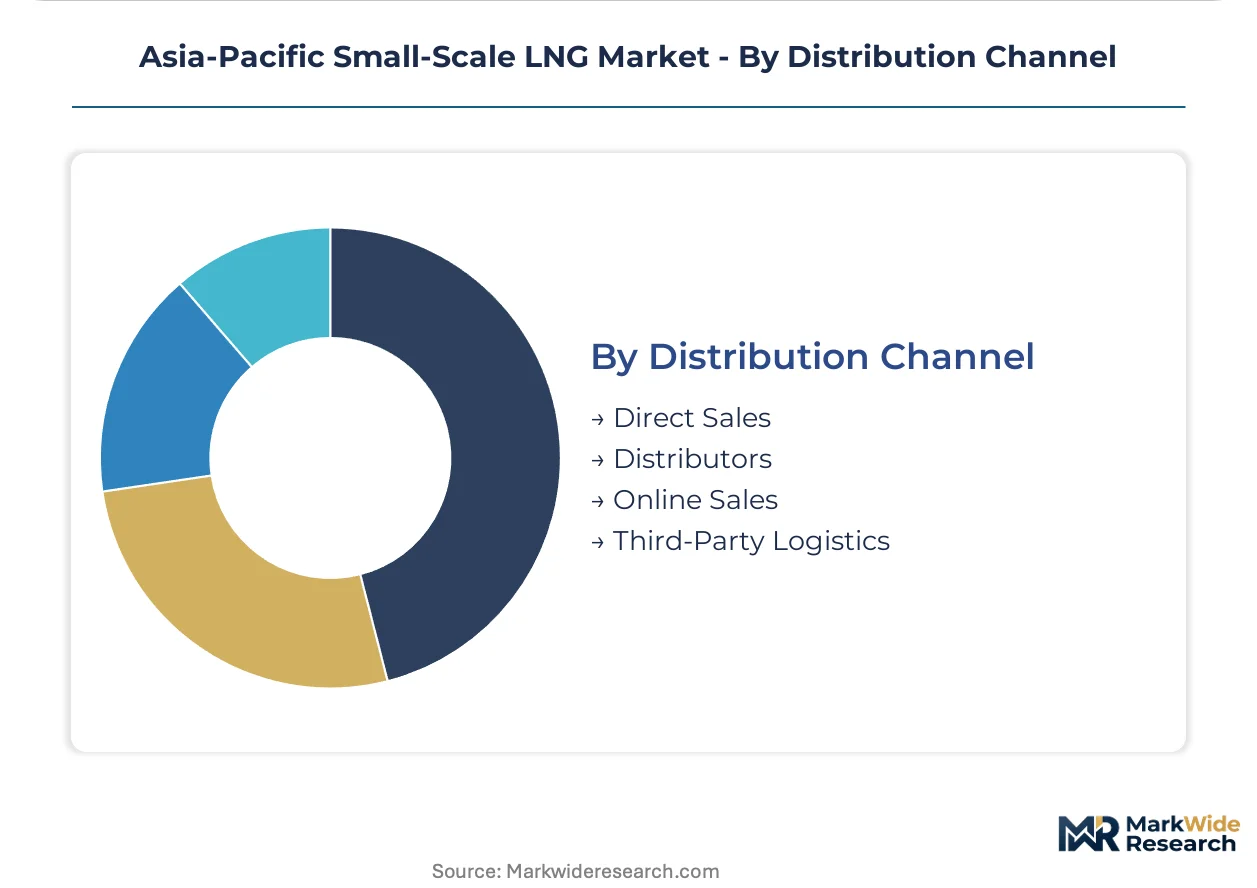
Distribution Channel:
Channel selection reflects customer scale and technical complexity, with integrated logistics providers capturing margin through bundled fuel-switching optimization.
- Direct Sales:Large-scale mining houses and power utilities procure turnkey regasification systems through bilateral negotiations with equipment manufacturers.
- Distributors:Regional intermediaries serve mid-tier industrial offtakers across Vietnam's emerging coastal power clusters.
- Online Sales:Standardized cryogenic components and spare parts move through digital procurement platforms.
- Third-Party Logistics:Specialized handlers manage last-mile LNG delivery to remote archipelagic installations where conventional supply chains fail.
Direct Sales commands the largest transaction value; Third-Party Logistics expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia-Pacific's small-scale LNG trade flows reflect a structural import dependency concentrated in Japan and South Korea, balanced against export-oriented liquefaction capacity emerging across Southeast Asian archipelagos. Australia anchors regional supply through Gladstone and Pilbara infrastructure while serving as a demand center for remote mining electrification.
Japan
Kansai and Chubu power utilities drive regasification demand as METI hydrogen co-firing mandates require 30% blending compatibility in new plant designs. Japan's ClassNK certification standards impose divergent welding qualifications that delay project commissioning. Tokyo Bay industrial clusters retrofit existing LNG terminals to preserve gas infrastructure value through 2040 transition timelines.
Australia
Western Australia's Pilbara iron ore corridors and Queensland's Bowen Basin coal operations substitute diesel gensets with skid-mounted regasification units. NOPSEMA enforces offshore safety standards for floating storage and regasification units that complicate deployment timelines. Gladstone's industrial cluster concentrates energy-as-a-service contracting where integrated logistics providers capture margin through fuel-switching optimization.
Indonesia
Marine fuel bunkering operations across the archipelagos compress payback periods for small-scale LNG infrastructure below five years. Downstream gas regulations under revision signal potential import monopoly relaxations that would open coastal power clusters to private terminal developers. Morowali's nickel processing corridor contracts for delivered megawatt-hours through bundled supply agreements.
China
SAMR implements GB standard certification for small-scale cryogenic equipment that restricts market access for uncertified foreign suppliers. Yangtze River Delta manufacturing bases concentrate modular liquefaction skid production under domestic sourcing mandates. Dual carbon goals accelerate LNG-to-power retrofits in coastal industrial zones previously dependent on coal-fired generation.
Vietnam
Draft LNG terminal licensing frameworks propose regulatory structures that would relax state import monopolies and enable private small-scale terminal development. Coastal power clusters from Haiphong to Ho Chi Minh City prioritize fuel-switching flexibility over greenfield liquefaction. Port authority low-emission mandates elevate LNG cost competitiveness against scrubber-fitted heavy fuel oil in marine applications.
Asia-Pacific Small-Scale LNG Market Competitive Environment
Concentration sits with integrated energy majors possessing liquefaction terminal footprints and bunkering network density. The vendor base stratifies across three tiers: global oil majors with integrated supply chains, specialized cryogenic equipment fabricators, and regional logistics providers capturing last-mile margins. Strategic moves center on FSRU-as-a-service model expansion and hydrogen-ready metallurgy retrofits that future-proof existing regasification assets.
Within the integrated major tier, Shell PLC and TotalEnergies SE exemplify archetypes combining bunkering network control with coastal liquefaction terminal ownership. Chart Industries Inc occupies a position among specialized cryogenic fabricators anchoring remote power installations through storage solution relationships. Wärtsilä Oyj ABP represents the equipment-technology intersection where dual-fuel engine retrofits multiply across intra-Asian shipping routes.
| Leading Market Players |
|---|
| Wärtsilä Oyj ABP |
| Gazprom PJSC |
| Shell PLC |
| Black & Veatch Corp |
| Chart Industries Inc |
| TotalEnergies SE |
| Eni SpA |
| Engie SA |
| Linde plc |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts with Henry Hub-linked pricing lock in supply access for Australian mining houses and Japanese power utilities while exposing small-scale offtakers to commodity volatility that diesel contracts hedge more effectively. These contractual structures concentrate pricing power with integrated terminal operators who bundle regasification capacity with delivered energy-as-a-service.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across Queensland's Gladstone cluster and Western Australia's Pilbara corridors. Price differentiation stems from volume scale and IMO 2020 sulfur compliance certification tiers. Pricing pressure stems from feedstock volatility linked to Henry Hub benchmarks. Domestic consumers in Indonesian archipelagos exhibit highest price sensitivity; marine bunkering operators show lowest.
Supply Chain Analysis
Malacca Strait transit underwrites LNG cargo movements from Qatar and Australia to Southeast Asian bunkering hubs. Cryogenic equipment sourcing concentrates in China's Yangtze River Delta manufacturing bases, Japan's precision engineering corridors, and South Korea's shipbuilding clusters. Supply chain risk centers on SAMR GB standard certification bottlenecks that restrict uncertified foreign suppliers. Distribution runs through integrated logistics providers capturing last-mile margins to remote mining camps and island grids.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dual-fuel marine engine retrofits across Indonesian and Philippine archipelagos constitute a high-growth disruption accelerated by IMO 2020 enforcement and port authority low-emission mandates.
For Market Incumbents: Consolidate cryogenic equipment certification advantages under China's SAMR GB standards and Australia's NOPSEMA offshore safety frameworks to exclude uncertified foreign competitors. Deepen backward integration into modular liquefaction skid production within Yangtze River Delta manufacturing bases. Capture margin through FSRU-as-a-service models that eliminate upfront capex for remote mining operators. For New Entrants and Emerging Players: Lead with hydrogen-ready metallurgy retrofits for Japan's METI-subsidized LNG-to-hydrogen transition pilots requiring 30% co-firing compatibility. Target Vietnam's draft LNG terminal licensing frameworks signaling import monopoly relaxation. Pursue biogas-to-LNG upgrading from palm oil mill effluent in Malaysia and Indonesia as carbon-negative marine fuel positioning. For Investors and Strategic Acquirers: Specialized cryogenic fabricators with established supplier relationships to remote power installations represent prime acquisition targets for integrated energy majors seeking bunkering network density. Long-term viability hinges on hydrogen infrastructure transition timelines preserving gas asset value through 2040. Monitor Indonesia's forthcoming downstream gas regulations as inflection indicator for import monopoly relaxation.| Strategic Initiative | Industry Significance |
|---|---|
| FSRU-as-a-Service Expansion | Eliminates upfront terminal capex for Australian mining camps and Indonesian island grids. |
| Hydrogen-Ready Metallurgy Retrofit | Preserves gas infrastructure value under Japan's METI 30% co-firing mandates. |
| Biogas-to-LNG Upgrading | Captures carbon-negative marine fuel premiums from Malaysian palm oil effluent. |
| Modular Liquefaction Capacity Buildout | Monetizes stranded associated gas in Papua New Guinea and Timor-Leste coastal zones. |
| Dual-Fuel Engine Technician Certification | Addresses scarcity of high-pressure gas injection maintenance skills across Southeast Asia. |
Study Parameters
A standing panel of LNG terminal operators, EPC contractors, marine fuel procurement officers, and cryogenic equipment fabricators provided ongoing calibration against project commissioning timelines and feedstock cost structures. Primary interviews with utility planning officers at Kansai and Chubu power utilities, IPP project developers in Vietnam's coastal power clusters, and aftermarket service heads at dual-fuel engine retrofit yards were cross-referenced against secondary sources including EIA data, IEA marine fuel reports, FERC small-scale terminal filings, and project development databases. Bottom-up capacity installation tracking was triangulated with top-down trade flow analysis.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include infrastructure type (liquefaction, regasification, vessels, storage), end-use sector (industrial, power, transportation, domestic), application (power generation, industrial heating, marine fuel, backup supply), and regional regulatory framework. CAGRs were derived from installation capacity trajectories and offtake contract velocity. Industry-specific inputs incorporated IMO 2020 sulfur compliance deadlines, METI hydrogen co-firing roadmap milestones, and SAMR certification pipeline status.
The analysis sits within stated boundaries; outcomes outside sustained IMO enforcement, stable Henry Hub pricing, and unimpeded Malacca Strait transit would require recalibration. Forecasts reflect documented assumptions regarding dual-fuel engine retrofit penetration rates and modular liquefaction technology cost curves. Practitioners should keep alternative scenarios live as Indonesia's downstream gas regulations and Vietnam's terminal licensing frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
North America Oil Storage Market
Oil & Gas
India LNG Bunkering Market
Oil & Gas
Oil and Gas Processing Seals Market
Oil & Gas
Digital Oilfield Services Market
Oil & Gas
Azerbaijan Oil and Gas Downstream Market
Oil & Gas
Asia Pacific Upstream Oil and Gas Services Market
Oil & Gas
Digital Oilfield Solutions Market
Oil & Gas
Oil Breather Tank Market
Oil & Gas
Large Scale LNG Terminal Market
Oil & Gas
Europe Coiled Tubing Market
Oil & Gas
Bunker Liners Market
Oil & Gas
Egypt Natural Gas Market
Oil & Gas
Oil and Gas Pipeline Management Software Market
Oil & Gas
Mexico Wireline Services Market
Oil & Gas
Nigeria Wireline Logging Services Market
Oil & Gas
Asia-Pacific Oilfield Auxiliary Rental Equipment Market