
 China LNG Bunkering Market | 2026-2036
China LNG Bunkering Market Size, Share, and Industry Trends Forecast 2026-2036
China LNG Bunkering Market Outlook
China's coastal port infrastructure expansion is tilting investment toward LNG bunkering terminals along the Bohai Rim and Yangtze River Delta. PetroChina leverages its integrated upstream gas position to secure feedstock for marine fuel operations. Sinopec anchors downstream distribution through its coastal refinery network and terminal partnerships. CNOOC competes via its LNG import terminal portfolio, converting regasification capacity into bunkering supply points.
LNG bunkering denotes the transfer of liquefied natural gas, stored cryogenically at minus 162 degrees Celsius, to vessels for propulsion or auxiliary power generation. The process requires specialized cryogenic hoses, vapor return systems, and strict safety protocols to prevent boil-off gas release during transfer. Ship-to-ship delivery dominates operational deployment for deepwater container routes, while truck-to-ship methods occupy coastal feeder networks where permanent infrastructure remains limited. Emergency supply services sustain premium pricing during port congestion events, whereas scheduled supply contracts lock in volume commitments from freight operators.
MEE enforces sulfur emission control areas at Shanghai, Shenzhen, and Tianjin ports, compelling vessel operators to switch from heavy fuel oil to LNG. GB standards issued by SAMR specify cryogenic equipment certification and bunkering procedure harmonization across provincial maritime jurisdictions. The PLI scheme subsidizes domestic LNG equipment manufacturing, reducing import dependency for critical cryogenic pumps and transfer arms. Stakeholders must monitor MEE's expansion of emission control zones beyond current coastal clusters to inland river ports.
Market Dynamics
MEE's sulfur emission control areas at Shanghai, Shenzhen, and Tianjin ports are compressing the compliance timeline for vessel operators, redirecting capital from scrubber retrofits toward LNG propulsion systems and shore-based bunkering infrastructure.
Growth Catalysts
- Dual carbon goals:China's national emissions reduction framework under MEE oversight mandates sulfur caps at coastal ports, compelling container lines to convert fleets.
- Yangtze River Delta concentration:Dense container traffic along this corridor creates economies of scale for truck-to-ship bunkering networks.
- GB standards harmonization:SAMR-issued cryogenic equipment certification rules reduce jurisdictional friction across provincial maritime authorities.
Market Restraints
- LNG price volatility:Feedstock costs tied to global spot markets expose bunkering operators to margin compression during supply shocks.
- Import terminal concentration:Coastal regasification capacity clusters in state-controlled port zones, limiting third-party supplier entry.
- Cryogenic infrastructure gap:Inland river ports lack permanent storage tanks, forcing reliance on truck-to-ship methods with higher unit costs.
Strategic Opportunities
- Pearl River Delta expansion:Shenzhen's emission control zone creates demand for ship-to-ship bunkering in deepwater anchorages.
- PLI scheme subsidies:Domestic manufacturing incentives for cryogenic pumps and transfer arms reduce equipment import dependency.
- Bohai Rim terminal conversion:Existing LNG import facilities at Tianjin and Dalian offer ready feedstock access for marine fuel operations.
Industry Challenges
- Cryogenic technician shortage:Specialized training for minus 162 degrees Celsius handling operations lags fleet conversion timelines.
- Multi-jurisdictional certification:Provincial maritime authorities apply divergent safety inspection protocols, delaying operational permits.
- Legacy fuel system incompatibility:Dual-fuel engine retrofits require extensive hull modifications, extending drydock periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China LNG Bunkering Market |
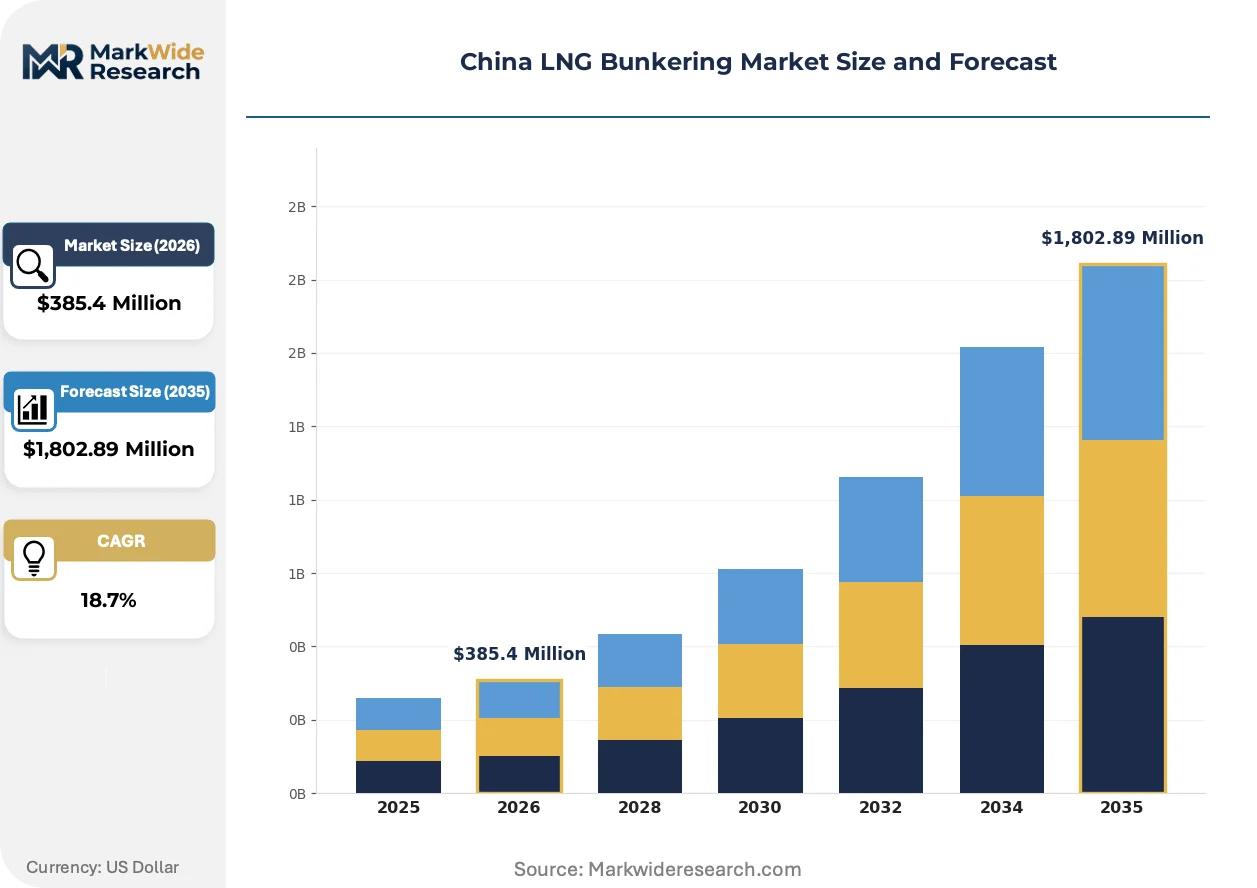
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,802.89 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Mode: Truck-to-Ship, Ship-to-Ship, Port Facility, Barge Delivery Ship Type: Container Vessels, Bulk Carriers, Tankers, Ferries Service Type: Regular Supply, Emergency Supply, On-Demand Supply, Scheduled Supply End User: Shipping Companies, Freight Operators, Port Authorities, Vessel Owners |
| Companies Covered | ENN Energy Holdings Ltd, PetroChina, Sinopec, CNOOC, CHIMBUSCO, TotalEnergies, Shell, JERA Co Inc, Gazprom, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China LNG Bunkering Market Strategic Shifts
Digital bunkering coordination platforms and automated cryogenic transfer systems are compressing port turnaround times while MEE tightens emissions monitoring protocols at coastal clusters.
Type-C tank independent fuel systems are rendering obsolete traditional cylindrical LNG storage configurations in newbuild container vessels. Yangtze River feeder operators are specifying these compact tanks to maximize cargo hold volume. The technology is rendering obsolete older bunker barge designs that cannot accommodate pressure-rated containment.
MEE's expansion of sulfur emission control areas beyond coastal ports to inland river terminals is forcing fleet operators to accelerate LNG conversion timelines. Container lines now face compliance deadlines at Wuhan and Chongqing anchorages previously exempt from heavy fuel oil bans. The regulation is compressing retrofit schedules for mid-size bulk carriers operating Yangtze corridor routes.
Freight operators are consolidating fuel procurement under multi-year LNG supply contracts with state-owned terminal operators, displacing spot market purchases. Container shipping lines operating Shanghai-Shenzhen routes are locking in volume commitments to secure berth priority during port congestion. This concentration is visible among Pearl River Delta feeder services where scheduled bunkering dominates emergency supply calls.
China LNG Bunkering Market Segmentation
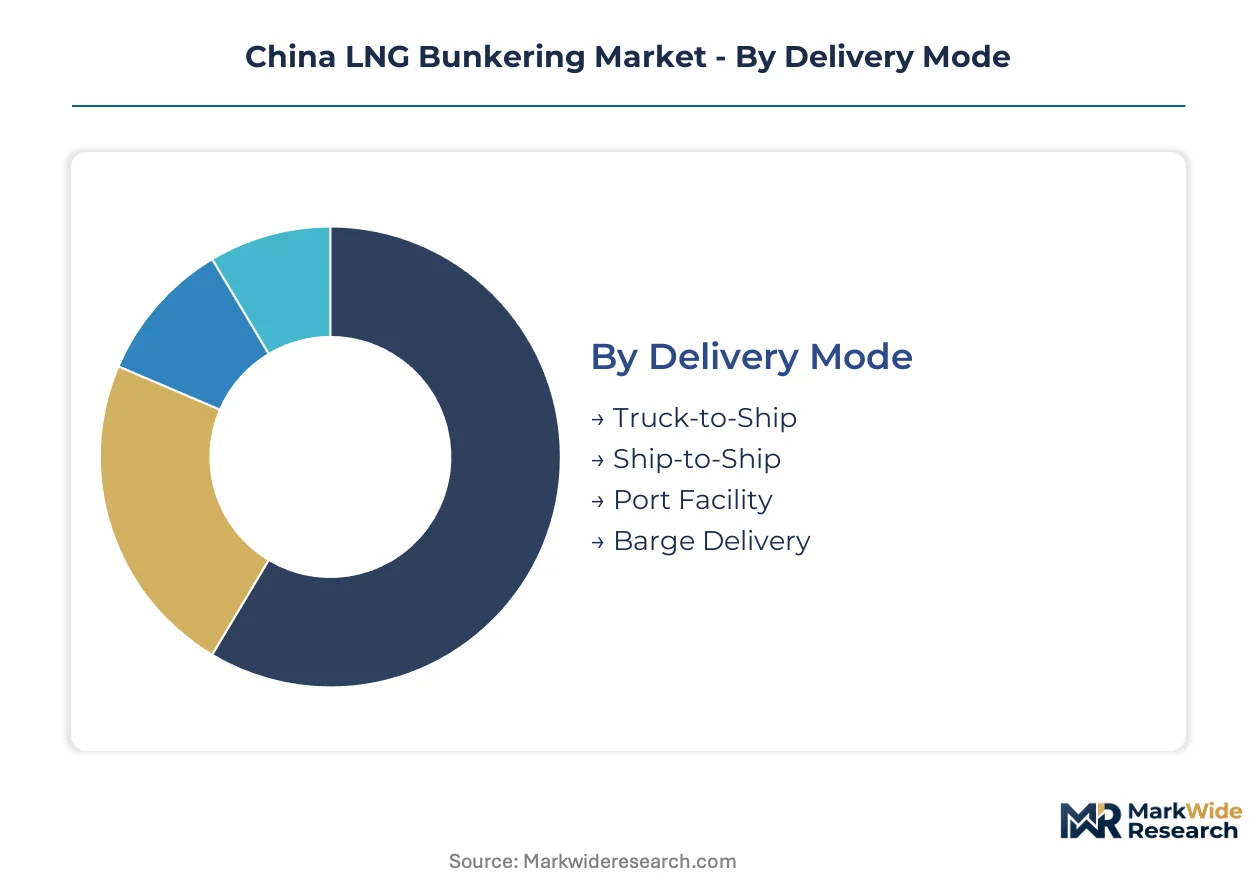
LNG bunkering service intensity varies sharply across operational modes, with cryogenic equipment maintenance and emergency response protocols demanding differentiated after-sales support structures. Segment boundaries reflect infrastructure maturity rather than fuel chemistry, creating divergent margin profiles across coastal versus inland deployment.
Delivery Mode:
After-sales service intensity peaks with permanently installed port infrastructure, where cryogenic pump maintenance contracts and vapor recovery system calibration generate recurring revenue streams distinct from mobile delivery methods.
- Truck-to-Ship:Mobile cryogenic tanker trucks transfer LNG via articulated loading arms at anchorage points lacking fixed infrastructure. Yangtze River feeder operators rely on this method at Wuhan and Chongqing anchorages where permanent storage tanks remain absent, though higher per-unit costs compress margins during spot price spikes.
- Ship-to-Ship:Dedicated bunker barges equipped with cryogenic containment systems deliver fuel alongside deepwater container vessels. Shanghai and Shenzhen anchorages concentrate demand here, with MEE emission control zone enforcement accelerating barge fleet expansion along coastal corridors.
- Port Facility:Fixed shore-based terminals integrate LNG storage with direct vessel connection systems. Tianjin's converted import terminal infrastructure anchors this segment in the Bohai Rim.
- Barge Delivery:Flat-deck barges with ISO tank containers serve intermittent demand at secondary ports. Pearl River Delta feeder networks deploy these for scheduled replenishment at smaller anchorages.
By volume, Ship-to-Ship leads. By growth pace, Truck-to-Ship is ahead.
Ship Type:
Cost tier segmentation separates deepwater container fleets with capital for dual-fuel retrofits from coastal bulk operators managing tighter conversion timelines.
- Container Vessels:Large boxships operating Shanghai-Shenzhen routes specify Type-C independent fuel tanks to maximize cargo hold volume. MEE sulfur caps at core ports compel these operators to lock in multi-year supply contracts with state terminal operators.
- Bulk Carriers:Mid-size dry bulk operators on Yangtze corridor routes face compressed retrofit schedules as emission controls reach Wuhan and Chongqing. Legacy hull designs require extensive drydock modification for dual-fuel engine compatibility.
- Tankers:Product carriers with established cargo heating systems adapt cryogenic infrastructure more readily than dry cargo segments.
- Ferries:Coastal passenger operators in Bohai Rim port clusters convert first due to predictable route structures and shorter capital recovery periods.
Container Vessels dominate absolute consumption. Bulk Carriers are climbing the fastest as inland river compliance deadlines tighten.
Service Type:
Customer procurement patterns stratify between freight operators seeking volume certainty through scheduled contracts and spot-market participants absorbing congestion premiums.
- Regular Supply:Fixed-interval replenishment agreements with defined berth windows. Major container lines operating Yangtze River Delta corridors favor this structure to secure priority during port congestion events.
- Emergency Supply:Unscheduled call-outs during route deviations or consumption forecasting errors. Premium pricing applies, though MEE monitoring protocols reduce unplanned emissions excursions that previously triggered urgent demand.
- On-Demand Supply:Ad-hoc procurement without volume commitments. Smaller vessel owners lacking credit relationships with terminal operators default to this tier.
- Scheduled Supply:Long-term contracts with annual volume minimums and price indexation clauses. State-owned terminal operators concentrate procurement here, displacing spot market liquidity.
Scheduled Supply locks in the largest volumes. Emergency Supply shows the steepest expansion trajectory as fleet conversion outpaces infrastructure deployment.
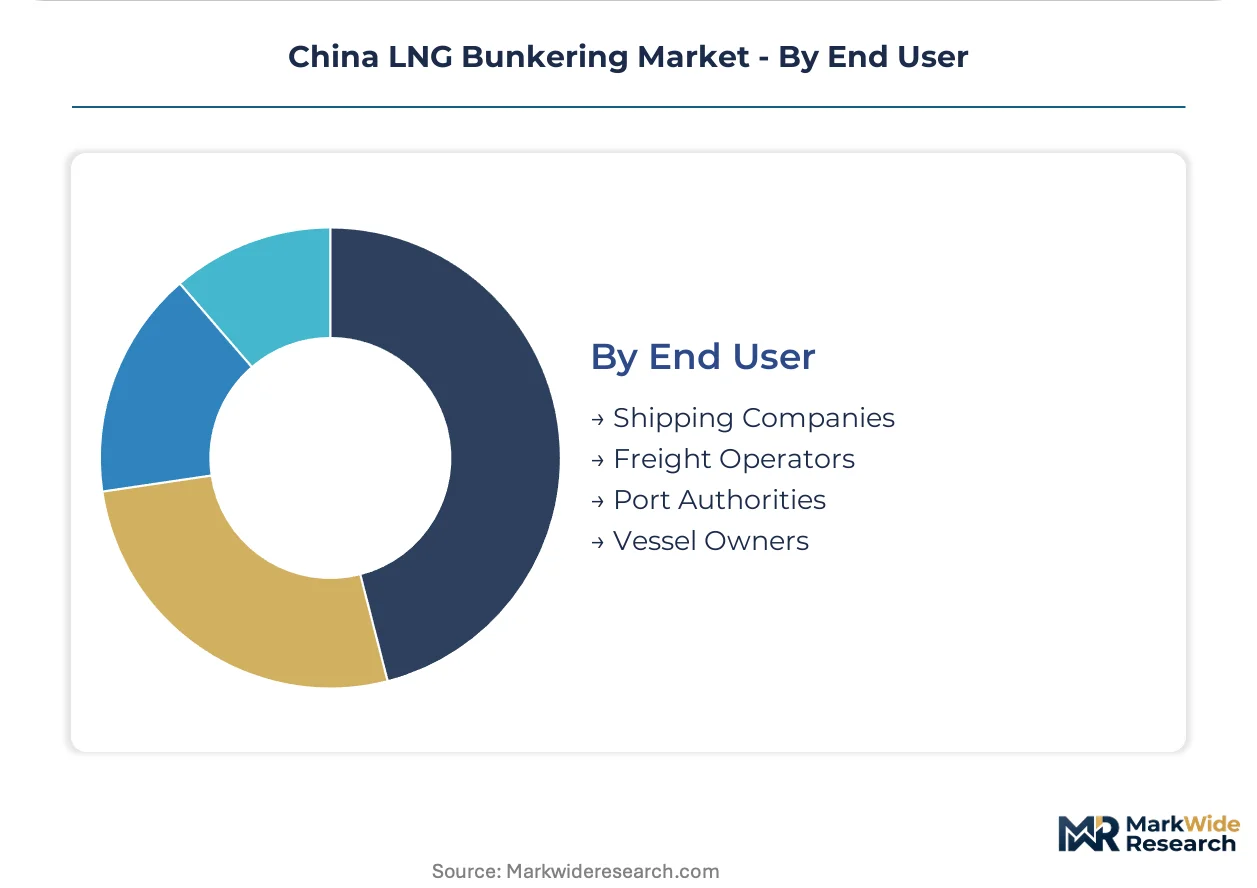
End User:
Supply concentration tilts toward integrated shipping groups with direct terminal access, while fragmented vessel ownership structures persist among coastal feeder operators.
- Shipping Companies:Integrated liner operators with owned fleets and established credit facilities. These entities negotiate directly with PetroChina and Sinopec for bunkering rights at import terminals.
- Freight Operators:Non-asset logistics providers chartering vessel capacity. Their fuel procurement aggregates across multiple carriers, limiting individual negotiation leverage.
- Port Authorities:Municipal maritime administrations mandating fuel quality standards and berth allocation protocols. Shanghai and Shenzhen port authorities influence supplier qualification through safety certification requirements.
- Vessel Owners:Independent shipowners operating single vessels or small fleets. This segment relies on third-party fuel procurement agents and truck-to-ship networks at secondary ports.
Shipping Companies anchor procurement volume. Port Authorities are gaining share fastest as MEE delegates enforcement infrastructure to local maritime administrations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feedstock access concentrates along coastal import corridors where regasification terminals anchor marine fuel supply chains. State-controlled port zones limit third-party entry while MEE emission mandates compress retrofit timelines for vessel operators.
Yangtze River Delta
Shanghai's deepwater anchorages concentrate container traffic requiring ship-to-ship bunkering services. MEE sulfur emission control areas at core ports compel fleet conversions. Wuhan and Chongqing anchorages now face compliance deadlines previously limited to coastal clusters.
Pearl River Delta
Shenzhen's emission control zone drives demand for scheduled supply contracts among feeder operators. GB standards harmonization across Guangdong provincial jurisdictions reduces certification friction. Guangzhou and Zhuhai port clusters anchor barge delivery networks for secondary anchorages.
Bohai Rim
Tianjin's converted LNG import terminal infrastructure anchors fixed shore-based bunkering capacity. Dalian port authorities mandate fuel quality standards through safety certification requirements. Coastal ferry operators in this corridor convert first due to predictable route structures.
Beijing-Tianjin-Hebei
Industrial port demand concentrates at Caofeidian and Huanghua anchorages serving bulk carrier traffic. Dual carbon goals under MEE oversight accelerate shore power and LNG fuel substitution mandates. Truck-to-ship methods dominate where permanent storage tanks remain absent.
Shandong Peninsula
Qingdao and Yantai ports anchor cryogenic equipment maintenance contracts for regional vessel fleets. SAMR-issued certification rules standardize transfer arm specifications across maritime jurisdictions. Independent vessel owners rely on third-party fuel procurement agents at these secondary ports.
China LNG Bunkering Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream. The vendor base stratifies between state-owned energy majors with terminal access and international trading houses with global LNG portfolios. Three archetypes dominate: upstream-integrated suppliers leveraging captive feedstock, downstream distributors anchoring coastal refinery networks, and international traders arbitraging spot market positions. Competitive moves concentrate on terminal partnership formation and multi-year supply contract aggregation.
Among state-controlled energy majors, PetroChina, Sinopec, and CNOOC exemplify the upstream-integrated archetype. These entities occupy positions where regasification terminal ownership translates directly into bunkering supply point control. PetroChina represents the feedstock security model through integrated gas field operations. Sinopec anchors downstream distribution scale via coastal refinery network density. CNOOC sits within the import terminal conversion strategy, repurposing receiving capacity for marine fuel deployment. International trading houses including Shell and TotalEnergies compete via portfolio diversification across global LNG supply chains rather than fixed infrastructure control.
| Leading Market Players |
|---|
| ENN Energy Holdings Ltd |
| PetroChina |
| Sinopec |
| CNOOC |
| CHIMBUSCO |
| TotalEnergies |
| Shell |
| JERA Co Inc |
| Gazprom |
| Others |
Value Chain & Pricing Dynamics
Global LNG price volatility tethered to spot market fluctuations compresses margin buffers for bunkering operators while simultaneously dictating supply chain configuration toward state-controlled terminal zones. This feedstock cost exposure widens pricing tier spreads between scheduled contract volumes and emergency spot purchases, concentrating procurement leverage within integrated energy majors possessing captive regasification capacity.
Pricing Analysis
MEE sulfur emission control area enforcement dictates the pricing tier structure across coastal port clusters. Three-tier pricing structure across premium, standard, and economy levels separates scheduled supply contracts with berth priority from on-demand spot purchases and emergency call-outs during congestion events. Price differentiation hinges on volume commitment scale and cryogenic equipment certification tier under SAMR-issued GB standards. Cost compression in the emergency supply tier is intensifying because fleet conversion timelines outpace barge infrastructure deployment. Independent vessel owners operating Yangtze River feeder routes exhibit highest price sensitivity, while integrated container lines with direct PetroChina terminal access absorb premium positioning for berth certainty.
Supply Chain Analysis
Extended payment terms from state-owned terminal operators anchor working capital structures for third-party logistics providers serving fragmented vessel ownership segments. Geographic supply concentration centers on Qatar, Australia, and Malaysia as primary LNG feedstock origins, with regasification capacity clustering at Tianjin, Shanghai, and Shenzhen port zones. Raw material dependencies encompass cryogenic pumps, vapor return arms, and Type-C tank containment systems subject to PLI scheme domestic manufacturing incentives. Single-source vulnerability persists for specialized minus 162 degrees Celsius handling equipment where certified technician pools remain shallow. Distribution runs through state-controlled import terminal gatekeeping, limiting independent supplier participation to truck-to-ship mobile networks at secondary anchorages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against methanol and ammonia marine fuel alternatives gaining regulatory traction under MEE's evolving emissions framework. Incumbents must secure feedstock optionality while infrastructure investments remain recoverable within dual carbon goal timelines.
For Market Incumbents: Pre-empt terminal partnership saturation by converting existing LNG import infrastructure at Dalian and Qingdao into dedicated bunkering supply points before competitor lock-in. Secure backward integration into cryogenic equipment manufacturing through PLI scheme qualification to reduce transfer arm import dependency. Anchor multi-year supply contracts with Yangtze River Delta container lines now, before Wuhan and Chongqing compliance deadlines force emergency procurement fragmentation.
For New Entrants and Emerging Players: Establish a beachhead in truck-to-ship services at inland river ports lacking permanent storage infrastructure, specifically Wuhan and Chongqing anchorages facing imminent MEE emission control expansion. Target independent bulk carrier operators on Yangtze corridor routes with equipment-leasing bundled fuel procurement, addressing the cryogenic technician shortage constraining fleet conversions. Differentiate through digital bunkering coordination platforms compressing port turnaround times versus state-owned operator scheduling rigidity.
For Investors and Strategic Acquirers: Regional cryogenic logistics specialists with established SAMR certification relationships and mobile tanker fleet assets represent priority acquisition targets. Long-term viability rests on feedstock access security through state terminal partnership depth rather than spot market arbitrage capability. Monitor MEE emission control zone expansion announcements as inflection indicators for infrastructure deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Terminal Infrastructure Conversion | Repurposing Tianjin and Dalian LNG import terminals anchors fixed shore-based bunkering capacity for Bohai Rim demand. |
| Cryogenic Equipment Manufacturing Scale-Up | PLI scheme qualification for domestic pump and transfer arm production reduces import dependency under SAMR GB standards. |
| Multi-Year Supply Contract Aggregation | Scheduled volume commitments with PetroChina and Sinopec secure berth priority for container lines during port congestion. |
| Inland River Network Expansion | Truck-to-ship deployment at Wuhan and Chongqing captures MEE compliance deadline acceleration beyond coastal clusters. |
| Digital Coordination Platform Development | Automated bunkering scheduling compresses turnaround times while MEE tightens emissions monitoring protocols. |
Study Parameters
A standing panel of bunker barge operators, cryogenic equipment maintenance directors, port authority fuel quality inspectors, and container line fleet procurement managers provided ongoing calibration across primary interview cycles. Secondary validation drew from MEE emission control zone announcements, SAMR GB standards documentation, China Customs LNG import statistics, and state-owned energy major annual disclosures. Bottom-up vessel fleet conversion timelines and top-down terminal capacity expansion announcements were triangulated to anchor volume projections.
Scenario-bracketing across feedstock price volatility bands and MEE regulatory expansion pacing shaped the analytical framework across the analysis window. Segmentation dimensions modeled encompass delivery mode infrastructure maturity, vessel type retrofit complexity, service type procurement pattern, and end-user credit facility access. CAGRs were derived from terminal utilization trajectories and fleet orderbook specifications for dual-fuel propulsion systems. Industry-specific forecast inputs included PLI scheme subsidy phase-out schedules and cryogenic technician training pipeline capacity.
Stress conditions across global LNG spot price spikes, MEE emission zone acceleration, and cryogenic equipment import disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding state terminal access continuity and dual carbon goal enforcement intensity. Macroeconomic deviation, regulatory timeline shift, or alternative marine fuel technology breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Renewable Fuel Quality and Regulatory Compliance Test Instruments Market
Fuels
UAE Chemical Logistics Market
Fuels
South America Commercial Aircraft Aviation Fuel Market
Fuels
Germany Bunker Fuel Market
Fuels
Global Methane Hydrate Market
Fuels
Oil Dispenser Market
Fuels
China Bunker Fuel Market
Fuels
Marine Fuel Optimization Market
Fuels
Coal Liquefaction Market
Fuels
United States Bunker Fuel Market
Fuels
China LNG Market
Fuels
Brazil LNG Market
Fuels
Gas Pooling Mechanism Market
Fuels
Wood Pellet Market
Fuels
Europe Gas Market
Fuels
Gasoline Octane Improvers Market