
 Downhole Motor Market | 2026-2036
Downhole Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Downhole Motor Market Insights
Independent directional drilling contractors is rotating toward premium mud motor fleets as operators push longer lateral lengths in unconventional basins. Schlumberger Limited dominates high-temperature motor engineering through its integrated drilling services division. Baker Hughes Company anchors North American aftermarket support with extensive repair and rental infrastructure. Weifang Shengde competes on manufacturing scale, supplying standardized positive displacement motors to Asian oilfield service distributors.
A downhole motor is a drilling tool positioned above the drill bit that converts hydraulic or electrical energy into mechanical rotational force, typically operating at torque outputs exceeding 10,000 lb-ft in modern high-performance configurations. The device enables directional steering, extended-reach drilling, and improved rate of penetration in vertical and deviated wellbores. Positive displacement motors retain the largest installed base due to proven reliability in abrasive drilling environments, while rotary steerable systems command premium pricing by eliminating slide-drilling inefficiencies. Electrical technology segments are gaining traction in geothermal applications where precise temperature management proves critical.
API, ISO, and NORSOK standards govern material certification, pressure testing, and operational safety for downhole motor deployment across offshore and onshore jurisdictions. EPA venting regulations and OSHA drilling safety mandates in the United States compel operators to specify motors with enhanced seal integrity and reduced failure rates. Stakeholders must monitor evolving methane performance standards and assess motor fleet compatibility with automated drilling platforms before committing capital to new equipment procurement.
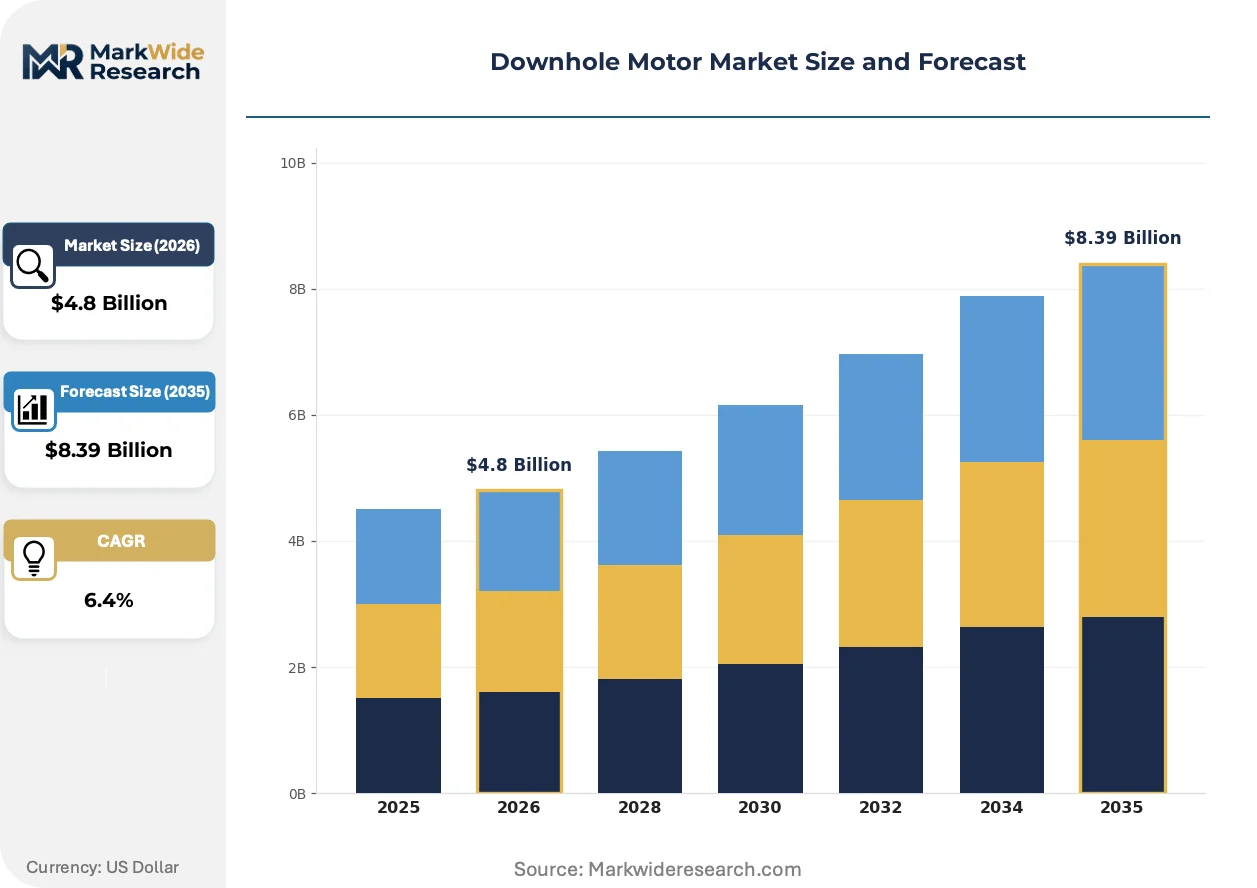
Market Dynamics
Directional drilling contractors face mounting pressure to extend lateral reach beyond 15,000 feet while maintaining rate of penetration, forcing capital rotation toward higher-torque positive displacement motor configurations and integrated power section designs.
Growth Catalysts
- Extended-reach horizontal drilling:Unconventional operators in the Permian Basin and Middle Eastern tight formations mandate longer laterals, expanding procurement of high-performance mud motors capable of sustained torque delivery.
- API specification 7-1 compliance:Material certification requirements for downhole equipment are tightening, advantaging suppliers with in-house metallurgy capabilities and certified manufacturing processes.
- Geothermal energy expansion:Electrical submersible motor technology is penetrating high-temperature geothermal drilling applications where precise thermal management proves critical.
Market Restraints
- Power section elastomer supply concentration:Specialized nitrile and hydrogenated nitrile rubber formulations for motor stators concentrate among a limited supplier base, creating input vulnerability.
- Rotary steerable substitution:Integrated rotary steerable systems are capturing premium drilling contracts by eliminating slide-drilling inefficiencies, compressing addressable demand for conventional positive displacement motors.
- OSHA drilling safety mandates:Enhanced seal integrity requirements and failure-rate reduction specifications are extending qualification timelines and elevating compliance costs for motor deployment.
Strategic Opportunities
- Automated drilling platform integration:Motor fleet compatibility with autonomous rig systems represents an underdeveloped configuration layer, with early movers capturing preferred vendor status.
- Aftermarket service unbundling:Independent repair and rental infrastructure for power section refurbishment is consolidating, creating channel control opportunities outside OEM networks.
- EPA methane performance standards:Enhanced motor seal designs that reduce fugitive emissions during drilling operations align with emerging regulatory thresholds and operator ESG commitments.
Industry Challenges
- Power section design engineering talent:Specialized expertise in elastomer formulation and rotor-stator geometry optimization remains scarce, constraining product development velocity.
- ISO 10424-1 certification timelines:Pressure testing and operational safety validation protocols are extending product qualification cycles, delaying revenue recognition for new motor configurations.
- Legacy rig fleet integration:Compatibility friction between advanced high-torque motors and older top-drive systems is complicating field deployment and requiring custom adapter engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Downhole Motor Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Positive Displacement, Rotary Steerable Systems, Mud Motors, Adjustable Speed Motors Application: Oil Extraction, Gas Production, Geothermal Applications, Water Well Drilling Technology: Electrical, Hydraulic, Mechanical, Pneumatic End User: Oilfield Services, Exploration Companies, Consulting Firms, Research Institutions |
| Companies Covered | National Oilwell Varco Inc., Weifang Shengde, Schlumberger Limited, NOV Inc., Abaco Drilling, Baker Hughes Company, Weatherford International plc, Hunting PLC, Halliburton Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Downhole Motor Market Trends and Innovations
Downhole motor engineering is pivoting toward modular power section architectures and intelligent torque monitoring systems that enable predictive maintenance and real-time drilling optimization.
High-temperature elastomer compounds rated above 350°F are displacing conventional nitrile formulations in geothermal and deep unconventional applications. Operators in the Permian Basin and Saudi Arabian tight gas fields are specifying these materials for extended motor life in abrasive environments. The shift is compressing replacement cycle frequency and elevating supplier technical qualification barriers.
EPA venting regulations and OSHA drilling safety mandates are compelling motor specification changes toward enhanced seal integrity designs. These requirements are elevating capital allocation toward qualification testing and material traceability systems. North American onshore operators are responding fastest, embedding compliance documentation into procurement workflows.
Rental and service-based contracting is displacing outright equipment purchase in North American unconventional drilling. Independent directional drilling contractors are consolidating aftermarket relationships, unbundling repair and refurbishment from original equipment supply. The Permian Basin and Bakken formations exhibit the most pronounced shift toward performance-based motor utilization models.
Downhole Motor Market Segmentation
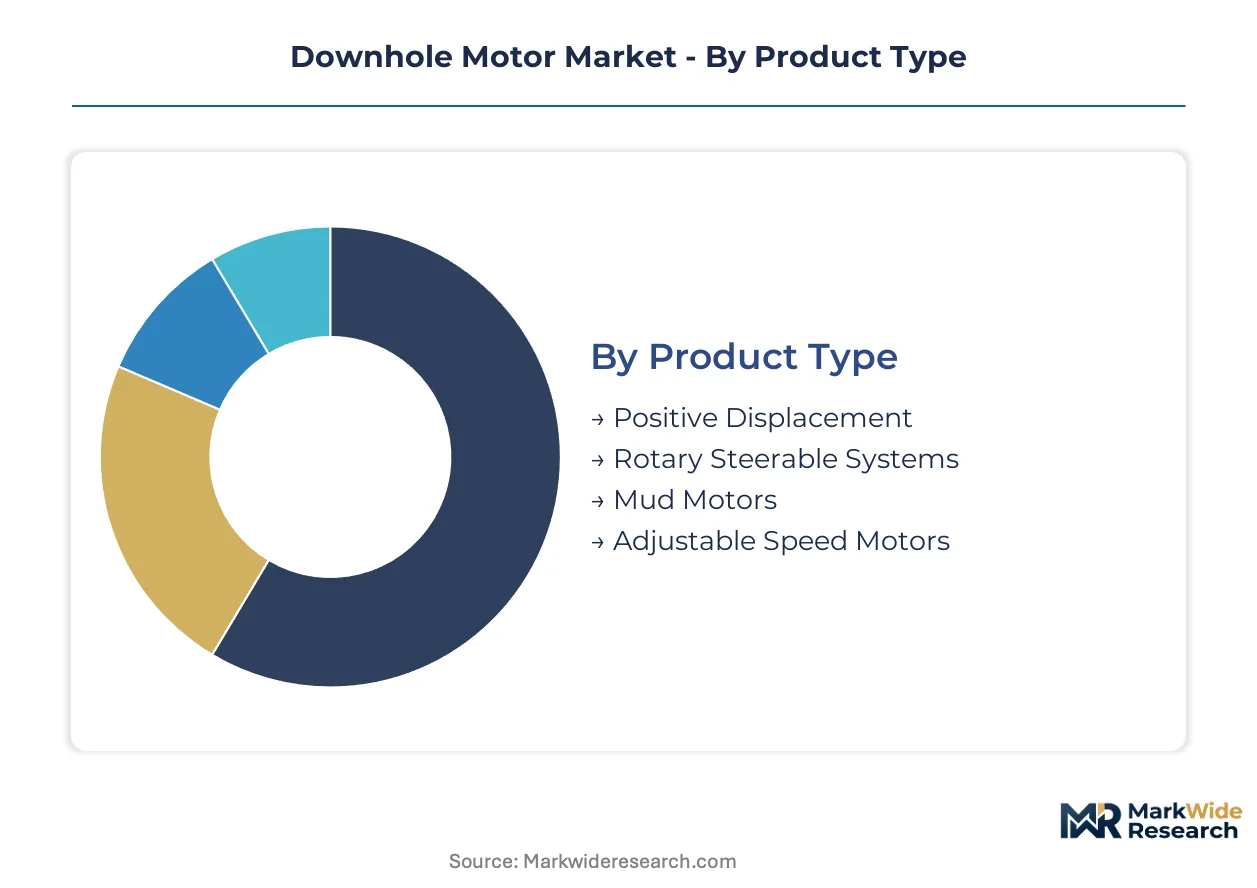
Downhole motor procurement decisions hinge on torque specifications, thermal ratings, and directional complexity. Regulatory compliance tiers across API, ISO, and NORSOK standards create material certification barriers that segment supplier capabilities and end-user access.
Product Type:
API specification 7-1 and ISO 10424-1 material certifications stratify this category, with certified manufacturers commanding premium positioning in high-temperature applications.
- Positive Displacement:These motors convert hydraulic pressure into rotational force through rotor-stator interaction, achieving torque outputs exceeding 10,000 lb-ft. Demand concentrates in Permian Basin extended-reach horizontal wells where abrasive formations require proven reliability and contractors prioritize fleet standardization.
- Rotary Steerable Systems:Integrated systems eliminate slide-drilling inefficiencies through continuous rotation and real-time steering. Saudi Arabian tight gas fields and North American unconventional operators specify these for laterals beyond 15,000 feet, though capital intensity limits deployment to premium drilling contracts.
- Mud Motors:Standardized positive displacement configurations dominate rental fleets across North American onshore markets.
- Adjustable Speed Motors:Variable frequency designs are gaining traction in geothermal drilling where precise rotational control manages thermal stress.
Established volume favors Positive Displacement; emerging adoption favors Rotary Steerable Systems.
Application:
Cost tier differentiation separates capital-intensive unconventional projects from regulated utility-scale deployment.
- Oil Extraction:Directional drilling in tight formations demands sustained torque delivery and extended motor life. Middle Eastern national oil companies and Permian Basin independents anchor procurement, with EPA venting regulations and OSHA safety mandates elevating seal integrity specifications.
- Geothermal Applications:Electrical submersible motors rated above 350°F penetrate high-temperature drilling where precise thermal management proves critical. Operators in Iceland, Turkey, and Kenya specify these for renewable energy expansion, though specialized elastomer supply concentration creates input vulnerability.
- Gas Production:Extended-reach drilling in shale formations drives demand for high-torque configurations.
- Water Well Drilling:Standardized mud motors serve municipal and agricultural contractors with lower specification thresholds.
Revenue concentration sits with Oil Extraction; steepest expansion trajectory belongs to Geothermal Applications.
Technology:
Customer type segmentation separates integrated service companies from independent contractors with varying capital access.
- Hydraulic:Positive displacement and mud motor architectures dominate through proven field reliability. Contractors across Texas, Oklahoma, and North Dakota specify hydraulic systems for abrasive environments where maintenance simplicity outweighs efficiency trade-offs.
- Electrical:Submersible motor technology enables precise speed control and real-time diagnostics. Geothermal operators in Indonesia and the Philippines adopt these for high-temperature reservoirs, though power electronics complexity elevates qualification timelines.
- Mechanical:Turbine-based systems retain niche deployment in straight-hole vertical drilling.
- Pneumatic:Compressed-air motors serve specialized mining and water well applications with limited hydrocarbon penetration.
Installed base dominance favors Hydraulic; technology transition momentum favors Electrical.
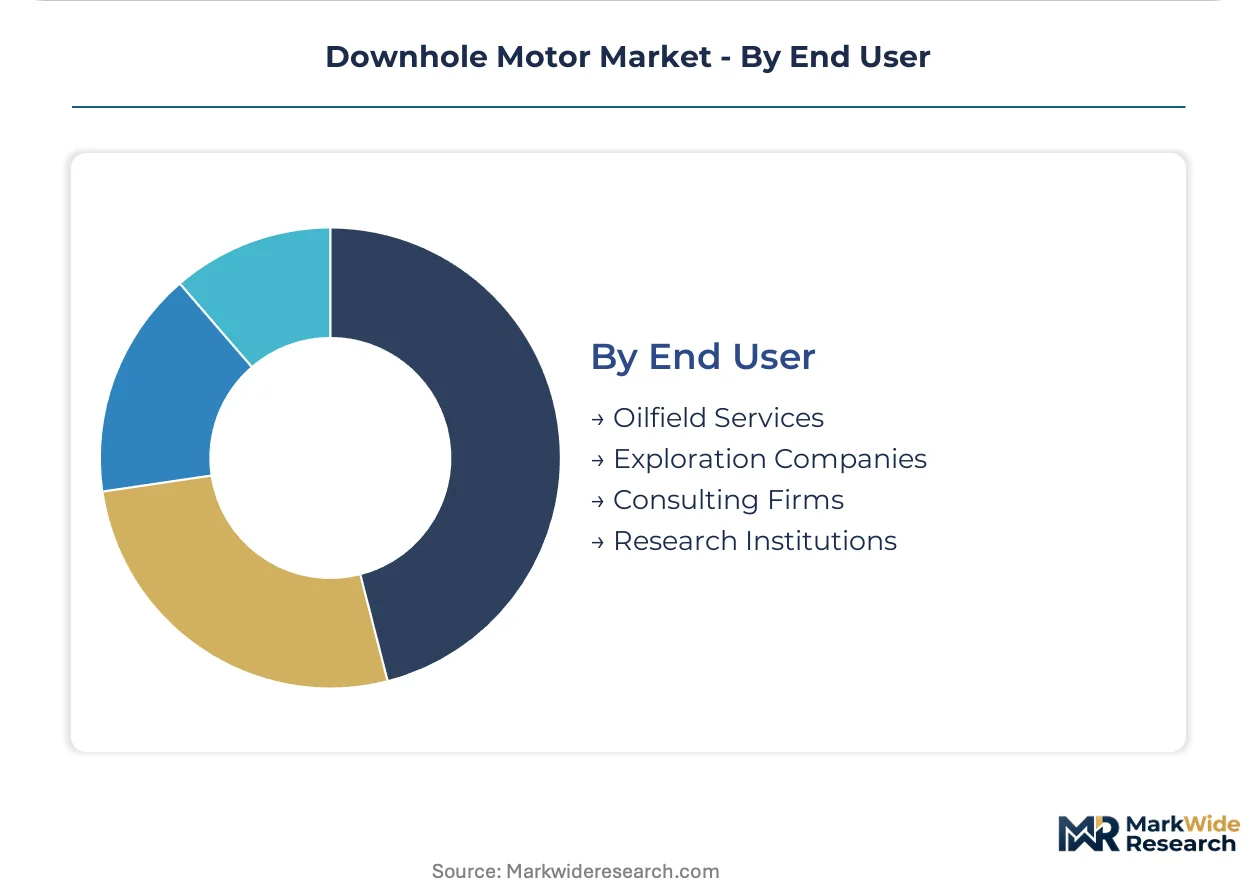
End User:
Supply concentration among OEM networks versus independent aftermarket channels shapes procurement flexibility and cost structure.
- Oilfield Services:Schlumberger, Baker Hughes, and Halliburton anchor integrated drilling services with captive motor fleets. These operators specify API-certified equipment for international contracts, with repair and refurbishment infrastructure creating vendor lock-in.
- Exploration Companies:Independent producers in the Permian Basin and Bakken formations unbundle motor procurement from drilling contracts. Rental and performance-based utilization models are displacing outright purchase, compressing capital deployment timelines.
- Consulting Firms:Technical advisors influence specification standards for national oil company tenders.
- Research Institutions:Universities and government laboratories test advanced elastomer formulations and rotor geometries.
Channel control concentrates with Oilfield Services; procurement flexibility expands fastest among Exploration Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel pipeline network anchors North American energy logistics, while the Saudi Master Gas System and China's West-East Gas Pipeline shape procurement corridors for downhole equipment across their respective domains.
United States
Permian Basin operators in Texas and New Mexico are extending lateral lengths beyond 15,000 feet, mandating high-torque positive displacement motor procurement. EPA venting regulations and OSHA drilling safety mandates compel enhanced seal integrity specifications across onshore fleets. Midland-Odessa service yards concentrate aftermarket refurbishment capacity for independent directional drilling contractors.
Saudi Arabia
Saudi Aramco's tight gas development in the South Ghawar field drives demand for rotary steerable systems capable of sustained high-temperature operation. The national oil company's In-Kingdom Total Value Add program mandates local content thresholds for downhole equipment procurement. Dhahran's industrial corridor hosts service facilities for integrated drilling contractors operating under long-term production agreements.
China
Sinopec and PetroChina are expanding shale gas development in the Sichuan Basin, rotating procurement toward standardized mud motor configurations. GB standards and MIIT equipment certification protocols govern material traceability for domestic manufacturing. Weifang's manufacturing cluster supplies positive displacement motors to Asian oilfield service distributors at scale-driven price points.
United Arab Emirates
ADNOC's offshore sour gas expansion at the Hail and Ghasha fields requires high-temperature motor engineering for corrosive environments. The national oil company's ICV certification program elevates local supplier qualification barriers for downhole equipment. Jebel Ali's free zone logistics hub channels imported motor assemblies to drilling contractors across the Middle East and North Africa.
Norway
Equinor's Johan Sverdrup and Northern Lights projects sustain demand for electrically actuated subsea drilling systems with integrated motor packages. NORSOK standards and PSA drilling facility regulations enforce material certification and pressure testing protocols for offshore deployment. Stavanger's technology corridor concentrates engineering expertise for high-pressure high-temperature motor development.
Downhole Motor Market Competitive Landscape
Concentration sits with integrated oilfield service conglomerates that control captive motor fleets and aftermarket infrastructure. The vendor base stratifies across three tiers: full-service drilling contractors with in-house manufacturing, specialized motor engineering houses, and regional fabrication shops serving rental markets. Consolidation pressure is accelerating through OEM acquisition of independent power section suppliers, while technology licensing agreements proliferate between Western engineering groups and Asian manufacturing platforms.
Within the integrated services tier, Schlumberger Limited and Baker Hughes Company anchor global positioning through drilling services divisions that specify internally developed motor configurations. Weifang Shengde occupies a scale-driven position among Chinese fabricators supplying standardized positive displacement motors to regional distributors. Halliburton Company represents the diversified energy services archetype with motor fleet integration across North American unconventional basins.
| Leading Market Players |
|---|
| National Oilwell Varco Inc. |
| Weifang Shengde |
| Schlumberger Limited |
| NOV Inc. |
| Abaco Drilling |
| Baker Hughes Company |
| Weatherford International plc |
| Hunting PLC |
| Halliburton Company |
| Others |
Pricing and Supply Chain Analysis
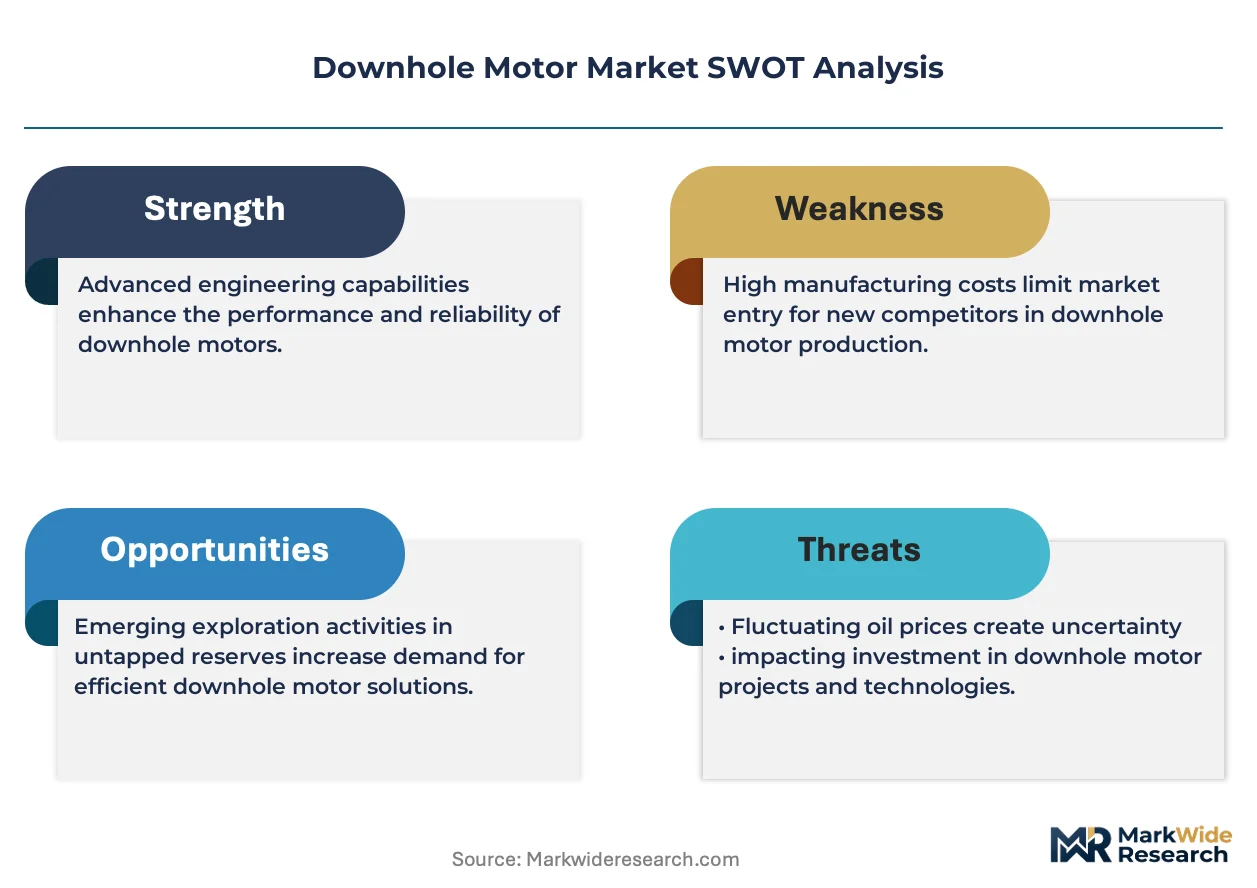
API specification 7-1 certification gates both supplier qualification and price differentiation simultaneously, compressing market access for uncertified fabricators while elevating premium positioning for metallurgy-capable manufacturers serving Permian Basin operators and Middle Eastern national oil companies.
Pricing Analysis
Volume-discount tiering structures separate procurement contracts for integrated oilfield services from spot-market rentals by independent directional drilling contractors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales bundling intensity. Pricing pressure stems from rotary steerable substitution compressing conventional positive displacement motor margins. Exploration companies exhibit highest price sensitivity; Saudi Aramco and ADNOC long-term production agreements anchor least-sensitive demand.
Supply Chain Analysis
Power section inventory cycles stretch 12-16 weeks for specialized nitrile and hydrogenated nitrile rubber formulations, constraining rapid fleet scaling for Permian Basin contractors. Manufacturing concentrates in China, United States, and Norway. Raw material dependencies center on elastomer compounds, high-grade steel alloys, and precision-machined rotor components. Single-source vulnerability concentrates in stator elastomer supply. Distribution runs through OEM captive networks and independent rental yards across Midland-Odessa and Dhahran industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The downhole motor market is recovering from cyclical lows as unconventional drilling activity rebounds and geothermal energy expansion opens adjacent demand channels.
For Market Incumbents: Compound aftermarket service density through power section refurbishment infrastructure in the Permian Basin and Bakken formations. Deepen backward integration into elastomer formulation to offset supply concentration risk. Capture preferred vendor status with automated drilling platform integrators before specification standards crystallize.
For New Entrants and Emerging Players: API specification 7-1 fast-track certification enables rapid qualification for geothermal electrical submersible motor segments where incumbent presence remains thin. Target Iceland, Turkey, and Kenya high-temperature drilling contractors with performance-based rental models. Partner with Asian manufacturing platforms to compress qualification timelines.
For Investors and Strategic Acquirers: EPA methane performance standards reshape the acquisition landscape toward seal-integrity engineering capabilities. Five-to-ten-year viability favors targets with ISO 10424-1 certification infrastructure and geothermal temperature rating expansion. Monitor rotary steerable adoption curves as inflection signal for conventional motor addressable demand compression.
| Strategic Initiative | Industry Significance |
|---|---|
| API Certification Investment | API specification 7-1 qualification opens access to Saudi Aramco and ADNOC tender pipelines. |
| Power Section Refurbishment Network | Aftermarket infrastructure in Midland-Odessa captures rental fleet standardization momentum. |
| High-Temperature Elastomer R&D | 350°F-rated compounds penetrate geothermal applications in Iceland and Kenya. |
| Automated Platform Integration | Motor fleet compatibility with autonomous rig systems secures preferred vendor positioning. |
| Local Content Partnership | In-Kingdom Total Value Add compliance enables Saudi Aramco contract participation. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across directional drilling contractors, oilfield service procurement managers, power section engineering leads, and aftermarket refurbishment specialists. Secondary validation drew from API certification registries, EPA enforcement disclosures, OSHA incident databases, and customs trade records for downhole equipment. Bottom-up motor fleet sizing and top-down drilling activity projections were triangulated to anchor volume estimates.
Across the analysis window, the forecasting framework modeled product type, application, technology, and end-user segmentation dimensions. CAGRs were derived from drilling intensity projections and equipment replacement cycle analysis. Inputs included Permian Basin lateral length extension curves, Saudi tight gas development timelines, and geothermal capacity expansion announcements.
Decision-makers should treat outputs as directional under base assumptions of regulatory stability and unconventional drilling economics; material deviation in oil price or EPA methane enforcement stringency would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas EPC Market
Oil & Gas
Europe Well Intervention Market
Oil & Gas
Canada Oil and Gas Upstream Market
Oil & Gas
Digital Oil Rigs Market
Oil & Gas
Thailand Oil and Gas Upstream Market
Oil & Gas
Australia Oil and Gas Market
Oil & Gas
Land Drilling Rig Market
Oil & Gas
Norway Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Downhole Cables Market
Oil & Gas
Oil and Gas Data Management Market
Oil & Gas
United States Liner Hanger System Market
Oil & Gas
US Sand Control Systems Market
Oil & Gas
Oil and Gas Nuclear Magnetic Resonance Market
Oil & Gas
Europe Oil and Gas Drones Market
Oil & Gas
Africa Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Asia-Pacific Well Intervention Market