
 Small Scale LNG (SSLNG) Market | 2026-2036
Small Scale LNG (SSLNG) Market Size, Share, and Industry Trends Forecast 2026-2036
Small Scale LNG (SSLNG) Market Insights
Marine bunkering is repositioning the Small Scale LNG demand profile as vessel operators switch from heavy fuel oil to LNG for compliance with IMO 2020 sulfur limits. Shell plc leverages its integrated bunkering network across Rotterdam, Singapore, and Jacksonville to capture this shift. Wärtsilä Corporation specializes in dual-fuel engine retrofits that anchor its equipment sales to shipyards in Northern Europe. Chart Industries, Inc. dominates cryogenic storage tank manufacturing, extending its product line to modular regasification skids for port operators.
Small Scale LNG denotes liquefied natural gas handled in volumes typically below 0.5 million tonnes per annum, stored at minus 162 degrees Celsius in vacuum-insulated tanks and distributed via purpose-built carriers or ISO containers to off-grid consumers. Its primary purpose is to deliver pipeline-quality gas to industrial facilities, power plants, and marine vessels lacking conventional grid access. Storage Tanks and Regasification Units command the largest capital allocation within product type segments, as terminal developers prioritize asset durability over speed of deployment. The Marine end user category outpaces Power Generation in growth velocity, driven by European and Asian port authorities mandating LNG-ready infrastructure.
The International Maritime Organization enforces sulfur content limits that directly expand SSLNG bunkering demand at major transshipment hubs. EPA and MEE regulations on stationary source emissions tighten eligibility for onshore diesel generators, redirecting industrial offtake toward LNG microgrids in the United States and China. Stakeholders must monitor how port authorities in Japan, South Korea, and Germany sequence infrastructure tenders, as timing mismatches between storage availability and vessel fleet conversion will determine regional margin capture.
Market Dynamics
IMO 2020 sulfur caps are restructuring marine fuel procurement patterns, forcing transshipment hubs to install LNG bunkering infrastructure ahead of fleet conversion timelines. Port authorities in Japan, South Korea, and Germany now sequence storage tenders against vessel retrofit schedules.
Growth Catalysts
- EU F-Gas Regulation:The regulation accelerates cryogenic storage technology upgrades across European coastal facilities, mandating lower-emission insulation systems for new terminal builds.
- Marine bunkering demand:Ship operators switching from heavy fuel oil to LNG for IMO 2020 compliance are repositioning procurement patterns at Rotterdam, Singapore, and Jacksonville.
- Industrial microgrids:EPA and MEE emissions rules on stationary diesel generators redirect industrial offtake toward LNG-powered distributed generation in the United States and China.
Market Restraints
- Cryogenic equipment concentration:Vacuum-insulated tank manufacturing concentrates among a limited supplier base, creating bottleneck risks for modular regasification skid deployment.
- Regulatory timing friction:Port infrastructure tender sequencing in Japan and South Korea often misaligns with vessel fleet conversion schedules, compressing margin capture windows.
- Heavy fuel oil residual demand:Scrubber retrofits on existing vessels preserve bunker fuel demand at major hubs, delaying full LNG transition economics for some operators.
Strategic Opportunities
- Japan port infrastructure:METI-backed investments concentrate demand for SSLNG import terminals, creating first-mover advantages for storage and regasification providers.
- Dual-fuel engine convergence:Integration of LNG bunkering systems with battery-hybrid propulsion opens retrofit opportunities at Northern European shipyards.
- ISO container distribution:Purpose-built carriers and standardized containers enable off-grid industrial supply chains previously unreachable by pipeline infrastructure.
Industry Challenges
- Cryogenic engineering talent scarcity:Specialized expertise in minus 162-degree Celsius system design remains concentrated among legacy industrial gas specialists, constraining project execution velocity.
- Terminal certification complexity:Multi-jurisdictional approval processes for coastal LNG facilities extend development timelines beyond conventional hydrocarbon storage projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Scale LNG (SSLNG) Market |
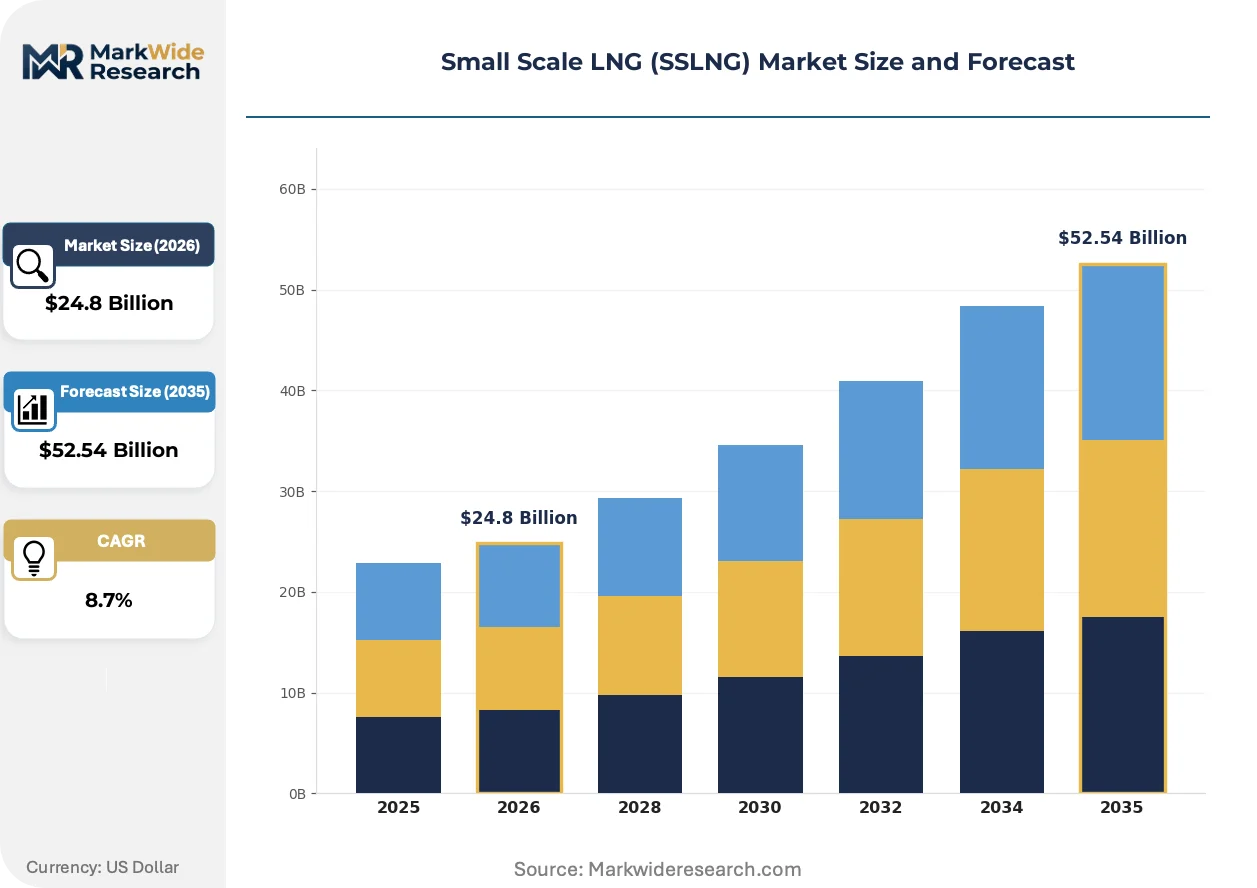
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $52.54 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Storage Tanks, Regasification Units, Distribution Systems, LNG Carriers End User: Power Generation, Industrial, Marine, Transport Application: Remote Power, Transportation Fuel, Peak Shaving, Export Distribution Channel: Direct Sales, Wholesale, Online Platforms, Third-Party Logistics |
| Companies Covered | Shell plc, Linde plc, Wärtsilä Corporation, TotalEnergies SE, ENGIE SA, Gazprom, New Fortress Energy LLC, Chart Industries, Inc., Excelerate Energy Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Scale LNG (SSLNG) Market Trends and Innovations
Modular regasification technology is compressing deployment timelines for port operators, while regulatory pressure on sulfur emissions accelerates bunkering infrastructure investment. These forces are converging to reshape how LNG reaches off-grid industrial and marine consumers.
Modular regasification skids integrate cryogenic storage with vaporization systems in factory-built units. Port developers in Germany and Japan are adopting these systems to reduce on-site construction duration. This standardization is decentralizing terminal development authority from integrated energy majors toward specialized infrastructure funds.
The EU Green Deal's F-Gas Regulation mandates phasedown of high-global-warming-potential refrigerants in cryogenic applications. Terminal operators must retrofit or replace insulation systems using alternative cooling technologies. European coastal facilities face the most compressed compliance timelines, driving equipment replacement demand through 2030.
Ship operators now contract bunkering services through volume-commitment agreements rather than spot procurement. Major transshipment hubs are responding with dedicated LNG-only berths and integrated fueling logistics. This contracting shift is most visible at Singapore and Rotterdam, where port authorities have prioritized LNG-ready infrastructure in terminal expansion plans.
Small Scale LNG (SSLNG) Market Segmentation
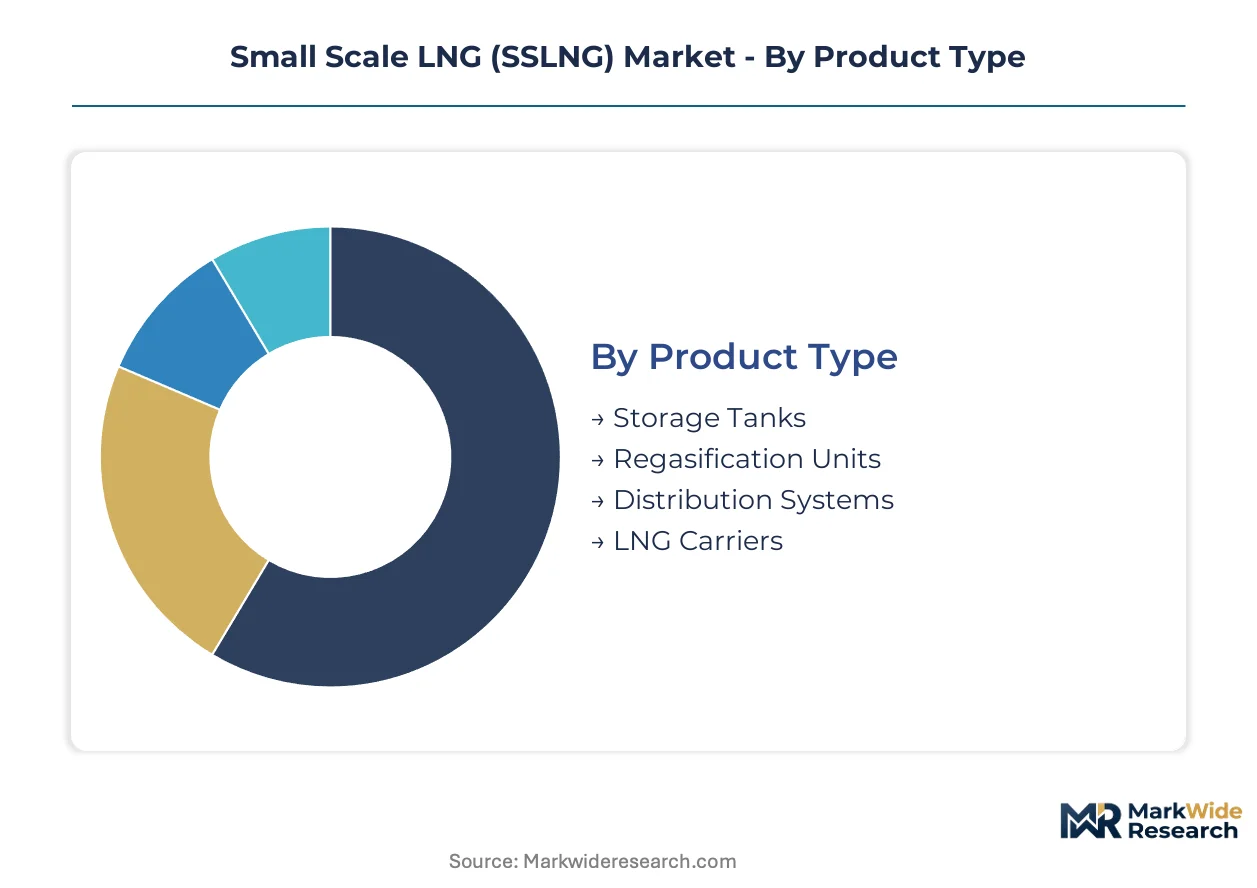
SSLNG market segmentation reveals how capital allocation priorities differ across infrastructure types, end-use applications, and delivery mechanisms. Equipment replacement cycles and regulatory compliance timelines create divergent growth trajectories within each category.
Product Type:
Upgrade and replacement cycles dominate procurement decisions as terminal operators balance asset longevity against evolving insulation standards.
- Storage Tanks:Vacuum-insulated double-wall vessels maintain minus 162 degrees Celsius with perlite or aerogel insulation. Demand concentrates at Japanese and German port authorities modernizing coastal terminals under F-Gas Regulation timelines. METI-backed infrastructure tenders in Japan favor tank systems with 25-year operational life.
- Regasification Units:Ambient air vaporizers and submerged combustion systems convert LNG back to gaseous state. European coastal facilities prioritize modular skid-mounted units to compress deployment schedules against EU Green Deal compliance deadlines.
- Distribution Systems:Cryogenic pumps, loading arms, and metering skids handle transfer operations at minus 160 degrees Celsius.
- LNG Carriers:Purpose-built vessels below 30,000 cubic meters serve coastal and riverine routes.
Volume placements concentrate in Storage Tanks; the faster expansion belongs to Regasification Units.
End User:
Cost tier differentiation separates heavy industrial offtakers from marine operators with divergent fuel switching economics.
- Power Generation:Remote microgrids and island utilities deploy SSLNG as baseload replacement for diesel generators. EPA emissions rules on stationary sources redirect U.S. industrial facilities toward LNG-powered distributed generation.
- Marine:Dual-fuel vessel operators at Rotterdam, Singapore, and Jacksonville drive bunkering infrastructure investment. IMO 2020 sulfur caps force transshipment hubs to install LNG-ready berths ahead of fleet conversion schedules.
- Industrial:Off-grid manufacturing facilities and mining operations lacking pipeline access.
- Transport:Heavy-duty trucking and rail operators in China and the United States testing LNG as diesel alternative.
Capital deployment favors Marine terminals; steepest expansion trajectory runs through Power Generation microgrids.
Application:
Application selection hinges on grid connectivity status and peak demand volatility rather than uniform fuel substitution logic.
- Remote Power:Off-grid industrial facilities and island communities replace diesel with LNG microgrids. Chinese MEE regulations on stationary emissions accelerate adoption at manufacturing plants beyond pipeline reach.
- Transportation Fuel:Marine bunkering at European and Asian transshipment hubs dominates volume. Ship operators contract through volume-commitment agreements rather than spot procurement.
- Peak Shaving:Grid operators inject vaporized LNG during seasonal demand spikes.
- Export:Small-volume liquefaction trains serve stranded gas fields.
Contract value concentrates in Remote Power; share gains accrue fastest to Transportation Fuel bunkering.
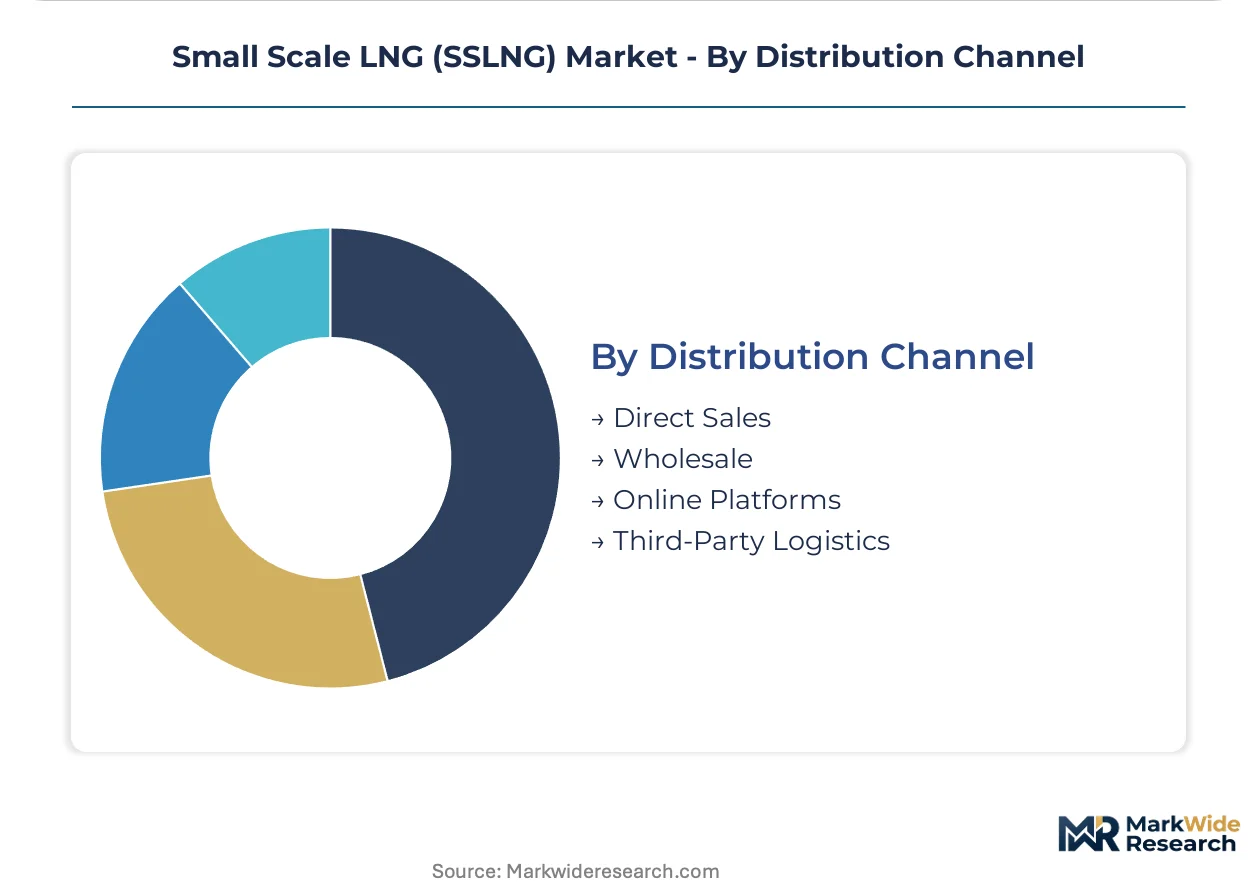
Distribution Channel:
Channel selection reflects project scale and technical complexity, with direct engagement preferred for cryogenic infrastructure.
- Direct Sales:Terminal developers negotiate directly with equipment manufacturers for storage and regasification systems. German and Japanese port authorities favor this channel for modular skid procurement.
- Wholesale:Aggregators supply ISO containers and standardized cryogenic equipment to smaller industrial offtakers.
- Third-Party Logistics:Specialized cold-chain operators handle LNG container movements.
- Online Platforms:Digital marketplaces for spare parts and standard components.
Revenue weight sits with Direct Sales; channel expansion runs fastest through Third-Party Logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in Fujairah and Jebel Ali concentrate bunkering infrastructure investment across the Middle East. METI-designated special zones in Japan accelerate SSLNG terminal deployment through streamlined permitting. EU Green Deal implementation zones in Rotterdam and Hamburg prioritize cryogenic storage upgrades.
Japan
Dual-fuel vessel retrofit demand at Nagoya and Yokohama shipyards drives equipment procurement. METI's port infrastructure program sequences storage tenders against IMO 2020 fleet conversion timelines. Chubu region terminal operators prioritize 25-year-life vacuum-insulated tanks under F-Gas Regulation-aligned standards.
Germany
Industrial microgrid adoption in the Ruhr Valley redirects diesel generator replacement toward LNG. The EU F-Gas Regulation mandates cryogenic insulation retrofits at coastal facilities by 2030. Hamburg port authorities install modular regasification skids to compress deployment schedules against compliance deadlines.
United States
EPA stationary source emissions rules redirect Gulf Coast industrial facilities toward LNG-powered distributed generation. Jacksonville port infrastructure supports Shell plc's integrated bunkering network across the Atlantic corridor. Texas and Louisiana chemical complexes lacking pipeline access adopt ISO container distribution for off-grid supply.
South Korea
Busan transshipment hub mandates LNG-ready berths ahead of fleet conversion schedules. The country's national maritime regulator enforces sulfur caps that expand bunkering infrastructure tenders. Ulsan shipyards specialize in dual-fuel engine retrofits anchoring equipment sales to domestic and export markets.
Singapore
Volume-commitment contracting for marine bunkering displaces spot procurement at the world's largest transshipment hub. The Maritime and Port Authority sequences LNG-only berth installation against vessel operator conversion timelines. Jurong Island industrial cluster adopts cryogenic storage for peak shaving and remote power applications.
Small Scale LNG (SSLNG) Market Competitive Landscape
Top-tier vendors anchor integrated energy majors, while specialized equipment fabricators occupy mid-tier positions. The vendor structure concentrates cryogenic storage manufacturing among vacuum-insulation specialists with legacy industrial gas expertise. Two strategic archetypes dominate: bunkering network operators with port authority relationships, and modular skid manufacturers with factory-build capabilities. Competitive moves center on backward integration into cryogenic tank production and geographic expansion through port infrastructure partnerships.
Within the integrated energy archetype, Shell plc and TotalEnergies SE exemplify bunkering network scale. Among specialized equipment fabricators, Chart Industries, Inc. occupies a position representing modular regasification technology. Wärtsilä Corporation anchors the dual-fuel engine retrofit segment at Northern European shipyards. Linde plc sits within industrial gas heritage players extending cryogenic expertise into SSLNG storage systems.
| Leading Market Players |
|---|
| Shell plc |
| Linde plc |
| Wärtsilä Corporation |
| TotalEnergies SE |
| ENGIE SA |
| Gazprom |
| New Fortress Energy LLC |
| Chart Industries, Inc. |
| Excelerate Energy Inc. |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between F-Gas Regulation-compliant cryogenic systems and legacy insulation equipment manifests in both procurement premiums and supplier concentration. Japanese and German port authorities pay material premiums for vacuum-insulated tanks meeting METI-mandated 25-year operational life standards, while non-compliant inventory from secondary fabricators clears at distressed valuations through wholesale channels.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as port authorities compress deployment schedules against EU Green Deal deadlines. Spot inventory of standardized regasification skids trades at discounts to factory-order pricing, while custom-engineered storage systems for Japanese coastal terminals command sustained premiums. Price differentiation hinges on insulation certification tier and volume-commitment scale, with marine bunkering operators showing lowest price sensitivity due to IMO 2020 compliance imperatives. Cost compression in modular skid manufacturing is intensifying as factory-build capacity expands in Germany.
Supply Chain Analysis
Freight costs for vacuum-insulated tanks from U.S. and European fabricators to Asian port sites represent 12-18% of delivered equipment value, driving localization decisions. Cryogenic steel and perlite insulation draw from concentrated U.S., German, and Japanese metallurgical suppliers. Single-source vulnerability in aerogel insulation manufacturing constrains project execution velocity. Distribution runs through direct sales channels for terminal-scale equipment, with ISO container logistics handled by specialized cold-chain operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
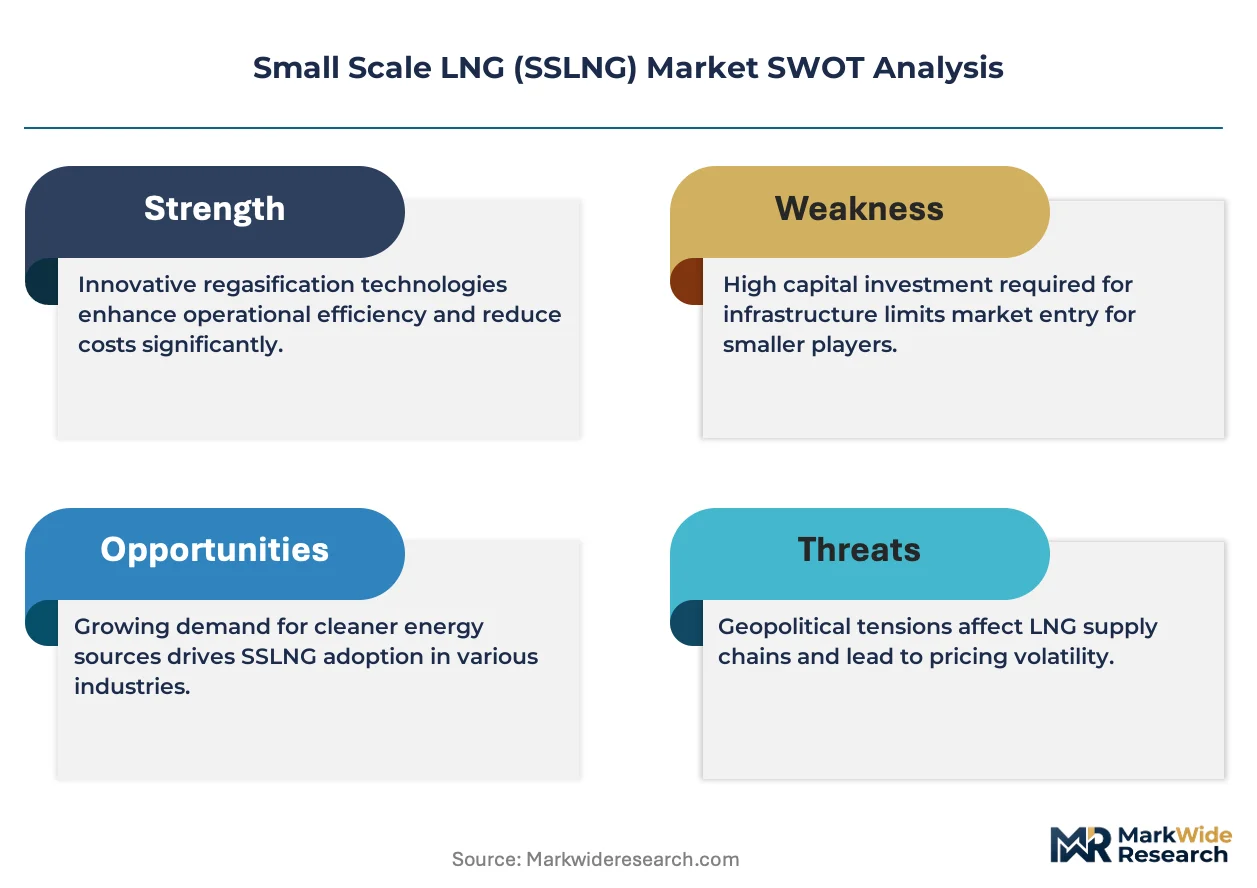
The SSLNG market functions as a cost-of-compliance story where the EU F-Gas Regulation and IMO 2020 sulfur caps erect capital-intensive barriers that protect incumbents with certified equipment portfolios and stranded challengers with legacy inventory.
For Market Incumbents: Lock in port authority relationships through volume-commitment contracting ahead of tender sequencing in Japan and South Korea. Prioritize backward integration into aerogel insulation manufacturing to neutralize single-source supply risk. Defensive capacity positioning in Hamburg and Yokohama clusters anchors margin capture against emerging modular skid competitors. For New Entrants and Emerging Players: The EU F-Gas Regulation in Germany opens a window for cryogenic retrofit specialists targeting 2030 compliance deadlines at coastal facilities. ISO container distribution networks for off-grid industrial supply chains in China's manufacturing zones present the most penetrable white-space target. A go-to-market angle anchored to EPA emissions rules for stationary diesel generators unlocks U.S. power generation microgrid contracts. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated energy majors seeking bunkering network scale. Five-to-ten-year viability hinges on fleet conversion timelines aligning with port infrastructure deployment. Watch vessel order backlogs at Northern European shipyards as the inflection signal for equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Regasification Capacity Buildout | Factory-built skids compress German port deployment schedules against F-Gas deadlines. |
| Backward Integration into Cryogenic Insulation | Captive aerogel supply neutralizes bottleneck risks for Japanese tank manufacturers. |
| Long-term Bunkering Supply Agreement | Volume commitments from Rotterdam and Singapore operators secure offtake visibility. |
| Dual-fuel Engine Technology Licensing | Wärtsilä's retrofit expertise transfers to Ulsan shipyard partnerships. |
| Green Certification Program for Storage Assets | F-Gas Regulation alignment opens premium pricing at EU coastal terminals. |
Research Methodology
Document review covered trade customs data, EPA stationary source emissions filings, and EU Green Deal regulatory texts, complemented by interviews with terminal development executives, cryogenic equipment procurement leads at Japanese port authorities, shipyard retrofit specialists in Northern Europe, and LNG bunkering logistics coordinators. Secondary validation drew from FERC infrastructure filings, IEA marine fuel transition reports, and METI port investment disclosures. Bottom-up project pipeline analysis triangulated against top-down energy transition demand modeling.
Installed capacity and revenue outputs were generated through segmented modeling across product type, end user category, application, and distribution channel dimensions, with geographic regulatory cluster as an additional stratification layer. CAGRs were derived from regression analysis of historical deployment velocity against fleet conversion timelines and infrastructure tender sequencing. Industry-specific inputs included vessel order backlogs at major shipyards and port authority capital expenditure commitments.
The model assumes a particular technology adoption path favoring vacuum-insulated double-wall storage; alternative pathways for membrane tank systems would alter the outlook for equipment supplier market shares. Forecasts reflect assumptions regarding IMO regulatory enforcement consistency and EU Green Deal implementation pacing. Stakeholders should weight assumptions against their own operating context and regional regulatory uncertainty.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
North America Drilling Completion Fluids Market
Oil & Gas
Oilwell Completion Tools Market
Oil & Gas
Multi-Point Ground Flares (MPGF) Market
Oil & Gas
Well Completion Market
Oil & Gas
Rig-Less Intervention Service Market
Oil & Gas
Middle-East and Africa Liner Hanger System Market
Oil & Gas
Coal Bed Methane Market
Oil & Gas
Canada LNG Market
Oil & Gas
Australia Oil and Gas Upstream Market
Oil & Gas
Rig and Oilfield Mats Market
Oil & Gas
North America Frac Sand Market
Oil & Gas
Norway Oilfield Equipment Rental Services Market
Oil & Gas
Southeast Asia Oil and Gas Market
Oil & Gas
North Sea Oilfield Equipment Market
Oil & Gas
Floating Liquefied Natural Gas (FLNG) Terminals Market
Oil & Gas
Well Test Market