
 Geothermal Power Generation Market | 2026-2036
Geothermal Power Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Geothermal Power Generation Market Analysis
Project finance with long-term power purchase agreements is narrowing the pool of developers capable of absorbing reservoir risk. Ormat Technologies leverages its integrated project development and equipment manufacturing model to sustain competitive positioning across multiple geographies. Enel anchors its growth strategy in established volcanic zones where it controls operational data and subsurface expertise. Mitsubishi Heavy Industries competes through turbine technology leadership in high-enthalpy resource environments.
Geothermal power generation harnesses subsurface heat to produce electricity through steam-driven turbines, with resource temperatures typically exceeding 150°C for commercial viability and reservoir depths ranging from 1 to 3 kilometers. Binary cycle plants now dominate new installations where moderate-temperature resources prevail, while enhanced geothermal systems represent the fastest-growing technology segment as hydraulic stimulation unlocks hot dry rock formations. Flash steam technology occupies mature baseload positions in volcanic regions, and direct heating applications capture margin pools in agricultural and aquaculture end uses.
The US EPA enforces geothermal emissions standards under the Clean Air Act, while Indonesia's MEMR regulates resource licensing and state utility offtake obligations. Kenya's EPRA sets feed-in tariff structures that shape developer returns and capital commitment timelines. Stakeholders must monitor permitting velocity and grid interconnection queue positions as the primary variables determining project economics and deployment schedules.
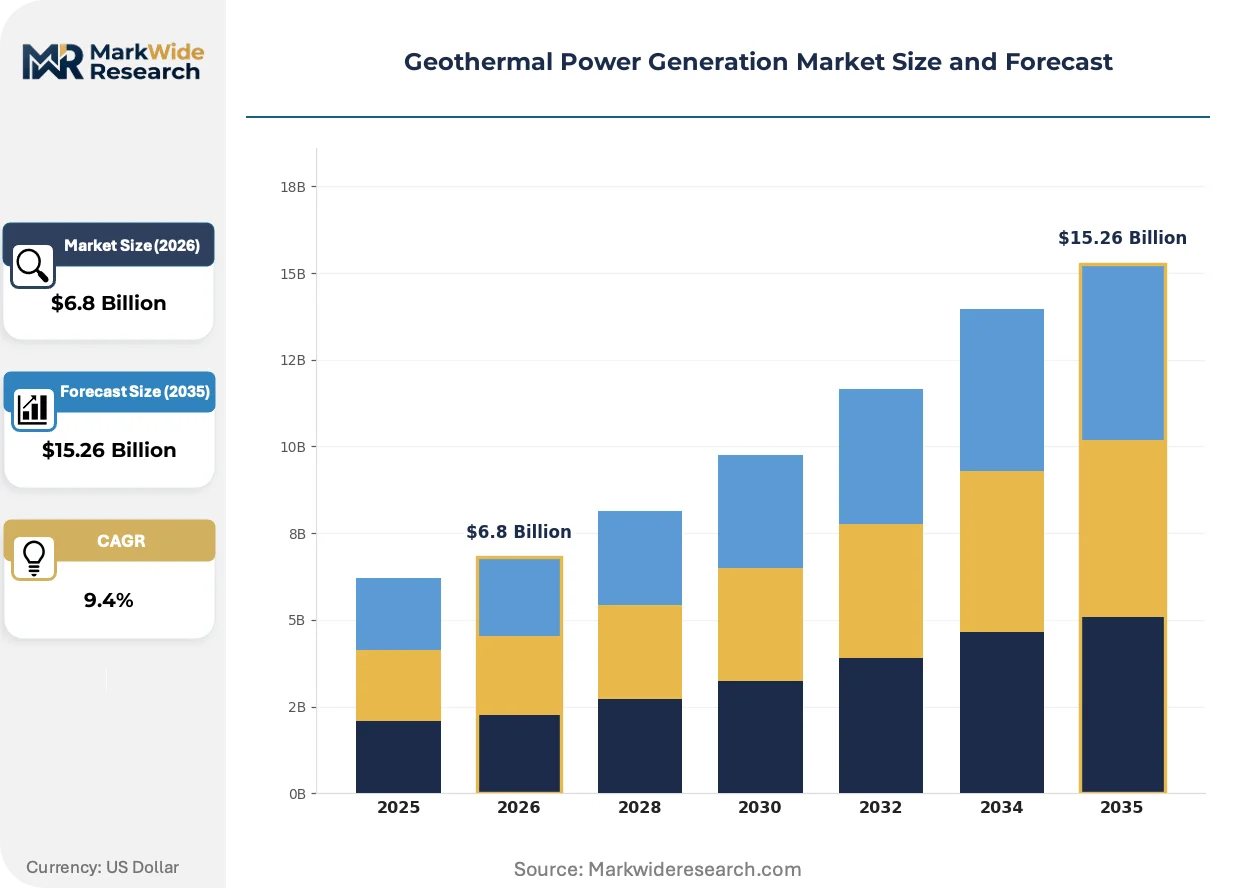
Market Dynamics
Enhanced geothermal systems are collapsing the geological constraints that historically confined development to volcanic corridors, unlocking hot dry rock formations across sedimentary basins and transforming project economics through hydraulic stimulation advances.
Growth Catalysts
- US IRA Production Tax Credits:Federal incentives redirect institutional capital toward reservoir engineering and drilling technology, compressing developer equity requirements and accelerating deployment timelines.
- East African Rift Valley baseload procurement:Kenya's EPRA feed-in tariffs and Ethiopia's state utility offtake commitments displace diesel imports with indigenous renewable capacity.
- Binary cycle plant efficiency gains:Organic Rankine cycle improvements enable commercial extraction from moderate-temperature resources previously classified as subeconomic.
Market Restraints
- Drilling cost volatility:Steel tubulars and directional drilling services concentrate supply among Oklahoma and Texas oilfield service clusters, exposing project budgets to hydrocarbon sector demand cycles.
- Reservoir performance uncertainty:Subsurface permeability estimation errors trigger production shortfalls that invalidate power purchase agreement revenue projections.
- Grid interconnection queue congestion:Utility interconnection study backlogs in California and Nevada extend commercial operation dates by 18-36 months.
Strategic Opportunities
- Indonesia's MEMR licensing reforms:Simplified geothermal work area awards and direct state utility offtake obligations reduce regulatory friction for greenfield developers.
- Direct use district heating convergence:Integration of geothermal brine with heat pump networks captures margin pools in Icelandic and Turkish municipal markets.
- Lithium extraction from geothermal brine:Salton Sea and Upper Rhine Valley projects pilot selective extraction technologies that monetize mineral byproducts.
Industry Challenges
- Reservoir engineering talent scarcity:Subsurface geoscience and drilling operations expertise concentrates among aging specialists in volcanic zone operators.
- Extended resource confirmation timelines:Temperature gradient drilling and flow testing requirements delay final investment decisions by 24-48 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geothermal Power Generation Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Dry Steam, Flash Steam, Binary Cycle, Enhanced Geothermal Systems Application: Electricity Generation, Direct Heating, Greenhouse Heating, Aquarium Heating End User: Utilities, Commercial, Industrial, Residential Installation: Onshore, Offshore, Small Scale, Large Scale |
| Companies Covered | Ormat Technologies, Enel, Calpine, Mitsubishi Heavy Industries, General Electric, Toshiba Corporation, ABB, Berkshire Hathaway Energy, Halliburton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geothermal Power Generation Market Emerging Trajectories
Closed-loop geothermal architectures and supercritical CO2 working fluids are reshaping resource accessibility, collapsing the distinction between hydrothermal and petrothermal systems while compressing development cycles.
Supercritical CO2 as a heat extraction working fluid is collapsing the temperature threshold for commercial viability, enabling electricity generation from 100°C resources that binary plants previously dominated. European pilot installations in France and Germany demonstrate 15-20% efficiency improvements over water-based systems. Equipment suppliers are recalibrating turbine designs and heat exchanger specifications to accommodate corrosive fluid chemistries and non-condensable gas fractions.
The US EPA's pending geothermal emissions standards under Clean Air Act Section 111 are mandating hydrogen sulfide abatement systems and non-condensable gas reinjection for flash steam facilities. This regulatory pressure accelerates binary cycle adoption in Nevada and Utah where air quality attainment status restricts permitting. Developers are pre-emptively engineering closed-loop architectures to eliminate surface emissions liability.
Utility procurement is consolidating around 25-year power purchase agreements with take-or-pay structures that transfer reservoir performance risk to developers. This contractual evolution compresses the developer pool to vertically integrated firms capable of absorbing exploration and drilling cost overruns. Kenya's KPLC and Indonesia's PLN anchor this shift, prioritizing baseload security over least-cost dispatch in their renewable portfolio standards.
Geothermal Power Generation Market Segmentation
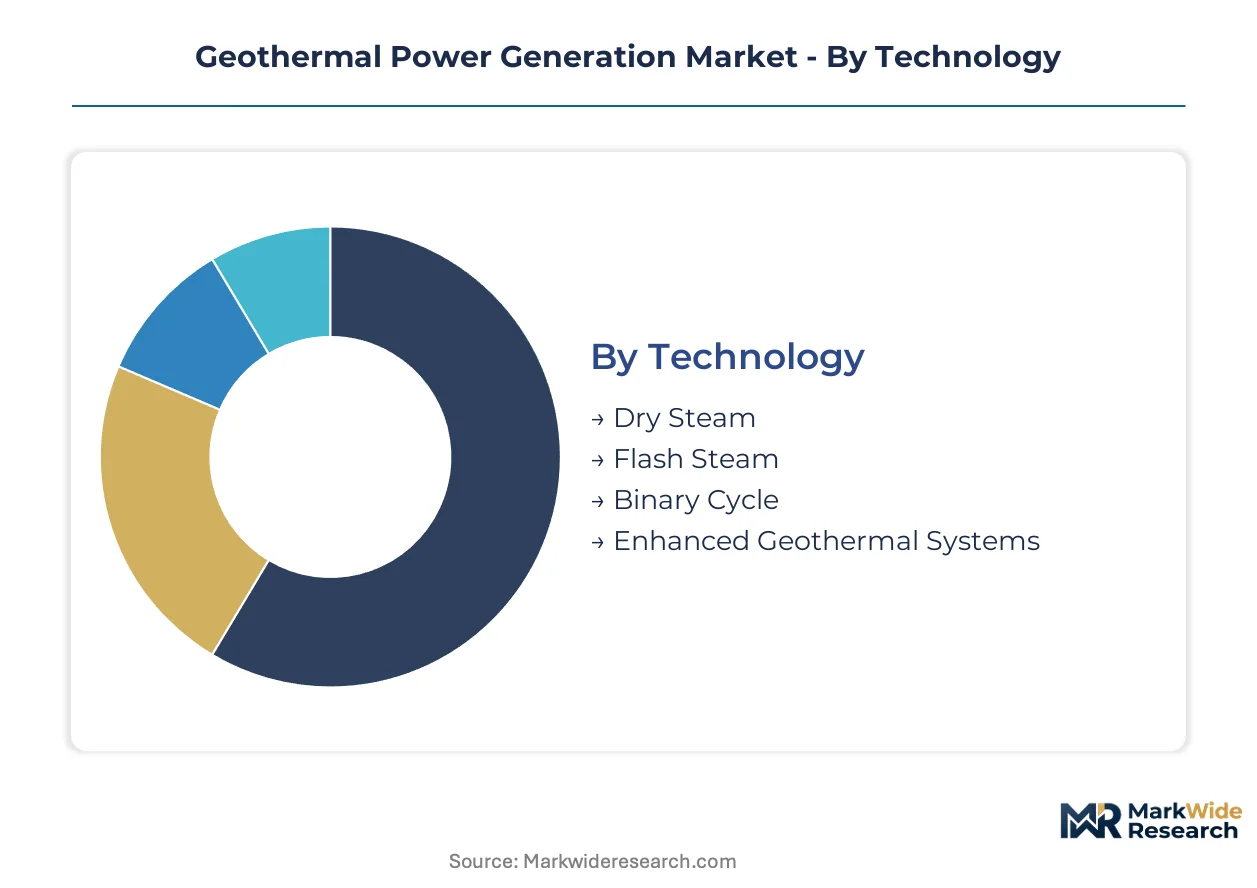
Technology choice dictates reservoir economics and capital intensity across geothermal developments. Application diversity expands addressable markets beyond electricity into thermal services. End-user concentration and installation scale determine project finance structures and risk allocation.
Technology:
Mature hydrothermal technologies anchor baseload procurement while emerging systems unlock previously inaccessible formations.
- Dry Steam:The simplest geothermal architecture channels natural steam directly to turbines without intermediate heat exchangers. Larderello in Italy and The Geysers in California sustain this technology's volume position through decades of reservoir management data.
- Flash Steam:High-enthalpy resources above 180°C undergo pressure reduction to separate steam from brine, enabling dual-phase energy extraction. Indonesia's volcanic corridor concentrates flash steam deployment where PLN offtake obligations provide revenue certainty.
- Binary Cycle:Organic Rankine cycle systems extract energy from moderate-temperature resources through secondary working fluids. Lower temperature thresholds expand deployable inventory across sedimentary basins.
- Enhanced Geothermal Systems:Hydraulic stimulation creates artificial permeability in hot dry rock formations, collapsing geological constraints that confined development to volcanic zones. US IRA production tax credits compress equity requirements for these capital-intensive projects.
Flash Steam retains volume leadership; Enhanced Geothermal Systems hold the steepest expansion curve.
Application:
Electricity dominates revenue capture while thermal applications diversify monetization pathways.
- Electricity Generation:Grid-connected baseload power commands premium pricing in renewable portfolio standards. Kenya's EPRA feed-in tariffs and Ethiopia's state utility commitments anchor demand concentration in the East African Rift Valley.
- Direct Heating:District heating networks in Iceland and Turkey capture geothermal brine for residential and commercial thermal loads. Municipal procurement prioritizes indigenous heat sources over imported natural gas.
- Greenhouse Heating:Agricultural thermal applications stabilize year-round crop production in temperate climates. Netherlands and Hungary greenhouse clusters integrate geothermal heat pumps.
- Aquarium Heating:Controlled thermal environments support aquaculture and research facilities. Japanese and Norwegian marine research stations deploy small-scale geothermal circulation systems.
Electricity Generation commands revenue concentration; Direct Heating expands most quickly through municipal decarbonization mandates.
End User:
Procurement scale separates centralized utility buyers from distributed commercial and industrial offtake.
- Utilities:Vertically integrated power companies aggregate reservoir risk across multi-decade power purchase agreements. Indonesia's PLN and Kenya's KPLC structure take-or-pay contracts that transfer performance risk to developers.
- Commercial:Hotels, resorts, and agricultural processors seek thermal reliability independent of grid volatility. Philippine resort developments in Laguna province anchor direct-use commercial demand.
- Industrial:Mining operations and mineral processing facilities require process heat at scale. Chilean lithium extraction operations pilot geothermal brine integration.
- Residential:Single-family and multi-unit buildings access geothermal heat pumps for space conditioning. Ground-source heat pump adoption concentrates in US Midwest and German suburban developments.
Utilities dominate capital deployment; Industrial offtake is climbing the fastest as process heat electrification accelerates.
Installation:
Resource depth and surface footprint determine onshore versus offshore feasibility and scale economics.
- Onshore:Land-based drilling accesses conventional hydrothermal reservoirs at 1-3 kilometer depths. Nevada, Utah, and Iceland concentrate onshore development through established permitting frameworks.
- Offshore:Submarine geothermal systems exploit coastal volcanic formations where land access is restricted. Japan's coastal research programs evaluate offshore reservoir potential.
- Small Scale:Distributed systems below 5 MW serve isolated communities and industrial campuses. East African rural electrification programs prioritize small-scale geothermal over diesel microgrids.
- Large Scale:Utility-scale installations above 50 MW aggregate reservoir capacity for grid baseload service. Indonesia's Sarulla and Philippines' Tiwi anchor large-scale deployment in volcanic corridors.
Onshore installations retain project volume leadership; Small Scale systems gain share fastest through rural electrification capital flows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Geothermal power generation capacity concentrates in volcanic corridor economies that export baseload electricity while importing drilling equipment and turbine components. Trade balances tilt toward capital goods deficits in East Africa and Southeast Asia, where project development outpaces domestic manufacturing.
United States
Nevada and Utah utilities procure enhanced geothermal systems under IRA production tax credit structures that compress developer equity requirements. The EPA enforces Clean Air Act Section 111 emissions standards that mandate hydrogen sulfide abatement at flash steam facilities. The Salton Sea corridor in California pilots lithium extraction from geothermal brine alongside electricity generation.
Indonesia
State utility PLN anchors demand through take-or-pay power purchase agreements that transfer reservoir risk to developers. The MEMR regulates geothermal work area licensing and directs state utility offtake obligations. The volcanic corridor spanning Java and Sumatra hosts Sarulla and other large-scale installations.
Kenya
Kenya Power and Lighting Company structures feed-in tariffs that displace diesel imports with indigenous renewable baseload. The EPRA sets tariff structures shaping developer returns and capital commitment timelines. The Olkaria field in the Great Rift Valley concentrates operational capacity and subsurface expertise.
Philippines
Private utilities and electric cooperatives scale procurement across the Pacific Ring of Fire volcanic belt. The Department of Energy regulates service contracts and renewable energy market transactions. The Tiwi and Mak-Ban fields in Laguna and Batangas provinces anchor flash steam deployment.
Iceland
Municipal district heating networks capture geothermal brine for residential and commercial thermal loads independent of electricity export. The National Energy Authority regulates resource licensing and direct-use applications. The Reykjanes Peninsula and Hellisheiði fields integrate power generation with industrial process heat supply.
Geothermal Power Generation Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in turbine manufacturing and drilling services. The developer pool narrows to vertically integrated firms capable of absorbing reservoir risk across multi-decade power purchase agreements. Two strategic archetypes dominate: integrated project developers controlling subsurface data and equipment manufacturers licensing turbine technology. Competitive moves concentrate on securing long-term offtake contracts and acquiring drilling technology capabilities.
Within the integrated developer tier, Ormat Technologies and Enel occupy positions exemplifying the project-equipment convergence model. Mitsubishi Heavy Industries and General Electric sit within the turbine technology supplier archetype, anchoring high-enthalpy resource segments. These named entities represent the competitive structure without exhausting its composition.
| Leading Market Players |
|---|
| Ormat Technologies |
| Enel |
| Calpine |
| Mitsubishi Heavy Industries |
| General Electric |
| Toshiba Corporation |
| ABB |
| Berkshire Hathaway Energy |
| Halliburton |
| Others |
Supply Flow & Price Mechanics
Overcapacity in US drilling rig fleets is compressing day rates for directional services and shifting supplier pricing power toward geothermal developers negotiating long-term equipment procurement contracts.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures tied to named megawatt capacity thresholds and reservoir confirmation milestones. Three-tier pricing structure across premium, standard, and economy levels reflects binary cycle turbine efficiency ratings and after-sales service bundling. Pricing pressure stems from steel tubular commodity volatility and Oklahoma-Texas oilfield service demand cycles. Utility offtakers exhibit lowest price sensitivity given baseload procurement mandates, while commercial greenhouse operators negotiate aggressively on thermal delivery contracts.
Supply Chain Analysis
Extended payment terms from Indonesian and Kenyan state utilities are forcing turbine manufacturers to absorb working capital strain through supply-chain finance facilities. Manufacturing concentrates in Japan, Germany, and the United States for high-enthalpy turbine components, while China dominates heat exchanger fabrication. Raw material dependencies include nickel-based superalloys, corrosion-resistant steel tubulars, and organic Rankine cycle working fluids. Single-source vulnerability runs through specialized directional drilling contractors clustered in Oklahoma and Texas. Distribution runs through EPC contractors integrating reservoir engineering with equipment installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technology fragmentation across binary, flash, and enhanced geothermal systems is creating specialized niches as reservoir characteristics diverge and procurement specifications harden.
For Market Incumbents: Build subsurface data moats through proprietary temperature gradient drilling archives and flow testing databases accumulated across volcanic corridors. Acquire directional drilling capabilities in-house to capture margin pools currently flowing to Oklahoma-Texas oilfield service clusters. Prioritize certification investment for EPA Clean Air Act Section 111 compliance to preempt permitting delays in Nevada and Utah air quality attainment zones. For New Entrants and Emerging Players: Establish a beachhead in enhanced geothermal systems development where IRA production tax credits compress equity requirements and reservoir engineering talent scarcity limits incumbent expansion velocity. Target East African Rift Valley procurement corridors where Kenya's EPRA feed-in tariffs and Ethiopia's state utility commitments displace diesel imports. Pursue joint development structures with established volcanic zone operators to access subsurface expertise without multi-decade data accumulation timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across enhanced geothermal systems as hydraulic stimulation and deep drilling requirements escalate front-loaded capital deployment. Long-term viability favors vertically integrated developers controlling both reservoir confirmation workflows and turbine technology selection. Monitor permitting velocity in California and Nevada interconnection queues as the primary inflection signal for deployment schedule realization.| Strategic Initiative | Industry Significance |
|---|---|
| Reservoir Data Platform Acquisition | Captures proprietary temperature gradient archives that compress exploration timelines in volcanic corridors. |
| Binary Cycle Turbine Efficiency Upgrade | Enables commercial extraction from moderate-temperature sedimentary basin resources previously classified subeconomic. |
| Direct Lithium Extraction Integration | Monetizes Salton Sea and Upper Rhine Valley brine chemistry through selective mineral recovery alongside electricity generation. |
| Extended Power Purchase Agreement Structuring | Locks in 25-year take-or-pay contracts with Indonesia's PLN and Kenya's KPLC that transfer reservoir risk to developers. |
| Closed-Loop Architecture Engineering | Eliminates surface emissions liability under EPA Clean Air Act Section 111 pending hydrogen sulfide standards. |
Methodological Framework
Desk research of EIA geothermal capacity databases, FERC interconnection filings, and IEA renewable technology roadmaps preceded structured interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Primary fieldwork captured reservoir engineering workflows, drilling cost structures, and power purchase agreement negotiation dynamics. Secondary validation drew from EPA emissions standards documentation, Indonesia MEMR licensing records, and Kenya EPRA tariff determinations. Bottom-up project economics modeling triangulated against top-down capacity deployment forecasts.
Assumptions held fixed include IRA production tax credit continuity, current permitting velocity in Nevada and California interconnection queues, and established volcanic zone resource temperature profiles. Variables stress-tested encompass drilling cost inflation trajectories, steel tubular supply constraints, and binary cycle organic Rankine fluid price volatility. Segmentation modeling spanned technology type, application, end-user procurement scale, and installation configuration across the projection horizon. CAGRs derived from capacity deployment run rates and capital intensity curves indexed to named project development timelines.
Stress conditions across drilling service availability, state utility offtake commitment durability, and grid interconnection study backlogs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory incentive continuity and reservoir confirmation timeline distributions. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geothermal Energy
Geothermal Power Infrastructure and Components Market
Geothermal Energy
Geothermal Power Market
Geothermal Energy
Indonesia Geothermal Energy Market
Geothermal Energy
Enhanced Geothermal System Market
Geothermal Energy
United Kingdom Geothermal Energy Market
Geothermal Energy
Hungary Geothermal Energy Market
Geothermal Energy
Asia-Pacific Geothermal Energy Market
Geothermal Energy
Netherlands Geothermal Energy Market
Geothermal Energy
Sweden Geothermal Energy Market
Geothermal Energy
Philippines Geothermal Energy Market
Geothermal Energy
Geothermal Energy Market
Geothermal Energy
Global Geothermal Heat Pumps Market
Geothermal Energy
Denmark Geothermal Energy Market
Geothermal Energy
Geothermal Power Infrastructure Market
Geothermal Energy
US Geothermal Heat Pump Market