
 Oilfield Roller Chain Market | 2026-2036
Oilfield Roller Chain Market Size, Share, and Industry Trends Forecast 2026-2036
Oilfield Roller Chain Market Analysis
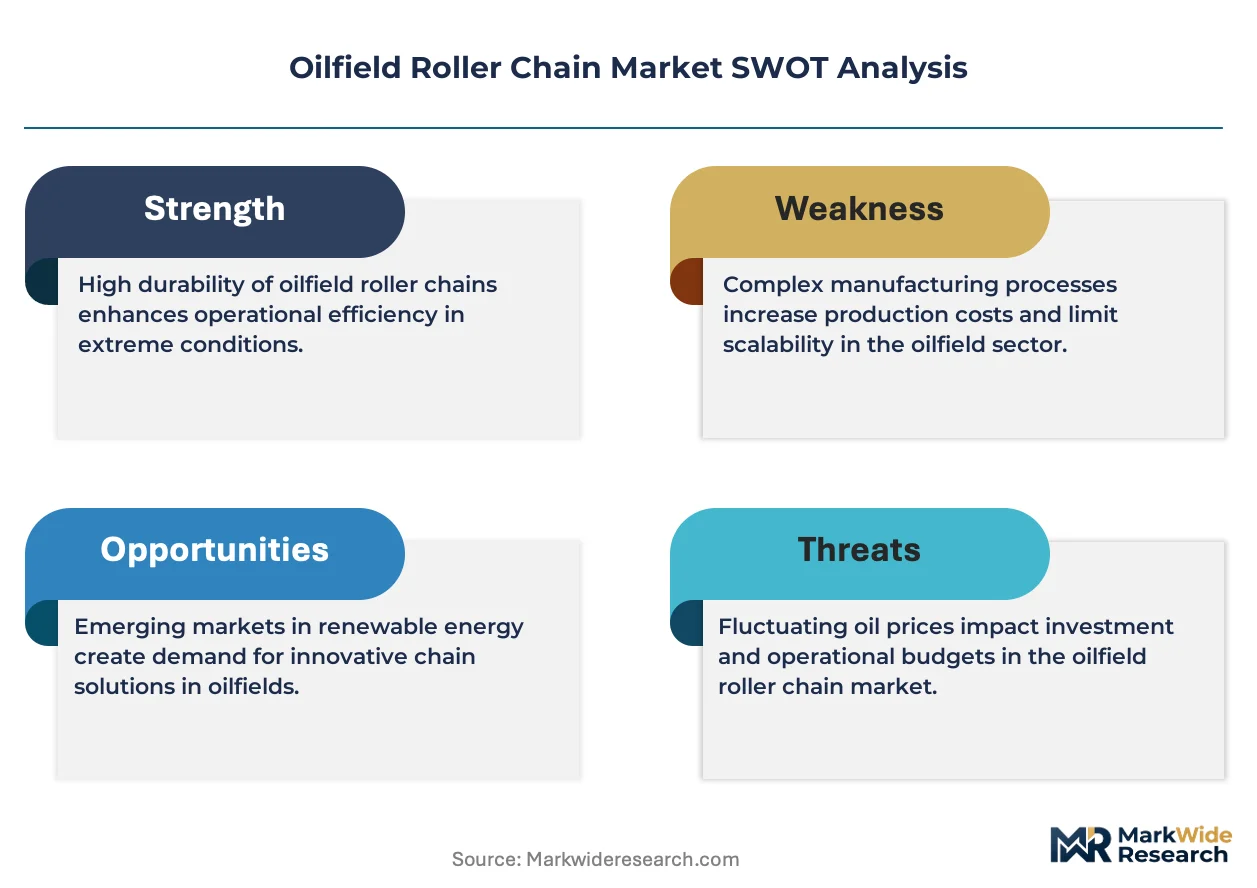
Capital-intensity divergence between integrated forgers and assembly-only suppliers is bifurcating competitive tiers in oilfield roller chain supply. Rexnord Corporation leverages captive heat-treatment capacity to command premium positioning in corrosion-resistant grades. Renold Plc anchors its footprint through long-term MRO contracts with North Sea drilling contractors. Tsubakimoto Chain Co. specializes in precision pitch control for high-load pump drive applications.
Oilfield roller chain consists of interconnected pin-link assemblies engineered from alloy steel with case-hardened bushings and precision-ground rollers, typically manufactured through controlled atmosphere carburizing and shot-peening to achieve fatigue resistance above 100,000 cycles in abrasive drilling environments. Its primary function is transmitting mechanical power between sprockets under high shock loads, corrosive exposure, and extended duty cycles common to wellhead equipment and mud pump drives. Heavy-duty chain and corrosion-resistant chain command the deepest margin pools due to material certification burdens and limited qualified supplier bases, while standard chain competes primarily on replacement velocity and distributor availability. Application demand concentrates in drilling equipment and pump systems where failure costs exceed product value by orders of magnitude, shifting procurement criteria toward mean-time-between-failure documentation over unit price.
API Specification 7F governs roller chain performance for oilfield service, while ISO 606 and ANSI B29.1 set dimensional interchangeability standards that determine market access for non-domestic suppliers. OSHA and BSEE enforcement in US offshore waters is elevating traceability requirements for chain origin and test documentation, effectively filtering smaller uncertified producers from platform supply chains. Buyers must weigh total cost of failure against procurement price when qualifying second-source suppliers for critical path equipment.
Market Dynamics
API Specification 7F revisions and ISO precision standards are compressing the qualified supplier base for offshore deployments, forcing capital reallocation toward captive heat-treatment and material certification infrastructure.
Growth Catalysts
- Shale basin replacement cycles:Operators in the Permian Basin are retiring legacy chain systems after extended duty cycles in high-shock drilling environments, generating pull-through demand for heavy-duty assemblies.
- OSHA traceability mandates:Enforcement actions in US offshore waters now require documented chain origin and test records, filtering uncertified producers and expanding market share for compliant suppliers.
- Pre-salt field development:Offshore Brazilian exploration is driving specification-grade procurement for corrosion-resistant grades in subsea pump installations.
Market Restraints
- Alloy steel input volatility:Case-hardening grade steel pricing swings compress margin predictability for assembly-only suppliers lacking backward integration into forging operations.
- Supplier concentration in North Sea MRO:Long-term maintenance contracts anchor incumbent positioning, creating switching friction for new entrants despite technical equivalence.
- Carburizing capacity scarcity:Controlled atmosphere heat-treatment infrastructure concentrates among integrated forgers, limiting scale-up options for precision pitch requirements.
Strategic Opportunities
- Offshore Middle East expansion:Saudi Aramco and ADNOC drilling programs are specifying API 7F chains for new jack-up rigs, opening procurement windows outside established North Sea relationships.
- Digital twin integration:Predictive maintenance platforms are converging with chain wear-monitoring sensors, enabling subscription-based replacement scheduling for critical path equipment.
- EU Green Deal alignment:Scope 3 emissions disclosure requirements under CSRD are favoring European suppliers with documented low-carbon heat-treatment processes.
Industry Challenges
- Metallurgical certification timelines:Third-party witness testing for offshore deployments extends qualification cycles by 8-14 months, delaying revenue recognition on new specifications.
- Shot-peening parameter transfer:Fatigue resistance above 100,000 cycles depends on proprietary surface treatment protocols that resist standardization across supplier shifts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oilfield Roller Chain Market |
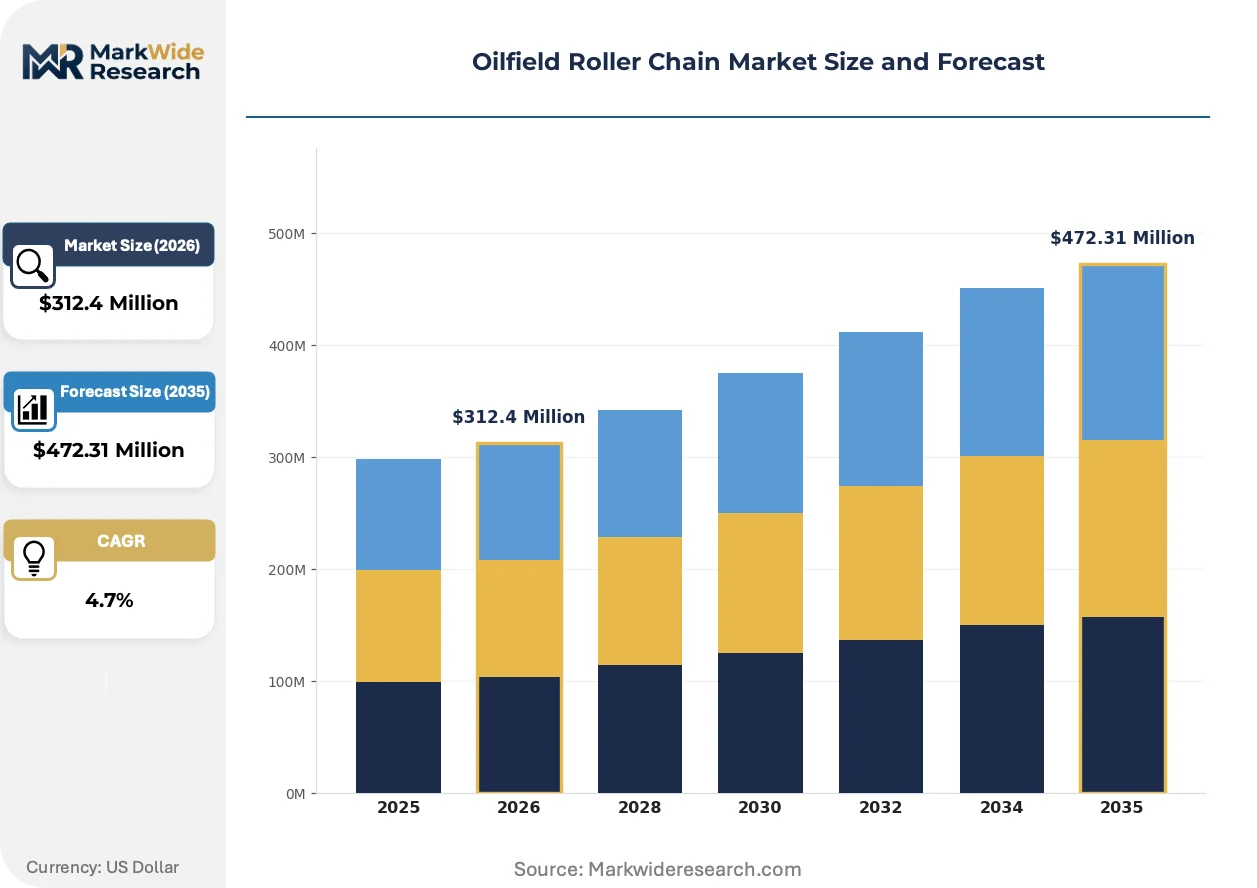
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Chain, Heavy-Duty Chain, Corrosion-Resistant Chain, Double Pitch Chain Application: Drilling Equipment, Pump Systems, Transportation, Production Facilities End User: Oil Companies, Service Providers, Equipment Manufacturers, Maintenance Providers Installation: Onshore, Offshore, Temporary Setup, Permanent Installation |
| Companies Covered | Rexnord Corporation, Renold Plc, Tsubakimoto Chain Co., Daido Kogyo Co. Ltd., Diamond Chain Company, Wippermann jr. GmbH, Zhejiang Gidi Industrial Chain Co., Ltd., Emerson Bearing Company, Flowtools Middle East LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oilfield Roller Chain Market Emerging Trajectories
Material science advances and regulatory disclosure mandates are restructuring how buyers evaluate total cost of failure against procurement price, elevating documentation and predictive capabilities over unit economics.
Plasma nitriding surface treatment is decomposing the traditional carburizing monopoly in corrosion-resistant chain production. North Sea drilling contractors are piloting nitrided assemblies for subsea installations. The technology is decomposing capital barriers for mid-scale forgers seeking offshore qualification without atmosphere furnace investments.
EU CSRD scope 3 emissions reporting is mandating supply chain carbon disclosure for listed oilfield service companies. Heat-treatment energy intensity now factors into procurement scoring alongside mechanical performance. European offshore operators are prioritizing suppliers with verified low-carbon process documentation.
Performance-based replacement contracting is displacing transactional spot purchasing for critical pump drive installations. Major drilling contractors are unbundling chain procurement from bundled MRO agreements, creating direct supplier relationships with documented mean-time-between-failure guarantees. This shift is most visible in US shale basins where non-productive time costs dwarf component pricing.
Oilfield Roller Chain Market Segmentation
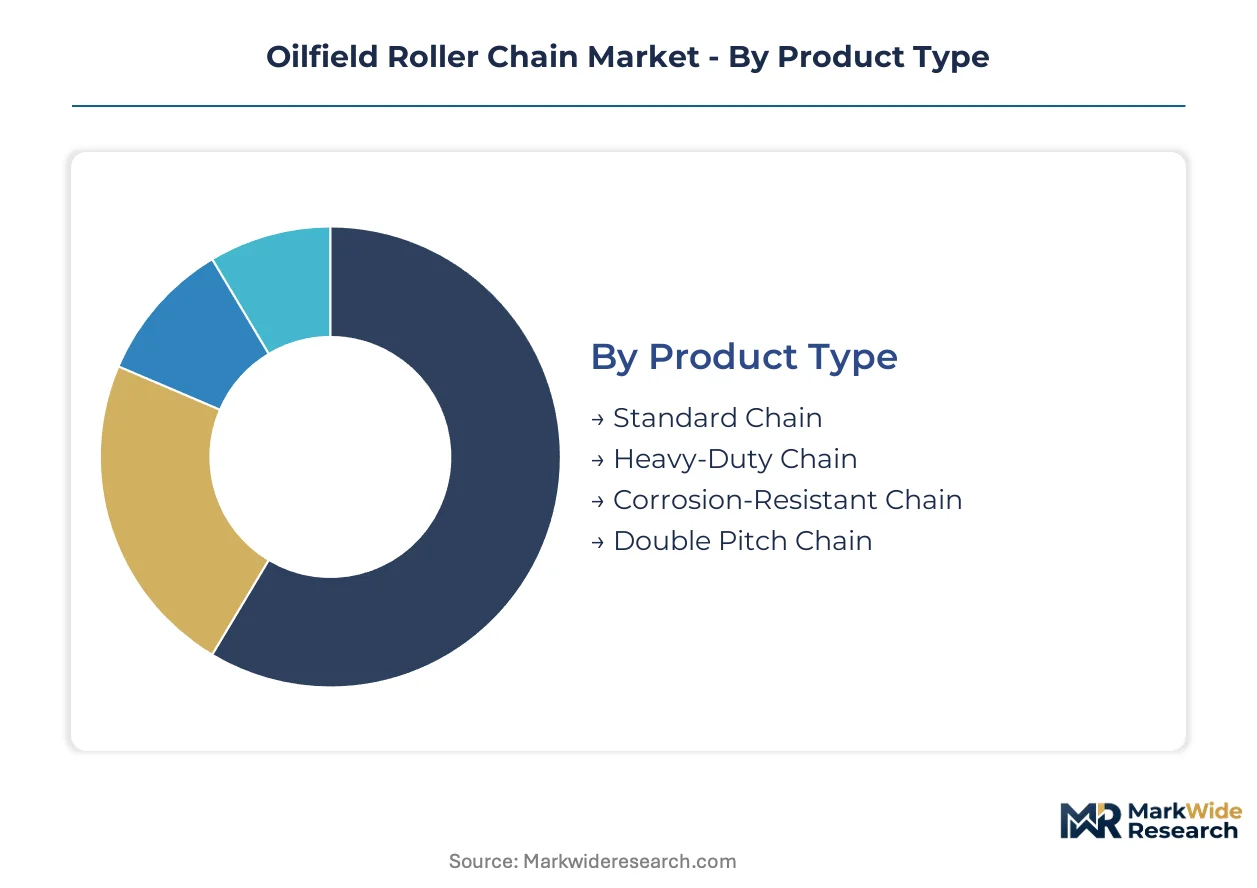
Oilfield roller chain procurement patterns diverge sharply across product grades and deployment contexts. Specification requirements, failure cost exposure, and channel access determine how buyers navigate the four-dimensional segmentation structure.
Product Type:
Channel mix varies dramatically by product grade, with heavy-duty and corrosion-resistant chains flowing through direct OEM relationships while standard chain moves primarily through distributor networks.
- Heavy-Duty Chain:Case-hardened alloy steel construction with shot-peened surfaces delivers fatigue resistance above 100,000 cycles. Demand concentrates in Permian Basin drilling operations where shock loads from extended duty cycles drive replacement velocity.
- Corrosion-Resistant Chain:Plasma nitriding and specialized coatings withstand subsea saltwater exposure. Brazilian pre-salt field development is pulling specification-grade procurement through API 7F-certified channels with documented metallurgical traceability.
- Standard Chain:General-purpose assemblies serve non-critical auxiliary equipment through MRO distributors with rapid availability.
- Double Pitch Chain:Extended pitch design reduces weight for low-speed conveyor and lifting applications in production facilities.
Heavy-duty chain dominates installed base. Corrosion-resistant chain is where expansion concentrates.
Application:
Cost tier stratification separates critical-path applications from auxiliary systems, with failure cost exposure determining procurement sophistication.
- Drilling Equipment:Mud pump drives and top drive systems transmit torque under cyclical shock loads. North Sea contractors demand mean-time-between-failure documentation over unit price given non-productive time economics.
- Pump Systems:Artificial lift and injection pump drives require precision pitch control. US shale operators are unbundling chain procurement from bundled MRO agreements for these installations.
- Transportation:Pipeline pigging and material handling systems use standardized assemblies with replacement velocity prioritized over specification grade.
- Production Facilities:Separator and processing equipment drives tolerate lower duty cycles with distributor-sourced standard chain.
Drilling equipment commands premium procurement processes. Pump systems are climbing the fastest as predictive maintenance platforms penetrate.
End User:
Customer type determines contract structure, with integrated oil companies leveraging volume scale while service providers prioritize technical service intensity.
- Oil Companies:Saudi Aramco and ADNOC drilling programs specify API 7F chains for new jack-up rigs, opening procurement windows outside established North Sea supplier relationships.
- Service Providers:Schlumberger and Halliburton fleets standardize on qualified suppliers with global logistics capability for remote deployment.
- Equipment Manufacturers:OEMs source through long-term supply agreements with captive heat-treatment capacity for specification consistency.
- Maintenance Providers:Independent MRO contractors compete on replacement velocity and local inventory availability.
Oil companies anchor volume concentration. Service providers are gaining procurement influence through fleet standardization.
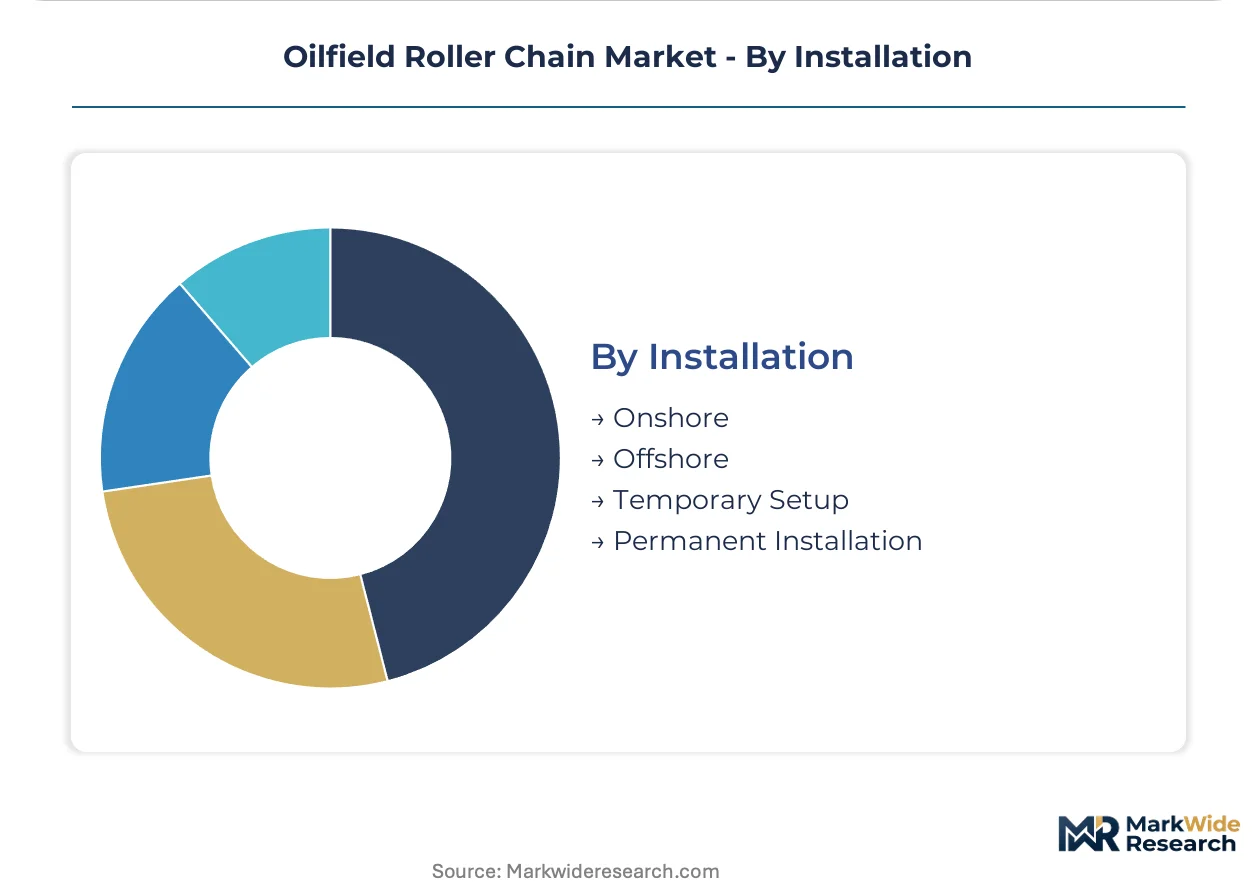
Installation:
Geography and permanence drive regulatory scope and documentation burden, with offshore permanent installations facing the steepest compliance requirements.
- Offshore:BSEE and OSHA traceability mandates require documented chain origin and test records, filtering uncertified producers from platform supply chains.
- Onshore:Permian and Bakken shale basins generate replacement demand through high-shock drilling environments with less stringent documentation.
- Permanent Installation:Subsea pump drives in Brazilian pre-salt fields require third-party witness testing extending qualification cycles.
- Temporary Setup:Workover and completion rigs prioritize rapid availability through distributor channels with standard-grade acceptance.
Onshore permanent installations dominate unit volume. Offshore permanent installations are gaining share fastest through pre-salt and Middle East expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. US shale operators prioritize rapid replacement velocity over specification documentation, while offshore markets in Brazil and the North Sea demand metallurgical traceability that extends procurement cycles by months.
United States
Permian Basin drilling contractors generate replacement pull-through demand after extended duty cycles in high-shock environments. OSHA enforcement actions now mandate documented chain origin and test records for offshore platform supply chains. Houston anchors the domestic distribution network with MRO inventory positioning for onshore spot purchasing.
Brazil
Pre-salt field development is driving specification-grade procurement for subsea pump installations requiring corrosion-resistant grades. ANVISA, the national health surveillance agency, maintains parallel oversight of industrial equipment safety standards affecting platform certification timelines. Macaé and Rio de Janeiro host the primary supplier qualification centers for offshore deployment.
Norway
North Sea drilling contractors demand mean-time-between-failure documentation over unit price given non-productive time economics. The Norwegian Petroleum Safety Authority enforces traceability requirements that filter uncertified producers from platform supply chains. Stavanger concentrates MRO contract relationships with long-term maintenance providers.
Saudi Arabia
Aramco drilling programs specify API 7F chains for new jack-up rigs, opening procurement windows outside established North Sea supplier relationships. The national oil company mandates third-party witness testing for critical path equipment. Dhahran and the Eastern Province anchor the procurement specification process for regional deployment.
China
Domestic shale development in Sichuan and Xinjiang is generating incremental demand for heavy-duty assemblies in high-shock drilling environments. GB standards and MIIT regulations govern dimensional interchangeability for equipment imports. Shanghai and Tianjin host the primary forging clusters serving both domestic and export specifications.
Oilfield Roller Chain Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in oilfield roller chain supply. Captive heat-treatment capacity and material certification infrastructure separate the upper tier from assembly-only competitors. Two strategic archetypes dominate: precision forgers with backward integration into alloy steel processing, and regional specialists with rapid MRO logistics capability. Competitive moves concentrate on capacity expansion for controlled atmosphere carburizing and strategic partnerships for offshore qualification acceleration.
Among integrated forgers, Rexnord Corporation and Renold Plc occupy positions representing the premium-tier vector with captive infrastructure. Tsubakimoto Chain Co. exemplifies the precision-specialist archetype with emphasis on pitch control technology. These three names anchor the competitive structure without exhausting the qualified supplier base.
| Leading Market Players |
|---|
| Rexnord Corporation |
| Renold Plc |
| Tsubakimoto Chain Co. |
| Daido Kogyo Co. Ltd. |
| Diamond Chain Company |
| Wippermann jr. GmbH |
| Zhejiang Gidi Industrial Chain Co., Ltd. |
| Emerson Bearing Company |
| Flowtools Middle East LLC |
| Others |
Supply Flow & Price Mechanics
API Specification 7F certification gates both supply qualification and price differentiation simultaneously, compressing the qualified supplier base while enabling compliant producers to command premium positioning in offshore deployments. Buyers in Brazilian pre-salt and North Sea markets accept extended procurement cycles and higher unit costs to secure documented metallurgical traceability that uncertified competitors cannot replicate.
Pricing Analysis
Long-term MRO contracts dominate procurement for critical-path drilling equipment, while spot purchasing persists for standard-grade auxiliary chain. Pricing stratifies across premium, standard, and economy tiers based on certification grade and captive heat-treatment capability. Cost compression in standard chain is intensifying because alloy steel input volatility squeezes assembly-only suppliers lacking backward integration into forging operations. Integrated oil companies demonstrate lowest price sensitivity given non-productive time economics, while independent maintenance providers compete aggressively on unit cost.
Supply Chain Analysis
Strategic stockpiling of case-hardening grade steel and finished chain inventory characterizes buyer behavior in Permian Basin operations, where replacement velocity trumps just-in-time efficiency. Manufacturing concentrates in China, Germany, and Japan, with forging clusters in Shanghai, Tianjin, and Kaga anchoring global supply. The chain draws from alloy steel mills, atmosphere furnace capacity, and precision grinding equipment as core inputs. Single-source vulnerability in controlled atmosphere carburizing infrastructure concentrates among integrated forgers. Distribution runs through OEM direct channels for specification-grade product and MRO distributors for standard replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oilfield roller chain supply exhibits defensive-moat characteristics rooted in regulatory entrenchment, where API 7F and ISO certification timelines create switching costs that protect incumbent positioning against unqualified competitors.
For Market Incumbents: Shield market position by accelerating plasma nitriding capacity additions in corrosion-resistant grades before mid-scale forgers achieve offshore qualification. Deepen backward integration into alloy steel processing to insulate margin structures from input volatility that threatens assembly-only competitors. The priority lever sits with preemptive certification investment rather than price competition. For New Entrants and Emerging Players: API 7F fast-track qualification through third-party witness testing partnerships offers the most viable entry path into Brazilian pre-salt and Middle East offshore markets. White-space concentrates in temporary setup applications for workover rigs, where distributor relationships and rapid availability outweigh specification documentation. Target onshore shale basins with heavy-duty chain positioned on replacement velocity rather than mean-time-between-failure guarantees. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision forging specialists lacking captive heat-treatment infrastructure. The five-to-ten year viability window favors targets with documented low-carbon process documentation aligned to EU CSRD scope 3 disclosure requirements. Watch plasma nitriding adoption curves as the inflection signal for competitive displacement of traditional carburizing incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Heat-Treatment Capacity Expansion | Atmosphere furnace investments in Houston and Macaé lock in API 7F qualification dominance for offshore deployments. |
| Plasma Nitriding Technology Adoption | Surface treatment partnerships with North Sea contractors decompose capital barriers for mid-scale forgers seeking subsea certification. |
| Digital Twin Integration | Predictive maintenance platforms with wear-monitoring sensors enable subscription-based replacement scheduling for critical pump drives. |
| Long-Term MRO Contract Anchoring | Stavanger and Dhahran maintenance agreements with drilling contractors create switching friction against new entrants. |
| EU Green Deal Alignment | Verified low-carbon heat-treatment documentation opens procurement scoring advantages with European offshore operators under CSRD. |
Methodological Framework
Desk research of API certification registries, OSHA enforcement records, and alloy steel trade data preceded structured interviews with drilling contractors, MRO procurement managers, forging plant engineers, and aftermarket service heads. Primary fieldwork across Permian Basin operations, North Sea platforms, and Brazilian pre-salt developments validated secondary estimates of replacement velocity and specification-grade procurement patterns. Bottom-up unit economics triangulated against top-down market sizing from customs filings and industry association membership data.
Variance decomposition across product grade, application criticality, installation geography, and end-user contract structure anchored the analytical framework throughout the projection horizon. CAGRs derived from replacement cycle modeling in shale basins and greenfield development timelines in offshore markets. Segmentation dimensions included chain specification tier, drilling equipment versus pump system application, and permanent versus temporary installation permanence. Forecast inputs incorporated alloy steel price elasticity, carburizing capacity utilization, and regulatory enforcement intensity trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained OSHA and BSEE traceability enforcement; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding certification timeline stability and pre-salt field development continuity. Revision becomes warranted when plasma nitriding qualification velocity crosses thresholds that restructure competitive tiering.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Netherlands LNG Bunkering Market
Oil & Gas
Asia Pacific Oil Storage Tank Service Market
Oil & Gas
Brazil Oil and Gas Market
Oil & Gas
Workover Rigs Market
Oil & Gas
India Oil and Gas Midstream Market
Oil & Gas
Kuwait & Iraq Oilfield Chemicals Market
Oil & Gas
Global Drilling Jars Market
Oil & Gas
North America Wireline Services Market
Oil & Gas
Oil and Gas Automation Market
Oil & Gas
Oilfield Rotary Table Market
Oil & Gas
South and Central America Oil Field Services Market
Oil & Gas
Middle-East and Africa Liner Hanger System Market
Oil & Gas
China Oil and Gas Market
Oil & Gas
Egypt Oil and Gas Midstream Market
Oil & Gas
Norway Oil and Gas Upstream Market
Oil & Gas
Crude Oil Desalter Market