
 Southeast Asia LNG Market | 2026-2036
Southeast Asia LNG Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia LNG Market Analytics
Spot cargo allocation channels is narrowing as long-term contract volumes reclaim share from short-term trading. Shell PLC leverages its integrated trading arm to sustain offtake flexibility across multiple Southeast Asian regasification terminals. Petronas anchors supply security through its Bintulu liquefaction complex and downstream petrochemical integration. PTT LNG Co Ltd dominates Thailand's import infrastructure with control over the Map Ta Phut terminal network.
Liquefied natural gas (LNG) consists predominantly of methane condensed to liquid form at minus 162 degrees Celsius for maritime transport, enabling energy-dense shipment across distances where pipeline economics fail. The primary commercial purpose centers on delivering cleaner-burning fuel to power grids and industrial facilities lacking domestic gas reserves or pipeline connectivity. Regasification terminals represent the most mature infrastructure segment with established margin pools, while floating storage units capture the fastest expansion as Vietnam and the Philippines seek lower-carbon baseload without onshore construction delays. LNG carrier vessels compete on boil-off rate efficiency and vessel size, with newbuilds concentrating in the 170,000-180,000 cubic meter range for Southeast Asian route economics.
Thailand's Energy Regulatory Commission and Indonesia's BPH Migas jointly shape import licensing frameworks that determine market access for new terminal developers. Singapore's Energy Market Authority enforces stringent storage and bunkering standards that cascade across ASEAN trading hub operations. Vietnam's Ministry of Industry and Trade is drafting domestic gas distribution regulations that will determine how LNG competes with coal in northern industrial provinces. Stakeholders must monitor which regulatory body moves first on carbon border adjustments, as this will redirect LNG procurement toward lower-emission supply sources.
Market Dynamics
Long-term contract structures are reclaiming procurement share from spot markets as buyers seek supply security amid price volatility, fundamentally altering how regasification terminals allocate throughput capacity across Indonesia, Thailand, and Vietnam.
Growth Catalysts
- Indonesia's BPH Migas import licensing reforms:Streamlined terminal access permits are accelerating private sector participation in Java's power generation expansion.
- Floating storage and regasification units (FSRUs):These vessel-based terminals are compressing project timelines for Vietnam and the Philippines, bypassing onshore construction delays.
- Industrial zone clustering near Ba Ria-Vung Tau:Vietnam's steel and petrochemical facilities are aggregating demand sufficient to anchor dedicated LNG supply infrastructure.
Market Restraints
- Henry Hub-linked contract exposure:Southeast Asian buyers face margin compression when US benchmark prices spike, creating procurement cost volatility.
- Qatari and Australian supply concentration:Overreliance on these two source markets creates vulnerability to upstream disruptions or diplomatic friction.
- Thailand's Energy Regulatory Commission tariff structures:Regulated terminal access fees limit importer flexibility to optimize landed costs through portfolio trading.
Strategic Opportunities
- Myanmar's underdeveloped power grid:Cross-border electricity trade from Thai LNG-fired plants could supply Yangon's industrial corridor without domestic terminal investment.
- Carbon border adjustment mechanisms:Early alignment with emerging EU carbon border rules positions LNG to capture market share from coal in export-oriented manufacturing.
- Bunkering infrastructure at Singapore:The Maritime Port Authority's LNG marine fuel standards are creating a regional hub for vessel refueling services.
Industry Challenges
- Cryogenic engineering talent scarcity:Terminal operators in Vietnam and the Philippines struggle to recruit sufficient trained personnel for FSRU commissioning and maintenance.
- Legacy coal plant retrofit complexity:Converting existing Indonesian and Thai thermal units to gas firing requires boiler modifications and pipeline interconnections that extend project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia LNG Market |
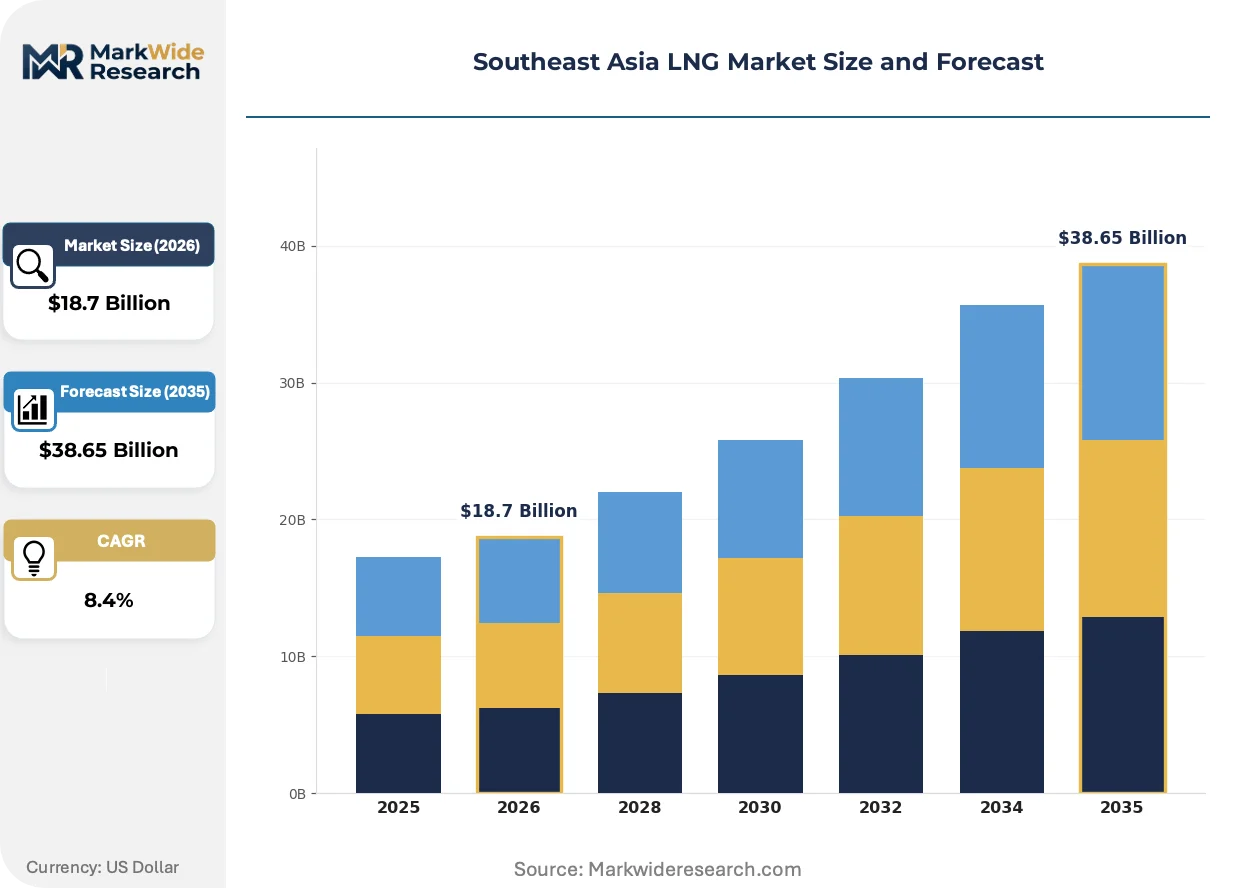
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquefaction Facilities, Regasification Terminals, Floating Storage Units, LNG Carrier Vessels End User: Power Generation, Industrial, Residential, Transportation Distribution Channel: Direct Sales, Wholesale, Online Platforms, Trading Hubs Application: Electricity Generation, Heating, Fuel for Vehicles, Industrial Processes |
| Companies Covered | PTT LNG Co Ltd, GULF, Petronas, TotalEnergies SE, Shell PLC, Singapore LNG Corporation Pte Ltd, PT PGN LNG Indonesia, Petroliam Nasional Bhd, JGC Holding Corporation, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia LNG Market Evolving Landscape
Technology deployment and regulatory recalibration are compressing traditional infrastructure timelines while procurement behaviors adapt to energy security imperatives across the ASEAN region.
Modular liquefaction trains are collapsing the minimum efficient scale for gas monetization, enabling stranded field development in East Kalimantan and Papua that previously failed pipeline economics. Indonesian state planners are evaluating these systems for remote archipelago supply, with initial deployments targeting 0.5-1.0 million tonne per annum output. The structural consequence is fragmentation of supply sources, reducing buyer concentration risk but complicating quality standardization.
Thailand's Energy Regulatory Commission revised its third-party access framework for Map Ta Phut terminal capacity, mandating published tariffs and non-discriminatory queue management. This industrial consequence opens import infrastructure to independent power producers previously dependent on PTT LNG Co Ltd's merchant supply. The segment most affected—industrial estates in Rayong and Chonburi—is responding by negotiating direct offtake agreements with portfolio suppliers.
Buyers are consolidating procurement through centralized purchasing desks, with Vietnam's Ministry of Industry and Trade coordinating state-owned utility demand into unified tenders. This aggregation disrupts the bilateral contract tradition that dominated early market development, replacing it with competitive auction mechanisms. The shift is most visible in northern industrial provinces where Vinacomin's coal displacement timeline is accelerating gas demand aggregation.
Southeast Asia LNG Market Segmentation
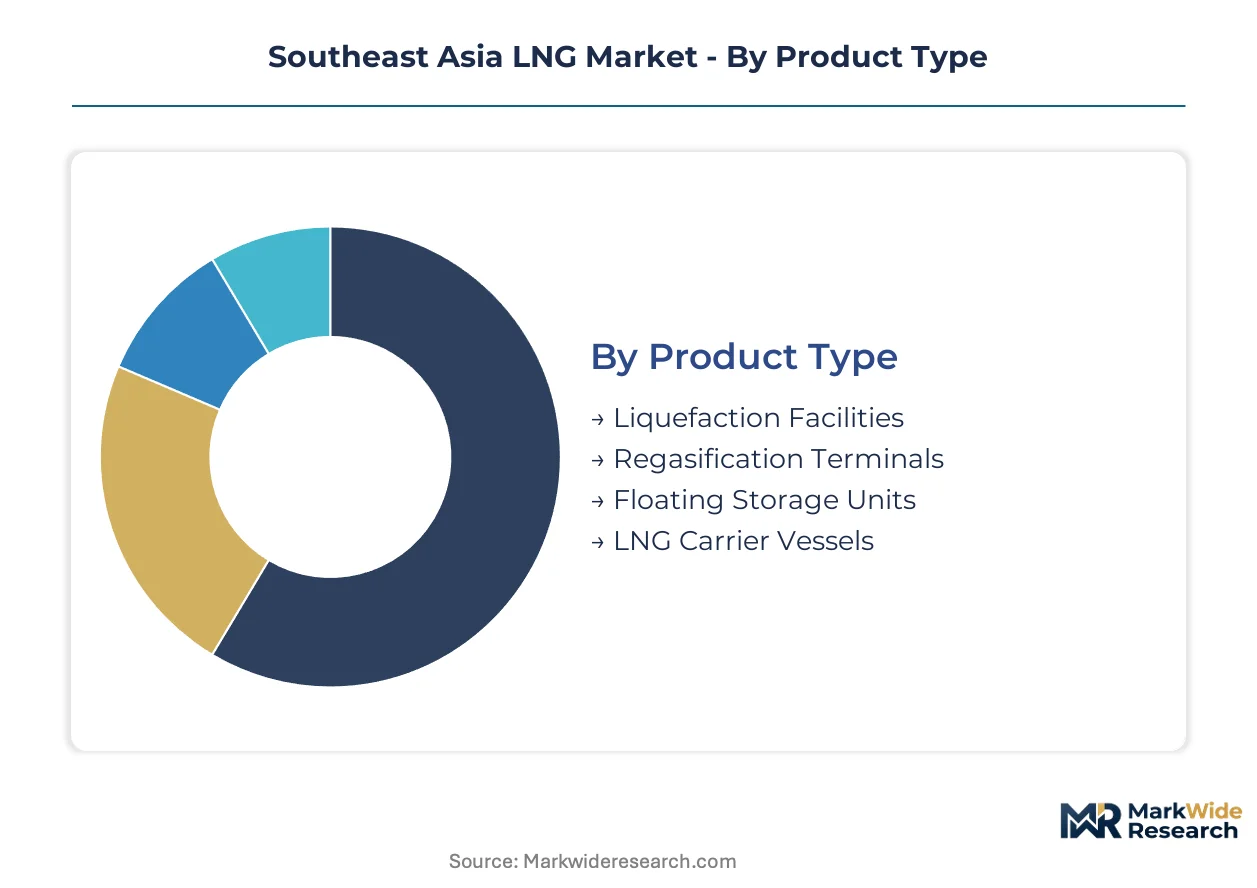
LNG infrastructure segmentation reveals how capital allocation and operational complexity vary across asset classes and customer interfaces. Service intensity differs sharply between terminal operations requiring continuous cryogenic maintenance versus vessel chartering with discrete deployment cycles.
Product Type:
After-sales service intensity peaks with regasification terminals demanding 24/7 cryogenic monitoring and scheduled turbine overhauls, while carrier vessels operate on voyage-based maintenance windows.
- Liquefaction Facilities:These upstream plants condense feedstock gas to minus 162 degrees Celsius through multi-stage refrigeration trains. Demand concentrates in Indonesia's Bintulu complex and proposed East Kalimantan modular projects driven by stranded field monetization. After-sales contracts center on turbine and heat exchanger refurbishment cycles.
- Regasification Terminals:Onshore facilities vaporize liquid cargo for pipeline injection through open-rack or submerged combustion systems. Thailand's Map Ta Phut network and Vietnam's Thi Vai project anchor regional capacity expansion constrained by jetty dredging permits and third-party access negotiations.
- Floating Storage Units:Vessel-based terminals compress project timelines for markets lacking onshore construction capacity. FSRU deployments in Vietnam and the Philippines accelerate import infrastructure without land acquisition delays.
- LNG Carrier Vessels:Specialized tankers compete on boil-off rate efficiency and cargo containment system reliability. Newbuilds concentrate in the 170,000-180,000 cubic meter range optimized for Southeast Asian route economics and port depth constraints.
Regasification terminals hold the largest share; momentum sits with floating storage units.
End User:
Customer sophistication and contract scale separate baseload power utilities from fragmented residential distributors.
- Power Generation:Grid-connected utilities procure through long-term take-or-pay contracts indexed to Henry Hub or Brent spreads. Indonesia's PLN and Thailand's EGAT anchor demand as coal displacement accelerates in Java and the Chao Phraya basin.
- Industrial:Steel, petrochemical, and ceramics facilities purchase through direct terminal offtake or aggregator intermediaries. Vietnam's Ba Ria-Vung Tau industrial zone clusters sufficient demand to anchor dedicated FSRU mooring.
- Residential:City gas distribution networks serve urban households through localized regasification and pipeline reticulation. Penetration remains limited to Bangkok, Jakarta, and Singapore due to infrastructure capital requirements.
- Transportation:Marine bunkering and heavy-duty trucking represent emerging demand segments. Singapore's Maritime Port Authority standards are creating a regional LNG marine fuel hub at Jurong Port.
Power generation dominates procurement volumes; industrial offtake is climbing the fastest.
Distribution Channel:
Channel selection reflects buyer scale, creditworthiness, and portfolio sophistication across the ASEAN region.
- Direct Sales:Producer-to-utility contracts eliminate intermediary margins for creditworthy offtakers with terminal access rights. Shell and Petronas leverage integrated trading arms for direct delivery to Indonesian and Thai power generators.
- Wholesale:Aggregators consolidate fragmented industrial demand into import-scale cargoes. Portfolio suppliers intermediate between Qatari and Australian sources and Vietnamese manufacturing estates.
- Online Platforms:Digital trading screens match spot cargo availability with short-term demand, though liquidity remains thin relative to European and East Asian hubs.
- Trading Hubs:Singapore anchors regional price discovery through storage and bunkering infrastructure, with Malaysian and Indonesian terminals increasingly referencing its benchmarks.
Direct sales command the largest contract value; wholesale aggregation is gaining share fastest.
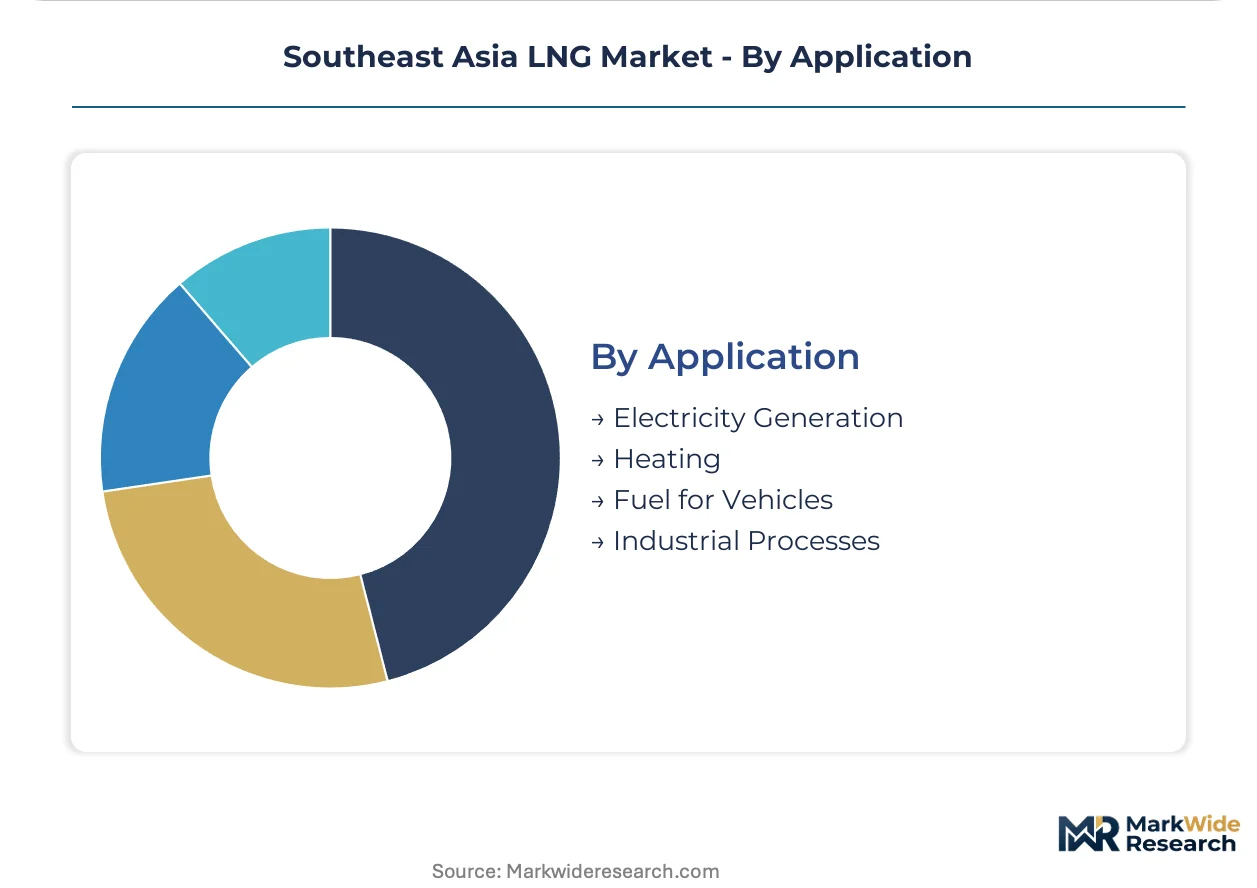
Application:
Application segmentation tracks how LNG competes against coal, diesel, and pipeline gas across energy service requirements.
- Electricity Generation:Combined-cycle gas turbines displace coal in baseload and mid-merit dispatch. Thailand's IPP auctions and Vietnam's PDP8 implementation are redirecting capacity additions toward gas-fired units.
- Heating:Industrial process heat and limited residential space conditioning utilize LNG where pipeline networks are absent. Ceramics and food processing plants in Indonesia's outer islands rely on small-scale regasification.
- Fuel for Vehicles:Heavy-duty trucking and maritime propulsion adopt LNG to meet sulfur emission limits. Singapore's LNG bunkering standards cascade to regional port authorities.
- Industrial Processes:Petrochemical feedstock and metallurgical applications require consistent heating value specifications. Ammonia and methanol producers in Malaysia's Kertih complex anchor dedicated liquefaction offtake.
Electricity generation holds the largest share; fuel for vehicles shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's Energy Regulatory Commission tariff reforms are compressing project timelines for private terminal access. Indonesia's BPH Migas import licensing streamlines are accelerating Java power generation expansion. Vietnam's Ministry of Industry and Trade coordinates state utility demand into unified procurement tenders.
Indonesia
Java's PLN baseload expansion drives LNG demand as coal displacement accelerates in the Chao Phraya basin. BPH Migas import licensing reforms streamline terminal access permits for private sector participation. East Kalimantan and Papua stranded fields target modular liquefaction deployment for remote archipelago supply.
Thailand
EGAT's combined-cycle gas turbine procurement anchors regional demand through long-term Henry Hub-linked contracts. The Energy Regulatory Commission's third-party access framework mandates published tariffs and non-discriminatory queue management at Map Ta Phut. Rayong and Chonburi industrial estates negotiate direct offtake agreements with portfolio suppliers.
Vietnam
Ba Ria-Vung Tau steel and petrochemical facilities aggregate sufficient demand to anchor dedicated FSRU mooring infrastructure. The Ministry of Industry and Trade drafts domestic gas distribution regulations determining LNG competition with coal in northern provinces. Thi Vai project capacity expansion proceeds constrained by jetty dredging permits.
Singapore
The Maritime Port Authority's LNG marine fuel standards create regional bunkering hub operations at Jurong Port. The Energy Market Authority enforces stringent storage standards that cascade across ASEAN trading operations. Jurong Island petrochemical complexes anchor dedicated liquefaction offtake for ammonia and methanol producers.
Philippines
FSRU deployments accelerate import infrastructure without land acquisition delays that plague onshore construction. The Department of Energy evaluates cross-border electricity trade from Thai LNG-fired plants for Luzon industrial supply. Batangas Bay clustering concentrates demand for vessel-based terminal mooring.
Southeast Asia LNG Market Competitive Landscape
On the supply side, the industry is consolidating around integrated energy majors with captive liquefaction and trading arms. National oil companies anchor supply security through domestic liquefaction complexes and downstream petrochemical integration. Three archetypes dominate: integrated majors with global trading desks, state-owned national champions with infrastructure control, and specialized terminal operators with regional geographic focus. Competitive moves center on long-term offtake contract aggregation and floating storage technology deployment.
Within the state-owned tier, Petronas exemplifies vertical integration from Bintulu liquefaction through downstream petrochemical offtake. PTT LNG Co Ltd anchors Thailand's import infrastructure position through Map Ta Phut terminal network control. Shell PLC represents the integrated major archetype with trading arm flexibility across multiple Southeast Asian regasification terminals.
| Leading Market Players |
|---|
| PTT LNG Co Ltd |
| GULF |
| Petronas |
| TotalEnergies SE |
| Shell PLC |
| Singapore LNG Corporation Pte Ltd |
| PT PGN LNG Indonesia |
| Petroliam Nasional Bhd |
| JGC Holding Corporation |
| Others |
Value Network & Pricing Analysis
Underutilization at Vietnam's Thi Vai terminal is compressing spot cargo premiums and forcing suppliers toward longer-term contract structures that lock in offtake commitments. Thailand's Energy Regulatory Commission tariff reforms simultaneously reshape how importers optimize landed costs through portfolio trading versus regulated terminal access.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with Henry Hub-linked contracts commanding premium positions against Brent-indexed alternatives and spot cargoes occupying the economy tier. Price differentiation rests on supply source diversity and carbon intensity certification, with Qatari supply attracting brand premiums over Australian volumes. Cost compression in the spot tier is intensifying because floating storage deployment is collapsing project timelines and expanding import capacity faster than demand aggregation. Industrial offtakers in Vietnam's Ba Ria-Vung Tau zone exhibit highest price sensitivity due to coal displacement economics, while Singapore bunkering operators show least sensitivity given marine fuel regulatory mandates.
Supply Chain Analysis
Extended payment terms from Qatari and Australian suppliers are becoming standard practice as liquefaction project developers seek to secure Southeast Asian offtake commitments amid competing supply source proliferation. Geographic supply concentration centers on Qatar, Australia, and emerging US Gulf Coast export capacity, with Indonesian Bintulu and Malaysian Bintulu providing regional diversification. Raw material dependencies include natural gas feedstock, specialized cryogenic steel for containment systems, and membrane containment technology licensed from French and Japanese engineering houses. Single-source vulnerability in FSRU vessel availability creates bottleneck risk as Vietnam and the Philippines compete for limited charter fleet. Distribution runs through integrated major trading arms and national oil company aggregators rather than independent merchant intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Southeast Asia LNG operates as a substitution defense market where coal displacement timelines and renewable intermittency management determine incumbent value capture against solar-plus-storage and hydrogen pilot projects.
For Market Incumbents: Insulate contract portfolios through backward integration into floating storage technology deployment and captive liquefaction offtake at Bintulu and Map Ta Phut. Secure terminal access rights under Thailand's third-party access framework before queue congestion materializes. Prioritize carbon intensity certification investment to capture EU carbon border adjustment alignment premiums as manufacturing export demand evolves. For New Entrants and Emerging Players: Myanmar's underdeveloped power grid and cross-border electricity trade potential from Thai LNG-fired plants represent the most penetrable entry point without domestic terminal capital requirements. Philippine FSRU deployment timelines, compressed by land acquisition constraints blocking onshore construction, offer second-mover infrastructure participation. Pursue direct offtake negotiations with Rayong and Chonburi industrial estates bypassing PTT LNG Co Ltd's merchant supply monopoly. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated majors with captive liquefaction and long-term utility offtake contracts indexed to Henry Hub or Brent spreads. Five-to-ten year viability favors state-backed national champions with infrastructure control and downstream petrochemical integration over pure trading plays. Monitor Vietnam's Ministry of Industry and Trade domestic gas distribution regulation finalization as the signal indicating whether northern industrial province coal displacement accelerates or stalls.| Strategic Initiative | Industry Significance |
|---|---|
| FSRU Fleet Expansion | Vessel-based terminals compress Vietnam and Philippines project timelines without land acquisition delays. |
| Long-term Supply Agreement | Henry Hub-linked contracts anchor Indonesian PLN and Thai EGAT baseload procurement security. |
| Backward Integration into Storage | Terminal access rights at Map Ta Phut and Thi Vai lock in throughput capacity for portfolio suppliers. |
| Green Certification Program | Carbon intensity alignment positions LNG to capture EU carbon border adjustment premiums from export manufacturers. |
| Joint Venture | Modular liquefaction partnerships in East Kalimantan enable stranded field monetization for remote archipelago supply. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EIA data, IEA reports, FERC filings, and project development databases to establish supply-demand balances and infrastructure commissioning timelines. Utility planning officers, IPP project developers, EPC contractors, and fuel supply specialists provided operational perspectives on terminal utilization and contract structuring. Bottom-up cargo flow analysis triangulates against top-down macro demand projections from national power development plans.
Forecast inputs span liquefaction capacity additions, regasification terminal commissioning schedules, and Henry Hub price trajectory assumptions across the analysis window. Segmentation dimensions include infrastructure asset class, end-use sector, and distribution channel sophistication. CAGRs derive from weighted capacity expansion timelines and demand aggregation patterns in Vietnam's industrial zones and Indonesia's Java power corridor.
Macroeconomic conditions sit as an overlay; deviation in regional currency stability, US benchmark gas price volatility, or EU carbon border implementation timing would shift the trajectory. Forecasts reflect documented assumptions regarding coal displacement policy enforcement and FSRU charter fleet availability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
North America Fracking Chemicals Market
Oil & Gas
Russia Oilfield Services Market
Oil & Gas
North America Frac Sand Market
Oil & Gas
Crown Block Market
Oil & Gas
Angola Oil and Gas Upstream Market
Oil & Gas
Libya Oil and Gas Upstream Market
Oil & Gas
Liquefied Natural Gas Market
Oil & Gas
Oil and Gas Automation Market
Oil & Gas
Geothermal Drilling Market
Oil & Gas
Enclosed Flares Market
Oil & Gas
Pipeline Pigging Services Market
Oil & Gas
Australia Oil and Gas Upstream Market
Oil & Gas
Saudi Arabia Drilling Services Market
Oil & Gas
Central Asia Oil and Gas Market
Oil & Gas
Canada Oil and Gas Pipeline Services Market
Oil & Gas
Hydraulic Fracturing Market