
 Open Hole Logging Services Market | 2026-2036
Open Hole Logging Services Market Size, Share, and Industry Trends Forecast 2026-2036
Open Hole Logging Services Market Analytics
The procurement channel between national oil companies and independent logging contractors is rewriting contract structures across offshore basins. Schlumberger Limited leverages its integrated wireline platform to sustain long-term service agreements in the Middle East. Halliburton Company anchors its position through Logging While Drilling specialization in unconventional plays. Baker Hughes Company differentiates via electromagnetic logging toolsets for high-temperature formations.
Open hole logging services encompass subsurface measurement operations conducted in uncased wellbores, utilizing wireline-conveyed or drillstring-integrated sensor arrays to capture acoustic, nuclear, and resistivity data at temperatures exceeding 175°C and pressures above 20,000 psi. These measurements enable hydrocarbon saturation mapping, porosity determination, and mechanical property assessment for completion design and reserve certification. Wireline services retain the largest revenue share due to established reliability in standard well profiles, while Logging While Drilling commands premium pricing in extended-reach and horizontal trajectories where real-time geosteering reduces non-productive time. Nuclear logging maintains steady demand for lithology identification in complex carbonate reservoirs, though electromagnetic logging grows fastest as operators seek reduced radioactive source dependency.
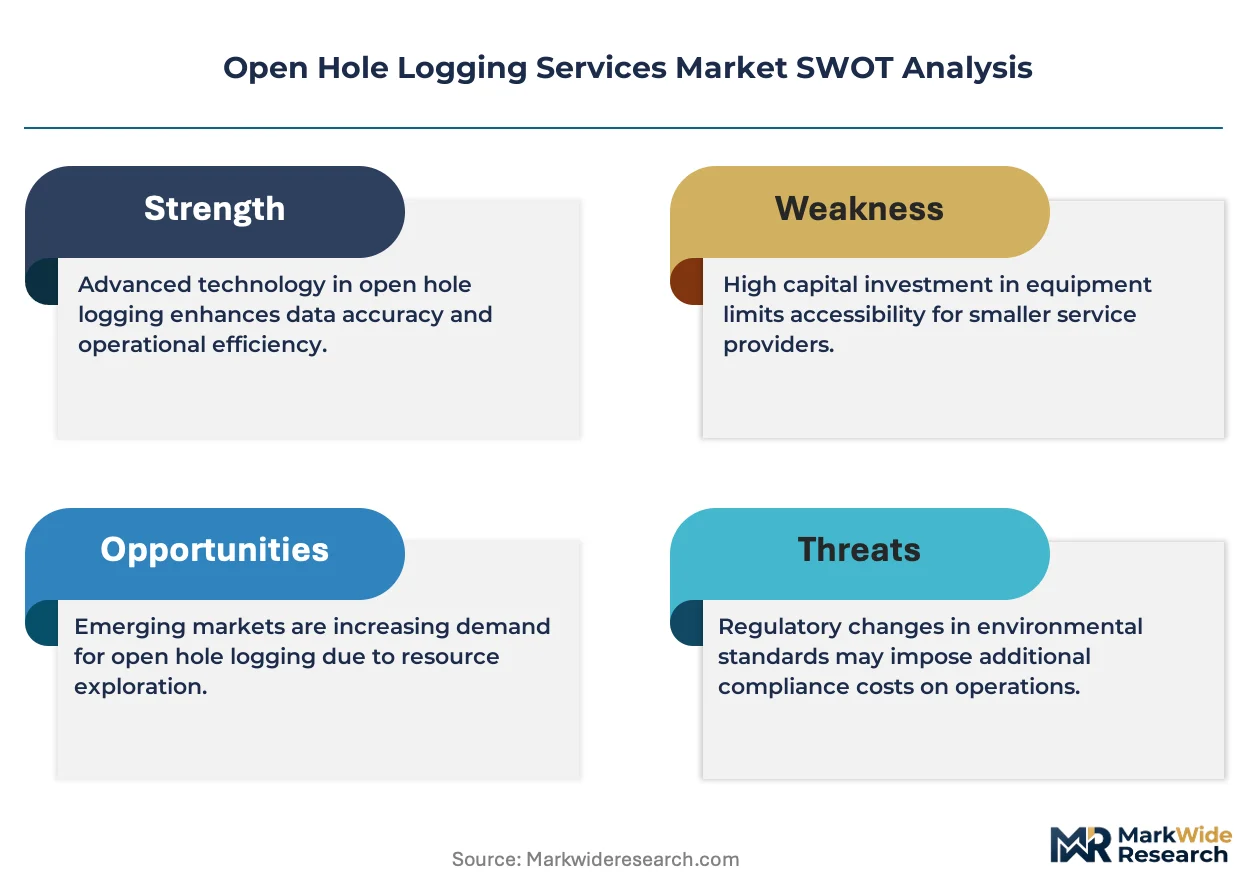
Offshore regulators including BSEE in the United States, NORSOK standards in Norway, and ANP technical requirements in Brazil mandate comprehensive formation evaluation documentation before casing installation, directly expanding logging service scope. The EPA and OSHA frameworks governing radioactive source transport and handling impose compliance costs that favor larger service organizations with dedicated logistics infrastructure. Stakeholders must weigh technology substitution risks against contractual lock-in as resistivity and acoustic platforms displace legacy nuclear tools in environmentally sensitive jurisdictions.
Market Dynamics
Wireline-conveyed measurement platforms face structural pressure from drillstring-integrated sensor arrays that compress logging timelines in extended-reach trajectories. Real-time data transmission capabilities now determine contract award criteria across offshore basins.
Growth Catalysts
- ANP Technical Requirements:Brazil's offshore regulator mandates comprehensive formation evaluation documentation before casing installation, expanding mandatory service scope for logging contractors operating in pre-salt blocks.
- Shale operators:US Gulf of Mexico independents pursue higher-resolution reservoir characterization to optimize fracture staging, pulling demand for advanced acoustic and resistivity packages.
- Electromagnetic logging:This technology eliminates radioactive source dependency in environmentally sensitive jurisdictions, opening access to permits previously restricted under EPA transport frameworks.
Market Restraints
- Radioactive source logistics:EPA and OSHA compliance costs for cesium and americium handling favor organizations with dedicated logistics infrastructure, creating barriers for mid-scale contractors.
- High-temperature tool reliability:Formation temperatures exceeding 175°C degrade conventional electronics, limiting addressable reservoir depth in deepwater Brazil and West Africa.
- Wireline platform concentration:Established reliability in standard well profiles locks in legacy equipment depreciation cycles, slowing capital rotation toward LWD systems.
Strategic Opportunities
- West Africa deepwater:Underpenetrated pre-salt analogs in Angola and Nigeria offer whitespace for integrated logging-while-drilling packages with geosteering capabilities.
- Carbonate lithology identification:Complex Middle Eastern reservoirs drive demand for nuclear spectroscopy tools that distinguish dolomite from limestone porosity systems.
- NORSOK standards convergence:Norway's offshore safety framework is migrating toward real-time well integrity monitoring, creating pull for permanent downhole gauge integration with open hole measurements.
Industry Challenges
- Petrophysicist specialization:Shortage of engineers capable of interpreting tri-axial resistivity and azimuthal sonic data in unconventional trajectories extends project timelines.
- Legacy system integration:Operators running 1990s-era acquisition software face data format incompatibilities with modern cloud-based interpretation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Open Hole Logging Services Market |
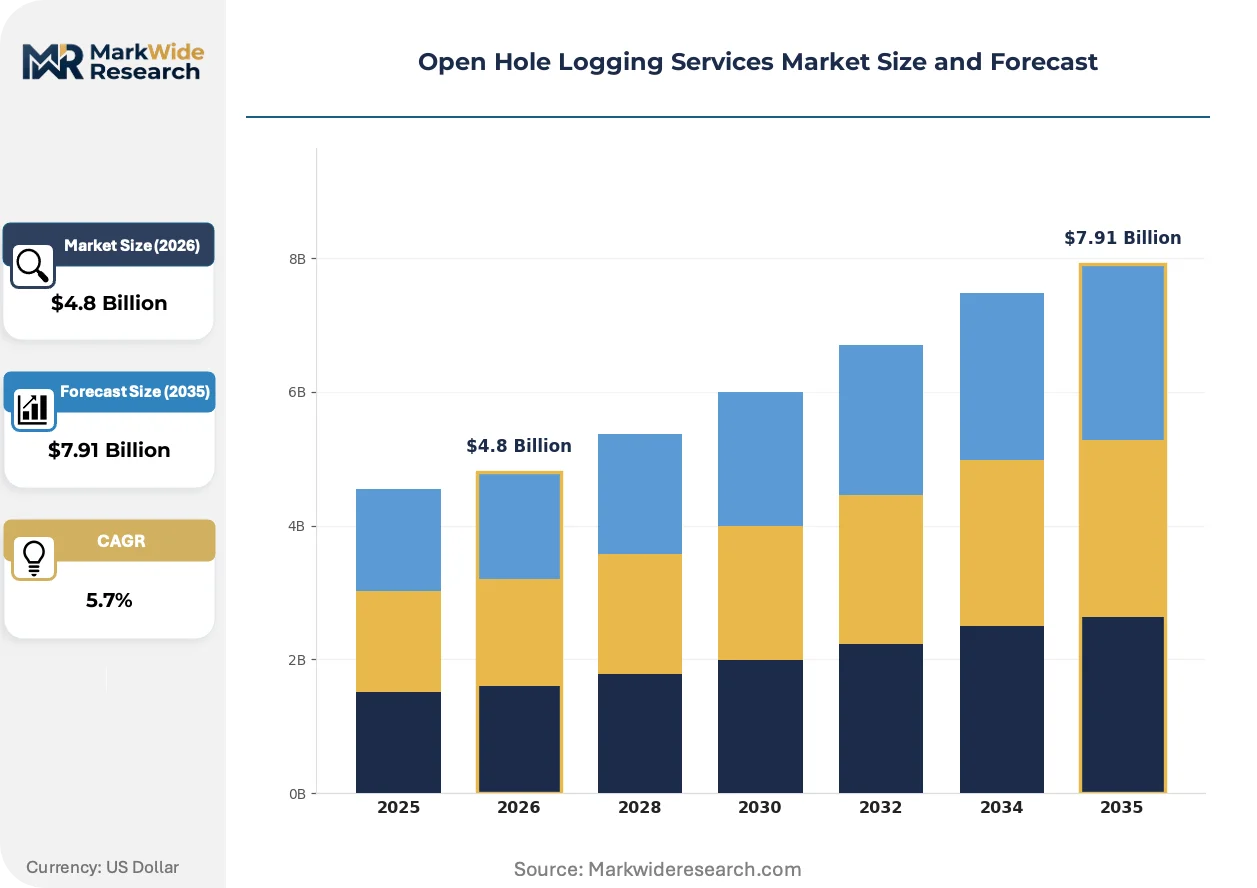
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Wireline, Logging While Drilling, Perforation, Pressure Testing Technology: Acoustic Logging, Nuclear Logging, Electromagnetic Logging, Resistivity Logging End User: Oil Companies, Service Providers, Exploration Firms, Research Institutions Application: Hydrocarbon Exploration, Resource Assessment, Reservoir Characterization, Formation Evaluation |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, Weatherford International Plc, China Oilfield Services Limited, Superior Energy Services Inc, Nabors Industries Ltd, OilServ, RECON Petrotechnologies Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Open Hole Logging Services Market Evolving Landscape
Measurement-while-drilling sensor density is compressing the traditional wireline logging window. Tool miniaturization and telemetry bandwidth expansion now enable reservoir characterization without dedicated trip times.
Ultrasonic borehole imagers with 360-degree coverage are rendering obsolete conventional four-arm caliper tools for fracture orientation mapping. Shale operators in the Permian and Eagle Ford have adopted these systems for 70 percent of horizontal sections. The technology is compressing the time between drilling and completion design decisions from days to hours.
EPA source material handling restrictions are tightening transport corridors for radioactive logging tools across US interstate highways. Rail and dedicated freight contracts now dominate cesium-137 movement, adding 15-20 percent to mobilization costs for nuclear spectroscopy services. Independent operators in the Rockies and Mid-Continent are accelerating electromagnetic induction substitutions to bypass these logistics constraints.
Integrated service contracting is displacing discrete logging procurement in deepwater projects. National oil companies in Brazil and West Africa now bundle formation evaluation with directional drilling and mud logging under single-vendor frameworks. This consolidation concentrates award decisions on total well delivery performance rather than individual tool specifications.
Open Hole Logging Services Market Segmentation
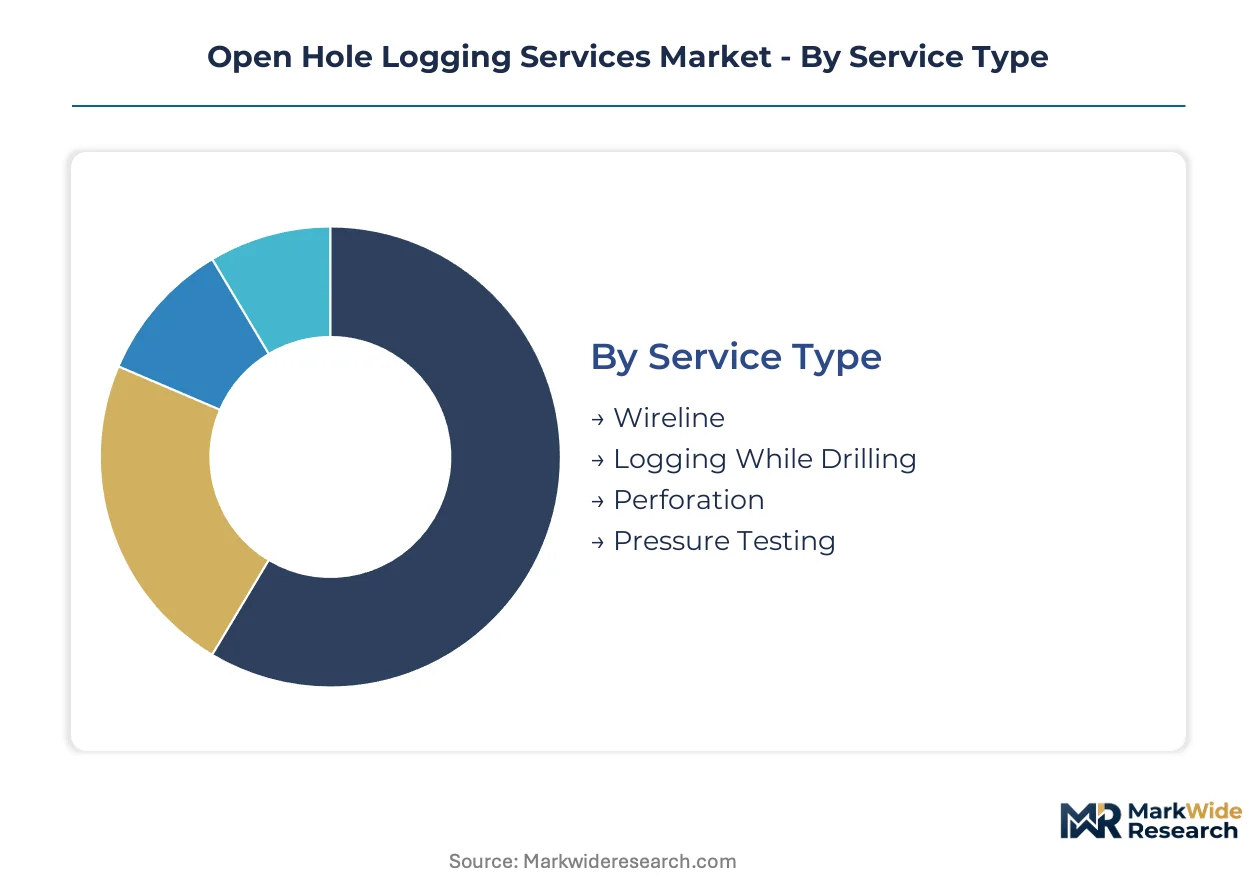
Open hole logging services fragment across four operational dimensions. Service type and technology determine equipment depreciation cycles and contract pricing. End-user concentration shapes procurement leverage and vendor selection criteria.
Service Type:
Wireline services turn capital fastest through standardized mobilization, while Logging While Drilling compresses timelines in extended-reach trajectories. Perforation and pressure testing operate on slower replacement cycles tied to completion schedules.
- Wireline:Conveyed via cable from surface to uncased boreholes, wireline platforms capture acoustic, nuclear, and resistivity measurements at temperatures exceeding 175°C. Demand concentrates in the US Gulf of Mexico where shale operators pursue higher-resolution reservoir characterization for fracture staging optimization.
- Logging While Drilling:Drillstring-integrated sensor arrays transmit real-time data during drilling operations, eliminating dedicated logging trips. West Africa deepwater campaigns in Angola and Nigeria pull demand for geosteering-capable packages where wellbore stability risks escalate.
- Perforation:Services create controlled fractures in casing and cement to enable hydrocarbon flow from formation to wellbore.
- Pressure Testing:Operations validate formation integrity and zonal isolation prior to completion installation.
Wireline dominates installed base. Logging While Drilling is where expansion concentrates.
Technology:
Technology selection tracks formation complexity and environmental compliance exposure. Electromagnetic and resistivity platforms displace legacy nuclear tools in regulated jurisdictions.
- Acoustic Logging:Ultrasonic borehole imagers with 360-degree coverage map fracture orientation and mechanical properties. Permian and Eagle Ford shale operators have adopted these systems for horizontal section evaluation, compressing drilling-to-completion decision timelines from days to hours.
- Nuclear Logging:Cesium-137 and americium-based spectroscopy tools distinguish lithology in complex carbonate reservoirs. EPA and OSHA transport restrictions across US interstate highways have added 15-20 percent to mobilization costs, pushing Rockies and Mid-Continent independents toward electromagnetic substitutions.
- Electromagnetic Logging:Induction-based measurements eliminate radioactive source dependency, opening permit access in environmentally sensitive jurisdictions.
- Resistivity Logging:Tri-axial and azimuthal arrays map hydrocarbon saturation and formation water salinity.
Acoustic and resistivity platforms anchor current deployment. Electromagnetic logging is gaining share fastest as regulatory pressure intensifies.
End User:
Customer type determines contract structure and technical specification authority. National oil companies bundle services; independents prioritize discrete tool performance.
- Oil Companies:Integrated operators and national oil companies in Brazil and West Africa now procure formation evaluation through single-vendor frameworks that bundle logging with directional drilling and mud logging.
- Service Providers:Independent logging contractors compete on specialized tool reliability and petrophysicist interpretation quality.
- Exploration Firms:Early-stage operators prioritize rapid reservoir characterization to secure farm-out agreements.
- Research Institutions:Academic and government laboratories drive next-generation sensor development for extreme-pressure environments.
Oil companies command procurement volume. Service providers face margin pressure from integrated contracting consolidation.
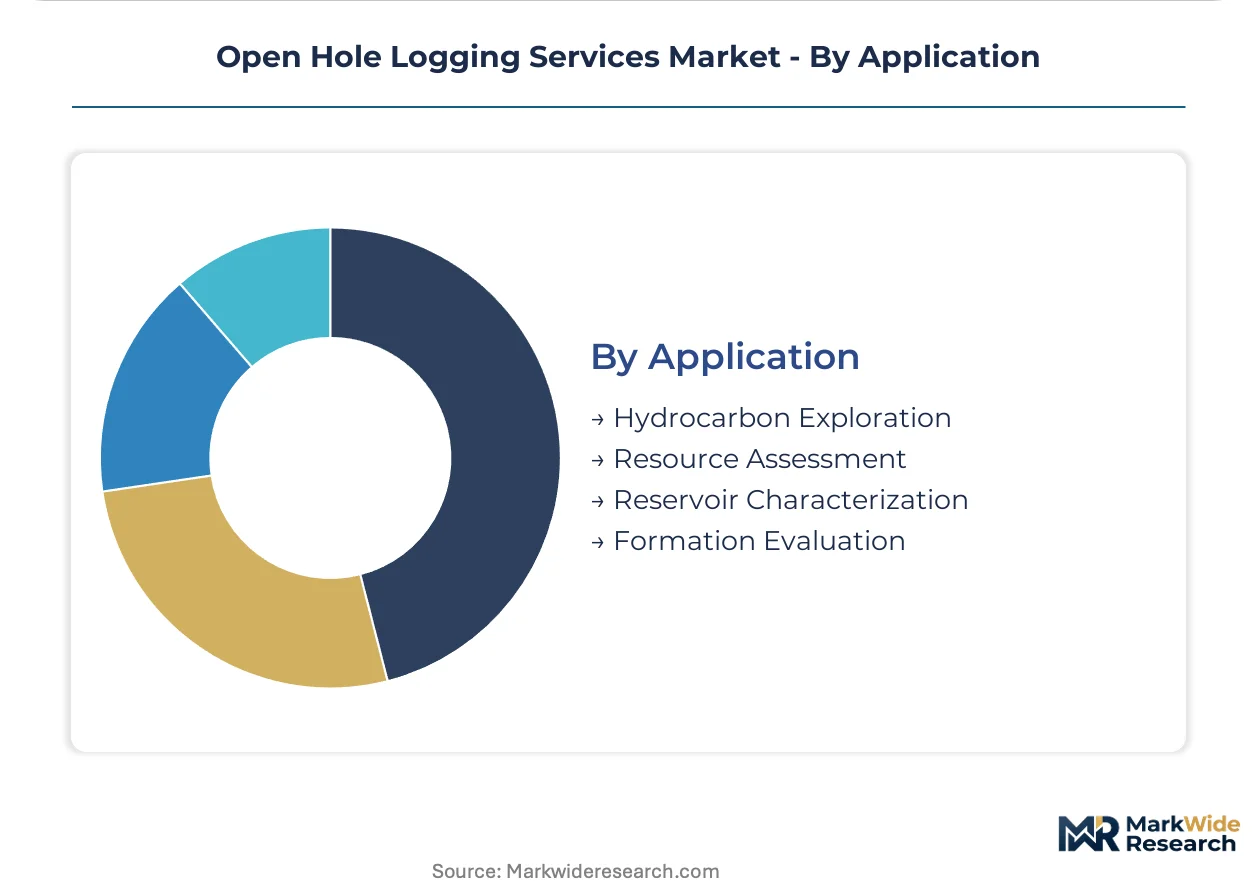
Application:
Application scope tracks regulatory mandate intensity and reserve certification requirements. Formation evaluation carries mandatory documentation obligations in offshore jurisdictions.
- Hydrocarbon Exploration:Greenfield drilling campaigns in pre-salt Brazil and West Africa require comprehensive logging programs to satisfy ANP technical requirements before casing installation.
- Resource Assessment:Reserve certification for capital markets and joint venture partners demands auditable formation evaluation data.
- Reservoir Characterization:Detailed porosity and permeability mapping enables optimized completion design and production forecasting.
- Formation Evaluation:BSEE in the United States, NORSOK standards in Norway, and ANP in Brazil mandate comprehensive documentation, directly expanding mandatory service scope.
Formation evaluation dominates regulatory-driven demand. Reservoir characterization is where technology substitution accelerates fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BSEE offshore safety mandates in the United States anchor the dominant geography for open hole logging services. Deepwater pre-salt campaigns in Brazil and West Africa pull specialized formation evaluation packages. Stricter well integrity requirements across multiple jurisdictions expand mandatory service scope.
United States
Shale operators in the Permian and Eagle Ford pursue higher-resolution reservoir characterization for fracture staging optimization. EPA transport restrictions on cesium-137 across interstate highways add 15-20 percent to nuclear logging mobilization costs. Houston anchors the largest concentration of wireline service contractors and equipment manufacturing facilities.
Brazil
Pre-salt deepwater exploration in the Santos Basin demands integrated logging-while-drilling packages with geosteering capabilities. ANP technical requirements mandate comprehensive formation evaluation documentation before casing installation. Rio de Janeiro hosts the primary operational headquarters for offshore logging contractors serving pre-salt blocks.
Norway
NORSOK standards convergence toward real-time well integrity monitoring creates demand for permanent downhole gauge integration. Electromagnetic logging tool adoption accelerates as operators seek reduced radioactive source dependency. Stavanger concentrates advanced sensor development for extreme-pressure North Sea environments.
United Kingdom
North Sea decommissioning schedules extend logging service windows for late-life reservoir characterization. Health and Safety Executive frameworks govern radioactive source handling protocols across offshore installations. Aberdeen maintains specialized petrophysicist talent pools for complex carbonate interpretation.
China
Sinopec and CNPC unconventional campaigns in Sichuan shale basins pull demand for azimuthal sonic and tri-axial resistivity arrays. MIIT equipment certification requirements shape procurement criteria for high-temperature logging tools. Tianjin and Shenzhen host manufacturing clusters for drillstring-integrated sensor systems.
Open Hole Logging Services Market Competitive Landscape
Integrated energy service conglomerates and specialized logging contractors split the market into distinct capability tiers. Three strategic archetypes dominate: full-service wireline platform operators, Logging While Drilling technology specialists, and regional electromagnetic logging pure-plays. Consolidation pressures intensify as national oil companies bundle formation evaluation with directional drilling under single-vendor frameworks. Technology licensing agreements and strategic partnerships represent the dominant competitive moves for capability expansion without capital-intensive manufacturing investments.
Within the integrated service tier, Schlumberger Limited, Halliburton Company, and Baker Hughes Company occupy positions as archetype anchors. These entities exemplify the full-service model through established wireline platforms and drillstring-integrated sensor arrays. Their scale enables dedicated logistics infrastructure for EPA and OSHA radioactive source compliance, creating structural barriers for mid-scale contractors. Regional specialists compete on petrophysicist interpretation quality and specialized tool reliability in niche formation environments.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| Weatherford International Plc |
| China Oilfield Services Limited |
| Superior Energy Services Inc |
| Nabors Industries Ltd |
| OilServ |
| RECON Petrotechnologies Ltd |
| Others |
Value Network & Pricing Analysis
Wireline tool manufacturing concentrates in Houston and Stavanger, anchoring margin pools in integrated service contracting where Schlumberger, Halliburton, and Baker Hughes bundle formation evaluation with directional drilling. This upstream equipment concentration feeds downstream pricing power toward vendors with dedicated logistics infrastructure for EPA and OSHA radioactive source compliance.
Pricing Analysis
Price spreads between US Gulf of Mexico and West Africa deepwater contracts reflect mobilization cost differentials and regulatory complexity premiums. Three-tier pricing structure across premium, standard, and economy levels tracks tool capability tiers: geosteering-enabled Logging While Drilling commands top rates, conventional wireline occupies mid-tier, and basic nuclear logging faces cost compression from electromagnetic substitution. Price differentiation hinges on real-time data transmission bandwidth and after-sales petrophysicist interpretation support. Margins are tightening in nuclear spectroscopy services as rail freight contracts for cesium-137 add logistics overhead. Independent operators in the Rockies and Mid-Continent exhibit highest price sensitivity, driving fastest adoption of electromagnetic alternatives.
Supply Chain Analysis
Extended payment terms from national oil companies in Brazil and West Africa strain independent logging contractors without balance-sheet depth for 90-120 day receivables cycles. Supply concentrates in the United States, Norway, and China, with Houston hosting wireline platform manufacturing, Stavanger anchoring extreme-pressure sensor development, and Shenzhen producing drillstring-integrated electronics. Raw material dependencies center on high-temperature ceramics for electronics packaging, specialized alloys for pressure housings, and rare-earth elements for magnetic sensors. Single-source vulnerability runs through cesium-137 suppliers regulated under EPA transport frameworks. Distribution runs through dedicated service bases at deepwater port facilities, with equipment staged in Rio de Janeiro, Luanda, and Singapore for rapid offshore mobilization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data interpretation and petrophysicist consulting layers expand faster than hardware deployment, transforming open hole logging from discrete tool procurement into recurring-revenue service relationships. This service-attach dynamic favors vendors with captive interpretation talent and cloud-based delivery platforms.
For Market Incumbents: Entrench position through backward integration into high-temperature sensor manufacturing and exclusive petrophysicist talent pools. Electromagnetic logging substitution threatens nuclear tool revenue streams; counter by certifying integrated LWD-wireline platforms under ANP, BSEE, and NORSOK frameworks simultaneously. Channel control over dedicated logistics infrastructure for radioactive source handling remains the critical defensive lever against mid-scale competitors.
For New Entrants and Emerging Players: West Africa deepwater pre-salt analogs in Angola and Nigeria represent the most penetrable entry point, with underdeveloped local service infrastructure and growing demand for geosteering-capable packages. Electromagnetic logging pure-plays in environmentally sensitive US jurisdictions offer second white-space avenue, bypassing EPA transport restrictions that constrain incumbents. Go-to-market angle: partner with independent operators on outcome-based contracts linking logging data quality to completion design optimization.
For Investors and Strategic Acquirers: Capital is best deployed toward regional electromagnetic logging specialists with MIIT certification for Chinese unconventional campaigns and proprietary high-temperature tool reliability above 175°C. Long-term viability over the next decade rests on technology substitution resilience as resistivity and acoustic platforms displace legacy nuclear tools. Monitor NORSOK standards convergence toward real-time well integrity monitoring as inflection signal for permanent downhole gauge integration demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Agreement | Electromagnetic logging patents unlock permit access under EPA frameworks without radioactive source logistics. |
| Joint Venture with National Oil Company | Brazil's ANP mandates favor integrated contractors with pre-salt block operational experience. |
| Acquisition of Specialist Interpretation Firm | Petrophysicist talent scarcity extends project timelines; captive expertise accelerates data-to-decision velocity. |
| Geographic Expansion to West Africa | Angola and Nigeria deepwater campaigns lack established LWD service density relative to pre-salt Brazil. |
| Green Certification Program | Electromagnetic toolsets satisfy environmental compliance for operators in regulated North Sea jurisdictions. |
Research Methodology
The analysis maps wireline services, Logging While Drilling, perforation, and pressure testing segments, each validated through petrophysicist interviews, offshore drilling contractor procurement leads, national oil company technical managers, and regulatory affairs specialists at BSEE and ANP. Primary fieldwork combined with secondary triangulation against SEC 10-K filings, ANP technical requirement documents, NORSOK standards databases, and offshore project development registries. Bottom-up equipment deployment counts and top-down service revenue estimates converge through iterative reconciliation.
Assumptions held fixed include current regulatory frameworks across BSEE, ANP, and NORSOK jurisdictions, while oil price volatility and electromagnetic logging substitution rates varied across sensitivity scenarios. The forecast framework models service type, technology platform, end-user category, and application scope dimensions. CAGRs derive from segmented growth rate reconciliation against aggregate market expansion. Key inputs include deepwater rig count trajectories in Brazil and West Africa, shale well completion intensity in the Permian, and EPA enforcement patterns for radioactive source transport.
Practitioners should monitor ANP regulatory amendments, BSEE well integrity framework updates, and electromagnetic logging patent expiration schedules for early signals of structural shift. Forecasts embed assumptions about continued offshore safety mandate expansion and technology substitution velocity. Macroeconomic oil price collapse, regulatory reversal on radioactive source handling, or breakthrough high-temperature electronics reliability would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Frac Services Market
Oil & Gas
Well Abandonment Services Market
Oil & Gas
Sand Screen Sales Market
Oil & Gas
Asia-Pacific Oilfield Auxiliary Rental Equipment Market
Oil & Gas
South and Central America Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Whipstocks Market
Oil & Gas
Sand Control Screens Market
Oil & Gas
North Sea Oilfield Equipment Market
Oil & Gas
Russian Federation Oil and Gas Market
Oil & Gas
Australia LNG Bunkering Market
Oil & Gas
Oilwell Spacer Fluids Market
Oil & Gas
Middle-East and Africa Frac Stack Market
Oil & Gas
Malaysia Oil and Gas Pipeline Market
Oil & Gas
Downhole Tools Market
Oil & Gas
Indonesia Coal Market
Oil & Gas
Middle East and Africa Pipeline Maintenance Market