
 North America Oil and Gas Storage Tank Market | 2026-2036
North America Oil and Gas Storage Tank Market Size, Share, and Industry Trends Forecast 2026-2036
North America Oil and Gas Storage Tank Market Analytics
Multi-source procurement for tank fabrication and field erection is hardening across the North American midstream sector. McDermott leverages its modular construction expertise to compete for large-scale aboveground storage projects along the Gulf Coast. Shawcor anchors its position through specialized corrosion protection and lining systems that extend tank service life in sour crude service. CST Industries differentiates via bolted steel tank technology that reduces on-site welding requirements and accelerates installation schedules.
North America oil and gas storage tanks are welded or bolted steel vessels designed to API 650, API 620, or UL-142 standards, with shell thicknesses ranging from 3/16 inch to 2 inches depending on diameter, product specific gravity, and design pressure. These structures contain crude oil, refined products, natural gas liquids, and petrochemical feedstocks at atmospheric or low pressure, providing inventory management, surge capacity, and strategic reserve functions for the petroleum supply chain. Aboveground tanks dominate installed base value due to lower capital cost and easier inspection access, though floating roof variants command premium pricing for volatile product service where emissions control is mandated. Underground tanks represent a mature replacement segment driven by EPA spill prevention rules, while modular installation types are gaining share in remote shale plays where permanent construction faces labor and logistics constraints.
EPA Spill Prevention, Control, and Countermeasure rules and OSHA process safety management standards shape tank design, secondary containment, and inspection frequency across US facilities. Canada's Energy Regulator and provincial authorities enforce CSA Z662 pipeline and storage integrity requirements that parallel API standards with additional cold climate provisions. Texas Commission on Environmental Quality and Louisiana Department of Environmental Quality administer state-level air permits that dictate floating roof seal technologies and vapor recovery unit deployment. Stakeholders must weigh capital allocation between brownfield retrofit compliance and greenfield capacity that accommodates denser crude slates and renewable feedstock blending.
Market Dynamics
API 653 inspection mandates are forcing accelerated replacement cycles across aging aboveground storage infrastructure, particularly along the Gulf Coast where 1970s-era tank farms face corrosion-driven integrity failures under heavier Permian crude slates.
Growth Catalysts
- EPA SPCC Rule Tightening:Secondary containment upgrades for existing facilities are mandating new tank construction and berm expansions across Texas and Louisiana refineries.
- Floating Roof Vapor Recovery:Texas Commission on Environmental Quality air permits now require advanced seal technologies on volatile product service, driving premium tank retrofits.
- Permian Basin NGL Expansion:Midstream operators in West Texas and New Mexico are adding bullet tanks and spheroids for natural gas liquids fractionation capacity.
Market Restraints
- Steel Plate Price Volatility:API 650 shell-grade carbon steel plate costs fluctuate with scrap metal and energy input indices, compressing fabrication margins.
- Specialized Welder Scarcity:Certified API 650/653 welders concentrate in Gulf Coast metropolitan zones, creating labor bottlenecks for remote shale play installations.
- Underground Double-Wall Substitution:EPA-mandated UST replacements with corrosion-resistant fiberglass threaten traditional steel tank demand in retail fuel segments.
Strategic Opportunities
- Alberta Oil Sands Diluent Storage:Canadian midstream operators require insulated tank capacity for diluted bitumen handling under CSA Z662 cold climate provisions.
- Renewable Diesel Feedstock Tanks:Refinery retrofits for soybean oil and tallow storage create demand for stainless-clad vessels with heating coils.
- Modular Bolted Tank Channel Expansion:CST Industries and regional fabricators are bypassing traditional field-erection contractors through direct-to-operator sales platforms.
Industry Challenges
- API 653 Recertification Backlogs:Third-party inspection firms face scheduling delays exceeding six months, forcing operators to idle tanks or seek emergency waivers.
- Legacy Tank Foundation Settlement:Subsidence-prone Gulf Coast soils require costly ringwall repairs and geotechnical remediation before new shell courses can be added.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Oil and Gas Storage Tank Market |
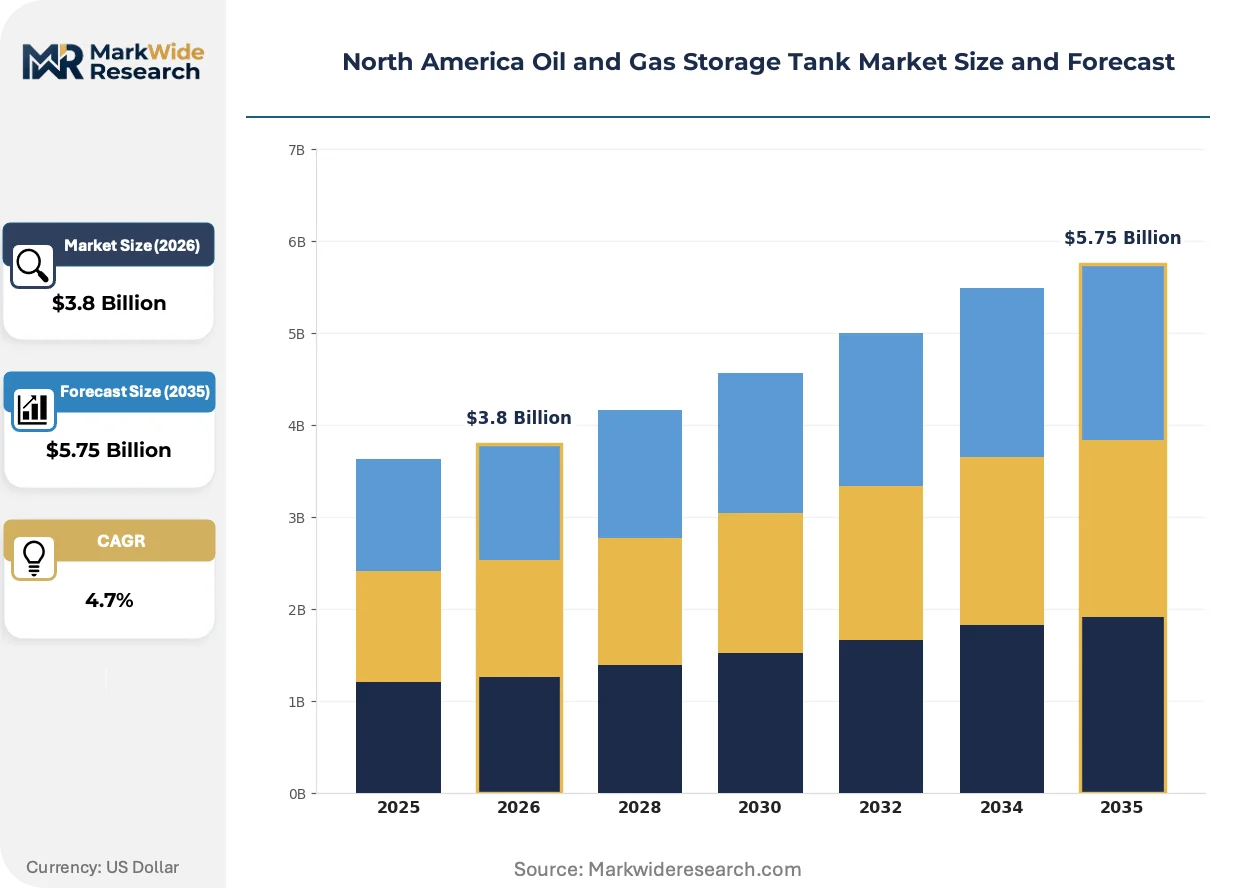
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aboveground Tanks, Underground Tanks, Floating Roof Tanks, Fixed Roof Tanks End User: Refineries, Petrochemical Companies, Oil and Gas Producers, Fuel Distributors Installation Type: Permanent, Temporary, Modular, Mobile Capacity: Small Scale, Medium Scale, Large Scale, Extra Large Scale |
| Companies Covered | McDermott, Shawcor, Matrix NAC, Manchester Tank, Hassco Industries, CST Industries, Superior Tank Co., Tank Connection, Highland Tank, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Oil and Gas Storage Tank Market Evolving Landscape
Digital corrosion monitoring and robotic inspection technologies are compressing maintenance cycles while API standards evolve to accommodate automated weld assessment protocols across North American tank farms.
Automated ultrasonic testing (AUT) systems is overtaking traditional radiographic inspection for API 650 shop and field welds. Midstream operators in the Permian Basin are specifying AUT protocols on new construction to accelerate commissioning schedules. This technology is overtaking film-based radiography by eliminating chemical processing delays and enabling real-time defect classification.
OSHA Process Safety Management updates are mandating quantitative risk assessments for tank overfill protection systems at facilities exceeding 10,000 barrels capacity. Refinery operators must install independent high-high level switches and automated valve interlocks. Floating roof tank segments in Louisiana face the steepest compliance costs due to concurrent state air permit renewal requirements.
Operator procurement teams are consolidating fabrication awards under multi-site framework agreements rather than project-specific tenders. This pattern compresses supplier margins while favoring tank builders with modular construction capabilities and in-house coating shops. The shift is most pronounced among integrated supermajors operating across Texas, Louisiana, and Alberta corridors.
North America Oil and Gas Storage Tank Market Segmentation
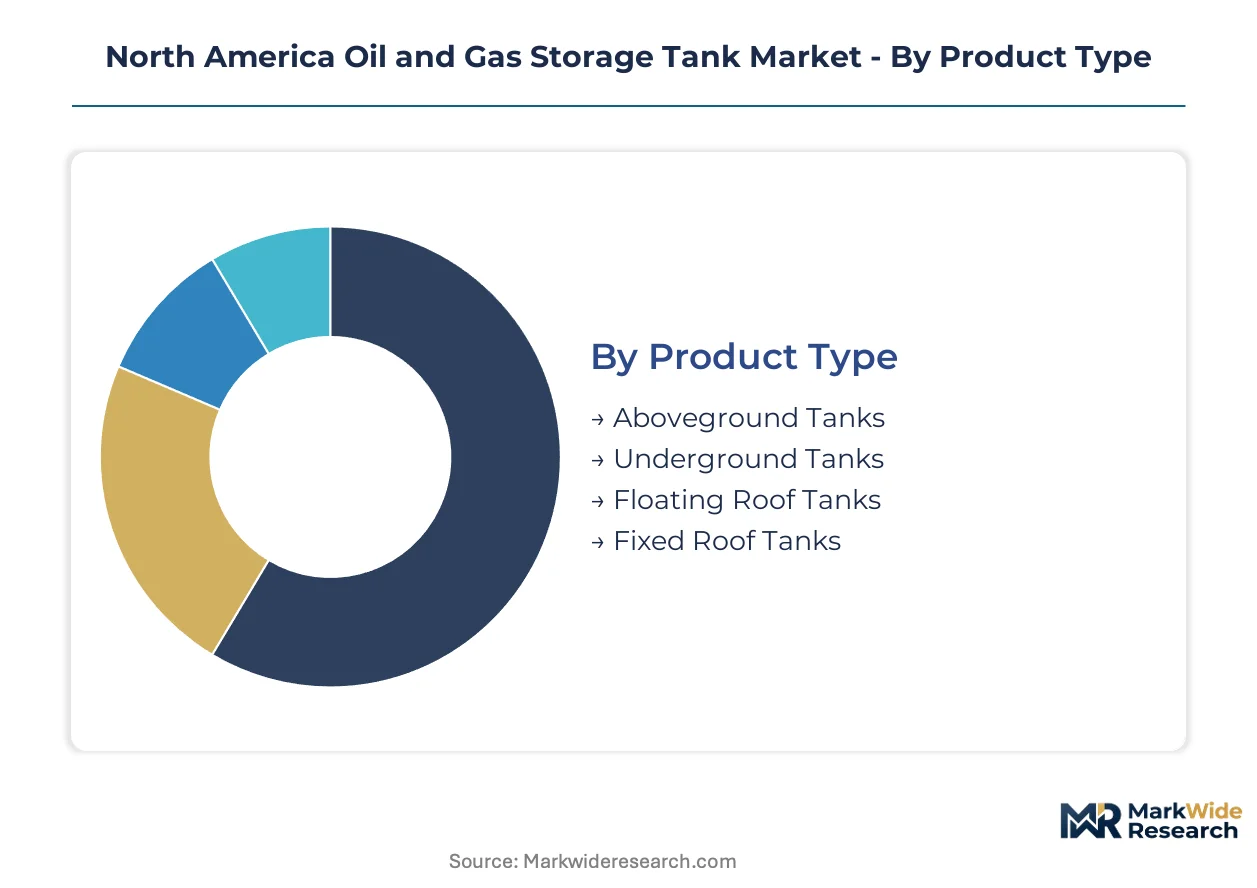
Segmentation in the North America oil and gas storage tank market reveals how API 650/653 compliance cycles, Permian Basin production growth, and Gulf Coast refinery expansion create divergent demand profiles across tank technologies and installation approaches. Procurement patterns vary sharply between brownfield replacement mandates and greenfield capacity additions.
Product Type:
Replacement cycles driven by API 653 recertification deadlines are redistributing capital across tank architectures, with corrosion-prone legacy infrastructure forcing technology upgrades.
- Aboveground Tanks:Welded steel vessels built to API 650 specifications with shell thicknesses from 3/16 inch to 2 inches dominate new construction. Texas and Louisiana refineries are expanding tank farm footprints to handle heavier Permian crude slates requiring enhanced corrosion monitoring.
- Floating Roof Tanks:Internal or external floating roof designs with advanced seal technologies command premium pricing for volatile product service. Texas Commission on Environmental Quality air permits mandate vapor recovery systems on these units, driving retrofit demand across Gulf Coast terminals.
- Underground Tanks:Double-wall fiberglass and steel designs serve EPA-mandated UST replacement programs in retail fuel segments.
- Fixed Roof Tanks:Cone roof or dome roof configurations handle lower vapor pressure products at reduced capital cost.
Volume placements concentrate in Aboveground Tanks; the faster expansion belongs to Floating Roof Tanks.
End User:
Customer scale dictates procurement sophistication, with integrated operators consolidating fabrication awards under multi-site frameworks while independent distributors favor project-specific tenders.
- Refineries:Gulf Coast facilities along the Texas-Louisiana corridor require API 650 compliant capacity for crude receipt, intermediate storage, and finished product blending. Heavier Permian Basin feedstocks accelerate corrosion-driven replacement cycles.
- Oil and Gas Producers:Upstream operators in West Texas and New Mexico lease tank capacity for wellhead storage and pipeline batching. Modular bolted solutions gain traction where permanent construction faces labor constraints.
- Petrochemical Companies:Feedstock storage for ethylene crackers and aromatics complexes demands specialized materials of construction.
- Fuel Distributors:Midstream marketers manage product terminals with mixed tankage for gasoline, diesel, and jet fuel.
Capital deployment tilts toward Refineries; Petrochemical Companies show the steepest capacity expansion trajectory.
Installation Type:
Logistics constraints and labor availability shape installation modality selection, with remote shale plays demanding alternatives to conventional field erection.
- Permanent:Field-welded API 650 construction with ringwall foundations represents conventional practice for Gulf Coast refinery tank farms.
- Modular:Bolted steel tank technology from CST Industries and regional fabricators reduces on-site welding requirements and accelerates commissioning schedules in the Permian Basin.
- Temporary:Leased capacity addresses short-term surge requirements during turnaround seasons.
- Mobile:Skid-mounted units serve drilling pad storage and emergency response applications.
Permanent installations retain the largest installed base; Modular approaches are gaining share fastest in remote production zones.
Capacity:
Economies of scale in fabrication and foundation work favor larger units where crude receipt and strategic inventory functions justify capital intensity.
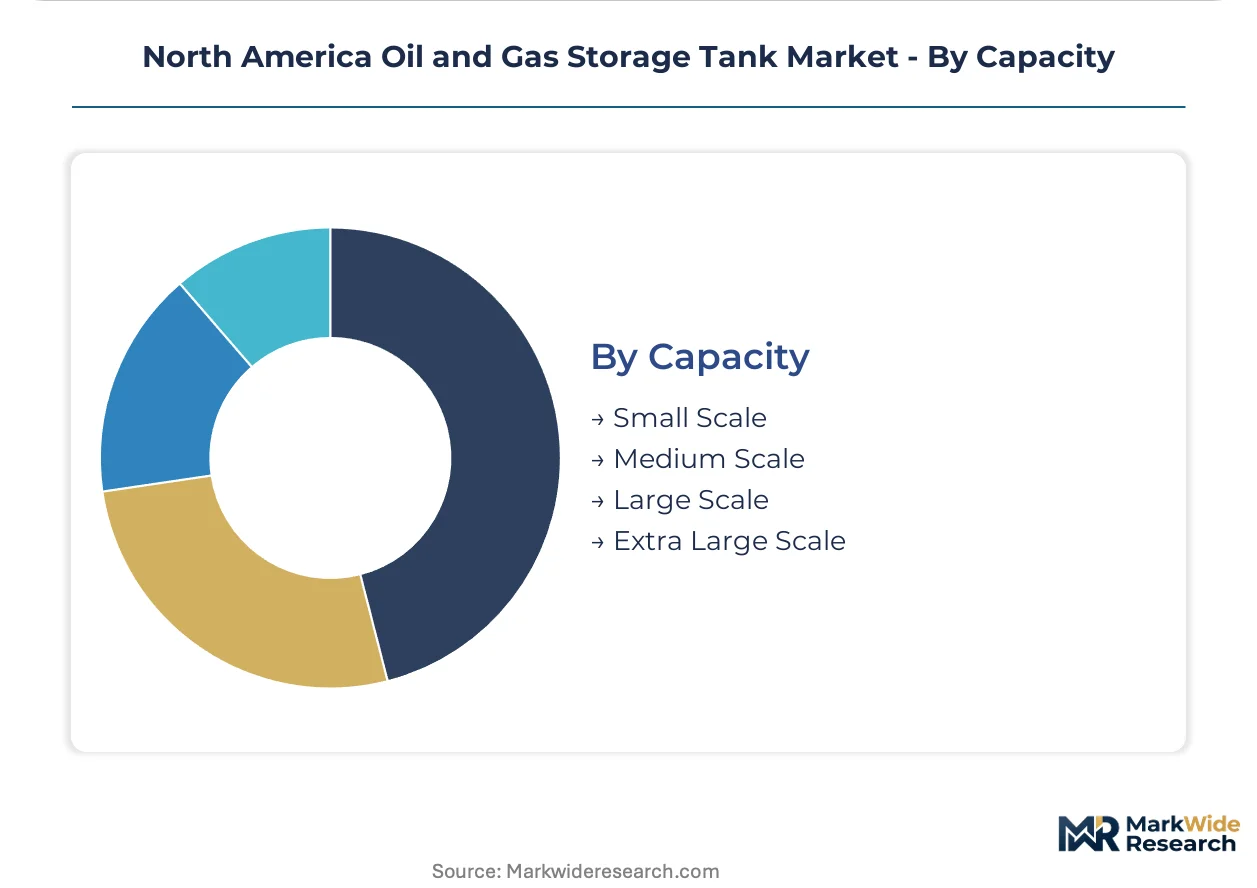
- Large Scale:Tanks exceeding 300,000 barrels capacity anchor Gulf Coast refinery crude receipt terminals. These units minimize per-barrel foundation costs but require extensive geotechnical remediation on subsidence-prone soils.
- Extra Large Scale:Ultra-large crude carriers and strategic petroleum reserve specifications drive 500,000+ barrel designs along the Louisiana Gulf Coast.
- Medium Scale:50,000 to 300,000 barrel units balance capital efficiency with operational flexibility.
- Small Scale:Below 50,000 barrel tanks serve product blending, additive injection, and batch segregation.
Project awards cluster in Large Scale; Extra Large Scale exhibits the most aggressive capacity expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas and Louisiana concentrate the majority of new tank construction awards, driven by Gulf Coast refinery expansion and Permian Basin midstream infrastructure buildout. The regional distribution reflects proximity to crude production, processing capacity, and deepwater export terminals.
United States
Texas dominates capital deployment, with Houston and Beaumont-Port Arthur refineries adding API 650 compliant capacity for heavier Permian crude slates. EPA SPCC secondary containment rules mandate berm expansions at existing facilities. The Louisiana Gulf Coast corridor sees aggressive tank farm construction to support ultra-large crude carrier loading operations.
Canada
Alberta's oil sands operations require insulated storage for diluted bitumen under CSA Z662 cold climate provisions. Edmonton and Hardisty terminal hubs anchor midstream investment. The Canada Energy Regulator enforces pipeline and storage integrity standards that parallel API protocols with additional freeze-protection requirements.
Mexico
Refinery modernization at Dos Bocas and Salamanca drives demand for atmospheric storage capacity. Pemex procurement emphasizes API 650 compliance for crude receipt terminals. Tamaulipas and Veracruz states concentrate new construction along the Gulf Coast export corridor.
North America Oil and Gas Storage Tank Market Competitive Landscape
Multi-site framework agreements dominate the current landscape as integrated operators consolidate fabrication awards. The vendor base stratifies across three tiers: full-service EPC contractors with modular construction capabilities, specialized corrosion protection and lining specialists, and regional bolted tank fabricators with direct-to-operator sales platforms. The two dominant competitive moves are backward integration into coating and lining operations, and geographic expansion through regional fabrication yard networks.
Among Gulf Coast-based EPC contractors, McDermott exemplifies the scale-driven archetype with modular construction expertise for large aboveground storage projects. Shawcor occupies a position within the specialized services tier, anchoring corrosion protection and lining system provision. CST Industries represents the technology-differentiated segment, with bolted steel tank solutions that reduce field welding requirements.
| Leading Market Players |
|---|
| McDermott |
| Shawcor |
| Matrix NAC |
| Manchester Tank |
| Hassco Industries |
| CST Industries |
| Superior Tank Co. |
| Tank Connection |
| Highland Tank |
| Others |
Value Network & Pricing Analysis
Backward integration into coating and lining operations anchors pricing power for Gulf Coast tank fabricators while compressing margins for non-integrated competitors. Captive control over corrosion protection systems allows McDermott and Shawcor to bundle extended warranty terms into fixed-price EPC contracts, insulating project awards from steel plate volatility.
Pricing Analysis
Warranty bundling separates full-service EPC contractors from regional fabricators competing on bare tank delivery. Project-based pricing dominates large aboveground storage awards, with differentiation driven by API 653 certification tier and vapor recovery system inclusion. Cost compression in standard welded tank segments is intensifying because steel plate indices feed directly into shell-grade carbon steel quotes. Independent distributors show highest price sensitivity, while integrated supermajors prioritize multi-site framework stability over per-unit savings.
Supply Chain Analysis
Regional distribution centers in Houston, Beaumont-Port Arthur, and Edmonton anchor hub-and-spoke patterns for shell-grade steel plate and specialized welding consumables. Manufacturing concentrates in the United States, Canada, and Mexico, with heavy reliance on domestic mill capacity for API 650-compliant carbon steel. Supply chains draw from scrap metal and energy input indices that amplify fabrication cost volatility. Single-source vulnerability in certified API 650/653 welder pools creates bottlenecks for remote shale play installations. Distribution runs through dedicated fabrication yards with in-house blasting and coating capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API 653 recertification backlogs exceeding six months prop pricing power for inspection-capable contractors. Certified welder scarcity locks capacity expansion behind labor pipeline development.
For Market Incumbents: Acquire third-party inspection firm capacity to capture API 653 recertification backlog revenue streams. Expand modular fabrication yard networks into the Permian Basin to bypass field welder scarcity. Corrosion monitoring technology substitution threatens traditional inspection margins; preemptive investment in automated ultrasonic testing protocols defends service attach rates. Vertical integration into geotechnical remediation addresses ringwall repair demand from legacy foundation settlement. For New Entrants and Emerging Players: EPA SPCC secondary containment rule tightening in Texas and Louisiana opens a window for berm expansion specialists. Target floating roof seal retrofit segments where Texas Commission on Environmental Quality air permits mandate vapor recovery deployment. Bolted tank direct-to-operator platforms bypass established EPC channel control. White-space concentrates in remote shale play modular installation where labor logistics constrain incumbent response times. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated midstream operators seeking captive fabrication capacity. Long-term viability hinges on exposure to Permian Basin production growth and Gulf Coast refinery expansion corridors. Acquisition target archetype: regional fabricators with API 650 shop certification and underutilized coating capacity. Watch automated weld assessment protocol adoption rates as inflection indicator for inspection technology displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Operations | Captive corrosion protection capacity locks in EPC margin and accelerates commissioning schedules. |
| Modular Fabrication Yard Expansion | Bolted tank preassembly in Houston and Midland bypasses field welder scarcity in West Texas. |
| API 653 Inspection Capability Acquisition | Third-party recertification backlogs exceeding six months create pricing power for integrated providers. |
| Automated Ultrasonic Testing Deployment | Real-time defect classification eliminates radiographic processing delays on Permian Basin projects. |
| Vapor Recovery System Bundling | Texas Commission on Environmental Quality permit compliance drives premium retrofit attach rates. |
Research Methodology
Document review covered API standards documentation, EPA SPCC regulatory filings, and state-level air permit records, complemented by interviews with tank farm engineering directors, EPC procurement leads, certified welding inspectors, and corrosion protection specialists. Secondary sources included FERC facility filings, EIA storage capacity reports, and CSA Z662 cold climate provisions. Bottom-up project tracking across Texas, Louisiana, and Alberta terminals triangulated against top-down capacity expansion announcements from integrated operators.
Historical construction award patterns cross-referenced with panel input from fabrication yard operators and midstream capital planning officers. Segmentation modeling covered product type, end user, installation modality, and capacity tier across the projection horizon. CAGRs derived from weighted capacity expansion pipelines and replacement cycle timing. Industry-specific inputs included Permian Basin NGL fractionation buildout schedules and API 653 recertification deadline clustering.
The model assumes a particular technology adoption path; alternative pathways for robotic inspection and digital corrosion monitoring would alter the outlook for traditional maintenance service demand. Forecasts reflect stated assumptions regarding regulatory enforcement intensity and steel input cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Kuwait Oilfield Services Market
Oil & Gas
Asia-Pacific Digital Oilfield Market
Oil & Gas
Oil and Gas Cloud Applications Market
Oil & Gas
Thailand Oil and Gas Market
Oil & Gas
Oil and Gas Downhole Vibration Monitoring and Control System Market
Oil & Gas
Russia Oil and Gas EPC Market
Oil & Gas
Microbial Enhanced Oil Recovery Market
Oil & Gas
Latin America AI in Oil and Gas Market
Oil & Gas
Crown Block Market
Oil & Gas
Oil and Gas Industry Turbomachinery Market
Oil & Gas
Subsea Well Intervention Market
Oil & Gas
Modular Refinery Market
Oil & Gas
India Artificial Lift Systems Market
Oil & Gas
Drones for Oil & Gas Market
Oil & Gas
Russia Drill Pipe Market
Oil & Gas
Subsea Manifolds Market