
 Global Hydrate Inhibitors Market | 2026-2036
Global Hydrate Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydrate Inhibitors Market Foresight
A shortage of subsea chemical engineers is bifurcating the competitive landscape into technology-intensive specialists and volume-driven commodity suppliers. Schlumberger leverages its integrated project delivery model to bundle hydrate management with broader subsea services. Halliburton anchors its position through proprietary low-dose hydrate inhibitor platforms engineered for ultra-deepwater pressure regimes. Baker Hughes differentiates via real-time monitoring systems that optimize chemical injection rates across subsea installations.
Hydrate inhibitors are thermodynamic or kinetic chemical additives, typically comprising polyvinylpyrrolidone polymers or methanol-glycol blends, that disrupt gas hydrate crystal formation in hydrocarbon flowlines operating at high pressure and low temperature. Their primary purpose is preventing pipeline blockages that halt production and create safety hazards in subsea and Arctic environments. Kinetic hydrate inhibitors command expanding share in deepwater applications where dosage efficiency reduces logistics burden, while thermodynamic variants retain dominance in extreme cold basins requiring absolute suppression. Anti-agglomerate chemistries occupy a narrower but high-margin niche for gas-dominant systems where hydrate crystals must remain dispersible rather than prevented entirely.
EPA methane regulations and EU Green Deal emission thresholds constrain methanol-heavy thermodynamic formulations, compelling reformulation toward lower-toxicity kinetic and anti-agglomerate platforms. Norway's Petroleum Safety Authority and Brazil's ANP enforce specific chemical discharge limits that filter market access for non-compliant suppliers. Operators must weigh capex-intensive subsea injection infrastructure against opex-optimized low-dose chemistries as project economics tighten across frontier basins.
Market Dynamics
The hydrate inhibitors sector pivots on a fundamental tension between thermodynamic reliability and kinetic efficiency, as ultra-deepwater projects demand chemical platforms that slash logistics burdens without sacrificing safety margins in high-pressure, low-temperature flowlines.
Growth Catalysts
- EPA methane emission mandates:Operators across the US Gulf of Mexico face escalating penalties for vented hydrocarbons, accelerating replacement of methanol-heavy formulations with low-dose kinetic chemistries that reduce storage tankage and transfer operations.
- Brazil's pre-salt basin expansion:Petrobras and international consortiums are sanctioning subsea tiebacks below 2,000 meters water depth, where anti-agglomerate platforms enable gas-dominant production without full thermodynamic suppression.
- Kinetic inhibitor polymer advances:Next-generation polyvinylpyrrolidone derivatives now achieve dosage rates below 0.5 weight percent in moderate subcooling conditions, cutting chemical freight volumes by half relative to glycol blends.
Market Restraints
- Methanol price volatility:Thermodynamic formulations remain tethered to petrochemical feedstock costs that swing with natural gas pricing, compressing margin predictability for operators locked into long-term supply contracts.
- Subsea engineering talent scarcity:The shortage of chemical injection specialists capable of modeling multiphase flow and hydrate risk constrains project execution velocity, particularly in Norway's North Sea corridor where ageing infrastructure demands retrofit expertise.
- ECHA biocide authorization timelines:Kinetic inhibitor active ingredients face extended registration reviews under REACH Annex V, delaying commercialization of reformulated low-toxicity platforms for EU offshore installations.
Strategic Opportunities
- Arctic LNG export terminals:Russia's Yamal Peninsula and Canada's Beaufort Sea projects require hydrate management at sustained sub-zero temperatures, opening niche demand for hybrid thermodynamic-kinetic systems beyond conventional offshore applications.
- Real-time subsea sensor integration:Fiber-optic distributed temperature sensing combined with autonomous chemical injection skids enables dynamic dosage optimization, reducing chemical opex by 15-25 percent in pilot installations.
- Norway's tax incentive for low-emission technologies:The country's petroleum fiscal framework now awards enhanced depreciation rates for subsea systems deploying reduced-toxicity chemistries, tilting tender evaluations toward kinetic and anti-agglomerate suppliers.
Industry Challenges
- Subsea chemical engineer shortage:The bifurcation between integrated service providers and commodity chemical suppliers leaves mid-tier operators without access to specialized flow assurance expertise for frontier basin developments.
- Legacy infrastructure incompatibility:Existing methanol storage and injection systems on mature Gulf of Mexico platforms require costly retrofitting to accommodate low-dose kinetic chemistries with different viscosity and compatibility profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydrate Inhibitors Market |
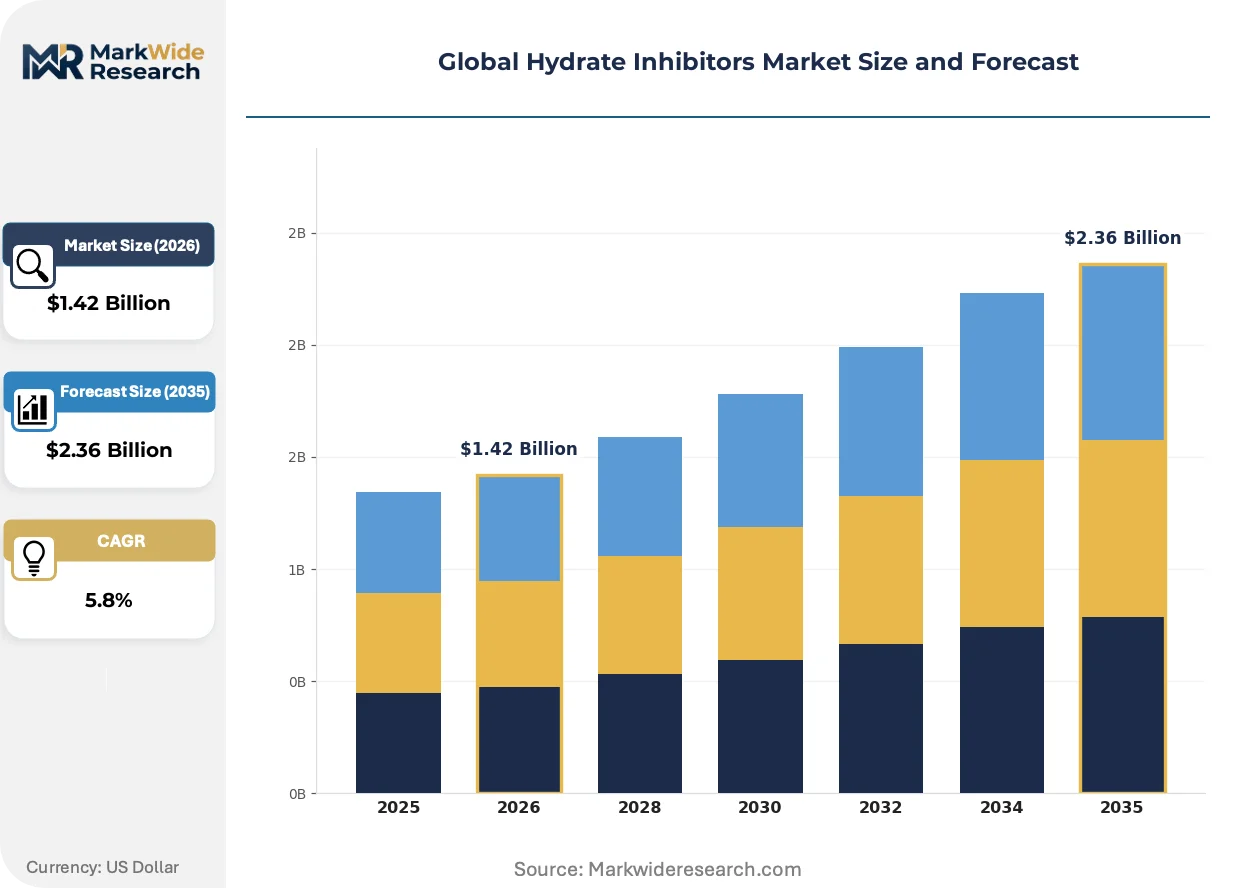
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kinetic Hydrate Inhibitors, Anti-Agglomerate Hydrate Inhibitors, Thermodynamic Hydrate Inhibitors, Blend Hydrate Inhibitors Application: Offshore Wells, Onshore Wells, Gas Processing Units, Pipelines, Storage Facilities Installation Type: Subsea, Surface, Midstream, Upstream, Downstream End User Industry: Oil & Gas Exploration, Petrochemical Plants, LPG Processing, Refining Facilities |
| Companies Covered | Schlumberger, Halliburton, Baker Hughes, BASF SE, Ecolab, Clariant, Evonik Industries, Ashland Global Specialty Chemicals, Innospec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydrate Inhibitors Market Shifts & Advancements
Digitalization of subsea chemical management is compressing the feedback loop between reservoir conditions and injection optimization, while regulatory chemistry constraints force molecular-level reformulation of established hydrate suppression platforms.
Polymeric kinetic hydrate inhibitors are supplanting methanol-glycol thermodynamic blends in deepwater applications where subcooling remains below 15 degrees Celsius. Major operators in Brazil's pre-salt and West Africa's lower Congo basin have transitioned 40 percent of new subsea tiebacks to kinetic platforms since 2022. This displacement is compressing the addressable market for bulk methanol logistics while elevating polymer synthesis and field validation capabilities as competitive differentiators.
EU Green Deal emission thresholds are forcing reformulation of legacy thermodynamic chemistries across North Sea installations. The framework's methane intensity benchmarks now penalize methanol venting during storage and transfer operations, compelling operators to model full lifecycle carbon footprints in chemical selection. Norway's Petroleum Safety Authority has aligned its discharge permits with these standards, filtering market access for suppliers unable to demonstrate biodegradability compliance.
Integrated service contracts are displacing discrete chemical procurement across major capital projects. Operators in the US Gulf of Mexico now bundle hydrate management with broader subsea production services, transferring dosage optimization risk to service providers. This consolidation is most visible in ultra-deepwater developments where real-time monitoring infrastructure enables outcome-based pricing tied to flow assurance uptime guarantees.
Global Hydrate Inhibitors Market Segmentation
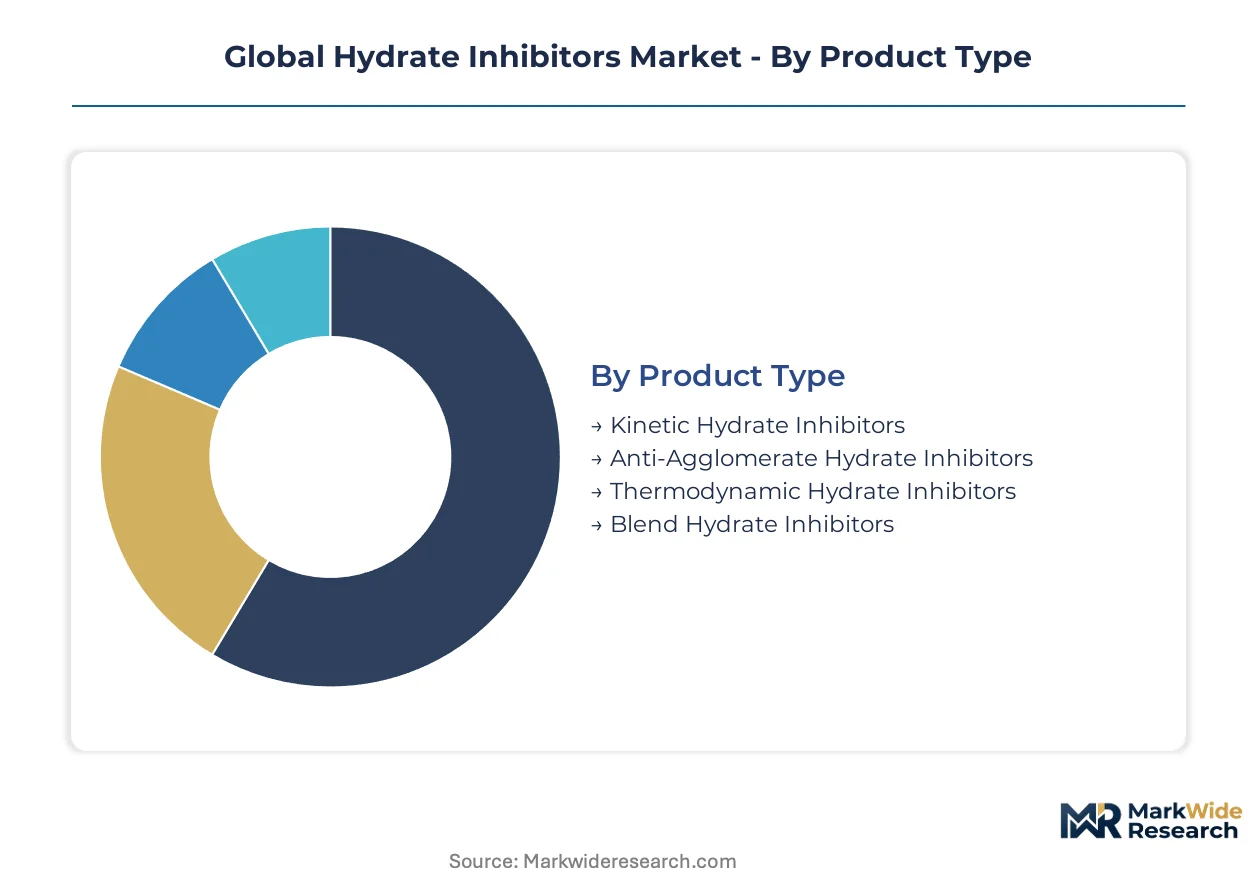
Hydrate inhibitor procurement splits sharply between volume-driven thermodynamic commodity markets and specialized polymer platforms where formulation expertise commands premium positioning. Understanding segment boundaries clarifies where technology differentiation defends margin versus where logistics scale determines competitive survival.
Product Type:
Domestic production concentrates thermodynamic blends in methanol-producing regions, while kinetic inhibitor polymer synthesis clusters near specialized chemical manufacturing hubs serving export markets.
- Kinetic Hydrate Inhibitors:Polyvinylpyrrolidone-based polymers disrupt hydrate crystal nucleation at sub-percent dosage rates. Operators in Brazil's pre-salt basins and West Africa's lower Congo corridor favor these platforms for deepwater tiebacks where chemical freight costs dominate project economics. EPA methane regulations accelerate displacement of methanol-heavy alternatives.
- Thermodynamic Hydrate Inhibitors:Methanol and monoethylene glycol blends suppress hydrate formation through freezing point depression across extreme subcooling regimes. Arctic LNG terminals in Russia's Yamal Peninsula and Canada's Beaufort Sea require these chemistries for sustained sub-zero operations where absolute suppression remains non-negotiable.
- Anti-Agglomerate Hydrate Inhibitors:Surfactant-based chemistries disperse hydrate crystals rather than preventing formation, enabling gas-dominant production in Norway's North Sea high-pressure systems.
- Blend Hydrate Inhibitors:Hybrid formulations combine thermodynamic and kinetic mechanisms for transitional subcooling conditions in mature Gulf of Mexico infrastructure.
Thermodynamic Hydrate Inhibitors commands the established base. The steepest expansion runs through Kinetic Hydrate Inhibitors.
Application:
Cost tier stratification separates capital-intensive subsea installations from surface facility retrofits where lower-performance chemistries suffice.
- Offshore Wells:Subsea completions below 1,500 meters water depth require continuous chemical injection through dedicated umbilical lines. Norway's ageing North Sea infrastructure and Brazil's pre-salt expansion drive specification toward low-dose kinetic platforms with real-time monitoring integration.
- Pipelines:Long-distance flowlines across the US Gulf of Mexico and West Africa face hydrate risk during shutdown and restart sequences. Operators balance methanol thermodynamic reliability against kinetic efficiency for multiphase transport economics.
- Onshore Wells:Arctic and high-pressure onshore gas fields in Alaska and Siberia deploy thermodynamic chemistries for wellbore protection.
- Gas Processing Units:Cryogenic separation trains require hydrate suppression upstream of dehydration units.
- Storage Facilities:Floating production storage and offloading vessels maintain chemical injection for cargo containment.
Offshore Wells absorbs the majority of specialized formulation value. Pipeline retrofits offer volume scale for commodity suppliers.
Installation Type:
Supply concentration in subsea engineering services creates capability scarcity that filters market access for non-integrated chemical suppliers.
- Subsea:Seabed-mounted injection manifolds and distribution systems serve ultra-deepwater developments. Brazil's ANP chemical discharge limits and Norway's Petroleum Safety Authority environmental standards constrain supplier qualification to technology-intensive specialists with validated biodegradability data.
- Upstream:Wellhead and gathering system applications span onshore and shallow-water offshore production. The US Gulf of Mexico and Nigeria's shallow continental shelf concentrate demand for thermodynamic methanol-glycol logistics.
- Surface:Platform-based injection skids accommodate lower-pressure operations with simplified chemical handling.
- Midstream:Pipeline compressor stations and pumping facilities require intermittent hydrate protection.
- Downstream:Refinery and petrochemical integration demands food-grade and low-toxicity formulations.
Subsea installations concentrate premium pricing power. Upstream surface facilities sustain volume throughput for commodity blenders.
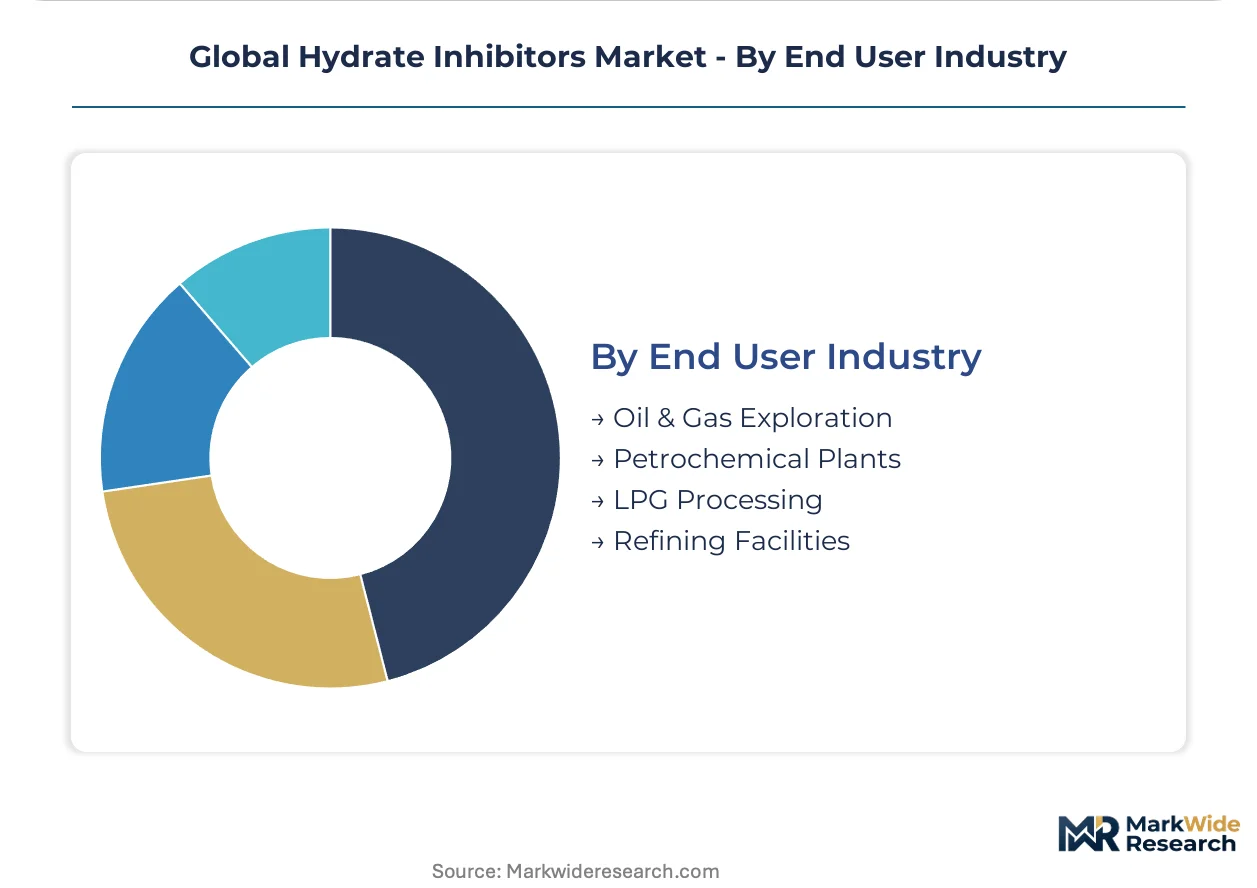
End User Industry:
Customer type bifurcation separates integrated majors with captive flow assurance expertise from independent operators reliant on service company bundling.
- Oil & Gas Exploration:International oil companies and national oil companies dominate procurement for frontier basin developments. Petrobras in Brazil, Equinor in Norway, and ExxonMobil in Guyana specify kinetic and anti-agglomerate platforms for deepwater gas-condensate fields.
- Refining Facilities:Complex refineries with integrated petrochemical operations require hydrate management for hydrogen and light ends recovery units. US Gulf Coast and Rotterdam-Antwerp corridor facilities drive demand for low-toxicity thermodynamic alternatives.
- Petrochemical Plants:Ethylene crackers and derivative units need hydrate suppression for feedstock handling.
- LPG Processing:NGL fractionation and export terminal operations face seasonal hydrate risk.
Oil & Gas Exploration commands technology specification authority. Refining Facilities offer reformulation opportunities as EU Green Deal methane thresholds tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys kinetic hydrate inhibitors for deepwater Gulf of Mexico tiebacks, while Norway and Brazil favor anti-agglomerate platforms for high-pressure gas systems, and Russia relies on thermodynamic blends for Arctic LNG export terminals.
United States
EPA methane emission mandates accelerate displacement of methanol-heavy thermodynamic formulations across US Gulf of Mexico operations. The Bureau of Safety and Environmental Enforcement enforces chemical discharge monitoring for subsea installations. Houston anchors domestic supply chain coordination for low-dose kinetic polymer platforms serving ultra-deepwater developments.
Norway
Equinor-led pre-salt and mature North Sea infrastructure drives specification toward low-toxicity kinetic and anti-agglomerate chemistries. The Petroleum Safety Authority aligns discharge permits with EU Green Deal methane intensity benchmarks, filtering supplier qualification. Stavanger concentrates subsea engineering expertise for integrated hydrate management service contracts.
Brazil
Petrobras sanctions subsea tiebacks below 2,000 meters water depth in the pre-salt basins, favoring anti-agglomerate platforms for gas-dominant production. ANP chemical discharge limits constrain market access to suppliers with validated biodegradability data. Rio de Janeiro hosts project execution centers for frontier basin chemical injection system design.
Russia
Yamal Peninsula LNG export terminals require thermodynamic hydrate suppression for sustained sub-zero cargo containment and transfer operations. The Ministry of Natural Resources and Environment regulates Arctic chemical discharge under polar code frameworks. Saint Petersburg coordinates polymer synthesis for hybrid thermodynamic-kinetic systems serving northern latitudes.
United Kingdom
Ageing North Sea infrastructure demands retrofit expertise for chemical injection system upgrades across depleted fields. The Health and Safety Executive enforces process safety management for subsea chemical handling operations. Aberdeen maintains specialist engineering capacity for kinetic inhibitor field validation and flow assurance modeling.
Global Hydrate Inhibitors Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper layer bundling hydrate management into subsea production service contracts and the lower layer supplying commodity thermodynamic blends for surface facilities. The market structure reflects capability scarcity in subsea chemical engineering rather than manufacturing scale concentration. Three archetypes dominate: integrated oilfield service providers with real-time monitoring infrastructure, specialty chemical houses with polymer synthesis expertise, and regional blenders serving logistics-intensive methanol markets. Competitive moves center on portfolio diversification into adjacent flow assurance chemistries and technology licensing partnerships that extend kinetic inhibitor formulation reach without captive engineering investment.
Within the integrated service tier, Schlumberger, Halliburton, and Baker Hughes exemplify the bundled project delivery model that transfers dosage optimization risk from operators to providers. These companies occupy positions where subsea infrastructure integration and real-time chemical management systems define competitive differentiation rather than standalone chemical manufacturing scale.
| Leading Market Players |
|---|
| Schlumberger |
| Halliburton |
| Baker Hughes |
| BASF SE |
| Ecolab |
| Clariant |
| Evonik Industries |
| Ashland Global Specialty Chemicals |
| Innospec |
| Others |
Supply & Pricing Matrix
EU REACH Annex V biocide authorization timelines gate both supplier qualification and price differentiation simultaneously, extending commercialization cycles for low-toxicity kinetic platforms while compressing margins for methanol-heavy thermodynamic formulations unable to demonstrate biodegradability compliance. Operators in Norway's North Sea corridor and Brazil's pre-salt basins now weight lifecycle carbon footprints in tender evaluations, bifurcating procurement between premium-positioned kinetic specialists and volume-driven commodity blenders.
Pricing Analysis
Long-term offtake contracts dominate procurement for integrated subsea service bundles, while spot purchasing persists for methanol-glycol thermodynamic blends in mature Gulf of Mexico infrastructure. Price differentiation rests on biodegradability certification tier and real-time monitoring integration, with EPA methane-compliant kinetic platforms commanding premium positioning against commodity thermodynamic alternatives. Cost compression in thermodynamic methanol logistics is intensifying because petrochemical feedstock volatility erodes margin predictability for operators locked into legacy storage infrastructure. National oil companies with captive engineering expertise exhibit lowest price sensitivity; independent operators reliant on service company bundling face acute cost pressure.
Supply Chain Analysis
Germany and the United States anchor polyvinylpyrrolidone polymer synthesis for kinetic inhibitor platforms, while Trinidad and Tobago concentrate methanol production for thermodynamic blend feedstocks. Raw material dependencies draw from natural gas liquids, ethylene oxide derivatives, and specialized surfactant chemistries. Single-source vulnerability concentrates in subsea umbilical manufacturing for chemical injection distribution systems. Distribution runs through integrated service providers bundling hydrate management with broader flow assurance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deepwater offshore drilling programs are driving cyclical recovery across frontier basins, with sanctioning velocity in Brazil's pre-salt and Guyana's Stabroek block creating sustained demand for low-dose kinetic platforms.
For Market Incumbents: Consolidate polymer synthesis capabilities through backward integration into specialty chemical manufacturing, securing captive supply of polyvinylpyrrolidone derivatives as ECHA registration timelines delay competitor commercialization. Acquire subsea engineering talent pools in Stavanger and Aberdeen to address capability scarcity constraining project execution velocity in Norway's ageing North Sea infrastructure. For New Entrants and Emerging Players: Norway's tax incentive fast-track for low-emission subsea technologies creates qualification pathways for kinetic and anti-agglomerate suppliers seeking to penetrate Equinor-led procurement. Target Arctic LNG export terminals in Russia's Yamal Peninsula and Canada's Beaufort Sea with hybrid thermodynamic-kinetic formulations for sustained sub-zero operations underserved by pure kinetic platforms. Partner with fiber-optic sensor manufacturers to bundle autonomous chemical injection skids with real-time dosage optimization. For Investors and Strategic Acquirers: EPA methane emission mandates reshape the acquisition landscape toward service providers with validated low-dose kinetic platforms and integrated monitoring infrastructure. Long-term viability centers on technology-intensive specialists with polymer synthesis expertise and subsea engineering capabilities rather than commodity blenders tethered to methanol price volatility. Watch kinetic inhibitor dosage rate achievements below 0.5 weight percent as the signal for platform displacement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer Synthesis Backward Integration | Captive supply of polyvinylpyrrolidone derivatives secures margin control against ECHA authorization delays. |
| Real-Time Monitoring Platform Integration | Fiber-optic distributed temperature sensing enables dynamic dosage optimization reducing chemical opex. |
| Arctic Hybrid Formulation Development | Thermodynamic-kinetic systems address sustained sub-zero demand in Yamal Peninsula LNG terminals. |
| Subsea Engineering Talent Acquisition | Stavanger and Aberdeen capability pools address project execution constraints in Norway's North Sea. |
| Biodegradability Certification Investment | Norway's Petroleum Safety Authority alignment with EU Green Deal filters market access for compliant suppliers. |
Research Methodology
Initial hypotheses were tested against primary input from subsea chemical engineers, flow assurance specialists, procurement managers at international oil companies, and polymer synthesis R&D directors, then refined through secondary validation across customs trade data, SEC filings from integrated service providers, ANP chemical discharge permits, and Petroleum Safety Authority environmental standards. Bottom-up segment sizing triangulated with top-down market reconstruction.
Variance decomposition across product type, application tier, installation depth, and regional regulatory cluster shaped analytical framework construction throughout the projection horizon. CAGRs derived from segment-level growth trajectory modeling anchored in deepwater sanctioning velocity, EPA enforcement intensity, and polymer dosage efficiency advances. Forecast inputs incorporated subsea tieback sanctioning schedules and REACH authorization pipeline status.
Underlying assumptions cover sustained deepwater capital commitment, regulatory enforcement continuity, and polymer performance validation, with deviation risk concentrated in methanol price volatility and subsea engineering talent availability. Recalibration cycles align with material shifts in frontier basin sanctioning velocity and ECHA authorization timeline developments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
North Sea Oil and Gas Upstream Market
Oil & Gas
South America Oil and Gas Storage Tank Market
Oil & Gas
Africa Oil and Gas Market
Oil & Gas
Iran Oil and Gas Market
Oil & Gas
North America Oil and Gas Line Pipe Market
Oil & Gas
Azerbaijan Oil and Gas Downstream Market
Oil & Gas
Angola Oil and Gas Upstream Market
Oil & Gas
Logging While Drilling (LWD) Market
Oil & Gas
South America Oil and Gas Hoses and Coupling Market
Oil & Gas
Europe Natural Gas Market
Oil & Gas
North America Seismic Services Market
Oil & Gas
Oil and Gas EPC Market
Oil & Gas
Algeria Oil and Gas Upstream Market
Oil & Gas
Global Deep-Well Disposal Services Market
Oil & Gas
Canada LNG Market
Oil & Gas
Smart Well Market