
 Oil and Gas Gasket Market | 2026-2036
Oil and Gas Gasket Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Gasket Market Intelligence
The capability gap between capital-intensive integrated seal manufacturers and smaller component suppliers is collapsing as advanced material formulations become commoditized. Freudenberg Sealing Technologies leverages its polymer science heritage to sustain premium positioning in PTFE-composite gasket architectures. Flexitallic LP anchors its competitive stance through specialized spiral wound production for refinery turnaround cycles. Parker Hannifin Corporation competes across multiple installation categories with distributed manufacturing scale.
Oil and gas gaskets are precision-engineered sealing elements, typically fabricated from metal, graphite, rubber, or PTFE composites, designed to maintain pressure containment across flanged joints operating under cyclic thermal and mechanical stress. Their primary purpose is preventing fugitive emissions and fluid loss in hydrocarbon processing, transmission, and storage infrastructure. Spiral wound and ring joint formats dominate severe-service applications where ASME B16.20 pressure ratings govern procurement specifications. Metal-reinforced graphite sheet materials occupy the fastest-growing material tier as operators seek fire-safe, low-emission sealing solutions compatible with hydrogen blending in existing pipeline networks.
API standards, ASME Boiler and Pressure Vessel Code provisions, and EPA methane emissions regulations collectively shape product certification requirements and replacement cycle timing across North American oilfield operations. The EPA's New Source Performance Standards and emerging state-level methane intensity rules are forcing gasket specification upgrades at compressor stations and wellhead assemblies. Stakeholders must monitor evolving fugitive emissions enforcement thresholds and hydrogen service compatibility standards to align R&D portfolios with next-cycle procurement criteria.
Market Dynamics
API 6A and ISO 13628-7 certification tightening is compressing supplier margins while elevating material performance thresholds for subsea and high-temperature applications.
Growth Catalysts
- Shale field redevelopment:United States operators are sustaining replacement cycles for pipeline sealing systems across Permian and Bakken basins.
- EPA methane regulations:New Source Performance Standards are forcing specification upgrades at compressor stations and wellhead assemblies.
- Spiral wound format adoption:Refinery turnaround cycles in the Gulf Coast are concentrating procurement volumes for severe-service gasket architectures.
Market Restraints
- Specialized alloy input costs:Inconel and Monel price volatility constrains margin flexibility for metal-reinforced gasket producers.
- Supply concentration in PTFE composites:Three integrated polymer science houses control premium formulation IP.
- Fire-safe graphite substitution limits:Metal-reinforced graphite sheet materials face performance ceilings above 500°C continuous operation.
Strategic Opportunities
- Hydrogen blending infrastructure:Existing natural gas pipeline networks in Germany and the Netherlands require retrofitted sealing solutions compatible with hydrogen service.
- LNG export terminal construction:United States Gulf Coast projects are creating demand for cryogenic-rated gasket specifications.
- Digital inventory platforms:Distributor-led e-procurement channels are compressing lead times for turnaround maintenance procurement.
Industry Challenges
- API 6A certification timelines:Third-party validation cycles for new material formulations extend 18-24 months.
- Polymer science talent scarcity:Formulation chemistry expertise concentrates among retiring specialists at legacy seal manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Gasket Market |
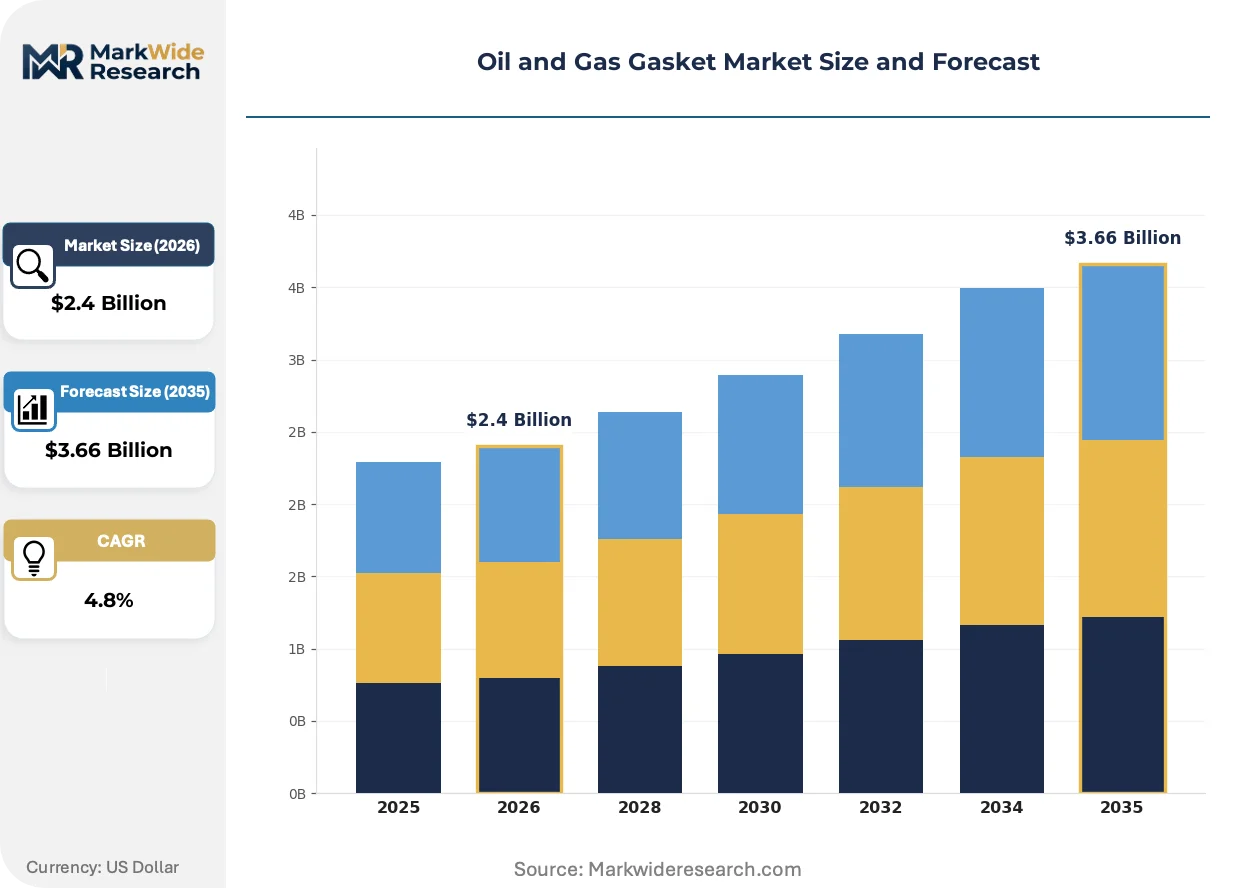
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spiral Wound, Ring Joint, Sheet, O-Ring Material: Rubber, Graphite, PTFE, Metal Application: Pipelines, Pressure Vessels, Pumps, Compressors Installation: Onshore, Offshore, Refineries, Storage Tanks |
| Companies Covered | Flowserve Corporation, Flexitallic LP, Freudenberg Sealing Technologies, Dechengwang, Parker Hannifin Corporation, Trelleborg Sealing Solutions, Garlock Sealing Technologies, Dana Incorporated, ElringKlinger AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Gasket Market Strategic Shifts & Innovations
Material science convergence with emissions compliance is redefining competitive advantage across precision sealing architectures.
Metal-reinforced graphite sheet laminates are displacing pure PTFE composites in fire-safe applications. United States pipeline operators are adopting these architectures for hydrogen blending compatibility. The shift is compressing addressable market share for non-reinforced elastomeric gasket producers.
EPA methane intensity rules are mandating fugitive emissions monitoring at flange assemblies. Compressor station operators must now specify low-emission sealing technologies with verified leak rates. The Permian Basin and Appalachian shale plays are experiencing the most acute procurement specification upgrades.
Integrated procurement platforms are consolidating maintenance spend for supermajor operators. Distributor networks are losing share to direct manufacturer relationships for large-turnaround contracts. The United States refinery sector shows the most pronounced channel consolidation.
Oil and Gas Gasket Market Segmentation
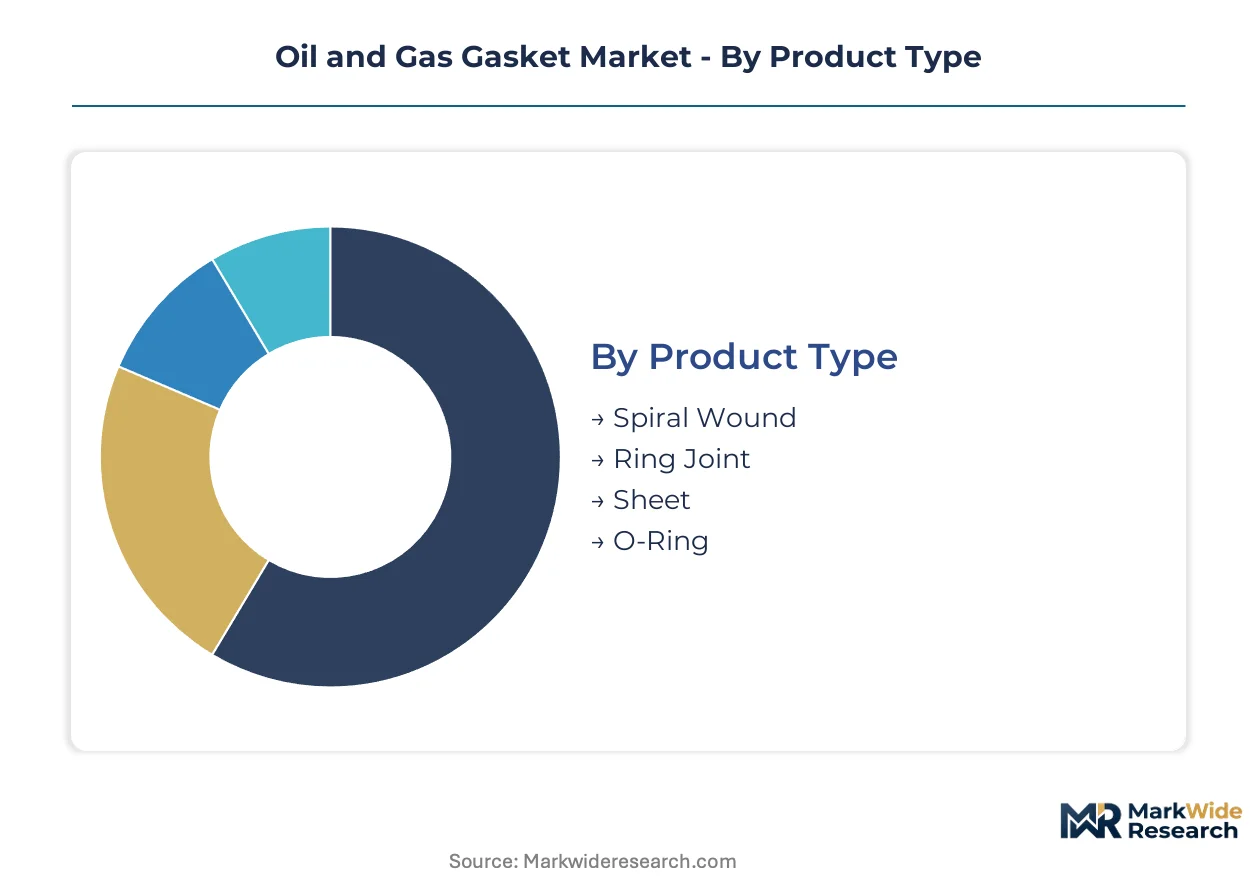
Gasket procurement patterns diverge sharply across product architectures and installation environments. Material selection and application severity dictate channel preferences, from distributor-led maintenance procurement to direct manufacturer relationships for large-turnaround contracts.
Product Type:
Spiral wound and ring joint formats flow through specialized industrial distributors with API certification capabilities, while sheet and O-ring products increasingly migrate to digital procurement platforms.
- Spiral Wound:Constructed from alternating metal windings and filler material, typically graphite or PTFE, wound into a V-shaped profile. Demand concentrates in United States Gulf Coast refinery turnaround cycles where ASME B16.20 pressure ratings govern severe-service specifications. These installations require verified fire-safe performance under cyclic thermal stress.
- Ring Joint:Solid metal gaskets machined into oval or octagonal cross-sections for high-pressure flange connections. Procurement volumes are climbing fastest in North Sea and Gulf of Mexico offshore installations where subsea flanged connections must withstand extreme pressure differentials.
- Sheet:Compressed fiber or graphite laminates cut to custom dimensions for low-to-moderate pressure applications.
- O-Ring:Elastomeric toroidal seals deployed in dynamic equipment assemblies where flange geometry prohibits rigid gasket formats.
Spiral wound dominates installed base. Ring joint is where expansion concentrates.
Material:
Cost tiers separate commodity elastomers from engineered composites with certified emissions performance.
- Metal:Inconel, Monel, and stainless steel alloys form ring joints and spiral wound windings. United States shale operators specify these for wellhead assemblies under EPA methane monitoring requirements.
- Graphite:Flexible graphite sheet reinforced with metal foils or tangs. Metal-reinforced graphite laminates are displacing pure PTFE in fire-safe applications across Permian Basin pipeline networks preparing for hydrogen blending.
- PTFE:Virgin or filled polytetrafluoroethylene for chemical resistance.
- Rubber:Nitrile, EPDM, and fluorocarbon elastomers for low-pressure sealing.
Metal-reinforced graphite commands premium pricing. PTFE composite formulations face margin compression from commoditization.
Application:
Volume scales inversely with specification intensity — pipeline maintenance generates recurring demand while pressure vessel procurement concentrates in capital project windows.
- Pipelines:Flange connections across transmission and distribution networks require replacement cycles driven by fugitive emissions regulations. United States compressor station operators are upgrading sealing specifications under EPA New Source Performance Standards.
- Pressure Vessels:ASME-coded containment systems in processing facilities demand certified gasket architectures with documented pressure-temperature ratings.
- Pumps:Rotating equipment seals subject to dynamic loading and media compatibility constraints.
- Compressors:High-cycle machinery where gasket fatigue life determines maintenance intervals.
Pipeline replacement sustains baseline volume. Pressure vessel procurement spikes with LNG terminal construction cycles.
Installation:
Customer type stratifies procurement — supermajors consolidate direct manufacturer relationships while independent operators rely on distributor networks.
- Onshore:Wellhead assemblies, gathering lines, and processing facilities across Permian, Bakken, and Appalachian basins. United States shale field redevelopment is sustaining replacement cycles for pipeline sealing systems with specification upgrades for methane intensity compliance.
- Offshore:Subsea production systems and platform infrastructure in the Gulf of Mexico and North Sea. API 6A and ISO 13628-7 certification requirements are tightening material specifications for high-pressure, high-temperature applications.
- Refineries:Process unit turnarounds and revamps with concentrated procurement volumes for severe-service architectures.
- Storage Tanks:Atmospheric and pressurized containment with lower specification intensity.
Onshore installations anchor replacement demand. Offshore procurement is climbing the fastest on subsea expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States operators consume spiral wound and ring joint formats for severe-service refinery turnarounds, while European demand tilts toward hydrogen-compatible sheet materials for pipeline retrofitting. This consumption-mix differential shapes procurement specification divergence across Atlantic basin markets.
United States
Permian Basin shale redevelopment and Gulf Coast LNG terminal construction sustain replacement cycles for pipeline sealing systems. EPA New Source Performance Standards mandate fugitive emissions monitoring at compressor stations, forcing specification upgrades at wellhead assemblies. Houston-Galveston corridor fabricators concentrate procurement volumes for API 6A-certified architectures serving offshore Gulf of Mexico installations.
Germany
Natural gas pipeline operators require retrofitted sealing solutions compatible with hydrogen blending under national energy transition targets. REACH regulations govern material composition disclosures for graphite and PTFE composite formulations. Industrial clusters in North Rhine-Westphalia and Bavaria anchor demand for metal-reinforced sheet materials in chemical processing infrastructure.
United Kingdom
North Sea decommissioning and subsea tieback projects elevate procurement for ISO 13628-7 certified high-pressure connections. Offshore Petroleum Regulator for Environment and Decommissioning oversight tightens material traceability requirements. Aberdeen fabrication yards concentrate specification development for deepwater flange assemblies.
Netherlands
Rotterdam port hydrogen import terminal construction creates demand for cryogenic-rated gasket specifications in LNG and ammonia handling. National hydrogen backbone pipeline planning requires sealing compatibility validation for 100% hydrogen service. Eemshaven and Maasvlakte industrial zones concentrate procurement for large-diameter pipeline flange retrofits.
Saudi Arabia
Upstream expansion in Marjan and Zuluf fields drives procurement for high-temperature wellhead sealing under Saudi Aramco engineering standards. Domestic content requirements incentivize local fabrication partnerships for spiral wound production. Eastern Province industrial cities anchor demand for severe-service architectures in gas processing and NGL fractionation trains.
Oil and Gas Gasket Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the Oil and Gas Gasket Market structure. Premium-tier manufacturers command specification influence through API certification depth and polymer formulation heritage. Mid-scale fabricators compete on turnaround responsiveness and distributor channel density. Competitive moves concentrate on strategic partnerships for hydrogen service validation and selective capacity expansion for LNG cryogenic grades.
Among integrated sealing technology houses, Freudenberg Sealing Technologies and Parker Hannifin Corporation occupy positions spanning multiple installation categories through distributed manufacturing scale. Flexitallic LP exemplifies the specialized spiral wound archetype, anchoring competitive stance in refinery turnaround procurement. These three represent distinct strategic postures: polymer science heritage, diversified industrial scale, and focused severe-service specialization.
| Leading Market Players |
|---|
| Flowserve Corporation |
| Flexitallic LP |
| Freudenberg Sealing Technologies |
| Dechengwang |
| Parker Hannifin Corporation |
| Trelleborg Sealing Solutions |
| Garlock Sealing Technologies |
| Dana Incorporated |
| ElringKlinger AG |
| Others |
Cost & Logistics Intelligence
API 6A certification requirements gate both supplier qualification and price differentiation simultaneously, compressing margins for uncertified fabricators while elevating premium tiers for validated architectures serving subsea and high-temperature applications.
Pricing Analysis
Long-term offtake agreements dominate procurement for supermajor turnaround contracts, while spot purchasing persists for emergency maintenance. Three-tier pricing structure across premium, standard, and economy levels separates API-certified spiral wound formats from commodity sheet materials. Price differentiation rests on certification depth and alloy specification grade. Cost compression in PTFE composites is intensifying because formulation IP concentrates among three integrated polymer houses. Independent operators exhibit highest price sensitivity; offshore project developers demonstrate lowest.
Supply Chain Analysis
Inventory lead times stretch longest for Inconel and Monel alloy inputs subject to mining concentration volatility. Manufacturing concentrates in the United States, Germany, and China. Raw material sourcing draws from Chilean copper, Indonesian nickel, and domestic graphite deposits. Single-source vulnerability persists for specialized PTFE resin formulations. Distribution runs through API-certified industrial distributors for severe-service formats, with digital platforms capturing sheet and O-ring volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated supermajor procurement platforms, fragmenting distributor influence as direct manufacturer relationships capture large-turnaround contract flow.
For Market Incumbents: Secure API 6A certification depth as a defensive moat against emerging polymer science entrants. Deepen backward integration into graphite sheet lamination to offset alloy price volatility. Prioritize hydrogen service validation partnerships in Germany and the Netherlands to preempt substitution threats from metal-reinforced composite upstarts. For New Entrants and Emerging Players: API 6A fast-track validation programs offer the most penetrable entry path for specialized fabricators targeting refinery turnaround procurement. White-space concentrates in cryogenic-rated gasket specifications for United States Gulf Coast LNG terminals. Digital inventory platform partnerships provide go-to-market velocity without distributor network buildout. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across subsea-certified production lines, favoring scaled manufacturers with existing validation infrastructure. Five-to-ten year viability favors integrated sealing technology houses with polymer formulation heritage over pure-play metal fabricators. Watch hydrogen blending infrastructure commitment announcements in European industrial clusters as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| API 6A Certification Investment | Validates subsea and high-temperature architectures for Gulf of Mexico expansion. |
| Hydrogen Service Validation Partnership | Unlocks retrofit demand from German and Dutch pipeline operators. |
| Alloy Input Backward Integration | Reduces margin exposure to Inconel and Monel price volatility. |
| Digital Procurement Platform Integration | Captures independent operator maintenance spend from distributor networks. |
| Cryogenic Specification Development | Positions for United States LNG terminal construction cycles. |
Research Approach
Desk research of trade association databases, customs filings, and API certification registries preceded structured interviews with refinery maintenance directors, subsea project procurement leads, gasket distributor category managers, and polymer formulation chemists. Primary fieldwork across the United States, Germany, and the United Kingdom validated secondary estimates from ASME documentation, EPA enforcement records, and industrial distributor financial disclosures. Bottom-up volume builds triangulated against top-down spending allocation models.
Variance decomposition across product architecture, material grade, installation environment, and regional regulatory cluster shaped the analytical framework. Modeled dimensions include gasket format, alloy specification tier, application severity, and customer consolidation level. CAGRs derived from replacement cycle timing, capital project pipelines, and specification upgrade trajectories. Industry-specific inputs incorporated methane intensity compliance deadlines and hydrogen blending infrastructure commitments.
The analysis sits within stated boundaries; outcomes outside sustained shale field investment or accelerated European hydrogen backbone deployment would require recalibration. Forecasts reflect documented assumptions regarding certification timeline stability and alloy supply continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Middle East Wireline Logging Services Market
Oil & Gas
Downhole Motor Market
Oil & Gas
Europe Digital Oilfield Market
Oil & Gas
North America Wireline Services Market
Oil & Gas
Well Test Market
Oil & Gas
Workover Rigs Market
Oil & Gas
Africa Oilfield Services Market
Oil & Gas
Smart Pigging Market
Oil & Gas
Chad Oil and Gas Market
Oil & Gas
Indonesia Oilfield Equipment Rental Services Market
Oil & Gas
Global Oilfield Communications Market
Oil & Gas
FTIR Oil Condition Monitoring Market
Oil & Gas
Asia-Pacific AI in Oil and Gas Market
Oil & Gas
China Oil and Gas Midstream Market
Oil & Gas
Geothermal Drilling Market
Oil & Gas
Algeria Oil and Gas Market