
 Asia-Pacific Well Intervention Market | 2026-2036
Asia-Pacific Well Intervention Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Well Intervention Market Outlook
A capital-intensity divergence between integrated service providers and specialized tool manufacturers is reorganizing competitive dynamics across the Asia-Pacific well intervention sector. Schlumberger Limited leverages its integrated project management footprint to anchor long-term contracts across Australia's offshore complexes. Baker Hughes Company differentiates through proprietary downhole tool portfolios tailored to high-pressure, high-temperature reservoirs in the region. Halliburton Company sustains operational density through established bases in Thailand and Indonesia, competing on mobilization speed for emergency well control.
Asia-Pacific well intervention encompasses engineered services and equipment deployed to restore, enhance, or terminate production from existing oil and gas wells, typically involving coiled tubing units rated for pressures exceeding 10,000 psi and wireline conveyance systems capable of operating at depths beyond 6,000 meters. These technologies address reservoir depletion, mechanical failure, and sand production in both platform-supported and subsea completions. Coil tubing services command the largest revenue share among service types, reflecting repeated deployment for nitrogen lifts and acid stimulations across Indonesia's mature Duri field. Offshore delivery modes generate premium pricing relative to onshore equivalents, driven by vessel mobilization costs and subsea intervention complexity in Malaysia's deepwater Sabah basins.
China's MEE enforces stringent emissions reporting for offshore drilling campaigns, compelling operators to adopt lower-carbon intervention fleets. Australia's NOPSEMA mandates well integrity management systems that require periodic mechanical verification, directly sustaining demand for wireline logging and downhole diagnostic services. India's CEA petroleum safety protocols impose certification requirements on pressure control equipment used in Bombay High operations. Stakeholders must monitor regulatory divergence across these jurisdictions to align capital allocation with compliance-driven spending cycles.
Market Dynamics
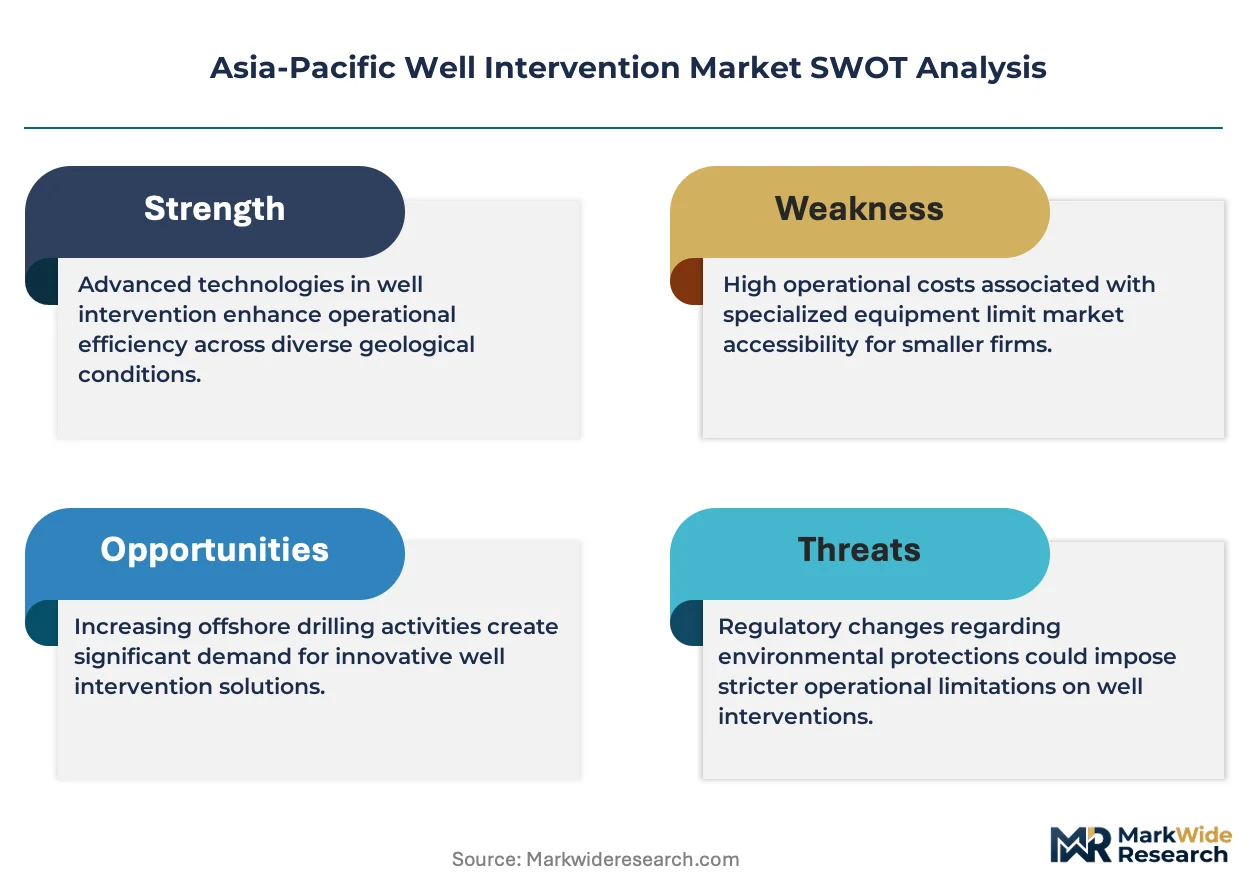
China's MEE emissions enforcement is compressing deployment timelines for conventional intervention fleets across Southeast Asian offshore basins, forcing operators to accelerate capital rotation toward lower-carbon service configurations.
Growth Catalysts
- Dual carbon goals:China's binding carbon intensity targets under MEE oversight mandate fleet electrification and fuel switching in offshore drilling campaigns, sustaining equipment replacement cycles.
- NOPSEMA well integrity mandates:Australia's regulatory framework requires periodic mechanical verification and documented barrier testing, institutionalizing demand for wireline logging and diagnostic services.
- Maturing basins:Indonesia's Duri field and Malaysia's shallow-water assets exhibit accelerating production decline rates that necessitate repeated nitrogen lift and acid stimulation workovers.
Market Restraints
- Specialized vessel scarcity:Purpose-built intervention ships capable of dynamic positioning in deepwater Sabah basins concentrate among a limited contractor pool, creating mobilization bottlenecks.
- High-pressure equipment certification:India's CEA petroleum safety protocols impose extended validation timelines on pressure control equipment destined for Bombay High operations.
- Steel alloy input volatility:Coiled tubing manufacturing depends on chromium-molybdenum alloy supply chains exposed to commodity price swings and export restriction risk.
Strategic Opportunities
- Subsea abandonment services:Australia's North West Shelf hosts an expanding inventory of end-of-life platform wells requiring P&A campaigns that command premium day rates.
- Digital twin integration:Convergence of real-time downhole telemetry with predictive maintenance algorithms enables condition-based intervention scheduling for Thai operators.
- Vietnam's unexplored blocks:Underpenetrated shallow-water concessions off Vietnam's southern coast offer first-mover positioning for integrated intervention packages.
Industry Challenges
- Subsea systems engineering talent:Deepwater intervention planning requires rare cross-training in wellbore hydraulics and subsea architecture, constraining project staffing.
- Legacy platform integration:Retrofitting coiled tubing systems onto decades-old Indonesian production facilities demands custom structural reinforcement and safety system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Well Intervention Market |
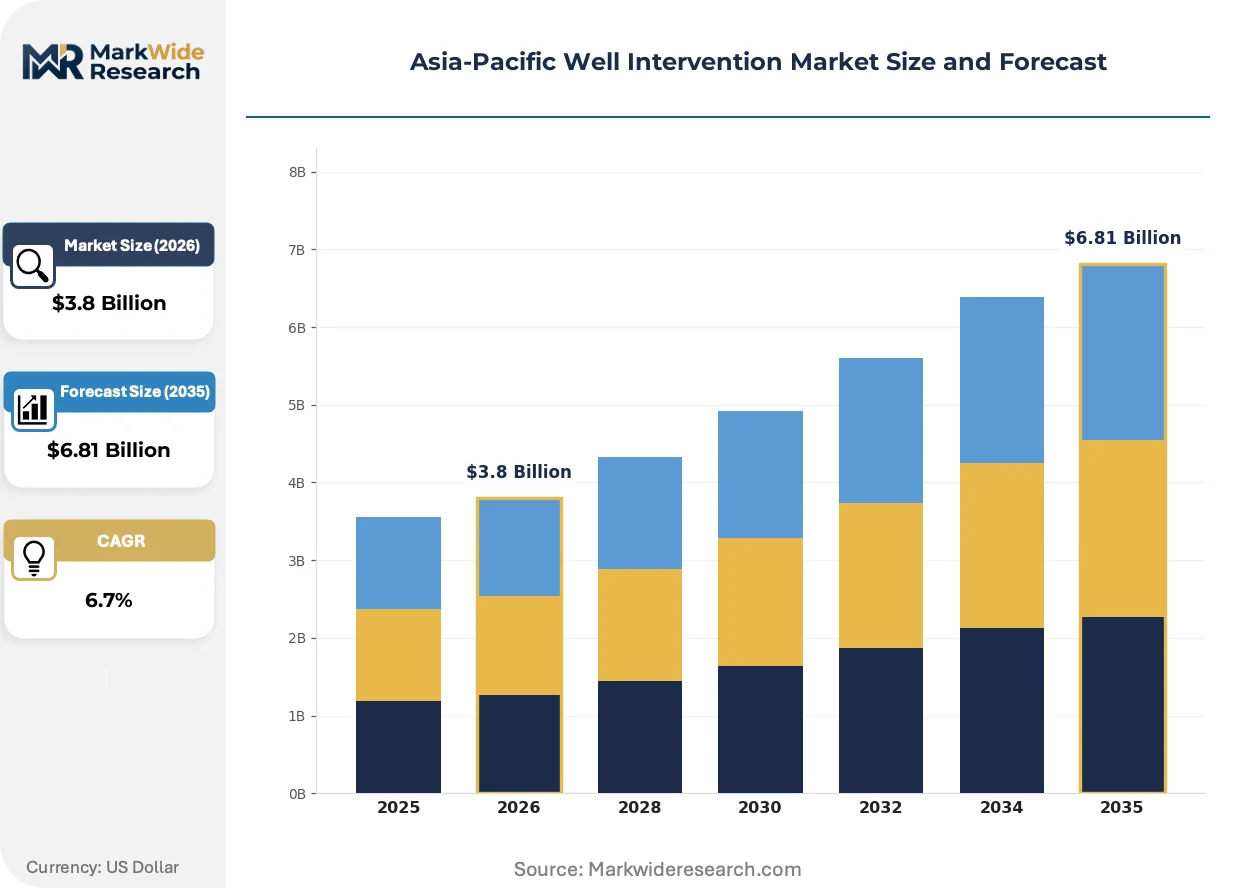
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Coil Tubing, Pressure Control, Downhole Tools, Wireline Services Application: Well Abandonment, Reservoir Management, Well Maintenance, Production Optimization Delivery Mode: Onshore, Offshore, Subsea, Integrated End User: Independent Operators, National Oil Companies, Service Providers, OEMs |
| Companies Covered | Weatherford International PLC, Oceaneering International Inc., Schlumberger Limited, National Oilwell Varco Inc., China Oilfield Services Limited, Baker Hughes Company, Expro Group, Welltec A/S, Halliburton Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Well Intervention Market Strategic Shifts
Electrification of offshore intervention fleets is intersecting with digital workflow integration to compress operational carbon intensity while expanding real-time decision-making capabilities across dispersed asset bases.
Lightweight composite coiled tubing is fragmenting traditional steel-dominated service lines. The material reduces deck load constraints on marginal platforms and extends fatigue life in high-cycle nitrogen lift applications. Malaysian operators in shallow-water Sabah fields are piloting hybrid fleets, and this material substitution is fragmenting supplier hierarchies that built market position on steel metallurgy expertise.
China's MEE tightened offshore emissions reporting thresholds in 2024, compelling operators to document fuel consumption and methane leakage across intervention campaigns. The regulation elevates capital allocation toward dual-fuel vessel charters and shore-power-ready rig modifications. Australian NOPSEMA audits now incorporate MEE-aligned disclosure standards, regionalizing compliance architecture across Asia-Pacific.
Performance-based contracting is displacing conventional day-rate structures for major workover programs. Thai and Indonesian national oil companies now tie contractor compensation to production restoration targets rather than time-on-well. This model concentrates risk with service providers and demands integrated project management capabilities that smaller tool specialists cannot support.
Asia-Pacific Well Intervention Market Segmentation
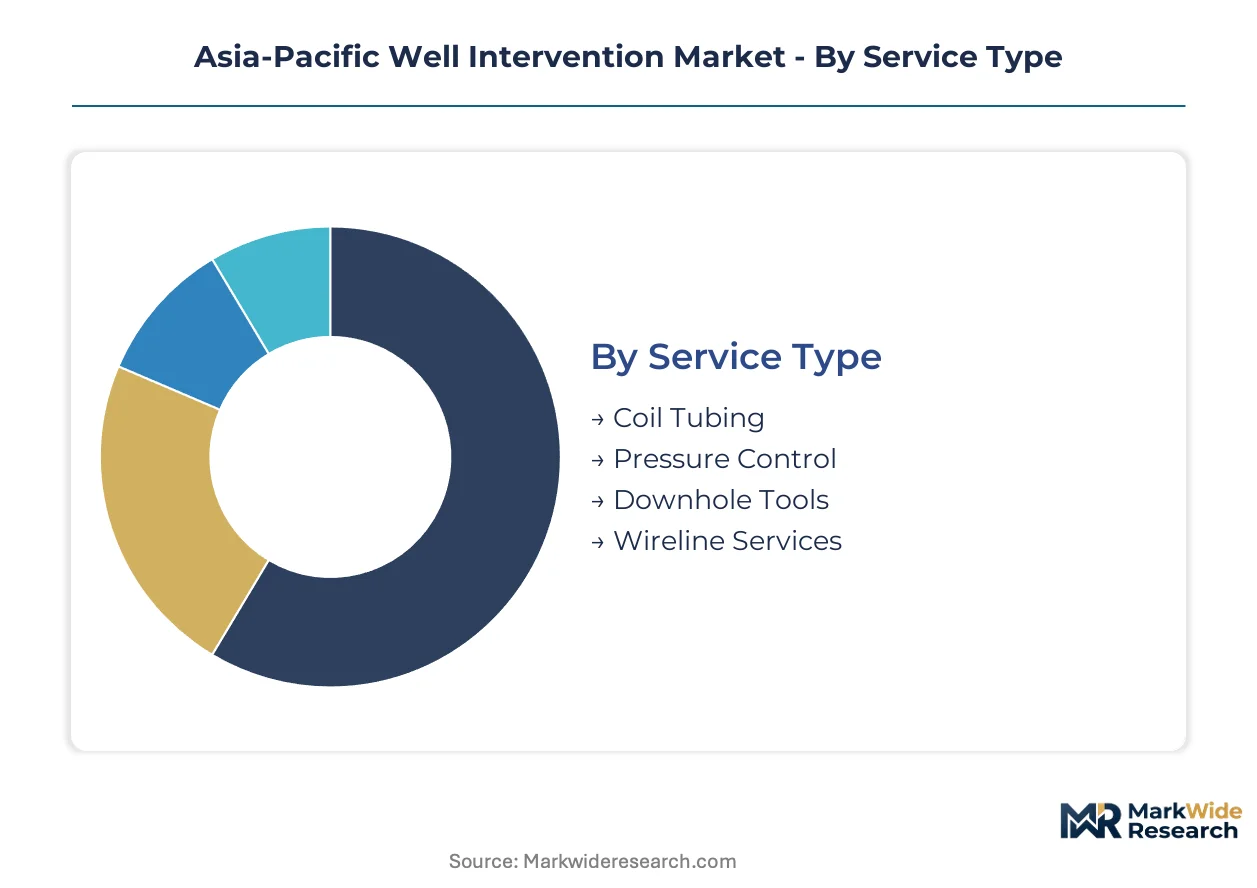
Service differentiation across intervention categories determines procurement channel selection and margin capture for contractors operating in Asia-Pacific's fragmented basin geography. Segment boundaries increasingly blur as integrated providers bundle discrete capabilities into performance-based contracts.
Service Type:
Channel mix varies sharply by service complexity—coil tubing and wireline flow through established service company networks, while pressure control equipment concentrates with specialized manufacturers and OEM direct sales.
- Coil Tubing:Continuous steel or composite tubing deployed on reels for nitrogen lifts, acid stimulations, and mechanical interventions. Demand concentrates in Indonesia's Duri field and Malaysia's shallow-water assets where mature reservoirs require repeated workover cycles.
- Pressure Control:Blowout preventers, wellheads, and choke manifolds rated for HPHT conditions. Australia's North West Shelf and deepwater Sabah basins drive specification intensity as NOPSEMA mandates escalate barrier testing frequencies.
- Downhole Tools:Packers, bridge plugs, and fishing tools for mechanical isolation and debris retrieval. China's MEE emissions enforcement is compressing deployment timelines for conventional tool fleets.
- Wireline Services:Electric line and slickline conveyance for logging, perforating, and plug setting. India's CEA certification requirements extend validation timelines for Bombay High operations.
Coil tubing dominates installed base. Pressure control is where expansion concentrates.
Application:
Cost tier stratification separates commoditized maintenance work from premium abandonment and optimization contracts with outcome-based pricing structures.
- Well Abandonment:Permanent plugging and abandonment of depleted wells per regulatory mandates. Australia's North West Shelf platform inventory generates premium day rates as end-of-life campaigns accelerate.
- Reservoir Management:Surveillance, zonal isolation, and pressure maintenance programs. Thailand's mature Gulf of Thailand assets sustain recurring demand for diagnostic and intervention packages.
- Well Maintenance:Routine mechanical repairs, sand control remediation, and tubular replacement. Indonesia's legacy platforms require custom structural reinforcement for coiled tubing system retrofits.
- Production Optimization:Stimulation, artificial lift installation, and choke management. Vietnam's underpenetrated shallow-water concessions offer first-mover positioning for integrated optimization services.
Well maintenance commands volume share. Well abandonment is climbing the fastest.
Delivery Mode:
Geography determines mobilization economics—onshore operations leverage road-transportable units while offshore and subsea modes require vessel charter networks with concentrated contractor pools.
- Onshore:Land-based coil tubing and workover rigs with lower mobilization overhead. China's Sichuan and Tarim basins anchor regional onshore demand as shale development matures.
- Offshore:Platform-based interventions using jackup rigs or liftboats. Malaysia's shallow-water Sabah fields and Indonesia's Java Sea assets generate recurring campaign requirements.
- Subsea:Riserless light well intervention via dynamically positioned vessels. Deepwater Sabah and Australia's North West Shelf concentrate scarce vessel capacity among limited contractors.
- Integrated:Bundled project management combining multiple service lines under single accountability. Thai and Indonesian national oil companies are displacing day-rate structures with production restoration targets.
Offshore delivery anchors revenue. Subsea is gaining share fastest.
End User:
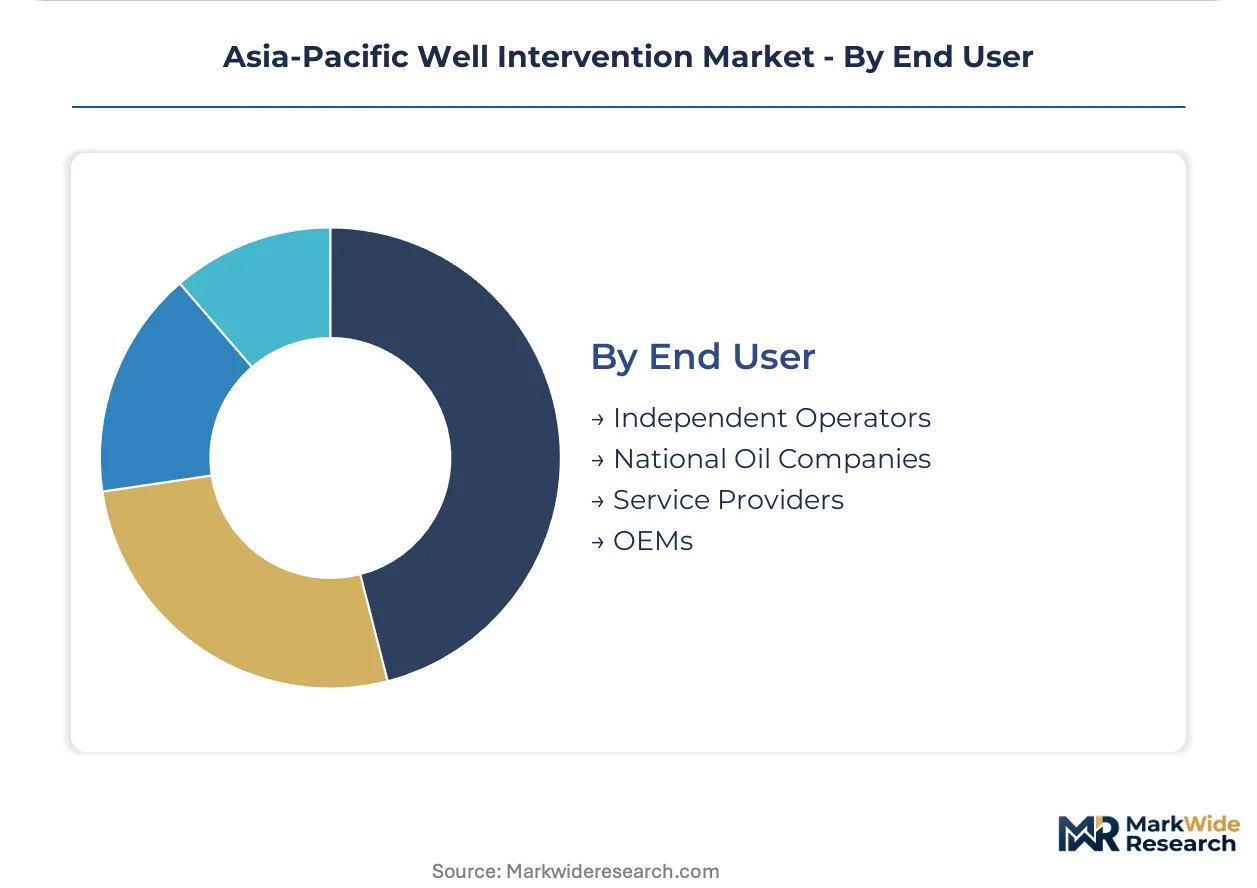
Customer type shapes contract structure—independent operators prioritize mobilization speed, national oil companies drive performance-based terms, and OEMs capture aftermarket through equipment-anchored service agreements.
- Independent Operators:Smaller exploration and production companies with focused asset portfolios. Australia's mid-cap offshore players demand rapid emergency response capabilities for well control events.
- National Oil Companies:State-owned entities including Pertamina, Petronas, and CNOOC. These buyers institutionalize performance-based contracting that concentrates risk with service providers.
- Service Providers:Integrated contractors and specialized tool companies delivering execution capacity. Schlumberger, Baker Hughes, and Halliburton anchor long-term contracts across Australia's offshore complexes.
- OEMs:Original equipment manufacturers capturing recurring revenue through parts, upgrades, and field service. Downhole tool OEMs leverage proprietary portfolios for HPHT reservoir differentiation.
National oil companies dominate procurement volume. Independent operators are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for high-pressure intervention equipment tilts the trade balance toward specialized manufacturing centers in the United States and Europe, while service execution capacity concentrates within Asia-Pacific's offshore basins. Domestic fabrication remains limited for subsea-rated pressure control systems.
Australia
NOPSEMA mandates periodic well integrity verification across the North West Shelf, sustaining demand for wireline logging and diagnostic campaigns. The regulator's barrier testing requirements institutionalize recurring service expenditure. Perth anchors contractor headquarters for deepwater abandonment programs targeting end-of-life platform wells.
China
MEE emissions enforcement compresses deployment timelines for conventional intervention fleets, accelerating capital rotation toward lower-carbon configurations. Dual carbon goals bind offshore operators to documented fuel consumption and methane leakage reporting. Sichuan and Tarim basin shale maturation sustains onshore coil tubing demand for nitrogen lift operations.
Indonesia
Pertamina's workover programs in the Duri field generate repeated acid stimulation and sand control remediation requirements. The country's national oil company institutionalizes performance-based contracting that concentrates risk with service providers. Java Sea shallow-water assets require legacy platform retrofits for coiled tubing system integration.
Malaysia
Petronas prioritizes production restoration targets over day-rate structures for major workover campaigns in shallow-water Sabah fields. Deepwater basins concentrate scarce dynamically positioned intervention vessel capacity among limited contractors. Kuala Lumpur anchors regional procurement decision-making for integrated project management contracts.
India
CEA petroleum safety protocols impose extended validation timelines on pressure control equipment destined for Bombay High operations. The regulator's certification requirements create procurement bottlenecks for high-pressure blowout preventers. Mumbai anchors technical service coordination for offshore campaign planning.
Asia-Pacific Well Intervention Market Competitive Environment
Concentration sits with integrated service providers capable of bundling discrete capabilities under performance-based accountability structures. The vendor base separates into three tiers: full-service contractors with project management footprints, specialized tool manufacturers with proprietary downhole portfolios, and regional execution specialists competing on mobilization speed. M&A activity targets subsea engineering talent pools, while strategic partnerships address vessel capacity constraints in deepwater basins.
Within the integrated contractor tier, Schlumberger Limited, Baker Hughes Company, and Halliburton Company represent archetypal positioning across long-term contract anchoring, proprietary HPHT tool differentiation, and emergency response density respectively. These Houston-headquartered entities exemplify the capital intensity divergence reorganizing competitive dynamics. China Oilfield Services Limited occupies a distinct geography-first position serving domestic operators under MEE compliance frameworks. Specialists including Welltec A/S and Expro Group sit within technology-differentiated niches addressing riserless light well intervention and subsea diagnostic conveyance.
| Leading Market Players |
|---|
| Weatherford International PLC |
| Oceaneering International Inc. |
| Schlumberger Limited |
| National Oilwell Varco Inc. |
| China Oilfield Services Limited |
| Baker Hughes Company |
| Expro Group |
| Welltec A/S |
| Halliburton Company |
| Others |
Value Chain & Pricing Dynamics
India's CEA petroleum safety protocols gate both supplier qualification timelines and price differentiation for pressure control equipment, compressing margins for uncertified manufacturers while enabling certified incumbents to capture premium positioning in Bombay High operations. This regulatory architecture simultaneously restricts supply base breadth and stratifies pricing tiers by compliance tier.
Pricing Analysis
Industrial OEM buyers anchor a project-based pricing structure for high-pressure intervention equipment. Price differentiation stems from HPHT certification grade and after-sales service bundling. Pricing pressure intensifies in shallow-water segments as Malaysian and Indonesian national oil companies displace day-rate contracts with production restoration targets. Independent operators exhibit highest price sensitivity due to limited workover campaign budgets.
Supply Chain Analysis
United States and European manufacturing centers anchor fabrication of subsea-rated pressure control systems and specialized downhole tools. Chromium-molybdenum alloy supply chains for coiled tubing production draw from commodity markets exposed to export restriction risk. Single-source vulnerability concentrates in dynamically positioned intervention vessel capacity for deepwater Sabah basins. Distribution runs through integrated service company networks and OEM direct sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific well intervention functions as a service-attach opportunity where integrated project management and condition-based maintenance contracts expand faster than discrete equipment sales. Recurring revenue from diagnostic telemetry subscriptions and predictive maintenance algorithms outpaces hardware replacement cycles.
For Market Incumbents: Consolidate proprietary HPHT tool portfolios through targeted capability acquisition in subsea systems engineering. Lock in long-term platform contracts across Australia's North West Shelf before performance-based contracting fully displaces day-rate structures. Vertical integration into composite coiled tubing manufacturing mitigates steel alloy input volatility threatening margin stability. For New Entrants and Emerging Players: Fast-track NOPSEMA well integrity certification enables positioning against established wireline incumbents in Australian abandonment campaigns. Vietnam's underpenetrated shallow-water blocks offer lowest competitive density for integrated optimization packages. Partner with regional liftboat operators to bypass scarce dynamically positioned vessel bottlenecks in Malaysian deepwater. For Investors and Strategic Acquirers: China's MEE emissions enforcement milestones reshape the acquisition landscape toward lower-carbon service configurations and electrified fleet operators. Five-to-ten year viability favors integrated contractors with project management capabilities spanning multiple intervention service lines. Monitor Petronas and Pertamina procurement policy shifts toward outcome-based contracting as inflection signals for sector margin redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Subsea Systems Engineering Acquisition | Addresses talent scarcity constraining deepwater intervention project staffing across Sabah basins. |
| Composite Coiled Tubing Manufacturing Scale-Up | Reduces deck load constraints on Indonesia's legacy platforms while extending fatigue life cycles. |
| Digital Twin Platform Integration | Enables condition-based intervention scheduling for Thai operators transitioning from time-based maintenance. |
| Dual-Fuel Vessel Fleet Conversion | Aligns with MEE emissions reporting thresholds compressing deployment timelines for conventional fleets. |
| Performance-Based Contracting Capability Buildout | Matches procurement evolution at Pertamina and Petronas toward production restoration targets. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and contractor financial disclosures. Interviews with offshore operations managers, well integrity engineers, procurement leads at national oil companies, and aftermarket service directors inform demand-side validation. Secondary sources include NOPSEMA audit records, MEE emissions reporting databases, CEA certification registries, and vessel charter market data. Bottom-up project pipeline analysis triangulates against top-down expenditure benchmarking across the analysis window.
Segmentation dimensions modeled encompass service type, application category, delivery mode, and end-user archetype across regional basin clusters. CAGRs derive from expenditure trajectory analysis tied to maturing field inventories and regulatory compliance cycles. Forecast inputs incorporate Duri field workover frequency, North West Shelf abandonment campaign scheduling, and MEE enforcement intensity assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained regulatory enforcement and stable commodity price environments; material deviation would warrant model refresh. Specific risks include accelerated platform decommissioning timelines, intervention vessel capacity constraints, and alloy supply chain disruptions. Recalibration cycles align with material shifts in national oil company procurement policy and environmental regulator enforcement posture.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Argentina Oil and Gas Upstream Market
Oil & Gas
Bunker Liners Market
Oil & Gas
Crude Oil Carriers Market
Oil & Gas
Drilling Fluids Market
Oil & Gas
Chad Oil and Gas Upstream Market
Oil & Gas
Fracking Fluid Market
Oil & Gas
Digital Twin in Oil and Gas Market
Oil & Gas
Deepwater and Ultra-Deepwater Exploration and Production Market
Oil & Gas
Deepwater Hydrocarbons Exploration Market
Oil & Gas
Iron Ore Mining Market
Oil & Gas
Pipeline Integrity Market
Oil & Gas
South-East Asia Oil and Gas Pipeline Market
Oil & Gas
Crown Block Market
Oil & Gas
East Africa Oil and Gas Market
Oil & Gas
Oil and Gas Hose Assemblies Market
Oil & Gas
Oil and Gas Fabrication Market