
 Flow Computer Oil Gas Market | 2026-2036
Flow Computer Oil Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Flow Computer Oil Gas Market Foresight
Buyer concentration across North American pipeline operators is pivoting toward integrated custody transfer solutions. Emerson Electric Co. leverages its DeltaV automation platform to anchor large-diameter pipeline contracts. Honeywell International Inc. competes through Experion-based flow measurement systems deployed across Permian gathering networks. ABB Ltd. differentiates via integrated analytics packages that extend hardware value into predictive maintenance services.
A flow computer for oil and gas is a dedicated microprocessor-based instrument that calculates corrected volumetric or mass flow rates using inputs from differential pressure, ultrasonic, or Coriolis meters, typically achieving accuracy within 0.1% for custody transfer applications. Its primary purpose is to enforce fiscal metering standards, allocate hydrocarbon volumes among stakeholders, and enable real-time leak detection across pipeline networks. Smart flow computers command premium positioning due to embedded edge-computing capabilities that reduce dependency on centralized SCADA polling. Modular architectures represent the fastest-expanding configuration category as operators phase out legacy single-function units during brownfield retrofits.
API Chapter 21.1 custody transfer protocols, NIST traceability requirements, and EPA greenhouse gas reporting mandates collectively shape product certification roadmaps and vendor qualification timelines. The Federal Energy Regulatory Commission's interstate pipeline tariff rules further constrain acceptable measurement uncertainty bands for cross-border liquids movements. Stakeholders must weigh embedded cybersecurity compliance against total cost of ownership when specifying next-generation flow computer architectures.
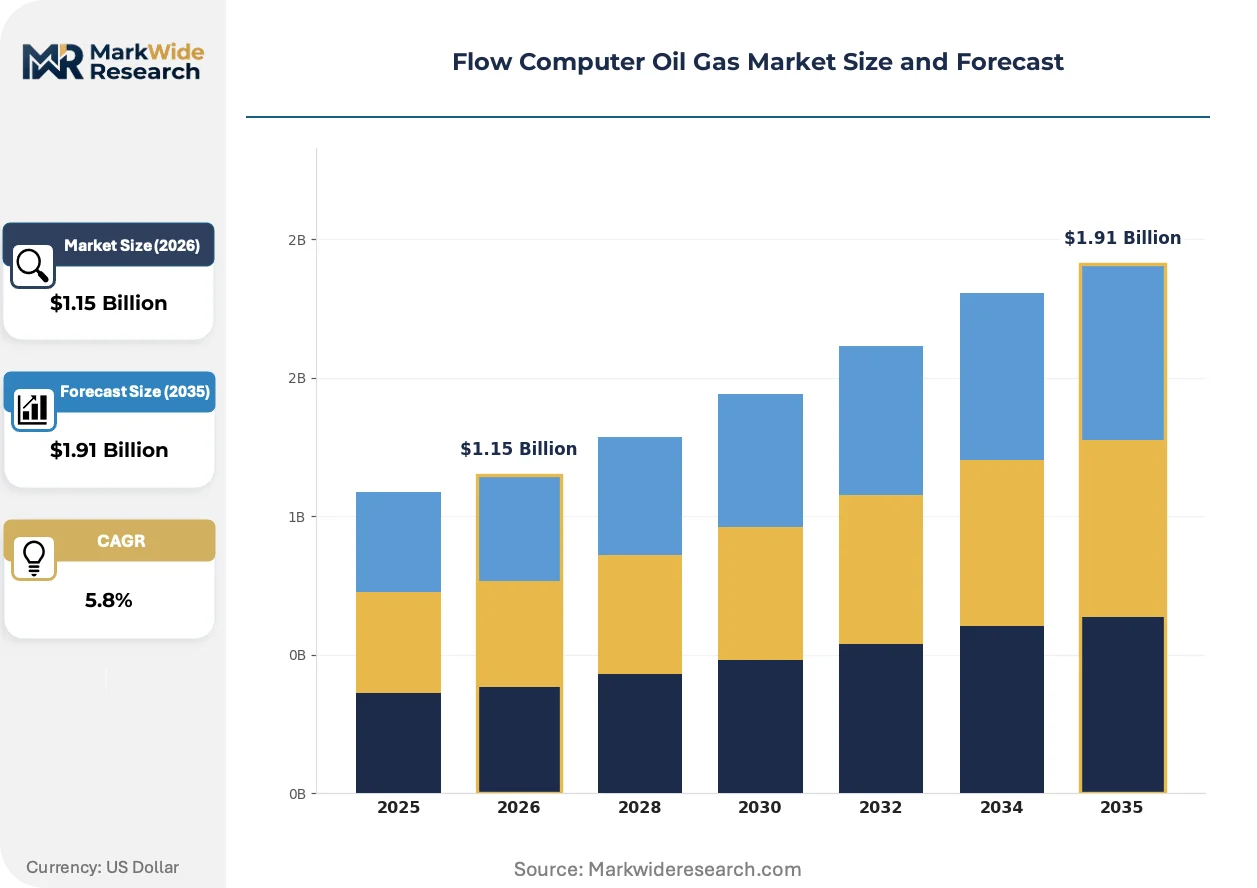
Market Dynamics
Pipeline operators are retiring legacy single-function flow computers in favor of modular, edge-capable architectures that embed API Chapter 21.1 compliance and reduce SCADA polling dependency. This hardware refresh cycle is compressing vendor qualification timelines and reshaping procurement specifications across North American shale basins.
Growth Catalysts
- API Chapter 21.1 Custody Transfer Mandates:The American Petroleum Institute's updated fiscal metering standards are forcing pipeline operators to replace aging mechanical measurement systems with electronic flow computers that deliver 0.1% accuracy bands.
- Permian Basin Infrastructure Buildout:Gathering network expansions across West Texas and southeastern New Mexico are generating concentrated demand for high-capacity ultrasonic meter-integrated flow computers.
- Edge Computing Integration:Embedded processing capabilities that enable real-time leak detection algorithms and local data logging are differentiating next-generation units from legacy polling-dependent architectures.
Market Restraints
- Semiconductor Component Volatility:Prolonged lead times for industrial-grade microprocessors and analog-to-digital converters are extending manufacturing cycles and inflating unit costs for flow computer OEMs.
- Specialized Calibration Labor Scarcity:NIST-traceable flow calibration facilities remain concentrated in Houston, Calgary, and Rotterdam, creating geographic bottlenecks for custody transfer certification.
- Proprietary Protocol Lock-in:Emerson's Modbus-RTU and Honeywell's proprietary fieldbus implementations create switching costs that deter multi-vendor standardization efforts among pipeline operators.
Strategic Opportunities
- EPA Greenhouse Gas Reporting Compliance:Mandatory methane emissions monitoring under 40 CFR Part 98 Subpart W is creating pull-through demand for flow computers with integrated gas composition analysis and automated reporting outputs.
- Brazil Pre-Salt Development:Petrobras-led subsea tieback projects in the Santos Basin represent underpenetrated demand for subsea-rated flow computers capable of 3,000-meter depth operation.
- Digital Twin Convergence:Pairing physical flow computers with simulation-based predictive models enables operators to optimize meter proving intervals and reduce calibration downtime.
Industry Challenges
- Cybersecurity Certification Complexity:NERC CIP-005 and API 1164 compliance requirements are extending engineering validation cycles by 6-12 months for networked flow computer deployments.
- Brownfield Integration Friction:Retrofitting edge-capable flow computers into 1990s-era SCADA architectures requires custom protocol gateways and creates commissioning delays at legacy pipeline stations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flow Computer Oil Gas Market |
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $1.91 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Flow Computers, Modular Flow Computers, Wireless Flow Computers, Smart Flow Computers, Multi-Channel Flow Computers Technology: Programmable Logic Controllers, SCADA Integration, IoT Enabled, Wireless Communication, Data Logging Systems Application: Refinery Monitoring, Pipeline Management, Custody Transfer, Gas Metering, Liquids Measurement End User: Upstream Operations, Midstream Operators, Downstream Processing Units, Field Service Providers, Metering Stations |
| Companies Covered | Schneider Electric SE, Thermo Fisher Scientific Inc., Emerson Electric Co., TechnipFMC plc, Krohne Messtechnik GmbH, Honeywell International Inc., Yokogawa Electric Corporation, OMNI Flow Computers Inc., ABB Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flow Computer Oil Gas Market Shifts & Advancements
Flow computer architectures are converging around software-defined measurement platforms that decouple hardware acquisition from algorithm licensing. This shift is compressing product lifecycles and forcing vendors to defend recurring revenue streams through firmware subscription models rather than capital equipment replacement cycles.
Multivariable transmitters with embedded flow computation are consolidating discrete component stacks into single-device custody transfer solutions. Midstream operators in the Bakken and DJ Basins are specifying these integrated units for new wellpad installations. The technology is consolidating vendor roles by absorbing functions previously performed by standalone flow computers, pressure transmitters, and temperature sensors into unified measurement chains.
FERC Order 1920 interstate pipeline tariff rules are mandating tighter measurement uncertainty bands for cross-border crude movements. The regulation is forcing operators to retire mechanical chart recorders and adopt ultrasonic meter-integrated electronic systems. Gulf Coast liquids corridors serving export terminals are experiencing the most acute compliance-driven replacement activity.
After-sales service unbundling is separating hardware warranties from calibration and algorithm update subscriptions. Large pipeline operators are negotiating direct meter-proving contracts with third-party labs, bypassing OEM service departments. This pattern is most pronounced among Permian Basin independents seeking to reduce per-unit lifecycle costs through competitive calibration sourcing.
Flow Computer Oil Gas Market Segmentation
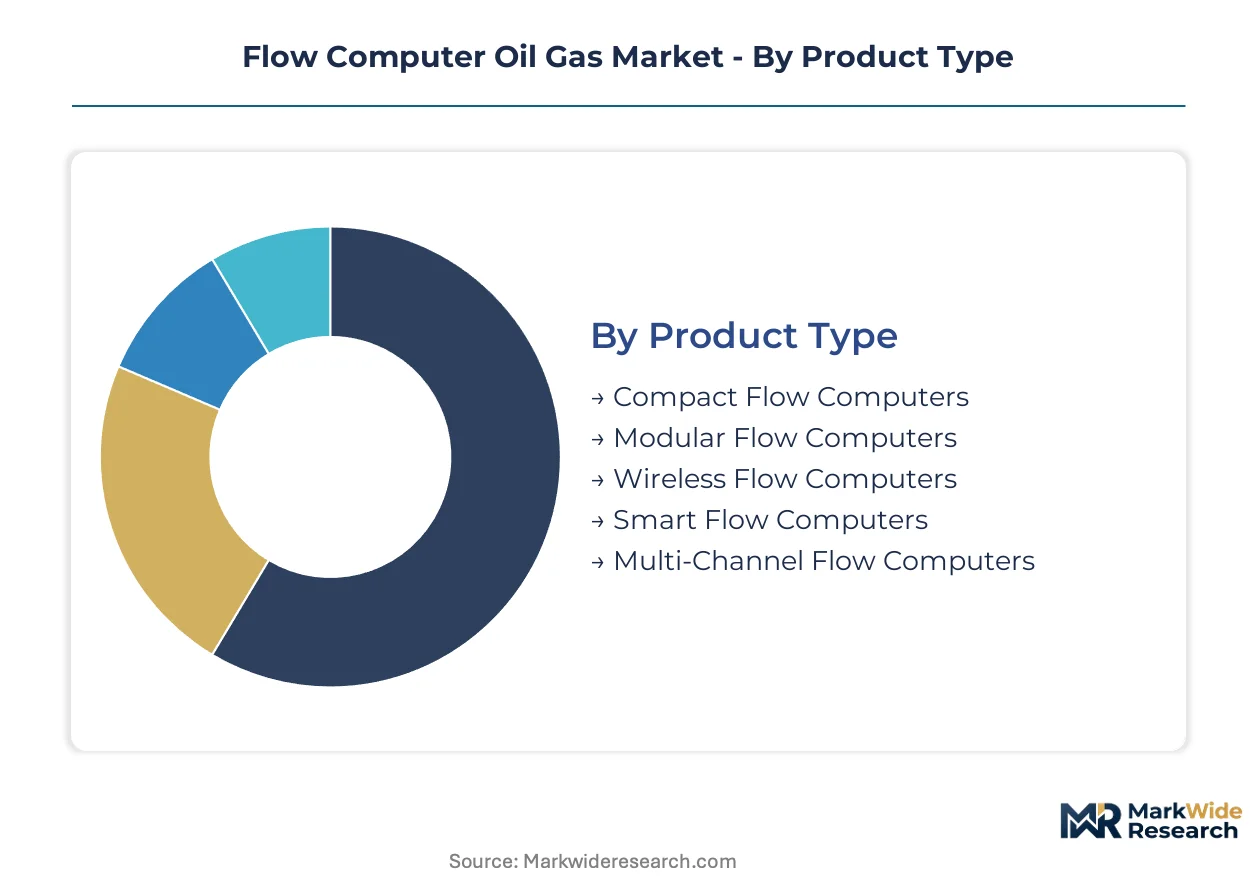
Flow computer segmentation reflects divergent technical requirements across custody transfer precision, SCADA integration depth, and field deployment conditions. Procurement specifications vary sharply between greenfield pipeline installations and brownfield retrofit environments.
Product Type:
Architectural design determines scalability, maintenance access, and upgrade pathways across metering station deployments.
- Compact Flow Computers:Single-board designs integrate differential pressure and temperature compensation in sealed enclosures for wellpad custody transfer. Operators in the Permian Basin specify these units for high-density gathering networks where space constraints dominate.
- Modular Flow Computers:Hot-swappable I/O cards and expandable processor slots enable phased migration from mechanical chart recorders without full system replacement. This architecture is gaining share fastest among midstream operators managing legacy SCADA integration.
- Wireless Flow Computers:Battery-powered units with cellular or satellite backhaul eliminate trenching costs at remote lease automatic custody transfer sites.
- Smart Flow Computers:Edge-processing capability with embedded API Chapter 21.1 algorithms reduces polling dependency on centralized hosts.
- Multi-Channel Flow Computers:Single chassis aggregates inputs from multiple ultrasonic or Coriolis meters at large-diameter pipeline interconnections.
Modular flow computers lead on scale; smart flow computers lead on momentum.
Technology:
Communication protocol and data architecture choices constrain vendor selection and cybersecurity compliance timelines.
- Programmable Logic Controllers:Hardwired ladder logic execution delivers deterministic scan times for safety-critical shutdown systems. Downstream processing units in Gulf Coast refineries favor PLC-based architectures for SIL-rated applications.
- SCADA Integration:Native DNP3 and Modbus TCP/IP stacks enable direct polling by centralized control systems without protocol gateways. Pipeline operators specify deep SCADA compatibility to minimize commissioning delays.
- IoT Enabled:Cloud-fluent architectures with MQTT brokers support predictive analytics and remote firmware management.
- Wireless Communication:License-free ISM band or licensed cellular radios extend measurement reach beyond cabled infrastructure.
- Data Logging Systems:Redundant solid-state storage with NIST-traceable timestamps preserves audit trails for FERC tariff disputes.
SCADA integration leads on scale; IoT enabled configurations lead on momentum.
Application:
Metering purpose dictates accuracy requirements, regulatory jurisdiction, and maintenance intervals.
- Custody Transfer:API Chapter 21.1-compliant flow computers achieve 0.1% measurement uncertainty for commercial settlement between producers and midstream operators. Gulf Coast liquids corridors generate concentrated demand as FERC Order 1920 mandates electronic replacement of mechanical systems.
- Pipeline Management:Real-time leak detection algorithms process pressure transient data at kilometer intervals for rupture identification. This application is expanding most quickly under EPA methane monitoring mandates.
- Refinery Monitoring:Mass balance reconciliation across process units requires multivariable transmitters with embedded flow computation.
- Gas Metering:AGA-8 compressibility calculations and gas chromatograph integration handle wet gas and varying composition streams.
- Liquids Measurement:Prover loop integration and meter factor tracking support crude oil and NGL allocation.
Custody transfer leads on scale; pipeline management leads on momentum.
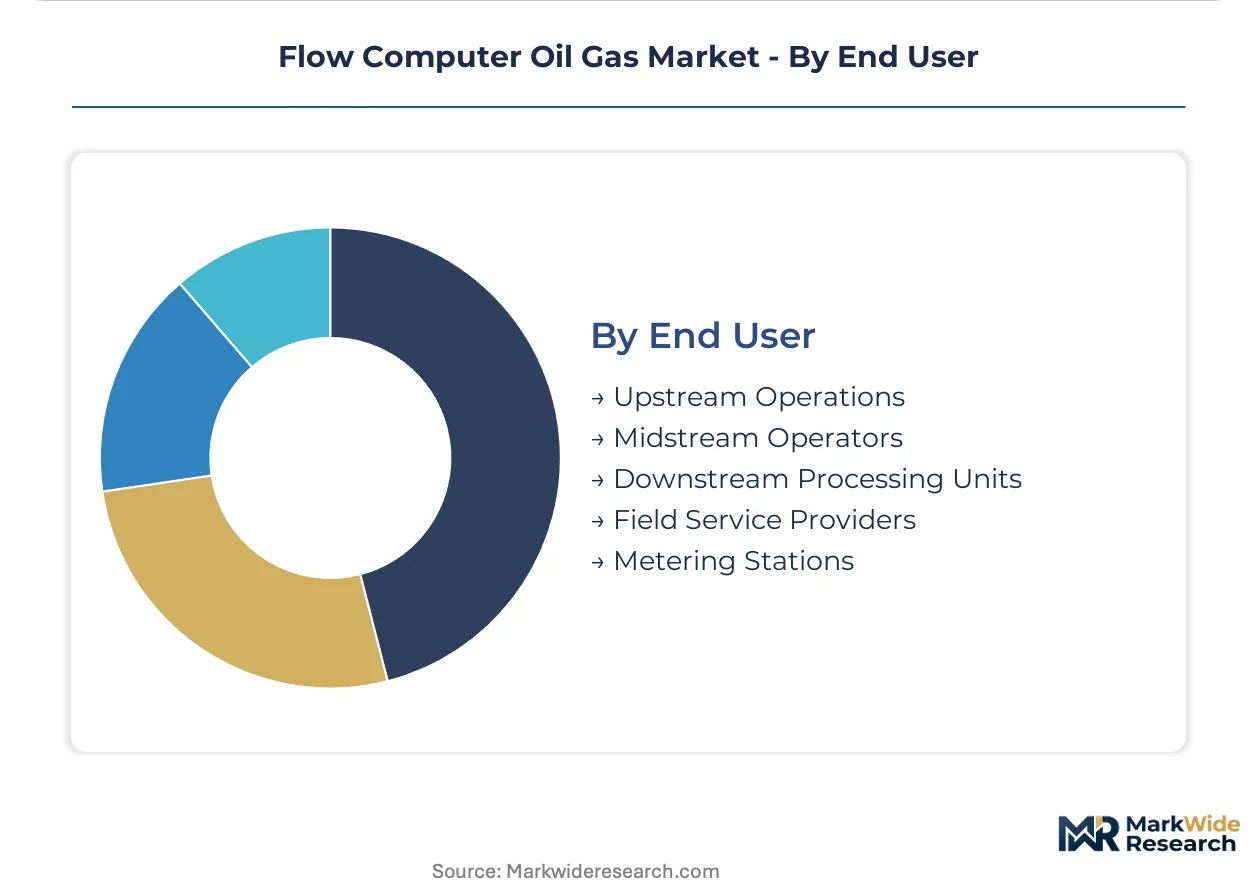
End User:
Organizational role determines capital allocation authority, technical staffing depth, and vendor relationship intensity.
- Midstream Operators:Pipeline and gathering system owners specify flow computers across tariff-regulated interstate movements and intrastate gathering. West Texas independents concentrate procurement for Permian Basin infrastructure buildout.
- Upstream Operations:Exploration and production companies deploy units at wellhead separation facilities and lease automatic custody transfer points. This segment shows steepest expansion trajectory as shale producers automate field operations.
- Downstream Processing Units:Refinery and fractionation plant engineers prioritize SIL safety ratings and hazardous area certifications.
- Metering Stations:Dedicated measurement facilities operated by joint ventures or third-party calibrators enforce multi-party audit protocols.
- Field Service Providers:Rental and maintenance contractors supply temporary custody transfer capacity during turnaround periods.
Midstream operators lead on scale; upstream operations lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum measurement engineers and SCADA integration specialists concentrate in Houston, Calgary, and Rotterdam, anchoring regional capability clusters for custody transfer system deployment.
United States
Permian Basin gathering network expansions and Gulf Coast export terminal buildouts drive concentrated demand for API Chapter 21.1-compliant flow computers. FERC Order 1920 mandates tighter measurement uncertainty bands for interstate crude movements. West Texas independents automate lease automatic custody transfer points across Midland and Delaware sub-basins.
Canada
Alberta oil sands producers and British Columbia LNG exporters require high-accuracy flow computers for multi-party allocation agreements. Measurement Canada enforces NIST-traceable calibration standards for custody transfer certification. Calgary hosts the dominant concentration of flow calibration laboratories serving North American shale operators.
Brazil
Petrobras-led pre-salt subsea tieback projects in the Santos Basin generate demand for pressure-rated flow computers capable of ultra-deepwater operation. ANP regulatory frameworks mandate fiscal metering integrity for production sharing contracts. Rio de Janeiro engineering clusters specialize in subsea measurement system integration.
Saudi Arabia
Aramco's Master Gas System expansion and Red Sea coastal terminal developments require high-capacity ultrasonic meter-integrated flow computers. Saudi Standards, Metrology and Quality Organization (SASO) enforces custody transfer accuracy requirements. Eastern Province industrial cities anchor downstream metering infrastructure deployment.
Germany
Ruhr Valley chemical complexes and Nord Stream transit metering stations demand SIL-rated flow computers for safety-critical applications. REACH compliance and EU Measurement Instrument Directive shape product certification requirements. Hamburg hosts specialized calibration facilities serving Central European pipeline networks.
Flow Computer Oil Gas Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: integrated automation platforms bundling flow measurement with distributed control systems, standalone flow computer specialists emphasizing modular architectures, and multivariable transmitter manufacturers consolidating discrete functions into unified devices. Dominant competitive moves include firmware subscription models replacing capital replacement cycles and third-party calibration service partnerships bypassing OEM after-sales channels.
Among diversified automation conglomerates, Emerson Electric Co., Honeywell International Inc., and ABB Ltd. represent the integrated platform tier, each anchoring distinct competitive positions through embedded edge-computing capabilities and SCADA-native architectures. These firms exemplify the shift toward software-defined measurement platforms that decouple hardware acquisition from algorithm licensing.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Thermo Fisher Scientific Inc. |
| Emerson Electric Co. |
| TechnipFMC plc |
| Krohne Messtechnik GmbH |
| Honeywell International Inc. |
| Yokogawa Electric Corporation |
| OMNI Flow Computers Inc. |
| ABB Ltd. |
| Others |
Supply & Pricing Matrix
Captive semiconductor fabrication for industrial-grade microprocessors anchors supply positioning for flow computer OEMs while concentrating pricing power among vendors with backward-integrated component sourcing. Emerson, Honeywell, and ABB leverage in-house analog-to-digital converter procurement to defend margin structures against tier-two competitors dependent on spot-market chip purchases.
Pricing Analysis
Capacity additions in South Korea and Taiwan are reshaping price floors for industrial microprocessors, compressing hardware margins for modular flow computer architectures. Three-tier pricing structure across premium smart units, standard SCADA-integrated models, and economy compact devices stratifies by edge-computing capability and API Chapter 21.1 certification tier. Cost compression in the economy tier is intensifying because semiconductor spot-market volatility feeds through to BOM costs. Upstream shale operators in the Permian Basin exhibit highest price sensitivity due to per-wellpad volume procurement, while FERC-regulated interstate pipeline operators accept premium positioning for custody transfer certainty.
Supply Chain Analysis
NIST-traceable calibration certification gates supply chain participation, restricting qualified vendors to those with accredited Houston, Calgary, or Rotterdam laboratory partnerships. Component sourcing draws from Taiwan for industrial microprocessors, Germany for precision pressure sensors, and Japan for solid-state storage modules. Single-source vulnerability concentrates in analog-to-digital converter supply from TSMC-affiliated foundries. Distribution runs through authorized automation distributors serving Gulf Coast petrochemical corridors and direct OEM contracts for supermajor pipeline operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
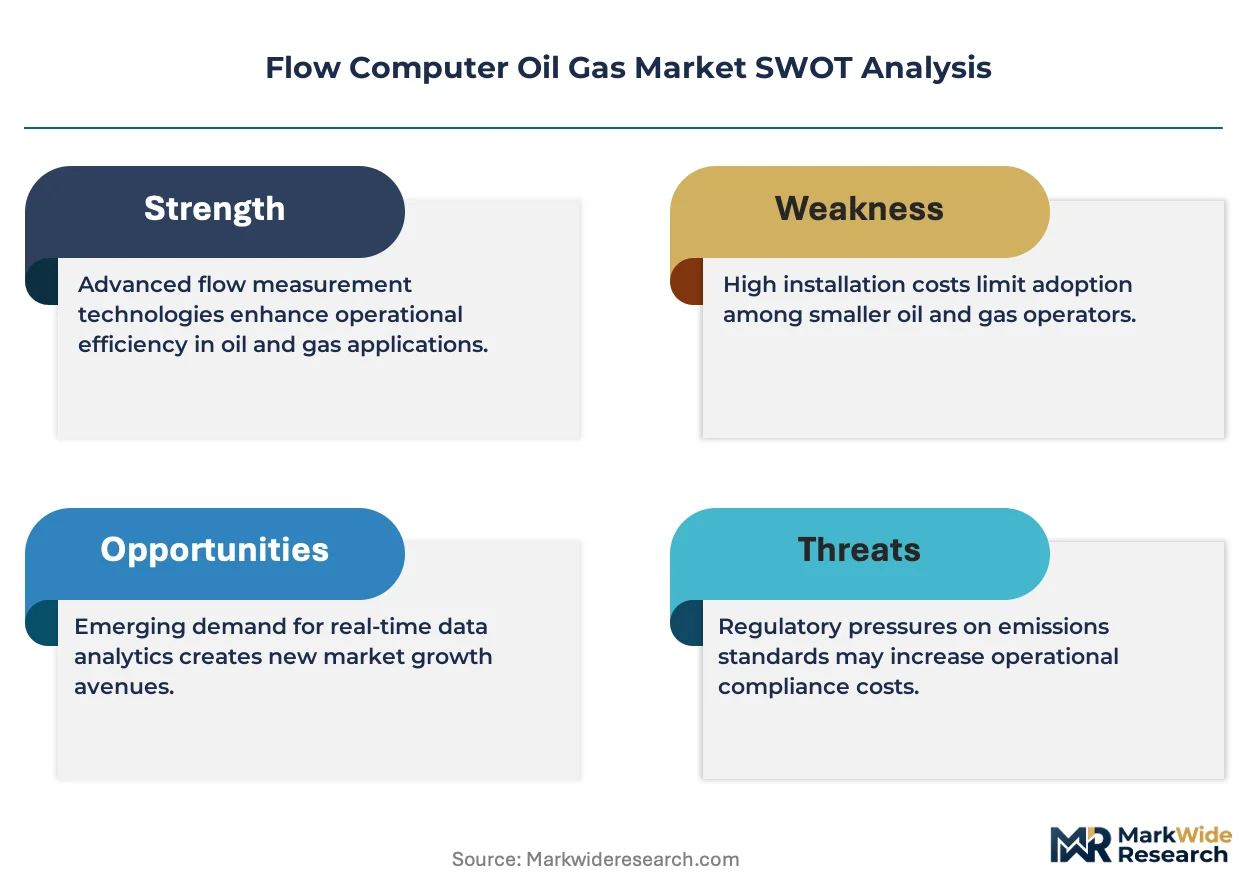
Flow computer procurement functions as a geographic-arbitrage play between North American shale automation intensity and Brazilian pre-salt subsea qualification requirements, with labor cost differentials in calibration engineering favoring Calgary-based service consolidation.
For Market Incumbents: Anchor defensive positioning through firmware subscription models that displace capital replacement cycles and capture recurring revenue from installed base. Consolidate third-party calibration partnerships to neutralize independent meter-proving labs eroding aftermarket attach rates. Deepen backward integration into industrial-grade semiconductor sourcing to buffer margin pressure from foundry capacity constraints. For New Entrants and Emerging Players: Independent shale producers operating Delaware Basin lease automatic custody transfer points represent the most penetrable buyer archetype due to fragmented procurement authority and price sensitivity. Target subsea-rated flow computer white space in Brazil's Santos Basin where ANP regulatory frameworks favor specialized engineering capabilities over integrated platform bundling. Pursue direct-to-operator sales models bypassing established automation distributor relationships. For Investors and Strategic Acquirers: Roll-up economics work for modular flow computer specialists because brownfield retrofit demand fragments procurement across hundreds of midstream operators lacking standardized vendor relationships. Target acquisition profiles emphasize firms with NIST-traceable calibration accreditation and API Chapter 21.1 algorithm libraries. Watch FERC Order 1920 enforcement intensity as inflection indicator for compliance-driven replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Subscription Migration | Transforms capital equipment vendors into recurring revenue platforms serving Permian Basin automation budgets. |
| Third-Party Calibration Partnership | Neutralizes independent meter-proving labs eroding Emerson and Honeywell aftermarket service attach rates. |
| Subsea Depth Rating Expansion | Captures Petrobras-led Santos Basin demand for 3,000-meter rated flow computers in pre-salt tiebacks. |
| Edge Computing Capability Integration | Reduces SCADA polling dependency and commands premium positioning against legacy polling-dependent architectures. |
| API Chapter 21.1 Algorithm Licensing | Decouples hardware acquisition from software revenue streams across software-defined measurement platforms. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with pipeline automation engineers, SCADA integration specialists, custody transfer metrologists, and midstream procurement directors with secondary validation against FERC tariff filings, API standards documentation, EPA greenhouse gas reporting databases, and semiconductor trade flow records. Bottom-up unit deployment estimates across Permian, Bakken, and DJ Basin gathering networks triangulated against top-down automation capital expenditure projections from midstream operator disclosures.
Historical reference periods anchored volume and value outputs to pre-pandemic baseline infrastructure investment cycles, with projection horizons extending through brownfield retrofit saturation and greenfield export terminal buildout phases. Segmentation dimensions modeled include architectural configuration, SCADA integration depth, custody transfer versus operational metering application, and upstream versus midstream end-user category. CAGRs derived from meter installation density curves and replacement cycle compression factors, with EPA methane monitoring mandates and FERC Order 1920 compliance deadlines serving as demand-pull inputs.
Inputs from NIST-traceable calibration laboratories and API standards committees were available through the study window; gaps in subsea flow computer performance data introduce uncertainty bands around Brazil pre-salt projections. Forecasts reflect documented assumptions regarding semiconductor supply normalization and shale production plateau timing. A model refresh is warranted upon material change in FERC interstate pipeline tariff enforcement or ANP subsea metering regulatory revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Subsea Well Intervention Market
Oil & Gas
United States Oil and Gas Midstream Market
Oil & Gas
Latin America Coiled Tubing Market
Oil & Gas
Chad Oil and Gas Market
Oil & Gas
Coiled Tubing System Market
Oil & Gas
India Artificial Lift Systems Market
Oil & Gas
3D Printing in Oil and Gas Market
Oil & Gas
Norway Oil and Gas Upstream Market
Oil & Gas
Intelligent Completion Sales Market
Oil & Gas
Oil and Gas Accumulators Market
Oil & Gas
China Oil and Gas Midstream Market
Oil & Gas
Middle-East Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Proppant Market
Oil & Gas
Central Asia Oil and Gas Market
Oil & Gas
Middle-East and Africa Liner Hanger System Market
Oil & Gas
Well Completion Equipment Service Market