
 Asia-Pacific Intelligent Pigging Market | 2026-2036
Asia-Pacific Intelligent Pigging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Intelligent Pigging Market Outlook
Software-defined analytics bundled with inspection contracts is broadening what pipeline operators purchase beyond hardware runs. Baker Hughes Company leverages its digital twin integration to anchor long-term service agreements across Australian offshore fields. Rosen Group sustains technology leadership through proprietary magnetic flux leakage sensor arrays calibrated for heavy crude lines. Dacon Inspection Technologies specializes in compact ultrasonic systems tailored for Southeast Asia's aging onshore distribution networks.
Intelligent pigging deploys self-propelled robotic devices through pressurized pipelines to detect metal loss, cracks, and geometric deformations using non-destructive testing technologies, with magnetic flux leakage sensors achieving detection thresholds below 5 percent wall thickness loss and ultrasonic tools providing direct wall measurement accuracy within 0.1 millimeters. Its primary purpose remains preventing catastrophic failure in hydrocarbon and water transport infrastructure while extending operational life beyond original design specifications. Ultrasonic technology commands premium positioning for subsea deployments where direct measurement replaces inferred corrosion rates, while magnetic inspection dominates onshore crude trunk lines across India and China where cost-per-kilometer drives procurement decisions. The oil and gas end-user segment absorbs the majority of capital allocation, though water utilities in Australia and Japan represent an emerging margin pool as desalination and recycled water networks expand.
China's SAMR enforces GB standards for pressure pipeline integrity that mandate periodic intelligent inspection of Class I and II hydrocarbon lines, while Australia's National Offshore Petroleum Safety and Environmental Management Authority requires submission of verified inspection data for facility safety cases. India's Petroleum and Natural Gas Regulatory Board ties city gas distribution licenses to demonstrated pipeline integrity programs including inline inspection schedules. Stakeholders must weigh technology refresh cycles against regulatory compliance deadlines as subsea deployment complexity outpaces standard magnetic tool capabilities.
Market Dynamics
Pipeline integrity mandates across Australia, China, and India are compressing inspection intervals while subsea deployment complexity forces technology refresh cycles that outpace standard magnetic tool capabilities.
Growth Catalysts
- Offshore Gas Corridor Expansion:Southeast Asian operators are extending maintenance contracts for ultrasonic inspection tools across subsea export networks. Deepwater field development in Australia's North West Shelf drives recurring tool deployment.
- China's GB Standards Enforcement:SAMR-mandated periodic intelligent inspection of Class I and II hydrocarbon lines creates compliance-driven procurement cycles. Pipeline operators must submit verified data or face operational suspension.
- India's City Gas Distribution Push:PNGRB licensing requirements tie new distribution authorizations to demonstrated inline inspection programs. Rural network buildouts generate first-time demand for compact magnetic flux leakage systems.
Market Restraints
- Subsea Tool Cost Concentration:Ultrasonic inspection hardware for deepwater pipelines requires specialized sensor arrays and pressure-rated housings. Equipment procurement concentrates among a limited supplier base with proprietary calibration protocols.
- Specialized Technician Scarcity:Interpretation of magnetic flux leakage data demands certified analysts trained on heavy crude line signatures. Training pipelines in Australia and Southeast Asia lag field deployment needs.
- Heavy Crude Measurement Limitations:Viscous crude residues interfere with ultrasonic signal propagation in India's trunk line networks. Operators must deploy hybrid tool configurations that increase per-kilometer inspection costs.
Strategic Opportunities
- Japanese Water Utility Modernization:Desalination and recycled water network expansion creates demand for geometric deformation detection in stainless steel distribution lines. Tokyo Metropolitan Government infrastructure budgets prioritize non-disruptive assessment methods.
- Digital Twin Convergence:Integration of inline inspection data with predictive analytics platforms enables condition-based maintenance scheduling. Australian offshore operators pilot real-time corrosion rate modeling linked to robotic pig outputs.
- Southeast Asian Aging Infrastructure:Vietnam and Indonesia's onshore distribution networks built during the 1980s-1990s require first-time baseline assessment. Compact tool formats suit narrow-diameter lines prevalent in these systems.
Industry Challenges
- Multi-Standard Certification Complexity:Tools deployed across Australian, Chinese, and Indian jurisdictions must satisfy divergent pressure equipment directives. Manufacturers maintain separate calibration procedures for SAMR, NOPSEMA, and PNGRB compliance.
- Legacy Pipeline Geometry Constraints:India's cross-country crude networks contain tight-radius bends and valve configurations designed before intelligent pigging standards. Tool passage requires pre-inspection modification or specialized bi-directional designs.
- Data Interpretation Bottlenecks:Inspection runs generate terabyte-scale datasets requiring analyst review within regulatory submission windows. Australian and Chinese operators report backlogs in defect classification and reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Intelligent Pigging Market |
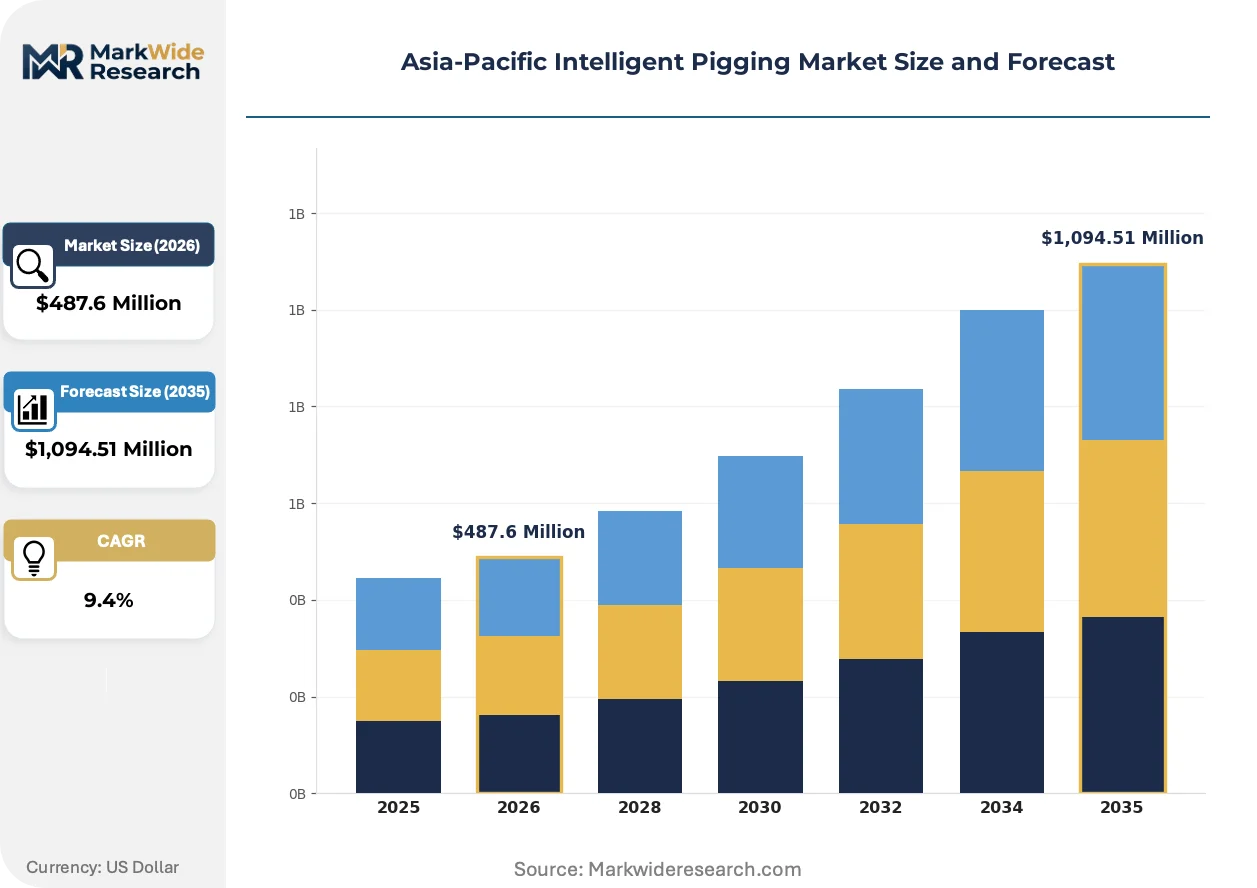
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,094.51 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ultrasonic, Magnetic, Electromagnetic, Laser End User: Oil & Gas, Water Utilities, Chemical, Mining Application: Pipeline Inspection, Corrosion Detection, Leak Detection, Data Collection Deployment: Onshore, Offshore, Subsea, Hybrid |
| Companies Covered | Rosen Group, NDT Global Services Ltd, SGS SA, Baker Hughes Company, Penspen Limited, Dtaic Inspection Equipment (Suzhou) Co Ltd, Dacon Inspection Technologies, NDTS India (P) Limited, Panorama Oil & Gas Sdn Bhd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Intelligent Pigging Market Strategic Shifts
Sensor fusion architectures and software-defined analytics are redefining what constitutes a complete inspection solution, shifting procurement emphasis from hardware runs toward integrated data service platforms.
Electromagnetic acoustic transducer (EMAT) technology is electrifying corrosion detection capabilities in liquid-carrying pipelines without requiring direct surface contact or couplant fluids. Australian subsea operators are adopting EMAT-based tools for gas-condensate lines where conventional ultrasonic methods face signal attenuation challenges. The technology is compressing deployment preparation time and expanding inspection windows in offshore production schedules.
Australia's NOPSEMA has tightened submission requirements for facility safety cases, mandating verified inline inspection data as primary evidence of structural integrity. Pipeline operators must now demonstrate traceable measurement uncertainty budgets and analyst certification records. Subsea export corridors in the North West Shelf and Bass Strait face the most intensive documentation scrutiny, with operators investing in third-party validation partnerships.
Service contract unbundling is fragmenting traditional inspection procurement models across Southeast Asian markets. National oil companies increasingly separate tool provision from data interpretation, awarding analytics segments to specialized software vendors. This pattern is most visible in Thailand and Malaysia, where state operators maintain captive inspection fleets but outsource defect assessment to independent engineering consultancies.
Asia-Pacific Intelligent Pigging Market Segmentation
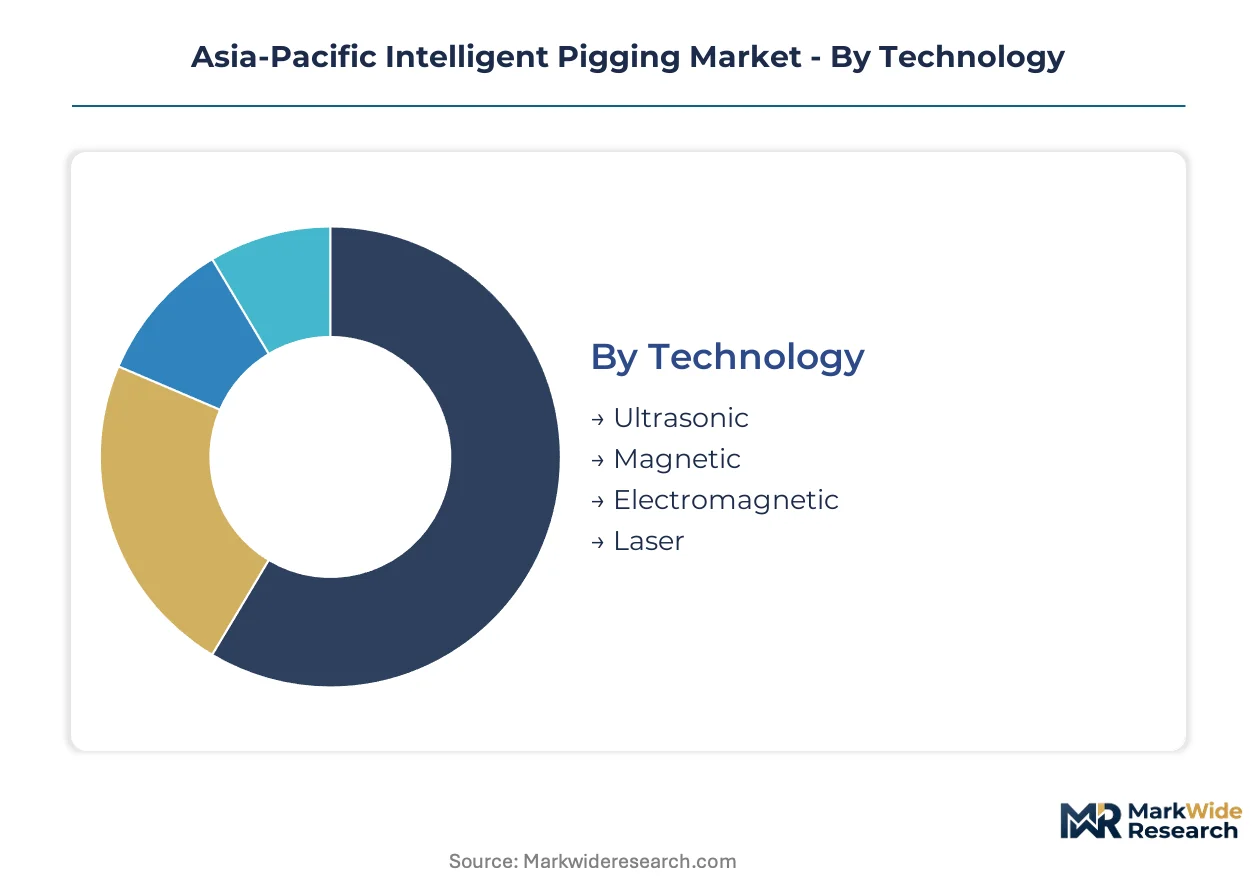
Intelligent pigging procurement across the Asia-Pacific region fragments along technology capability tiers and deployment complexity levels. Operators in Australia, China, and India select inspection configurations based on pipeline age, fluid characteristics, and regulatory submission requirements.
Technology:
Standardization dominates magnetic flux leakage platforms while ultrasonic systems demand extensive customization for pressure ratings and sensor array density.
- Ultrasonic:Direct wall thickness measurement achieves 0.1 millimeter accuracy through pulse-echo or time-of-flight sensor configurations. Australian North West Shelf subsea export corridors specify ultrasonic tools for gas-condensate lines where inferred corrosion rates prove insufficient for NOPSEMA safety case submissions.
- Magnetic:Flux leakage sensors detect metal loss below 5 percent wall thickness through magnetization of the pipe wall. India's cross-country crude trunk lines and China's National Pipeline Network Group onshore corridors prioritize magnetic inspection for cost-per-kilometer efficiency across extended distances.
- Electromagnetic:EMAT technology eliminates couplant fluid requirements for liquid-carrying pipelines. Australian operators deploy EMAT-based tools where conventional ultrasonic methods face signal attenuation.
- Laser:Geometric deformation mapping through structured light projection suits small-diameter distribution networks. Japanese water utilities pilot laser-based internal geometry assessment for stainless steel desalination lines.
Leading the category by volume: Magnetic. Growing fastest: Ultrasonic.
End User:
Capital allocation intensity separates hydrocarbon transport from utility infrastructure, with oil and gas commanding multi-year service contracts against water utility spot procurement.
- Oil & Gas:Hydrocarbon pipeline operators mandate continuous integrity verification for Class I and II pressure lines under China's SAMR GB standards. Australia's offshore production facilities and India's PNGRB-licensed city gas distribution networks anchor recurring inspection spend.
- Water Utilities:Desalination and recycled water network expansion in Australia and Japan creates demand for non-destructive assessment in stainless steel distribution systems. Tokyo Metropolitan Government infrastructure budgets prioritize geometric deformation detection without service disruption.
- Chemical:Process pipeline integrity programs in Southeast Asian petrochemical clusters require specialized tool materials compatibility. Singapore and Thailand industrial zones specify corrosion-resistant sensor housings for acid service lines.
- Mining:Slurry transport pipelines in Western Australia and Papua New Guinea face extreme abrasion monitoring requirements. Slurry density variations complicate standard magnetic tool calibration protocols.
Highest contract value concentration: Oil & Gas. Steepest expansion trajectory: Water Utilities.
Application:
Regulatory scope determines whether operators purchase baseline assessment or continuous monitoring configurations.
- Pipeline Inspection:Comprehensive metal loss, crack, and deformation assessment constitutes the core service offering. China's SAMR mandates periodic intelligent inspection with verified data submission for operational continuation.
- Corrosion Detection:Internal and external corrosion mapping drives technology selection between magnetic inference and ultrasonic direct measurement. Subsea deployments in Australia's Bass Strait favor ultrasonic for accurate corrosion rate modeling.
- Leak Detection:Acoustic and pressure differential methods identify incipient failures before rupture. India's rural city gas distribution buildouts prioritize leak detection for public safety compliance.
- Data Collection:High-resolution sensor outputs feed digital twin platforms for predictive maintenance scheduling. Australian offshore operators pilot real-time corrosion rate modeling linked to robotic pig outputs.
Widest regulatory mandate coverage: Pipeline Inspection. Gaining share fastest: Data Collection.
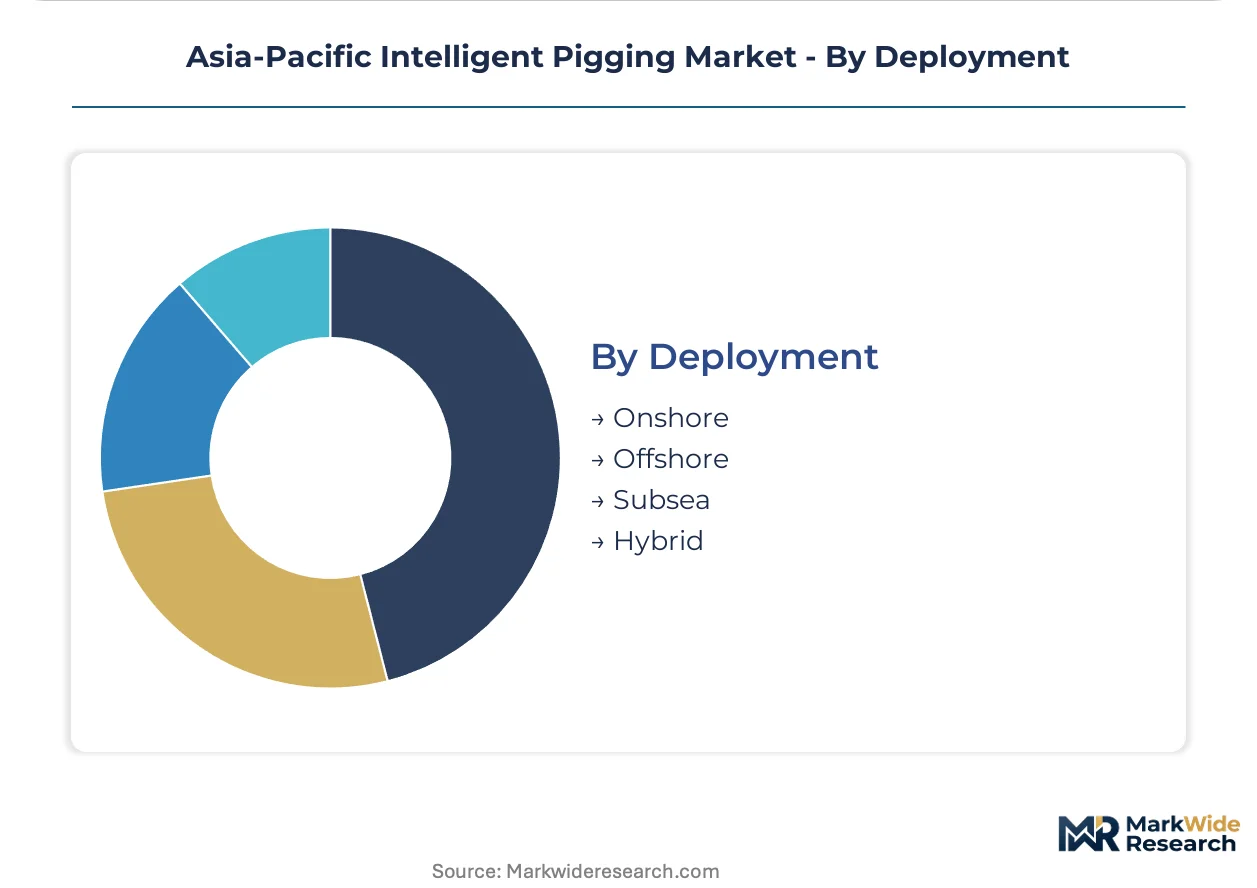
Deployment:
Pressure rating and accessibility constraints fragment procurement between standardized onshore fleets and engineered subsea systems.
- Onshore:Standard magnetic flux leakage tools traverse extended crude and gas transmission corridors. India's cross-country networks and China's trunk lines deploy conventional pig configurations with established passage protocols.
- Offshore:Platform-based inspection requires pressure-rated launchers and specialized handling equipment. Australia's North West Shelf production facilities maintain captive inspection fleets for scheduled maintenance windows.
- Subsea:Deepwater export pipelines demand ultrasonic tools with pressure-compensated sensor arrays and autonomous navigation capabilities. Equipment procurement concentrates among suppliers with proprietary calibration protocols for deepwater service.
- Hybrid:Bi-directional tool designs accommodate tight-radius bends and valve configurations in legacy pipeline networks. India's pre-1990 crude lines require passage modification or specialized tool geometry.
Dominant deployment mode by kilometer inspected: Onshore. Climbing the fastest: Subsea.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North West Shelf offshore production corridor anchors Asia-Pacific intelligent pigging deployment, with subsea export pipelines from Karratha and Dampier driving recurring ultrasonic tool demand for gas-condensate integrity verification.
Australia
Western Australia's offshore production facilities and Bass Strait subsea networks dominate regional inspection spend. NOPSEMA mandates verified inline inspection data for facility safety case submissions, compressing deployment windows. Queensland's coal seam gas gathering systems and South Australia's emerging hydrogen pipeline trials generate demand for compact magnetic flux leakage configurations.
China
The National Pipeline Network Group's trunk line expansion across Xinjiang-to-coast corridors consumes magnetic inspection capacity at scale. SAMR-enforced GB standards for Class I and II hydrocarbon lines mandate periodic intelligent inspection with operational suspension risks for non-compliance. Sichuan-Chongqing shale gas gathering networks and Bohai Bay offshore clusters drive technology refresh cycles.
India
Cross-country crude networks from Gujarat to Paradip and emerging city gas distribution buildouts in Uttar Pradesh and Bihar generate bifurcated demand. PNGRB licensing ties distribution authorizations to demonstrated inline inspection programs. Mumbai-Pune industrial corridors and Hazira-Vijaipur-Jagdishpur trunk lines face legacy geometry constraints requiring specialized bi-directional tool designs.
Japan
Tokyo Metropolitan Government infrastructure budgets prioritize geometric deformation detection for stainless steel desalination and recycled water distribution networks. METI-aligned water utilities pilot laser-based internal geometry assessment without service disruption. Osaka-Kobe industrial zones and Kyushu LNG import terminals concentrate procurement for non-destructive pipeline assessment.
Vietnam
Onshore distribution networks built during the 1980s-1990s in the Nam Con Son basin and Red River delta require first-time baseline assessment. Compact tool formats suit narrow-diameter lines prevalent in these aging systems. Hai Phong port industrial zones and Ho Chi Minh City periphery gas distribution generate emerging demand for ultrasonic inspection services.
Asia-Pacific Intelligent Pigging Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the Asia-Pacific intelligent pigging market. Equipment manufacturers with captive fabrication facilities and pressure-rated testing infrastructure dominate subsea ultrasonic system supply, while specialized analytics vendors capture recurring data interpretation revenue without asset ownership. Three archetypes define competitive positioning: integrated oilfield service conglomerates bundling digital twin integration, pure-play inspection technology specialists with proprietary sensor calibration protocols, and regional fabrication houses serving narrow-diameter onshore distribution networks. Consolidation pressure concentrates around technology licensing partnerships and captive fleet expansion for scheduled maintenance windows.
Within the integrated service tier, Baker Hughes Company and Rosen Group exemplify capital-intensive positioning through digital twin integration and proprietary magnetic flux leakage sensor arrays respectively. Dacon Inspection Technologies represents the regional specialist archetype, occupying a fabrication-focused position calibrated for Southeast Asia's aging onshore infrastructure. These three entities anchor the competitive spectrum from subsea premium systems to compact distribution network formats.
| Leading Market Players |
|---|
| Rosen Group |
| NDT Global Services Ltd |
| SGS SA |
| Baker Hughes Company |
| Penspen Limited |
| Dtaic Inspection Equipment (Suzhou) Co Ltd |
| Dacon Inspection Technologies |
| NDTS India (P) Limited |
| Panorama Oil & Gas Sdn Bhd |
| Others |
Value Chain & Pricing Dynamics
Certified EMAT sensor technicians concentrated in Western Australia and Singapore drive labor-cost differentials that widen spreads between premium ultrasonic service tiers and economy-grade magnetic inspection contracts across the Asia-Pacific basin.
Pricing Analysis
Outcome-based pricing anchored to pipeline uptime guarantees dominates subsea service contracts, with Australian North West Shelf operators paying premiums tied to verified defect detection thresholds. Three-tier pricing structure across premium, standard, and economy levels separates NOPSEMA-certified ultrasonic deployments from routine magnetic flux leakage runs and spot-hire legacy tool configurations. Pricing pressure stems from India's PNGRB-mandated inspection schedules compressing procurement timelines for rural city gas distribution networks. National oil companies exhibit lowest price sensitivity for subsea digital-twin-integrated contracts, while Southeast Asian distribution utilities drive hardest bargaining on per-kilometer magnetic tool rates.
Supply Chain Analysis
China's GB standard compliance requirements and India's phased manufacturing program are reshaping sourcing patterns for pressure-rated sensor housings and magnetization circuits. Component fabrication concentrates in China, South Korea, and Japan, with Australian final assembly facilities handling subsea system integration. Supply chains draw from rare-earth magnet suppliers in Inner Mongolia, piezoelectric crystal foundries in Osaka-Kobe industrial zones, and composite pressure vessel manufacturers in Busan. Single-source vulnerability sits with proprietary EMAT calibration protocols held by a limited supplier base. Distribution runs through oilfield service conglomerates' captive fleets for scheduled maintenance windows, supplemented by independent tool hire networks for spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subsea ultrasonic tool deployment capacity constraints in Australia's North West Shelf prop pricing premiums, with qualified vessel availability and certified analyst pipelines operating at effective saturation.
For Market Incumbents: Deploy digital twin integration as the anchor lever for multi-year service contract renewals across Australian offshore fields. Consolidate position through captive fabrication capacity expansion in Western Australia to reduce vessel mobilization lead times. Counter emerging pure-play analytics vendors by bundling real-time corrosion rate modeling with hardware runs under unified outcome guarantees. For New Entrants and Emerging Players: Laser-based geometric deformation detection for Japanese stainless steel water distribution networks offers a technology-first wedge with limited incumbent penetration. Target Tokyo Metropolitan Government infrastructure budgets and Australian hydrogen pipeline trial operators seeking non-disruptive assessment methods. Enter through equipment-as-a-service models that eliminate upfront capital barriers for municipal utility procurement committees. For Investors and Strategic Acquirers: Re-rating potential sits with regional fabrication houses possessing SAMR and NOPSEMA dual certification given China's trunk line expansion and Australia's subsea replacement cycles. Acquisition focus should center on Southeast Asian specialists with narrow-diameter tool portfolios serving Vietnam and Indonesia's aging 1980s-era distribution networks. Watch PNGRB licensing volume as the inflection signal for India's inspection service demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| EMAT Technology Licensing | Australian subsea operators bypass couplant fluid dependencies in gas-condensate lines. |
| Digital Twin Platform Integration | Baker Hughes anchors long-term agreements through predictive analytics bundling. |
| Regional Fabrication Expansion | Dacon Inspection Technologies targets Southeast Asia's aging narrow-diameter networks. |
| Dual Certification Investment | Manufacturers satisfy divergent SAMR, NOPSEMA, and PNGRB compliance requirements. |
| Service Contract Unbundling | Thai and Malaysian state operators separate tool provision from analytics outsourcing. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with pipeline integrity managers, subsea operations directors, and inspection tool procurement leads across Australian, Chinese, and Indian operators. Bottom-up triangulation combined equipment fleet deployment tracking with top-down validation against National Pipeline Network Group capital expenditure disclosures and PNGRB licensing registers. Secondary sources included SAMR GB standard enforcement notices, NOPSEMA safety case submission databases, and Asia-Pacific oilfield service contractor procurement records.
Reconciliation of inspection run frequency data, regulatory compliance deadline schedules, and technology refresh cycle timelines informed the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed technology tier, deployment complexity, end-user capital allocation intensity, and regional regulatory cluster. CAGRs were derived from pipeline kilometer expansion forecasts cross-referenced with mandated inspection interval compression rates. Industry-specific inputs incorporated subsea field development timelines and city gas distribution buildout trajectories.
Several conditions sit outside the modeled scope, including unannounced regulatory interval changes, breakthrough sensor technology disruptions, and geopolitical trade restrictions affecting component sourcing. Forecasts reflect documented assumptions regarding inspection technology capability maturation and analyst certification pipeline expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Desalter Market
Oil & Gas
Oil Breather Tank Market
Oil & Gas
Hydraulic Workover Units Market
Oil & Gas
Europe Oil and Gas Drones Market
Oil & Gas
Middle East Wireline Logging Services Market
Oil & Gas
Coal Mining Market
Oil & Gas
Well Cementing Market
Oil & Gas
Middle-East Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Clear Brine Fluids Market
Oil & Gas
Casing Centralizer Market
Oil & Gas
Brazil Oil and Gas Market
Oil & Gas
Europe Wireline Logging Services Market
Oil & Gas
United Arab Emirates Oil and Gas Downstream Market
Oil & Gas
Central Asia Oil and Gas Market
Oil & Gas
Containment and Handling Drilling Waste Management Market
Oil & Gas
Oil and Gas Infrastructure Market