
 Drilling Fluids Market | 2026-2036
Drilling Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Drilling Fluids Market Analysis
Fluid management as a subscription service is decoupling capital equipment sales from recurring revenue streams in the drilling fluids sector. Schlumberger Limited leverages its integrated drilling services platform to bundle chemical supply with real-time performance monitoring. Baker Hughes Company anchors its position through backward integration into base fluid manufacturing and additive formulation.
Drilling fluids are engineered liquid and gaseous mixtures—typically comprising base fluids, weighting agents, viscosifiers, and chemical additives—designed to cool drill bits, transport cuttings, and maintain hydrostatic pressure during borehole excavation. Water-based formulations dominate total volume owing to lower cost and simpler disposal protocols, while synthetic-based systems command premium positioning in deepwater and high-temperature applications where thermal stability and environmental compliance requirements intensify. Additive demand concentrates in viscosity modifiers and corrosion inhibitors as operators push into harsher downhole conditions.
The US EPA regulates drilling waste discharge under the Clean Water Act, while BSEE mandates well control and fluid integrity standards for offshore operations. OSHA enforces worker exposure limits to petroleum distillates and chemical additives at onshore mixing facilities. Stakeholders must weigh synthetic fluid substitution economics against evolving regulatory thresholds for toxicity and biodegradability.
Market Dynamics
Synthetic-based fluid substitution economics are compressing water-based system margins while offshore operators absorb BSEE discharge compliance costs into operating budgets. Base fluid producers face backward integration pressure from integrated service companies seeking supply security.
Growth Catalysts
- Permian Basin shale corridor expansion:Horizontal drilling intensity in West Texas and New Mexico is pulling high-performance fluid volumes as laterals extend past 15,000 feet.
- OSHA worker exposure mandates:Stricter petroleum distillate handling protocols at onshore mixing facilities are accelerating closed-loop system adoption.
- High-temperature stability requirements:Deepwater Gulf of Mexico wells exceeding 400°F bottom-hole temperatures are forcing synthetic formulation upgrades.
Market Restraints
- Barite supply concentration:Chinese export controls on weighting agent raw materials are creating input cost volatility for mud weight maintenance.
- EPA toxicity testing timelines:Extended biodegradability certification cycles for new synthetic base fluids are delaying product launches by 18-24 months.
- Water-based system substitution limits:Thermal degradation above 350°F prevents water-based fluids from penetrating high-temperature offshore segments.
Strategic Opportunities
- Brazil pre-salt development:ANVISA environmental licensing for deepwater blocks is creating demand for low-toxicity synthetic systems in the Santos Basin.
- Real-time viscosity monitoring:Integration of downhole sensors with automated additive injection is enabling predictive fluid optimization.
- Used fluid reclamation services:Third-party reconditioning infrastructure in the US Gulf Coast is opening recurring revenue streams independent of new drilling activity.
Industry Challenges
- Drilling fluid engineer scarcity:Specialized expertise in rheology modeling and formation damage prevention is concentrating at integrated service firms.
- Legacy mud plant retrofit costs:Automated batching and closed-loop mixing systems require capital deployment that independent blenders struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drilling Fluids Market |
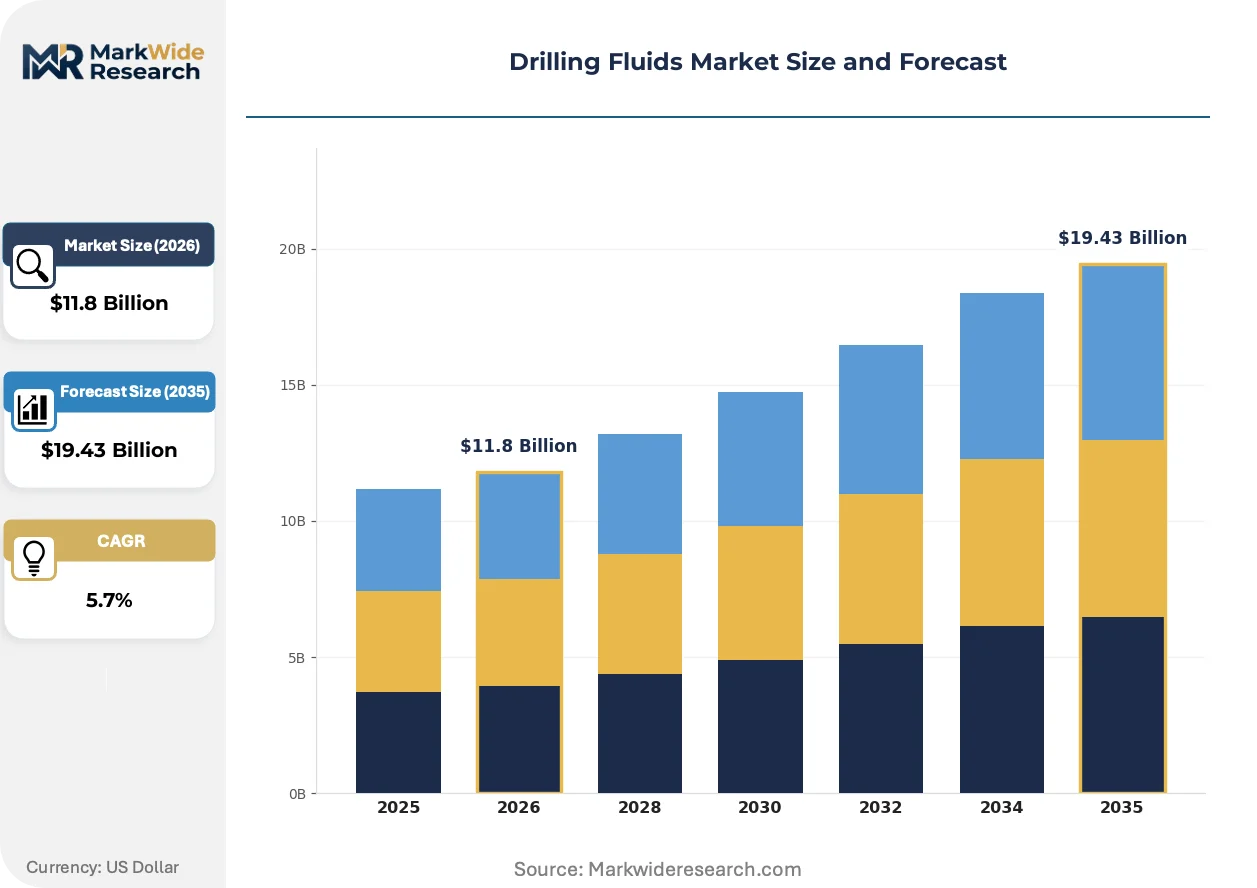
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $19.43 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Oil-Based, Synthetic-Based, Foam-Based Additive Type: Viscosity Modifiers, Friction Reducers, pH Control Agents, Corrosion Inhibitors End User: Onshore Drilling, Offshore Drilling, Mining, Geothermal Application: Exploratory Drilling, Development Drilling, Well Completion, Workover |
| Companies Covered | Newpark Resources Inc., CES Energy Solutions Corp, Schlumberger Limited, Q'Max Solutions Inc., Tetra Technologies Inc., Halliburton Company, Weatherford International plc, China Oilfield Services Limited, Baker Hughes Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drilling Fluids Market Emerging Trajectories
Digital fluid monitoring architectures are collapsing the information lag between downhole conditions and surface treatment decisions. Real-time data streams are redefining how operators optimize viscosity and weighting agent consumption.
Microemulsion base fluids are decentralizing additive logistics for remote drilling sites. These systems allow on-site dilution of concentrated surfactant packages rather than transporting pre-blended volumes across long supply chains. Exploration teams in the Permian Basin and North Dakota Bakken are adopting portable mixing skids that reduce trucking intensity by 60 percent.
EPA effluent limitation guidelines under the Clean Water Act are tightening discharge parameters for synthetic-based drilling waste. Operators must now demonstrate that retained cuttings meet toxicity characteristic leaching procedure thresholds before ocean disposal. Deepwater Gulf of Mexico drillships are responding by installing enhanced solids-control equipment and expanding onshore waste processing partnerships.
Integrated service bundling is compressing standalone chemical procurement cycles. Exploration and production companies are consolidating fluid supply contracts with directional drilling and logging services under single-vendor frameworks. This pattern is most pronounced among Permian Basin independents seeking simplified vendor management and unified performance accountability.
Drilling Fluids Market Segmentation
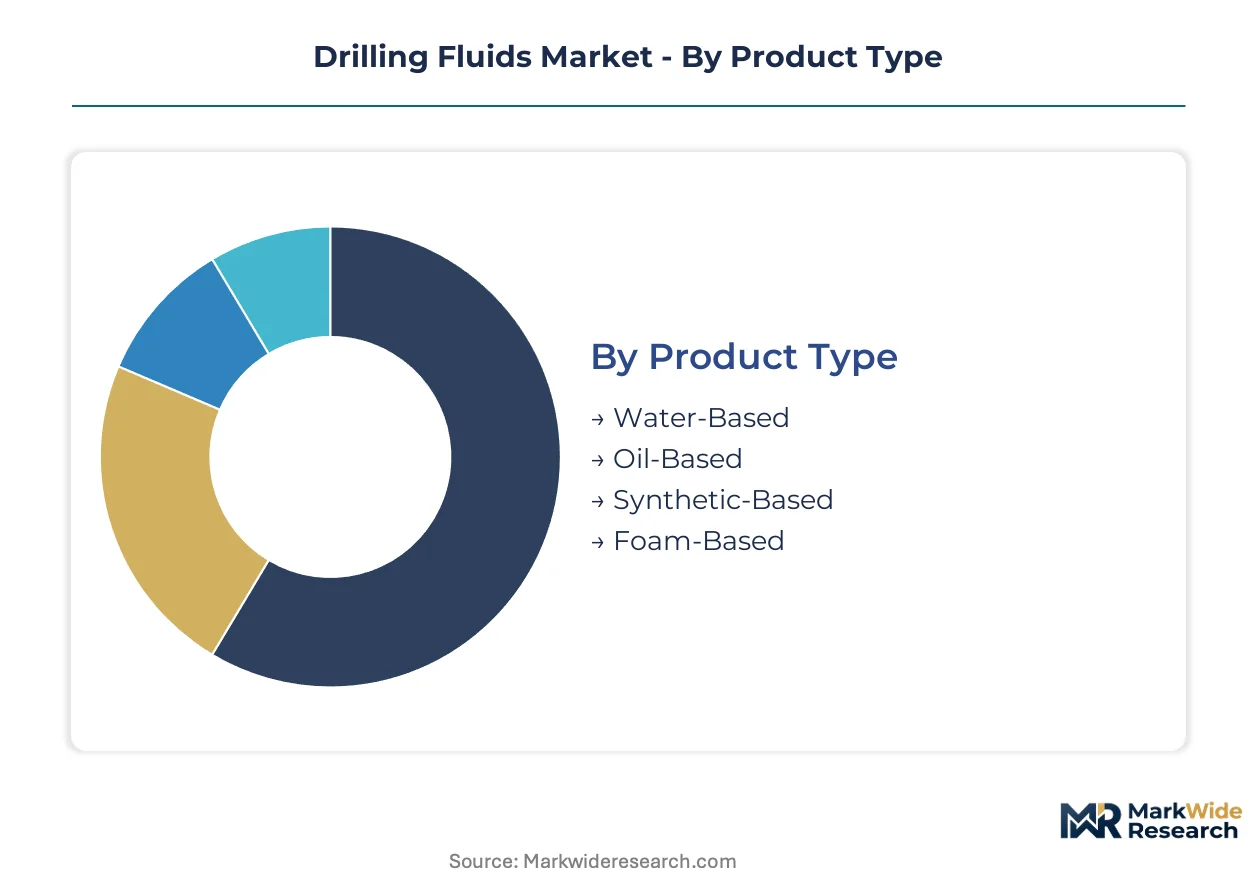
Drilling fluid selection hinges on downhole temperature, formation pressure, and disposal economics. Segmentation reveals where synthetic formulations command premium positioning against water-based commodity volumes, and which additive categories absorb disproportionate R&D investment.
Product Type:
Water-based systems dominate standalone procurement cycles, while synthetic formulations embed into integrated service contracts with real-time performance guarantees.
- Water-Based:Comprising bentonite clay, polymers, and freshwater or brine carriers, these formulations handle 70-80% of global drilling footage. Demand clusters in Permian Basin shale corridors where disposal costs and regulatory simplicity outweigh thermal limitations. EPA discharge permits favor these systems for onshore horizontal wells.
- Synthetic-Based:Engineered ester and olefin base fluids deliver thermal stability above 400°F with lower toxicity than traditional oil-based mud. Offshore Gulf of Mexico drillships specify these systems for deepwater exploration where BSEE mandates biodegradability certification. Premium pricing reflects backward integration into base fluid manufacturing.
- Oil-Based:Diesel and mineral oil carriers persist in high-temperature drilling where synthetic substitution economics remain unfavorable. These systems face tightening EPA toxicity testing timelines.
- Foam-Based:Compressed air and surfactant mixtures enable underbalanced drilling in depleted reservoirs. Applications concentrate in mature North American gas fields.
Volume placements concentrate in Water-Based; the faster expansion belongs to Synthetic-Based.
Additive Type:
Cost tier differentiation separates commodity pH buffers from specialty corrosion chemistry requiring formulation expertise.
- Viscosity Modifiers:Xanthan gum, guar derivatives, and synthetic polymers control rheology across shear rate ranges. Horizontal laterals exceeding 15,000 feet in West Texas pull disproportionate volumes as annular pressure management grows critical.
- Corrosion Inhibitors:Amine-based and film-forming compounds protect drillstring metallurgy in sour gas environments. Deepwater Gulf of Mexico high-pressure high-temperature wells mandate these additives under BSEE well integrity standards.
- Friction Reducers:Polyacrylamide chemistry minimizes torque and drag in extended-reach drilling. Mining applications in Chilean copper operations adopt these for raise boring efficiency.
- pH Control Agents:Caustic soda, lime, and bicarbonate systems maintain alkalinity for clay stabilization. These commodity additives face margin compression from Chinese chemical exporters.
Procurement volume tilts toward Viscosity Modifiers; Corrosion Inhibitors capture the steepest expansion trajectory as sour service drilling intensifies.
End User:
Application maturity separates established onshore workflows from emerging geothermal segments requiring fluid innovation.
- Onshore Drilling:Horizontal shale development in the Permian Basin and North Dakota Bakken consumes high-performance water-based systems with friction reducer packages. OSHA worker exposure mandates accelerate closed-loop mixing plant upgrades.
- Offshore Drilling:Deepwater Gulf of Mexico drillships and Brazil pre-salt operations specify synthetic-based fluids with real-time viscosity monitoring. ANVISA environmental licensing in the Santos Basin favors low-toxicity formulations.
- Mining:Raise boring and exploration coring in Australian iron ore and Chilean copper deposits use modified drilling fluid chemistry for ground stabilization.
- Geothermal:High-temperature geothermal wells exceeding 500°F bottom-hole conditions test fluid thermal stability limits. Iceland and Kenya development projects drive specialty formulation demand.
Revenue concentration sits with Onshore Drilling; Geothermal presents the most rapid demand acceleration.
Application:
Customer type stratification distinguishes capital-intensive exploratory campaigns from recurring workover services.
- Development Drilling:Infill horizontal wells in established shale fields require consistent fluid performance across hundreds of identical laterals. Permian Basin independents favor subscription-based fluid management to decouple chemical costs from drilling intensity.
- Exploratory Drilling:Wildcat and appraisal wells in frontier basins demand adaptive fluid systems responding to unknown formation pressures. Brazil pre-salt and Guyana-Suriname blocks pull premium synthetic volumes.
- Well Completion:Displacement fluids and packer fluids bridge drilling and production phases. Completion fluid cleanliness standards exceed drilling specifications.
- Workover:Remedial drilling and well intervention services utilize simplified fluid systems for short-duration operations. Third-party reclamation services reduce new chemical procurement.
Development Drilling anchors current volume; Exploratory Drilling shows the fastest share gain as frontier basin leasing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of synthetic base fluids concentrates along the US Gulf Coast, while consumption patterns follow drilling permit issuance in shale corridors and deepwater lease blocks. This geographic split creates supply chain tension as logistics costs compound formulation premiums.
United States
Horizontal drilling intensity in the Permian Basin and West Texas shale corridors pulls high-performance water-based systems as laterals extend past 15,000 feet. The US EPA enforces discharge standards under the Clean Water Act that favor closed-loop mixing systems at onshore facilities. Houston anchors Gulf Coast supply infrastructure where backward integration into base fluid manufacturing is concentrating.
Brazil
Pre-salt development in the Santos Basin is generating demand for low-toxicity synthetic drilling fluids as operators target deepwater carbonate reservoirs. ANVISA environmental licensing mandates biodegradability certification for offshore discharge scenarios. Macaé serves as the primary logistics hub where service companies are expanding fluid storage and reconditioning capacity.
China
Domestic shale development in Sichuan Basin and tight gas operations in Ordos Basin are absorbing water-based fluid volumes despite thermal limitations. The Ministry of Ecology and Environment (MEE) is tightening standards for drilling waste disposal at onshore mixing facilities. Tianjin's chemical manufacturing corridor supplies weighting agents and viscosifiers to regional operators.
Norway
North Sea high-pressure high-temperature wells are forcing synthetic formulation upgrades as bottom-hole conditions exceed 400°F. The Norwegian Environment Agency enforces strict biodegradability thresholds for offshore cuttings discharge that exceed EU baseline requirements. Stavanger clusters integrated service providers offering real-time viscosity monitoring for subsea completions.
Saudi Arabia
Unconventional gas drilling in the Jafurah Basin is testing fluid thermal stability limits in high-temperature carbonate formations. The country's national oil company mandates closed-loop solids control systems to minimize desert disposal footprints. Dhahran's technology centers are piloting microemulsion base fluids for remote site logistics reduction.
Drilling Fluids Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the drilling fluids sector. Integrated oilfield service conglomerates with captive chemical manufacturing anchor the premium tier, while independent blenders and regional specialists occupy commodity segments. Three archetypes dominate: backward-integrated majors controlling base fluid supply chains, technology-focused specialists in high-temperature formulations, and logistics-optimized regional distributors. Competitive intensity centers on M&A consolidation of independent blenders and strategic partnerships between additive suppliers and automated mixing system vendors.
Within the integrated service tier, Schlumberger Limited and Baker Hughes Company exemplify backward integration strategies that decouple chemical supply from drilling performance risk. Halliburton Company occupies a position bridging integrated bundling with standalone fluid procurement. Among Asia-Pacific operators, China Oilfield Services Limited represents state-affiliated vertical integration into offshore drilling support services.
| Leading Market Players |
|---|
| Newpark Resources Inc. |
| CES Energy Solutions Corp |
| Schlumberger Limited |
| Q'Max Solutions Inc. |
| Tetra Technologies Inc. |
| Halliburton Company |
| Weatherford International plc |
| China Oilfield Services Limited |
| Baker Hughes Company |
| Others |
Supply Flow & Price Mechanics
Microemulsion base fluid adoption is collapsing transportation costs for remote drilling sites while simultaneously shifting additive procurement from centralized blending plants to portable on-site mixing systems. This production-method transition concentrates formulation value in concentrated surfactant packages rather than finished fluid volumes, reshaping both cost economics and supplier power across the value chain.
Pricing Analysis
Margin tightening in water-based fluid tiers reflects Chinese export controls on barite weighting agents and polymer viscosifiers. Three-tier pricing structure across premium synthetic, standard water-based, and economy bulk-mud levels separates thermal stability certification from basic clay-polymer formulations. Cost compression accelerates in commodity water-based segments as independent blenders compete for Permian Basin shale contracts. Price sensitivity peaks among onshore independents seeking subscription-based fluid management; offshore deepwater operators show lowest sensitivity due to BSEE compliance mandates.
Supply Chain Analysis
Domestic-content mandates in Brazil's ANVISA licensing framework and Saudi Arabia's local procurement rules are reshaping sourcing patterns for base fluid manufacturing. Supply concentrates in the US Gulf Coast, China's Tianjin chemical corridor, and Norway's Stavanger cluster. Raw material dependencies center on Chinese barite exports, US Gulf Coast olefin feedstocks, and Indian guar derivatives for viscosity modifiers. Single-source vulnerability from Chinese weighting agent concentration creates input cost volatility. Distribution runs through integrated service company logistics networks and third-party bulk terminals at Macaé, Houston, and Dhahran.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over base fluid manufacturing and real-time monitoring technology determines margin capture. Players are pursuing backward integration into specialty additive formulation as the decisive upstream lever.
For Market Incumbents: Anchor market position through captive supply of synthetic base fluids and automated closed-loop mixing systems. Consolidate independent blenders in the Permian Basin to defend against subscription-based fluid management entrants. Invest in EPA biodegradability certification infrastructure to preempt regulatory compliance delays. For New Entrants and Emerging Players: Capture white-space opportunity in geothermal drilling fluid formulations exceeding 500°F thermal stability. Target Kenya and Iceland project developers with specialty chemistry partnerships. Enter through portable microemulsion mixing skid deployments for remote North Dakota Bakken operators. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated oilfield service conglomerates seeking additive formulation capabilities. Long-term viability favors specialists with ANVISA and BSEE environmental certifications. Watch EPA effluent limitation guideline enforcement intensity as the inflection signal for synthetic fluid substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Fluid Manufacturing | Schlumberger and Baker Hughes have secured captive olefin supply from US Gulf Coast petrochemical complexes. |
| Real-Time Viscosity Monitoring Deployment | Downhole sensor integration enables predictive additive injection for extended-reach Permian Basin laterals. |
| Used Fluid Reclamation Service Expansion | Third-party reconditioning infrastructure in Houston creates recurring revenue independent of drilling cycles. |
| Microemulsion Mixing Skid Proliferation | Portable on-site dilution systems reduce trucking intensity by sixty percent for remote Bakken drilling sites. |
| Biodegradability Certification Pre-Investment | Early EPA toxicity testing completion avoids eighteen-to-twenty-four month product launch delays for synthetic formulations. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with drilling fluid engineers, mud plant operations managers, offshore procurement leads at exploration companies, and EPA regulatory affairs specialists combined with secondary validation from BSEE discharge reports, ANVISA licensing databases, and Chinese Ministry of Ecology and Environment standards. Bottom-up volume estimates triangulated against top-down spending patterns across onshore shale corridors and deepwater lease blocks.
Reconciliation of production capacity data from base fluid manufacturers with consumption patterns reported by drilling contractors informed the analytical framework across the projection horizon. Segmentation dimensions modeled include fluid type, additive chemistry, end-use application, and regional regulatory cluster. CAGRs derived from weighted-average drilling intensity projections and fluid consumption per foot metrics. Industry-specific inputs incorporated thermal stability requirements for high-pressure high-temperature wells and OSHA worker exposure mandate implementation timelines.
The model holds under stable regulatory enforcement and continued horizontal drilling intensity; deviation in EPA discharge standard acceleration or Chinese barite export restriction severity would shift volume trajectories. Forecasts reflect documented assumptions about synthetic substitution economics and biodegradability certification timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oilfield Casing Spools Market
Oil & Gas
United States Onshore Drilling Fluid Market
Oil & Gas
Swellable Packers Market
Oil & Gas
Wireline Logging Services Market
Oil & Gas
US Oil and Gas Infrastructure Market
Oil & Gas
GCC Natural Gas Market
Oil & Gas
Global Oilfield Stimulation Chemicals Market
Oil & Gas
Coal Seam Gas Market
Oil & Gas
Oriented Perforating System Market
Oil & Gas
North America Proppants Market
Oil & Gas
Gulf of Mexico Oil and Gas Upstream Market
Oil & Gas
Digital Oilfield Market
Oil & Gas
Europe Hydraulic Fracturing Fluids Market
Oil & Gas
Small Scale LNG Terminal Market
Oil & Gas
Thailand Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Downhole Cables Market