
 South America Deep Water and Ultra Deep Water Exploration and Production (Eandp) Market | 2026-2036
South America Deep Water and Ultra Deep Water Exploration and Production (Eandp) Market Size, Share, and Industry Trends Forecast 2026-2036
South America Deep Water and Ultra Deep Water Exploration and Production (Eandp) Market Analytics
Offshore power generation integration is shifting the end-use vertical mix toward electrified floating production systems. Petrobras leverages its pre-salt dominance to anchor deepwater project economics across the Santos and Campos basins. Shell competes through subsea tieback expertise that reduces capital intensity for marginal field developments. Transocean LTD specializes in harsh-environment drillship fleets purpose-built for South Atlantic pressure regimes.
Deep water and ultra deep water exploration and production encompasses hydrocarbon recovery from seabed depths exceeding 400 meters, utilizing subsea trees, dynamic positioning vessels, and high-pressure high-temperature riser systems rated above 15,000 psi to extract crude from geological formations beneath thick salt layers. Seismic imaging leads technology investment as operators resolve sub-salt geological complexity beneath Brazil's pre-salt carbonate reservoirs. Floaters dominate drilling technique deployment, with semisubmersibles occupying the deepest water depths where jackup platforms cannot operate. Independent Producers represent the fastest-growing end user segment as ANP divestment rounds fragment legacy concession holdings.
ANP licensing frameworks shape market access through production-sharing contract terms and local content requirements mandating Brazilian supply chain participation. Brazil's environmental regulator, IBAMA, enforces stringent offshore drilling permits that delay project sanctioning timelines. Stakeholders must monitor pre-salt unit cost trajectories against breakeven thresholds as international oil companies reposition capital toward lower-carbon portfolios.
Market Dynamics
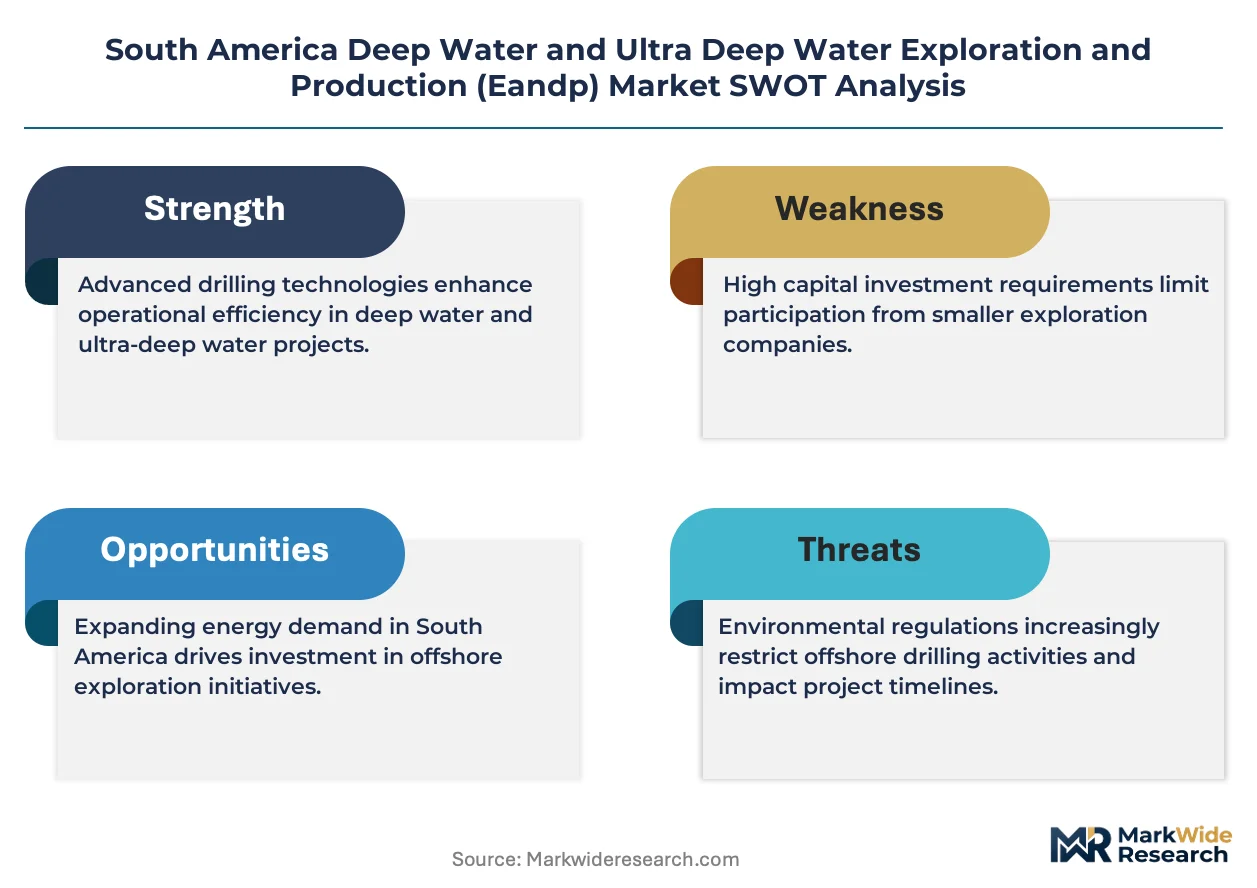
ANP production-sharing contract reforms are fragmenting Brazil's pre-salt concessions, accelerating capital redeployment toward independent producers while tightening local content mandates reshape supplier economics across the Santos Basin.
Growth Catalysts
- Pre-salt licensing rounds:ANP divestment of legacy Petrobras holdings creates new entry points for international operators seeking carbonate reservoir exposure.
- Seismic imaging advances:Full-azimuth wide-azimuth surveys now resolve sub-salt geological complexity that previously rendered pre-salt targets undrillable.
- Floating production unit electrification:Offshore power generation integration enables semisubmersible platforms to displace gas turbine dependence with shore-fed grid connections.
Market Restraints
- High-pressure riser supply concentration:Subsea hardware fabrication capacity concentrates among a limited set of Brazilian-certified suppliers, constraining project sanctioning velocity.
- IBAMA permitting timelines:Brazil's environmental regulator enforces multi-year offshore drilling permit reviews that delay field development schedules.
- Carbon portfolio reallocation:International oil companies redirect capital toward lower-emission assets, compressing pre-salt investment commitments from integrated majors.
Strategic Opportunities
- Argentina offshore frontier:The North Falkland Basin and Malvinas West licensing areas offer untapped deepwater acreage with analogous geological characteristics to Brazil's pre-salt.
- Subsea tieback architectures:Marginal field developments in the Campos Basin deploy satellite wells connected to existing floating production infrastructure, reducing standalone facility requirements.
- ANP local content incentives:Relaxed domestic sourcing thresholds for subsea equipment create procurement flexibility for operators balancing cost and compliance.
Industry Challenges
- HPHT engineering talent scarcity:South Atlantic pressure regimes exceeding 15,000 psi demand specialized subsea systems expertise that outpaces regional workforce development.
- Dynamic positioning vessel scheduling:Drillship fleet utilization conflicts between pre-salt exploration campaigns and completion activities create rig availability bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Deep Water and Ultra Deep Water Exploration and Production (Eandp) Market |
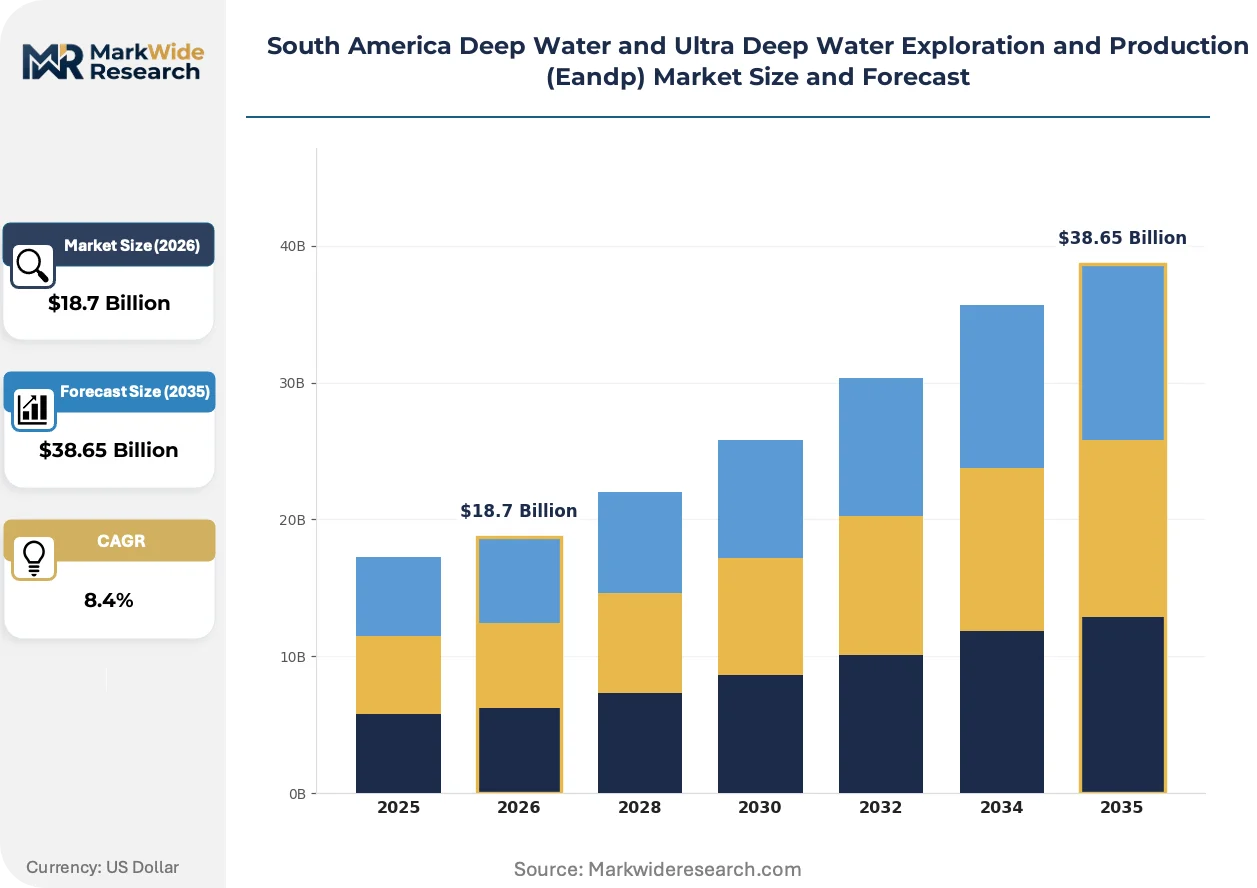
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Seismic Imaging, Subsea Production, Drilling Technology, Riser Systems Service Type: Consulting Services, Equipment Supply, Maintenance Services, Project Management Drilling Technique: Floaters, Semisubmersibles, Jackups, Spar Platforms End User: NOCs, IOCs, Service Companies, Independent Producers |
| Companies Covered | Petrobras, Shell, Chevron, Equinor ASA, ExxonMobil, TotalEnergies, Halliburton Company, Transocean LTD, BP PLC, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Deep Water and Ultra Deep Water Exploration and Production (Eandp) Market Evolving Landscape
Digital reservoir characterization and electrified production systems are compressing development timelines while regulatory frameworks force faster environmental compliance cycles across South Atlantic deepwater operations.
4D seismic monitoring combined with permanent reservoir monitoring systems is rewriting how operators manage pre-salt carbonate production decline. Petrobras and independent producers now deploy ocean-bottom node arrays to track fluid contact movement in real time. This capability is rewriting field development planning by enabling proactive infill drilling before productivity degradation accelerates.
IBAMA's streamlined environmental licensing procedures for projects with reduced flaring profiles are accelerating project sanctioning timelines for electrified platforms. The industrial consequence compresses front-end engineering design phases by eliminating redundant impact assessments. Floating production system operators in the Santos Basin are responding by prioritizing shore power connections over onboard generation to qualify for expedited permitting.
Integrated project delivery contracts are displacing traditional engineering-procurement-construction sequential arrangements among deepwater operators in Brazil. The contracting model transfers construction risk to vessel yards and subsea integrators, replacing arm's-length supplier management with single-point accountability. This shift is most visible in the Búzios and Mero field developments where operators bundle drilling, completion, and production facility scope under unified commercial frameworks.
South America Deep Water and Ultra Deep Water Exploration and Production (Eandp) Market Segmentation
Segmentation reveals how technology specialization, service bundling, and operator economics fragment procurement patterns across Brazil's pre-salt cluster. Each category maps distinct value capture points from reservoir characterization through production facility deployment.
Technology Type:
Customization intensity spans from commoditized hardware to bespoke subsurface imaging systems purpose-built for South Atlantic geological complexity.
- Seismic Imaging:Full-azimuth wide-azimuth surveys resolve sub-salt carbonate structures beneath Santos Basin salt layers. Petrobras deploys ocean-bottom node arrays for 4D reservoir monitoring, compressing infill drilling decision cycles. Leading the category by volume: Seismic Imaging. Growing fastest: Subsea Production.
- Subsea Production:High-pressure high-temperature trees and manifolds rated above 15,000 psi extract hydrocarbons from pre-salt reservoirs. Demand concentrates among independent producers accessing ANP divestment blocks requiring subsea tieback architectures.
- Drilling Technology:Managed pressure drilling systems and dual-gradient technologies navigate narrow pressure windows in deepwater salt sections.
- Riser Systems:Steel catenary and hybrid riser configurations connect subsea wells to floating production facilities in water depths exceeding 2,000 meters.
Technology procurement gravitates toward integrated packages that bundle imaging, drilling, and production hardware under unified performance guarantees.
Service Type:
Margin profiles diverge sharply between asset-heavy equipment supply and knowledge-intensive consulting engagements.
- Equipment Supply:Subsea hardware fabrication concentrates among Brazilian-certified suppliers meeting ANP local content mandates. Búzios and Mero field developments drive procurement volume for christmas trees, jumpers, and umbilicals.
- Consulting Services:Reservoir characterization and field development planning expertise commands premium pricing for pre-salt carbonate complexity. Fastest volume expansion: Project Management.
- Maintenance Services:Life-of-field contracts for subsea intervention and riser inspection sustain recurring revenue streams.
- Project Management:Integrated project delivery models transfer construction risk to vessel yards, displacing traditional engineering-procurement-construction sequential arrangements.
Service bundling accelerates as operators seek single-point accountability across drilling, completion, and production facility scope.
Drilling Technique:
Water depth and metocean conditions dictate platform selection across the Santos and Campos basin portfolio.
- Floaters:Drillship and semisubmersible rigs with dynamic positioning systems dominate pre-salt exploration campaigns. Demand clusters in Santos Basin ultra-deepwater blocks where jackup platforms cannot operate.
- Semisubmersibles:Harsh-environment hull designs withstand South Atlantic pressure regimes and looping current patterns. Largest installed base: Floaters.
- Jackups:Independent leg cantilever units serve marginal field developments and workover campaigns in Campos Basin mid-water depths.
- Spar Platforms:Deep-draft single-point mooring systems anchor production facilities in ultra-deepwater configurations beyond semisubmersible limits.
Drilling fleet scheduling conflicts between exploration and completion activities create rig availability bottlenecks across the pre-salt campaign queue.
End User:
Capital allocation patterns and risk tolerance stratify procurement behavior across operator categories.
- Independent Producers:ANP divestment rounds fragment legacy concession holdings, accelerating capital redeployment toward new entrants seeking carbonate reservoir exposure. These operators prioritize subsea tieback architectures to reduce standalone facility capital intensity.
- NOCs:Petrobras anchors deepwater project economics through pre-salt dominance and integrated execution capabilities across Santos and Campos basins. Steepest expansion trajectory: Independent Producers.
- IOCs:International oil companies compete through subsea tieback expertise and carbon portfolio reallocation pressures compress pre-salt investment commitments from integrated majors.
- Service Companies:Schlumberger, Halliburton, and Baker Hughes deploy integrated service packages spanning drilling, evaluation, and completion technologies.
End user composition is shifting as ANP production-sharing contract reforms fragment Brazil's pre-salt concessions toward independent producer participation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil produces nearly all South American deepwater hydrocarbons while consuming limited volumes domestically, creating a massive export-oriented production base concentrated in the Santos Basin pre-salt cluster.
Brazil
Petrobras operates the Búzios and Mero field complexes, driving procurement for floating production units and subsea trees. ANP production-sharing contract reforms fragment legacy concessions toward independent producers. Rio de Janeiro anchors the national oilfield services cluster, with Macaé and Niterói hosting fabrication yards for high-pressure riser systems.
Argentina
The North Falkland Basin and Malvinas West licensing areas attract frontier exploration targeting pre-salt analog formations. The national hydrocarbons regulator oversees offshore bidding rounds with fiscal terms designed to offset geological risk. Tierra del Fuego and Buenos Aires provinces concentrate maritime logistics capacity for South Atlantic campaigns.
Guyana
ExxonMobil-led Stabroek Block developments validate ultra-deepwater production economics at water depths exceeding 1,800 meters. The country's petroleum regulator negotiates production-sharing agreements with escalating government take mechanisms. Georgetown serves as the operational hub for floating production storage and offloading vessel support.
Suriname
Block 58 discoveries by TotalEnergies and Apache Corporation confirm extension of the Guyana-Suriname petroleum system into Dutch-speaking waters. The state oil company manages partnership structures with international operators. Paramaribo coordinates supply chain logistics for drillship mobilization and subsea hardware staging.
Colombia
Deepwater Caribbean campaigns in the Colón and Sinú basins target turbidite reservoirs at moderate depths relative to Santos Basin benchmarks. The national hydrocarbons agency regulates environmental permitting through streamlined offshore procedures. Cartagena hosts the primary maritime logistics cluster for Caribbean deepwater exploration.
South America Deep Water and Ultra Deep Water Exploration and Production (Eandp) Market Competitive Landscape
Top-tier vendors anchor integrated project delivery, while specialized subsea fabricators and independent drilling contractors occupy distinct lower tiers. Market structure concentrates around three strategic archetypes: state-backed national champions with basin-scale execution capabilities, international majors competing through subsea tieback expertise, and drilling specialists with harsh-environment fleet assets. Dominant competitive moves include integrated project delivery contracting that transfers construction risk to vessel yards, and strategic partnerships between operators and seismic imaging providers to compress pre-salt development timelines.
Within the national champion archetype, Petrobras S.A. anchors deepwater project economics through pre-salt dominance and integrated execution capabilities across the Santos and Campos basins. Among international majors, Shell plc and Chevron Corporation occupy positions defined by subsea tieback architectures that reduce capital intensity for marginal field developments. At the drilling specialist tier, Transocean LTD exemplifies harsh-environment drillship fleet positioning purpose-built for South Atlantic pressure regimes.
| Leading Market Players |
|---|
| Petrobras |
| Shell |
| Chevron |
| Equinor ASA |
| ExxonMobil |
| TotalEnergies |
| Halliburton Company |
| Transocean LTD |
| BP PLC |
| Others |
Value Network & Pricing Analysis
High-pressure riser steel alloys flow from specialty mills through ANP-certified fabricators in Rio de Janeiro state, accumulating local content premiums before reaching independent producers bidding on Santos Basin divestment blocks. This input cost cascade stratifies final project economics between integrated majors with captive supply and new entrants exposed to spot procurement volatility.
Pricing Analysis
Margin tightening in subsea hardware tiers reflects ANP local content mandates that restrict supplier qualification pools. Three-tier pricing structure across premium certified, standard compliant, and economy import-substitute levels separates Petrobras-scale volume buyers from independent producers facing certification premiums. Price differentiation hinges on IBAMA environmental approval status and after-sales intervention bundling. Independent producers exhibit highest price sensitivity as they optimize subsea tieback architectures against standalone facility economics.
Supply Chain Analysis
Dual-sourcing requirements for HPHT christmas trees compel operators to qualify both domestic Brazilian fabricators and Asian specialist suppliers. Geographic supply concentration centers on Brazil, South Korea, and Norway for subsea production systems. Raw material dependencies include high-grade steel forgings, tungsten carbide valve components, and synthetic umbilical sheathing. Single-source vulnerability concentrates in dynamic positioning vessel availability where drillship fleet utilization conflicts create scheduling chokepoints. Distribution runs through Macaé and Niterói logistics clusters serving Santos Basin campaign staging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained HPHT engineering talent scarcity props pricing power for certified subsea integrators capable of executing pre-salt developments. This capacity bottleneck sustains margin premiums across the contracting queue.
For Market Incumbents: Anchor pre-salt dominance through integrated project delivery contracting that transfers construction risk to vessel yards while tightening control over subsea hardware specification. Defend position against independent producer fragmentation by locking in long-term ocean-bottom node array deployment contracts. Prioritize certification investment in ANP local content compliance to maintain supplier qualification status.
For New Entrants and Emerging Players: Capture Argentina offshore frontier acreage in North Falkland Basin licensing rounds where fiscal terms offset geological risk. Target subsea tieback architecture specialization for Campos Basin marginal field developments requiring satellite well connections to existing floating production infrastructure. Deploy consulting-led go-to-market positioning emphasizing reservoir characterization expertise for pre-salt carbonate complexity.
For Investors and Strategic Acquirers: Distressed-cycle entries favor harsh-environment drillship operators with South Atlantic pressure regime specialization. Long-term viability frames around electrified floating production system deployment across the analysis window. Monitor pre-salt unit cost trajectories against breakeven thresholds as the inflection signal for capital redeployment timing. Deviation in IBAMA permitting velocity would shift the outlook materially.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Project Delivery Contracting | Transfers construction risk to vessel yards while compressing front-end engineering timelines for Búzios-scale developments. |
| Subsea Tieback Architecture Deployment | Enables marginal field economics in Campos Basin by eliminating standalone floating production facility capital requirements. |
| Ocean-Bottom Node Array Installation | Delivers 4D seismic monitoring capability that compresses infill drilling decision cycles for pre-salt carbonate reservoirs. |
| Shore Power Connection Qualification | Qualifies electrified platforms for IBAMA expedited permitting through reduced flaring profile compliance. |
| ANP Local Content Certification | Maintains supplier qualification status for high-pressure riser fabrication mandates across Santos Basin procurement. |
Research Methodology
Document review covered ANP licensing round disclosures, IBAMA environmental permit databases, and Petrobras quarterly operational reports, complemented by interviews with subsea engineering directors, drilling fleet managers, and ANP regulatory affairs specialists. Secondary validation drew from customs trade data, offshore vessel utilization trackers, and SEC filings from listed drilling contractors. Bottom-up project sanctioning timelines and top-down basin production forecasts were triangulated to anchor volume estimates.
Cross-reference between historical pre-salt development cost trajectories and expert panel input on electrification adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include technology type, service bundling intensity, drilling platform category, and operator archetype. CAGRs were derived from unit cost progression analysis and capacity expansion schedules. Forecast inputs incorporated seismic imaging technology deployment rates and ANP divestment round pacing assumptions.
The model holds under stable ANP production-sharing contract terms and IBAMA permitting velocity; deviation in carbon portfolio reallocation intensity among integrated majors or local content mandate relaxation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Azerbaijan Oil and Gas Downstream Market
Oil & Gas
Oilfield Drilling Elevator Market
Oil & Gas
Frac Stack Market
Oil & Gas
North America Proppants Market
Oil & Gas
Clear Brine Fluids Market
Oil & Gas
Global Deep-Well Disposal Services Market
Oil & Gas
Tricone Bits Market
Oil & Gas
Connected Oil and Gas Market
Oil & Gas
Wellhead System Market
Oil & Gas
Crude Oil Desalter and Electrostatic Dehydrator Market
Oil & Gas
Cased Hole Logging Services Market
Oil & Gas
Global Hydrate Inhibitors Market
Oil & Gas
United States Oil and Gas Downstream Market
Oil & Gas
Africa Oil and Gas Market
Oil & Gas
Russia Oilfield Services Market
Oil & Gas
Canada LNG Market