
 Subsea Flowlines Market | 2026-2036
Subsea Flowlines Market Size, Share, and Industry Trends Forecast 2026-2036
Subsea Flowlines Market Insights
Buyer concentration among national oil companies and integrated majors is decoupling from the traditional supermajor-dominated procurement pattern as independent operators and private equity-backed developers enter frontier basins. TechnipFMC anchors its position through integrated subsea production systems that bundle flowlines with trees and manifolds. Baker Hughes differentiates via metallurgical R&D in corrosion-resistant alloys for sour service environments. Saipem competes through vessel-based installation capabilities that reduce third-party charter exposure.
Subsea flowlines are pressure-containing conduits fabricated from carbon steel, duplex stainless steel, or unbonded flexible composite layers, designed to transport hydrocarbons from subsea wellheads to surface facilities across seabed profiles exceeding 3,000 meters water depth. Flexible pipe systems lead in dynamic riser applications where vessel motion and seabed topography demand bending compliance, while steel pipe dominates static flowline corridors where thermal expansion management and collapse resistance govern design. Reel-lay installation method captures growing share in pre-salt and West African developments where pipeline diameter and coating weight favor single-line deployment efficiency.
API standards, DNV offshore codes, and BSEE safety regulations collectively govern material qualification, welding protocol, and pressure-testing regimes that determine market access for flowline suppliers. The EU Green Deal's methane emission thresholds and the EPA's updated offshore combustion requirements are reshaping specifications for leak-tight connection systems and annulus monitoring. Stakeholders must monitor how decommissioning liability frameworks and Scope 3 disclosure mandates alter project sanctioning timelines and flowline design life assumptions.
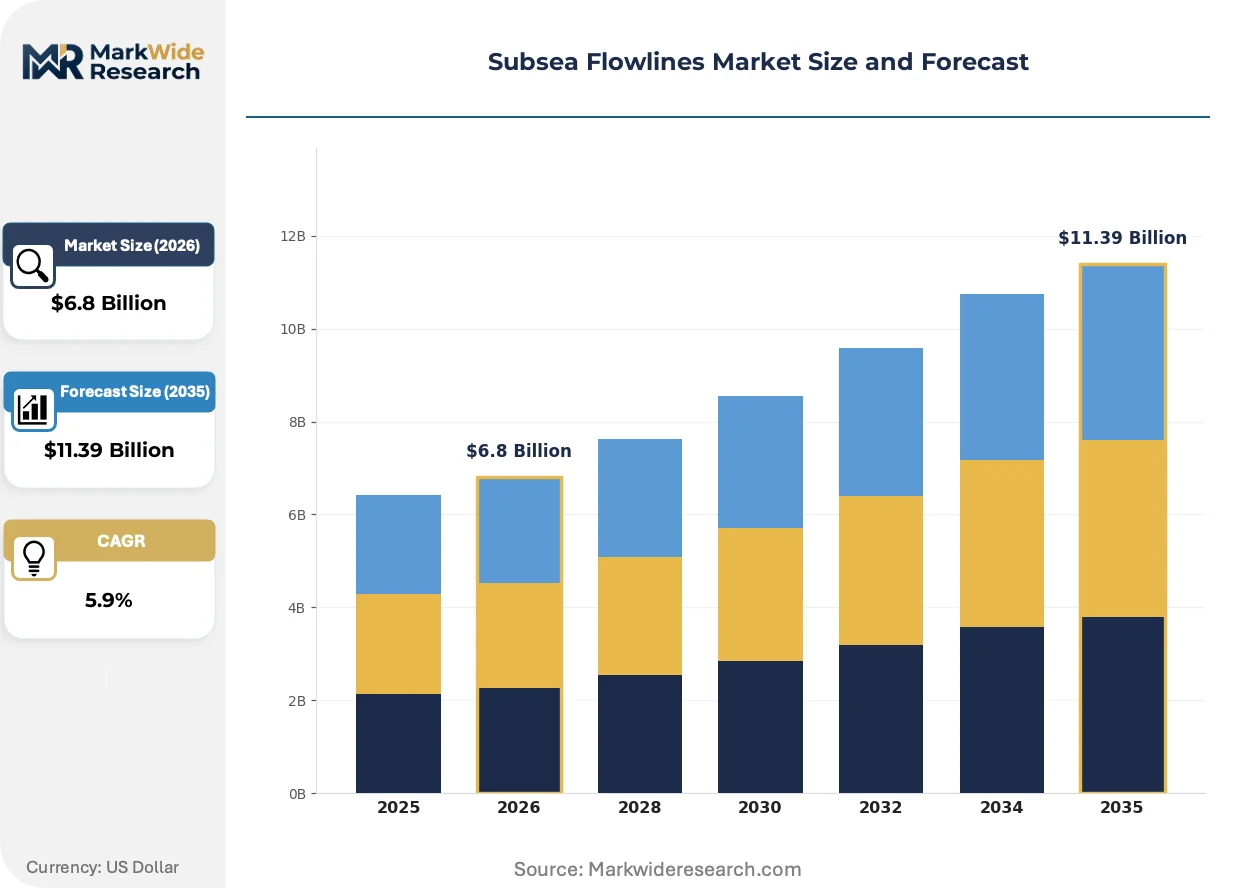
Market Dynamics
API 17J qualification tightening and ultra-deepwater field maturation are compressing supplier lead times while fragmenting procurement authority among private equity-backed developers and national oil companies.
Growth Catalysts
- Pre-salt basin expansion:Petrobras and international partners in Brazil's Santos and Campos basins are sanctioning subsea tieback projects at water depths exceeding 2,000 meters, requiring steel catenary risers and dynamic flowline systems.
- EU Green Deal methane thresholds:Leak-tight connection specifications and annulus monitoring mandates are accelerating replacement cycles for legacy flowline infrastructure in North Sea developments.
- Reel-lay installation adoption:Pipeline coating weight and diameter requirements in West African pre-salt corridors favor single-line deployment efficiency over conventional S-lay methods.
Market Restraints
- Corrosion-resistant alloy supply concentration:Duplex stainless steel and super-duplex forging capacity concentrates among specialized European and Japanese metallurgical suppliers, creating input bottlenecks during project sanctioning waves.
- Deepwater qualification timelines:API 17J and DNV-ST-F201 unbonded flexible pipe certification protocols extend vendor approval cycles to 18-24 months for new product variants.
- Decommissioning liability frameworks:BSEE and UK North Sea decommissioning security requirements are extending project sanctioning timelines and compressing assumed flowline design life economics.
Strategic Opportunities
- Electrification of subsea production:All-electric subsea control systems and wet-mate connector convergence are reducing hydraulic umbilical complexity and enabling longer step-out distances from host facilities.
- Scope 3 disclosure mandates:CSRD-aligned carbon accounting requirements are creating specification premiums for low-emission flowline installation methods and materials sourcing transparency.
- Guyana-Suriname basin entry:ExxonMobil-operated Stabroek block developments and emerging Suriname offshore licensing rounds are generating demand for high-pressure high-temperature flowline systems in 1,500-2,500 meter water depths.
Industry Challenges
- Welding technician scarcity:Automated orbital welding certification and sour service overlay expertise shortages are constraining fabrication yard throughput in Brazil, Singapore, and Norway.
- Integration complexity:Brownfield tie-in requirements with 1980s-era rigid pipeline infrastructure demand bespoke spoolpiece engineering and pressure-isolation methodologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subsea Flowlines Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Pipe, Flexible Pipe, Composite Pipe, Umbilicals Installation Method: Reel-Lay, S-Lay, J-Lay, Tow-in End User: Oil & Gas Operators, Engineering Contractors, Service Providers, Government Bodies Pressure Rating: Low Pressure, Medium Pressure, High Pressure, Ultra High Pressure |
| Companies Covered | Aker Solutions, OneSubsea, TechnipFMC, Prysmian Group, Halliburton, Subsea 7, Baker Hughes, Nexans, Saipem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subsea Flowlines Market Trends and Innovations
Thermal management and digital monitoring capabilities are converging with metallurgical advances to redefine flowline performance specifications across ultra-deepwater frontiers.
Carbon fiber-reinforced thermoplastic composite pipe (TCP) is unifying pressure containment and thermal insulation functions in a single unbonded structure. Operators in Norway's northern North Sea and Australia's Browse Basin are piloting TCP for 10,000 psi sour service applications at 150°C. This unification is compressing the traditional separation between flexible dynamic risers and rigid steel flowlines, enabling hybrid field architectures that reduce subsea connection counts.
EPA updated offshore combustion requirements and BSEE blowout preventer testing mandates are tightening leak-path documentation for subsea connection systems. Fabricators must now demonstrate annulus venting integrity and thermal sleeve performance under sustained pressure cycling. High-pressure high-temperature (HPHT) projects in the Gulf of Mexico and offshore Angola are absorbing the largest compliance cost increments, with specification revisions adding 8-12 weeks to procurement cycles.
Integrated subsea production system bundling is displacing discrete component procurement for pre-salt and West African developments. National oil companies and integrated majors are consolidating tree, manifold, and flowline awards with single-source suppliers capable of interface warranty coverage. Brazil's Petrobras and Nigeria's NNPC are most advanced in this consolidation, with technical specification alignment now preceding rather than following contract award.
Subsea Flowlines Market Segmentation
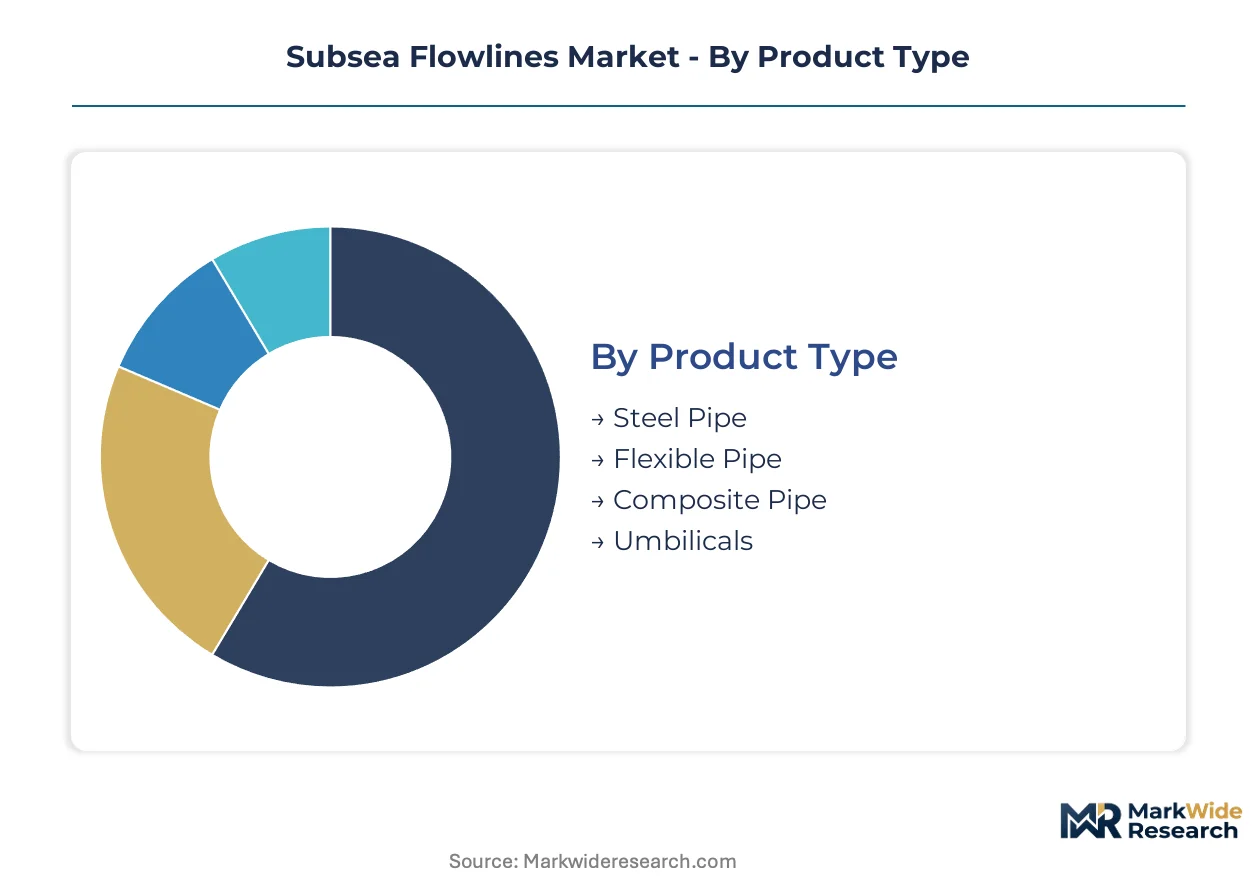
Subsea flowline procurement patterns diverge sharply across product architecture and deployment methodology. Capital allocation priorities in ultra-deepwater basins favor integrated system bundling over discrete component sourcing.
Product Type:
Steel pipe and flexible pipe configurations command the highest upfront capital deployment due to metallurgical complexity and qualification overhead.
- Steel Pipe:Carbon steel and duplex stainless steel constructions deliver collapse resistance for static corridors in Brazil's pre-salt fields and West African developments. Wall thickness and concrete weight coating specifications drive material cost premiums in water depths exceeding 2,000 meters.
- Flexible Pipe:Unbonded composite layers with steel armor wires enable dynamic riser compliance where vessel motion and seabed topography demand bending tolerance. Petrobras deploys these systems for steel catenary riser alternatives in Santos Basin ultra-deepwater tiebacks.
- Composite Pipe:Carbon fiber-reinforced thermoplastic unifies pressure containment with thermal insulation in pilot deployments across Norway's northern North Sea.
- Umbilicals:Hydraulic and electric conductor bundles for subsea control systems accompany flowline infrastructure in integrated production system awards.
Most installed capacity flows through steel pipe. Expansion is steepest in flexible pipe as dynamic riser applications multiply.
Installation Method:
Vessel fleet specialization and pipeline diameter dictate contractor selection and day-rate economics across deployment methodologies.
- Reel-Lay:Single-line deployment from dedicated reel vessels captures growing share in pre-salt and West African corridors where coating weight and diameter favor continuous spooling efficiency over jointed construction.
- S-Lay:Conventional stinger-based installation from lay barges dominates large-diameter trunkline construction in shallower water depths where stinger curvature limits do not constrain operations.
- J-Lay:Near-vertical pipeline departure from tower-equipped vessels addresses high-tension requirements in deepwater and ultra-deepwater environments.
- Tow-in:Pre-fabricated pipeline towing to site reduces offshore welding exposure in protected nearshore and shelf developments.
Reel-lay vessels concentrate in Atlantic Basin contractor fleets. J-lay capability is expanding fastest among Asia-Pacific installation contractors.
End User:
Procurement authority fragmentation between national oil companies and private equity-backed developers is reshaping contract structuring and technical specification alignment.
- Oil & Gas Operators:Integrated majors and national oil companies including Petrobras and Nigeria's NNPC drive integrated subsea production system bundling with single-source interface warranties.
- Engineering Contractors:TechnipFMC and Saipem anchor demand through turnkey subsea installation contracts that internalize flowline procurement within broader field development scopes.
- Service Providers:Inspection, maintenance, and repair specialists absorb replacement cycles for legacy infrastructure under EU Green Deal methane threshold compliance mandates.
- Government Bodies:BSEE and UK North Sea regulators influence specification through decommissioning security requirements and blowout preventer testing mandates.
Operator direct procurement dominates capital expenditure. Contractor-led sourcing is gaining share fastest in integrated system awards.
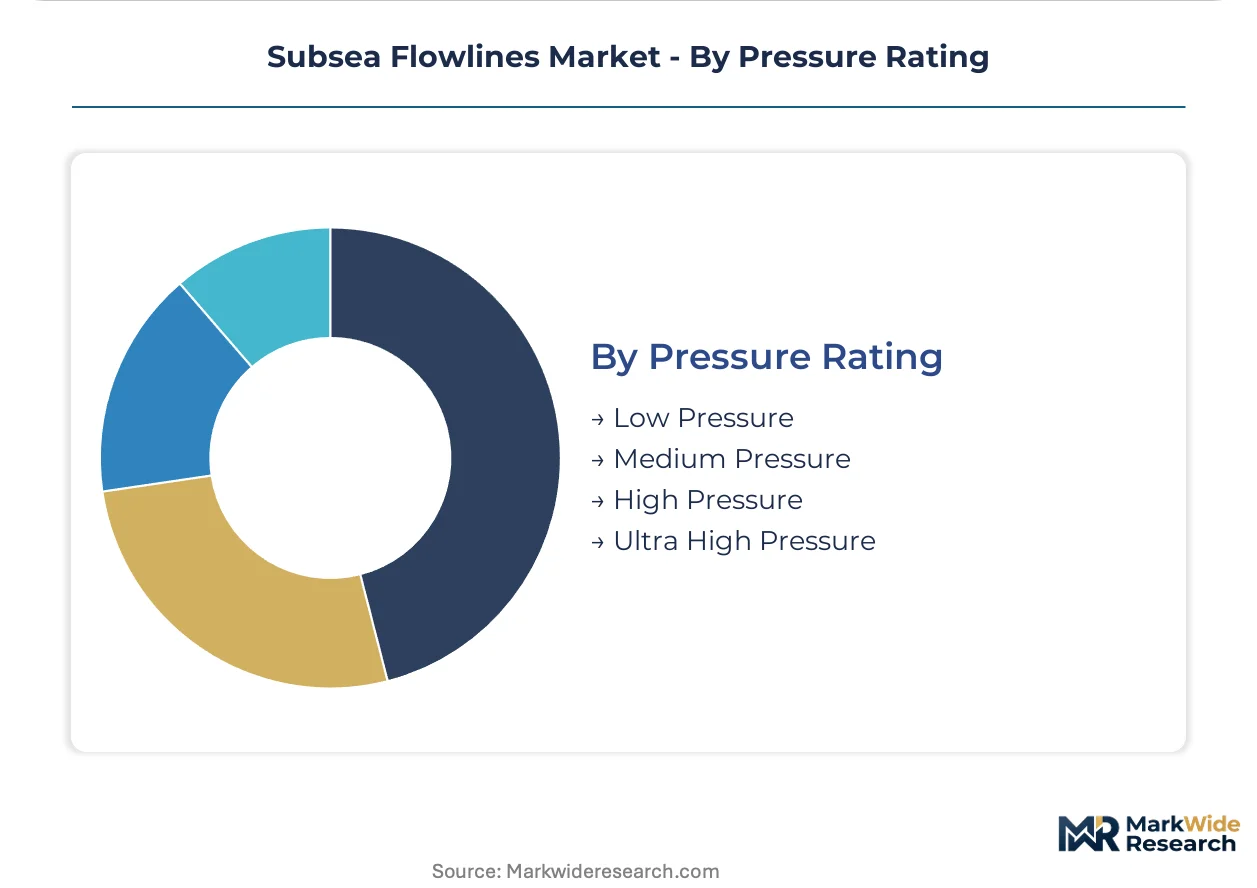
Pressure Rating:
High-pressure and ultra-high-pressure specifications absorb disproportionate qualification and metallurgical investment in frontier basin developments.
- High Pressure:5,000-10,000 psi ratings govern steel pipe and flexible pipe designs for Gulf of Mexico and Angola HPHT reservoirs where sour service corrosion resistance adds specification complexity.
- Ultra High Pressure:Exceeding 10,000 psi, these systems demand super-duplex forgings and specialized welding protocols for Stabroek block and Suriname basin developments at 1,500-2,500 meter depths.
- Medium Pressure:Standard tieback applications in mature North Sea and Southeast Asian fields with established infrastructure.
- Low Pressure:Shallow-water developments and certain gas injection lines where collapse resistance requirements relax material specifications.
High-pressure systems carry the largest installed base. Ultra-high-pressure demand is climbing the fastest as frontier basins mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands deeper pre-salt development than Norway's mature North Sea infrastructure, while the United States and Angola absorb diverging regulatory pressures on subsea installation methods.
Brazil
Petrobras sanctions subsea tieback projects exceeding 2,000 meters in the Santos and Campos basins, requiring steel catenary risers and dynamic flowline systems. ANVISA environmental licensing and BSEE-aligned safety protocols govern qualification timelines for flexible pipe vendors. The Rio de Janeiro industrial cluster concentrates reel-lay vessel operations and automated welding fabrication yards serving pre-salt developments.
United States
Gulf of Mexico HPHT reservoirs drive demand for ultra-high-pressure flowlines exceeding 10,000 psi in 1,500-meter water depths. EPA updated offshore combustion requirements and BSEE blowout preventer testing mandates tighten leak-path documentation for subsea connection systems. Houston anchors engineering procurement centers where integrated subsea production system bundling consolidates tree, manifold, and flowline awards.
Norway
North Sea operators pilot carbon fiber-reinforced thermoplastic composite pipe for 10,000 psi sour service at 150°C in the northern North Sea. EU Green Deal methane emission thresholds and CSRD-aligned carbon accounting accelerate replacement cycles for legacy infrastructure. Stavanger and Bergen harbor subsea technology clusters where all-electric control system integration reduces hydraulic umbilical complexity.
Angola
West African pre-salt corridors favor reel-lay installation efficiency over conventional S-lay methods for pipeline coating weight and diameter requirements. DNV offshore codes and local content regulations shape procurement authority fragmentation among international operators and national oil company partnerships. Luanda serves as the logistics hub for vessel-based installation capabilities reducing third-party charter exposure.
United Kingdom
North Sea decommissioning liability frameworks compress assumed flowline design life economics and extend project sanctioning timelines. UK North Sea regulators influence specification through decommissioning security requirements and methane threshold compliance mandates. Aberdeen maintains subsea engineering clusters focused on brownfield tie-in engineering with 1980s-era rigid pipeline infrastructure.
Subsea Flowlines Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across subsea flowline procurement, creating a tiered structure where integrated production system bundling displaces discrete component sourcing. The vendor base concentrates among vessel-owning installation contractors and metallurgical R&D houses, with national oil companies consolidating awards under single-source interface warranties. Two strategic archetypes dominate: integrated subsea production system suppliers and specialized flexible pipe manufacturers. Competitive moves center on strategic partnerships for vessel fleet access and backward integration into corrosion-resistant alloy forging capacity.
Among Norway-based engineering conglomerates, Aker Solutions and Subsea 7 occupy positions within the integrated installation tier, exemplifying vessel-based capabilities that internalize flowline procurement within broader field development scopes. TechnipFMC anchors the bundled system archetype through its integrated subsea production system offerings. These three entities represent the competitive concentration where technical specification alignment now precedes rather than follows contract award.
| Leading Market Players |
|---|
| Aker Solutions |
| OneSubsea |
| TechnipFMC |
| Prysmian Group |
| Halliburton |
| Subsea 7 |
| Baker Hughes |
| Nexans |
| Saipem |
| Others |
Pricing and Supply Chain Analysis
Captive integration into corrosion-resistant alloy forging anchors both supply security and pricing power for subsea flowline fabricators serving ultra-deepwater projects. Petrobras and integrated majors consolidate procurement under single-source warranties, compressing margin negotiation leverage for vendors without backward control over super-duplex metallurgical inputs.
Pricing Analysis
Capacity additions in Singapore and Brazil are reshaping price floors for reel-lay installation services as vessel fleet expansion outpaces pre-salt sanctioning waves. Project-based contract pricing dominates, with differentiation running through API 17J qualification tier and sour service certification grade. Cost compression in standard steel pipe tiers is intensifying because European forging bottlenecks concentrate super-duplex supply among Japanese and specialized metallurgical suppliers. National oil companies exhibit lowest price sensitivity due to interface warranty requirements, while private equity-backed developers drive hardest bargain on day-rate economics.
Supply Chain Analysis
API 17J and DNV-ST-F201 certification gating restricts vendor approval to 18-24 month qualification cycles, concentrating supply among incumbent flexible pipe manufacturers. Norway, Brazil, and Singapore anchor fabrication yard capacity, drawing from super-duplex stainless steel forgings, carbon fiber composite preforms, and concrete weight coating aggregates. Single-source vulnerability runs through European and Japanese metallurgical suppliers during project sanctioning waves. Distribution runs through integrated subsea production system bundling where TechnipFMC and Subsea 7 internalize procurement within turnkey field development scopes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EPA offshore combustion requirements and BSEE blowout preventer mandates accelerate replacement cycles for legacy connection systems.
For Market Incumbents: Cement position through captive forging partnerships with Japanese metallurgical suppliers and API 17J qualification pre-investment ahead of Guyana-Suriname basin maturation. Threat from carbon fiber-reinforced thermoplastic composite pipe substitution demands R&D allocation to hybrid steel-composite architectures. Backward integration into super-duplex forging capacity is the critical defensive lever against input bottlenecks during sanctioning waves. For New Entrants and Emerging Players: Enter via inspection, maintenance, and repair specialization for EU Green Deal methane threshold compliance in North Sea brownfield infrastructure. White space concentrates in composite pipe pilot deployments for 10,000 psi sour service applications where incumbent qualification timelines exclude immediate competition. Go-to-market angle centers on CSRD-aligned carbon accounting transparency for installation method specification premiums. For Investors and Strategic Acquirers: Consolidation pressure builds where welding technician scarcity constrains fabrication yard throughput in Brazil, Singapore, and Norway. Long-term viability favors vessel-owning installation contractors with reel-lay capability and integrated system bundling credentials. Acquisition target archetype: automated orbital welding specialists with sour service overlay certification. Signal to watch is ANVISA environmental licensing velocity for pre-salt tieback approvals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forging | Captive super-duplex supply secures margin control against Japanese metallurgical bottlenecks. |
| API 17J Pre-Qualification Investment | Early certification locks vendor status for Petrobras pre-salt flexible pipe awards. |
| Composite Pipe Pilot Deployment | TCP validation in Norway's northern North Sea opens hybrid architecture substitution. |
| Reel-Lay Vessel Fleet Expansion | Dedicated spooling capacity captures West African pre-salt installation efficiency premiums. |
| All-Electric Control System Integration | Wet-mate connector convergence reduces hydraulic umbilical complexity for longer step-outs. |
Research Methodology
Bottom-up operator capex modeling reconciled against top-down vessel fleet tracking forms the analytical core of this study. Primary interviews with subsea project engineers, procurement leads at national oil companies, flexible pipe qualification managers, and reel-lay vessel operators combined with secondary validation from BSEE safety filings, ANVISA licensing databases, DNV offshore code revisions, and Petrobras annual procurement disclosures. Triangulation across these sources calibrated market sizing and installation method adoption rates.
Input-output matrices mapped flowline demand by water depth tier, pressure rating, and product architecture against supply-side fabrication yard capacity and vessel availability throughout the forecast period. Segmentation dimensions modeled include steel versus flexible versus composite pipe, reel-lay versus S-lay versus J-lay methodology, and operator direct versus contractor-led procurement authority. CAGRs derived from project sanctioning pipeline analysis and qualification timeline compression factors, with HPHT reservoir complexity and decommissioning liability frameworks as industry-specific forecast inputs.
Inputs from BSEE, ANVISA, and DNV regulatory filings were available through the study window; gaps in private equity-backed developer disclosure introduce uncertainty bands around frontier basin demand timing. Forecasts reflect documented assumptions regarding pre-salt sanctioning velocity and metallurgical supply expansion. Deviation in API 17J qualification timeline compression or EU Green Deal methane threshold enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Japan LNG Bunkering Market
Oil & Gas
Qatar Oil and Gas Market
Oil & Gas
GCC Natural Gas Market
Oil & Gas
Tricone Bits Market
Oil & Gas
Europe Natural Gas Market
Oil & Gas
Reservoir Analysis Market
Oil & Gas
Operational Digital Oilfield Solution Market
Oil & Gas
Middle-East Oilfield Services Market
Oil & Gas
Rigless Intervention Systems Sales Market
Oil & Gas
South-East Asia Oil and Gas Pipeline Market
Oil & Gas
Casing and Cementation Hardware Market
Oil & Gas
Central Asia Oil and Gas Market
Oil & Gas
Malaysia Oil and Gas Midstream Market
Oil & Gas
South America Intelligent Pigging Market
Oil & Gas
Brazil Oil and Gas Midstream Market
Oil & Gas
Europe Digital Oilfield Market