
 Sic Wafer Reclaim Services Market | 2026-2036
Sic Wafer Reclaim Services Market Size, Share, and Industry Trends Forecast 2026-2036
Sic Wafer Reclaim Services Market Intelligence
The capital-intensity divergence between integrated reclaim specialists and standalone service providers is reorganizing competitive tiers across the Sic wafer reclaim landscape. RS Technologies Co., Ltd. leverages its captive polishing infrastructure to anchor premium reclaim cycles for power-device foundries. Pure Wafer competes on geographic density, sustaining multiple processing nodes across North American and Asian hubs. Kinik Company differentiates through defect-repair specialization, occupying a narrow but defensible tier for high-value epitaxial reclaim.
Sic wafer reclaim services encompass the recovery, surface restoration, and qualification of used silicon carbide substrates for re-entry into semiconductor manufacturing flows. The process typically involves sequential mechanical grinding, chemical-mechanical planarization, and thermal oxidation to restore crystalline surface integrity to sub-nanometer roughness specifications. Chemical etching and cleaning & stripping services command the largest service-type volumes, as these stages address the most common post-epitaxy contamination modes. Power electronics and semiconductor foundries represent the dominant end-use industries, with the former generating higher per-w reclaim values due to thicker epitaxial stacks and stricter defect-density thresholds.
China's MEE enforces hazardous-waste tracking for spent abrasive slurries and etchant chemistries, elevating compliance costs for reclaim operators serving domestic foundries. Japan's METI coordinates JIS standards for recycled semiconductor materials, creating technical barriers for non-certified reclaim houses seeking access to Japanese device manufacturers. Taiwan's central environmental authority mandates periodic reporting of heavy-metal discharge from chemical etching lines, tightening operational permits for reclaim facilities in the Hsinchu Science Park corridor. Stakeholders must monitor how regional certification fragmentation affects cross-border reclaim logistics and customer qualification timelines.
Market Dynamics
Original silicon carbide wafer prices have climbed sharply, compressing foundry margins and forcing power-device manufacturers to maximize substrate reuse cycles rather than defaulting to virgin material procurement.
Growth Catalysts
- Power electronics expansion:Electric vehicle inverters and renewable energy converters consume SiC substrates at accelerating rates, generating substantial reclaimable inventory for processing.
- China's NMPA-aligned environmental directives:Mandatory semiconductor waste recovery protocols are tightening material traceability requirements and institutionalizing reclaim channels.
- East Asian fabrication clustering:Taiwan and South Korea sustain elevated foundry utilization rates that produce continuous reclaim volume pipelines.
Market Restraints
- Polishing slurry cost volatility:Abrasive consumables and specialized chemistries represent significant variable costs that fluctuate with rare earth supply constraints.
- Substrate supply concentration:Limited qualified virgin wafer suppliers in Japan and the United States create bottleneck risks that propagate through reclaim service tiers.
- Epitaxial defect density floors:Crystalline damage from multiple reclaim cycles imposes hard technical limits on substrate reusability for high-voltage applications.
Strategic Opportunities
- India's emerging compound semiconductor ecosystem:PLI scheme incentives for domestic SiC device manufacturing will create captive reclaim demand as fabrication scales.
- Automotive qualification pathways:AEC-Q101 stress-test protocols for reclaimed substrates open premium pricing tiers for power-module suppliers.
- Closed-loop chemical regeneration:On-site etchant recovery systems reduce hazardous waste discharge and lower per-wafer processing costs.
Industry Challenges
- Crystallographic metrology talent scarcity:Operators capable of operating atomic force microscopy and X-ray diffraction systems for sub-nanometer surface qualification remain in short supply.
- Cross-border certification latency:Japan's METI-coordinated JIS standards for recycled semiconductor materials create multi-month qualification timelines for non-certified reclaim houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sic Wafer Reclaim Services Market |
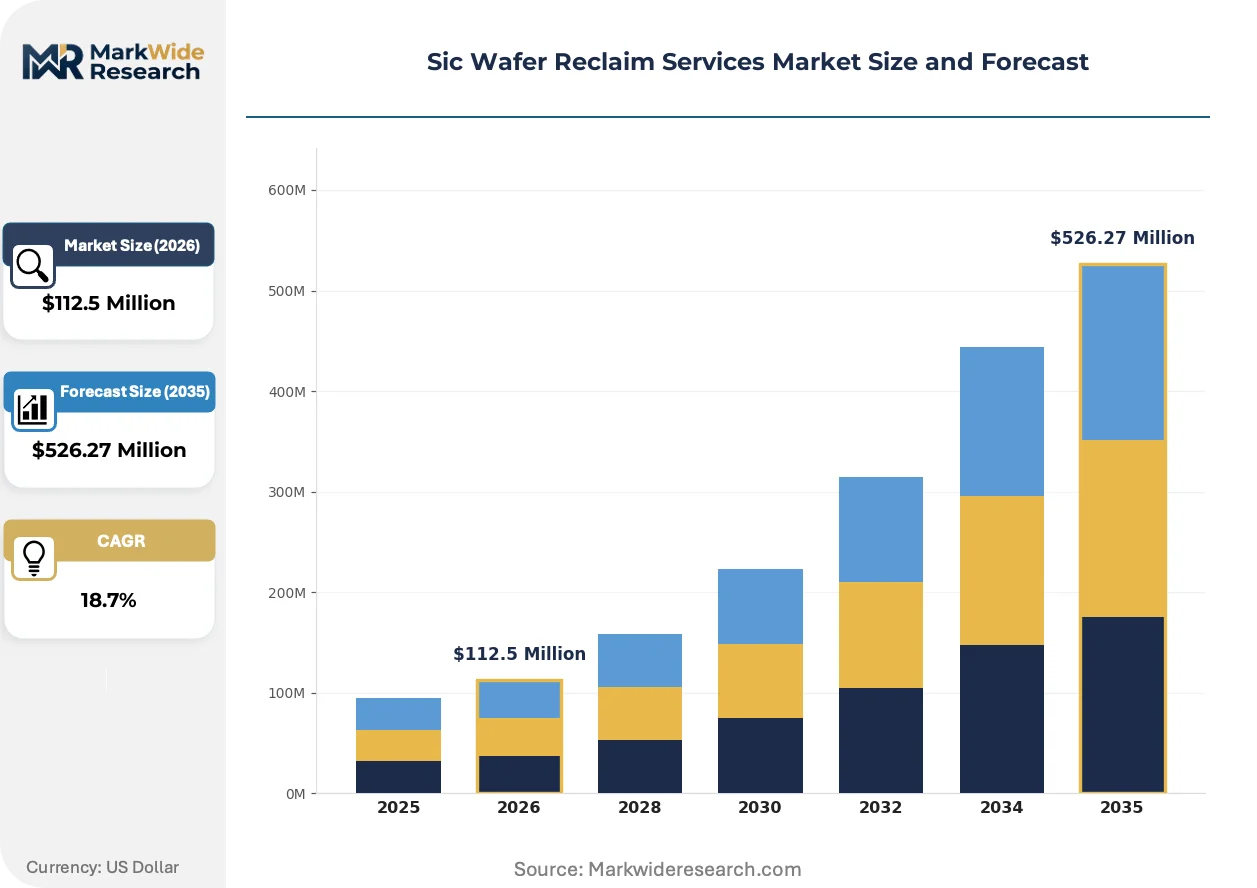
| Market Size in 2026 | $112.5 Million |
| Market Size in 2035 | $526.27 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Surface Polishing, Chemical Etching, Thermal Oxidation, Cleaning & Stripping, Defect Repair End Use Industry: Power Electronics, LED Manufacturing, Semiconductor Foundries, Photovoltaic Cells, Microelectromechanical Systems Wafer Size: 100 mm, 150 mm, 200 mm, 300 mm, 450 mm Reclaim Stage: Post-Epitaxy, Post-Photolithography, Post-Device Fabrication, Post-Packaging |
| Companies Covered | RS Technologies Co., Ltd., Pure Wafer, Phoenix Silicon International Corporation, Semiconductor Industry Co., Ltd., Mimasu, TOPCO Scientific, Scientech Corporation, Kinik Company, NOVA Electronic Materials, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sic Wafer Reclaim Services Market Strategic Shifts & Innovations
Process automation and surface characterization advances are compressing reclaim cycle times while expanding the addressable substrate damage profiles that service providers can economically restore.
Plasma-enhanced chemical etching is miniaturizing defect removal resolution for SiC reclaim operations. Advanced foundries in Taiwan are adopting these systems to address micro-pipe and stacking fault densities that mechanical grinding cannot resolve. The technology is miniaturizing the minimum recoverable substrate thickness, effectively extending usable wafer life by one to two additional reclaim cycles.
China's MEE hazardous-waste tracking mandates for spent abrasive slurries and etchant chemistries are elevating compliance costs for reclaim operators serving domestic foundries. Facilities must now install real-time discharge monitoring and maintain chain-of-custody documentation for all chemical streams. Operators in the Yangtze River Delta corridor are consolidating processing volumes to amortize these fixed compliance investments across larger throughput bases.
Power-device manufacturers are unbundling reclaim services from captive foundry arrangements and contracting directly with specialized providers. Tier-one automotive suppliers now specify substrate provenance and reclaim cycle count in procurement contracts, displacing generic vendor qualifications. South Korean power-module producers have pioneered this specification intensity, pressuring reclaim houses to demonstrate crystallographic lineage documentation.
Sic Wafer Reclaim Services Market Segmentation
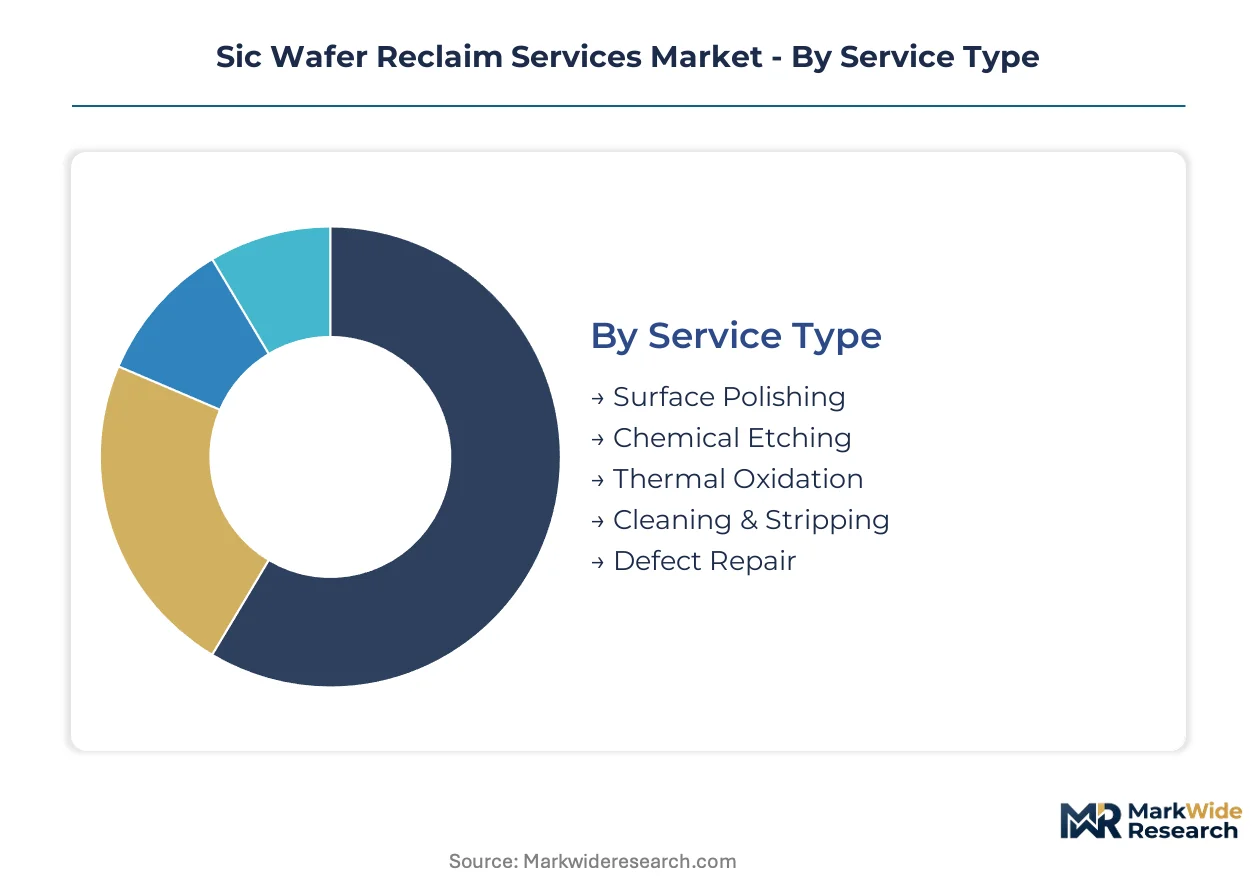
SiC wafer reclaim services fragment across service modalities, device manufacturing stages, and substrate specifications. Each segmentation dimension carries distinct regulatory footprints, cost structures, and qualification thresholds that reshape procurement patterns for power-device foundries.
Service Type:
Regulatory differentiation across chemical handling regimes elevates compliance costs for wet-process services versus dry alternatives. China's MEE hazardous-waste tracking mandates for spent abrasive slurries and etchant chemistries impose stricter documentation burdens on chemical-intensive operations than on mechanical polishing lines.
- Chemical Etching:Acid-based and plasma-enhanced systems remove epitaxial residue and subsurface damage layers. Taiwan's central environmental authority mandates heavy-metal discharge reporting for these lines, concentrating capacity among operators with integrated waste-treatment infrastructure in the Hsinchu Science Park corridor.
- Cleaning & Stripping:Solvent and megasonic processes address organic contamination and photoresist residues from device fabrication. Demand concentrates in South Korean foundries where multi-project wafer runs generate frequent strip-and-reclaim cycles for test vehicles and engineering lots.
- Surface Polishing:Mechanical grinding and chemical-mechanical planarization restore sub-nanometer surface roughness specifications.
- Thermal Oxidation:High-temperature oxide growth passivates surface defects and enables thickness-controlled removal.
- Defect Repair:Laser and focused ion beam techniques address micro-pipe and stacking fault densities for premium epitaxial reclaim.
Established volume favors Chemical Etching; emerging adoption favors Defect Repair.
End Use Industry:
Application-specific qualification tiers separate premium reclaim cycles from commodity processing. Automotive power-module suppliers impose substrate provenance documentation that generic LED manufacturers do not require.
- Power Electronics:Electric vehicle inverters and renewable energy converters consume thick epitaxial SiC stacks with stricter defect-density thresholds. AEC-Q101 stress-test protocols for reclaimed substrates open premium pricing tiers unavailable to other end-use segments.
- Semiconductor Foundries:Multi-project wafer services and engineering lots generate continuous reclaim pipelines with faster turnaround requirements. Taiwan and South Korean foundry clusters sustain the highest reclaim volumes globally due to elevated utilization rates.
- LED Manufacturing:GaN-on-SiC epitaxial reclaim for solid-state lighting applications.
- Photovoltaic Cells:Concentrator solar cell substrate recovery with lower surface-quality requirements.
- Microelectromechanical Systems:Sensor and actuator wafer reclaim with specialized thickness tolerances.
Margin concentration sits with Power Electronics; throughput scale sits with Semiconductor Foundries.
Wafer Size:
Substrate diameter determines equipment compatibility and reclaim cycle economics across regional fabrication bases.
- 150 mm:Dominant format for SiC power-device production with established reclaim toolsets and qualified process recipes. Japanese and United States virgin wafer suppliers concentrate output at this diameter, propagating reclaim demand through service tiers.
- 200 mm:Transition format attracting capital investment as foundries scale beyond legacy 100 mm and 150 mm lines. India's PLI scheme incentives for domestic SiC device manufacturing will create captive reclaim demand at this diameter as fabrication scales.
- 100 mm:Legacy diameter for discrete device and research applications.
- 300 mm:Emerging format with limited reclaim infrastructure due to low SiC substrate volumes.
- 450 mm:Not commercially relevant for SiC substrates; included for completeness.
Equipment amortization favors 150 mm; capacity expansion favors 200 mm.
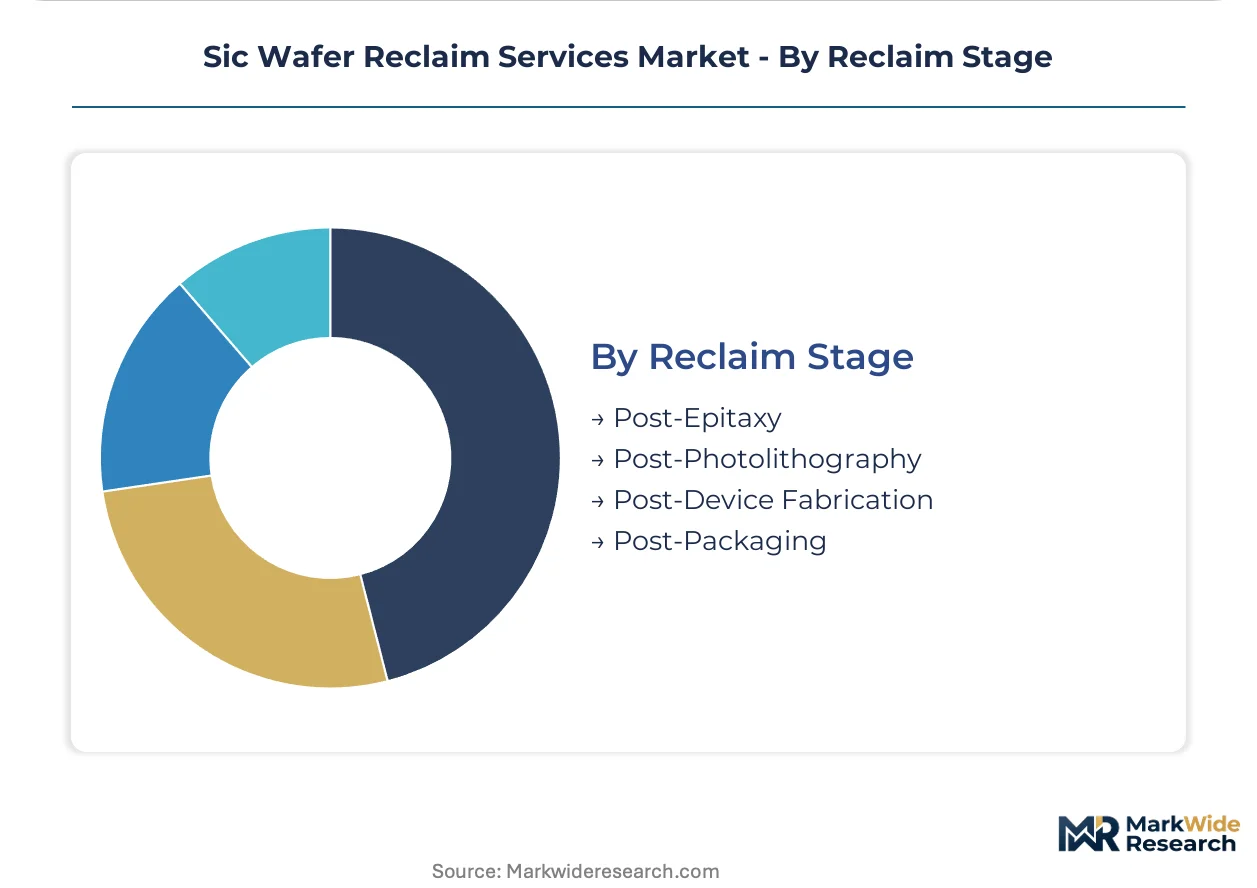
Reclaim Stage:
Insertion point in the manufacturing flow dictates contamination profiles and restoration complexity.
- Post-Epitaxy:Dominant reclaim entry point where thick deposited layers require aggressive removal without substrate damage. Plasma-enhanced chemical etching miniaturizes defect removal resolution for these operations, extending usable wafer life by additional reclaim cycles.
- Post-Device Fabrication:Metal and dielectric contamination from front-end processing requires specialized chemistries. South Korean power-module producers specify substrate provenance and reclaim cycle count in procurement contracts for these stages.
- Post-Photolithography:Photoresist and anti-reflective coating removal with moderate surface damage.
- Post-Packaging:Final-stage reclaim with highest contamination loads and lowest recovery yields.
Value recovery rates favor Post-Epitaxy; processing complexity favors Post-Device Fabrication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in virgin SiC substrates are reshaping where reclaim services concentrate. Countries with limited domestic wafer production rely more heavily on reclaim cycles to offset procurement costs and supply volatility.
China
Domestic power-device foundries in Ningbo and Suzhou consume reclaimed substrates at accelerating rates. The MEE enforces hazardous-waste tracking for spent abrasive slurries, elevating compliance costs for operators in the Yangtze River Delta. Facilities are consolidating processing volumes to amortize fixed environmental investments.
Japan
Automotive power-module suppliers in Nagoya and Kyoto specify substrate provenance documentation in procurement contracts. METI coordinates JIS standards for recycled semiconductor materials, creating multi-month qualification timelines for non-certified reclaim houses. Domestic virgin wafer suppliers concentrate output at 150 mm, propagating reclaim demand through service tiers.
South Korea
Power-module producers in Seoul and Busan pioneered specification intensity for reclaim cycle counts. Foundry utilization rates in the Seoul Capital Area sustain continuous reclaim volume pipelines. The MFDS maintains material traceability protocols that align with automotive qualification requirements.
Taiwan
Multi-project wafer services in Hsinchu generate frequent strip-and-reclaim cycles for engineering lots. The central environmental authority mandates heavy-metal discharge reporting from chemical etching lines. Operators with integrated waste-treatment infrastructure dominate capacity in the Hsinchu Science Park corridor.
United States
Power electronics manufacturers in Texas and Arizona unbundle reclaim services from captive foundry arrangements. The EPA regulates hazardous waste from semiconductor processing under RCRA subtitle C provisions. Southwestern fabrication clusters are contracting directly with specialized reclaim providers to maximize substrate reuse cycles.
Sic Wafer Reclaim Services Market Key Industry Players
Concentration sits with integrated reclaim specialists possessing captive polishing infrastructure and geographic density players sustaining multiple processing nodes. The vendor base organizes into three strategic archetypes: integrated specialists with in-house surface restoration capabilities, geographic density operators with distributed hub networks, and defect-repair specialists occupying narrow premium tiers. Dominant competitive moves include capacity consolidation in East Asian fabrication corridors and technology licensing agreements for plasma-enhanced chemical etching systems.
Among Japan- and Taiwan-based operators, RS Technologies Co., Ltd. and Kinik Company exemplify the integrated specialist archetype through their positioning in premium reclaim cycles. Pure Wafer represents the geographic density model with its sustained presence across North American and Asian processing hubs. These three anchors illustrate how competitive positioning fragments across service modality specialization rather than consolidating around scale alone.
| Leading Market Players |
|---|
| RS Technologies Co., Ltd. |
| Pure Wafer |
| Phoenix Silicon International Corporation |
| Semiconductor Industry Co., Ltd. |
| Mimasu |
| TOPCO Scientific |
| Scientech Corporation |
| Kinik Company |
| NOVA Electronic Materials, LLC |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between power-device foundries and reclaim specialists lock in both substrate supply continuity and multi-year price visibility. These arrangements concentrate pricing power among integrated operators with captive polishing infrastructure in Taiwan and South Korea.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Power electronics manufacturers purchasing AEC-Q101 qualified substrates pay certification premiums, while generic LED reclaim commands lower per-wafer rates. Cost compression in economy tiers is intensifying because China's MEE hazardous-waste tracking mandates elevate fixed compliance burdens. Semiconductor foundries exhibit highest price sensitivity due to high-volume, thin-margin MPW operations.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication, generating continuous reclaim pipelines through elevated foundry utilization. The supply chain draws from Japanese and United States virgin substrate producers, with abrasive consumables and rare earth polishing agents sourced from China. Single-source vulnerability concentrates in qualified virgin wafer supply, where limited qualified producers propagate bottleneck risks. Distribution runs through dedicated logistics corridors serving Hsinchu Science Park and Seoul Capital Area clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across service modalities and certification tiers creates multiple defendable niches for specialized operators. Automotive qualification pathways for reclaimed substrates are splintering procurement patterns and opening pricing premiums.
For Market Incumbents: Fortify integrated polishing infrastructure against geographic density competitors by expanding plasma-enhanced chemical etching capacity in Taiwan. Pursue METI-coordinated JIS certification to capture Japanese automotive power-module contracts. Defend margin position through on-site etchant recovery systems that lower per-wafer processing costs below standalone competitors. For New Entrants and Emerging Players: JIS fast-track certification opens access to Nagoya and Kyoto automotive clusters where substrate provenance documentation commands pricing premiums. Target India's emerging compound semiconductor ecosystem under PLI scheme incentives before captive reclaim infrastructure consolidates. Lead with defect-repair specialization for high-value epitaxial reclaim rather than commodity chemical etching. For Investors and Strategic Acquirers: Capital is best deployed toward integrated specialists with captive surface restoration capabilities and established automotive qualification pathways. Over the projection horizon, consolidation will favor operators with multi-node geographic density and integrated waste-treatment infrastructure. Watch for India's domestic SiC fabrication scale-up as inflection indicator for 200 mm reclaim demand.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma-Enhanced Chemical Etching Adoption | Taiwanese foundries extend substrate life by one to two additional reclaim cycles. |
| JIS Certification Investment | Non-certified reclaim houses face multi-month qualification timelines for Japanese device manufacturers. |
| On-Site Etchant Recovery Systems | Closed-loop chemical regeneration reduces hazardous waste discharge and lowers processing costs. |
| Geographic Expansion to India | PLI scheme incentives for domestic SiC device manufacturing will create captive reclaim demand. |
| Automotive Qualification Pathways | AEC-Q101 stress-test protocols open premium pricing tiers for power-module suppliers. |
Research Approach
A standing panel of reclaim service operations directors, power-device foundry procurement managers, semiconductor equipment engineers, and environmental compliance officers provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with secondary validation against customs records, SEC filings from substrate suppliers, EPA hazardous waste manifests, and METI JIS certification databases. Bottom-up segment sizing triangulated against top-down industry aggregates.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. The analytical framework modeled service type, end-use industry, wafer size, and reclaim stage dimensions. CAGRs were derived from regression analysis of historical reclaim volumes and foundry utilization projections. Forecast inputs incorporated virgin substrate price trajectories and regional environmental compliance cost escalations.
Underlying assumptions cover sustained foundry utilization rates in East Asian clusters, with deviation risk concentrated in substrate supply concentration and rare earth abrasive pricing volatility. Recalibration cycles align with material shifts in automotive qualification requirements and India's PLI scheme implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Vapor Deposition Market
Semiconductor Fabrication
Etching Machine Market
Semiconductor Fabrication
Semiconductor Fab Water Reuse Systems Market
Semiconductor Fabrication
Global Dry Etching Machine Market
Semiconductor Fabrication
Holmium Sputtering Target Market
Semiconductor Fabrication
Solar Grade Wafer Market
Semiconductor Fabrication
Semiconductor Photoresist Polymer Market
Semiconductor Fabrication
Porous Silicon Substrates Market
Semiconductor Fabrication
Global Micromachining Market
Semiconductor Fabrication
Ion Implantation Machine Market
Semiconductor Fabrication
Diamond Semiconductor Substrates Market
Semiconductor Fabrication
Global Foundry Service Market
Semiconductor Fabrication
Thin Layer Deposition Market
Semiconductor Fabrication
Semiconductor Advanced Substrate Market
Semiconductor Fabrication
Additive Manufacturing in Semiconductor Market
Semiconductor Fabrication
Manual Wafer Aligner Market