
 Global Foundry Service Market | 2026-2036
Global Foundry Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Foundry Service Market Analysis
Chiplets and advanced packaging is rewriting how semiconductor systems are architected, enabling modular designs that split monolithic dies into smaller, interconnected components. TSMC leverages its CoWoS and InFO platforms to anchor leadership in high-performance computing and AI accelerators. Samsung Foundry competes aggressively on process node roadmaps, while GlobalFoundries specializes in differentiated silicon for automotive and industrial end markets with less capital-intensive geometries.
Foundry services encompass the outsourced manufacturing of semiconductor wafers and related post-fabrication operations, spanning processes from photolithography at nodes as refined as 3nm to back-end test and assembly. The primary purpose is to convert fabless design house blueprints into physical chips without those firms bearing the full cost of multi-billion-dollar fabrication facilities. Wafer fabrication occupies the largest value pool given its capital intensity and technical barriers, while packaging services represent the fastest-growing margin segment as 2.5D and 3D integration becomes standard for AI and 5G Technologies workloads. Silicon remains the dominant substrate technology, though GaN is gaining traction in power electronics for Automotive Electronics applications where efficiency and thermal performance matter.
REACH and RoHS in Europe restrict hazardous substances in semiconductor manufacturing inputs, while the EU Chips Act directly shapes demand by conditioning state aid on local production targets. In the United States, CHIPS and Science Act disbursements administered through the Department of Commerce require recipients to meet domestic content thresholds and avoid capacity expansion in countries of concern. China's MIIT sets GB standards for domestic foundry equipment qualification, influencing which tool vendors can access its fabrication ecosystem. Stakeholders must monitor how export control alignments between the United States, Japan, and the Netherlands evolve, as these tripartite restrictions on lithography and deposition equipment access determine which foundries can advance to leading nodes and which remain constrained at mature geometries.
Market Dynamics
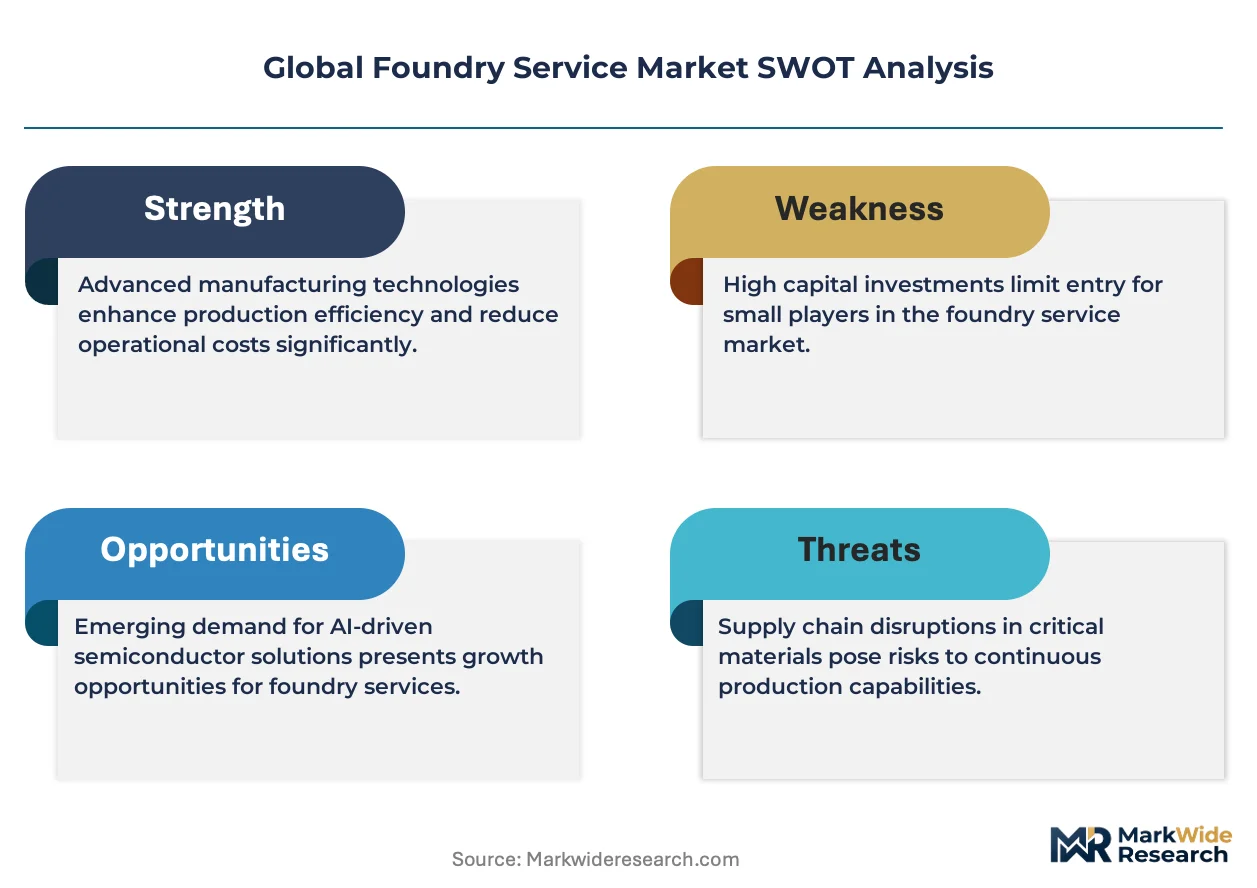
Capital concentration at leading-edge nodes is bifurcating the foundry landscape into a handful of multi-billion-dollar advanced-node operators and a fragmented tier of specialty-geometry suppliers serving automotive and industrial demand.
Growth Catalysts
- EU Chips Act capital allocation:The framework's direct subsidies and loan guarantees are redirecting private investment toward domestic 300mm fab construction in Germany, France, and Italy.
- Automotive chip complexity:Advanced driver-assistance systems and zonal architectures require 16nm to 28nm silicon with automotive-grade reliability, pulling fabless automotive semiconductor designers toward outsourced wafer supply.
- Chiplets architecture:Modular die disaggregation is expanding addressable market for interposer-based packaging and heterogeneous integration services beyond traditional monolithic logic.
Market Restraints
- EUV lithography equipment access:Tripartite export controls between the United States, Japan, and the Netherlands restrict leading-edge tool shipments to specific geographies, capping node advancement for non-aligned foundries.
- 300mm silicon wafer supply:Five Japanese and Taiwanese suppliers control over 80 percent of prime-grade substrate output, creating input cost volatility during demand surges.
- Power consumption physics:Transistor density gains at 3nm and below yield diminishing performance-per-watt improvements, extending ROI timelines for node migration investments.
Strategic Opportunities
- India semiconductor mission:The country's PLI scheme for fabs and ATMP units offers 50 percent capital expenditure reimbursement for first-movers establishing 28nm or larger geometry capacity.
- GaN-on-silicon power integration:Convergence of gallium nitride epitaxy with standard CMOS foundry processes opens high-voltage, high-frequency applications in electric vehicle traction inverters and renewable energy converters.
- Automotive ISO 26262 certification services:Foundries bundling functional safety documentation with wafer supply capture premium positioning as tier-one automotive suppliers consolidate vendor lists.
Industry Challenges
- Process engineer scarcity:Leading-edge etch and deposition expertise concentrates among veterans of five or fewer operational fabs, constraining talent mobility for new market entrants.
- Cleanroom construction timelines:300mm facility build-out requires 36 to 48 months from groundbreaking to first wafer, misaligning capacity ramps with demand cyclicality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Foundry Service Market |
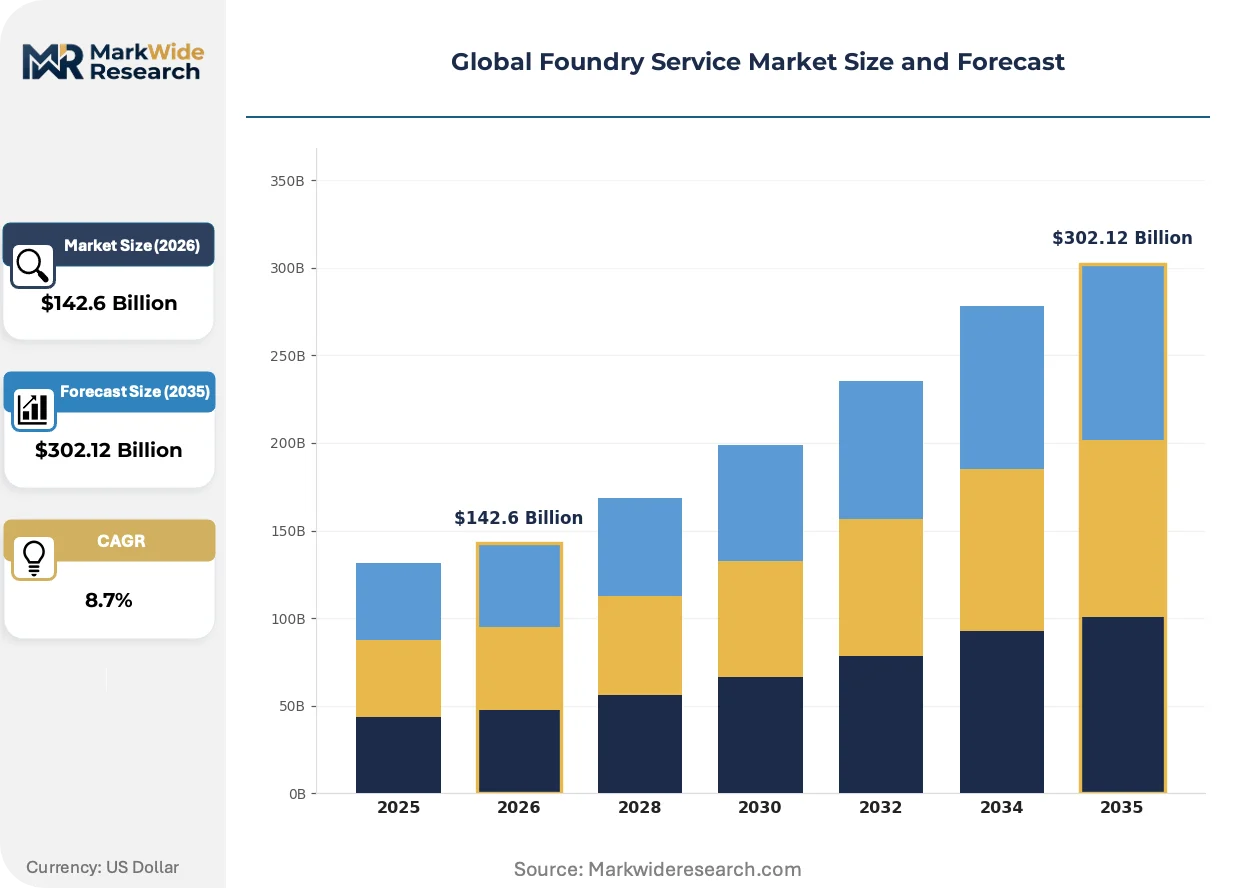
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $302.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
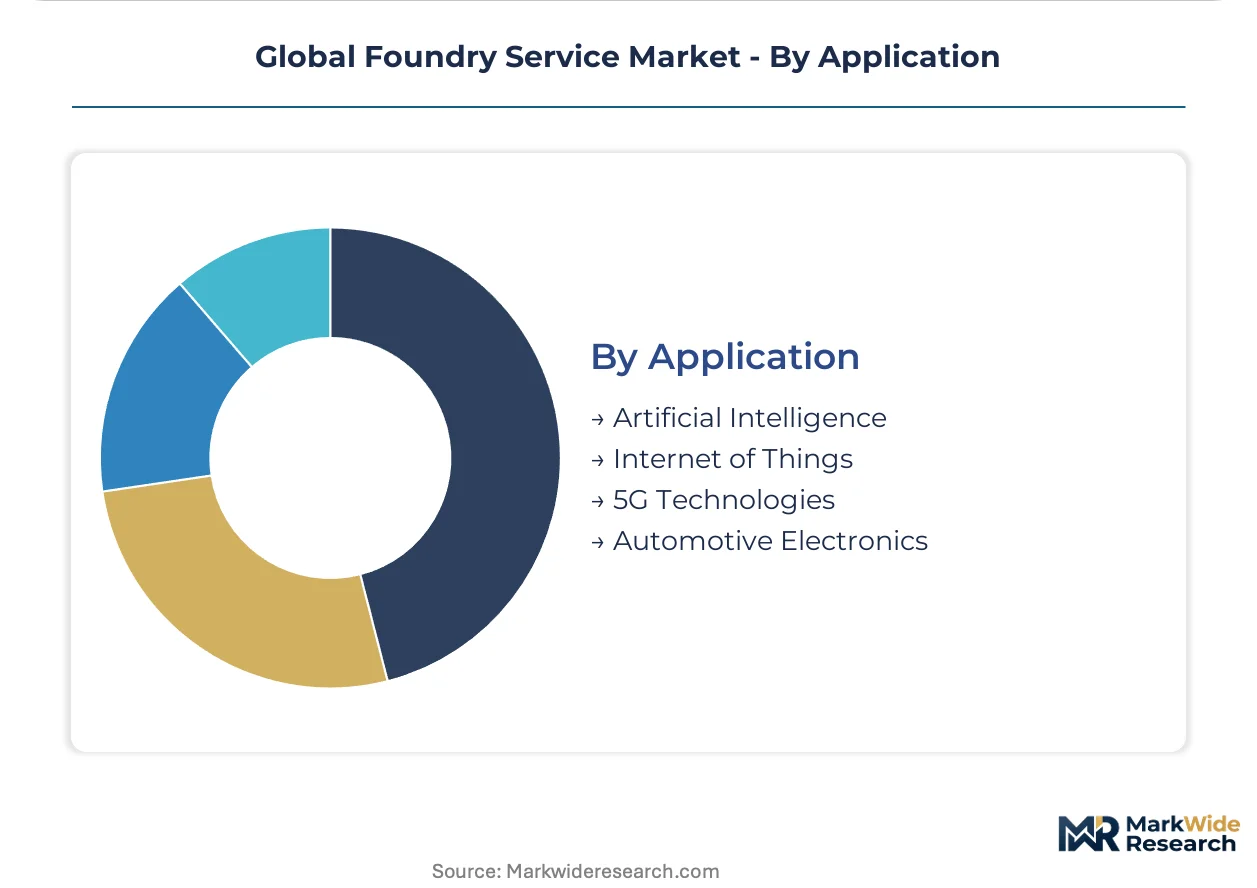
| Segmentation | Service Type: Wafer Fabrication, Test Services, Packaging Services, Design Services End User: Semiconductor Companies, Automotive OEMs, Consumer Electronics, Telecommunication Firms Technology: Silicon, GaN, GaAs, SOI Application: Artificial Intelligence, Internet of Things, 5G Technologies, Automotive Electronics |
| Companies Covered | United Microelectronics Corporation (UMC), Tower Semiconductor, TSMC, Vanguard International Semiconductor (VIS), Powerchip Semiconductor Manufacturing Corporation (PSMC), Samsung Foundry, SMIC, Hua Hong Semiconductor, GlobalFoundries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Foundry Service Market Emerging Trajectories
Foundry service architecture is fragmenting into specialized layers as artificial intelligence workloads force rapid iteration in packaging, memory integration, and substrate technology.
Gate-all-around transistor structures are hybridizing planar and finFET architectures into nanosheet geometries that improve electrostatic control at sub-3nm dimensions. High-performance computing and AI accelerator designers are qualifying these processes for 2025 tape-outs, compressing the performance gap between foundry offerings and forcing second-tier suppliers toward differentiated specialty nodes rather than node-matching competition.
REACH substance restrictions are tightening disclosure requirements for per- and polyfluoroalkyl substances in semiconductor etching chemistries, forcing reformulation of critical cleaning processes. The regulation's industrial consequence extends production qualification timelines by 12 to 18 months for affected wet chemistry suppliers. European automotive and industrial semiconductor buyers are now requiring full material disclosure documentation upstream, shifting procurement criteria toward regulatory-ready foundry partners.
Long-term supply agreements are displacing spot-market wafer purchases as fabless designers prioritize allocation certainty over price optimization. The behavior change concentrates negotiation leverage with foundries possessing visible capacity expansion pipelines, particularly in Taiwan and the United States. This pattern is most visible among AI chip designers securing multi-year CoWoS advanced packaging capacity ahead of product launches.
Global Foundry Service Market Segmentation
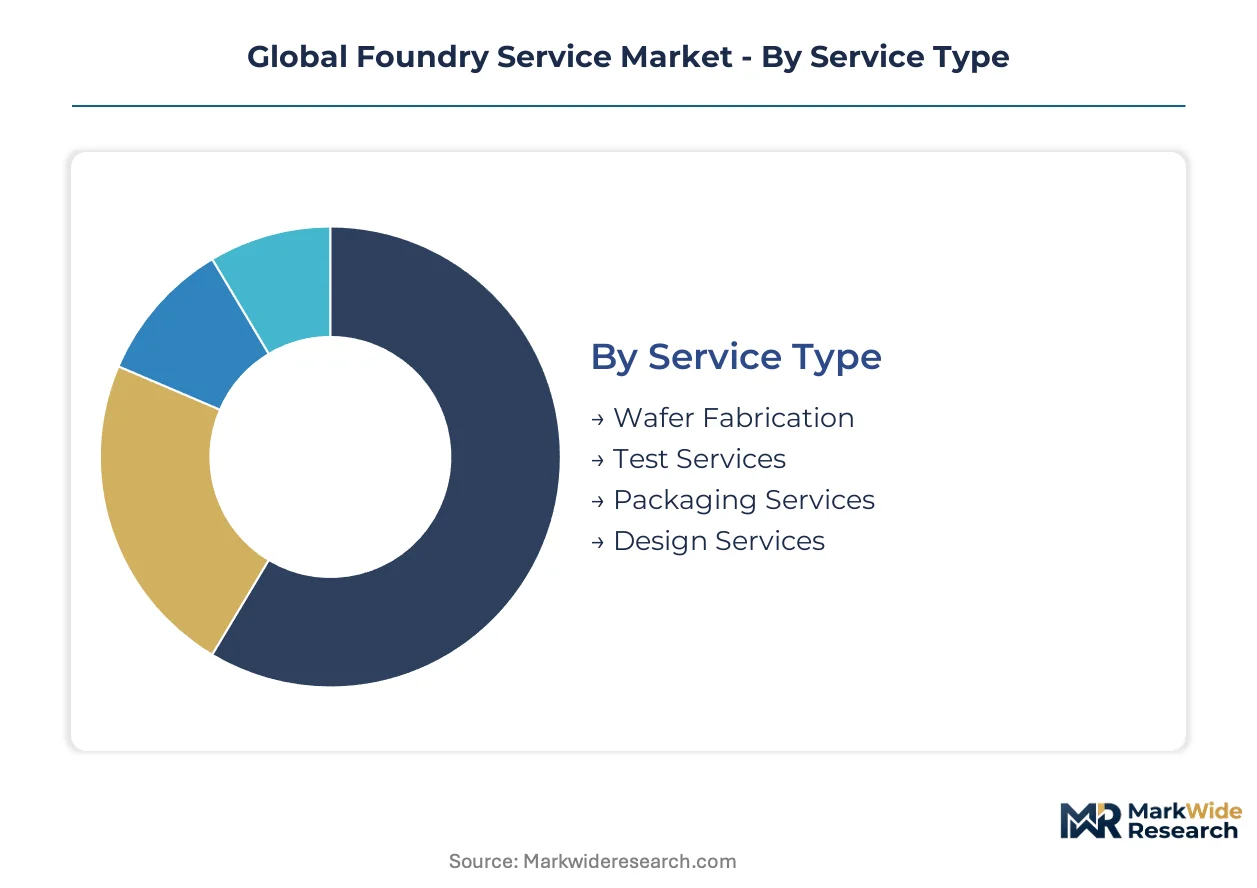
Foundry service segmentation reveals how capital intensity, node specialization, and end-use certification requirements fragment purchasing behavior across customer categories. Distinct technical specifications and regulatory compliance thresholds drive divergent sourcing strategies for each segment cluster.
Service Type:
Mature wafer fabrication commands the largest capital deployment, while emerging packaging services reshape margin structures through advanced interposer technologies.
- Wafer Fabrication:Core manufacturing process converting photomask designs into silicon wafers through photolithography, etch, and deposition sequences. Automotive OEMs in Germany and Japan concentrate demand for 16nm to 28nm geometries with ISO 26262 qualification. EU Chips Act subsidies in Dresden and Crolles accelerate 300mm fab construction for this segment.
- Packaging Services:Post-fabrication die assembly including 2.5D interposers and 3D stacking for heterogeneous integration. AI accelerator designers in Taiwan and the United States secure multi-year CoWoS capacity ahead of product tape-outs. This segment captures expanding margins as chiplets architectures proliferate.
- Test Services:Wafer-level and final package validation ensuring functional compliance across temperature and voltage corners.
- Design Services:Process design kits and IP libraries enabling fabless customers to optimize layouts for specific foundry nodes.
Wafer fabrication handles the majority of throughput; packaging services is the fastest mover on share.
End User:
Customer concentration varies by certification burden, with automotive procurement imposing the steepest qualification requirements.
- Semiconductor Companies:Fabless design houses purchasing wafer supply and advanced packaging without captive fabrication assets. NVIDIA, AMD, and Qualcomm in the United States anchor leading-edge demand for 3nm and 5nm processes. These customers prioritize allocation certainty through long-term supply agreements over spot-market pricing.
- Automotive OEMs:Tier-one suppliers and vehicle manufacturers sourcing automotive-grade silicon for powertrain and ADAS systems. Bosch, Continental, and Denso in Germany and Japan drive demand for 28nm to 40nm geometries with zero-defect reliability protocols. REACH and RoHS compliance documentation now features in procurement criteria.
- Consumer Electronics:Smartphone and wearable manufacturers requiring high-volume, cost-optimized production at mature nodes.
- Telecommunication Firms:Base station and network equipment vendors sourcing RF and mixed-signal components for 5G infrastructure deployment.
Semiconductor companies dominate volume commitment; automotive OEMs command the steepest pricing premium for certified supply.
Technology:
Substrate selection tracks application power density and frequency requirements, with silicon maintaining cost advantage at scale.
- Silicon:Dominant CMOS substrate supporting logic, memory, and mixed-signal integration from 3nm to 180nm geometries. TSMC and Samsung Foundry in Taiwan and South Korea concentrate leading-edge capacity. Mature-node demand from industrial and automotive applications sustains utilization at specialty foundries.
- GaN:Wide-bandgap semiconductor enabling high-voltage, high-frequency power conversion with superior thermal performance. Electric vehicle traction inverters from Tesla, BYD, and Hyundai in the United States and China drive capacity expansion. GaN-on-silicon epitaxy convergence with standard CMOS processes reduces manufacturing cost barriers.
- GaAs:Compound semiconductor for RF and optoelectronic applications requiring high electron mobility.
- SOI:Silicon-on-insulator architectures reducing parasitic capacitance for low-power and RF-specific designs.
Silicon retains the deepest installed base; GaN is climbing the fastest on application expansion.
Application:
Workload characteristics determine packaging complexity and memory integration requirements across end markets.
- Artificial Intelligence:Training and inference accelerators demanding high-bandwidth memory integration and advanced thermal solutions. Hyperscalers in the United States and China contract TSMC CoWoS capacity for GPU and TPU deployments. HBM3 stacking and interposer scaling drive packaging intensity for this segment.
- Automotive Electronics:Zonal architectures and autonomous driving systems requiring functional safety certification and extended temperature operation. European OEMs through Infineon and NXP anchor demand for 22nm FD-SOI and 28nm bulk CMOS. ISO 26262 documentation bundling differentiates qualified foundry suppliers.
- Internet of Things:Low-power edge devices prioritizing cost minimization and extended battery life over performance scaling.
- 5G Technologies:Millimeter-wave and sub-6GHz infrastructure requiring RF-front-end modules with linearity and efficiency specifications.
Artificial intelligence absorbs the most advanced packaging capacity; automotive electronics shows the steepest expansion trajectory on electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan exports foundry services to hyperscalers across the United States and China, while South Korea ships memory-integrated logic to data center operators in North America and Europe. This trade corridor concentration shapes capacity allocation and pricing power across the global fabrication network.
United States
Hyperscalers in California and Washington state contract leading-edge capacity for AI accelerators and cloud infrastructure processors. CHIPS and Science Act disbursements through the Department of Commerce require domestic content thresholds for subsidy recipients. Arizona and Texas host expanding 300mm fab construction targeting 3nm and 5nm geometries for defense and commercial applications.
Taiwan
Fabless designers from NVIDIA, AMD, and Qualcomm anchor demand for CoWoS advanced packaging and 3nm logic production. The island's national development fund coordinates capital allocation toward specialty chemical and equipment supplier ecosystems. Hsinchu Science Park concentrates the highest density of operational 300mm fabs globally, with Taichung and Tainan hosting capacity expansion for 2nm pilot lines.
South Korea
Samsung Electronics and domestic memory suppliers drive demand for EUV-enabled logic and 3D NAND integration. METI-coordinated investments through the K-Semiconductor Belt program target materials and equipment localization. Pyeongtaek and Hwaseong industrial clusters host the country's most advanced 300mm facilities, with Yongin designated for next-generation research fab construction.
China
Domestic fabless designers source mature-node silicon for consumer electronics and industrial control systems amid equipment access constraints. MIIT sets GB standards for domestic foundry equipment qualification, influencing vendor selection for fabrication ecosystems. Shanghai and Beijing municipal governments direct capital toward 28nm and larger geometry capacity in Zhangjiang and Yizhuang technology zones.
Germany
Automotive OEMs through Bosch, Continental, and Infineon contract 22nm to 40nm silicon for powertrain and ADAS applications. EU Chips Act subsidies condition state aid on local production targets for automotive-grade reliability. Dresden anchors European 300mm fab construction, with partnerships targeting FD-SOI and embedded memory technologies for industrial and mobility end markets.
Global Foundry Service Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a bifurcated landscape where capital concentration at leading-edge nodes separates multi-billion-dollar advanced operators from specialty-geometry suppliers. The market structure consolidates around three to four dominant foundries at 5nm and below, while fragmenting across dozens of mature-node providers serving automotive and industrial demand. Strategic archetypes include scale-driven advanced-node specialists, differentiation-focused automotive-grade suppliers, and state-supported domestic champions. Competitive moves center on long-term supply agreement capture and advanced packaging capacity expansion rather than price-based rivalry.
Among Taiwan-based fabricators, TSMC and United Microelectronics Corporation occupy positions at opposite ends of the node spectrum, with the former exemplifying scale-driven advanced-node leadership and the latter representing mature-geometry specialization. Samsung Foundry anchors South Korean state-coordinated capacity expansion. GlobalFoundries exemplifies the automotive-grade supplier archetype through its deliberate avoidance of leading-edge capital intensity. These three named entities collectively represent the strategic diversity visible across the competitive set.
| Leading Market Players |
|---|
| United Microelectronics Corporation (UMC) |
| Tower Semiconductor |
| TSMC |
| Vanguard International Semiconductor (VIS) |
| Powerchip Semiconductor Manufacturing Corporation (PSMC) |
| Samsung Foundry |
| SMIC |
| Hua Hong Semiconductor |
| GlobalFoundries |
| Others |
Supply Flow & Price Mechanics
The Kaohsiung-to-Long Beach container corridor anchors foundry logistics cost dynamics, amplifying pricing power for Taiwan-based operators while forcing European and North American buyers into premium tiers for expedited wafer delivery. Supply concentration across the Taiwan Strait feeds directly into three-tier pricing stratification across automotive-certified, industrial-grade, and consumer-tier foundry services.
Pricing Analysis
Cost-plus contracts indexed to 300mm silicon wafer spot prices dominate long-term supply agreements between fabless designers and tier-one foundries. Price differentiation separates ISO 26262-certified automotive supply from standard industrial silicon through documentation bundling and defect-rate guarantees. Cost compression in mature-node geometries is intensifying as Chinese foundries expand 28nm capacity under MIIT-directed investment programs. Consumer electronics buyers exhibit highest price sensitivity, while AI accelerator designers prioritize allocation certainty over unit economics.
Supply Chain Analysis
Upstream feedstock supply rests on five Japanese and Taiwanese suppliers controlling prime-grade 300mm silicon wafer output. Key inputs include EUV photoresists from JSR and Shin-Etsu, high-purity specialty gases from Air Liquide and Linde, and photomask blanks from Hoya and S&S Tech. Single-source vulnerability concentrates around EUV lithography equipment where ASML holds effective monopoly. Distribution runs through direct foundry-to-fabless contracts with minimal intermediary presence, though ATMP units in Southeast Asia handle backend assembly overflow.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Foundry Service Market constitutes a high-growth disruption as EUV lithography access restrictions under tripartite export controls permanently bifurcate competitive positioning between leading-edge and mature-node operators.
For Market Incumbents: Harden geographic diversification by qualifying secondary fab locations in Germany and the United States under CHIPS Act subsidy frameworks. Deepen backward integration into specialty chemical supply through captive production of high-purity etchants and photoresists, insulating margin structures from JSR and Fujifilm pricing volatility. Lock in multi-year CoWoS capacity commitments from NVIDIA and AMD before Chinese foundries mature interposer capabilities. For New Entrants and Emerging Players: Pursue automotive-grade silicon certification as the most penetrable white space, where Bosch and Continental consolidate vendor lists around qualified European suppliers. Target India's PLI-subsidized 28nm fab construction through equipment supply partnerships with domestic ATMP units. Lead go-to-market efforts with ISO 26262 documentation bundling to capture premium positioning absent from commodity foundry offerings. For Investors and Strategic Acquirers: Mature-node specialists with automotive certification infrastructure present the most defensible acquisition profile for long-term viability across the five-to-ten-year window. Foundries possessing FD-SOI process expertise and zero-defect qualification protocols command scarcity premiums as electrification mandates accelerate. Monitor tripartite export control alignment between the United States, Japan, and the Netherlands as the critical inflection signal for node advancement access.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | TSMC and Samsung Foundry secure multi-year CoWoS commitments from hyperscalers ahead of AI accelerator tape-outs. |
| Backward Integration | GlobalFoundries deepens captive supply of automotive-grade substrates to reduce dependence on Shin-Etsu wafer pricing. |
| Geographic Expansion | Intel Foundry Services qualifies Arizona capacity for Department of Commerce CHIPS Act disbursement recipients. |
| Certification Investment | UMC accelerates ISO 26262 documentation capabilities to capture Bosch powertrain silicon procurement. |
| Technology Licensing | Samsung Foundry licenses FD-SOI process IP to European automotive semiconductor designers through Crolles partnerships. |
Methodological Framework
Desk research of SEMI equipment shipment databases, customs wafer trade records, and CHIPS Act disbursement filings preceded structured interviews with foundry operations executives, fabless design house procurement leads, automotive tier-one supplier quality managers, and EUV equipment vendor technical specialists. Bottom-up capacity utilization models triangulated against top-down foundry revenue disclosures from SEC 10-K and TSE filings.
Assumptions around EUV tool delivery schedules, 300mm wafer pricing trajectories, and automotive semiconductor content per vehicle were held fixed across baseline scenarios while node migration timelines and subsidy disbursement rates were stress-tested. Segmentation modeling spanned service type, end-user certification tier, substrate technology, and regional production cluster. CAGRs derived from installed base depreciation curves and capital expenditure pipeline visibility, with AI accelerator demand and automotive electrification mandates as primary volume drivers.
Sensitivities concentrate around tripartite export control enforcement intensity and 300mm silicon wafer supply disruptions. Forecasts reflect documented assumptions regarding equipment access permissions and subsidy program continuity. Cross-checking against SEMI capital equipment forecast benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Additive Manufacturing in Semiconductor Market
Semiconductor Fabrication
Physical Vapor Deposition (PVD) Market
Semiconductor Fabrication
Semiconductor Foundry Market
Semiconductor Fabrication
Porous Silicon Substrates Market
Semiconductor Fabrication
8-Inch Silicon Carbide (Sic) Wafer Market
Semiconductor Fabrication
Semiconductor Fab Water Reuse Systems Market
Semiconductor Fabrication
300mm Silicon Wafers Market
Semiconductor Fabrication
Epitaxial Wafer Market
Semiconductor Fabrication
Thin Layer Deposition Market
Semiconductor Fabrication
Etching Machine Market
Semiconductor Fabrication
Solar Grade Wafer Market
Semiconductor Fabrication
Semiconductor Etching Cleaner Market
Semiconductor Fabrication
Solar Ingot Wafer Market
Semiconductor Fabrication
Global Dry Etching Machine Market
Semiconductor Fabrication
Diamond Semiconductor Substrates Market
Semiconductor Fabrication
Ion Implanter Market