
 Wafer Processing Equipment Market | 2026-2036
Wafer Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Wafer Processing Equipment Market Analysis
Subscription-style service contracts for predictive maintenance and software-defined process optimization is hardening as a distinct revenue layer in wafer processing equipment. Applied Materials leverages its installed base to sustain recurring revenue through field service agreements. Tokyo Electron anchors its competitive stance through deep integration of chamber hardware with proprietary process control algorithms. ASML dominates lithography service intensity, where uptime guarantees and remote diagnostics now rival equipment sales in margin contribution.
Wafer processing equipment encompasses the specialized machinery used to transform bare silicon wafers into patterned semiconductor devices through sequential deposition, etching, ion implantation, and cleaning steps, typically operating at sub-10 nanometer precision thresholds in leading-edge nodes. Etch systems command substantial capital allocation as three-dimensional transistor architectures multiply etch steps per wafer, while deposition systems face accelerating demand from gate-all-around transistor transitions. Clean tools occupy a mature yet indispensable position, with margin pools concentrating in solvent recycling and contamination detection subsystems rather than base equipment sales.
Equipment qualification under SEMI standards, EPA emissions protocols for perfluorinated compounds, and FDA oversight for medical-grade MEMS fabrication collectively shape product design cycles and factory certification timelines. The EU F-Gas Regulation and REACH chemical restrictions are tightening process chemistry specifications, forcing equipment vendors to redesign gas delivery and abatement systems. Stakeholders must monitor how subsidy clawback provisions in the CHIPS Act and analogous frameworks alter equipment depreciation schedules and resale value recovery.
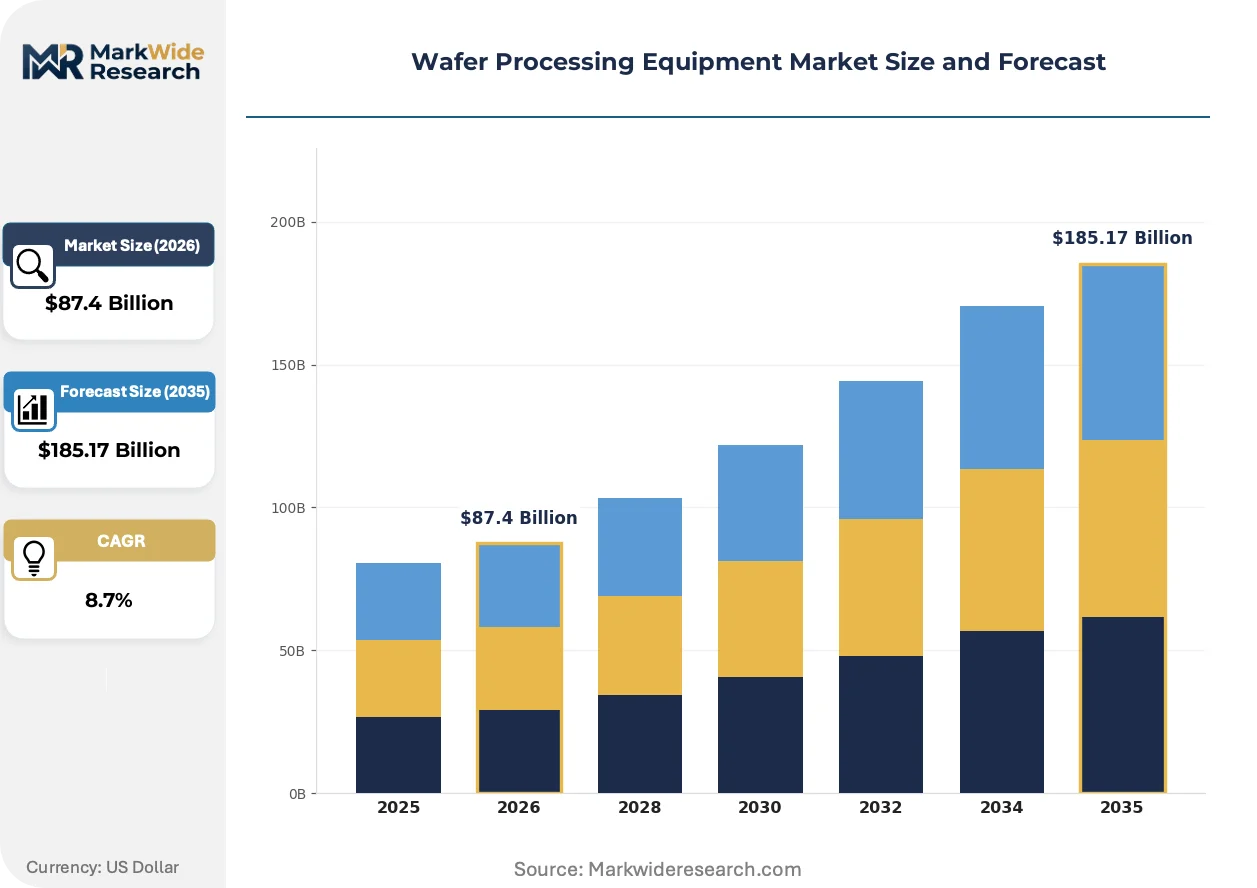
Market Dynamics
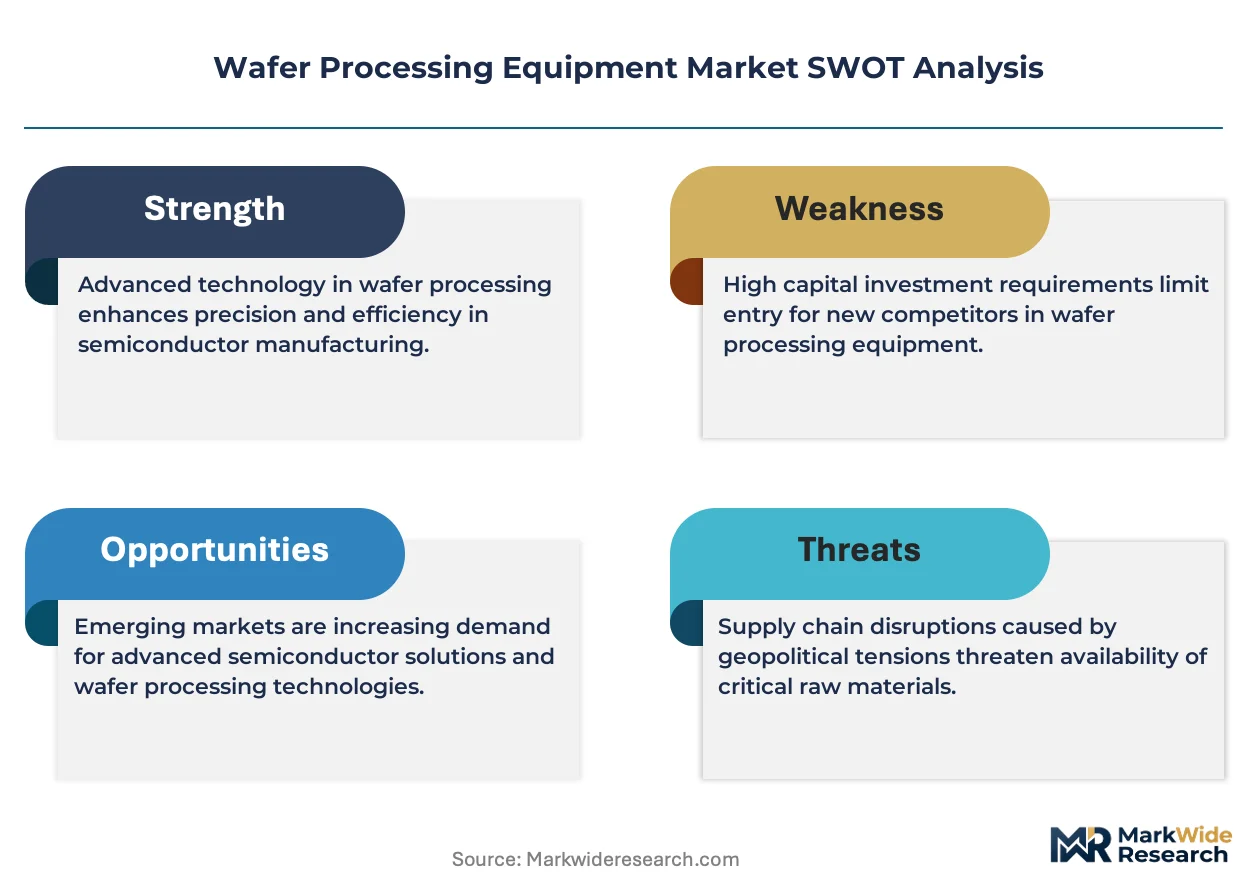
Gate-all-around transistor transitions are multiplying process steps per wafer while compressing equipment qualification windows, forcing foundries to synchronize tool procurement with node-specific yield ramps rather than generic capacity planning.
Growth Catalysts
- CHIPS Act subsidy frameworks:Equipment depreciation acceleration clauses in US legislation are pulling forward procurement timelines for 300mm advanced-node tools.
- Three-dimensional NAND stacking:String stacking architectures above 200 layers are multiplying etch and deposition cycles per wafer, expanding tool utilization rates.
- Taiwan cluster concentration:Foundry capex commitments in Hsinchu and Tainan Science Parks are anchoring lithography and metrology equipment demand.
Market Restraints
- Fluorinated gas abatement mandates:EU F-Gas Regulation compliance is forcing $2-4 million retrofits per etch chamber for plasma emission capture systems.
- Specialized component supply:Ceramic heater and electrostatic chuck production concentrates in Japanese suppliers, creating single-source vulnerability for high-temperature process tools.
- Dimensional scaling limits:EUV multi-patterning complexity is extending equipment development cycles beyond 36 months for sub-3nm nodes.
Strategic Opportunities
- India fab incentives:PLI scheme and state-level semiconductor policies are creating first-mover equipment positioning in Gujarat and Karnataka greenfield sites.
- Predictive maintenance platforms:Sensor fusion and machine learning integration is enabling subscription revenue models tied to chamber uptime guarantees.
- Silicon carbide power device fabrication:Automotive electrification is opening deposition and ion implantation tool demand outside traditional logic foundry channels.
Industry Challenges
- Process engineer scarcity:Deep expertise in atomic layer deposition recipe development is concentrating at leading-edge fabs, constraining second-tier foundry expansion.
- SEMI S2/S8 certification timelines:Safety and interoperability validation for multi-vendor tool clusters is extending factory acceptance test periods by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wafer Processing Equipment Market |
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $185.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Etch Systems, Deposition Systems, Ion Implantation, Clean Tools End User: Semiconductor Manufacturers, Research Institutions, Foundries, Fabless Companies Technology: Chemical Vapor Deposition, Molecular Beam Epitaxy, Atomic Layer Deposition, Photo-etching Application: Integrated Circuits, MEMS, Photonics, Power Devices |
| Companies Covered | Applied Materials, ASML, Tokyo Electron, Lam Research, KLA Corporation, DISCO Corporation, ASM International, Nikon Precision, SCREEN Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wafer Processing Equipment Market Emerging Trajectories
Equipment architectures are converging around software-defined process control, with hardware vendors competing through algorithmic differentiation rather than chamber specifications alone. This shift is compressing the traditional boundary between tool OEMs and fab automation layers.
Hybrid bonding equipment is unifying die-to-wafer and wafer-to-wafer attachment processes previously served by distinct tool categories. Memory manufacturers in South Korea are deploying these systems at 128-layer NAND and above. The technology is unifying front-end and advanced packaging equipment procurement decisions under single vendor relationships.
EPA perfluorinated compound emissions protocols are tightening abatement efficiency requirements from 90% to 95% destruction removal efficiency for etch process exhaust. Equipment vendors are redesigning thermal and plasma abatement subsystems to meet the standard. Clean tool manufacturers in Germany and the US are capturing margin expansion through integrated abatement module sales.
Service contract unbundling is separating predictive maintenance software licenses from field engineering support. Foundries in Taiwan are negotiating standalone algorithm subscriptions while retaining third-party service providers for hardware maintenance. The model is most visible among 300mm mature-node facilities seeking to reduce fixed cost structures.
Wafer Processing Equipment Market Segmentation
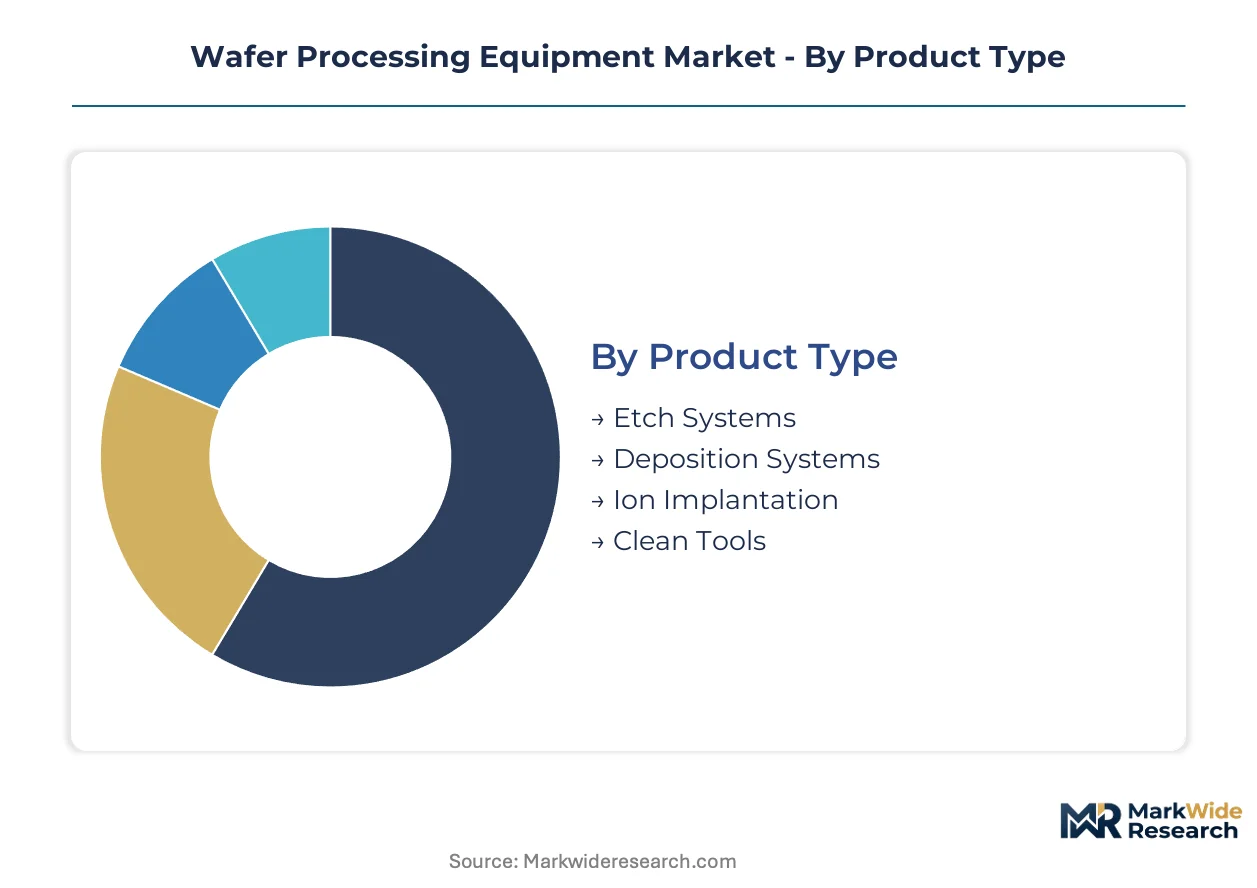
Wafer processing equipment segmentation reveals divergent capital intensity profiles across product categories, with lithography-adjacent tools commanding premium procurement cycles while mature segments compete through service attach rates. Equipment vendors calibrate R&D allocation and field service deployment based on these structural differences in buyer economics and replacement frequency.
Product Type:
Etch systems absorb the heaviest upfront capital burden per chamber, driven by multi-step patterning complexity in three-dimensional transistor architectures.
- Etch Systems:Plasma and wet etch platforms execute material removal with sub-nanometer selectivity across dielectric and metal films. Taiwan-based foundries in Hsinchu Science Park are expanding reactive ion etch fleets for gate-all-around transistor transitions, though fluorinated gas abatement retrofits add $2-4 million per chamber under EU F-Gas Regulation mandates.
- Deposition Systems:Chemical and physical vapor deposition tools deposit thin-film layers with atomic-scale thickness control. South Korean memory manufacturers in Pyeongtaek are driving atomic layer deposition demand for 200-plus layer NAND stacking, where each string multiplication adds deposition cycles per wafer.
- Ion Implantation:High-current and medium-current beam systems dope silicon with precise impurity concentrations. Automotive electrification is pulling silicon carbide power device fabrication into this segment's addressable market.
- Clean Tools:Wet benches and single-wafer cleaners remove particulate and chemical residues between process steps. Margin capture concentrates in solvent recycling subsystems and real-time contamination detection modules rather than base equipment.
Most installed capacity flows through Etch Systems. Expansion is steepest in Deposition Systems.
End User:
Procurement scale and technical specification authority vary sharply across buyer types, with foundries exercising the most concentrated purchasing power.
- Semiconductor Manufacturers:Integrated device manufacturers operate captive fabs with tool standardization across multiple process nodes. Intel's Arizona and Ohio investments exemplify the long depreciation schedules and vendor consolidation patterns typical of this segment.
- Foundries:Pure-play contract manufacturers procure at the largest single-facility scale, synchronizing tool qualification with customer-specific node ramps. Taiwan Semiconductor Manufacturing anchors global lithography and metrology demand through Tainan and Taichung greenfield expansions.
- Fabless Companies:Design houses without fabrication assets influence equipment selection indirectly through process development partnerships and multi-project wafer commitments.
- Research Institutions:Universities and national laboratories operate lower-utilization tools for process characterization and workforce training. Equipment vendors tolerate compressed margins here for talent pipeline access and early technology validation.
Foundries command the largest order volumes. Fabless Companies are gaining specification influence fastest.
Technology:
Process control complexity and chamber architecture differentiation determine vendor competitive moats within each deposition and patterning modality.
- Chemical Vapor Deposition:Thermal and plasma-enhanced CVD platforms deposit polysilicon, silicon nitride, and tungsten films at high throughput. Leading-edge logic transitions to gate-all-around transistors are multiplying CVD steps per wafer.
- Atomic Layer Deposition:Self-limiting surface reactions enable angstrom-level thickness precision for high-k dielectrics and work function metals. Process engineer scarcity in ALD recipe development is constraining second-tier foundry expansion.
- Molecular Beam Epitaxy:Ultra-high vacuum systems grow crystalline compound semiconductor layers for photonics and RF applications. III-V materials integration with silicon photonics is expanding MBE demand beyond traditional optoelectronics.
- Photo-etching:Lithography-adjacent wet and dry patterning techniques complement EUV and DUV exposure systems. Multi-patterning complexity at sub-3nm nodes is extending development cycles beyond 36 months.
Atomic Layer Deposition carries the steepest technical premium. Chemical Vapor Deposition maintains the broadest installed base.
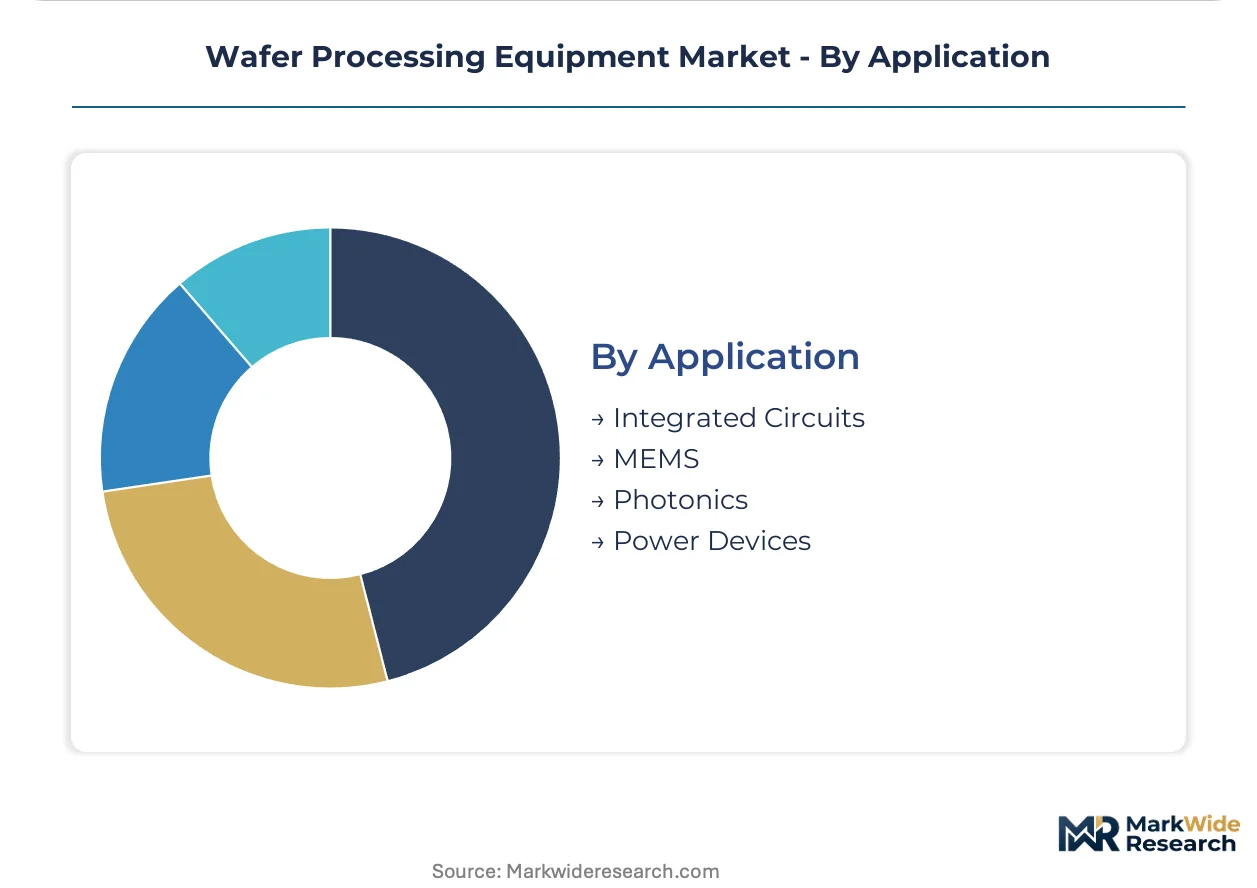
Application:
End-market diversification is accelerating as automotive and industrial demand decouples equipment procurement from consumer electronics cycles.
- Integrated Circuits:Logic and memory devices consume the majority of etch, deposition, and clean tool capacity. Advanced node production at 3nm and below requires synchronized multi-vendor tool clusters with extended SEMI S2/S8 certification timelines.
- Power Devices:Silicon carbide and gallium nitride fabrication for electric vehicle inverters and charging infrastructure is opening deposition and ion implantation demand outside traditional logic foundry channels.
- MEMS:Microelectromechanical systems for sensors and actuators require specialized deep reactive ion etch and wafer bonding equipment. FDA oversight for medical-grade MEMS fabrication shapes factory certification protocols.
- Photonics:Silicon photonics and III-V laser fabrication demand precise epitaxial growth and facet etch capabilities. Datacenter optical interconnect buildouts are concentrating demand in specific foundry partnerships.
Integrated Circuits dominate current installed capacity. Power Devices are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan concentrates more lithography and metrology procurement per square kilometer than any comparable geography, while the United States is pulling forward depreciation schedules through subsidy acceleration clauses that compress traditional procurement timelines.
United States
Intel's Arizona and Ohio fab investments anchor domestic etch and deposition demand as the CHIPS Act accelerates equipment depreciation timelines. EPA perfluorinated compound emissions protocols mandate 95% destruction removal efficiency for etch process exhaust, forcing subsystem redesigns. The Phoenix-Tucson corridor hosts expanding 300mm advanced-node capacity.
Taiwan
TSMC's Tainan and Taichung greenfield expansions drive synchronized lithography and metrology procurement with customer-specific node ramps. The island's national semiconductor strategy reinforces foundry cluster concentration. Hsinchu Science Park anchors reactive ion etch fleet expansion for gate-all-around transitions.
South Korea
Samsung and SK Hynix in Pyeongtaek multiply atomic layer deposition cycles for 200-plus layer NAND stacking. MFDS oversight shapes medical-grade MEMS fabrication protocols for select facilities. The Seoul Capital Area concentrates memory-specific clean tool and ion implantation demand.
Japan
Tokyo Electron and SCREEN Holdings anchor domestic ceramic heater and electrostatic chuck supply chains for high-temperature process tools. METI industrial policy reinforces equipment vendor ecosystem development. Kyoto-Osaka corridor facilities specialize in chamber hardware and process control algorithm integration.
India
Gujarat and Karnataka greenfield sites attract first-mover equipment positioning under the PLI scheme and state-level semiconductor policies. BIS certification requirements shape factory acceptance test protocols for imported tools. The Dholera Special Investment Region hosts emerging fab infrastructure with concentrated deposition and clean tool procurement.
Wafer Processing Equipment Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with lithography-adjacent tools consolidating around single-source vendors while etch and deposition platforms fragment across multi-vendor clusters. The vendor base organizes into three strategic archetypes: full-stack platform providers, chamber-hardware specialists, and software-defined process control vendors. M&A activity concentrates on predictive maintenance platform acquisitions, while geographic expansion targets India and Southeast Asia greenfield sites.
Within the full-stack platform tier, Applied Materials and Lam Research occupy positions as integrated equipment vendors with extensive installed bases. ASML exemplifies the lithography-specialist archetype through extreme ultraviolet system dominance. Tokyo Electron represents the chamber-hardware-plus-algorithms model with deep process control integration.
| Leading Market Players |
|---|
| Applied Materials |
| ASML |
| Tokyo Electron |
| Lam Research |
| KLA Corporation |
| DISCO Corporation |
| ASM International |
| Nikon Precision |
| SCREEN Holdings |
| Others |
Supply Flow & Price Mechanics
Captive backward integration into ceramic heater and electrostatic chuck production anchors pricing power for Japanese chamber-hardware specialists, while outsourced gas delivery subsystem sourcing exposes European etch tool vendors to margin compression under EU F-Gas Regulation compliance mandates. This integration divergence separates vendors who control critical thermal components from those absorbing abatement retrofit costs passed through from third-party suppliers.
Pricing Analysis
Capacity additions in the United States are reshaping price floors for 300mm advanced-node tools as CHIPS Act depreciation acceleration clauses compress procurement timelines. Three-tier pricing structure across premium, standard, and economy levels stratifies by chamber uptime guarantee tiers and predictive maintenance software bundling. Cost compression in mature-node clean tools is intensifying because foundries in Taiwan unbundle algorithm subscriptions from field engineering support. Fabless companies exercising indirect specification influence prove least price-sensitive, while research institutions operating lower-utilization tools for workforce training face compressed margins.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme and state-level semiconductor policies are reshaping sourcing patterns for greenfield fab equipment in Gujarat and Karnataka. Ceramic heaters and electrostatic chucks draw from Japanese suppliers, fluorinated gas delivery systems rest on German and US clean tool manufacturers, and high-purity process gases hinge on regional chemical specialists. Single-source vulnerability for high-temperature process components creates structural risk. Distribution runs through direct OEM-fab procurement relationships with extended SEMI S2/S8 certification timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between subsidy-rich US depreciation acceleration and Taiwan's concentrated foundry cluster scale, with equipment vendors capturing margin expansion in the former through premium uptime guarantees and facing price compression in the latter through unbundled service contracts.
For Market Incumbents: Acquire predictive maintenance platform capabilities to defend against software-defined process control vendors encroaching on chamber-hardware margins. Backward integration into ceramic heater production mitigates single-source supply risk from Japanese suppliers. Certification investment in EU F-Gas Regulation-compliant abatement subsystems captures retrofit demand pull-through. For New Entrants and Emerging Players: Second-tier foundries in India and Southeast Asia represent underserved buyer archetypes lacking atomic layer deposition recipe development expertise. White-space targets include silicon carbide power device fabrication for automotive electrification and medical-grade MEMS clean tools under FDA oversight. Go-to-market angle centers on bundled chamber hardware with third-party algorithm subscriptions. For Investors and Strategic Acquirers: Roll-up economics work for predictive maintenance platform specialists because service contract unbundling separates software licenses from field engineering support. Long-term viability favors vendors with installed base density enabling recurring revenue conversion. Watch SEMI S2/S8 certification timeline extensions as inflection indicator for factory acceptance test bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Acquisition | Applied Materials leverages installed base density to sustain recurring revenue through field service agreements. |
| Abatement Subsystem Redesign | EPA 95% destruction removal efficiency mandates force thermal and plasma subsystem overhauls for etch process exhaust. |
| Hybrid Bonding Equipment Deployment | Samsung and SK Hynix unify front-end and advanced packaging procurement under single vendor relationships. |
| India Greenfield Site Positioning | BIS certification requirements shape factory acceptance test protocols for imported tools in Gujarat and Karnataka. |
| Gate-All-Around Process Control Integration | Tokyo Electron anchors competitive stance through deep chamber hardware integration with proprietary algorithms. |
Methodological Framework
Bottom-up foundry capex modeling reconciled against top-down equipment vendor shipment tracking forms the analytical core of this study. Primary interviews with fab process engineers, OEM procurement directors, chamber hardware R&D leads, and aftermarket service heads combined with secondary validation from SEMI industry reports, EPA emissions filings, and CHIPS Act subsidy disclosure databases. Triangulation across these sources ensures segmentation integrity.
Input-output matrices map etch, deposition, and clean tool demand across technology nodes, end-use applications, and regional regulatory clusters. Modeled dimensions span equipment type, foundry versus integrated device manufacturer buyer archetype, process technology, and target application. CAGRs derive from node-specific yield ramp synchronization and greenfield fab investment trajectories. Forecast inputs incorporate EU F-Gas Regulation compliance cost pass-through and predictive maintenance subscription attach rates.
Underlying measurement precision varies by segment; lithography-adjacent tools carry tighter precision than mature clean equipment due to concentrated vendor disclosure. Forecasts reflect assumptions around subsidy clawback provisions and node transition timelines. Semiconductor cycle volatility and fluorinated gas abatement mandate evolution present revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Global Battery Manufacturing Equipment Market
Semiconductor Equipment
Semiconductor POD Cleaner Market
Semiconductor Equipment
X-Ray Lithography Equipment Market
Semiconductor Equipment
Die Bonder Equipment Market
Semiconductor Equipment
Epitaxy Equipment Market
Semiconductor Equipment
Asia-Pacific Semiconductor Etch Equipment Market
Semiconductor Equipment
Global Semiconductor Back-End Equipment Market
Semiconductor Equipment
Multi-Touch Equipment Market
Semiconductor Equipment
Plasma Etch System Market
Semiconductor Equipment
Semiconductor Laser Equipment Market
Semiconductor Equipment
Semiconductor Assembly Equipment Market
Semiconductor Equipment
Asia-Pacific Aligner Sheet Market
Semiconductor Equipment
FOUP Load Port Market
Semiconductor Equipment
PVD Coaters Market
Semiconductor Equipment
Vacuum Spin Coaters Market
Semiconductor Equipment
Europe Chip Mounter Market