
 Global Micromachining Market | 2026-2036
Global Micromachining Market Size, Share, and Industry Trends Forecast 2026-2036
Global Micromachining Market Intelligence
Leasing and asset-light project finance is narrowing the capital barrier for precision equipment entrants. TRUMPF GmbH + Co. KG leverages its captive laser source technology to sustain margin control across the value chain. Sodick Co., Ltd. anchors its position through deep specialization in electrical discharge machining architectures. Coherent, Inc. competes by extending vertical reach from photonics components into integrated micromachining systems.
Micromachining encompasses material removal and shaping processes operating at micron-scale tolerances, typically employing pulsed lasers, electro-erosion, or mechanical micro-tools to achieve surface finishes below Ra 0.1 micrometers for features under 500 micrometers. The discipline serves critical functions in semiconductor die singulation, stent fabrication, and MEMS cavity definition where conventional machining lacks resolution. Laser micromachining dominates current installed capacity due to its non-contact nature and compatibility with brittle substrates like silicon wafers and ceramics. Electrical discharge machining retains structural importance in conductive metal geometries where thermal damage must be eliminated. MEMS devices and microfluidics represent the fastest-expanding application clusters as miniaturized sensing and lab-on-chip architectures proliferate across diagnostics and telecommunications equipment.
FDA device regulations and EU MDR conformity requirements shape biocompatibility and traceability standards for medical implant micromachining, while REACH and RoHS frameworks in Europe restrict hazardous substances in processed polymers and coatings. Japan's METI promotes domestic precision manufacturing through JIS standard harmonization and advanced tooling subsidies. Stakeholders must monitor evolving dual-use export controls on ultraviolet laser sources and coordinate qualification strategies across divergent regional certification pathways.
Market Dynamics
Laser source consolidation and captive photonics manufacturing are compressing equipment margins while FDA and EU MDR biocompatibility protocols force medical implant fabricators toward higher-precision subtractive processes.
Growth Catalysts
- EU MDR traceability mandates:Medical device manufacturers in Germany and Switzerland are retrofitting production lines with laser micromachining systems to meet serialized implant documentation requirements under the 2017/745 framework.
- Silicon carbide wafer expansion:Power semiconductor foundries in Japan are scaling femtosecond laser dicing capacity to handle brittle wide-bandgap substrates for electric vehicle inverters.
- METI precision tooling subsidies:Domestic equipment vendors in Nagoya and Osaka clusters are accessing JIS-standard harmonization grants to accelerate MEMS cavity etching tool development.
Market Restraints
- Ultraviolet laser source concentration:German and US suppliers control 193nm and 248nm excimer laser crystal growth, creating single-source vulnerability for semiconductor via-drilling equipment.
- Platinum-group metal volatility:Electrical discharge machining electrode costs fluctuate with South African and Russian palladium supply disruptions, pressuring job shop profitability.
- RoHS substance restrictions:European REACH Annex XVII limits on hexavalent chromium coatings force aerospace micromachining facilities to qualify alternative passivation chemistries.
Strategic Opportunities
- India PLI scheme for semiconductors:Gujarat and Tamil Nadu greenfield fabs offer 25-50% capital expenditure reimbursement for precision lithography and singulation equipment.
- Neural interface electrode arrays:Utah array and Michigan probe geometries under 50 micrometers require combined laser ablation and electroplating process integration.
- China dual carbon targets:NMPA green channel registration and MIIT energy efficiency standards favor domestic suppliers of low-power fiber laser micromachining platforms.
Industry Challenges
- Multi-physics simulation expertise:Coupled thermal-mechanical-optical modeling for ultrashort pulse laser ablation requires physicists and materials scientists rarely available outside Aachen, Stuttgart, and MIT corridors.
- ISO 13485 certification timelines:Medical implant subcontractors face 12-18 month quality management system audits before qualifying for stent and catheter micromachining contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Micromachining Market |
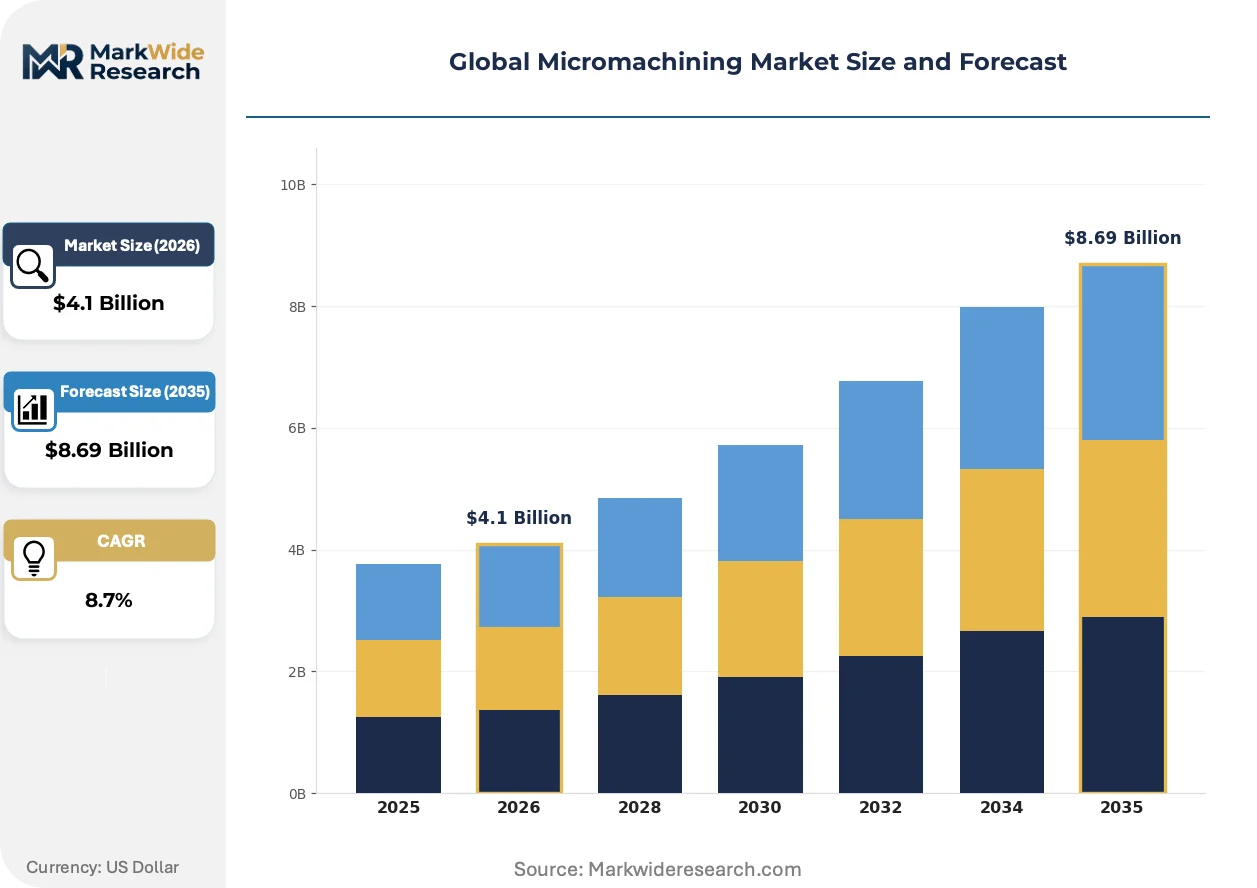
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $8.69 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Process Type: Laser Micromachining, Electrical Discharge Machining, Micro Milling, Ultrasonic Machining, Chemical Etching Material Type: Metals, Ceramics, Polymers, Composite Materials, Silicon Wafers End Use Industry: Semiconductor Fabrication, Aerospace Components, Precision Instrumentation, Wearable Devices, Telecommunications Equipment Market Application: Microfluidics, MEMS Devices, Medical Implants, Optical Components, Microelectronics |
| Companies Covered | Mitsubishi Heavy Industries Ltd., Sodick Co., Ltd., TRUMPF GmbH + Co. KG, Jenoptik AG, Amada Co., Ltd., IPG Photonics Corporation, Makino Milling Machine Co., Ltd., Renishaw plc, Coherent, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Micromachining Market Strategic Shifts & Innovations
Ultrafast laser technology and computational beam shaping are collapsing process development cycles while regulatory data integrity requirements force equipment vendors toward embedded metrology and closed-loop control architectures.
Femtosecond infrared and ultraviolet lasers are collapsing thermal damage zones in transparent material processing. Medical device manufacturers in Ireland and Minnesota are adopting burst-mode ablation for bioabsorbable stent scoring. This technology is collapsing the distinction between rough cutting and finishing operations in polymer micromachining workflows.
EU MDR Article 10 technical documentation requirements now mandate process validation records for every implant lot. German notified bodies in TÜV SÜD and BSI Group jurisdictions are rejecting laser micromachining qualifications lacking real-time power monitoring. Swiss orthopedic implant suppliers near Bern are consolidating supplier audits to reduce redundant facility certifications.
Device OEMs in Massachusetts and Tel Aviv are unbundling equipment procurement from process development contracts. Contract manufacturers now purchase laser micromachining platforms directly while licensing application-specific recipes from former turnkey vendors. This pattern concentrates most visibly in coronary stent and microfluidic chip production where FDA 510(k) predicate device strategies favor established process parameters over novel equipment configurations.
Global Micromachining Market Segmentation
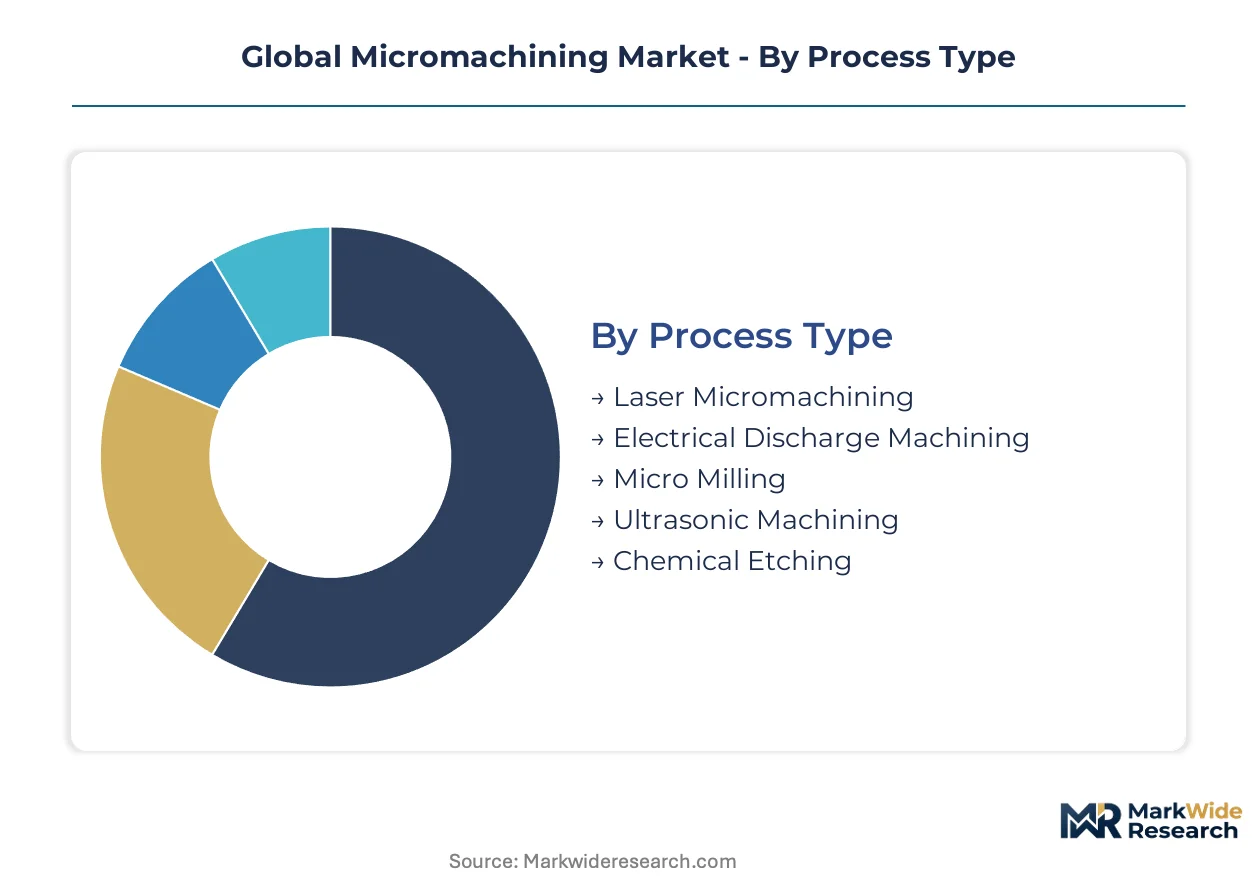
Micromachining market segmentation reflects the intersection of physics-driven process constraints and application-specific tolerance requirements. Distinct material-process pairings dominate each vertical, with semiconductor and medical implant fabricators driving divergent equipment specifications.
Process Type:
Cost tier differentiation separates capital-intensive laser platforms from lower-barrier mechanical and chemical alternatives.
- Laser Micromachining:Pulsed femtosecond and picosecond systems achieve sub-micron feature resolution in brittle substrates without thermal damage zones. Demand concentrates in German and Japanese semiconductor packaging facilities where silicon carbide wafer singulation requires non-contact processing.
- Electrical Discharge Machining:Spark-erosion technology machines conductive metals to Ra 0.1 micrometer finishes using shaped electrodes and dielectric flushing. Swiss medical implant manufacturers near Bern and Geneva deploy wire-EDM for titanium bone screw thread cutting under EU MDR traceability mandates.
- Micro Milling:High-speed spindles above 50,000 RPM with diamond-coated tools machine aluminum and copper heat spreaders for telecommunications base stations.
- Ultrasonic Machining:Abrasive slurry vibration processes advanced ceramics for aerospace turbine blade cooling holes.
- Chemical Etching:Wet chemistry and photochemical milling define microfluidic channel geometries in stainless steel and copper laminates.
Laser micromachining commands the established base. The steepest expansion runs through electrical discharge machining as medical implant volumes accelerate under tightened biocompatibility protocols.
Material Type:
Application requirements dictate material selection, with each substrate demanding specialized process adaptation and fixturing.
- Metals:Titanium, stainless steel, and platinum-group alloys dominate implant and instrumentation applications. Boston-area orthopedic device suppliers machine cobalt-chrome femoral heads using hybrid laser-EDM workflows.
- Ceramics:Alumina, zirconia, and silicon nitride substrates require diamond abrasive or ultrasonic methods for dental and bearing applications.
- Polymers:PEEK, bioabsorbable PLGA, and PMMA respond to ultraviolet and infrared laser ablation without thermal degradation. Irish stent manufacturers deploy burst-mode femtosecond systems for bioabsorbable scaffold scoring.
- Composite Materials:Carbon-fiber reinforced polymers and metal-matrix composites challenge conventional tooling in aerospace structural brackets.
- Silicon Wafers:Monocrystalline and silicon-on-insulator substrates define MEMS cavity and through-silicon via geometries. Japanese power semiconductor foundries scale femtosecond dicing capacity for electric vehicle inverter chips.
Metals retain the largest installed process base. Polymers are climbing the fastest as bioabsorbable medical devices and microfluidic disposables multiply.
End Use Industry:
Customer type concentration separates high-volume semiconductor capital expenditure cycles from medical device validation-intensive procurement.
- Semiconductor Fabrication:Front-end wafer processing and back-end packaging drive sub-10-micron alignment tolerances. German equipment clusters in Dresden and Munich supply die singulation systems to global foundries.
- Aerospace Components:Turbine blade cooling holes and fuel injector nozzles demand nickel superalloy machining without recast layers. Connecticut and Ohio job shops qualify processes under AS9100 and NADCAP frameworks.
- Precision Instrumentation:Optical encoders, atomic force microscope probes, and calibration artifacts require sub-micron geometric accuracy.
- Wearable Devices:Miniaturized sensor housings and biometric interfaces machine aluminum and polymer composites at consumer electronics volumes.
- Telecommunications Equipment:5G base station heat spreaders and fiber optic ferrules machine copper and ceramic substrates.
Semiconductor fabrication anchors capital equipment demand. Wearable devices are gaining share fastest as biometric sensor miniaturization accelerates.
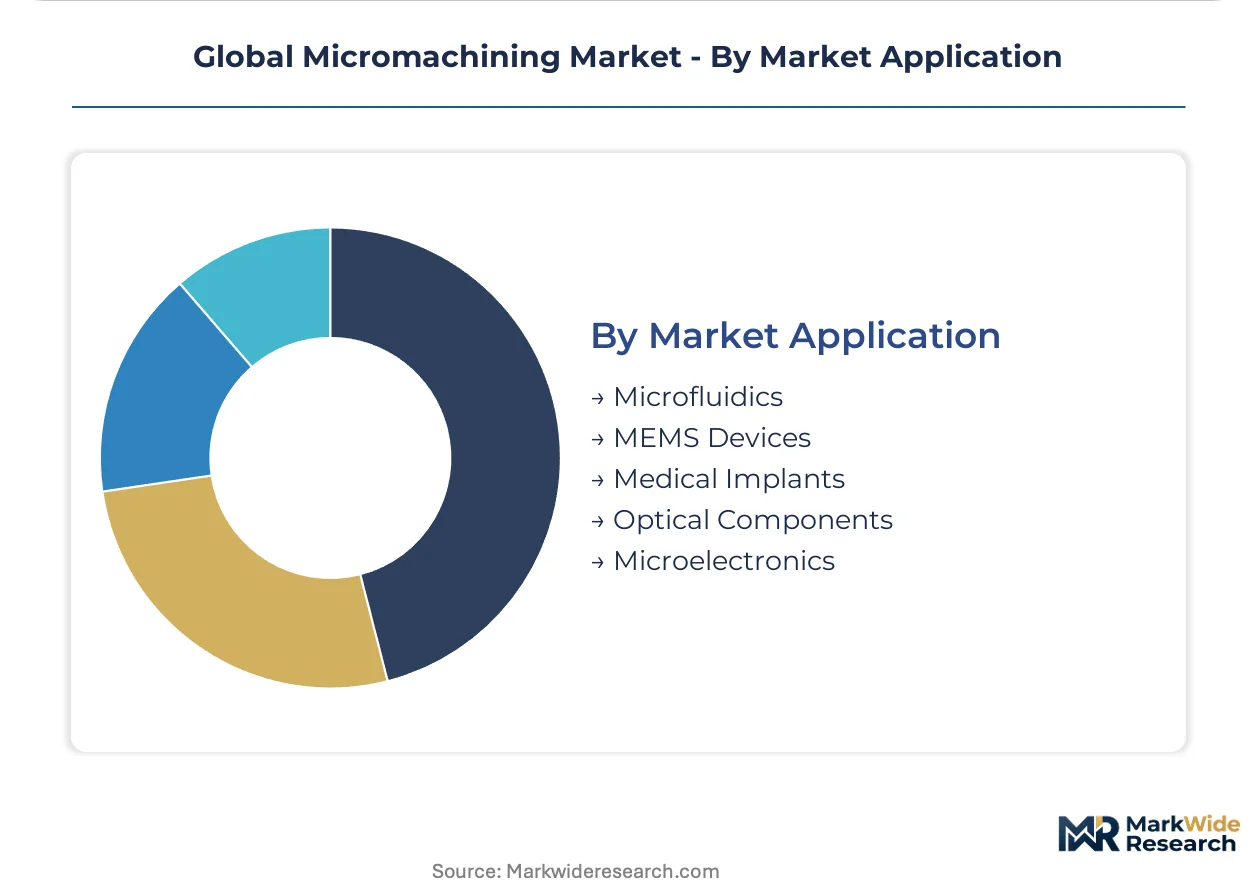
Market Application:
Maturity gradients separate established microelectronics from emerging MEMS and microfluidics architectures.
- Microfluidics:Lab-on-chip devices and point-of-care diagnostic cartridges machine polymer and glass substrates with channel geometries below 100 micrometers. Minnesota medical device OEMs license process recipes from specialized contract manufacturers.
- MEMS Devices:Accelerometers, gyroscopes, and pressure sensors define silicon cavity structures through deep reactive ion etching and laser ablation. Nagoya and Osaka equipment vendors access METI subsidies for cavity etching tool development.
- Medical Implants:Coronary stents, orthopedic screws, and neural electrodes demand biocompatible surface finishes and serialized lot documentation. FDA 510(k) predicate strategies favor established laser parameters over novel equipment.
- Optical Components:Lens barrels, fiber alignment fixtures, and laser cavities machine aluminum and invar to interferometric tolerances.
- Microelectronics:Printed circuit board microvias and connector housings represent the longest-established application with mature supply chains.
Microelectronics holds the deepest process legacy. MEMS devices show the steepest trajectory as automotive and consumer sensing applications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor established manufacturing economies with captive photonics supply chains. Germany and Japan maintain equipment trade surpluses through verticalized laser source production. The United States and China balance domestic fabrication capacity against specialized component imports from Swiss and Japanese precision clusters.
Germany
Femtosecond laser dicing systems and silicon carbide wafer processing equipment drive capital expenditure in Dresden and Munich semiconductor corridors. REACH and RoHS frameworks restrict hazardous substances in processed polymers, forcing equipment vendors to qualify alternative passivation chemistries. The Stuttgart-Aachen corridor anchors multi-physics simulation expertise for ultrashort pulse laser ablation modeling.
Japan
Power semiconductor foundries scale femtosecond laser capacity for electric vehicle inverter chips while MEMS cavity etching tool development accelerates under METI precision tooling subsidies. JIS standard harmonization grants support domestic equipment vendors in Nagoya and Osaka clusters. Palladium supply volatility from South African sources pressures electrical discharge machining electrode costs for job shops in the Chubu region.
United States
FDA 510(k) predicate device strategies concentrate coronary stent micromachining procurement in Massachusetts and Minnesota medical device corridors. EPA and OSHA frameworks govern hazardous waste from chemical etching operations. The Boston-Minneapolis axis dominates neural interface electrode array development, with Utah array geometries under 50 micrometers requiring combined laser ablation and electroplating integration.
Switzerland
Swissmedic biocompatibility protocols and EU MDR traceability mandates drive orthopedic implant fabrication near Bern and Geneva. Wire-EDM systems machine titanium bone screw threads under serialized lot documentation requirements. TÜV SÜD and BSI Group notified bodies enforce real-time power monitoring qualifications for laser micromachining systems serving the Basel-Zurich medical technology cluster.
China
NMPA green channel registration and MIIT energy efficiency standards favor domestic suppliers of low-power fiber laser micromachining platforms. Dual carbon targets accelerate demand for energy-efficient precision equipment in Yangtze River Delta fabrication parks. The country's national precision manufacturing regulator coordinates qualification strategies across divergent regional certification pathways for semiconductor packaging applications.
Global Micromachining Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in photonics and motion control subsystems. The vendor base stratifies between captive laser source manufacturers and pure-play equipment assemblers dependent on external supply. Three archetypes dominate: vertically integrated photonics houses with in-house crystal growth, precision mechanics specialists with deep EDM or micro-milling heritage, and modular platform vendors licensing application-specific process recipes. Consolidation pressure runs through laser source concentration while equipment margins compress from captive photonics manufacturing.
Among German-origin platform vendors, TRUMPF GmbH + Co. KG exemplifies the vertically integrated archetype through captive laser source technology. Japanese specialists Sodick Co., Ltd. and Makino Milling Machine Co., Ltd. occupy positions rooted in electrical discharge machining and high-speed spindle architectures respectively. These three represent divergent strategic paths: photonics backward integration versus deep process specialization versus precision mechanics scaling.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries Ltd. |
| Sodick Co., Ltd. |
| TRUMPF GmbH + Co. KG |
| Jenoptik AG |
| Amada Co., Ltd. |
| IPG Photonics Corporation |
| Makino Milling Machine Co., Ltd. |
| Renishaw plc |
| Coherent, Inc. |
| Others |
Cost & Logistics Intelligence
German and Japanese excimer laser crystal growth operations command upstream margin pools that downstream equipment assemblers struggle to reclaim through captive photonics investments. Buyers of femtosecond dicing systems face asymmetric pricing power where 193nm and 248nm source availability dictates total system economics.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in laser micromachining platforms. Premium tiers attach to FDA-validated medical implant systems with embedded metrology, while standard configurations serve semiconductor packaging without closed-loop power monitoring. Cost compression in economy tiers intensifies because Chinese domestic suppliers leverage MIIT energy efficiency subsidies to undercut Japanese and German incumbents. Contract manufacturers in Ireland and Minnesota exhibit highest price sensitivity due to unbundled equipment-procurement-from-process-development contracting patterns.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for ultraviolet laser source procurement. Manufacturing concentrates in Germany, Japan, and the United States for femtosecond systems, while South African and Russian palladium feeds electrode production for wire-EDM architectures. Equipment assemblers draw from concentrated photonics component suppliers in Stuttgart-Aachen and Nagoya-Osaka corridors. Distribution runs through direct OEM sales teams for semiconductor capital equipment and specialized distributors serving medical device job shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment vendor fragmentation creates specialist acquisition opportunities as FDA and EU MDR traceability mandates splinter demand across validated process niches. Medical implant fabricators now unbundle procurement from recipe licensing, opening gaps for modular platform vendors.
For Market Incumbents: Build captive laser source moats through backward integration into crystal growth or exclusive supply agreements with German and Japanese photonics houses. TRUMPF-style vertical control over fiber and disk laser architectures protects margin pools against Chinese low-power platform competition. Defensive patenting around burst-mode ablation parameters for bioabsorbable polymers blocks rival qualification pathways under EU MDR Article 10. For New Entrants and Emerging Players: Pursue neural interface electrode array fabrication as the most penetrable white-space target, where Utah array geometries under 50 micrometers lack established process recipe vendors. Gujarat and Tamil Nadu semiconductor fabs under India's PLI scheme offer greenfield equipment placement without incumbent replacement friction. License application-specific recipes to contract manufacturers rather than competing on turnkey system sales. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision mechanics specialists holding ISO 13485 certifications but lacking photonics integration. Five-to-ten-year viability hinges on successful backward integration into laser sources or forward integration into process recipe licensing. Watch FDA 510(k) predicate device strategies as the inflection signal: predicate stacking favors established parameter sets over novel equipment configurations.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Laser Source Integration | TRUMPF-style backward integration protects margins against photonics supplier concentration. |
| EU MDR Process Validation Investment | TÜV SÜD and BSI Group notified bodies demand real-time power monitoring for implant applications. |
| India PLI Scheme Participation | Gujarat and Tamil Nadu fabs offer capital expenditure reimbursement for singulation equipment. |
| Burst-Mode Ablation Patenting | Ireland-based stent manufacturers seek protected parameters for bioabsorbable scaffold scoring. |
| Neural Interface Recipe Licensing | Massachusetts and Tel Aviv device OEMs unbundle procurement from process development contracts. |
Research Approach
Desk research of SEC equipment vendor filings, METI subsidy disclosures, and FDA 510(k) predicate databases preceded structured interviews with biomedical engineers at orthopedic implant manufacturers, procurement leads at semiconductor foundries, and aftermarket service heads at laser system distributors. Primary fieldwork across Dresden, Stuttgart, Nagoya, and Minneapolis clusters validated secondary trade data on femtosecond dicing capacity expansion. Bottom-up equipment shipment analysis triangulated against top-down capital expenditure surveys from German and Japanese precision manufacturing associations.
Forecast assumptions held fixed the EU MDR regulatory framework and REACH substance restrictions while varying silicon carbide wafer adoption curves and palladium supply scenarios across the analysis window. Segmentation modeling captured process type, material substrate, end-use industry, and regional certification cluster dimensions. CAGRs derived from equipment replacement cycles, foundry capacity buildout schedules, and medical implant volume projections without year-specific anchoring.
Sensitivities concentrate around ultraviolet laser source export control tightening and South African palladium supply disruptions. Forecasts reflect assumptions about JIS standard harmonization continuity and FDA predicate device strategy stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Gan Substrate and Gan Wafer Market
Semiconductor Fabrication
Mask Alignment Lithography Market
Semiconductor Fabrication
Vapor Deposition Market
Semiconductor Fabrication
Solar Grade Wafer Market
Semiconductor Fabrication
Etchant for FPD Market
Semiconductor Fabrication
Global Spark Plasma Sintering Market
Semiconductor Fabrication
Additive Manufacturing in Semiconductor Market
Semiconductor Fabrication
Deep Reactive Ion Etching (DRIE) Etcher Market
Semiconductor Fabrication
Global Dry Etching Machine Market
Semiconductor Fabrication
Ion Implantation Machine Market
Semiconductor Fabrication
Etching Machine Market
Semiconductor Fabrication
Solar Ingot Wafer Market
Semiconductor Fabrication
Semiconductor Etching Cleaner Market
Semiconductor Fabrication
Semiconductor Photoresist Polymer Market
Semiconductor Fabrication
Sic Wafer Reclaim Services Market
Semiconductor Fabrication
Semiconductor Foundry Market