
 Global Dry Etching Machine Market | 2026-2036
Global Dry Etching Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dry Etching Machine Market Analysis
A shortage of plasma process engineers and vacuum technology specialists is unwinding capacity expansion timelines at several equipment suppliers. Applied Materials, Inc. leverages its installed base in conductor etch to sustain recurring revenue from upgrade kits and spares. NAURA Technology Group Co., Ltd. anchors its position through captive supply of radio-frequency power delivery subsystems. Tokyo Electron Limited dominates dielectric etch with tool architectures that integrate atomic-layer precision.
Global Dry Etching Machines are vacuum-based semiconductor fabrication tools that remove material from wafer surfaces through chemically reactive plasma or directed ion beams, operating at pressures typically below one torr with sub-nanometer critical dimension control. These systems enable pattern transfer for integrated circuits, MEMS devices, and advanced packaging structures where wet chemical methods fail at sub-7nm geometries. Plasma etching tools command the largest installed base due to their versatility across conductor and dielectric films, while reactive ion etching configurations are gaining share in MEMS and power device applications where anisotropic profiles reduce lithography overlay demands. Single wafer architectures lead revenue given their compatibility with 300mm foundry workflows, though multichamber platforms are penetrating memory fabs seeking throughput gains for 3D NAND stack etch.
EPA regulations on fluorinated greenhouse gas emissions from etch processes are tightening abatement requirements for US-based fabs, while REACH restrictions in Europe limit perfluorinated compound chemistries in tool consumables. Japan's METI enforces energy efficiency standards that shape thermal management subsystem designs for tools sold into domestic facilities. Semiconductor manufacturers must weigh geographic regulatory divergence when standardizing tool platforms across multi-site deployments.
Market Dynamics
The transition to gate-all-around transistor architectures at 3nm and below is forcing fabs to retool entire etch bays, creating simultaneous demand for new high-aspect-ratio dielectric etchers and upgraded conductor systems while compressing depreciation cycles for installed base.
Growth Catalysts
- Gate-All-Around Migration:Leading-edge logic fabs in Taiwan and South Korea are qualifying new etch platforms for nanosheet formation, pulling equipment deliveries forward by several quarters.
- EU Chips Act Capital Deployment:Public funding streams for domestic fabrication in Germany and France are unlocking greenfield fab projects that specify European-sourced abatement-integrated etch tools.
- 3D NAND Layer Stacking:Memory manufacturers are scaling vertical channel hole etch to over 200 layers, requiring multi-station platforms with synchronized gas delivery subsystems.
Market Restraints
- Fluorinated Gas Abatement Costs:EPA enforcement of fluorinated greenhouse gas capture mandates is adding seven-figure capital overhead per etch bay for US-based facilities.
- Specialized Talent Scarcity:Plasma physics PhD holders and vacuum system architects are concentrated in Japan and the United States, constraining supplier engineering bandwidth.
- Single-Source RF Subsystems:Solid-state radio-frequency power amplifier modules for sub-5nm precision control rely on a narrow supplier base in East Asia, creating concentration risk.
Strategic Opportunities
- India Semiconductor Mission:Greenfield fab commitments under India's PLI scheme create first-mover positioning for etch tool vendors willing to localize service engineering.
- Photonics Integration:Silicon photonics foundries require deep silicon etch with sidewall roughness below 2nm, opening adjacent demand from datacom transceiver manufacturers.
- Power Device Trench Etch:Silicon carbide MOSFET fabrication is driving reactive ion etch adoption for hexagonal trench profiles in automotive-qualified fabs.
Industry Challenges
- Plasma Process Engineer Shortfall:Equipment suppliers face 18-month backfills for senior etch recipe development roles, delaying customer qualification timelines.
- Legacy Tool Interoperability:New atomic-layer etch modules must integrate with 200mm-era factory automation protocols at analog and power fabs, complicating deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dry Etching Machine Market |
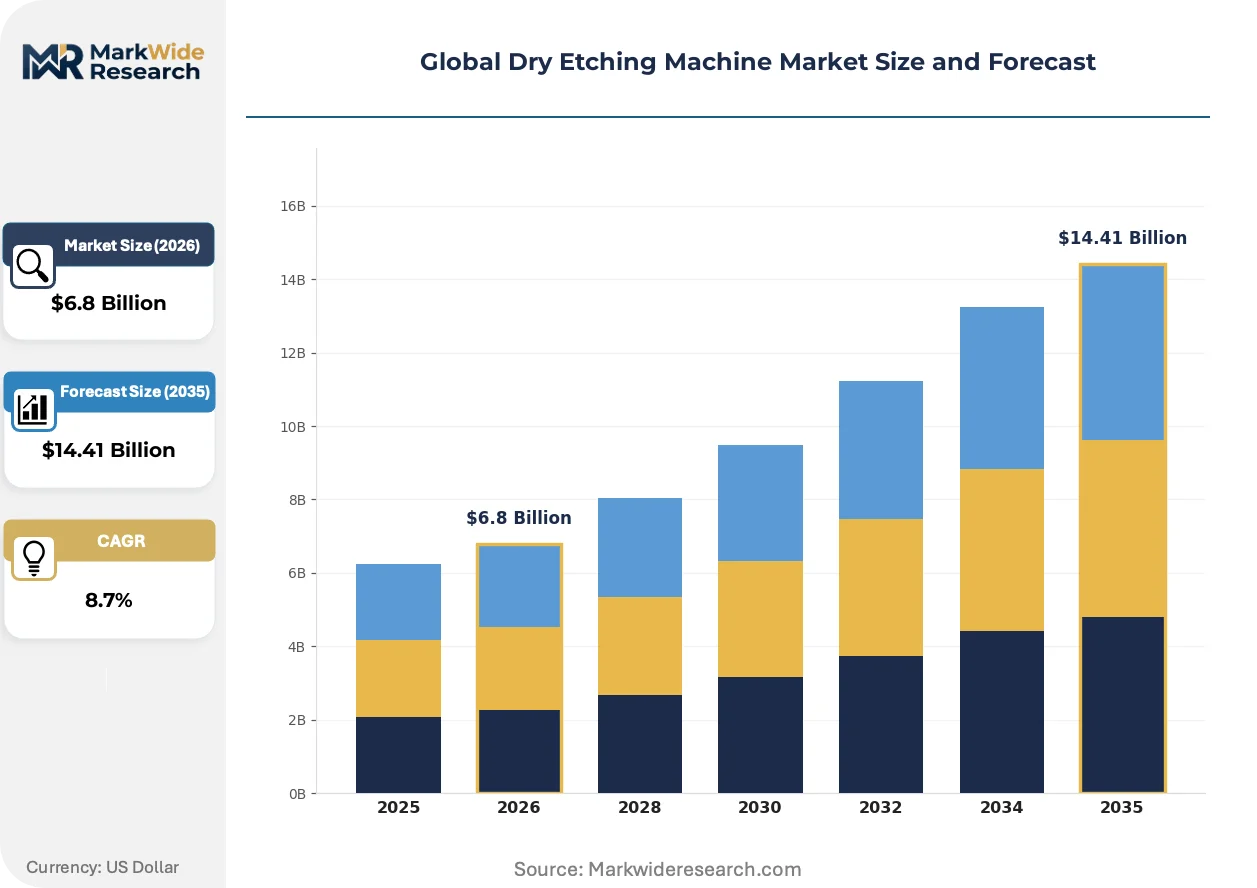
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wafer, Batch, Multichamber, Upgrade Kits Technology: Plasma Etching, Reactive Ion Etching, Ion Beam Etching, Laser Etching End User: Semiconductor Manufacturers, Research Laboratories, Electronic Component Manufacturers, Optoelectronics Application: Integrated Circuits, MEMS, Solar Cells, Nanotechnology |
| Companies Covered | Hitachi High-Technologies Corporation, NAURA Technology Group Co., Ltd., Applied Materials, Inc., Oxford Instruments plc, ULVAC Technologies, Inc., Lam Research Corporation, Advanced Micro-Fabrication Equipment Inc., SPTS Technologies Ltd., Tokyo Electron Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dry Etching Machine Market Emerging Trajectories
Process control architectures are fragmenting between atomic-scale precision requirements at the leading edge and throughput optimization for mature-node power devices, forcing suppliers to maintain divergent R&D roadmaps without scale economies.
Atomic-layer etch technology is bifurcating the competitive landscape. These systems remove material one atomic layer per cycle, enabling sub-nanometer critical dimension uniformity for gate-all-around transistors. Leading-edge foundries in Taiwan are qualifying these platforms for production ramps in 2025-2026. The technology is bifurcating vendor tiers, separating suppliers with proprietary chamber chemistries from those dependent on licensed process modules.
EPA fluorinated greenhouse gas regulations are tightening real-time emissions monitoring requirements for etch process exhaust streams. US-based fabs must now install continuous measurement systems tied to abatement equipment interlocks. Memory manufacturers with large 3D NAND footprints in the United States face the steepest compliance retrofit costs, accelerating evaluation of alternative chemistries.
Equipment procurement cycles are compressing as foundries pre-qualify multiple etch platforms simultaneously rather than sequential vendor selection. This pattern is displacing traditional sole-source relationships with parallel vendor development agreements. Taiwan-based logic manufacturers pioneered this approach, and it is now spreading to Korean memory fabs seeking supply security.
Global Dry Etching Machine Market Segmentation
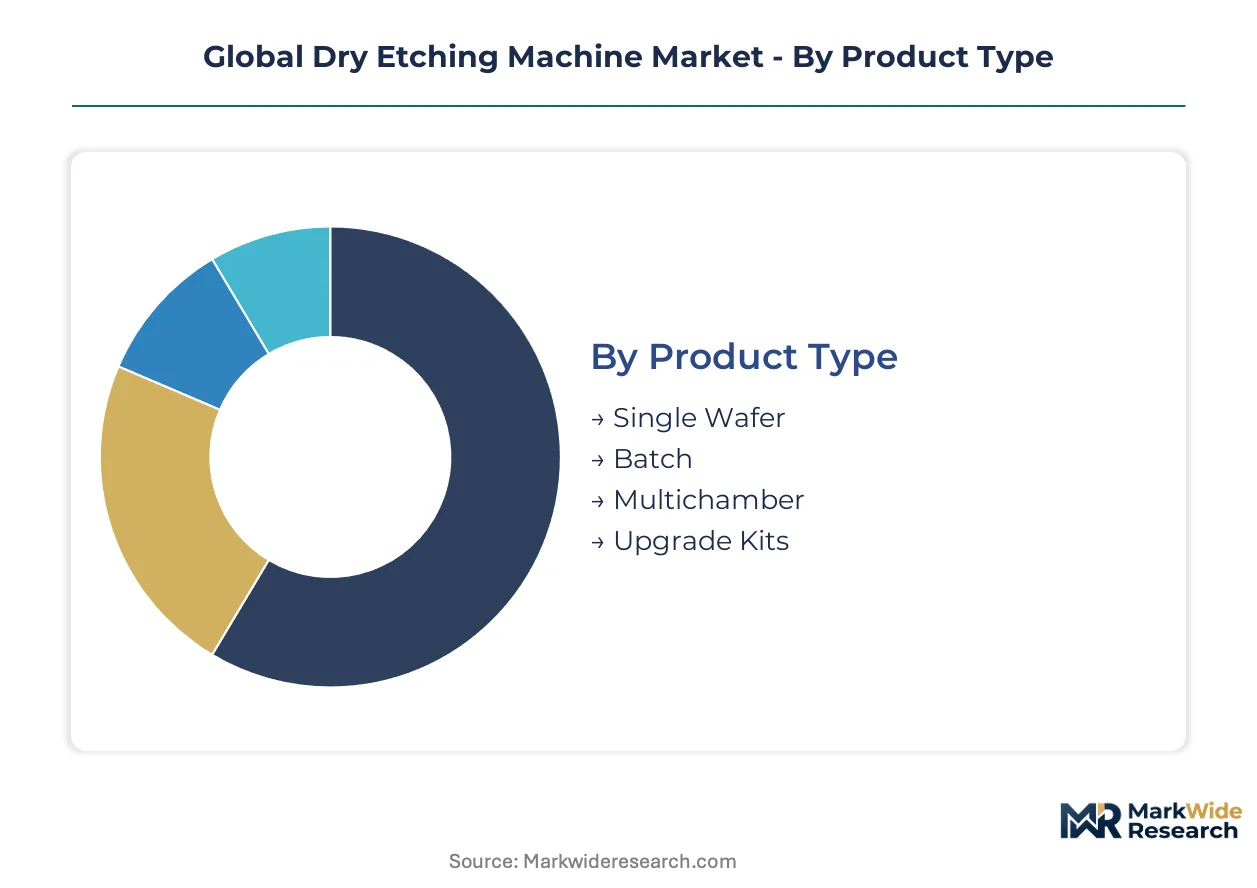
Segmentation in dry etching machines reflects divergent process requirements across node generations and substrate formats. Equipment suppliers must balance atomic-scale precision architectures against throughput-optimized platforms serving mature-node demand.
Product Type:
Substitution pressure concentrates on batch processing configurations as single wafer architectures extend dominance at leading-edge nodes.
- Single Wafer:These systems process one 300mm wafer per chamber, enabling precise temperature and gas flow control for sub-7nm patterning. Taiwan-based foundries and South Korean memory manufacturers anchor demand as gate-all-around transistor qualification pulls tool deliveries forward.
- Multichamber:Cluster tool architectures link multiple process modules through central wafer handling, allowing sequential etch steps without atmospheric exposure. Memory fabs scaling 3D NAND beyond 200 layers specify these platforms for synchronized high-aspect-ratio channel hole etching.
- Batch:Simultaneous processing of multiple wafers delivers cost efficiency for 200mm analog and power device production where critical dimension tolerances relax.
- Upgrade Kits:Retrofit packages extend installed base utility through chamber refurbishment, gas delivery subsystem replacement, and control software modernization.
Single wafer configurations retain volume leadership; multichamber platforms hold the steepest expansion curve.
Technology:
Cost tier stratification separates capital-intensive plasma systems from reactive ion etch alternatives penetrating price-sensitive power device applications.
- Plasma Etching:Chemically reactive plasma at sub-torr pressures removes material through neutral and ionized species interaction. The technology commands the largest installed base across conductor and dielectric films, with Applied Materials and Tokyo Electron dominating chamber design intellectual property.
- Reactive Ion Etching:Combined physical sputtering and chemical reaction produces anisotropic profiles critical for MEMS release structures and silicon carbide trench formation. Automotive-qualified fabs in Japan and Germany are expanding reactive ion etch capacity for MOSFET gate definition.
- Ion Beam Etching:Directed ion bombardment enables material removal without chemical reactants, serving magnetic sensor fabrication and photonic device patterning where plasma damage must be eliminated.
- Laser Etching:Pulsed laser ablation processes transparent substrates and compound semiconductors where conventional plasma chemistries prove ineffective.
Plasma etching sustains revenue concentration; reactive ion etching is expanding most quickly in automotive power electronics.
End User:
Customer type determines service intensity, with semiconductor manufacturers demanding 24-hour technical response while research laboratories prioritize recipe flexibility over throughput.
- Semiconductor Manufacturers:Integrated device foundries and memory producers operate high-volume fabs requiring matched tool fleets with identical process repeatability. These customers drive specifications for factory automation integration and predictive maintenance capabilities.
- Research Laboratories:University cleanrooms and national research institutes need rapid recipe reconfiguration for exploratory process development. Tool architectures here emphasize open-access gas chemistries and modular chamber designs.
- Electronic Component Manufacturers:Passive component and substrate producers utilize etch tools for surface texturing and via formation at relaxed geometry nodes.
- Optoelectronics:Compound semiconductor fabs processing gallium arsenide and indium phosphide require specialized plasma chemistries and corrosion-resistant chamber materials.
Semiconductor manufacturers retain volume leadership; optoelectronics holds the steepest expansion curve.
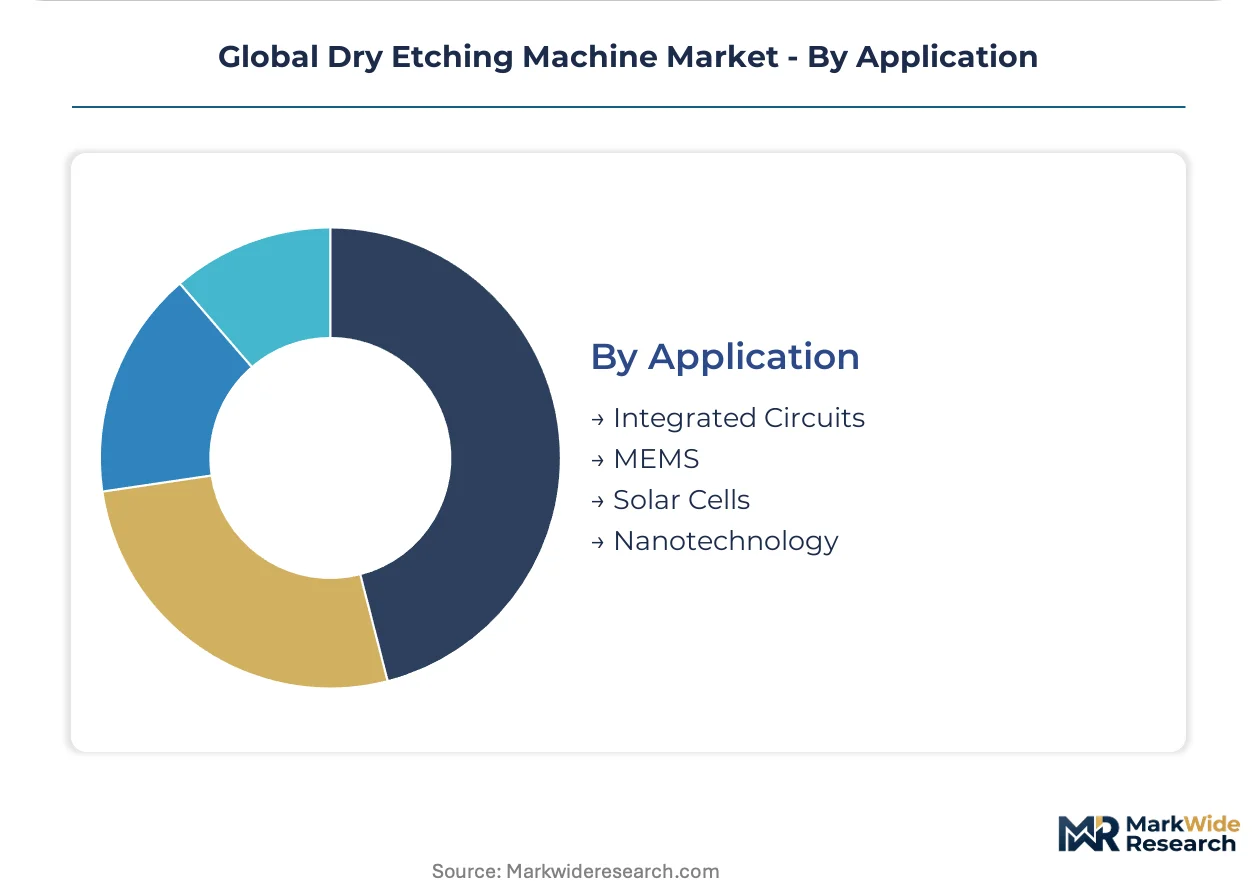
Application:
Maturity differentiation separates established integrated circuit demand from emerging nanotechnology applications where tool architectures remain unsettled.
- Integrated Circuits:Logic and memory chip fabrication consumes the majority of etch tool capacity, with process modules dedicated to gate, contact, and interconnect patterning. Leading-edge foundries in Taiwan are qualifying atomic-layer etch platforms for nanosheet transistor production ramps.
- MEMS:Microelectromechanical systems require deep silicon etch with vertical sidewall profiles for accelerometer, gyroscope, and pressure sensor fabrication. Bosch and STMicroelectronics fabs in Germany and Italy anchor European demand.
- Solar Cells:Crystalline silicon photovoltaic manufacturing employs etch tools for surface texturing and edge isolation, with PERC and TOPCon cell architectures driving chemistry refinements.
- Nanotechnology:Quantum device and 2D material research utilizes etch tools for exfoliation and patterning of graphene and transition metal dichalcogenides.
Integrated circuits sustain revenue concentration; MEMS is gaining share fastest in automotive and consumer sensor applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan consumes dry etching machines primarily for leading-edge logic foundry production, while South Korea deploys identical tools toward memory stack etching with radically different chamber configurations. Japan maintains distinct demand patterns centered on power device and MEMS fabrication. The United States and Germany represent emerging capacity expansion zones where regulatory frameworks reshape equipment specifications.
Taiwan
Leading-edge logic foundries drive demand for atomic-layer etch platforms qualifying for gate-all-around transistor production ramps. The National Development Council coordinates industrial policy supporting domestic equipment ecosystem development. Hsinchu Science Park anchors the highest concentration of 300mm foundry capacity globally, with tool deliveries accelerating ahead of 2025-2026 production timelines.
South Korea
Memory manufacturers scale vertical channel hole etch requirements beyond 200 layers for 3D NAND architectures. The Ministry of Trade, Industry and Energy enforces local content requirements for semiconductor equipment procurement under national strategic technology designations. Samsung and SK Hynix facilities in Pyeongtaek and Icheon dominate global 3D NAND output, pulling synchronized multi-station platform orders.
Japan
Automotive-qualified power device fabs expand reactive ion etch capacity for silicon carbide MOSFET trench formation. METI energy efficiency standards constrain thermal management subsystem designs for domestic facility deployments. Kyoto-Osaka industrial corridor hosts concentrated MEMS and power semiconductor manufacturing, with Bosch and Renesas operations driving specialized tool configurations.
United States
Greenfield fab projects under the CHIPS and Science Act unlock demand for abatement-integrated etch platforms. EPA fluorinated greenhouse gas regulations mandate seven-figure capital overhead per etch bay for continuous emissions monitoring and capture systems. Intel facilities in Arizona and Ohio, plus Samsung and TSMC greenfield sites, constitute the primary demand nodes for 2024-2027 equipment deliveries.
Germany
European-sourced etch tools gain specification preference under EU Chips Act capital deployment for domestic fabrication ecosystems. REACH restrictions limit perfluorinated compound chemistries in tool consumables, forcing chemistry portfolio adjustments. Dresden and Magdeburg clusters host emerging foundry capacity with Infineon and planned Intel operations specifying European-abatement-integrated platforms.
Global Dry Etching Machine Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the dry etching machine competitive structure. The upper tier commands proprietary chamber design intellectual property and captive radio-frequency subsystem supply, while specialists occupy niche positions in ion beam and laser etch configurations. Two strategic archetypes predominate: full-stack platform vendors integrating process modules with factory automation, and component specialists supplying gas delivery and power amplification subsystems to multiple OEMs. Competitive dynamics center on vertical integration into critical subsystems and parallel qualification agreements with foundries seeking supply security.
Within the integrated platform tier, Tokyo Electron Limited and Applied Materials, Inc. exemplify divergent specialization vectors—dielectric versus conductor etch dominance—while NAURA Technology Group Co., Ltd. represents the captive supply archetype through in-house radio-frequency power delivery production. These three entities anchor distinct competitive positions without overlapping core technology claims, enabling foundry customers to maintain parallel vendor development agreements without sole-source dependency.
| Leading Market Players |
|---|
| Hitachi High-Technologies Corporation |
| NAURA Technology Group Co., Ltd. |
| Applied Materials, Inc. |
| Oxford Instruments plc |
| ULVAC Technologies, Inc. |
| Lam Research Corporation |
| Advanced Micro-Fabrication Equipment Inc. |
| SPTS Technologies Ltd. |
| Tokyo Electron Limited |
| Others |
Supply Flow & Price Mechanics
EPA fluorinated greenhouse gas regulations gate both supplier qualification and price differentiation simultaneously, mandating seven-figure abatement system investments that stratify vendor tiers between integrated platform providers and component specialists lacking certification bandwidth. Equipment buyers face dual screening: technical validation for sub-nanometer precision and regulatory compliance for emissions capture, compressing the qualified supplier base and amplifying pricing power for compliant incumbents.
Pricing Analysis
Long-term offtake contracts dominate equipment procurement, with foundries locking multi-year tool deliveries to secure allocation amid plasma process engineer scarcity. Price differentiation separates premium-tier atomic-layer etch platforms from standard conductor systems through gate-all-around qualification status and captive RF subsystem supply. Pricing pressure stems from memory manufacturers delaying 3D NAND layer-stack expansions, forcing suppliers to absorb customization costs. Research laboratories exhibit highest price sensitivity; Taiwan-based logic foundries prioritize precision over unit economics.
Supply Chain Analysis
Strategic stockpiling of solid-state RF power amplifiers and specialized ceramics prevails over just-in-time inventory given single-source concentration in Japan and South Korea. Manufacturing draws from precision-machined aluminum chambers sourced from Germany, high-purity gas delivery components from the United States, and advanced ceramics from Japan. Single-source vulnerability in radio-frequency power modules creates concentration exposure. Distribution runs through direct OEM-fab relationships with embedded field service engineering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dry etching machine market sits in early-cycle expansion, with gate-all-around transistor migration pulling equipment deliveries forward and greenfield fab commitments under industrial policy schemes expanding addressable demand.
For Market Incumbents: Fortify captive supply positions in radio-frequency power delivery and gas abatement subsystems against emerging Chinese platform vendors. Prioritize backward integration into chamber chemistry intellectual property to defend margin structures as atomic-layer etch modules commoditize. Expand service engineering headcount in India and Germany ahead of localized fab ramp schedules. For New Entrants and Emerging Players: Anchor in silicon photonics foundry demand for deep silicon etch with sub-2nm sidewall roughness specifications, a segment where incumbent tooling configurations remain suboptimal. Target India's PLI-backed greenfield fabs with localized technical service capabilities as the most penetrable geography. Pursue joint development agreements with compound semiconductor manufacturers seeking corrosion-resistant chamber materials for gallium arsenide processing. For Investors and Strategic Acquirers: EU Chips Act capital deployment reshapes the acquisition landscape, privileging European-abatement-integrated platform vendors with domestic service infrastructure. Long-term viability centers on suppliers with proprietary chamber chemistries rather than licensed process module dependencies. Watch EPA enforcement intensity on fluorinated gas capture mandates as the signal indicating margin compression timing for non-compliant installed bases.| Strategic Initiative | Industry Significance |
|---|---|
| Atomic-Layer Etch Platform Qualification | Enables nanosheet transistor production ramps at Taiwan foundries. |
| RF Power Amplifier Backward Integration | Reduces single-source exposure from East Asian component suppliers. |
| Abatement-Integrated Tool Architecture | Satisfies EPA emissions mandates for US-based memory and logic fabs. |
| India Service Engineering Localization | Captures PLI-scheme greenfield fab demand with domestic technical presence. |
| Silicon Photonics Process Module Development | Addresses datacom transceiver manufacturer requirements for deep silicon etch. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with plasma process engineers, vacuum technology specialists, foundry procurement directors, and equipment supplier product managers; and secondary validation through SEC equipment supplier filings, SEMI capital expenditure databases, and national industrial policy documents. Bottom-up triangulation across fab-level tool delivery schedules and top-down reconciliation against foundry capacity expansion announcements anchored volume estimates.
Across the projection horizon, the analytical framework modeled demand segmentation by product architecture, technology type, end-user category, and application vertical, with particular attention to node-generation transitions. CAGRs derived from equipment procurement cycle compression patterns and regulatory-driven replacement demand. Forecast inputs incorporated gate-all-around transistor adoption curves and 3D NAND layer-stack scaling roadmaps without specifying timeline milestones.
Material uncertainties — geopolitical restrictions on semiconductor equipment trade, abrupt fluorinated chemistry regulatory bans, and plasma process engineer availability — sit outside the modeled envelope. Forecasts reflect assumptions about sustained foundry capital intensity and memory manufacturer technology transitions. Revision becomes warranted when EPA enforcement thresholds on greenhouse gas emissions trigger retroactive compliance retrofit mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Etching Machine Market
Semiconductor Fabrication
Semiconductor Etching Cleaner Market
Semiconductor Fabrication
Epitaxial Wafer Market
Semiconductor Fabrication
Semiconductor Fab Water Reuse Systems Market
Semiconductor Fabrication
Holmium Sputtering Target Market
Semiconductor Fabrication
Global Spark Plasma Sintering Market
Semiconductor Fabrication
Vapor Deposition Market
Semiconductor Fabrication
Solar Ingot Wafer Market
Semiconductor Fabrication
Thin Layer Deposition Market
Semiconductor Fabrication
Global Atomic Layer Deposition Market
Semiconductor Fabrication
8-Inch Silicon Carbide (Sic) Wafer Market
Semiconductor Fabrication
Global Foundry Service Market
Semiconductor Fabrication
Etchant for FPD Market
Semiconductor Fabrication
Semiconductor Logistics Market
Semiconductor Fabrication
Photoresist Removal Market
Semiconductor Fabrication
Ion Implanter Market