
 Vapor Deposition Market | 2026-2036
Vapor Deposition Market Size, Share, and Industry Trends Forecast 2026-2036
Vapor Deposition Market Outlook
Buyer concentration in semiconductor foundries is pivoting toward a handful of advanced-node manufacturers while specialty coating houses fragment across aerospace and medical tiers. Applied Materials leverages its installed base dominance in PVD and CVD platforms across logic and memory fabs. Tokyo Electron Limited anchors its position through etch and deposition tool integration. Lam Research Corporation competes aggressively in selective deposition and atomic layer etch adjacencies.
Vapor deposition encompasses thin-film material transport and condensation processes operating at vacuum pressures from millitorr to atmospheric ranges, depositing angstrom-to-micron layers with precise stoichiometric control for electronic, optical, and protective functions. Chemical Vapor Deposition retains the largest revenue pool due to its entrenched role in dielectric and conductor film stacks, though Atomic Layer Deposition captures the fastest expansion as sub-3nm nodes demand atomic-scale thickness precision. Physical Vapor Deposition occupies a mature but stable niche in hard coatings and barrier metallization where throughput economics still favor sputtering over sequential precursor chemistries.
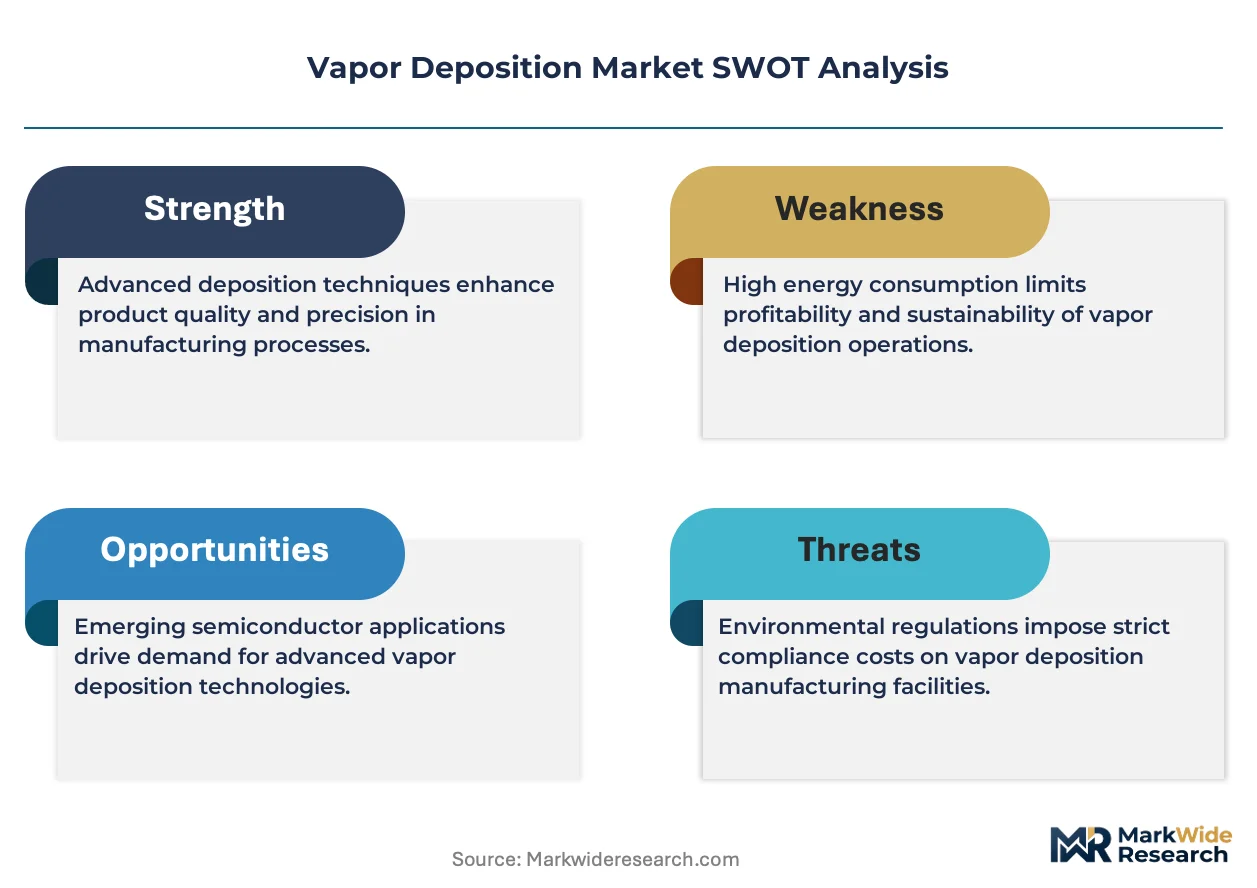
EPA precursor reporting requirements and REACH authorization lists for metal-organic compounds are elevating compliance costs and reshaping supplier qualification timelines for deposition chemical vendors. SEMI safety guidelines and ISO 14644 cleanroom standards further constrain process tool design and facility architecture decisions. Stakeholders must monitor regulatory divergence between US and European chemical frameworks while calibrating R&D roadmaps for next-generation precursor development.
Market Dynamics
The transition from planar transistors to gate-all-around architectures at sub-3nm nodes is forcing wholesale replacement of legacy deposition tools and precursor chemistries across Taiwan, South Korea, and Arizona fabrication clusters.
Growth Catalysts
- Advanced node scaling:Gate-all-around transistor architectures at 2nm and below require atomic-layer deposition for channel and spacer materials, pulling tool orders from logic foundries in Taiwan and South Korea.
- CHIPS Act incentives:US domestic fabrication subsidies are accelerating greenfield fab construction in Arizona, Texas, and New York, creating immediate demand for high-throughput CVD and ALD platforms.
- Automotive chip qualification:ISO 26262 functional safety mandates for autonomous and electric vehicle electronics are expanding the addressable market for automotive-grade deposition processes.
Market Restraints
- Precursor supply concentration:High-purity metal-organic precursor synthesis remains concentrated among German and Japanese chemical suppliers, exposing fabs to single-source risk for hafnium and zirconium precursors.
- REACH authorization bottlenecks:ECHA's expanding candidate list for Substances of Very High Concern is extending qualification timelines for new organometallic precursors by 18-24 months.
- Technical throughput ceiling:Atomic layer deposition's sequential precursor-purge cycles impose fundamental throughput limits versus CVD, constraining cost economics for thick dielectric films.
Strategic Opportunities
- India semiconductor ecosystem:PLI scheme subsidies for domestic fab and ATMP capacity are creating first-mover advantages for deposition tool vendors establishing local service infrastructure.
- Silicon carbide power devices:Epitaxial CVD for SiC wafers is emerging as a distinct equipment category as electric vehicle inverters and renewable energy converters expand demand.
- Photonics packaging integration:Heterogeneous integration of optical interconnects with compute dies is opening new applications for low-temperature PVD metallization in co-packaged optics.
Industry Challenges
- Process engineer scarcity:The specialized knowledge required for precursor chemistry optimization and chamber matching is concentrated among veterans of Intel, TSMC, and Samsung process development teams.
- Cleanroom capex intensity:ISO 14644 Class 1 facility requirements for sub-3nm deposition tools demand $500M-plus building investments before equipment installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vapor Deposition Market |
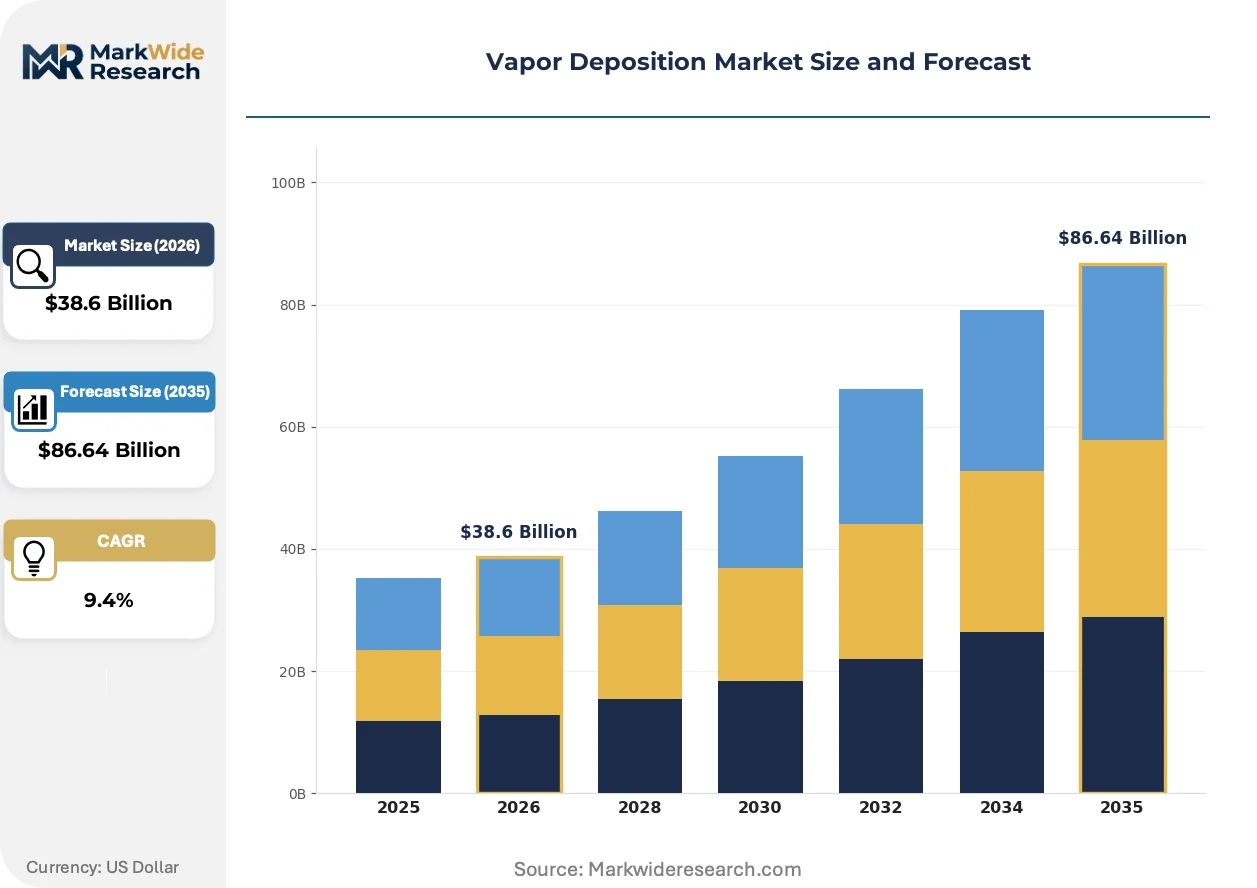
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $86.64 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Physical Vapor Deposition, Chemical Vapor Deposition, Atomic Layer Deposition, Laser Ablation End User: Electronics, Aerospace, Medical Devices, Automotive Application: Semiconductor Manufacturing, Coating, Thin Film Solar Cells, Optics Technology: HEM, LPCVD, PECVD, MBE |
| Companies Covered | Applied Materials, Tokyo Electron Limited, Lam Research Corporation, ULVAC, Veeco Instruments, OC Oerlikon Management AG, IHI Corporation, ASM International, CVD Equipment Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vapor Deposition Market Strategic Shifts
Selective deposition techniques are eliminating lithography-etch cycles in advanced logic, while regulatory pressure on fluorinated greenhouse gases is redirecting R&D toward alternative chemistries. Equipment architecture is converging around cluster-tool modularity to accommodate process diversification.
Area-selective atomic layer deposition is overtaking traditional pattern-and-etch sequences for self-aligned contacts and local interconnects. Samsung and TSMC process teams have integrated selective deposition modules into their 2nm pilot lines since 2024. The technology is compressing mask count and lithography tool utilization in critical layers.
EPA's expanded reporting requirements for fluorinated precursors under the Greenhouse Gas Reporting Program are elevating compliance burdens for NF3 and WF6 consumption. Deposition chemical suppliers are accelerating development of non-fluorinated tungsten and silicon precursors. Memory fabs in South Korea face the steepest reformulation timelines given their tungsten plug intensity.
Equipment procurement is consolidating around long-term service contracts bundling consumables, software updates, and predictive maintenance. Foundries in Taiwan are displacing transactional spare parts purchasing with full-fleet performance agreements. The shift transfers operational risk to tool vendors while locking in decade-long supplier relationships.
Vapor Deposition Market Segmentation
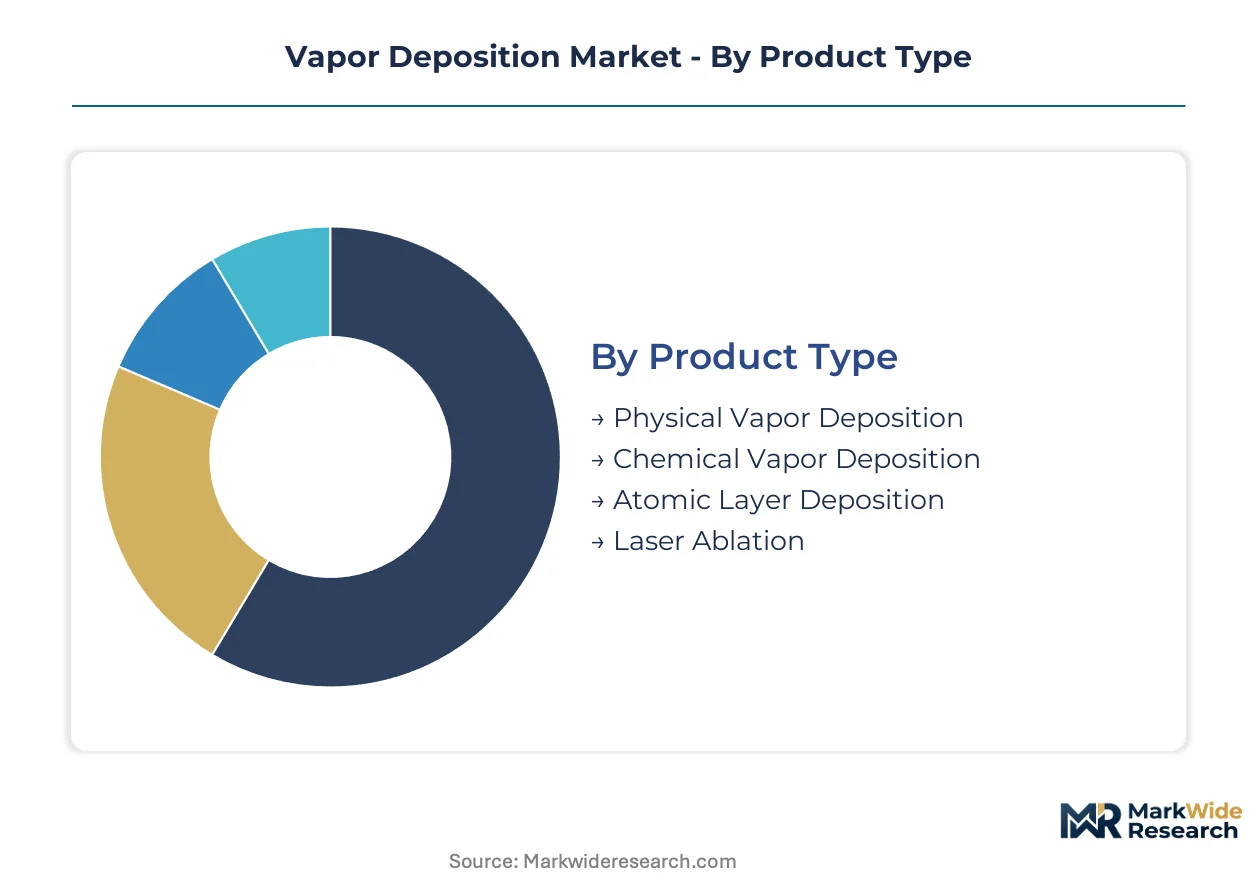
Vapor deposition technologies fragment across distinct process physics and equipment architectures. Each segment carries unique throughput economics, precursor requirements, and qualification timelines that shape vendor selection and fab deployment strategies.
Product Type:
Process physics and deposition control precision define the technology hierarchy across semiconductor and industrial coating applications.
- Chemical Vapor Deposition:Gas-phase precursor reactions deposit conformal films across complex topographies at elevated temperatures. Taiwan and South Korea foundries deploy high-throughput CVD platforms for dielectric and tungsten plug stacks in memory and logic fabs.
- Atomic Layer Deposition:Sequential self-limiting surface reactions achieve angstrom-level thickness control through discrete precursor-purge cycles. Sub-3nm gate-all-around transistor architectures in Taiwan fabrication clusters pull ALD tool orders for channel and spacer material deposition.
- Physical Vapor Deposition:Sputtered material flux from solid targets deposits metallic films at lower thermal budget. Barrier metallization and hard coating applications favor PVD throughput economics over precursor-based alternatives.
- Laser Ablation:Pulsed laser energy vaporizes target material for stoichiometrically complex oxide and nitride films. Research-scale deployment concentrates in national laboratory and university materials science programs.
Mature deployment sits with Chemical Vapor Deposition. Newer deployment is concentrated in Atomic Layer Deposition.
End User:
Customer sophistication and volume scale create tiered demand patterns across electronics manufacturing and industrial coating sectors.
- Electronics:Logic and memory foundries in Taiwan, South Korea, and Arizona drive equipment procurement cycles tied to node migration roadmaps. CHIPS Act subsidies accelerate greenfield fab construction with immediate demand for CVD and ALD platforms.
- Automotive:ISO 26262 functional safety mandates for autonomous and electric vehicle electronics expand qualification requirements for automotive-grade deposition processes. Power device manufacturers in Germany and Japan source SiC epitaxial CVD systems for inverter applications.
- Aerospace:Thermal barrier coatings and erosion-resistant surfaces on turbine blades utilize electron beam PVD and plasma-sprayed variants. OEMs in France and the United States specify coating thickness tolerances and adhesion standards.
- Medical Devices:Biocompatible thin films on implants and surgical instruments demand low-temperature PVD processes with validated sterility pathways. Orthopedic manufacturers in Switzerland and the United States qualify tantalum and titanium nitride coatings.
Volume concentration sits with Electronics. Margin expansion is concentrated in Medical Devices.
Application:
Film function and substrate compatibility determine process selection across device fabrication and surface engineering contexts.
- Semiconductor Manufacturing:Transistor gate stacks, interconnect metallization, and memory cell formation require angstrom-scale thickness control and atomic-level uniformity. Taiwan foundries lead in selective deposition module integration for self-aligned contact schemes.
- Coating:Wear resistance, corrosion protection, and decorative finishes on cutting tools and consumer goods utilize PVD and CVD variants. German tooling manufacturers specify TiAlN and DLC coatings for machining applications.
- Thin Film Solar Cells:Cadmium telluride and CIGS absorber layers deposit through vapor transport processes at atmospheric or reduced pressure. Utility-scale panel producers in the United States and India qualify deposition uniformity across large-area substrates.
- Optics:Anti-reflective, reflective, and filter coatings on lenses and laser components demand precise refractive index control. Precision optics houses in Japan and Germany specify ion-assisted deposition for low-defect dielectric stacks.
Capital intensity sits with Semiconductor Manufacturing. Technology refresh is concentrated in Thin Film Solar Cells.
Technology:
Chamber architecture and energy coupling mechanism differentiate equipment platforms within broader CVD and PVD categories.
- PECVD:Plasma-enhanced chemical vapor deposition enables low-temperature dielectric deposition on temperature-sensitive substrates. Memory fabs in South Korea deploy PECVD for interlayer dielectric and passivation films.
- LPCVD:Low-pressure chemical vapor deposition achieves superior step coverage and film purity through thermal activation at reduced pressures. Polysilicon and silicon nitride deposition for logic devices in Taiwan utilizes horizontal and vertical LPCVD furnace configurations.
- MBE:Molecular beam epitaxy provides ultra-high vacuum conditions for single-crystal semiconductor growth with in-situ monitoring. Compound semiconductor research in the United States and Japan employs MBE for quantum well and heterostructure fabrication.
- HEM:Hollow cathode electron beam melting supports reactive evaporation of refractory metals and oxides. Specialized coating vendors in Germany utilize HEM configurations for optical and decorative thin film production.
Production scale sits with PECVD. Precision frontier deployment is concentrated in MBE.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity expansion in Taiwan and South Korea is pulling the majority of deposition tool orders, while CHIPS Act subsidies are redirecting some fabrication investment toward Arizona and Texas. India and Japan represent emerging procurement zones with distinct policy drivers.
Taiwan
TSMC's 2nm pilot line ramp in Hsinchu Science Park is driving selective ALD module procurement for gate-all-around transistor architectures. The National Development Council's semiconductor initiative underwrites R&D tax credits for advanced process development. Tainan's Southern Taiwan Science Park hosts memory foundry expansion requiring high-throughput CVD platforms for dielectric stacks.
South Korea
Samsung Electronics and SK Hynix are scaling 3D NAND layer counts beyond 300 tiers, demanding specialized deposition tools for vertical channel formation. The Ministry of Trade, Industry and Energy's K-Semiconductor Belt program subsidizes domestic equipment ecosystem development. Pyeongtaek and Yongin fabrication clusters concentrate memory-specific tool qualification activity.
United States
Intel's Ohio and Arizona fab construction plus TSMC's Phoenix facility are creating immediate demand for CVD and ALD platforms with localized service infrastructure. EPA's expanded Greenhouse Gas Reporting Program for fluorinated precursors is forcing NF3 and WF6 consumption tracking reformulations. The Phoenix-Tucson corridor is emerging as a deposition chemical logistics hub serving Southwest fabrication clusters.
Japan
Tokyo Electron and Shin-Etsu Chemical are expanding precursor synthesis capacity to reduce German supplier dependency for hafnium and zirconium compounds. METI's semiconductor and digital industry strategy directs subsidies toward deposition equipment component localization. Kyushu's Kumamoto region hosts Rapidus Corporation's 2nm pilot fab with integrated ALD process development.
India
Tata Electronics and CG Power are establishing ATMP capacity in Gujarat and Assam, creating first-mover deposition tool installation opportunities. The PLI scheme for semiconductors offers 50% capex reimbursement for domestic fab and packaging facilities. Dholera Special Investment Region is designated as a semiconductor manufacturing zone with expedited environmental clearances for cleanroom construction.
Vapor Deposition Market Competitive Environment
United States producers anchor one tier; Japanese and European specialists hold differentiated positions in precursor chemistry and niche equipment categories. The vendor structure concentrates around three integrated platform providers while fragmenting across deposition chemical suppliers and regional service providers. Archetypes include full-stack equipment integrators, precursor chemistry specialists, and modular subsystem suppliers. Competitive moves center on long-term service contract bundling and selective geographic expansion into subsidy-supported fabrication zones.
Within the integrated equipment tier, Applied Materials and Lam Research Corporation exemplify platform breadth across PVD, CVD, and ALD modalities. Tokyo Electron Limited occupies a distinct position linking etch and deposition process modules. Among European specialists, OC Oerlikon Management AG represents the industrial coating equipment archetype serving aerospace and medical device manufacturers outside semiconductor fabrication.
| Leading Market Players |
|---|
| Applied Materials |
| Tokyo Electron Limited |
| Lam Research Corporation |
| ULVAC |
| Veeco Instruments |
| OC Oerlikon Management AG |
| IHI Corporation |
| ASM International |
| CVD Equipment Corporation |
| Others |
Value Chain & Pricing Dynamics
Tungsten hexafluoride spot indices and hafnium precursor contract benchmarks cascade through equipment and chemical supply tiers, compressing margins for deposition tool vendors while amplifying pricing power for German and Japanese organometallic specialists serving Taiwan and South Korea foundries.
Pricing Analysis
Volume concentration in high-throughput CVD platforms for memory dielectric stacks diverges from margin capture in selective ALD modules for sub-3nm logic. Price differentiation separates qualification-heavy automotive-grade processes from commodity barrier metallization. Pricing pressure stems from REACH authorization delays extending precursor qualification timelines. Foundry procurement teams in Taiwan exhibit highest price sensitivity on consumables, while medical device OEMs in Switzerland tolerate premium coatings for validated sterility pathways.
Supply Chain Analysis
Process engineer scarcity in Dresden and Osaka constrains chamber matching and precursor optimization capacity for equipment vendors. Supply concentrates in Taiwan for foundry tool deployment, Germany for metal-organic precursor synthesis, and Japan for high-purity gas distribution. Raw material dependencies include hafnium tetrachloride, zirconium alkoxides, and NF3 etchant gases. Single-source vulnerability for hafnium precursors exposes fabs to supply disruption. Distribution runs through long-term service contracts bundling consumables and predictive maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around full-stack platform providers as REACH compliance costs and cleanroom capex intensity force subscale chemical suppliers and regional equipment assemblers toward exit or acquisition.
For Market Incumbents: Deploy backward integration into precursor synthesis to reduce German supplier dependency for hafnium and zirconium compounds. Secure captive supply through joint development agreements with Shin-Etsu Chemical or domestic Japanese alternatives. Lock in decade-long fleet performance contracts with Taiwan foundries to transfer operational risk and block emerging entrants from service infrastructure access. For New Entrants and Emerging Players: The premium-to-economy gap in deposition chemicals for Indian ATMP facilities offers white-space entry below qualified Western supplier pricing. Target Gujarat and Assam packaging capacity buildouts under PLI scheme subsidies. Pursue equipment-leasing models with localized service partnerships to circumvent upfront cleanroom capex barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor modular subsystem suppliers with selective deposition chamber expertise in Japan and South Korea. Long-term viability hinges on 2nm node qualification timelines and CHIPS Act fab completion rates. Watch EPA fluorinated precursor reporting enforcement as inflection signal for non-fluorinated chemistry R&D valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Synthesis | Captive supply of hafnium compounds reduces single-source exposure for Taiwan foundries. |
| Selective Deposition Module Development | Samsung and TSMC pilot line integration validates area-selective ALD for self-aligned contacts. |
| Long-term Service Contract Bundling | Full-fleet performance agreements lock in decade-long supplier relationships with Arizona fabs. |
| Non-fluorinated Chemistry R&D Acceleration | EPA Greenhouse Gas Reporting Program compliance drives tungsten and silicon precursor reformulation. |
| India Local Service Infrastructure Establishment | PLI scheme subsidies for Gujarat and Assam ATMP capacity create first-mover installation advantages. |
Study Parameters
Document review covered SEC 10-K filings from equipment vendors, ECHA REACH authorization databases, and SEMI industry statistics, complemented by interviews with process development engineers at Taiwan foundries, precursor procurement leads at South Korea memory fabs, and chamber design directors at Japanese equipment manufacturers. Secondary validation drew from EPA greenhouse gas reporting disclosures, customs trade data for metal-organic compounds, and CHIPS Act funding award announcements. Bottom-up equipment shipment tallies and top-down fab capex analysis were triangulated against foundry node migration roadmaps.
Segmented outputs across the projection horizon reflect technology type, end-use industry, application function, and regional fabrication cluster. CAGRs were derived from equipment order backlogs, precursor consumption intensity per wafer layer, and fab capacity expansion schedules. Industry-specific inputs included gate-all-around transistor architecture adoption curves, 3D NAND layer count trajectories, and silicon carbide epitaxial wafer demand from electric vehicle inverter specifications.
Inputs from EPA reporting databases and ECHA candidate list updates were available through the study window; gaps in selective deposition yield data from 2nm pilot lines introduce uncertainty bands around ALD penetration assumptions. Forecasts reflect documented assumptions on node migration timing and subsidy disbursement rates. Material deviation in CHIPS Act fab construction schedules or REACH authorization bottlenecks warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Semiconductor Etching Cleaner Market
Semiconductor Fabrication
Semiconductor Advanced Substrate Market
Semiconductor Fabrication
Global Dielectric Etchers Market
Semiconductor Fabrication
Manual Wafer Aligner Market
Semiconductor Fabrication
Additive Manufacturing in Semiconductor Market
Semiconductor Fabrication
Solar Ingot Wafer Market
Semiconductor Fabrication
Physical Vapor Deposition (PVD) Market
Semiconductor Fabrication
Semiconductor Logistics Market
Semiconductor Fabrication
Etchant for FPD Market
Semiconductor Fabrication
300mm Silicon Wafers Market
Semiconductor Fabrication
Semiconductor Foundry Market
Semiconductor Fabrication
Global Foundry Service Market
Semiconductor Fabrication
Solar Grade Wafer Market
Semiconductor Fabrication
Global Micromachining Market
Semiconductor Fabrication
Ion Implanter Market
Semiconductor Fabrication
Ion Implantation Machine Market