
 Semiconductor Intellectual Property Market | 2026-2036
Semiconductor Intellectual Property Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Intellectual Property Market Outlook
REACH compliance is expanding the documentation and substance-testing obligations for IP cores deployed in European automotive and industrial systems. Arm Holdings leverages its architecture licensing model to sustain royalty streams across multiple foundry nodes. Synopsys anchors its position through EDA-integrated IP verification tools that reduce customer design cycles.
Semiconductor intellectual property encompasses reusable design blocks—ranging from standard cell libraries to complex processor cores and interface controllers—that are licensed for integration into custom chips, typically specified at process nodes from 28nm to 3nm with power, performance, and area constraints. These assets enable fabless companies to accelerate time-to-market without developing foundational circuitry from scratch. Soft IP, delivered as synthesizable RTL code, captures the fastest growth as customers demand portability across foundries and process nodes. Digital IP for interface protocols and security accelerators commands premium pricing due to complexity and certification requirements. Hard IP, while mature, still dominates in analog and mixed-signal applications where physical layout directly determines performance.
The EU AI Act, FDA software-as-medical-device guidance, and China's GB standards for information security are collectively tightening validation requirements for IP used in safety-critical and AI-enabled systems. These frameworks force vendors to maintain traceable development records and third-party certification, raising barriers for smaller licensors. Stakeholders must weigh the cost of compliance infrastructure against the revenue premium available in regulated end markets.
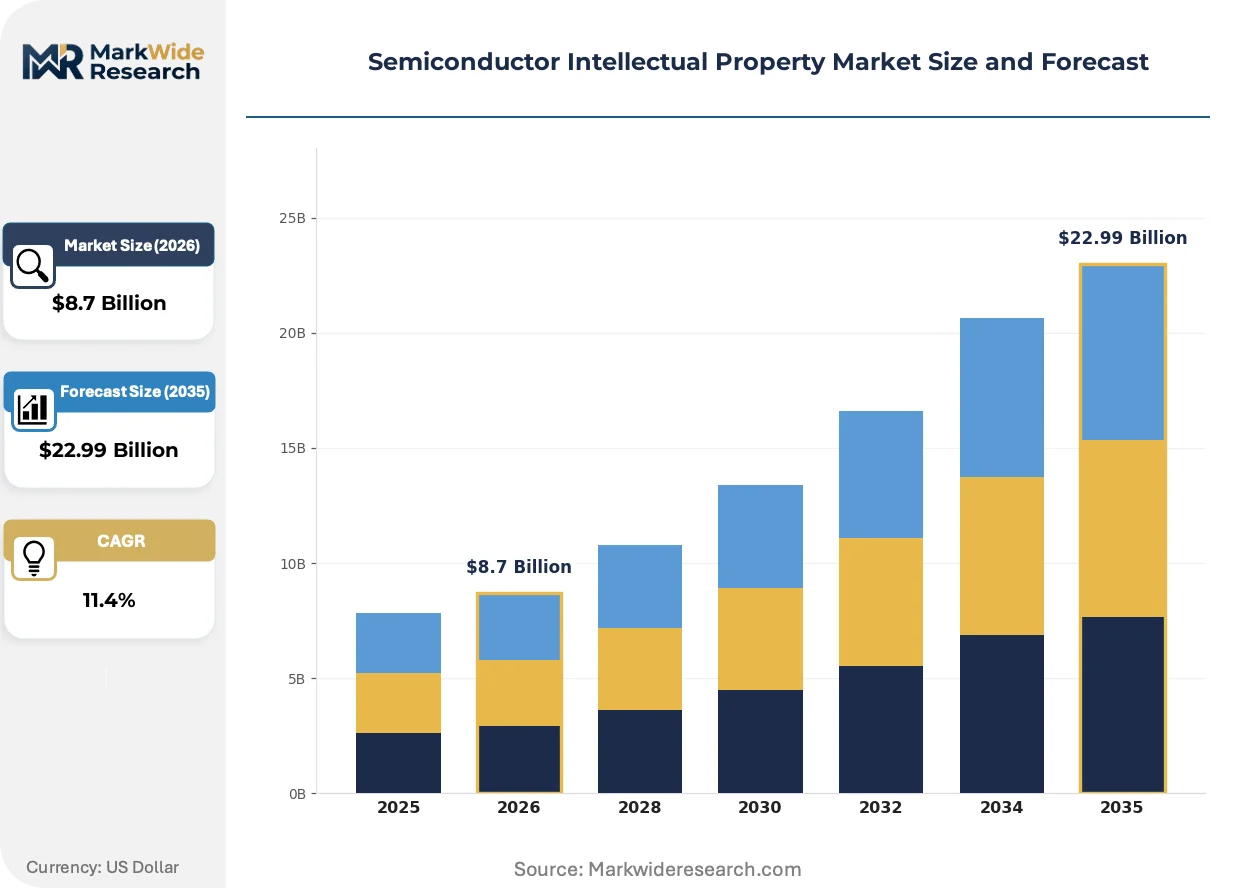
Market Dynamics
Foundry-IP co-development partnerships are compressing design cycles for advanced-node SoCs, concentrating capability among vertically integrated licensors who can validate silicon across multiple process technologies simultaneously.
Growth Catalysts
- Automotive Safety Mandates:EU AI Act certification requirements for autonomous driving processors are accelerating licensing of ASIL-D compliant cores by German and Japanese OEMs.
- Chiplets:Die-to-die interconnect standards are expanding addressable markets for interface IP as heterogeneous integration replaces monolithic SoC architectures.
- Hsinchu Cluster:Taiwan's foundry ecosystem is pulling demand for process-portable soft IP that migrates across 28nm to 3nm nodes without redesign.
Market Restraints
- Advanced Node Access:Export control frameworks on EUV lithography equipment are restricting Chinese fabless companies from licensing leading-edge IP portfolios.
- Certification Cost Burden:REACH substance documentation and third-party silicon validation are raising fixed costs for IP vendors serving European automotive markets.
- Foundry Concentration:Taiwan's geographic exposure creates supply continuity risk for hard IP physically characterized at TSMC-specific process nodes.
Strategic Opportunities
- RISC-V Ecosystem:Open-source instruction set architectures are creating white space for custom processor IP outside Arm's licensing umbrella.
- India PLI Scheme:Domestic semiconductor fabrication incentives are attracting IP vendors to establish design centers in Gujarat and Karnataka.
- Security Accelerators:Post-quantum cryptography standards are driving demand for hardware root-of-trust modules in data center and government applications.
Industry Challenges
- Verification Talent Scarcity:Formal methods engineers and silicon validation specialists command premium compensation, constraining IP vendor scaling.
- Multi-Foundry Qualification:Porting physical IP across Samsung, Intel, and TSMC process variants requires duplicate characterization runs that extend time-to-revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Intellectual Property Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft IP, Hard IP, Analog IP, Digital IP Technology: FPGA, ASIC, SoC, RTL End User: Telecommunications, Consumer Electronics, Automotive, Industrial Automation Application: Network Security, Data Processing, Embedded Systems, Machine Learning |
| Companies Covered | Arm Holdings, Synopsys, Cadence Design Systems, Imagination Technologies, Rambus, CEVA, Lattice Semiconductor, eMemory Technology, VeriSilicon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Intellectual Property Market Strategic Shifts
Silicon-proven subsystem integration is displacing discrete IP block licensing as customers prioritize pre-verified bundles that reduce system-level verification burden and accelerate tape-out schedules.
Soft IP delivered as synthesizable RTL is expanding into safety-critical automotive applications as customers demand portability across foundry nodes without physical redesign. German Tier-1 suppliers are adopting configurable processor cores that retarget across 22nm and 5nm processes within a single licensing agreement. This flexibility is compressing the traditional hard IP lock-in model that tied customers to specific foundry partnerships.
EU AI Act conformity assessment procedures are mandating traceable development records for IP deployed in high-risk AI systems. IP vendors must now maintain documented verification evidence and third-party certification chains that extend from RTL through physical implementation. Medical device and autonomous vehicle segments are absorbing these compliance costs through premium pricing for pre-certified IP subsystems.
Consolidated procurement of IP-EDA bundles is displacing discrete licensing negotiations as buyers seek integrated tool flows that compress design closure timelines. Taiwan's Hsinchu Science Park cluster exhibits the strongest concentration of this behavior, where foundry customers negotiate combined access to design libraries and verification environments. This bundling pressures standalone IP vendors to anchor through EDA partnerships or risk margin compression.
Semiconductor Intellectual Property Market Segmentation
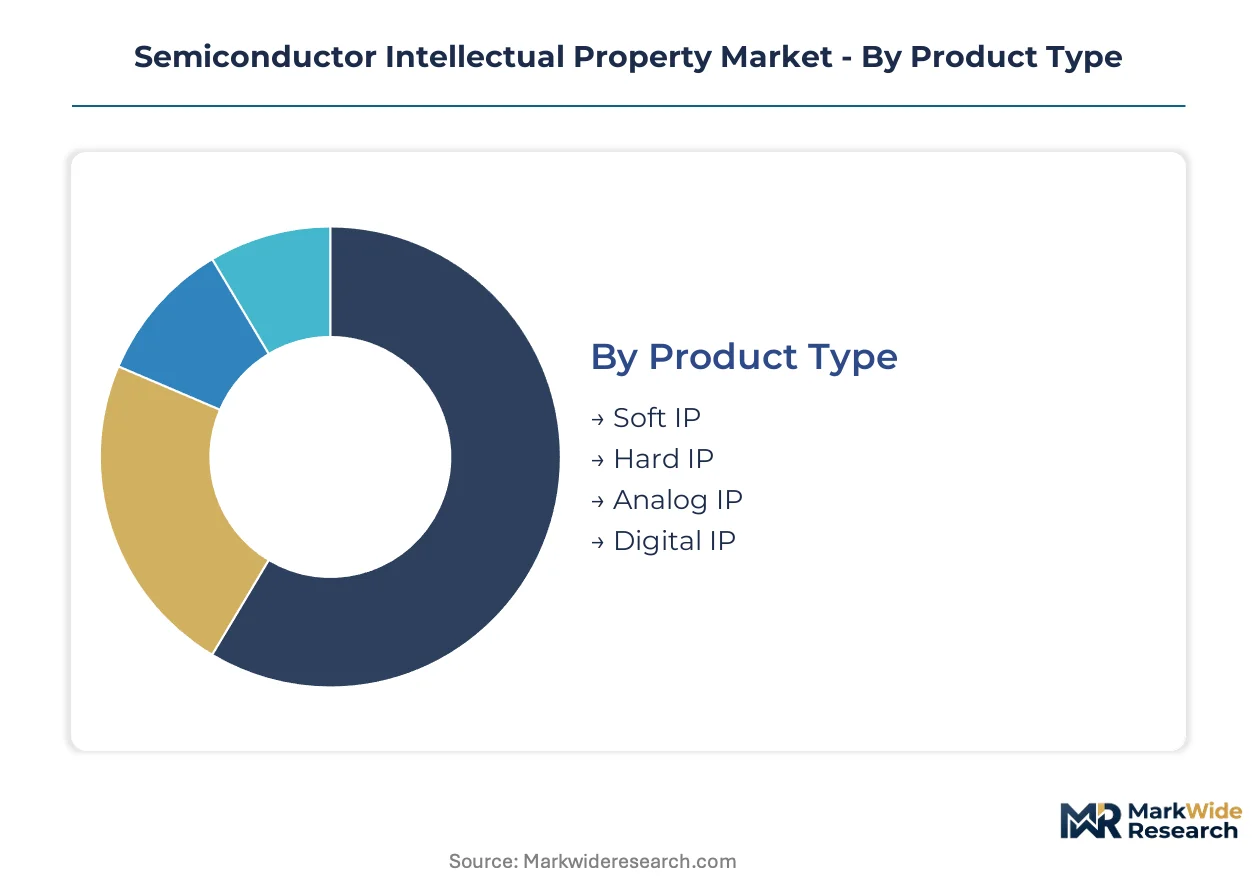
Semiconductor IP segmentation reveals divergent margin structures across physical versus synthesizable assets. Understanding these splits guides vendor resource allocation between high-volume standard products and premium-certified offerings.
Product Type:
Volume concentrates in portable code assets, while premium pricing attaches to physically characterized blocks.
- Soft IP:Delivered as synthesizable RTL code, this segment enables retargeting across foundry nodes without physical redesign. Automotive Tier-1 suppliers in Germany are adopting configurable processor cores that migrate across 22nm and 5nm processes within single licensing agreements, compressing traditional hard IP lock-in models.
- Hard IP:Physically characterized layouts for specific process nodes command premium pricing where analog performance depends on precise geometry. Taiwan's Hsinchu cluster dominates procurement of TSMC-specific hard IP for mixed-signal applications, though geographic concentration creates supply continuity exposure.
- Analog IP:PLLs, ADCs, and SerDes blocks where layout directly determines signal integrity and power consumption.
- Digital IP:Standard cell libraries and memory compilers serving high-volume digital SoC integration.
Mature deployment sits with Hard IP. Newer deployment is concentrated in Soft IP.
Technology:
Application-specific integration methods separate high-volume consumer deployments from low-volume aerospace and defense programs.
- SoC:System-on-chip integration absorbs the majority of advanced-node IP licensing as heterogeneous computing demands combine CPU, GPU, NPU, and I/O subsystems on single die. Taiwan's foundry ecosystem pulls demand for process-portable soft IP that migrates across 28nm to 3nm nodes without redesign.
- ASIC:Custom silicon for specific workloads commands premium unit economics in data center and networking applications where power efficiency justifies non-recurring engineering costs.
- FPGA:Field-programmable gate arrays serve prototyping and low-volume production where mask costs prohibit full custom designs.
- RTL:Register-transfer level descriptions form the foundational deliverable for soft IP portability across synthesis targets.
Established revenue flows through ASIC. Fastest expansion is occurring in SoC.
End User:
Regulatory intensity varies sharply across end markets, with automotive and medical applications absorbing compliance premiums.
- Automotive:Safety-certified processor cores for autonomous driving systems command substantial pricing premiums as EU AI Act and ASIL-D requirements mandate traceable development records. German and Japanese OEMs are accelerating licensing of pre-certified IP subsystems to compress validation timelines.
- Telecommunications:Baseband processors and network interface controllers drive high-volume licensing for 5G infrastructure deployment across multiple foundry nodes.
- Consumer Electronics:Mobile application processors and multimedia subsystems prioritize area and power optimization over certification depth.
- Industrial Automation:Real-time control systems and safety PLCs require deterministic performance with extended temperature qualification.
Volume leadership belongs to Consumer Electronics. Value concentration is shifting toward Automotive.
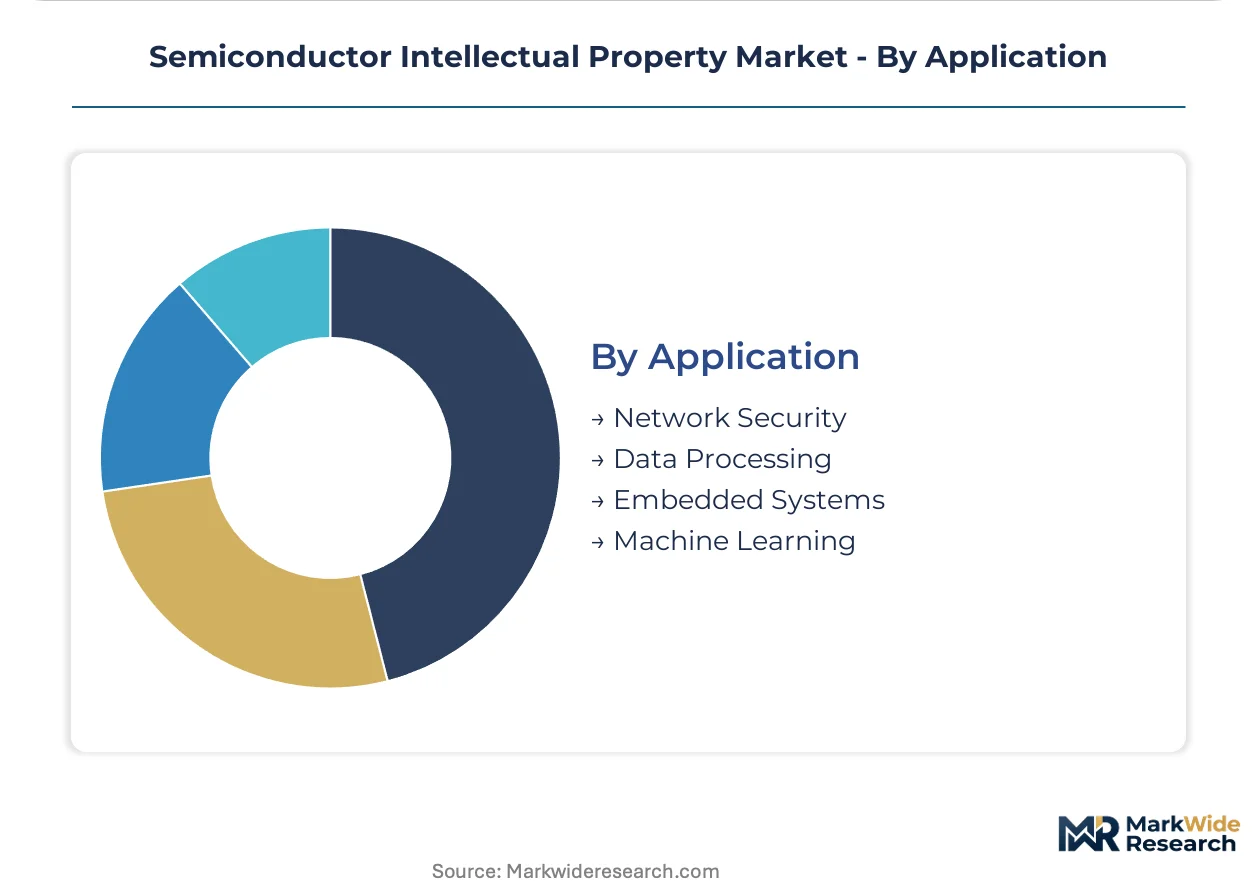
Application:
Security-critical workloads are decoupling from general-purpose processing, creating specialized IP categories.
- Machine Learning:Neural network accelerators and matrix multiplication engines are expanding addressable markets as edge AI deployment drives demand for INT8 and BF16-optimized datapaths. Post-quantum cryptography standards are further driving hardware root-of-trust integration.
- Network Security:Cryptographic accelerators, secure enclaves, and trusted execution environments command premium pricing in data center and government applications where FIPS 140-2 and Common Criteria certification is mandatory.
- Data Processing:General-purpose compute subsystems serving cloud and enterprise workloads.
- Embedded Systems:Microcontroller cores and peripheral controllers for resource-constrained environments.
Commodity positioning characterizes Embedded Systems. Steepest expansion trajectory is evident in Machine Learning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park's foundry-IP co-development ecosystem concentrates advanced-node design activity, while Germany's automotive safety mandates and India's PLI incentives reshape geographic demand patterns.
United States
Data center AI accelerators and defense-grade secure processors drive licensing demand from cloud hyperscalers and federal contractors. FDA software-as-medical-device guidance tightens validation requirements for IP deployed in healthcare applications. Austin's semiconductor corridor hosts design centers where vendors develop process-portable cores for multi-foundry deployment.
Germany
ASIL-D certified processor cores for autonomous driving systems command premium pricing from Tier-1 automotive suppliers. KBA safety mandates and EU AI Act conformity assessments mandate traceable development records for high-risk AI systems. Munich-Stuttgart industrial belt concentrates procurement of pre-certified IP subsystems that compress validation timelines.
Japan
Automotive OEMs accelerate licensing of safety-certified cores for next-generation vehicle architectures. METI semiconductor revitalization policies subsidize domestic IP development and foundry partnerships. Tokyo-Osaka corridor anchors design activity for mixed-signal and automotive applications with extended temperature qualification.
Taiwan
Foundry-IP co-development partnerships dominate leading-edge SoC design for 3nm and 5nm processes. Export control frameworks on EUV lithography equipment reshape compliance burdens for Chinese-facing IP transactions. Hsinchu Science Park cluster pulls demand for soft IP that migrates across process nodes without physical redesign.
India
Domestic semiconductor fabrication incentives attract IP vendors to establish design centers for fabless ecosystem support. PLI scheme subsidies for chip design and ATMP operations reduce cost barriers for local IP development. Gujarat and Karnataka emerging as hubs where vendors configure processor cores for industrial automation and telecommunications applications.
Semiconductor Intellectual Property Market Competitive Environment
United States producers anchor the premium-tier ecosystem; European and Asian specialists hold differentiated positions in automotive safety and analog integration. The vendor base stratifies across architecture licensors, EDA-integrated IP providers, and application-specific subsystem vendors. Three archetypes dominate: vertically integrated architecture stewards, EDA-platform anchors, and open-source ecosystem enablers. Competitive moves concentrate on strategic partnerships with foundry ecosystems and certification pre-qualification for regulated end markets.
Within the architecture licensing tier, Arm Holdings exemplifies the royalty-sustaining model across multiple foundry nodes. Synopsys and Cadence Design Systems occupy positions as EDA-integrated providers whose verification tool ecosystems reduce customer design cycles. These three anchors represent distinct competitive vectors: instruction set architecture control, design automation platform dominance, and silicon-proven subsystem bundling.
| Leading Market Players |
|---|
| Arm Holdings |
| Synopsys |
| Cadence Design Systems |
| Imagination Technologies |
| Rambus |
| CEVA |
| Lattice Semiconductor |
| eMemory Technology |
| VeriSilicon |
| Others |
Value Chain & Pricing Dynamics
Formal methods engineers concentrated in Hsinchu and Austin command premium compensation that compresses margins for IP vendors serving price-sensitive consumer electronics segments while sustaining wide spreads for ASIL-D certified automotive cores.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement negotiations, with German Tier-1 suppliers paying substantial premiums for pre-certified IP subsystems that compress validation timelines while spot inventory of mature hard IP trades at discounts. The market operates on a licensing-plus-royalty hybrid model where architecture stewards capture recurring revenue streams across multiple foundry nodes. Price differentiation separates EU AI Act-compliant safety cores from general-purpose processor IP, with certification grade and volume scale as primary tiering mechanisms. Pricing pressure stems from bundled IP-EDA procurement in Taiwan's foundry ecosystem, where consolidated negotiations compress standalone vendor margins. Consumer electronics buyers exhibit highest price sensitivity, while automotive OEMs absorb compliance premiums for traceable development records.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from cloud providers and automotive platforms, while EDA-integrated distribution serves mid-tier fabless companies through bundled tool flows. Supply concentrates in Taiwan's Hsinchu cluster for advanced-node physical IP, with South Korea and the United States anchoring memory compiler and analog block development. Raw material dependencies center on EUV lithography equipment access, process characterization data, and specialized EDA tool licenses. Single-source vulnerability from Taiwan's geographic exposure creates supply continuity risk for hard IP physically characterized at TSMC-specific nodes. Distribution runs through foundry-authorized design centers and direct licensing agreements with architecture stewards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Semiconductor Intellectual Property Market functions as a vertical-integration race where control over verification tool ecosystems and foundry co-development partnerships determines pricing power and customer lock-in.
For Market Incumbents: Deepen foundry-IP co-development partnerships at 3nm and 5nm nodes to anchor customer design cycles and defend against RISC-V ecosystem encroachment. Invest in in-house formal methods engineering capacity in Austin and Hsinchu to reduce reliance on scarce verification talent. Prioritize pre-certification of processor cores to EU AI Act and ASIL-D standards before competitor completion. For New Entrants and Emerging Players: India's PLI scheme subsidies for chip design open a window for establishing processor core configuration centers in Gujarat and Karnataka serving industrial automation and telecommunications applications. Target security accelerator segments where post-quantum cryptography hardware root-of-trust modules command premium pricing absent entrenched incumbents. Pursue RISC-V custom core development for data center and edge AI applications outside Arm's licensing umbrella. For Investors and Strategic Acquirers: The window for entry favors EDA-integrated IP providers with verification tool ecosystems that reduce customer design closure timelines. Long-term viability rests on silicon-proven subsystem bundling capabilities that displace discrete IP block licensing. Watch for inflection signals in heterogeneous integration adoption rates as die-to-die interconnect standards reshape addressable markets for interface IP.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry-IP Co-Development Partnership | TSMC's 3nm process characterization data accelerates time-to-silicon for advanced SoC designs. |
| ASIL-D Pre-Certification Investment | Third-party silicon validation from TÜV Rheinland compresses German OEM procurement cycles. |
| Security Accelerator Product Launch | FIPS 140-2 certification enables penetration into federal contractor and data center segments. |
| RISC-V Ecosystem Platform Integration | Open-source instruction set architectures create white space outside Arm's royalty structure. |
| India Design Center Geographic Expansion | PLI scheme subsidies in Karnataka reduce cost barriers for fabless ecosystem support services. |
Study Parameters
SEC filings from architecture licensors, EDA platform providers, and foundry operators formed the secondary backbone, supplemented by customs data on semiconductor equipment flows and EU regulatory filings on AI Act implementation. Primary interviews with IP vendor product managers, foundry design enablement directors, automotive Tier-1 procurement leads, and verification tool engineers validated secondary estimates. Bottom-up triangulation across licensing transaction volumes and top-down reconciliation against foundry wafer start data ensured cross-verified outputs.
Historical trendline analysis of royalty revenue growth and licensing transaction volumes established baseline momentum vectors across the projection horizon. The analytical framework segmented by product type (soft IP, hard IP, analog, digital), end-use application (automotive, telecommunications, consumer electronics, industrial), and technology integration method (SoC, ASIC, FPGA). CAGRs derived from regression analysis of node migration patterns and heterogeneous integration adoption curves. Industry-specific inputs included EUV lithography equipment deployment schedules and REACH compliance cost trajectories for European automotive markets.
The model assumes a particular technology adoption path for chiplets and die-to-die interconnect standards; alternative pathways for monolithic SoC architectures would alter the outlook for interface IP demand. Forecasts reflect assumptions on foundry capacity allocation and export control enforcement intensity that could shift with regulatory revisions. Periodic stress-testing of base assumptions against silicon wafer input costs and verification engineer compensation trends is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Semiconductor in Military and Aerospace Market
Semiconductors
Asia Pacific Flash Memory Market
Semiconductors
Europe Semiconductor Market
Semiconductors
Europe Discrete Semiconductor Market
Semiconductors
Discrete Semiconductor Market
Semiconductors
Europe Automotive Semiconductor Market
Semiconductors
Analog Semiconductor Market
Semiconductors
Semiconductor Bonding Market
Semiconductors
Global FD-SOI Wafers Market
Semiconductors
ASEAN Semiconductor Market
Semiconductors
India Semiconductor Market
Semiconductors
Global Computer Microchip Market
Semiconductors
Logic Semiconductor Market
Semiconductors
China Discrete Semiconductors Market
Semiconductors
Wide Bandgap Semiconductors Market
Semiconductors
Compound Semiconductor Market