
 Solar Grade Wafer Market | 2026-2036
Solar Grade Wafer Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Grade Wafer Market Insights
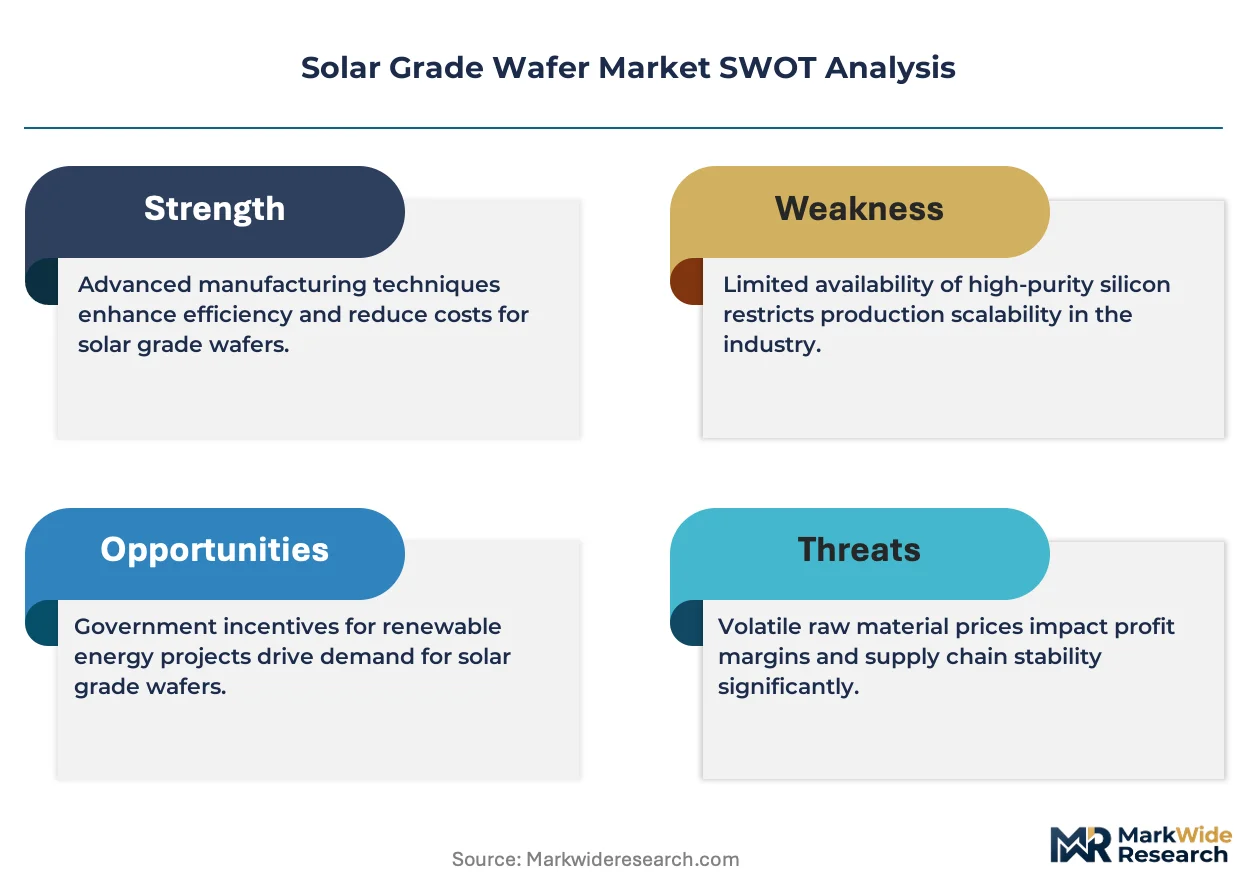
Polysilicon-to-wafer margin migration is rewriting competitive economics across the solar value chain. LONGi Green Energy Technology Co., Ltd. leverages full backward integration from polysilicon through cell production to capture margin pools that previously accrued to pure-play wafer vendors. TCL Zhonghuan Renewable Energy Technology Co., Ltd. anchors its position through ultra-large 210mm wafer formats that reduce downstream balance-of-system costs for utility developers. GCL-Poly Energy Holdings Limited competes through granular poly and wafer cost leadership in the multi-silicon tier serving price-sensitive distributed solar markets.
A solar grade wafer is a thin, circular slice of high-purity crystalline silicon, typically 150–210mm in diameter and 130–180 micrometers thick, produced via the Czochralski or directional solidification process for photovoltaic cell fabrication. Its primary purpose is to serve as the semiconductor substrate where photon absorption generates electron-hole pairs for electricity conversion. Mono-silicon wafers dominate product type margins due to superior conversion efficiency in PERC and TOPCon cell architectures, while bifacial formats represent the fastest-growing application segment as utility developers seek dual-side energy yield. Crystalline silicon technology sustains structural dominance, though gallium arsenide wafers occupy niche positions in concentrated photovoltaics where efficiency premiums justify material costs.
China's MIIT enforces GB standards on wafer dimensional tolerances and carbon intensity disclosures, while the EU Green Deal's carbon border adjustment mechanism shapes import competitiveness for non-European wafer suppliers. The US IRA production tax credits are reshoring some polysilicon and ingot capacity, though wafer slicing remains concentrated in Asia. Stakeholders must monitor how evolving country-of-origin rules and embodied-carbon accounting reshape sourcing decisions for module assembly.
Market Dynamics
Polysilicon-to-wafer margin migration is compressing pure-play wafer vendors while rewarding integrated producers with captive feedstock supply. China's MIIT carbon disclosure mandates and the EU Green Deal's embodied-carbon rules are reshaping import competitiveness for crystalline silicon substrates.
Growth Catalysts
- Utility-scale solar deployment:India and the Middle East are procuring high-efficiency mono-silicon wafers at volume for gigawatt-scale photovoltaic installations.
- EU Green Deal carbon border adjustments:The CBAM is tightening embodied-carbon thresholds for imported wafers, favoring manufacturers with low-carbon polysilicon supply chains.
- Hydropower-proximate production:Xinjiang and Yunnan provinces cluster integrated ingot-to-wafer plants near renewable energy and feedstock sources.
Market Restraints
- Polysilicon price volatility:Metallurgical-grade silicon and trichlorosilane input costs swing with energy prices, squeezing wafer fabrication margins.
- Xinjiang supply concentration:Geographic clustering of polysilicon feedstock and wafer slicing capacity creates geopolitical and logistics risk for international buyers.
- Multi-silicon efficiency ceiling:Directional solidification wafers hit conversion efficiency limits below PERC and TOPCon cell requirements.
Strategic Opportunities
- US IRA reshoring incentives:Production tax credits are attracting polysilicon and ingot capacity investment outside Asia for the first time in a decade.
- Bifacial module architectures:Dual-side energy yield formats are opening premium wafer tiers for utility developers seeking levelized cost reductions.
- Gallium arsenide niche expansion:Concentrated photovoltaics in desert installations are justifying material cost premiums for III-V compound substrates.
Industry Challenges
- Czochralski crystal growth expertise:The talent pipeline for 210mm monocrystal pulling and defect control remains shallow relative to capacity expansion plans.
- GB standard compliance timelines:China's MIIT dimensional tolerance and carbon intensity disclosure rules are forcing documentation system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Grade Wafer Market |
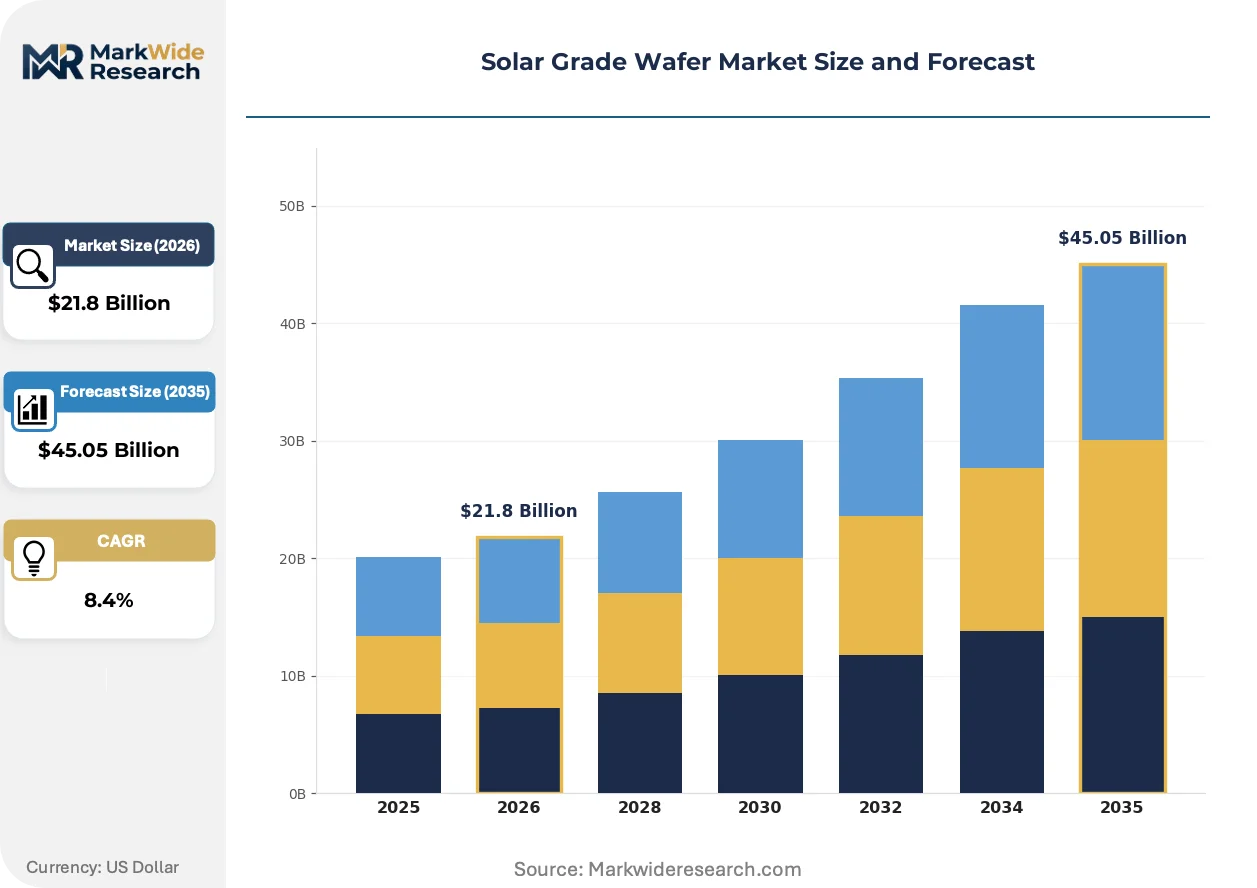
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $45.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mono-Silicon, Multi-Silicon, Thin Film, Bifacial Application: Residential, Commercial, Utility, Off-Grid Technology: Crystalline Silicon, Cadmium Telluride, Amorphous Silicon, Gallium Arsenide End User: Builders, Renewable Energy Companies, Investors, Research Institutions |
| Companies Covered | LONGi Green Energy Technology Co., Ltd., TCL Zhonghuan Renewable Energy Technology Co., Ltd., GCL-Poly Energy Holdings Limited, JinkoSolar Holding Co., Ltd., JA Solar Holdings Co., Ltd., Trina Solar Co., Ltd., Renewable Energy Corporation, Renesola, Sino-American Silicon Products Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Grade Wafer Market Trends and Innovations
Wafer format wars and cell architecture evolution are redefining equipment amortization and factory design across photovoltaic substrate manufacturing.
Ultra-large 210mm wafer formats are rendering obsolete legacy 156mm and 166mm production lines. Utility developers adopting these substrates slash balance-of-system costs through reduced cell interconnects and module framing. The transition is compressing equipment replacement cycles for ingot growers and diamond-wire slicers.
EU Green Deal carbon border adjustments are forcing embodied-carbon accounting across imported wafer supply chains. Manufacturers must now document polysilicon provenance and energy inputs to maintain European market access. Low-certificate producers in hydropower-rich regions are gaining procurement preference from module assemblers.
Long-term offtake contracting is displacing spot-market wafer procurement for tier-one module manufacturers. Vertically integrated cell producers are locking multi-year supply agreements directly with ingot growers, bypassing traditional merchant wafer distributors. This pattern concentrates most visibly in China, where LONGi and TCL Zhonghuan anchor bilateral supply relationships.
Solar Grade Wafer Market Segmentation
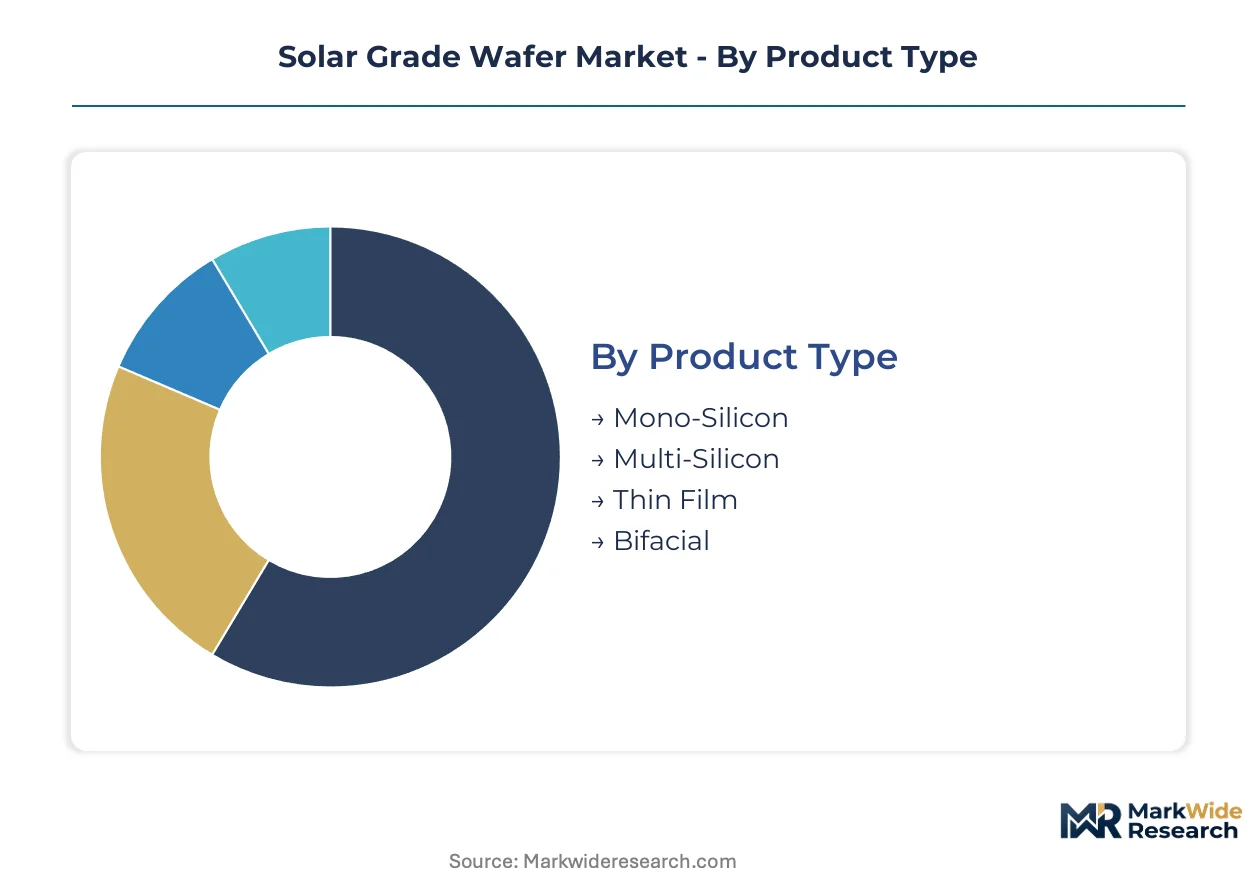
Wafer segmentation reveals how crystalline silicon architectures dominate procurement decisions while emerging formats capture premium niches. Each dimension—product type, application, technology, and end user—reflects distinct margin pools and technical requirements that reshape factory investment and customer targeting.
Product Type:
Mature mono-silicon formats anchor volume production while emerging bifacial structures redefine utility economics.
- Mono-Silicon:Single-crystal substrates pulled via Czochralski growth achieve the highest conversion efficiencies in PERC and TOPCon cell architectures. Indian and Middle Eastern utility developers concentrate procurement here for gigawatt-scale projects where efficiency premiums offset balance-of-system costs.
- Bifacial:Dual-side light-capturing wafers enable energy yield from reflected and diffuse radiation on rear surfaces. Desert installations in the UAE and Saudi Arabia drive adoption where albedo conditions maximize dual-side gain.
- Multi-Silicon:Directional solidification ingots serve price-sensitive distributed markets through cost leadership in polysilicon feedstock conversion.
- Thin Film:Cadmium telluride and amorphous silicon depositions occupy building-integrated applications where weight and flexibility outweigh efficiency metrics.
Mono-silicon handles the majority of throughput; bifacial is climbing the fastest on share.
Application:
Volume concentration follows cost tier differentiation across customer scale and project sophistication.
- Utility:Centralized photovoltaic plants exceeding 50MW capacity demand 210mm mono-silicon wafers with tight dimensional tolerances for automated cell assembly. China's Xinjiang and Yunnan provinces cluster manufacturing to serve this segment through hydropower-proximate production.
- Residential:Rooftop installations favor standardized 166mm and 182mm formats where module aesthetics and installation simplicity outweigh marginal efficiency gains. European Green Deal carbon accounting increasingly filters procurement toward low-embodied-carbon wafer sources.
- Commercial:Mid-scale distributed generation on industrial rooftops balances efficiency requirements against capital constraints through multi-silicon and standard mono-silicon hybrids.
- Off-Grid:Remote power systems prioritize reliability and temperature coefficient performance over maximum efficiency, accepting thinner wafers and alternative crystallization methods.
Utility-scale deployment commands the dominant revenue pool; residential applications are expanding most quickly on installed base.
Technology:
Supply concentration crystallizes around silicon purification and crystal growth expertise while compound semiconductors defend niche positions.
- Crystalline Silicon:Czochralski and directional solidification processes produce over ninety percent of photovoltaic substrates through ingot pulling and block casting methods. China's MIIT GB standards govern dimensional tolerances and carbon intensity disclosures for this dominant technology class.
- Gallium Arsenide:III-V compound substrates achieve conversion efficiencies exceeding silicon limits through multi-junction architectures. Concentrated photovoltaic installations in desert environments justify material cost premiums where optical concentration dilutes substrate expense per watt.
- Cadmium Telluride:Vapor transport deposition creates thin-film panels without silicon feedstock exposure, capturing utility-scale share where manufacturing scale offsets efficiency disadvantages.
- Amorphous Silicon:Plasma-enhanced chemical vapor deposition produces flexible, lightweight substrates for consumer electronics and building-integrated applications requiring mechanical compliance.
Crystalline silicon maintains absolute volume dominance; gallium arsenide exhibits the steepest expansion trajectory in efficiency-premium segments.
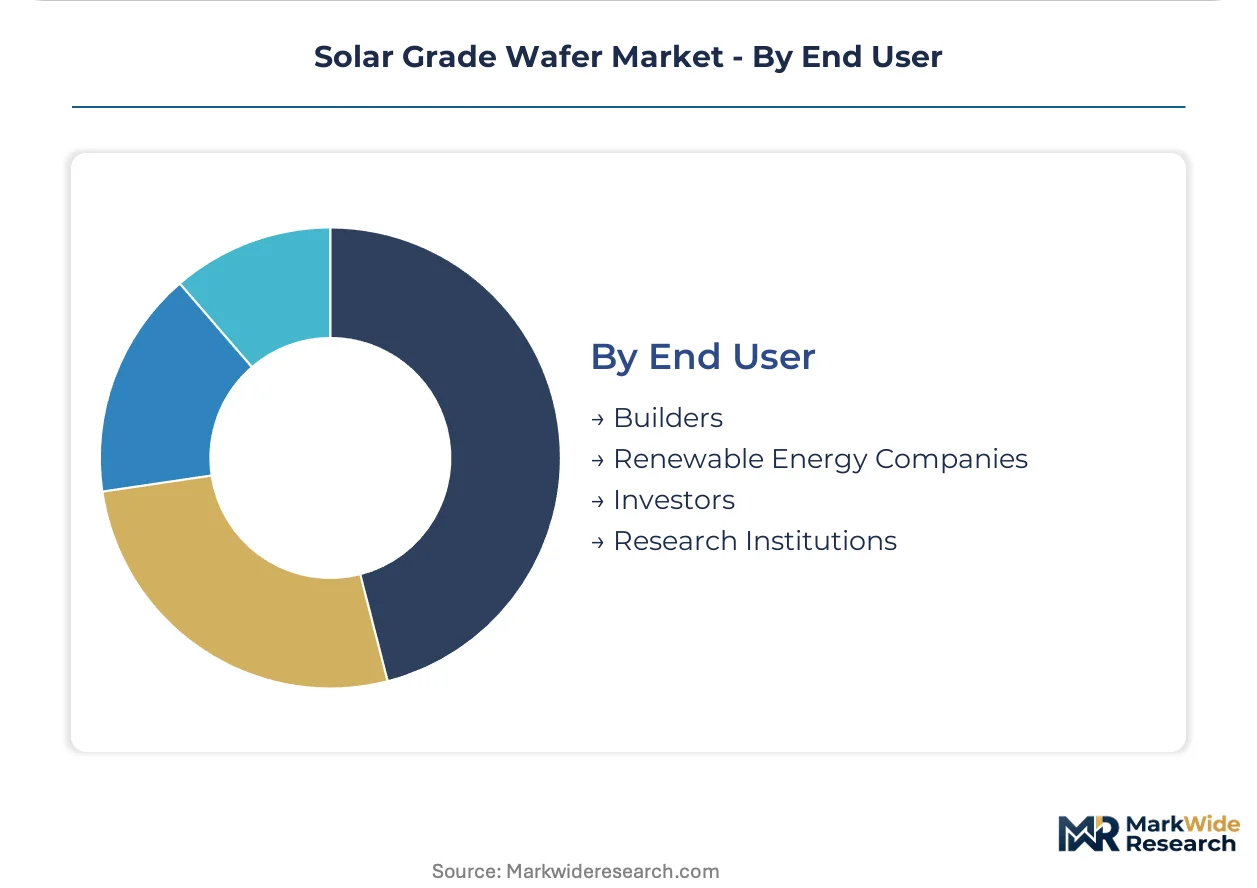
End User:
Customer type segmentation maps to procurement sophistication and contract structure variation.
- Renewable Energy Companies:Vertically integrated developers and independent power producers negotiate multi-year offtake agreements directly with ingot growers, bypassing merchant wafer distributors to secure volume and price predictability.
- Builders:Construction firms and engineering-procurement-construction contractors source wafers through module assemblers, prioritizing logistics coordination and installation compatibility over substrate specifications.
- Investors:Infrastructure funds and green bond issuers evaluate wafer supply chains through embodied-carbon accounting and country-of-origin risk frameworks, particularly under EU Green Deal CBAM compliance requirements.
- Research Institutions:National laboratories and university programs procure specialized wafer formats for next-generation cell architecture development, including heterojunction and tandem cell substrates.
Renewable energy companies drive the bulk of commercial volume; research institutions are gaining share fastest in premium specialty formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wafer slicing capacity clusters near polysilicon feedstock and low-cost power sources, with hydropower-rich provinces in China anchoring the dominant supply base. India's utility-scale procurement and Middle Eastern desert installations are redrawing demand geography. Regulatory carbon accounting in Europe and North America is fragmenting import competitiveness across supplier nations.
China
Xinjiang and Yunnan provinces host integrated ingot-to-wafer plants powered by hydropower and captive polysilicon sources. MIIT enforces GB standards on dimensional tolerances and carbon intensity disclosures that filter export eligibility. The dual carbon goals accelerate capacity migration toward renewable-powered industrial parks in southwestern China.
United States
IRA production tax credits are reshoring polysilicon and ingot capacity for the first time in a decade, though wafer slicing remains import-dependent. FERC interconnection rules and domestic content bonuses shape procurement math for utility developers. Arizona and Texas emerge as early concentration points for upstream silicon purification investments.
India
Utility-scale solar tenders exceeding 50GW drive procurement of 210mm mono-silicon wafers for gigawatt photovoltaic parks in Rajasthan and Gujarat. CEA mandates and PLI scheme incentives favor domestic module assembly, though wafer imports still dominate. Manufacturing clusters in Andhra Pradesh and Tamil Nadu attract cell and module investments that tighten backward integration timelines.
Germany
EU Green Deal carbon border adjustments tighten embodied-carbon thresholds for imported crystalline silicon substrates. REACH compliance and CSRD disclosure rules force documentation of polysilicon provenance across supply chains. Industrial demand concentrates in Bavaria and North Rhine-Westphalia for building-integrated and commercial rooftop installations.
Saudi Arabia
Desert utility installations and NEOM giga-projects procure bifacial wafers optimized for high-albedo energy yield. MOHAP and national industrial development programs support downstream module assembly capacity. Manufacturing zones in the Eastern Province and Western Region cluster near port infrastructure for export-oriented production.
Solar Grade Wafer Market Competitive Landscape
Backward-integrated polysilicon producers and pure-play wafer specialists split the market into margin-capture versus flexibility camps. The structure concentrates around tier-one module manufacturers locking multi-year offtake agreements directly with ingot growers. Three archetypes dominate: captive-feedstock integrated giants, format-specialist scale players, and cost-leader multi-silicon vendors. Competitive moves center on 210mm capacity conversion and bilateral supply contract negotiation.
Among Chinese integrated producers, LONGi Green Energy Technology Co., Ltd. and TCL Zhonghuan Renewable Energy Technology Co., Ltd. exemplify the backward-integration archetype with control from polysilicon through cell production. GCL-Poly Energy Holdings Limited occupies a position within the cost-leadership tier serving price-sensitive distributed markets. These three anchors represent the strategic spectrum: full integration versus format specialization versus feedstock efficiency.
| Leading Market Players |
|---|
| LONGi Green Energy Technology Co., Ltd. |
| TCL Zhonghuan Renewable Energy Technology Co., Ltd. |
| GCL-Poly Energy Holdings Limited |
| JinkoSolar Holding Co., Ltd. |
| JA Solar Holdings Co., Ltd. |
| Trina Solar Co., Ltd. |
| Renewable Energy Corporation |
| Renesola |
| Sino-American Silicon Products Inc. |
| Others |
Pricing and Supply Chain Analysis
Xinjiang's integrated ingot-to-wafer clusters leverage captive polysilicon and hydropower to compress production costs, translating geographic supply concentration into asymmetric pricing power over downstream module assemblers. The EU Green Deal's carbon border adjustment mechanism and China's MIIT disclosure mandates are bifurcating procurement premiums between low-certificate and high-carbon wafer sources.
Pricing Analysis
EU Green Deal carbon border adjustments dictate the pricing tier structure across crystalline silicon substrate imports. Three-tier pricing structure across premium, standard, and economy levels separates hydropower-proximate mono-silicon from coal-intensive multi-silicon and thin-film alternatives. Cost compression in the multi-silicon tier is intensifying because directional solidification wafers face efficiency ceilings below PERC and TOPCon requirements. Distributed solar installers in residential and commercial segments exhibit highest price sensitivity, while utility developers prioritize efficiency premiums and carbon certification over unit economics.
Supply Chain Analysis
Export-control regimes on semiconductor manufacturing equipment limit wafer slicing technology flows to non-Chinese producers, constraining capacity diversification. Manufacturing gravity centers on China, Vietnam, and Malaysia, with polysilicon feedstock drawn from Xinjiang, Inner Mongolia, and Yunnan provinces. Metallurgical-grade silicon, trichlorosilane, and diamond-wire consumables constitute critical input dependencies. Single-source vulnerability concentrates in Xinjiang polysilicon purification, where geographic clustering creates geopolitical and logistics exposure. Distribution runs through long-term bilateral offtake contracts directly between ingot growers and tier-one module manufacturers, displacing traditional merchant wafer distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shallow talent pipeline for 210mm Czochralski crystal growth and defect control represents the binding constraint on capacity expansion, rewarding players who secure specialized engineering capabilities before competitors. Wafer format transitions and embodied-carbon compliance are reshaping competitive positioning faster than capital deployment can match.
For Market Incumbents: Build captive-feedstock moats through backward integration into polysilicon purification and ingot pulling. Secure multi-year offtake agreements with Indian and Middle Eastern utility developers before emerging entrants capture procurement relationships. Invest in carbon accounting documentation systems to maintain EU market access under tightening CBAM thresholds. Defend against pure-play wafer vendors by leveraging scale advantages in 210mm format conversion. For New Entrants and Emerging Players: Establish a beachhead in gallium arsenide substrates for concentrated photovoltaic installations where efficiency premiums justify material costs and incumbent concentration remains lowest. Target US IRA reshoring incentives for polysilicon and ingot capacity in Arizona and Texas, exploiting geographic diversification demand from risk-averse module assemblers. Pursue technology licensing partnerships with established crystal growth equipment suppliers to bypass proprietary Czochralski expertise gaps. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated producers with control from polysilicon through cell production over pure-play wafer specialists facing margin compression. Long-term viability hinges on exposure to utility-scale deployment in India and the Middle East, bifacial format adoption, and low-carbon certification premiums. Monitor polysilicon price volatility and Xinjiang supply concentration as inflection indicators for portfolio rebalancing toward hydropower-proximate manufacturing assets.| Strategic Initiative | Industry Significance |
|---|---|
| 210mm Format Capacity Conversion | Ultra-large wafer adoption slashes balance-of-system costs for utility developers in India and Saudi Arabia. |
| Backward Integration into Polysilicon | Captive feedstock supply insulates margin pools from metallurgical-grade silicon price volatility. |
| Carbon Certification Program | EU Green Deal CBAM compliance secures procurement preference from European module assemblers. |
| Long-term Supply Agreement | Bilateral offtake contracts with ingot growers bypass merchant distributors and lock volume predictability. |
| Hydropower-proximate Manufacturing | Yunnan and Xinjiang renewable energy clustering reduces embodied-carbon intensity for export eligibility. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted to ground quantitative projections in operational reality. Primary interviews captured perspectives from polysilicon purification plant managers, wafer slicing equipment engineers, utility procurement officers at Indian and Middle Eastern IPPs, module assembler supply chain directors, and carbon accounting specialists at European certification bodies. Secondary validation drew from MIIT GB standard filings, EU Green Deal CBAM technical documentation, FERC interconnection records, CEA solar tender databases, and SEC disclosures from listed photovoltaic manufacturers. Bottom-up capacity and utilization data were triangulated against top-down demand forecasts from national renewable energy targets.
Calibration against historical capacity expansion cycles and polysilicon price volatility patterns anchored growth trajectory assumptions across the analysis window. Segmentation modeling incorporated product type, application scale, cell architecture compatibility, and regional regulatory framework dimensions. CAGRs were derived from installed base projections and average selling price evolution by format size. Forecast inputs included utility-scale tender pipelines in Rajasthan and Gujarat, IRA production tax credit uptake rates, and EU carbon border adjustment phase-in timelines.
Sensitivities concentrate around polysilicon supply disruption from Xinjiang logistics constraints, 210mm format adoption velocity among utility developers, and EU CBAM threshold stringency revisions. Forecasts reflect documented assumptions on technology transition rates and regulatory enforcement intensity. Material shifts in export-control regime scope or embodied-carbon accounting methodologies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Semiconductor Photoresist Polymer Market
Semiconductor Fabrication
Global Foundry Service Market
Semiconductor Fabrication
Sic Wafer Reclaim Services Market
Semiconductor Fabrication
Mask Alignment Lithography Market
Semiconductor Fabrication
Manual Wafer Aligner Market
Semiconductor Fabrication
Semiconductor Advanced Substrate Market
Semiconductor Fabrication
Photoresist Removal Market
Semiconductor Fabrication
Vapor Deposition Market
Semiconductor Fabrication
Etching Machine Market
Semiconductor Fabrication
Semiconductor Foundry Market
Semiconductor Fabrication
Thin Layer Deposition Market
Semiconductor Fabrication
North America Atomic Layer Deposition Market
Semiconductor Fabrication
Global Micromachining Market
Semiconductor Fabrication
Global Dry Etching Machine Market
Semiconductor Fabrication
Holmium Sputtering Target Market
Semiconductor Fabrication
Global Atomic Layer Deposition Market