
 Semiconductor Fab Water Reuse Systems Market | 2026-2036
Semiconductor Fab Water Reuse Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Fab Water Reuse Systems Market Insights
Process engineering talent scarcity is bifurcating the competitive landscape between integrated system suppliers and point-solution specialists. Veolia Water Technologies leverages its multi-technology platform to anchor large fab contracts across three continents. Gradiant differentiates through AI-driven water intelligence that optimizes chemical dosing in real time. Ovivo sustains dominance in zero liquid discharge configurations for advanced logic foundries.
Semiconductor fab water reuse systems recover and recondition process effluent through reverse osmosis, ion exchange, and advanced oxidation to achieve parts-per-trillion purity grades required for wafer manufacturing. These systems reduce freshwater withdrawal by capturing spent rinse water from wet etching and chemical mechanical polishing stages for recirculation. Membrane-based technologies command the deepest margin pools as fabs push toward sub-3nm nodes with escalating ultrapure water intensity. Reverse osmosis leads system type deployment due to its established reliability in removing dissolved ions and organic contaminants at scale. Wet etching applications generate the fastest-growing reuse demand as through-silicon via and FinFET architectures multiply rinse cycles per wafer.
The EPA enforces effluent limitation guidelines that compel US fabs to treat metal-bearing wastewater before discharge, while Taiwan's Industrial Development Bureau mandates water recycling rates above 85 percent for science park residents. REACH restrictions on per- and polyfluoroalkyl substances in Europe force membrane material substitutions that reshape supplier qualification pathways. Stakeholders must monitor how China's dual carbon goals and GB water reuse standards redirect procurement toward domestic system integrators.
Market Dynamics
Advanced node fabrication at Samsung and TSMC compresses water intensity per wafer while multiplying total ultrapure water volumes, forcing fabs to recapture spent rinse streams rather than discharge them. This structural pressure concentrates procurement authority among a handful of megafab operators.
Growth Catalysts
- EPA Effluent Limitation Guidelines:The EPA's metal-bearing wastewater discharge standards compel US semiconductor manufacturers to install closed-loop treatment infrastructure rather than rely on municipal discharge pathways.
- Sub-3nm node migration:Wet etching cycle multiplication in through-silicon via and FinFET architectures generates escalating rinse water volumes that fabs must recirculate to maintain cost structures.
- Taiwan's Industrial Development Bureau mandates:Science park residents face compulsory water recycling rates above 85 percent, locking in demand for membrane-based purification systems.
Market Restraints
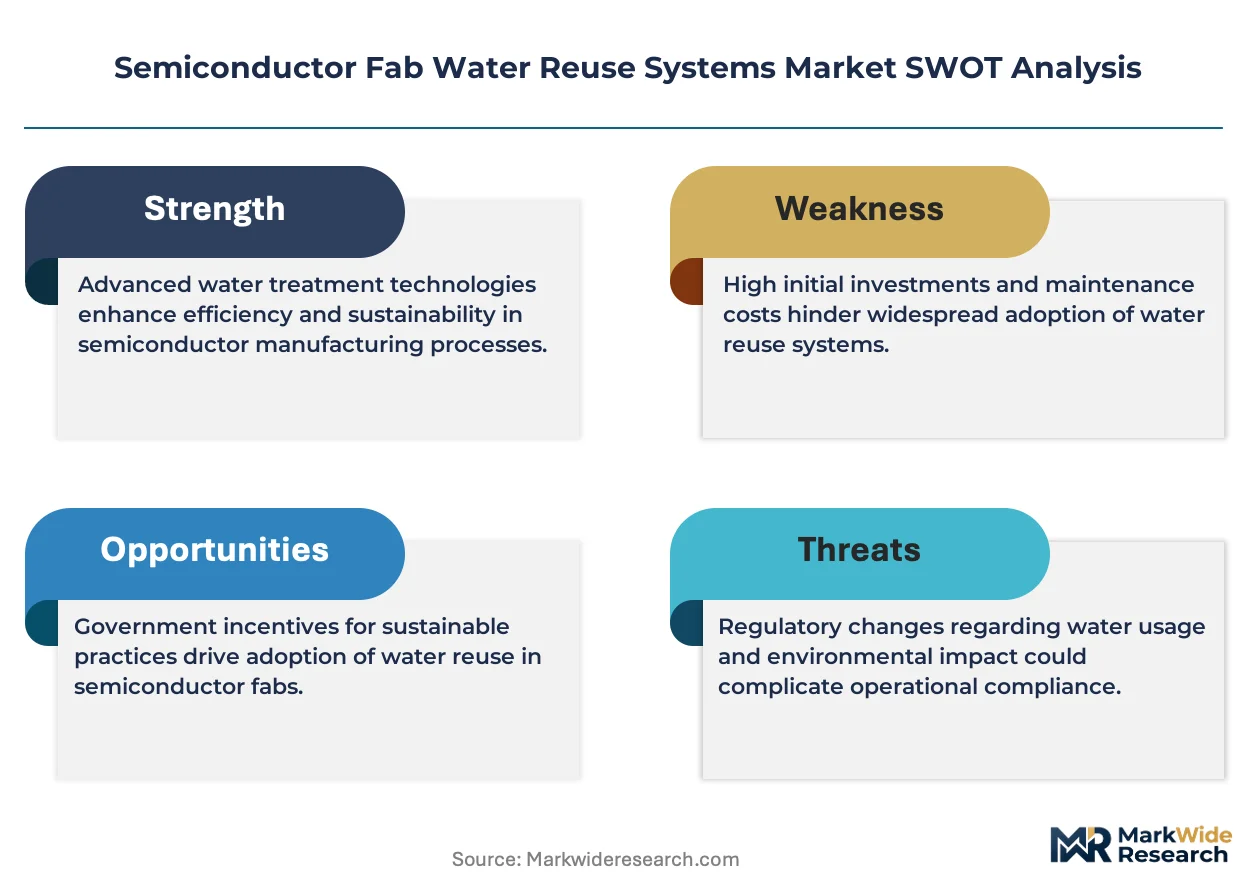
- Fluoropolymer membrane supply concentration:REACH restrictions on per- and polyfluoroalkyl substances force material substitutions that disrupt established supplier qualification pathways across European procurement.
- High-purity chemical input volatility:Ion exchange resin regeneration requires specialty acids and bases subject to semiconductor-grade purity premiums and spot market fluctuations.
- Legacy infrastructure incompatibility:Brownfield fabs built for 28nm and larger nodes lack physical footprint and utility capacity for closed-loop retrofit without fab-wide shutdowns.
Strategic Opportunities
- China's dual carbon goals:GB water reuse standards redirect procurement toward domestic system integrators, creating captive demand pools for locally qualified equipment vendors.
- AI-driven dosing optimization:Machine learning convergence with real-time conductivity and TOC sensing enables predictive chemical consumption models that slash operating expenditure.
- Zero liquid discharge expansion:Crystallizer and evaporator technology maturation opens advanced logic foundry segments previously served by conventional discharge-to-sewer configurations.
Industry Challenges
- Process engineering talent scarcity:The intersection of semiconductor manufacturing and water chemistry expertise remains underdeveloped in technical training pipelines, elongating commissioning timelines.
- Multi-technology integration complexity:Reverse osmosis, ion exchange, and advanced oxidation process trains must synchronize within single control architectures that few integrators have validated at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Fab Water Reuse Systems Market |
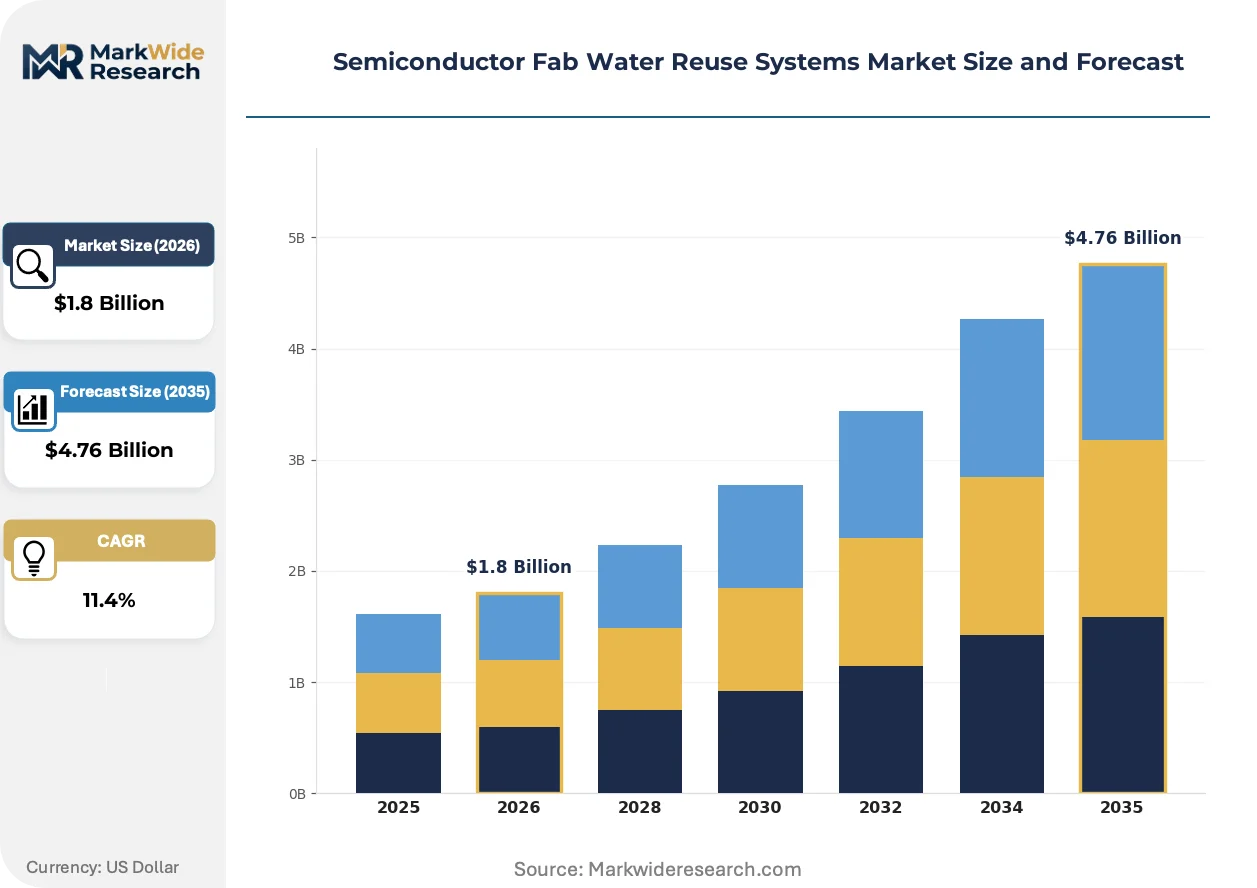
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
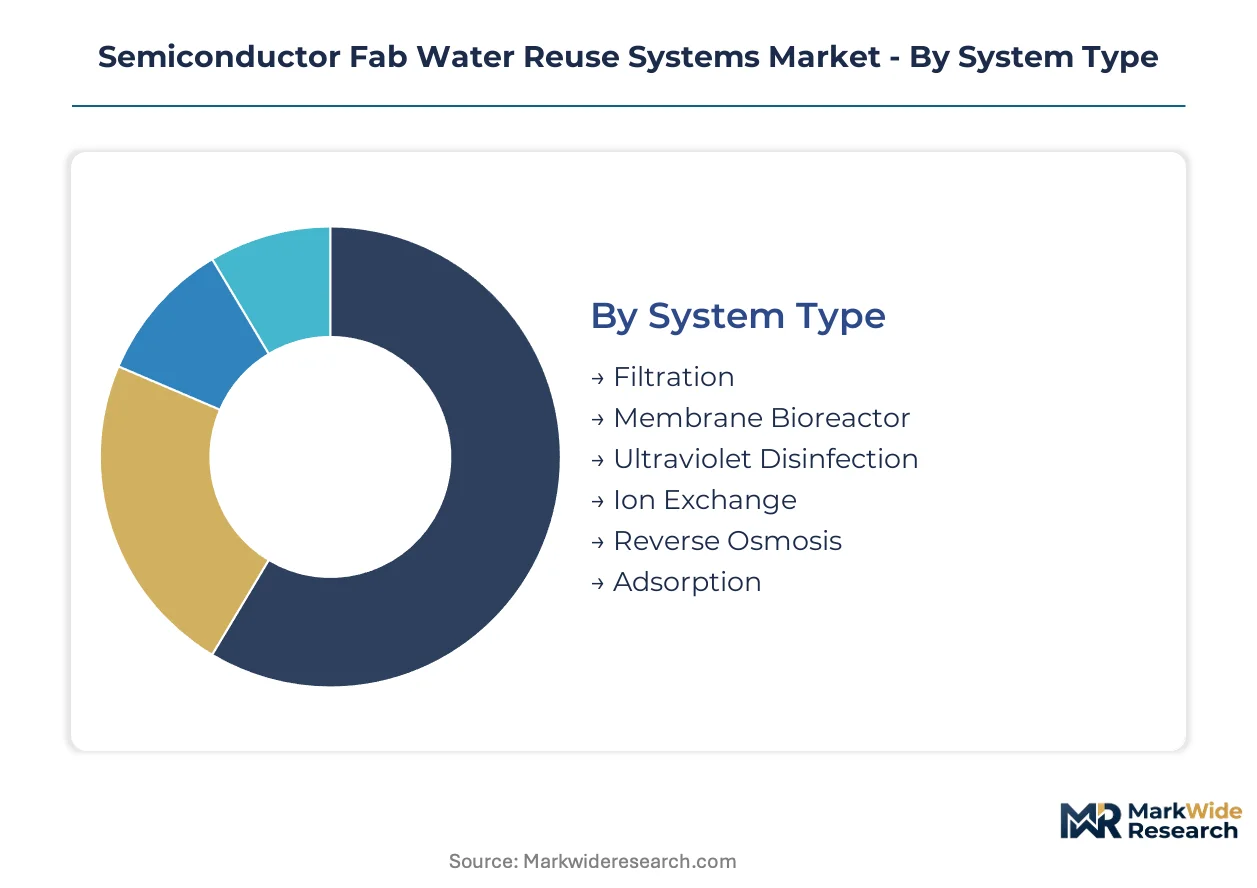
| Segmentation | System Type: Filtration, Membrane Bioreactor, Ultraviolet Disinfection, Ion Exchange, Reverse Osmosis, Adsorption Technology: Nanofiltration, Ultrafiltration, Electrocoagulation, Advanced Oxidation, Microfiltration, Coagulation & Flocculation Application: Wet Etching, Chemical Mechanical Polishing, Photoresist Stripping, Wafer Cleaning, Heat Exchangers, Process Cooling End User: Integrated Device Manufacturers, Silicon Foundries, Outsourced Assembly & Test Providers, Printed Circuit Board Makers |
| Companies Covered | Veolia Water Technologies, Ovivo, Xylem, Kurita Water Industries, Ecolab, Aquatech, Gradiant, Organo, DuPont Water Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Fab Water Reuse Systems Market Trends and Innovations
Membrane technology evolution and regulatory chemistry restrictions are actively restructuring supplier qualification pathways and procurement criteria across semiconductor water reuse.
Advanced oxidation processes incorporating vacuum ultraviolet and ozone-peroxide combinations are fragmenting the incumbent ultraviolet-disinfection installed base. Leading-edge logic foundries in Taiwan and South Korea are adopting these systems for organics destruction at sub-parts-per-billion thresholds. The technology is fragmenting competitive positioning between established ultraviolet suppliers and specialty chemical oxidation vendors.
REACH restrictions on per- and polyfluoroalkyl substances are forcing membrane material substitutions that invalidate decades of operational data. European semiconductor manufacturers must requalify polyvinylidene fluoride and polytetrafluoroethylene alternatives under compressed timelines. Wet etching applications face the steepest revalidation burdens given their direct contact with aggressive chemistries.
Fab operators are consolidating procurement authority under centralized technical specifications that span multiple sites. Equipment vendors now face consolidated tender processes from Samsung, TSMC, and Intel that demand interoperable control platforms and unified service contracts. This concentration is most visible in Taiwan's Hsinchu Science Park cluster where shared engineering standards accelerate supplier selection cycles.
Semiconductor Fab Water Reuse Systems Market Segmentation
Water reuse system procurement varies sharply by fab process stage and purity requirements. Equipment specifications diverge based on whether effluent originates from wet etching chemistry or cooling tower blowdown. Understanding these segment boundaries clarifies where membrane technology commands premium pricing versus commoditized filtration.
System Type:
Reverse osmosis and ion exchange systems capture the deepest margin pools as fabs push toward sub-3nm nodes with escalating ultrapure water intensity.
- Reverse Osmosis:Pressure-driven membrane separation removes dissolved ions and organic contaminants at scale. Taiwan's Hsinchu Science Park cluster deploys these systems most intensively under the Industrial Development Bureau's 85 percent recycling mandates. Membrane replacement cycles and energy consumption dominate total cost of ownership calculations.
- Ion Exchange:Resin-based demineralization achieves parts-per-trillion purity grades required for final rinse stages. Silicon foundries in South Korea concentrate demand here as advanced logic nodes multiply rinse cycles per wafer. Regeneration chemical costs fluctuate with semiconductor-grade acid and base spot markets.
- Filtration:Depth and surface filtration remove suspended solids upstream of membrane trains.
- Membrane Bioreactor:Biological treatment combined with membrane separation handles high-organic effluent streams.
- Ultraviolet Disinfection:UV-C irradiation destroys microorganisms without chemical residuals.
- Adsorption:Activated carbon and specialty media target trace organics and chlorine removal.
Reverse osmosis holds installed capacity. Ion exchange is rotating up the share rankings as advanced node migration accelerates.
Technology:
Application severity determines technology selection, with nanofiltration and advanced oxidation commanding premium positioning for aggressive chemical effluent.
- Advanced Oxidation:Vacuum ultraviolet and ozone-peroxide combinations destroy organics at sub-parts-per-billion thresholds. Leading-edge logic foundries in Taiwan and South Korea adopt these systems where REACH restrictions on per- and polyfluoroalkyl substances invalidate legacy ultraviolet operational data. The technology fragments competitive positioning between established UV suppliers and specialty chemical oxidation vendors.
- Nanofiltration:Selective ion rejection handles divalent-heavy wastewater from chemical mechanical polishing without full desalination. Integrated device manufacturers favor this technology for cost-sensitive intermediate purification stages where monovalent ion passage is acceptable. Membrane fouling rates vary with silica and organic loading.
- Ultrafiltration:Pore-size-based separation removes colloids and macromolecules as pretreatment.
- Electrocoagulation:Electrical current drives metal hydroxide precipitation for heavy metal removal.
- Microfiltration:Larger pore structures handle high-solids streams with minimal transmembrane pressure.
- Coagulation & Flocculation:Chemical precipitation clarifies suspended solids before membrane stages.
Coagulation and flocculation dominates brownfield retrofit volumes. Advanced oxidation is climbing the fastest as greenfield fabs specify organics destruction at tighter thresholds.
Application:
Process water intensity per wafer varies tenfold across applications, with wet etching generating the steepest reuse demand curves.
- Wet Etching:Through-silicon via and FinFET architectures multiply rinse cycles per wafer, generating spent streams with aggressive acid and solvent content. Samsung and TSMC concentrate procurement for closed-loop recovery here as total ultrapure water volumes escalate despite per-wafer efficiency gains. Effluent corrosivity demands fluoropolymer-compatible materials of construction.
- Chemical Mechanical Polishing:Slurry-laden wastewater requires solids separation and dissolved copper recovery. Outsourced assembly and test providers in Taiwan drive standardization of CMP effluent treatment modules. Silica abrasive loading challenges membrane fouling control strategies.
- Photoresist Stripping:Solvent-heavy streams demand organics recovery or destruction.
- Wafer Cleaning:Final rinse stages impose the strictest purity specifications on recovered water.
- Heat Exchangers:Cooling water blowdown carries lower contaminant loads suitable for simpler reuse loops.
- Process Cooling:Tower blowdown volumes scale with fab thermal loads rather than wafer throughput.
Heat exchangers and process cooling hold installed capacity. Wet etching is gaining share fastest as node shrinkage multiplies rinse intensity.
End User:
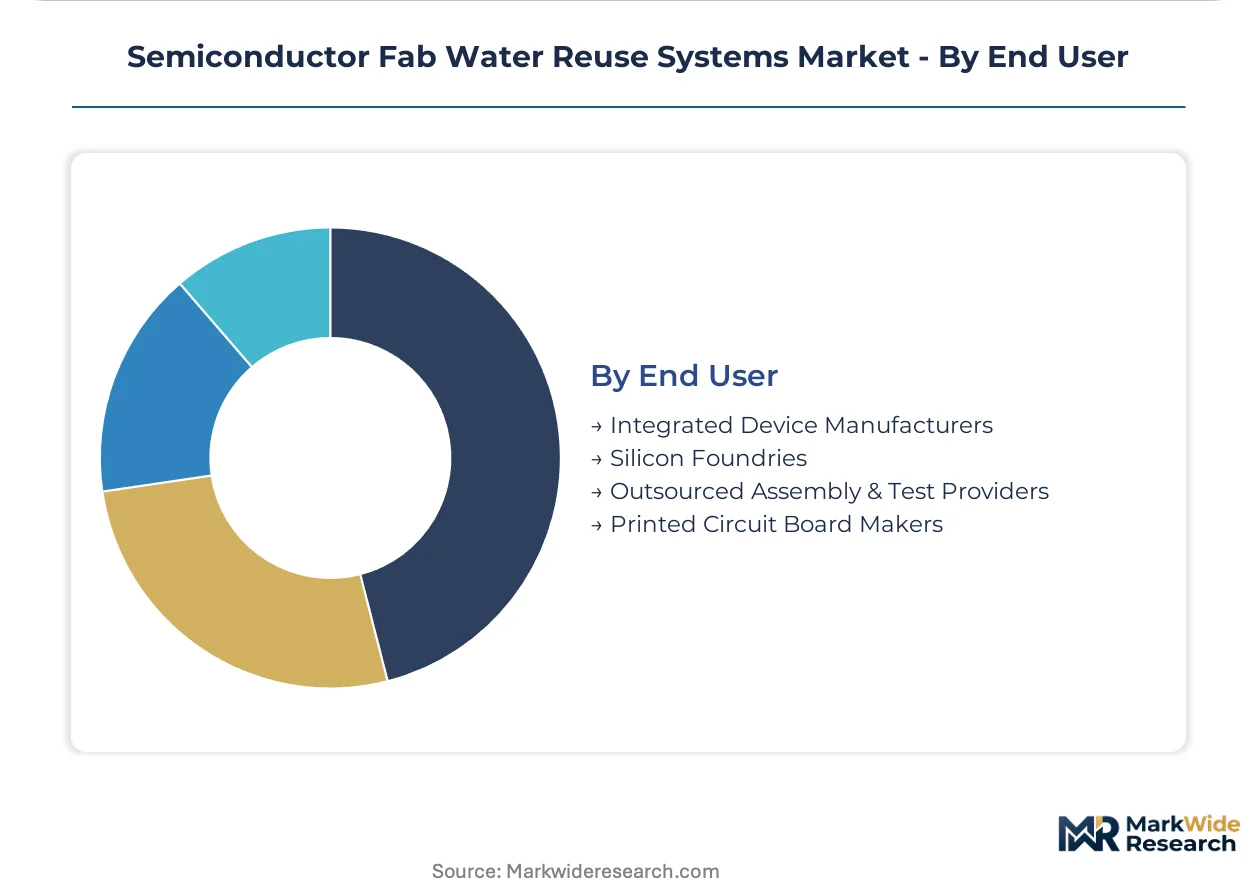
Procurement authority concentrates among megafab operators with multi-site standardization programs.
- Silicon Foundries:TSMC and Samsung anchor demand for zero liquid discharge configurations at advanced logic nodes. Centralized technical specifications span multiple sites, demanding interoperable control platforms and unified service contracts. Volume commitments enable supplier qualification at scale.
- Integrated Device Manufacturers:Intel and Texas Instruments balance legacy fab retrofit against greenfield construction timelines. Brownfield constraints around physical footprint and utility capacity limit closed-loop adoption without fab-wide shutdowns. Mixed technology nodes complicate standardized water reuse strategies.
- Outsourced Assembly & Test Providers:Lower water intensity processes reduce reuse system penetration rates.
- Printed Circuit Board Makers:Smaller scale operations rely more heavily on municipal discharge pathways.
Integrated device manufacturers hold installed capacity. Silicon foundries is rotating up the share rankings as pure-play logic capacity expands fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan consumes water reuse systems through science park mandates that force closed-loop adoption, while the United States deploys them reactively under discharge compliance pressure—a structural divergence in regulatory philosophy that shapes procurement timelines and system specifications.
United States
The EPA's effluent limitation guidelines compel domestic fabs to treat metal-bearing wastewater before municipal discharge. Intel's Arizona and Oregon facilities anchor demand for closed-loop infrastructure as advanced logic node investments multiply ultrapure water intensity. Brownfield retrofit constraints around physical footprint limit adoption speed at legacy sites.
Taiwan
TSMC and United Microelectronics Corporation drive procurement volumes as through-silicon via architectures multiply rinse cycles per wafer. The Industrial Development Bureau mandates recycling rates above 85 percent for Hsinchu Science Park residents. Kaohsiung's emerging fab cluster is replicating Hsinchu's shared engineering standards to accelerate supplier qualification cycles.
South Korea
Samsung Electronics and SK Hynix anchor demand for zero liquid discharge configurations at sub-3nm logic and memory nodes. METI-aligned water stress policies encourage recirculation over freshwater withdrawal despite abundant conventional supply. Pyeongtaek's semiconductor complex concentrates procurement authority under centralized technical specifications spanning multiple fabs.
China
Domestic foundry expansion under the dual carbon goals redirects procurement toward locally qualified system integrators. GB water reuse standards tighten discharge thresholds for Yangtze River Delta semiconductor manufacturing. Shanghai's Lingang New Area and Beijing's Zhongguancun cluster are emerging as captive demand pools for indigenous equipment vendors.
Japan
Kioxia and Tokyo Electron's supply chain partners drive adoption of membrane-based purification for advanced memory and logic processes. JIS standards and METI water security frameworks encourage closed-loop adoption despite lower regulatory pressure than regional peers. Kumamoto's TSMC-Joint Venture fab is importing Taiwanese engineering standards to accelerate local supplier development.
Semiconductor Fab Water Reuse Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with procurement authority concentrating among megafab operators that demand unified service contracts across multiple sites. The competitive terrain splits between multi-technology platform providers and point-solution specialists focused on membrane or oxidation subsystems. Strategic moves center on qualification pathway acceleration and control platform interoperability rather than price-based displacement.
Within the integrated platform tier, Veolia Water Technologies and Ovivo occupy positions as anchors for large fab contracts, while Gradiant exemplifies the AI-driven specialist archetype. Veolia's multi-technology portfolio spans three continents of semiconductor manufacturing. Ovivo sustains positioning in zero liquid discharge configurations. Gradiant represents the convergence of machine learning with real-time water quality sensing.
| Leading Market Players |
|---|
| Veolia Water Technologies |
| Ovivo |
| Xylem |
| Kurita Water Industries |
| Ecolab |
| Aquatech |
| Gradiant |
| Organo |
| DuPont Water Solutions |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month membrane qualification timelines concentrate procurement leverage among TSMC and Samsung, compressing supplier margins while amplifying volume-commitment discounts for closed-loop ultrapure water systems. This lead-time rigidity anchors pricing power with megafab operators who can guarantee multi-site standardization contracts.
Pricing Analysis
Long-term offtake agreements dominate procurement, with five-year service contracts bundling membrane replacement and chemical regeneration under unified pricing structures. Three-tier pricing stratifies across premium certified systems, standard membrane configurations, and economy-grade retrofit modules. Cost compression in the economy tier intensifies as Chinese domestic integrators undercut incumbent service rates. IDMs with brownfield legacy fabs exhibit highest price sensitivity due to shutdown-constrained retrofit budgets.
Supply Chain Analysis
Fluoropolymer resin supply from Japan and Germany underwrites membrane manufacturing viability for advanced node applications. PVDF and PTFE feedstocks draw from chemical conglomerates in Belgium and the United States, while ion exchange resin production centers on China and South Korea. REACH substance restrictions constitute the primary regulatory chokepoint disrupting established supplier qualification pathways. Distribution runs through direct OEM relationships with fab engineering teams rather than distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Megafab procurement consolidation under TSMC, Samsung, and Intel shifts bargaining power decisively toward buyers, fragmenting vendor pricing autonomy across Taiwan's Hsinchu cluster and South Korea's Pyeongtaek complex.
For Market Incumbents: Shield service contract renewals by embedding AI-driven dosing optimization into existing membrane installations before Gradiant-type specialists capture retrofit opportunities. Deepen backward integration into fluoropolymer membrane manufacturing to offset REACH-driven material substitution risks from European chemical suppliers. For New Entrants and Emerging Players: GB standard fast-track certification unlocks procurement access within China's Yangtze River Delta foundry expansion under dual carbon mandates. Target zero liquid discharge configurations for advanced logic foundries where Ovivo's incumbent positioning remains vulnerable on commissioning speed. Lead with predictive maintenance software bundles to differentiate from Veolia's hardware-centric service models. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with undermonetized water treatment divisions lacking semiconductor-specific qualification pathways. Five-to-ten year viability hinges on membrane technology convergence with real-time sensing platforms rather than commodity filtration hardware. Monitor EPA effluent guideline enforcement intensity as the inflection signal for US fab capital allocation toward closed-loop infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Dosing Optimization | Machine learning convergence with TOC sensing slashes chemical OPEX for TSMC-scale operators. |
| Zero Liquid Discharge Expansion | Crystallizer technology maturation opens Intel and Samsung advanced logic segments to new entrants. |
| Fluoropolymer Membrane Backward Integration | Captive resin supply insulates against REACH restrictions disrupting European procurement channels. |
| GB Standard Certification Fast-Track | Domestic qualification acceleration captures China's dual carbon-driven foundry buildout demand. |
| Predictive Maintenance Platform Launch | Real-time membrane health monitoring displaces scheduled replacement contracts with outcome-based pricing. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA enforcement records, Taiwan Industrial Development Bureau compliance filings, and semiconductor equipment customs data. Process engineering directors at leading foundries, membrane R&D leads at chemical suppliers, and fab construction project managers provided operational validation. SEC 10-K disclosures from water technology providers and METI water security white papers furnished financial and policy triangulation against bottom-up equipment shipment estimates.
Segmentation dimensions modeled span system type, technology class, application severity, and end-user procurement authority across the projection horizon. Wet etching intensity multipliers and node-shrinkage rinse cycle coefficients informed volume elasticity assumptions. CAGRs derive from equipment capacity deployment trajectories reconciled against foundry capex announcements and regulatory mandate implementation schedules.
Decision-makers should treat outputs as directional under sustained sub-3nm migration and stable REACH enforcement intensity; material deviation in fluoropolymer substitution timelines or EPA guideline stringency would warrant model refresh. Practitioners should keep alternative scenarios live as China's domestic equipment qualification pathways and dual carbon policy implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Solar Ingot Wafer Market
Semiconductor Fabrication
8-Inch Silicon Carbide (Sic) Wafer Market
Semiconductor Fabrication
Mask Alignment Lithography Market
Semiconductor Fabrication
Vapor Deposition Market
Semiconductor Fabrication
Global Atomic Layer Deposition Market
Semiconductor Fabrication
Semiconductor Foundry Market
Semiconductor Fabrication
Photoresist Removal Market
Semiconductor Fabrication
Global Micromachining Market
Semiconductor Fabrication
Solar Grade Wafer Market
Semiconductor Fabrication
Semiconductor Photoresist Polymer Market
Semiconductor Fabrication
Semiconductor Etching Cleaner Market
Semiconductor Fabrication
Diamond Semiconductor Substrates Market
Semiconductor Fabrication
Physical Vapor Deposition (PVD) Market
Semiconductor Fabrication
Global Dry Etching Machine Market
Semiconductor Fabrication
Ion Implanter Market
Semiconductor Fabrication
Global Spark Plasma Sintering Market