
 Etching Machine Market | 2026-2036
Etching Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Etching Machine Market Intelligence
Profitability from legacy wet etching system sales is narrowing as manufacturers prioritize advanced dry etching technologies. This shift favors firms with deep R&D in plasma and reactive ion etching. Lam Research Corporation specializes in dielectric and conductor etch systems for leading-edge logic and memory. Applied Materials, Inc. competes with a broad portfolio covering multiple semiconductor process steps, while Tokyo Electron Limited sustains a strong position in coater/developer and etch systems.
An etching machine selectively removes material from a substrate surface, typically a silicon wafer, using chemical or physical processes. These systems create microscopic patterns and circuits by applying etchants like corrosive liquids or energized plasma gas within a controlled vacuum chamber. Semiconductor fabrication remains the dominant application, commanding the highest investment in advanced equipment. Within product types, dry etching, particularly reactive ion etching, is the primary growth driver due to its precision in manufacturing smaller, more complex integrated circuits.
Environmental regulations, including the EPA's rules on chemical disposal in the United States and the EU's REACH framework managed by ECHA, govern the use and handling of hazardous etchants. Concurrently, equipment must comply with safety and electromagnetic compatibility standards like CE marking for market access in Europe. Equipment manufacturers must therefore balance the pursuit of higher etching precision with compliance to an increasingly stringent global environmental and safety landscape.
Market Dynamics
The central force shaping the etching machine market is the semiconductor industry's aggressive push towards advanced sub-7nm process nodes. This relentless miniaturization requires a fundamental shift from legacy wet etching to precision dry etching technologies like RIE and plasma systems.
Growth Catalysts
- Advanced Packaging Demand:The expansion of 3D and heterogeneous integration, including Fan-Out Wafer-Level Packaging (FOWLP), necessitates high-precision deep silicon etching and through-silicon via (TSV) formation, directly driving equipment sales.
- Semiconductor Hub Investment:Concentrated capital expenditure in leading semiconductor manufacturing centers, particularly Taiwan and South Korea, for next-generation memory and logic fabrication facilities creates sustained demand for state-of-the-art etching tools.
- National Industrial Policies:Government initiatives like the US CHIPS Act and the European Chips Act are stimulating the construction of new fabrication plants, creating a new wave of demand for a full suite of semiconductor equipment, including etchers.
Market Restraints
- High Capital Expenditure:The acquisition cost of advanced dry etching systems, especially those capable of atomic layer etching (ALE) for sub-3nm nodes, represents a significant capital barrier for new entrants and smaller-scale fabs.
- Component Supply Bottlenecks:The supply chain for critical sub-systems, such as radio frequency (RF) generators and specialized vacuum pumps, is highly concentrated among a few vendors, creating potential production delays and price volatility for equipment manufacturers.
- Physical Etching Limits:As device features approach atomic dimensions, manufacturers face fundamental physics challenges like aspect ratio-dependent etching (ARDE) and microloading effects, which can compromise yield and uniformity.
Strategic Opportunities
- Compound Semiconductors:The growing market for power electronics and 5G radio frequency components based on materials like Gallium Nitride (GaN) and Silicon Carbide (SiC) opens a new application frontier requiring specialized etching processes.
- Process Control Integration:Incorporating artificial intelligence and machine learning algorithms for real-time plasma monitoring and predictive maintenance offers a path to improve wafer-to-wafer consistency, reduce downtime, and increase overall equipment effectiveness.
- Emerging Geographic Markets:National semiconductor self-sufficiency goals in countries like India, backed by Production Linked Incentive (PLI) schemes, present greenfield opportunities for equipment sales as new fabrication ecosystems are established.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of experienced process engineers and equipment technicians capable of developing, operating, and maintaining complex plasma etching systems for leading-edge nodes constrains fab expansion and operational efficiency.
- Stringent Environmental Compliance:Navigating an intricate global regulatory landscape, including the EU's REACH framework and EPA rules on chemical disposal, adds significant cost and complexity to the management of hazardous etchant gases and liquid waste.
- Legacy System Integration:Integrating new, highly advanced etching tools into existing 200mm or 300mm fabs with established process flows and metrology systems presents significant technical hurdles, risking production disruptions and yield excursions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Etching Machine Market |
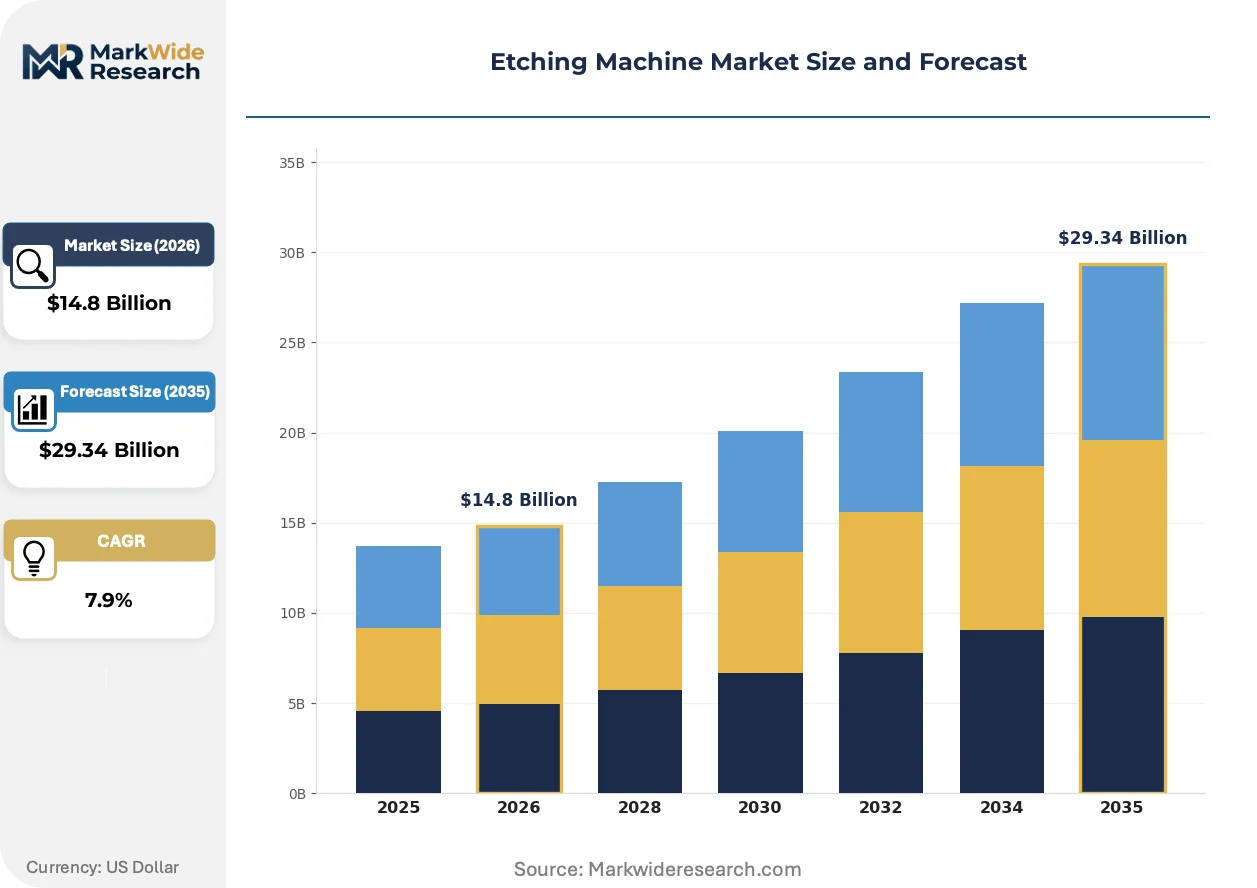
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $29.34 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Etching, Dry Etching, Plasma Etching, Reactive Ion Etching, Laser Etching Technology: Chemical Etching, Physical Etching, Photoresist Etching, Ion Beam Etching, Electrochemical Etching Application: Semiconductor Fabrication, Printed Circuit Board Manufacturing, Solar Cell Production, MEMS Fabrication, Optical Component Processing End User: Fabrication Facilities, Electronics Manufacturers, Solar Panel Producers, Microdevice Makers, Optical Equipment Vendors |
| Companies Covered | ASML Holding NV, Trotec Laser GmbH, Applied Materials Inc., Epilog Laser, Universal Laser Systems, Lam Research Corporation, Hitachi High-Technologies Corporation, Han's Laser, Tokyo Electron Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Etching Machine Market Strategic Shifts & Innovations
Process intelligence and material-specific etching capabilities are defining the next generation of equipment. The focus is shifting from raw throughput to achieving atomic-scale precision and adapting to a wider array of substrate materials beyond silicon, driven by device diversification.
Atomic Layer Etching (ALE) is a key technology that removes material one atomic layer at a time through self-limiting surface reactions. Leading-edge semiconductor manufacturers are adopting ALE for critical patterning steps in sub-5nm logic and 3D NAND memory fabrication. This technology is hybridizing with conventional reactive ion etching, creating advanced processes that combine the high precision of ALE with the higher throughput of RIE for fabricating complex gate-all-around (GAA) transistor architectures.
The European Union's F-Gas Regulation, which restricts the use of gases with high global warming potential, is impacting etchant chemistry. This policy is compelling equipment manufacturers and chemical suppliers to develop and qualify new etchant gases and chamber cleaning chemistries with lower environmental footprints. The dielectric and conductor etch segments are most affected, accelerating research into alternative plasma chemistries that maintain process performance while complying with stricter environmental mandates.
A notable shift in purchasing behavior involves semiconductor fabs moving toward collaborative co-development partnerships with equipment vendors. This model is displacing traditional, transactional equipment sales with long-term strategic alliances focused on creating bespoke etch processes tailored to specific, next-generation device roadmaps. This collaborative procurement is most visible in the competitive foundry sector in Taiwan and South Korea, where process innovation is a primary source of differentiation.
Etching Machine Market Segmentation
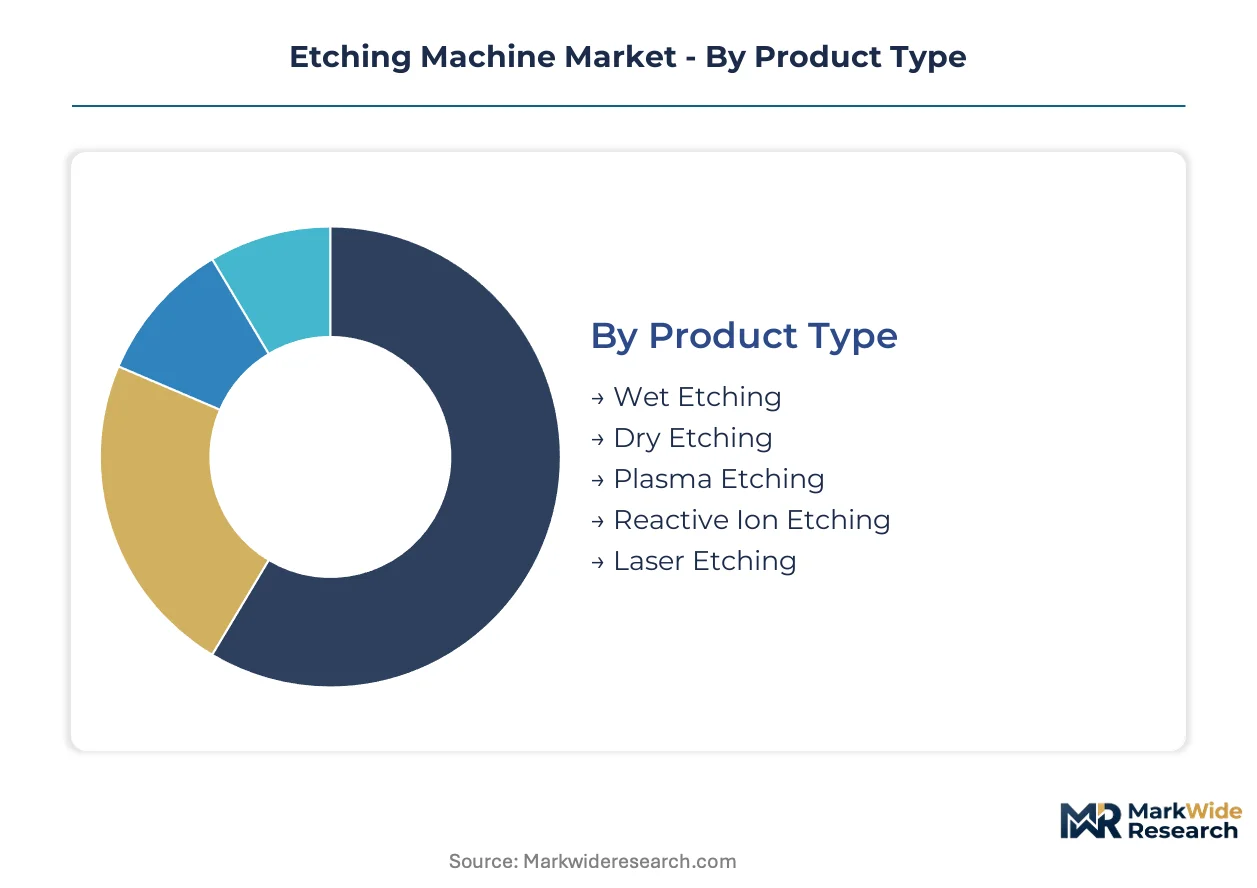
The etching machine market segments by critical process characteristics and end-user applications, reflecting the diverse technical requirements across microfabrication industries. Understanding these distinctions is crucial for equipment manufacturers to align product development with evolving industry demands and for fabs to optimize their procurement strategies.
Product Type:
The product type segmentation highlights the varying cycle times associated with different etching technologies, from slower, batch-oriented methods to rapid, precise processes.
- Dry Etching:This advanced method uses plasma or reactive gases in a vacuum chamber to selectively remove material. Demand is concentrating in leading-edge semiconductor fabrication, driven by the need for sub-7nm process nodes and complex 3D structures.
- Reactive Ion Etching:A hybrid dry etching technique combining chemical reactivity with physical ion bombardment, RIE provides anisotropic etching for high aspect ratio features. High-end memory and logic chip manufacturers in Taiwan and South Korea rely on RIE for critical patterning steps.
- Wet Etching:This traditional method employs liquid chemicals to remove material, often used for bulk material removal or less critical patterning. Its lower precision and isotropic nature limit its use in advanced device manufacturing.
- Plasma Etching:A form of dry etching utilizing plasma to generate reactive species that etch the substrate.
- Laser Etching:This technique uses focused laser beams for material removal, offering high precision for specific niche applications like micro-drilling or surface modification.
Wet Etching anchors the volume base while Reactive Ion Etching gains share at the steepest rate.
Technology:
The technology segment reflects the cost tiers associated with different material removal mechanisms, from established, lower-cost chemical processes to high-investment physical methods.
- Chemical Etching:This method relies on chemical reactions between the etchant and the substrate material. It offers high selectivity but often results in isotropic etching profiles, making it suitable for less demanding applications.
- Physical Etching:This broad category involves the physical removal of material, typically through ion bombardment, offering highly anisotropic profiles. It is essential for creating vertical sidewalls in advanced semiconductor devices.
- Photoresist Etching:This process specifically removes or patterns photoresist layers, which act as masks during subsequent etching steps. It is a foundational process in all photolithography-based fabrication.
- Ion Beam Etching:This technique uses a collimated beam of ions to physically mill away material with very high precision.
- Electrochemical Etching:This process uses an electrochemical cell to control material removal, often employed for specific metal or compound semiconductor applications.
The demand for Chemical Etching remains foundational, while Physical Etching demonstrates the most rapid expansion.
Application:
The application segment outlines where the highest volume of etching machine deployment occurs, alongside areas with specialized requirements.
- Semiconductor Fabrication:This application dominates the market, requiring the highest precision and advanced etching systems for manufacturing integrated circuits. Investment in cutting-edge equipment for sub-5nm logic and 3D NAND memory drives significant demand globally.
- MEMS Fabrication:Micro-electromechanical systems (MEMS) production demands highly specialized deep silicon etching and precise material removal for miniature sensors and actuators. This segment is growing rapidly, particularly for automotive and consumer electronics.
- Printed Circuit Board Manufacturing:Etching machines remove copper layers to create circuit patterns on PCBs. This segment uses high-volume, less precise etching compared to semiconductor fabrication.
- Solar Cell Production:Etching processes are used to texture silicon wafers and remove damaged layers in solar cell manufacturing. This application focuses on cost-effective, high-throughput solutions.
- Optical Component Processing:This application involves etching for creating waveguides, gratings, and other micro-optical structures.
Semiconductor Fabrication drives the largest equipment investments, with MEMS Fabrication showing significant momentum.
End User:
The end-user segment differentiates customers by their operational scale and specialization, influencing purchasing patterns and equipment configurations.
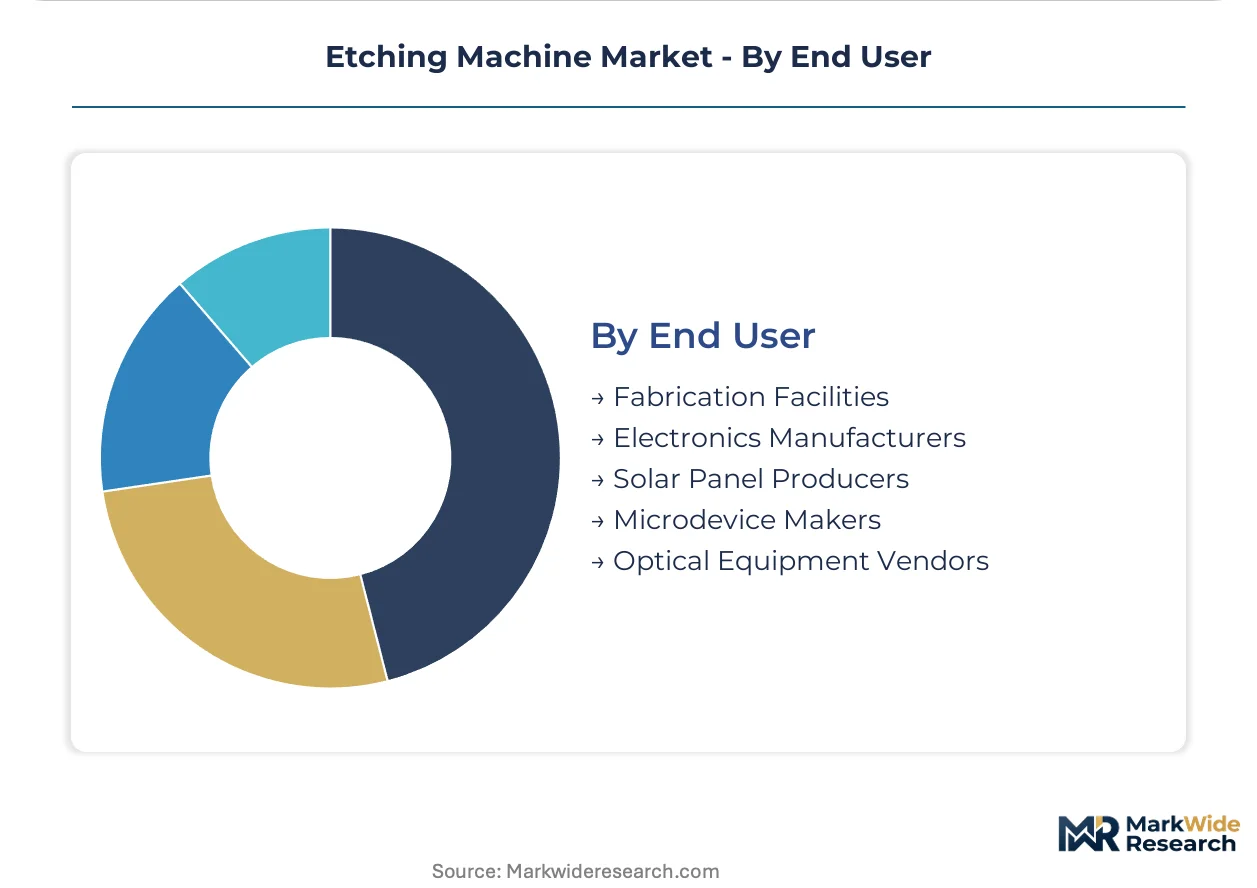
- Fabrication Facilities:These are large-scale semiconductor manufacturing plants (fabs) that require state-of-the-art, high-throughput, and highly precise etching systems. Their procurement is concentrated in major semiconductor hubs like Taiwan and South Korea.
- Electronics Manufacturers:This broad category includes companies producing printed circuit boards, display panels, and other electronic components. They seek reliable and cost-effective etching solutions for various production scales.
- Microdevice Makers:These specialized entities focus on producing MEMS, sensors, and other miniature devices. They often require customized etching solutions for unique material and structural requirements.
- Solar Panel Producers:Manufacturers of photovoltaic cells and panels utilize etching for surface preparation and texturing of silicon wafers.
- Optical Equipment Vendors:Companies manufacturing optical components and systems use etching for precise patterning and material removal in specialized applications.
Traditional Fabrication Facilities users represent consistent demand, but new opportunities emerge from Microdevice Makers specialists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The etching machine market exhibits a diverse consumption mix, with advanced semiconductor manufacturing hubs driving demand for high-precision dry etching systems. Other regions prioritize cost-effective solutions for less critical applications like PCB manufacturing. This differential shapes regional investment patterns and technological adoption.
United States
Demand for etching machines stems from advanced logic and memory fabrication, particularly for artificial intelligence and high-performance computing. The US CHIPS Act stimulates new fab construction, creating significant equipment demand. Silicon Valley and Arizona are expanding semiconductor manufacturing capabilities, requiring state-of-the-art etching tools.
Taiwan
High-end Reactive Ion Etching systems are crucial for Taiwan's dominant foundry sector, supporting sub-5nm process nodes. Taiwan's industrial policies prioritize domestic semiconductor supply chain resilience, influencing equipment procurement. Hsinchu Science Park remains a global center for advanced chip production, driving continuous investment in etching technology.
South Korea
Next-generation memory and logic fabrication facilities in South Korea require precision etching for complex 3D structures and advanced packaging. The South Korean government supports semiconductor research and development through various initiatives, fostering advanced equipment development. Pyeongtaek and Cheonan are expanding their fab capacities, necessitating significant upgrades in etching system deployments.
Japan
Precision etching tools are vital for Japan's specialized semiconductor component manufacturing and advanced materials research. METI initiatives encourage domestic semiconductor equipment production and technology innovation. Kumamoto Prefecture is attracting new fab investments, aiming to bolster Japan's position in leading-edge semiconductor manufacturing.
China
China's push for semiconductor self-sufficiency drives demand for etching machines across various technology nodes. National industrial policies, including the "Made in China 2025" plan, support domestic equipment development. Shanghai and Beijing are developing integrated circuit industrial parks, fostering local etching equipment production and deployment.
Etching Machine Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another in the etching machine market. This market exhibits a tiered structure, with a few dominant players controlling advanced dry etching technologies. Strategic archetypes include high-precision technology innovators, broad portfolio providers, and niche application specialists. Competitive moves center on research and development investment for sub-nanometer capabilities and strategic alliances with leading fabs.
Among global equipment suppliers, Applied Materials Inc. and Lam Research Corporation exemplify firms offering broad portfolios and deep research and development in advanced dry etching technologies. These companies represent the leading edge of innovation, providing critical tools for complex sub-5nm process nodes and 3D structures. Tokyo Electron Limited also occupies a significant position, particularly in coater/developer and etch systems, anchoring the high-volume semiconductor manufacturing sector. These established players consistently invest in next-generation solutions like Atomic Layer Etching, maintaining their competitive advantage in precision and throughput.
| Leading Market Players |
|---|
| ASML Holding NV |
| Trotec Laser GmbH |
| Applied Materials Inc. |
| Epilog Laser |
| Universal Laser Systems |
| Lam Research Corporation |
| Hitachi High-Technologies Corporation |
| Han's Laser |
| Tokyo Electron Limited |
| Others |
Cost & Logistics Intelligence
Taiwan's high capacity utilization in advanced semiconductor fabs drives both equipment supplier behavior and pricing posture for etching machines. This intense demand from leading foundries ensures premium pricing for sub-7nm dry etching systems.
Pricing Analysis
Long-term contract-based pricing dominates advanced dry etching system sales, reflecting the bespoke nature and high investment in these tools. Price differentiation stems from customization levels for specific process nodes and the inclusion of advanced analytics software. Pricing softness impacts legacy wet etching systems due to reduced demand and commoditization. Fabrication facilities investing in leading-edge nodes are least price-sensitive, prioritizing performance and precision over cost.
Supply Chain Analysis
Contract manufacturing concentration in Taiwan and South Korea for advanced semiconductors shapes the etching machine supply chain. Raw material dependencies include specialized quartz and silicon carbide components for vacuum chambers, alongside rare gases for plasma generation. Single-source vulnerability for critical sub-systems like radio frequency generators represents a structural risk. Downstream distribution primarily runs through direct sales channels and specialized technical support teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The etching machine market presents a significant service-attach opportunity, with advanced process control software and predictive maintenance services expanding faster than hardware sales.
For Market Incumbents:Entrench leadership in advanced dry etching by deepening R&D into atomic layer etching and novel plasma chemistries. Form strategic alliances with leading foundries in Taiwan and South Korea to co-develop next-generation process solutions. Address the talent scarcity threat by investing in comprehensive training programs for process engineers. Leverage existing relationships to offer integrated solutions, bundling hardware with advanced process control software.
For New Entrants and Emerging Players:Establish a beachhead in specialized etching applications like compound semiconductors or MEMS fabrication, where incumbent solutions may be less optimized. Target emerging geographic markets such as India, focusing on greenfield opportunities driven by national self-sufficiency goals. A go-to-market angle emphasizing cost-effectiveness with foundational performance for less critical nodes can secure initial market share. Focus on modular designs to enable easier integration into diverse fab environments.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upwards across the sub-5nm dry etching segment, indicating sustained investment requirements for competitive differentiation. Long-term viability hinges on companies with proprietary intellectual property in advanced process control and material science. An ideal acquisition target archetype includes specialized software firms offering AI/ML-driven process optimization for existing equipment. The signal to watch is the successful qualification of next-generation etching processes for new gate-all-around architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen R&D in Atomic Layer Etching | Enhances precision for sub-3nm nodes, securing competitive advantage for leading-edge logic fabrication. |
| Form Co-development Partnerships with Fabs | Accelerates qualification of bespoke etch processes, aligning solutions with specific device roadmaps in Taiwan. |
| Invest in Specialized GaN/SiC Etching Solutions | Captures growth in power electronics and 5G RF components, diversifying application beyond silicon. |
| Integrate AI/ML for Process Control | Improves wafer-to-wafer consistency and reduces downtime, boosting overall equipment effectiveness for fabs. |
| Expand into Emerging Semiconductor Hubs | Capitalizes on national industrial policies and new fab construction in regions like India. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to build a comprehensive understanding of the etching machine market. Primary interviews with process engineers, fab managers, equipment procurement specialists, and R&D directors provided qualitative insights. Secondary validation utilized industry association reports, academic publications, and semiconductor equipment manufacturer financial disclosures, triangulating data for accuracy.
The analytical framework calibrated market size and growth across the analysis window, modeling segmentation dimensions including product type, technology, application, and key geographic regions. CAGRs were derived from historical data analysis and projected based on anticipated technology shifts and capital expenditure trends. Industry-specific forecast inputs included semiconductor capital equipment spending forecasts and advanced process node adoption rates.
Stress conditions across semiconductor capital expenditure fluctuations and global trade policy changes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding continued miniaturization trends and increasing demand for specialized materials. Quarterly review of fab capacity expansion announcements and R&D breakthroughs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
8-Inch Silicon Carbide (Sic) Wafer Market
Semiconductor Fabrication
Semiconductor Fab Water Reuse Systems Market
Semiconductor Fabrication
Etchant for FPD Market
Semiconductor Fabrication
Semiconductor Advanced Substrate Market
Semiconductor Fabrication
Vapor Deposition Market
Semiconductor Fabrication
Ion Implantation Machine Market
Semiconductor Fabrication
Solar Ingot Wafer Market
Semiconductor Fabrication
300mm Silicon Wafers Market
Semiconductor Fabrication
Holmium Sputtering Target Market
Semiconductor Fabrication
Global Micromachining Market
Semiconductor Fabrication
Diamond Semiconductor Substrates Market
Semiconductor Fabrication
Semiconductor Photoresist Polymer Market
Semiconductor Fabrication
Manual Wafer Aligner Market
Semiconductor Fabrication
North America Atomic Layer Deposition Market
Semiconductor Fabrication
Deep Reactive Ion Etching (DRIE) Etcher Market
Semiconductor Fabrication
Global Dielectric Etchers Market