
 Semiconductor Advanced Substrate Market | 2026-2036
Semiconductor Advanced Substrate Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Advanced Substrate Market Outlook
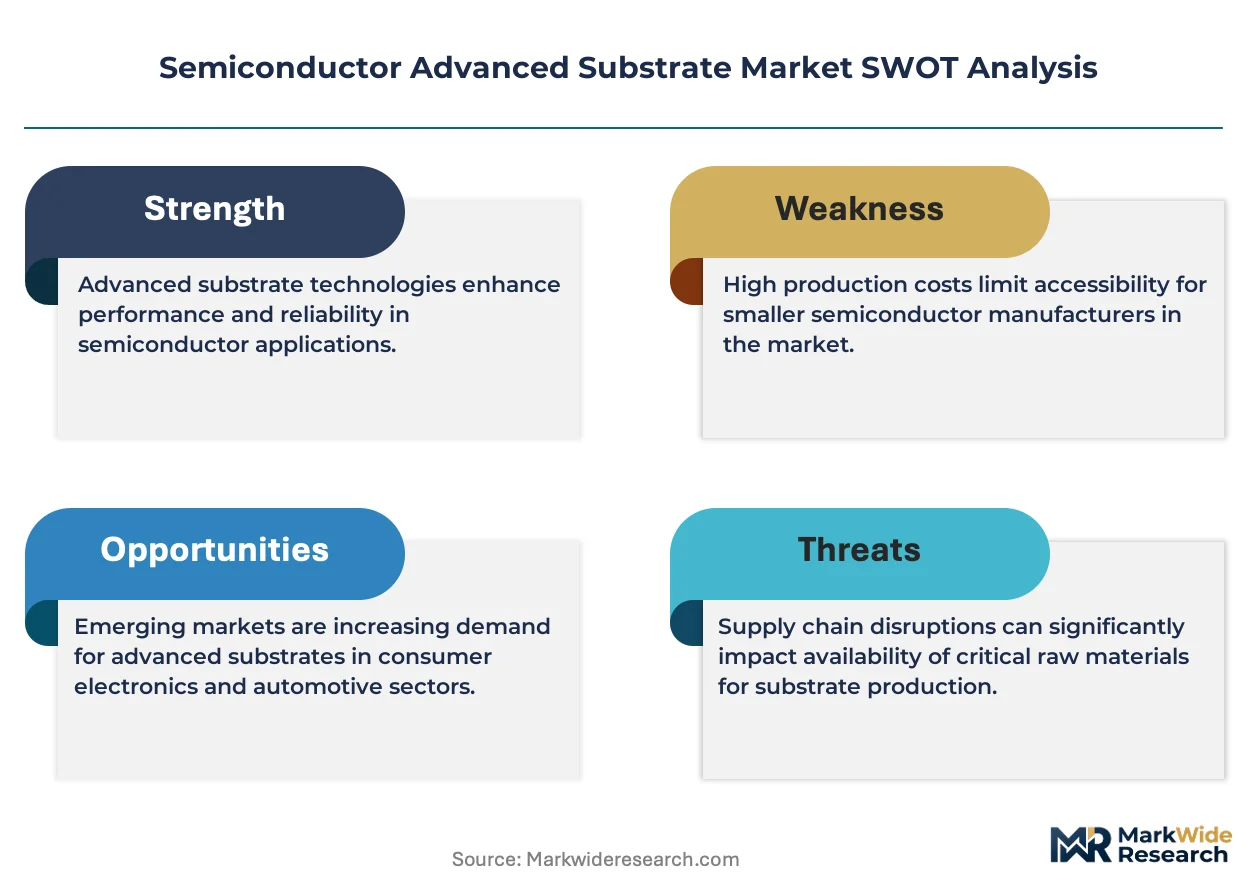
A shift from single-source reliance on captive substrate production toward multi-source qualification is rebalancing procurement across the semiconductor packaging tier. LG Innotek leverages its vertical integration with Samsung's device division to secure high-volume organic substrate allocations. Unimicron Technology Corporation anchors Taiwan's outsourced supply base with massive flip-chip and FC-BGA capacity. AT&S Austria Technologie & Systemtechnik differentiates through European proximity to automotive chip customers seeking shorter logistics loops.
Semiconductor advanced substrates are interposer and package-base materials engineered to manage thermal dissipation, signal integrity, and fine-pitch interconnect density, typically manufactured through multi-layer lamination, thin-film deposition, or laser direct structuring on organic resin, ceramic, or glass cores. Their primary purpose is to bridge the gap between nanometer-scale silicon dies and millimeter-scale printed circuit boards while preserving electrical performance under power and thermal stress. Organic substrates lead volume shipments due to mature supply chains and cost structures, though glass substrates are attracting capital as panel-level packaging scales toward larger form factors. Embedded die technology commands premium positioning where heterogeneous integration of chiplets demands ultra-thin profiles and minimized parasitic losses.
REACH and RoHS frameworks in Europe restrict halogenated flame retardants and heavy metals in substrate laminates, compelling reformulation of resin systems and metallization chemistries. The EU Chips Act and national equivalents in Japan and South Korea tie subsidy eligibility to local content thresholds, reshaping where substrate fabs locate and qualify. The US CHIPS and Science Act directs NIST and Department of Commerce reviewers to scrutinize advanced packaging supply chain security, affecting cross-border substrate flows. Stakeholders must monitor which substrate technology wins panel-level packaging standardization, as this determines capital allocation across organic, glass, and ceramic process lines for the next process node transitions.
Market Dynamics
Panel-level packaging is compressing substrate form factors beyond traditional reticle limits, forcing capital redeployment from organic laminate lines toward glass-core and embedded die processes. Equipment suppliers face qualification bottlenecks as 600mm x 600mm panel formats disrupt established 300mm round-wafer tooling paradigms.
Growth Catalysts
- High-performance computing clusters:Cloud data centers in Taiwan and South Korea are absorbing premium FC-BGA substrates for AI accelerator modules, pulling capacity away from legacy server platforms.
- EU Chips Act local content thresholds:Subsidy eligibility rules are redirecting packaging equipment investments toward Dresden and Grenoble fab corridors, creating captive demand for European-sourced interposers.
- Glass substrate processes:Panel-level packaging adoption is converging with thermal management requirements for 3D-stacked memory, opening process windows that organic laminates cannot fill.
Market Restraints
- ABF resin supply concentration:Mitsubishi Gas Chemical and Ajinomoto control over 80% of ABF film supply, exposing substrate fabricators to single-source pricing volatility and allocation constraints.
- REACH halogen restrictions:ECHA's flame-retardant substance restrictions are forcing resin reformulations that extend qualification cycles by 12-18 months for automotive-qualified laminates.
- Thin-glass handling yields:Sub-100 micron glass core substrates exhibit crack propagation rates above 15% in high-speed pick-and-place operations, constraining volume ramp.
Strategic Opportunities
- India PLI scheme packaging incentives:Subsidy tiers for semiconductor assembly and test are attracting substrate distributors to establish bonded warehouse operations in Gujarat and Karnataka.
- Automotive zone control architectures:Zonal ECU consolidation is creating demand for ultra-large 100mm x 100mm FC-BGA substrates that legacy infrastructure suppliers cannot manufacture.
- Japan METI semiconductor revitalization:Domestic packaging ecosystem grants are enabling Kyushu-based substrate consortia to reclaim advanced organic laminate share from Taiwanese competitors.
Industry Challenges
- Panel-level lithography talent scarcity:Semiconductor equipment operators lack expertise in large-format PCB exposure systems, creating hiring bottlenecks for glass substrate pilot lines.
- Chiplet interconnect standardization delays:UCIe and BoW protocol fragmentation is forcing substrate designers to maintain multiple bump-pattern libraries, inflating NRE costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Advanced Substrate Market |
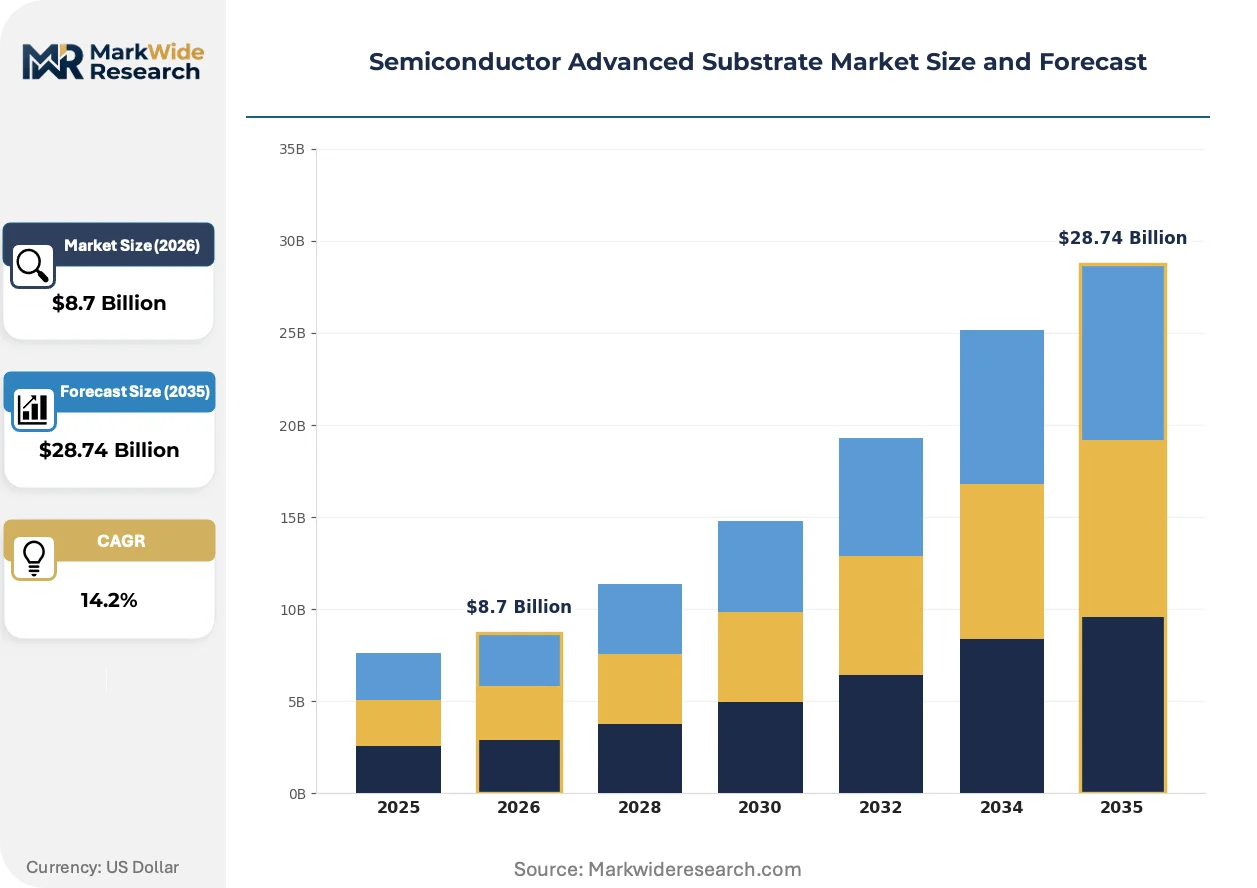
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic Substrate, Organic Substrate, Glass Substrate, Metal Substrate Technology: Embedded Die, Multi-Layer Construction, Thin-Film Technology, Laser Direct Structuring End User: Consumer Electronics, Automotive Components, Industrial Microelectronics, Communication Devices Application: Wireless Communication, Power Management, IoT Devices, High-Frequency Applications |
| Companies Covered | LG Innotek, Unimicron Technology Corporation, TTM Technologies, Zhen Ding Technology, Nippon Mektron, AT&S Austria Technologie & Systemtechnik, Ibiden, Shinko Electric Industries, Samsung Electro-Mechanics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Advanced Substrate Market Strategic Shifts
Substrate technology is bifurcating between evolutionary organic laminate refinements and revolutionary glass-core process development, with capital allocation increasingly favoring the latter for next-node AI packaging. Equipment suppliers are reconfiguring deposition and inspection platforms to accommodate rectangular panel formats.
Glass-core substrates are converging with embedded passive integration requirements for RF front-end modules in 5G millimeter-wave handsets. Samsung's device division has qualified 50-micron through-glass vias for antenna-in-package applications, compressing module z-heights by 40% versus ceramic alternatives. This convergence is enabling smartphone OEMs to reclaim board area for battery expansion without sacrificing RF performance.
ECHA's 2024 REACH candidate list expansion for microplastic additives is compelling substrate laminators to eliminate PTFE-based low-Dk reinforcements from high-speed digital designs. Automotive radar substrate suppliers in Germany and Austria are accelerating ceramic-filled hydrocarbon resin qualifications to maintain material transparency for type-approval documentation. The transition is most acute in 77-81GHz automotive radar modules, where dielectric stability across -40°C to 150°C thermal cycling is mandatory.
Cloud hyperscalers are consolidating substrate procurement through direct long-term supply agreements with Taiwanese and Japanese fabricators, bypassing traditional OSAT intermediaries. Microsoft and Amazon Web Services have established dedicated substrate engineering teams in Taipei and Osaka to co-develop custom FC-BGA designs for proprietary AI training silicon. This disintermediation is most visible in North American data center buildouts, where direct substrate contracts now cover 60% of advanced packaging material spend.
Semiconductor Advanced Substrate Market Segmentation
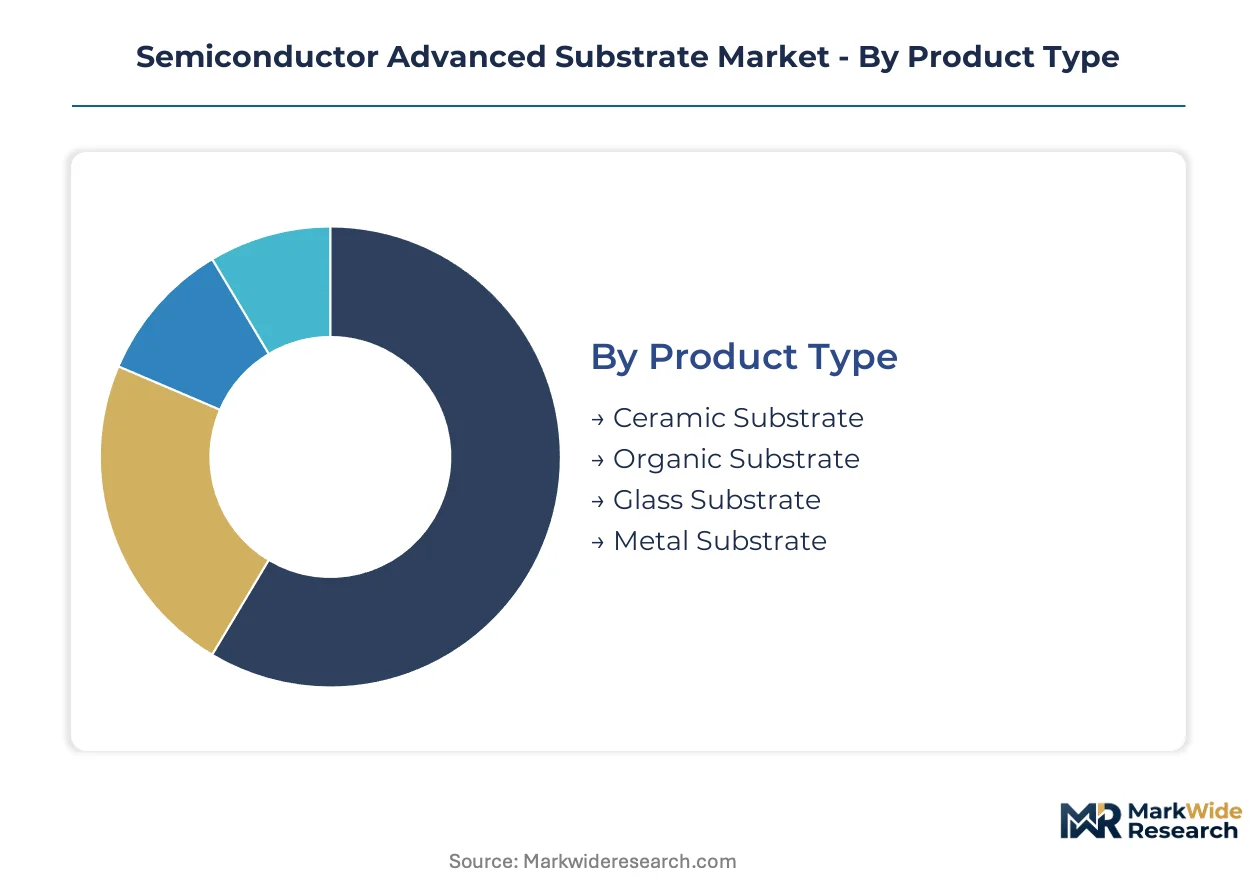
Substrate segmentation determines capital allocation across fabrication lines, with product type dictating equipment compatibility and end-user concentration shaping geographic fab placement. Technology and application splits further refine procurement strategies for heterogeneous integration roadmaps.
Product Type:
Supply concentration in ABF resin and glass core manufacturing creates divergent margin profiles across substrate categories.
- Organic Substrate:Multi-layer epoxy resin laminates reinforced with glass fiber and ABF film build-up layers. Cloud data centers in Taiwan absorb premium FC-BGA capacity for AI accelerator modules, though Mitsubishi Gas Chemical and Ajinomoto control over 80% of ABF supply.
- Glass Substrate:Borosilicate or alkali-free glass cores with through-glass vias manufactured via laser drilling and thin-film metallization. Samsung's device division qualifies 50-micron vias for antenna-in-package applications, compressing module z-heights by 40% versus ceramic alternatives.
- Ceramic Substrate:Alumina, aluminum nitride, or silicon nitride cores with thick-film or thin-film metallization for high-thermal-conductivity applications.
- Metal Substrate:Aluminum or copper base plates with dielectric isolation layers for power module thermal management in automotive traction inverters.
Organic substrates absorb the bulk of installed capacity; glass substrates are expanding most quickly.
Technology:
Process maturity determines qualification timelines, with thin-film and embedded die commanding premium positioning for advanced packaging.
- Multi-Layer Construction:Sequential lamination of resin-coated copper and dielectric layers with laser-drilled microvias. Taiwan's outsourced supply base anchors volume production for legacy flip-chip packages.
- Embedded Die:Active components buried within substrate build-up layers to minimize interconnect length and parasitic losses. Automotive radar suppliers in Germany accelerate ceramic-filled hydrocarbon resin qualifications to maintain material transparency for type-approval documentation.
- Thin-Film Technology:Sputtered or electroplated redistribution layers with sub-micron linewidth control on glass or silicon interposers.
- Laser Direct Structuring:Selective metallization activation on injection-molded thermoplastics for 3D antenna and sensor packaging.
Multi-layer construction dominates volume shipments; embedded die commands the steepest expansion trajectory.
End User:
Customer concentration in hyperscale procurement and automotive tier-1 supply chains reshapes substrate qualification priorities.
- Consumer Electronics:Smartphones, tablets, and wearables requiring ultra-thin profile substrates with high-density interconnect. 5G millimeter-wave handsets drive glass-core convergence with embedded passive integration for RF front-end modules.
- Automotive Components:Zonal ECU consolidation creates demand for ultra-large 100mm x 100mm FC-BGA substrates that legacy infrastructure suppliers cannot manufacture.
- Communication Devices:Base stations, routers, and optical transceivers with high-frequency laminate requirements.
- Industrial Microelectronics:Motor drives, power supplies, and automation controllers prioritizing thermal cycling reliability.
Consumer electronics absorbs the bulk of installed capacity; automotive components are gaining share fastest.
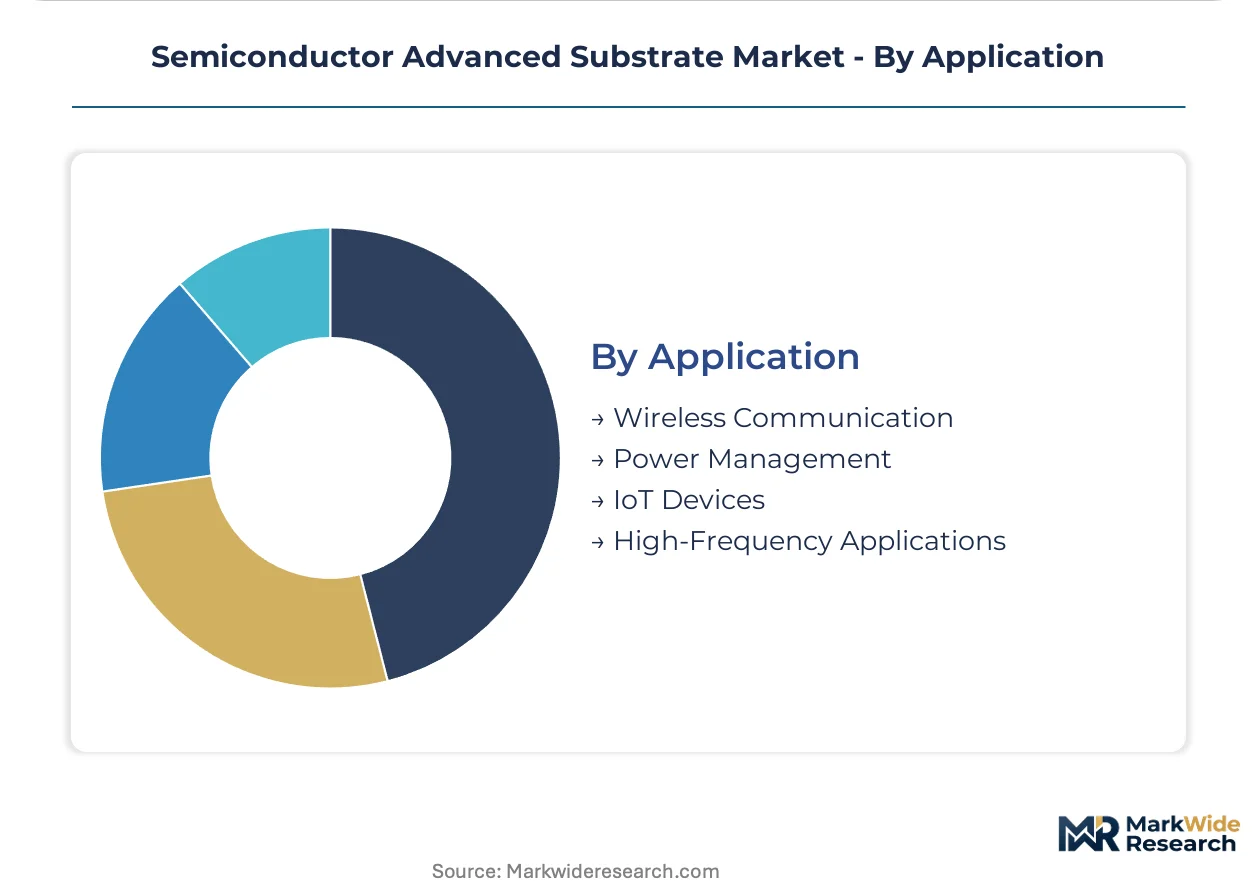
Application:
Performance specifications across frequency, power, and thermal regimes segment substrate material selection.
- High-Frequency Applications:Substrates with low dielectric constant and loss tangent for millimeter-wave and radar systems. ECHA's 2024 REACH candidate list expansion compels elimination of PTFE-based low-Dk reinforcements from 77-81GHz automotive radar designs.
- Power Management:Heavy copper and metal core substrates for thermal dissipation in voltage regulators and DC-DC converters.
- Wireless Communication:Antenna-in-package and RF module substrates with integrated passive components.
- IoT Devices:Cost-optimized laminates for low-power sensor nodes and edge computing endpoints.
High-frequency applications absorb the bulk of installed capacity; power management is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ABF resin supply from Mitsubishi Gas Chemical and Ajinomoto in Japan anchors advanced substrate fabrication geography. Taiwan, South Korea, and Japan concentrate the bulk of capacity, though sovereign semiconductor programs are redistributing investment toward Europe and India.
Taiwan
Cloud hyperscalers from the United States absorb premium FC-BGA substrates for AI accelerator modules through direct procurement agreements. The National Development Council's semiconductor industry promotion programs subsidize advanced packaging infrastructure expansion in Hsinchu and Taichung Science Parks. Unimicron Technology Corporation anchors the outsourced supply base with massive flip-chip capacity concentrated in Taoyuan.
Japan
5G millimeter-wave handset manufacturers drive glass-core substrate adoption with embedded passive integration requirements. METI's semiconductor revitalization grants enable Kyushu-based substrate consortia to reclaim advanced organic laminate share from regional competitors. Shinko Electric Industries and Ibiden concentrate manufacturing operations in Nagano and Gifu prefectures respectively.
South Korea
Samsung's device division qualifies 50-micron through-glass vias for antenna-in-package applications, compressing module z-heights substantially. The K-Chips Act local content thresholds redirect capital toward domestic packaging ecosystems in Suwon and Pyeongtaek. Samsung Electro-Mechanics leverages vertical integration with the parent device division to secure high-volume organic substrate allocations.
Germany
Automotive tier-1 suppliers seek shorter logistics loops for zonal ECU consolidation requiring ultra-large FC-BGA substrates. ECHA's REACH halogen restrictions compel resin reformulations extending qualification cycles for automotive-qualified laminates. AT&S Austria Technologie & Systemtechnik operates fabrication facilities in Leoben and Fehring to serve German automotive chip customers.
India
Semiconductor assembly and test subsidy tiers under the PLI scheme attract substrate distributors to establish bonded warehouse operations. BIS certification requirements for electronic components create compliance pathways for imported advanced packaging materials. Gujarat and Karnataka host emerging logistics hubs serving domestic electronics manufacturing clusters.
Semiconductor Advanced Substrate Market Competitive Environment
Global majors compete with regional champions across fabrication scale and customer proximity dimensions. The vendor base organizes around three tiers: integrated device manufacturer captives, large-scale outsourced specialists, and regional niche fabricators. Strategic archetypes include vertical integrators securing internal demand, scale players dominating volume categories, and proximity specialists serving automotive qualification requirements. Competitive moves center on capacity expansion for panel-level packaging formats and strategic partnerships to secure ABF resin allocations.
Among Asia-Pacific fabricators, LG Innotek exemplifies the captive-integrated archetype through its Samsung affiliation, while Unimicron Technology Corporation represents the outsourced scale specialist model. AT&S Austria Technologie & Systemtechnik occupies a position as the European proximity specialist serving automotive qualification cycles. These three anchors illustrate how geographic concentration in East Asia coexists with regional champions emerging in Europe under sovereign semiconductor program incentives.
| Leading Market Players |
|---|
| LG Innotek |
| Unimicron Technology Corporation |
| TTM Technologies |
| Zhen Ding Technology |
| Nippon Mektron |
| AT&S Austria Technologie & Systemtechnik |
| Ibiden |
| Shinko Electric Industries |
| Samsung Electro-Mechanics |
| Others |
Value Chain & Pricing Dynamics
Cloud hyperscaler direct procurement teams in Taipei and Osaka command contract-based long-term offtake agreements that compress margin buffers for Taiwanese and Japanese fabricators. This buyer concentration forces substrate suppliers to unbundle after-sales technical support and qualification engineering from base wafer pricing, shifting cost recovery toward volume commitments rather than service premiums.
Pricing Analysis
Warranty and qualification engineering services are unbundled from base substrate pricing, with automotive tier-1 suppliers paying separately for extended thermal cycling documentation under ECHA REACH compliance pathways. Three-tier pricing structure across premium, standard, and economy levels separates AI accelerator FC-BGA modules from legacy server substrates and commodity consumer laminates. Cost compression in standard-tier organic substrates is intensifying because Ajinomoto and Mitsubishi Gas Chemical control over 80% of ABF resin supply. Consumer electronics OEMs exhibit highest price sensitivity due to thin margin profiles, while cloud hyperscalers accept premium positioning for custom FC-BGA designs with dedicated engineering teams.
Supply Chain Analysis
Freight costs from Taoyuan and Nagano fabrication clusters to European automotive customers in Stuttgart and Munich add 8-12% landed cost premiums versus regional sourcing. Supply concentrates in Taiwan, Japan, and South Korea, with substrate fabrication drawing from ABF film, borosilicate glass cores, and ceramic-filled hydrocarbon resins as critical inputs. Single-source vulnerability in ABF resin allocation from Japanese chemical suppliers exposes fabricators to forced allocation during capacity crunches. Distribution runs through bonded warehouse operations in Gujarat and Karnataka under India's PLI scheme, bypassing traditional OSAT intermediaries for domestic electronics manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with substrate fabricators pursuing backward integration into ABF resin compounding and glass core melting to escape Japanese chemical supplier pricing power.
For Market Incumbents: Deepen captive ABF resin allocation agreements with Ajinomoto and Mitsubishi Gas Chemical through equity partnerships or dedicated production lines, insulating against forced allocation during AI accelerator demand surges. Expand panel-level packaging capacity in Hsinchu and Taichung Science Parks before equipment supplier qualification bottlenecks harden, securing first-mover positioning for 600mm x 600mm glass substrate formats. For New Entrants and Emerging Players: Direct-to-fabricator digital procurement platforms offer entry pathways for Indian substrate distributors seeking bonded warehouse operations under PLI scheme incentives, bypassing established OSAT intermediaries. Target automotive radar substrate qualifications in Germany and Austria where ECHA REACH halogen restrictions have extended legacy supplier qualification cycles, creating white-space for ceramic-filled hydrocarbon resin alternatives with transparent material documentation. For Investors and Strategic Acquirers: The window for entry favors panel-level packaging equipment suppliers with reconfigured deposition and inspection platforms for rectangular formats, as glass substrate pilot lines face acute lithography talent scarcity. Mid-cap substrate fabricators in Kyushu with METI semiconductor revitalization grants represent consolidation targets for hyperscalers seeking captive supply security. Watch for UCIe and BoW protocol standardization convergence as the inflection signal determining which bump-pattern library investments become stranded.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into ABF Resin Compounding | Reduces exposure to Ajinomoto and Mitsubishi Gas Chemical forced allocation during demand spikes. |
| Panel-Level Packaging Capacity Expansion | Captures 600mm x 600mm glass substrate formats before equipment qualification bottlenecks harden. |
| Automotive Radar Substrate Qualification | Exploits ECHA REACH halogen restriction delays for legacy suppliers in 77-81GHz modules. |
| Direct Hyperscaler Procurement Agreements | Bypasses OSAT intermediaries for 60% of advanced packaging material spend in North American data centers. |
| Embedded Die Technology Investment | Commands premium positioning for heterogeneous chiplet integration with minimized parasitic losses. |
Study Parameters
Document review covered SEC 10-K filings from substrate fabricators, METI semiconductor ecosystem reports, and ECHA REACH substance restriction databases, complemented by interviews with substrate procurement managers at cloud hyperscalers, plant managers at Taiwanese ABF laminate facilities, and regulatory affairs leads navigating EU Chips Act local content thresholds. Bottom-up capacity modeling across Hsinchu, Taoyuan, and Kyushu fabrication clusters was cross-checked against top-down spend analysis from hyperscaler direct procurement disclosures.
Segment-level projections across organic, glass, and ceramic substrate categories incorporate technology adoption curves for panel-level packaging formats and end-use concentration in AI accelerator modules versus automotive zonal ECUs. CAGRs were derived from elasticity-adjusted demand functions tied to cloud data center buildout schedules and sovereign semiconductor program capital deployment timelines. The analytical framework incorporates ABF resin supply concentration risk and glass substrate handling yield constraints as scenario-weighted inputs.
The model holds under sustained sovereign subsidy deployment and stable ABF resin allocation; deviation in Japanese chemical supplier production constraints or EU Chips Act threshold revisions would shift capacity expansion geography. Forecasts reflect documented assumptions about panel-level packaging standardization timelines and UCIe protocol adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Vapor Deposition Market
Semiconductor Fabrication
Photoresist Removal Market
Semiconductor Fabrication
Physical Vapor Deposition (PVD) Market
Semiconductor Fabrication
Ion Implantation Machine Market
Semiconductor Fabrication
Semiconductor Etching Cleaner Market
Semiconductor Fabrication
Gan Substrate and Gan Wafer Market
Semiconductor Fabrication
Ion Implanter Market
Semiconductor Fabrication
Diamond Semiconductor Substrates Market
Semiconductor Fabrication
Mask Alignment Lithography Market
Semiconductor Fabrication
Global Dry Etching Machine Market
Semiconductor Fabrication
Semiconductor Logistics Market
Semiconductor Fabrication
Manual Wafer Aligner Market
Semiconductor Fabrication
Global Dielectric Etchers Market
Semiconductor Fabrication
Solar Ingot Wafer Market
Semiconductor Fabrication
8-Inch Silicon Carbide (Sic) Wafer Market
Semiconductor Fabrication
Thin Layer Deposition Market