
 Ion Implantation Machine Market | 2026-2036
Ion Implantation Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Ion Implantation Machine Market Outlook
South Korea's Pyeongtaek semiconductor corridor is fragmenting as multiple domestic and foreign equipment suppliers establish parallel service and refurbishment capabilities. Applied Materials leverages its installed base of high-current systems to sustain aftermarket revenue across memory fabs. Nissin Ion Equipment anchors Japanese supply continuity through proprietary beamline architectures. ULVAC Technologies competes on low-energy platform specialization for power device foundries.
An ion implantation machine accelerates dopant ions into semiconductor wafers with precision energy control ranging from sub-keV to MeV levels, modifying electrical properties at targeted substrate depths. The equipment employs mass spectrometry filtration and electrostatic beam steering to achieve dose uniformity within one percent across 300-millimeter wafer surfaces. Single wafer architectures now dominate leading-edge logic production where thermal budget constraints demand sequential processing. High-current systems capture expanding margin pools in power device applications requiring deep junction profiles for insulated-gate bipolar transistors. Batch platforms retain structural relevance in mature node and research settings where throughput economics favor parallel wafer handling.
EPA emissions standards constrain fluorinated process gas handling in US-based fabrication facilities, while REACH substance restrictions in Europe limit specific beamline lubricant chemistries. Japan's METI coordinates export control alignment with Wassenaar Arrangement dual-use technology classifications for sub-65 nanometer implantation equipment. Stakeholders must monitor evolving multilateral semiconductor equipment trade restrictions and their cascading effects on regional service network viability.
Market Dynamics
The migration toward sub-3 nanometer logic nodes is compressing thermal budgets and forcing single-wafer architectures to displace batch processing in leading-edge fabs. This structural shift redistributes equipment demand toward high-precision electrostatic steering systems and away from legacy parallel-wafer platforms.
Growth Catalysts
- Advanced node capital expenditure:Logic chip manufacturers in Taiwan and South Korea are scaling fabrication capacity for sub-5 nanometer production, requiring precision ion implantation systems with sub-keV energy control.
- Power device junction requirements:Insulated-gate bipolar transistor manufacturing for electric vehicle inverters demands deep implant profiles that only high-current beamline architectures can deliver.
- REACH substance restrictions:European material purity mandates for beamline components are accelerating replacement cycles in legacy installed bases.
Market Restraints
- Beamline component supply concentration:Precision electrostatic lenses and mass spectrometry magnets depend on a narrow supplier base concentrated in Japan and Germany.
- Fluorinated gas handling costs:EPA emissions standards for process gas containment impose capital-intensive abatement infrastructure on US-based fabrication facilities.
- Technical limitation in ultra-low energy:Sub-200 eV implantation for shallow junction formation suffers from space-charge beam blowup that degrades dose uniformity.
Strategic Opportunities
- Power device foundry expansion:Silicon carbide and gallium nitride substrate processing for automotive traction inverters creates demand for specialized medium-current platforms.
- Service network localization:Equipment refurbishment and beamline optimization services are consolidating around Hsinchu and Pyeongtaek semiconductor corridors.
- Wassenaar Arrangement alignment:Japan's METI coordination of export controls for sub-65 nanometer equipment is creating compliance consulting and upgrade pathway services.
Industry Challenges
- Electrostatics engineering talent scarcity:Beam optics modeling and space-chage compensation algorithm development require specialized plasma physics expertise that fabs struggle to source.
- Legacy system integration friction:New single-wafer platforms must interface with existing fab automation protocols and metrology databases, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ion Implantation Machine Market |
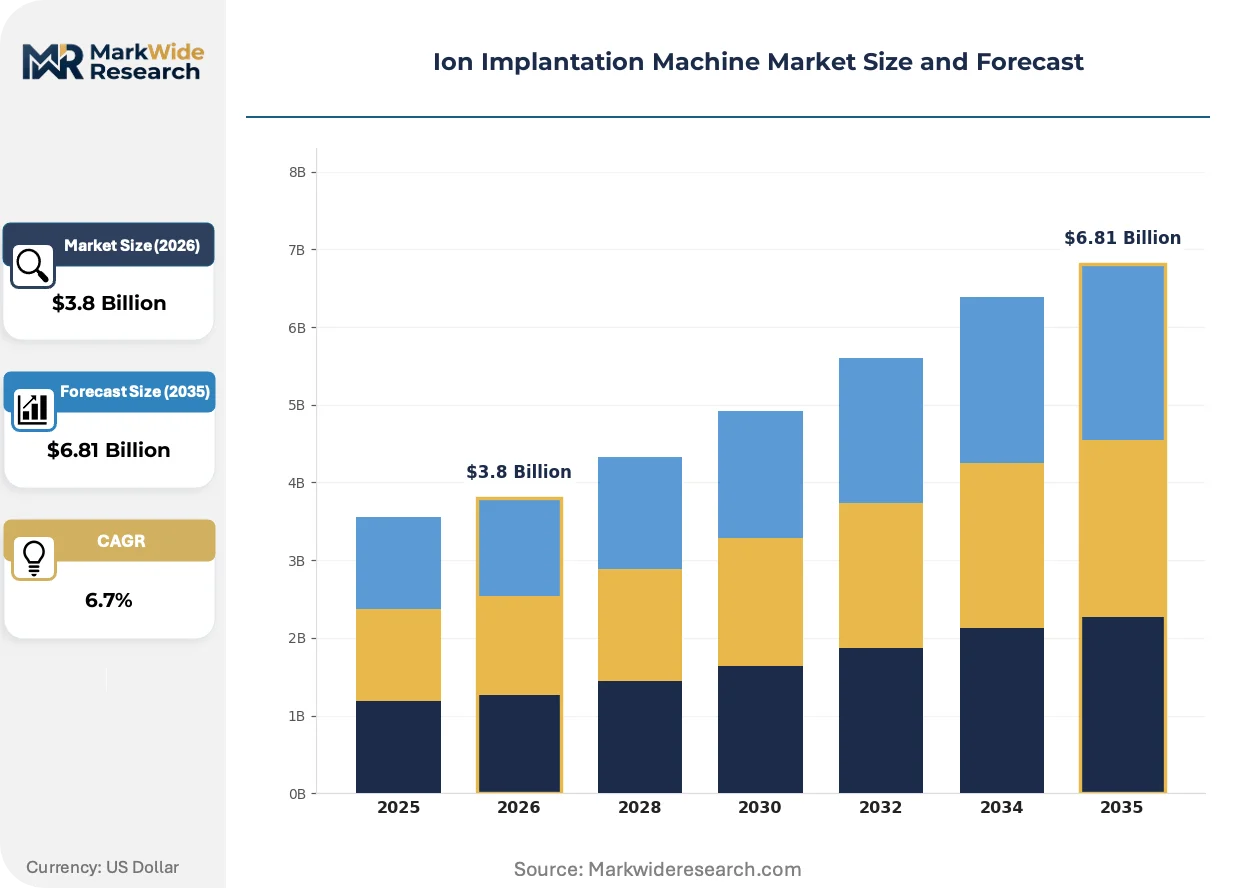
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch, Single Wafer, High-Current, Low-Energy Technology: Shallow Junction, Deep Junction, Pulsed, Continuous End User: Semiconductor Fabrication, University Research, Contract Manufacturing, MEMS Application: Power Devices, RF Devices, Optical Devices, Sensors |
| Companies Covered | Nissin Ion Equipment, ULVAC Technologies, Applied Materials, Kingstone Semiconductor, Advanced Ion Beam Technology, Axcelis Technologies, Intevac, Ion Beam Services, Sumitomo Heavy Industries Ion Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ion Implantation Machine Market Strategic Shifts
Beamline architectures are undergoing fundamental redesign as thermal budget constraints and precision requirements intensify simultaneously. Three converging developments are restructuring equipment specifications and vendor competitive positions.
Plasma doping technology is collapsing the distinction between conventional beamline implantation and conformal doping for three-dimensional device structures. Memory manufacturers in South Korea are piloting plasma-based systems for vertical NAND string formation. This convergence is collapsing the addressable market for conventional high-dose beamline systems in charge-trap flash fabrication.
Japan's METI has aligned domestic export licensing with Wassenaar Arrangement dual-use classifications for sub-65 nanometer implantation equipment. This regulatory harmonization is restricting technology transfer to specific fabrication facilities in designated countries. Equipment vendors are responding by segmenting product roadmaps into export-controlled and unrestricted platform variants.
Foundry customers are unbundling after-sales service contracts from original equipment purchases and awarding refurbishment work to independent service providers. This disintermediation is compressing vendor aftermarket revenue pools and accelerating knowledge transfer to third-party beamline specialists. The pattern is most visible in Taiwan's Hsinchu Science Park, where captive service capabilities have proliferated across multiple equipment generations.
Ion Implantation Machine Market Segmentation
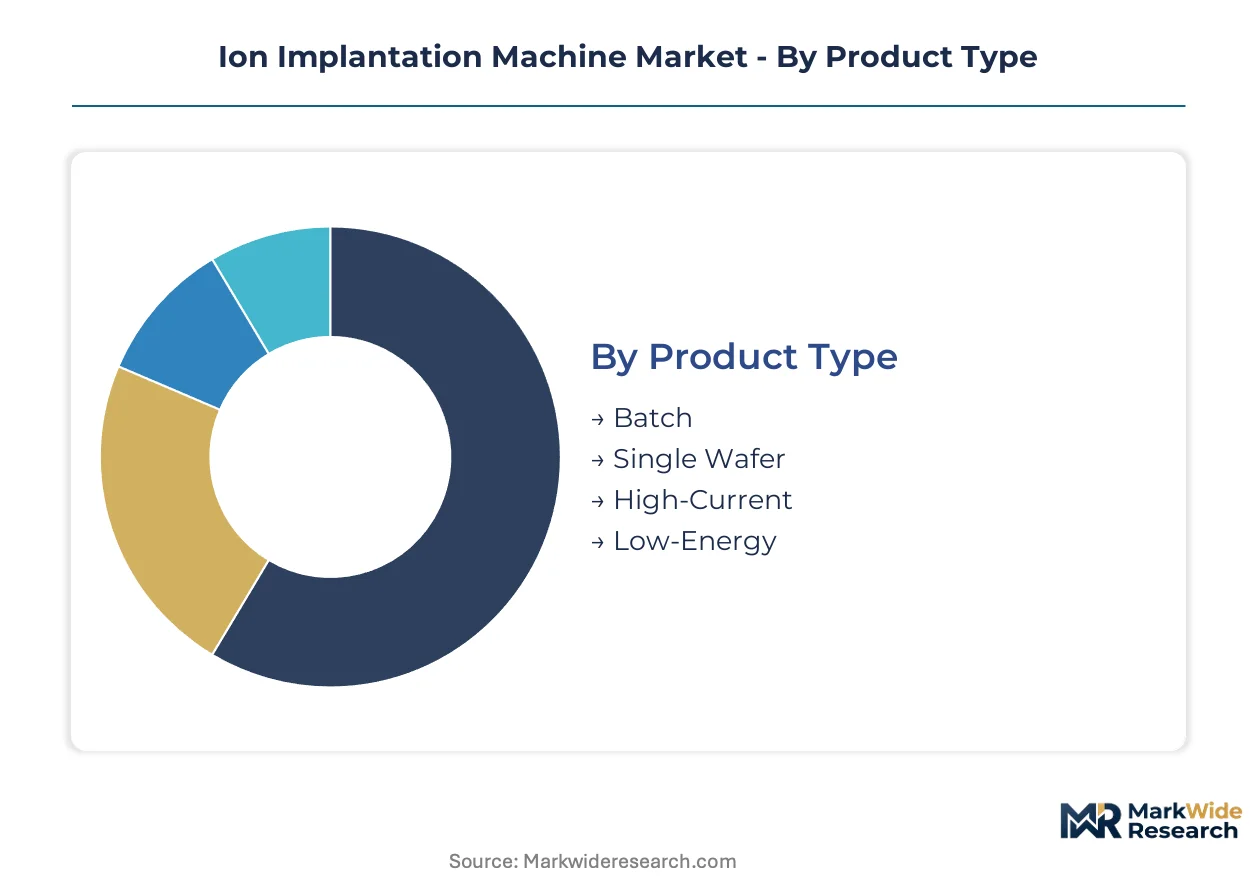
Ion implantation equipment specifications diverge sharply across thermal budgets, dose requirements, and wafer throughput economics. Segmentation reveals how vendor R&D investments align with distinct fabrication constraints rather than pursuing universal platform dominance.
Product Type:
Equipment architectures span from parallel-batch thermal processing to precision single-wafer sequential handling, each occupying distinct positions in the cost-precision tradeoff spectrum.
- Single Wafer:Sequential processing architectures enable sub-keV energy control with electrostatic beam steering for sub-5 nanometer logic nodes. Taiwan's Hsinchu foundries are scaling this platform fastest as thermal budget compression eliminates batch alternatives at leading edge.
- High-Current:Beamline systems delivering mega-electron-volt acceleration and deep junction profiles serve insulated-gate bipolar transistor manufacturing for automotive traction inverters. South Korean memory fabs and Chinese power device foundries anchor demand concentration here.
- Batch:Parallel wafer handling retains economic viability in mature node production and research settings where throughput per dollar supersedes precision requirements. European legacy installed bases sustain refurbishment demand for these platforms.
- Low-Energy:Specialized platforms address sub-200 eV implantation challenges for shallow junction formation, though space-charge beam blowup constrains dose uniformity at ultra-low energies.
The dominant share belongs to Single Wafer systems, while High-Current is closing the gap fastest on power device foundry expansion.
Technology:
Process modalities reflect competing imperatives between junction depth precision and throughput economics in dopant activation.
- Shallow Junction:Ultra-low energy implantation with rapid thermal annealing enables source-drain extension formation at sub-10 nanometer nodes. Logic manufacturers in Taiwan and South Korea specify these processes for fin field-effect transistor architectures.
- Deep Junction:High-dose MeV-level implantation creates buried layers and well structures for power discrete and analog integrated circuits. Silicon carbide substrate processing for electric vehicle inverters is accelerating adoption of enhanced deep junction capabilities.
- Pulsed:Time-modulated beam delivery reduces substrate heating during high-dose implants, extending applicability to temperature-sensitive compound semiconductor materials.
- Continuous:Steady-state beam operation maximizes throughput for standard complementary metal-oxide-semiconductor processes where thermal budget headroom permits conventional processing.
Shallow Junction processes command the largest equipment allocation, with Deep Junction applications expanding most quickly on wide-bandgap semiconductor ramp-ups.
End User:
Customer types span from high-volume production fabs to research institutions with diverging capital intensity and technical support requirements.
- Semiconductor Fabrication:Integrated device manufacturers and pure-play foundries operate the largest installed bases, with procurement concentrated among Taiwan Semiconductor Manufacturing Company, Samsung Electronics, and Intel Corporation capital expenditure cycles.
- Contract Manufacturing:Outsourced assembly and test providers are expanding into front-end processing, creating demand for flexible medium-current platforms with rapid recipe changeover capabilities.
- University Research:Academic cleanrooms prioritize versatile batch systems supporting multiple material systems and dopant species for exploratory device physics.
- MEMS:Microelectromechanical systems fabricators leverage implantation for piezoresistive element formation and hermetic sealing applications with specialized dose uniformity requirements across non-planar topographies.
Semiconductor Fabrication retains overwhelming equipment share, though Contract Manufacturing is gaining ground fastest on foundry outsourcing trends.
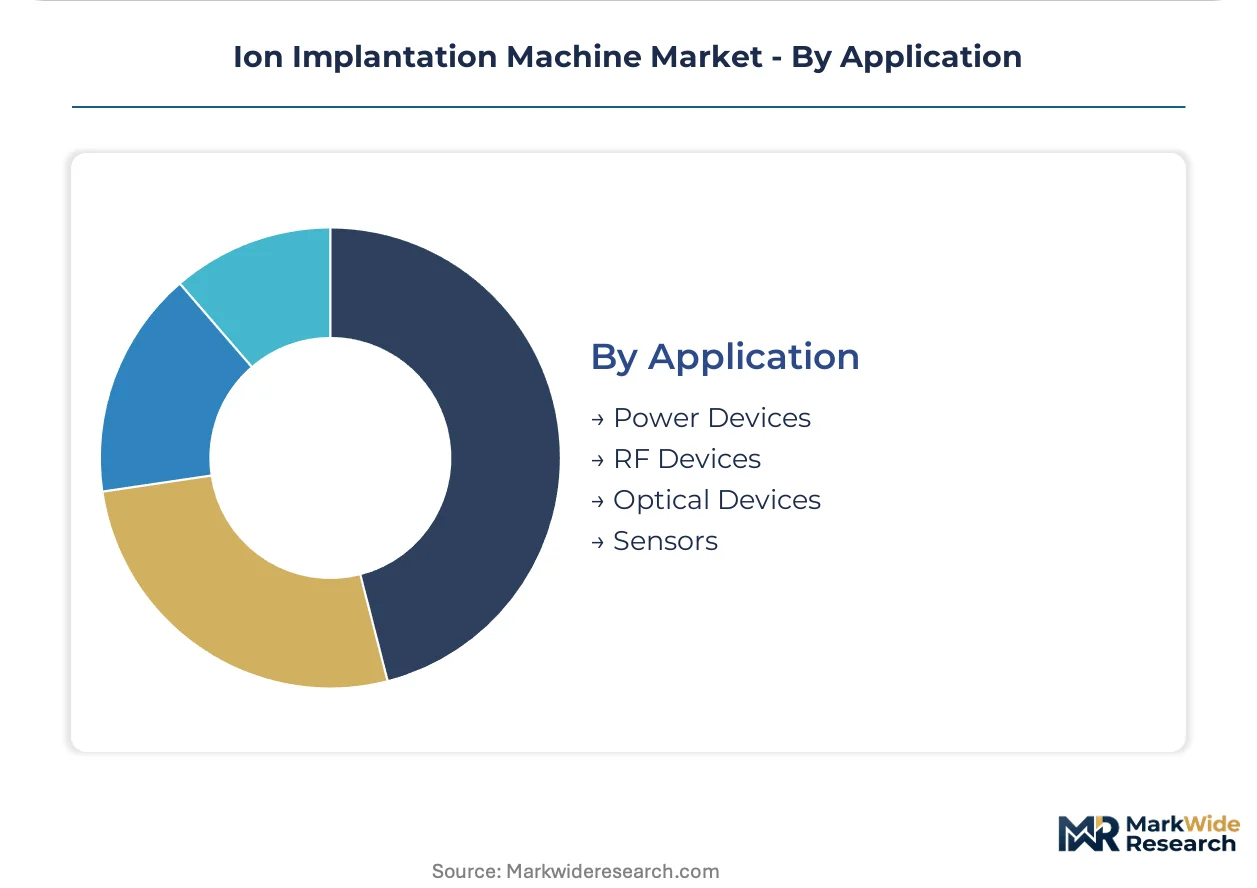
Application:
Device categories impose distinct beam energy, dose, and angular control specifications that reshape equipment configuration priorities.
- Power Devices:Insulated-gate bipolar transistors and metal-oxide-semiconductor field-effect transistors for electric vehicle inverters require deep, high-dose implants with precise depth control. Automotive qualification standards are tightening process traceability requirements.
- RF Devices:Radio frequency integrated circuits for 5G base stations and handsets demand ultra-shallow junctions with minimal crystal damage to preserve carrier mobility. Gallium arsenide and gallium nitride processing extends equipment specifications into compound semiconductor territory.
- Optical Devices:Photonic integrated circuits and image sensors utilize implantation for waveguide formation and pinned photodiode structures, requiring specialized annealing integration.
- Sensors:Accelerometers, gyroscopes, and pressure sensors employ implantation for piezoresistor definition and wafer-level encapsulation, with automotive safety standards driving zero-defect process protocols.
Power Devices represent the steepest expansion trajectory, while RF Devices maintain the largest cumulative installed base on mobile communications infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI coordinates export licensing with Wassenaar Arrangement classifications for sub-65 nanometer implantation equipment, anchoring Japan's regulatory influence over technology transfer to fabrication clusters in Taiwan and South Korea.
Taiwan
Logic foundries in Hsinchu are scaling single-wafer platform procurement for sub-3 nanometer node production, with capital expenditure cycles concentrated at Taiwan Semiconductor Manufacturing Company facilities. The National Science and Technology Council oversees cleanroom infrastructure subsidies under the Chip Implementation Act. Taichung's Central Taiwan Science Park is attracting beamline component suppliers seeking proximity to leading-edge demand.
South Korea
Samsung Electronics and SK Hynix are expanding Pyeongtaek corridor capacity for memory and logic fabrication, driving high-current system requirements for deep junction formation. The Ministry of Trade, Industry and Energy administers K-Chips Act tax credits for domestic equipment localization. Yongin's Giheung cluster is fragmenting as independent service providers establish parallel refurbishment capabilities alongside original vendor networks.
United States
Intel Corporation's Arizona and Oregon fabs are commissioning single-wafer architectures for advanced node production, though thermal budget constraints limit batch platform relevance. EPA emissions standards for fluorinated process gas handling impose capital-intensive abatement infrastructure on domestic fabrication facilities. Hillsboro's Ronler Acres campus is consolidating electrostatics engineering talent for beam optics development.
Japan
Tokyo Electron and domestic beamline specialists anchor precision component supply for electrostatic lenses and mass spectrometry magnets. METI's alignment with Wassenaar Arrangement dual-use classifications restricts technology transfer to designated fabrication facilities. Kyoto's semiconductor equipment corridor sustains narrow supplier concentration for critical beamline subsystems.
Germany
Infineon Technologies and automotive power device foundries are expanding Dresden and Regensburg capacity for silicon carbide substrate processing. ECHA REACH substance restrictions limit specific beamline lubricant chemistries, accelerating replacement cycles in legacy installed bases. Saxony's Silicon Saxony cluster is consolidating medium-current platform demand for insulated-gate bipolar transistor manufacturing.
Ion Implantation Machine Market Competitive Environment
Integrated beamline architects and specialized component suppliers split the market along precision-depth boundaries. Three strategic archetypes dominate: Japanese precision electrostatics houses, American high-current platform specialists, and emerging Chinese system integrators. Competitive positioning hinges on aftermarket service network density and export control compliance consulting capabilities.
Within the precision-tier segment, Nissin Ion Equipment and ULVAC Technologies occupy positions anchored by proprietary beamline architectures and regional service continuity. Applied Materials exemplifies the high-current archetype through installed base leverage across memory fabrication corridors. Sumitomo Heavy Industries Ion Technology represents diversified industrial conglomerate participation in semiconductor equipment verticals.
| Leading Market Players |
|---|
| Nissin Ion Equipment |
| ULVAC Technologies |
| Applied Materials |
| Kingstone Semiconductor |
| Advanced Ion Beam Technology |
| Axcelis Technologies |
| Intevac |
| Ion Beam Services |
| Sumitomo Heavy Industries Ion Technology |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in mature-node batch platforms across European legacy installed bases is compressing vendor pricing power while simultaneously accelerating service contract unbundling. This utilization imbalance feeds directly into supplier consolidation around Hsinchu and Pyeongtaek corridors, where proximity to leading-edge demand justifies premium positioning.
Pricing Analysis
Geographic price spreads of 15-25% separate East Asian procurement from European and North American transactions, reflecting bundled after-sales service density and export control compliance consulting. Equipment procurement follows a contract-based long-term offtake model with milestone payments tied to installation acceptance and yield qualification. Price differentiation centers on certification grade for Wassenaar Arrangement alignment and vertical integration depth for beamline component sourcing. Cost compression in standard-tier systems is intensifying because Chinese system integrators are fielding competitive medium-current platforms. Memory manufacturers exhibit highest price sensitivity due to cyclical capital expenditure constraints, while automotive power device foundries prioritize qualification speed over unit economics.
Supply Chain Analysis
Contract manufacturing concentration at Taiwan Semiconductor Manufacturing Company, Samsung Electronics, and Intel Corporation fabs anchors equipment demand forecasting and production scheduling. Precision electrostatic lenses and mass spectrometry magnets draw from supplier networks concentrated in Japan and Germany, with Kyoto's semiconductor equipment corridor sustaining narrow specialization for critical beamline subsystems. Supply chain risk centers on single-source vulnerability for high-purity beamline lubricants restricted under ECHA REACH substance mandates. Distribution runs through direct vendor-fab relationships with localized service subsidiaries, though independent refurbishment providers are fragmenting aftermarket channels in Taiwan and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ion implantation machine market sits in early-cycle expansion as power device foundry buildouts for silicon carbide traction inverters create equipment demand outside traditional logic and memory fabrication. Penetration of plasma doping alternatives remains below critical thresholds, preserving beamline architecture relevance through the projection horizon.
For Market Incumbents: Build installed base moats through captive refurbishment networks in Hsinchu and Pyeongtaek corridors to counter independent service provider disintermediation. Deepen backward integration into electrostatic lens manufacturing to reduce dependency on Japanese and German component suppliers. Pursue Wassenaar Arrangement compliance certification as a channel control mechanism for export-restricted platform variants. For New Entrants and Emerging Players: Build out specialized medium-current platforms for silicon carbide substrate processing in automotive power device foundries, where incumbent coverage remains thin. Target European legacy installed base replacement cycles accelerated by REACH substance restrictions on beamline lubricants. Lead with rapid recipe changeover capabilities and flexible service contracting to differentiate against bundled incumbent offerings. For Investors and Strategic Acquirers: Capital is best deployed toward precision electrostatics specialists with proprietary beamline architectures and regional service continuity in Japan. Long-term viability over the next decade hinges on positioning for sub-3 nanometer logic node thermal budget constraints and power device wide-bandgap semiconductor ramp-ups. Monitor plasma doping pilot adoption rates in South Korean vertical NAND fabrication as the critical inflection signal for conventional beamline demand displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Service Network Localization | Proximity to Hsinchu and Pyeongtaek corridors reduces commissioning timelines and captures unbundled refurbishment demand. |
| Beamline Component Backward Integration | In-house production of electrostatic lenses mitigates supply concentration risk in Kyoto and German precision optics clusters. |
| Export Control Compliance Consulting | Wassenaar Arrangement alignment services create recurring revenue streams alongside equipment sales to restricted destinations. |
| Plasma Doping Platform Development | Vertical NAND string formation pilots at Samsung Electronics and SK Hynix threaten conventional high-dose beamline positions. |
| Silicon Carbide Process Qualification | Automotive traction inverter demand at Infineon Dresden and Regensburg facilities drives medium-current platform specialization. |
Study Parameters
Cross-validation between equipment vendor sales disclosures and foundry capital expenditure announcements anchors the qualitative findings on procurement timing and specification priorities. Primary interviews with fab engineering directors, beamline service technicians, semiconductor equipment procurement managers, and export control compliance officers were combined with secondary validation from METI licensing records, ECHA substance restriction databases, SEC 10-K filings, and foundry investor day presentations. Bottom-up triangulation across individual tool procurement cycles and top-down reconciliation against aggregate capital expenditure flows ensure dimensional consistency.
Calibration against historical replacement cycle patterns and node migration timelines informs the projection framework across the analysis window. Segmentation dimensions modeled include equipment architecture, process technology, end-user type, application category, and regional regulatory cluster. CAGRs were derived from weighted average of vendor shipment projections and foundry capacity buildout announcements. Industry-specific forecast inputs incorporate thermal budget compression curves for sub-3 nanometer logic and silicon carbide substrate ramp rates for automotive power devices.
Stress conditions across Wassenaar Arrangement expansion scenarios, plasma doping adoption acceleration, and fluorinated gas regulatory tightening were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on node migration timelines and capital expenditure cyclicality. Cross-checking against SEMI equipment market statistics and foundry utilization rate disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Manual Wafer Aligner Market
Semiconductor Fabrication
Epitaxial Wafer Market
Semiconductor Fabrication
Etchant for FPD Market
Semiconductor Fabrication
Photoresist Removal Market
Semiconductor Fabrication
Diamond Semiconductor Substrates Market
Semiconductor Fabrication
300mm Silicon Wafers Market
Semiconductor Fabrication
Global Micromachining Market
Semiconductor Fabrication
Global Dielectric Etchers Market
Semiconductor Fabrication
Mask Alignment Lithography Market
Semiconductor Fabrication
Semiconductor Etching Cleaner Market
Semiconductor Fabrication
Deep Reactive Ion Etching (DRIE) Etcher Market
Semiconductor Fabrication
North America Atomic Layer Deposition Market
Semiconductor Fabrication
Gan Substrate and Gan Wafer Market
Semiconductor Fabrication
Global Foundry Service Market
Semiconductor Fabrication
Semiconductor Advanced Substrate Market
Semiconductor Fabrication
Solar Ingot Wafer Market