
 Global Consumer Standard Logic IC Market | 2026-2036
Global Consumer Standard Logic IC Market Size, Share, and Industry Trends Forecast 2026-2036
Global Consumer Standard Logic IC Market Foresight
Modular packaging of logic functions into integrated power-management bundles is pivoting buyer procurement away from discrete standard logic ICs toward functionally dense subsystems. Texas Instruments Incorporated leverages its analog-digital integration expertise to anchor premium socket positions in consumer device reference designs. NXP Semiconductors N.V. competes through automotive-qualified process lines that cross-serve consumer-grade reliability demands. ROHM Semiconductor specializes in ultra-low-voltage CMOS families that sustain design wins in battery-constrained wearables.
Consumer standard logic ICs are semiconductor devices built on CMOS, bipolar, BiCMOS, TTL, or ECL architectures that perform Boolean operations at supply voltages typically ranging from 0.8 V to 5.5 V, fabricated through silicon-gate or thin-film transistor processes on 200 mm or 300 mm wafers. These devices buffer, gate, and level-shift signals across smartphones, gaming consoles, digital cameras, and wearable devices where board space and power budgets constrain design choices. CMOS logic ICs occupy the largest volume tier due to their near-zero static power draw, while BiCMOS variants command margin premiums in mixed-signal consumer applications requiring speed without sacrificing energy efficiency. Silicon-gate technology leads manufacturing throughput, though programmable array configurations are gaining traction among ODMs seeking firmware-flexible logic replacements.
The US FCC governs electromagnetic emissions from logic-intensive consumer devices, pushing suppliers toward lower-noise switching specifications. EU REACH and RoHS frameworks restrict lead and halogenated flame retardants in IC packages, compelling substrate material transitions across the supply base. Japan's METI promotes domestic semiconductor resilience through production subsidies that indirectly standardize logic IC sourcing security expectations. Stakeholders must monitor how dual-use export control expansions affect mature-node logic device trade flows between Asian manufacturing hubs and Western consumer brands.
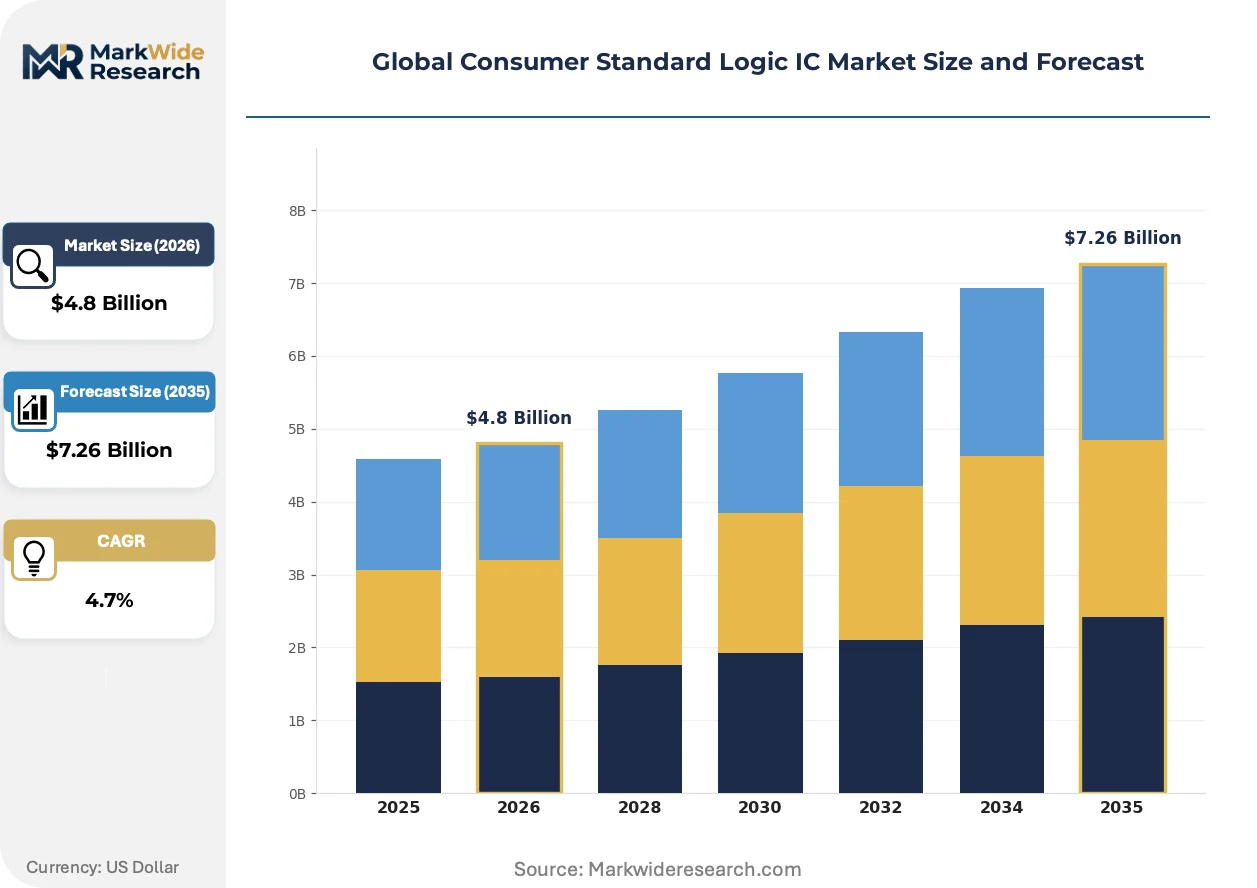
Market Dynamics
Foundry capacity bottlenecks for mature-node logic devices are compressing lead times and forcing consumer electronics brands into multi-year supply agreements that reshape procurement flexibility across the entire value chain.
Growth Catalysts
- 5G Handset Refresh Compression:Smartphone OEMs are accelerating replacement cycles for low-power logic ICs as sub-6 GHz and mmWave variants proliferate in mid-tier devices.
- EU REACH Material Compliance:Tightening substance restrictions on lead and halogenated flame retardants in IC packaging substrates are standardizing cleaner material transitions across supplier bases.
- Wearables Power Budget Constraints:Battery-constrained form factors in fitness trackers and smartwatches are pulling demand toward ultra-low-voltage CMOS families that minimize static power draw.
Market Restraints
- Foundry Concentration Risk:Mature-node logic capacity concentrates heavily in South Korea and Taiwan, creating single-source vulnerability for consumer-grade device manufacturers.
- Substrate Material Cost Volatility:Epoxy molding compounds and leadframe alloys face price pressure from energy-intensive production processes and rare earth supply tightness.
- Discrete Logic Substitution:Programmable logic devices and integrated power-management subsystems are displacing standard logic IC sockets in space-constrained reference designs.
Strategic Opportunities
- India Electronics Manufacturing:Production-linked incentive schemes are attracting assembly operations that will localize logic IC consumption for domestic smartphone and appliance brands.
- Automotive-Grade Process Crossover:Consumer device makers are sourcing from AEC-Q100 qualified lines to capture reliability premiums in premium-tier electronics.
- Firmware-Configurable Logic:Programmable array configurations enable ODMs to reduce SKU proliferation through field-updatable logic replacements.
Industry Challenges
- Packaging Engineer Talent Scarcity:Flip-chip and wafer-level packaging expertise remains concentrated among senior technologists near Hsinchu and Seoul clusters.
- Dual-Use Export Control Complexity:Expanding restrictions on mature-node logic device trade flows between Asian manufacturing hubs and Western consumer brands complicates supply chain planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Consumer Standard Logic IC Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CMOS Logic ICs, Bipolar Logic ICs, BiCMOS Logic ICs, TTL Logic ICs, ECL Logic ICs Technology: Silicon Gate, Thin Film Transistor, Resistor Transistor, Programmable Array, Bipolar Junction Application: Smartphones, Consumer Electronics, Wearable Devices, Gaming Consoles, Digital Cameras Customer Type: Original Design Manufacturers, Contract Manufacturers, Electronics Assemblers, Distributors |
| Companies Covered | Renesas Electronics Corporation, Toshiba Electronic Devices & Storage Corporation, Analog Devices Inc., Broadcom Inc., NXP Semiconductors N.V., Texas Instruments Incorporated, STMicroelectronics N.V., ROHM Semiconductor, MediaTek Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Consumer Standard Logic IC Market Shifts & Advancements
Silicon-gate CMOS architectures are converging with advanced packaging techniques to deliver function density that outpaces traditional discrete logic scaling limits.
Embedded non-volatile memory within standard logic ICs is integrating configuration bit storage directly onto the same die, eliminating external EEPROM requirements. Wearable device ODMs are adopting these monolithic solutions aggressively to reclaim board area for larger batteries. This integration is compressing bill-of-materials line counts while simplifying firmware update logistics for battery-constrained designs.
Japan's METI production subsidies are channeling capital toward domestic 200 mm wafer fab upgrades that indirectly standardize logic IC sourcing security expectations. Consumer brands now specify supplier geographic diversity clauses that mirror these resilience frameworks. South Korean smartphone OEMs are responding fastest, diversifying qualified vendor lists to include METI-backed Japanese sources.
Direct procurement contracts between consumer electronics brands and foundries are displacing traditional distributor-mediated purchasing for high-volume logic families. Tier-one smartphone manufacturers now negotiate wafer starts directly with Taiwan-based foundries, bypassing catalog distributors entirely. This channel compression is most visible in South Korea, where Samsung and LG Electronics have established captive procurement teams in Hsinchu Science Park.
Global Consumer Standard Logic IC Market Segmentation
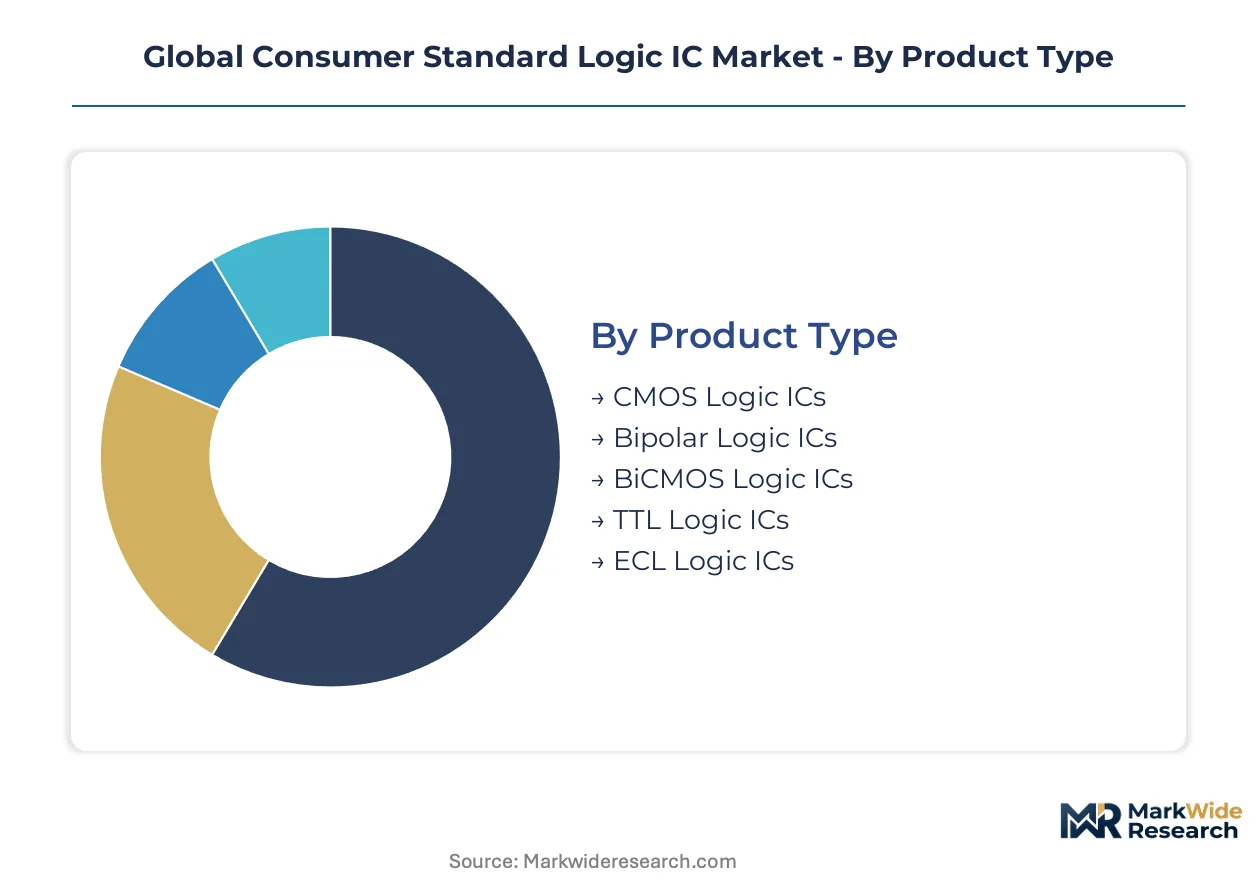
Logic IC procurement patterns diver sharply between high-volume consumer electronics and specialized wearable applications. Understanding where each segment sits on the integration spectrum—from standalone discrete devices to deeply embedded subsystems—reveals which categories command premium positioning versus commodity pricing.
Product Type:
CMOS variants dominate standalone logic implementations while BiCMOS penetrates mixed-signal consumer subsystems where analog-digital boundaries blur.
- CMOS Logic ICs:Near-zero static power consumption makes these the default choice for battery-powered smartphones and wearables operating at sub-1V thresholds. South Korean smartphone OEMs book mature-node CMOS capacity two years forward to secure sub-6 GHz 5G handset logic supplies.
- BiCMOS Logic ICs:Merged bipolar-CMOS architectures deliver speed without sacrificing energy efficiency in gaming console controllers and premium digital cameras. Taiwan-based foundries charge margin premiums for these mixed-signal process variants.
- Bipolar Logic ICs:High-speed switching characteristics sustain niche demand in legacy gaming peripherals and industrial-consumer crossover equipment.
- TTL Logic ICs:5V-compatible transistor-transistor logic persists in hobbyist electronics and educational equipment with minimal new design activity.
- ECL Logic ICs:Emitter-coupled logic addresses ultra-high-speed instrumentation and test equipment with negligible consumer volume.
Volume placements concentrate in CMOS Logic ICs; the faster expansion belongs to BiCMOS Logic ICs.
Technology:
Process maturity determines which technologies anchor high-volume production versus emerging programmable alternatives.
- Silicon Gate:Dominant manufacturing throughput leverages decades of process optimization across 200 mm and 300 mm wafer formats. Taiwan's Hsinchu cluster houses the densest concentration of silicon-gate logic capacity serving consumer brands.
- Programmable Array:Field-configurable logic arrays enable ODMs to consolidate multiple discrete functions into firmware-updatable devices. Wearable manufacturers in Shenzhen adopt these aggressively to reduce board area and inventory SKU counts.
- Thin Film Transistor:Specialized display-driver integration applications in Japan and South Korea leverage TFT processes for logic-display convergence.
- Resistor Transistor:Legacy process nodes sustain minimal production for replacement markets and obsolete equipment support.
- Bipolar Junction:Discrete bipolar processes serve high-current switching applications in power management companion circuits.
Silicon Gate captures the dominant production volume; Programmable Array is climbing the fastest as ODMs prioritize firmware flexibility.
Application:
End-use power budgets and form factor constraints create tiered demand profiles across consumer device categories.
- Smartphones:The largest discrete logic consumption category driven by 5G modem integration, camera subsystem buffering, and display interface level-shifting. South Korean and Chinese OEMs specify sub-1V logic families for flagship handset power management.
- Wearable Devices:Fitness trackers and smartwatches demand the most aggressive voltage scaling, with some designs operating at 0.8V thresholds. ROHM Semiconductor's ultra-low-voltage CMOS families anchor reference designs for Japanese wearable brands.
- Consumer Electronics:Broad category spanning smart home devices, audio equipment, and personal computing peripherals with moderate power constraints.
- Gaming Consoles:Stationary power sources enable higher-performance logic selections, though handheld variants follow wearable-like constraints.
- Digital Cameras:Declining standalone camera volumes compress logic demand, with remaining production concentrated in professional and vlogging segments.
Smartphone sockets absorb the highest absolute volumes; Wearable Devices are gaining share fastest as unit shipments accelerate.
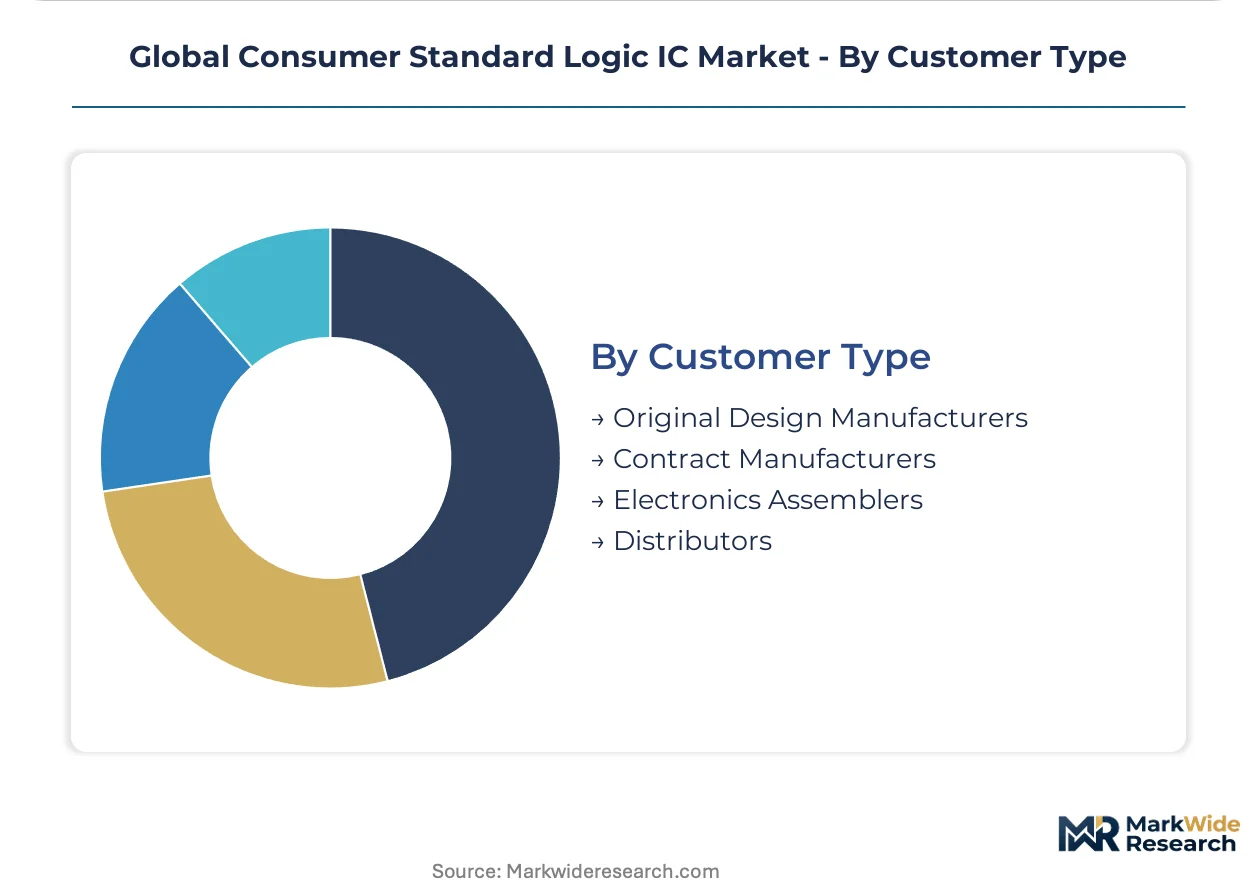
Customer Type:
Procurement channel structure shapes pricing power and supplier relationship dynamics across the value chain.
- Original Design Manufacturers:ODMs in Taiwan and China consolidate logic demand across multiple brand customers, achieving volume leverage in foundry negotiations. Foxconn and Pegatron direct-source mature-node logic wafers from Taiwan Semiconductor Manufacturing.
- Contract Manufacturers:Electronics manufacturing services providers manage component procurement for brand customers lacking direct foundry relationships.
- Electronics Assemblers:Final assembly operations in Vietnam and India source logic through regional distributors with limited direct foundry access.
- Distributors:Catalog and specialty distributors serve low-volume and prototype demand, though high-volume consumer brands increasingly bypass this channel.
Original Design Manufacturers command the deepest foundry access; Electronics Assemblers are expanding most quickly as production-linked incentives attract assembly to India.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park's tax incentives and infrastructure subsidies have concentrated foundry capacity for mature-node logic devices, drawing direct procurement teams from consumer electronics brands into Taiwan's northwest corridor.
South Korea
Samsung Electronics and LG Electronics drive premium smartphone logic demand through sub-1V CMOS specifications for 5G handset power management. The Ministry of Trade, Industry and Energy channels domestic production subsidies toward semiconductor resilience targets. Seoul-based procurement teams now negotiate multi-year wafer start agreements directly with Taiwan Semiconductor Manufacturing, bypassing traditional distributor channels.
Taiwan
Original design manufacturers in Taoyuan and Hsinchu consolidate logic demand across multiple brand customers, achieving volume leverage in foundry negotiations. The National Development Council prioritizes 200 mm and 300 mm wafer fab capacity expansion through its chip industry stimulus framework. Hsinchu Science Park houses the densest concentration of silicon-gate logic capacity serving global consumer brands.
China
Shenzhen wearable manufacturers adopt programmable array logic aggressively to reduce board area and inventory SKU counts. The Ministry of Industry and Information Technology enforces GB standards for electromagnetic emissions from logic-intensive consumer devices. Yangtze River Delta assembly operations source mature-node logic through regional distributors with limited direct foundry access.
Japan
Domestic wearable brands specify ROHM Semiconductor's ultra-low-voltage CMOS families for battery-constrained fitness trackers and smartwatches. METI production subsidies channel capital toward 200 mm wafer fab upgrades that standardize sourcing security expectations. Kyushu-based packaging engineers supply flip-chip expertise for advanced logic-display convergence applications.
United States
Smartphone OEMs headquartered in California accelerate refresh cycles for low-power logic ICs as mmWave variants proliferate in mid-tier devices. The FCC governs electromagnetic emissions specifications, pushing suppliers toward lower-noise switching requirements. Silicon Valley reference design houses anchor premium socket positions for analog-digital integration expertise.
Global Consumer Standard Logic IC Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure that concentrates premium positioning among analog-integrated suppliers while fragmenting commodity logic supply. Tier-one smartphone manufacturers now negotiate wafer starts directly with foundries, compressing distributor channels and reshaping procurement power. Three archetypes dominate: analog-digital integrators anchoring reference designs, automotive-qualified cross-servers capturing reliability premiums, and ultra-low-voltage specialists penetrating wearables. Dominant competitive moves include direct foundry contracting by high-volume brands and firmware-configurable logic substitution reducing discrete SKU proliferation.
Among diversified analog-semiconductor conglomerates, Texas Instruments Incorporated and Analog Devices Inc. exemplify the integration-driven archetype that anchors premium socket positions through mixed-signal expertise. NXP Semiconductors N.V. occupies a position bridging automotive-qualified process lines with consumer-grade reliability demands. ROHM Semiconductor represents the focused specialist tier targeting battery-constrained form factors through voltage-scaled CMOS families.
| Leading Market Players |
|---|
| Renesas Electronics Corporation |
| Toshiba Electronic Devices & Storage Corporation |
| Analog Devices Inc. |
| Broadcom Inc. |
| NXP Semiconductors N.V. |
| Texas Instruments Incorporated |
| STMicroelectronics N.V. |
| ROHM Semiconductor |
| MediaTek Inc. |
| Others |
Supply & Pricing Matrix
Epoxy molding compound costs cascade from petrochemical feedstock volatility through leadframe assembly operations into tiered logic IC pricing that separates AEC-Q100 qualified automotive-grade lines from standard consumer sockets. South Korean smartphone OEMs absorb premium wafer pricing for mature-node CMOS capacity locked under multi-year direct contracts with Taiwan-based foundries.
Pricing Analysis
Margin tightening in standard-grade CMOS logic traces to foundry capacity bottlenecks for 200 mm and 300 mm mature-node production. Three-tier pricing structure across automotive-qualified, industrial-grade, and consumer-grade certification levels separates reliability-premium sockets from commodity replacements. Cost-down pressure on discrete logic accelerates as programmable array configurations and integrated power-management subsystems displace standalone devices in space-constrained reference designs. Original design manufacturers exhibit highest price sensitivity due to consolidated multi-brand volume leverage, while automotive-crossover buyers accept reliability premiums for AEC-Q100 qualified lines.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale smartphone and wearable brand demand, compressing traditional distributor-mediated procurement for high-volume logic families. Foundry capacity concentrates in Taiwan's Hsinchu Science Park and South Korea's Seoul metropolitan cluster, with Kyushu-based Japanese packaging engineers supplying flip-chip expertise for advanced logic-display convergence. Silicon wafers, leadframe copper alloys, and epoxy molding compounds constitute critical upstream inputs tethered to energy-intensive production processes. Single-source vulnerability pervades mature-node logic supply as geopolitical restrictions on dual-use trade flows complicate cross-border component movements. Distribution runs through direct procurement teams stationed near foundry clusters, supplemented by regional distributors serving low-volume electronics assemblers in Vietnam and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity scarcity for mature-node logic devices props pricing power across the value chain, rewarding suppliers with secured wafer allocations and punishing buyers without multi-year supply agreements.
For Market Incumbents: Extend automotive-qualified process line utilization into consumer-grade reliability segments to capture crossover premiums as smartphone OEMs specify AEC-Q100 sources for flagship devices. Deepen backward integration into leadframe alloy supply through captive partnerships with Japanese and South Korean metal suppliers to buffer epoxy molding compound cost volatility. Defend against programmable logic substitution by embedding non-volatile memory configurations that eliminate external EEPROM requirements in wearable reference designs. For New Entrants and Emerging Players: Enter via India's production-linked incentive schemes for electronics manufacturing, where localized assembly operations for domestic smartphone brands create captive logic IC consumption without direct foundry access requirements. Target firmware-configurable programmable array segments where Shenzhen wearable ODMs prioritize board area reduction over discrete logic cost minimization. Pursue foundry-less fabless models leveraging Taiwan-based pure-play foundry capacity for initial wafer starts. For Investors and Strategic Acquirers: Direct procurement contract announcements between consumer electronics brands and Taiwan-based foundries are the leading indicator that channel compression is accelerating and distributor-mediated purchasing is structurally declining. Position acquisition screening around ultra-low-voltage CMOS specialists with anchored design wins in Japanese wearable brands and voltage-scaled process libraries. Monitor EU REACH substance restriction enforcement timelines as inflection signals for packaging substrate material transition costs.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Wafer Supply Agreement | Direct foundry contracting by Samsung and LG Electronics locks mature-node CMOS capacity against competitor access. |
| Automotive-Grade Process Crossover | AEC-Q100 qualified lines from NXP capture reliability premiums in premium-tier consumer electronics reference designs. |
| Firmware-Configurable Logic Integration | Programmable array adoption by Shenzhen ODMs reduces SKU proliferation while reclaiming board area for battery expansion. |
| Packaging Substrate Material Transition | EU REACH compliance investments by substrate suppliers standardize lead-free and halogen-free compound transitions. |
| Geographic Supplier Diversification | METI-backed Japanese 200 mm fab upgrades qualify as secondary sources for South Korean smartphone OEM procurement teams. |
Research Methodology
Multi-period observation of foundry capacity utilization rates, lead time fluctuations, and direct procurement contract announcements anchored the trend analysis, supplemented by interviews with Taiwan-based ODM procurement directors, South Korean smartphone platform engineers, Japanese wearable brand supply chain managers, and Hsinchu cluster packaging technologists. Secondary validation drew from Taiwan Semiconductor Manufacturing capacity disclosures, SEMI silicon wafer shipment statistics, EU ECHA substance restriction updates, and Japan METI production subsidy filings. Bottom-up logic IC unit demand estimates by smartphone, wearable, and gaming console application triangulated against top-down semiconductor consumption projections across the analysis window.
Segment-weighting approaches modeled CMOS versus BiCMOS architecture splits, silicon-gate versus programmable array technology trajectories, and ODM versus distributor procurement channel shares throughout the forecast period. CAGRs derived from regression analysis of historical mature-node logic demand against 5G handset refresh cycle compression rates and wearables unit shipment acceleration. Industry-specific forecast inputs included foundry capacity expansion timelines for 200 mm and 300 mm wafer formats and EU regulatory enforcement calendars for packaging material compliance.
Forecast precision tightens around the base case; tail outcomes carry wider variance under dual-use export control expansion scenarios or epoxy molding compound supply disruptions. Projections reflect assumptions regarding sustained South Korean and Taiwanese foundry concentration, India electronics manufacturing incentive effectiveness, and programmable logic substitution rates in space-constrained designs. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Digital Potentiometer IC Market
IC (Integrated Circuits)
Embedded Universal Integrated Circuit Card (eUICC) Market
IC (Integrated Circuits)
Global General Purpose Analog IC Market
IC (Integrated Circuits)
Americas Logic IC Market
IC (Integrated Circuits)
Consumer Special Purpose Logic IC Market
IC (Integrated Circuits)
Japan Analog IC Market
IC (Integrated Circuits)
Global Photonic Integrated Circuits (PIC) Market
IC (Integrated Circuits)
PFC Control IC Market
IC (Integrated Circuits)
Europe Analog IC Market
IC (Integrated Circuits)
Memory Integrated Circuits (IC) Market
IC (Integrated Circuits)
Rugged IC Market
IC (Integrated Circuits)
Automotive IC Market
IC (Integrated Circuits)
Global SRAM and ROM Design IP Market
IC (Integrated Circuits)
Global 3D Ics Market
IC (Integrated Circuits)
Readout Integrated Circuits (ROIC) Market
IC (Integrated Circuits)
Global Application Specific Automotive Analog IC Market