
 Holmium Sputtering Target Market | 2026-2036
Holmium Sputtering Target Market Size, Share, and Industry Trends Forecast 2026-2036
Holmium Sputtering Target Market Insights
Specialty distributor networks for rare-earth sputtering materials is fragmenting as direct procurement from refiners gains traction among large semiconductor fabs. American Elements leverages its integrated rare-earth refining and target fabrication capabilities to secure long-term supply agreements. Plansee sustains its position through captive tungsten-rhenium bonding expertise applied to holmium target assemblies. Materion competes by extending its thin-film materials portfolio into high-purity rare-earth compounds for magnetron sputtering systems.
A holmium sputtering target is a precision-machined disc or plate of metallic holmium, typically refined to 99.9% purity or higher, used as the cathode source in physical vapor deposition chambers to deposit thin films of holmium or holmium-containing alloys onto substrates. The material serves primarily in semiconductor fabrication for gate dielectric doping, magnetic thin films, and specialized optical coating stacks where its unique magnetic and spectral properties prove critical. Conventional targets still occupy the largest revenue share due to established tool compatibility, yet bonded targets are capturing faster growth as thermal management demands intensify in high-power sputtering processes. Semiconductor manufacturing anchors the dominant end-use channel, while optical coatings applications in aerospace and defense sensors represent a concentrated margin pool where custom-grade material certifications command premium positioning.
REACH registration requirements in Europe and RoHS substance restrictions shape material traceability obligations across the holmium target supply chain, with ECHA compliance costs filtering down to end-user pricing. The EPA and OSHA frameworks in the United States impose occupational exposure limits for rare-earth metal powders during target machining and recycling operations. FDA oversight applies where holmium coatings enter medical device components, particularly in targeted radiotherapy equipment. Stakeholders must monitor rare-earth export licensing shifts from Chinese regulators and evaluate dual-sourcing strategies for refined holmium feedstock before supply commitments lock in.
Market Dynamics
Semiconductor fabs are consolidating holmium target procurement around captive refining partnerships as Chinese export licensing tightens rare-earth feedstock availability. This supply-side concentration is forcing end-users to secure multi-year offtake agreements before capacity commitments lock in.
Growth Catalysts
- Advanced node expansion:Logic foundries in Taiwan and South Korea are ramping 3nm and 2nm production lines, each requiring holmium-doped gate stacks for threshold voltage control.
- REACH substance registration:ECHA compliance deadlines are accelerating purity certification investments among European coating houses, filtering demand toward qualified suppliers.
- Magnetic thin-film R&D:Data center storage manufacturers are qualifying holmium-terbium-iron alloys for next-generation heat-assisted magnetic recording media.
Market Restraints
- Feedstock concentration:Over seventy percent of refined holmium originates from Chinese separation facilities, creating single-source vulnerability for non-integrated target fabricators.
- Thermal bonding limitations:Conventional indium bonding fails above 150°C, restricting power density in high-rate sputtering applications without costly silver-epoxy alternatives.
- RoHS substance scrutiny:Ongoing ECHA reviews of rare-earth oxide classifications threaten to reclassify machining byproducts as hazardous waste, elevating disposal costs.
Strategic Opportunities
- India PLI scheme:Domestic semiconductor fabrication incentives are attracting target suppliers to establish local machining and bonding facilities near Gujarat and Tamil Nadu fab clusters.
- Medical device radiotherapy:Holmium-166 microspheres for liver cancer treatment are creating parallel demand for thin-film coating deposition on biocompatible substrates.
- Direct refiner contracting:Large fabs are bypassing specialty distributors to negotiate long-term supply agreements with integrated rare-earth processors, compressing channel margins.
Industry Challenges
- Rare-earth metallurgy expertise:Target fabrication requires specialized knowledge of pyrophoric powder handling and hot isostatic pressing that has concentrated among retiring workforce cohorts.
- Dual-source qualification timelines:Semiconductor fabs demand twelve-to-eighteen-month validation cycles for alternative holmium suppliers, delaying supply chain diversification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Holmium Sputtering Target Market |
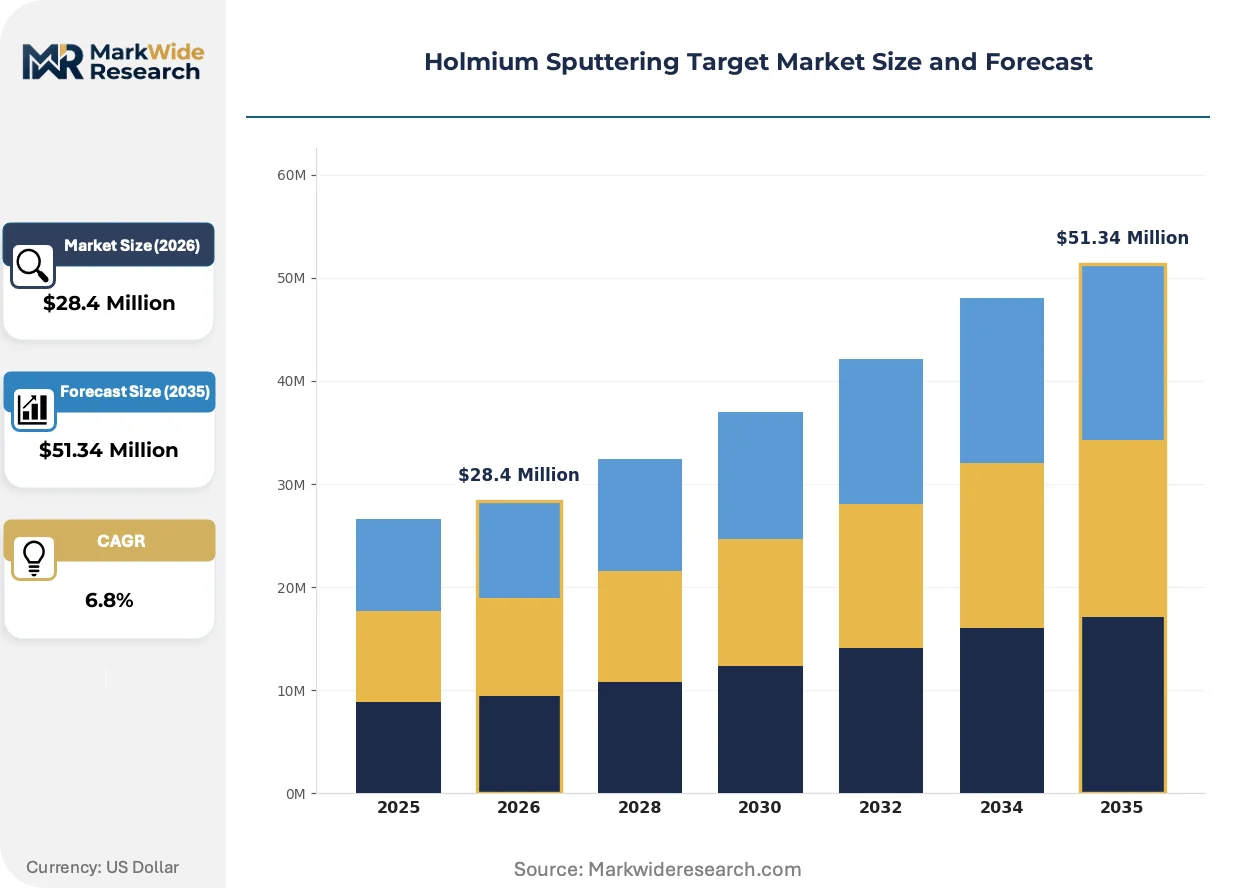
| Market Size in 2026 | $28.4 Million |
| Market Size in 2035 | $51.34 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Targets, Bonded Targets, Circular Targets, Rectangular Targets End User: Semiconductor Manufacturing, Display Technology, Optoelectronics, Coating Services Application: Thin Film Deposition, Optical Coatings, Hard Coatings, Surface Modification Material Grade: High Purity, Low Purity, Standard Grade, Custom Grade |
| Companies Covered | American Elements, Kurt J. Lesker Company, Molybdenum Products, Inc., Plansee, Materion, H.C. Starck, Stanford Advanced Materials, Mitsubishi Materials Corporation, Linde plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Holmium Sputtering Target Market Trends and Innovations
Physical vapor deposition equipment is evolving toward higher power density and real-time process control, reshaping target design specifications and supplier technical service models. Three developments are compressing competitive timelines across the value chain.
Rotatable cylindrical holmium targets are digitizing sputter utilization efficiency through continuous surface regeneration and automated thickness monitoring. Memory manufacturers in Japan are adopting these architectures for magnetic media deposition, reducing target changeout frequency by half while compressing chamber downtime. This technology is digitizing maintenance scheduling and enabling predictive replacement algorithms.
ECHA's expanding REACH candidate list for rare-earth compounds is tightening substance data sheet obligations across European coating supply chains. Fabricators must now document full lifecycle toxicity profiles from mining through end-of-life recycling, elevating compliance costs for small-batch optical coating houses. German aerospace sensor manufacturers are responding by consolidating supplier panels around pre-certified integrated refiners.
Consolidated procurement consortiums among Taiwanese and South Korean foundries are displacing spot-market purchasing for critical rare-earth materials. These buying cooperatives negotiate volume commitments across multiple fabs, extracting price transparency and technical service guarantees previously reserved for single large accounts. The shift is most visible in Hsinchu and Yongin clusters where three-fab joint sourcing agreements now cover holmium and terbium targets.
Holmium Sputtering Target Market Segmentation
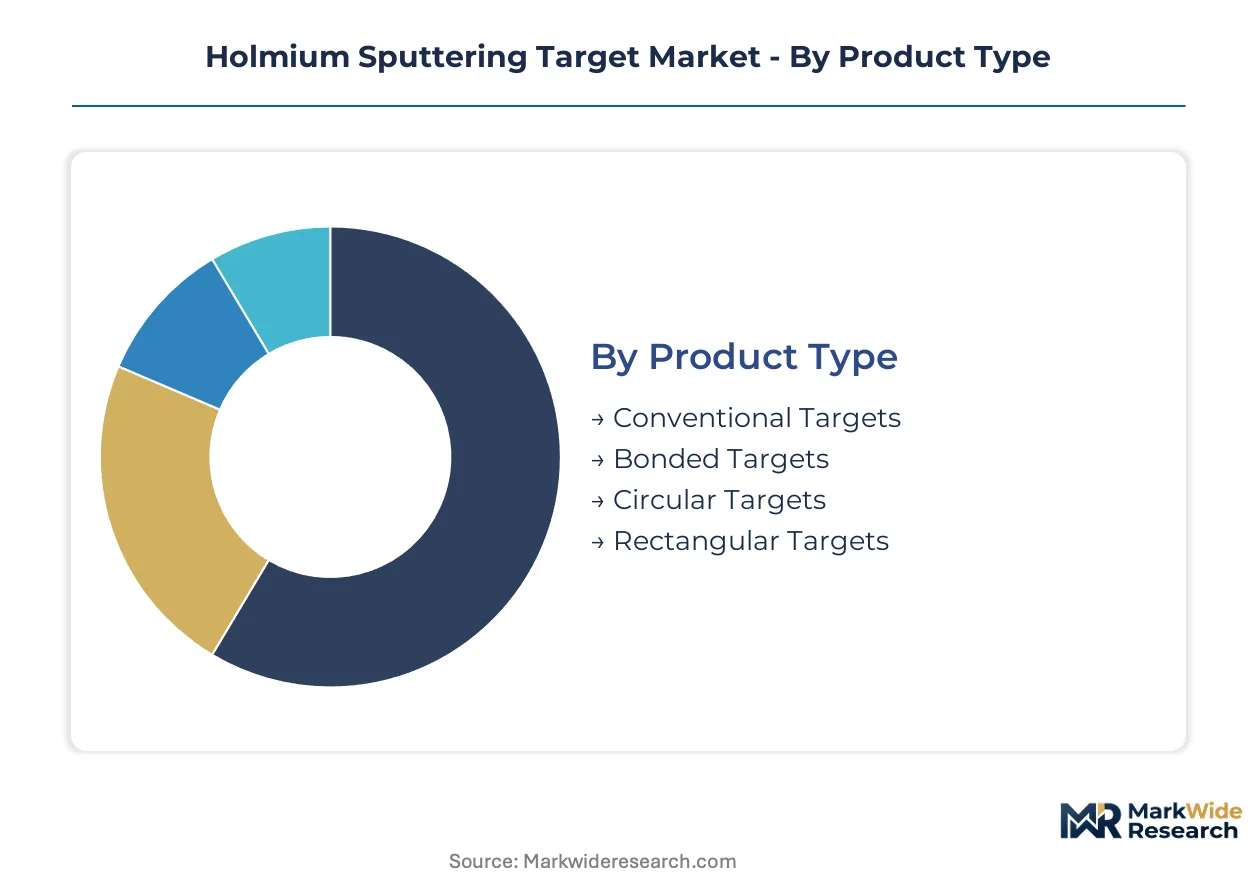
Holmium sputtering target segmentation reflects divergent technical service requirements across fabrication workflows. Bonded target assemblies demand intensive field engineering support for thermal interface optimization, while conventional disc formats rely on standardized machining tolerances.
Product Type:
After-sales service intensity varies sharply across product architectures, with bonded assemblies requiring dedicated thermal management consulting and conventional formats depending on routine dimensional recertification.
- Conventional Targets:Monolithic holmium discs machined to tight planar tolerances serve legacy magnetron systems where indium bonding suffices. Taiwan-based foundries in Hsinchu and Tainan dominate procurement volumes as 3nm node expansion accelerates gate stack doping requirements. REACH substance registration deadlines are compressing supplier qualification timelines for European coating houses.
- Bonded Targets:Multi-layer assemblies integrating holmium sputter surfaces with copper or molybdenum backing plates enable elevated power densities. South Korean memory manufacturers in Yongin and Icheon are adopting silver-epoxy thermal interfaces for high-rate deposition chambers. Technical service contracts now cover predictive bonding failure monitoring.
- Circular Targets:Rotationally symmetric geometries optimize magnetic field uniformity in circular magnetron configurations. Japanese optical coating specialists in Osaka prefecture specify these for precision interference filter production.
- Rectangular Targets:Linear geometries suit in-line sputtering systems for architectural glass and flat-panel display manufacturing. German aerospace sensor fabricators source custom rectangular formats for multi-layer thermal barrier coatings.
Conventional targets hold the largest share; momentum sits with bonded targets as power density requirements climb.
End User:
Cost tier stratification separates capital-intensive semiconductor fabs from price-sensitive coating service bureaus, with purity certification premiums concentrating in medical device and aerospace channels.
- Semiconductor Manufacturing:Logic and memory fabs demand 99.9%+ purity with full lot traceability from mine to target. Samsung and TSMC procurement consortiums negotiate multi-year offtake agreements covering holmium and terbium feedstocks. ECHA compliance documentation now extends to machining byproduct disposal chains.
- Display Technology:OLED and quantum-dot panel manufacturers deposit holmium-doped transparent conductive layers. Chinese display fabs in Hefei and Chengdu are expanding rotatable target adoption for continuous production lines.
- Optoelectronics:Laser and photonic device manufacturers specify tight compositional tolerances for spectral filtering applications. Japanese telecom component suppliers in Yokohama cluster represent concentrated demand for custom-grade material certifications.
- Coating Services:Job-shop optical coaters purchase standard-grade targets on spot-market terms with minimal technical support requirements. Indian coating houses near Pune and Bengaluru are consolidating procurement through distributor networks.
Semiconductor manufacturing commands the highest absolute spending; coating services are expanding most quickly as industrial outsourcing accelerates.
Application:
Volume concentration in thin film deposition contrasts with margin capture in specialized optical coating stacks where custom-grade certifications command substantial premiums.
- Thin Film Deposition:Physical vapor deposition for magnetic storage media and semiconductor gate stacks consumes the majority of holmium target tonnage. Heat-assisted magnetic recording development at Japanese HDD manufacturers is qualifying holmium-terbium-iron alloy compositions.
- Optical Coatings:Precision interference filters for aerospace sensors and medical imaging demand exacting thickness uniformity. German Fraunhofer Institute research programs are advancing multilayer designs incorporating holmium oxide layers.
- Hard Coatings:Wear-resistant surface treatments for cutting tools and mechanical components utilize holmium-doped ceramic matrices. South Korean automotive component suppliers are piloting these coatings for electric drivetrain parts.
- Surface Modification:Ion implantation and plasma treatment applications modify substrate properties without bulk deposition. Taiwanese semiconductor equipment manufacturers integrate these processes into advanced packaging workflows.
Thin film deposition dominates volume; optical coatings generate the steepest expansion trajectory as defense and medical sensor demand intensifies.
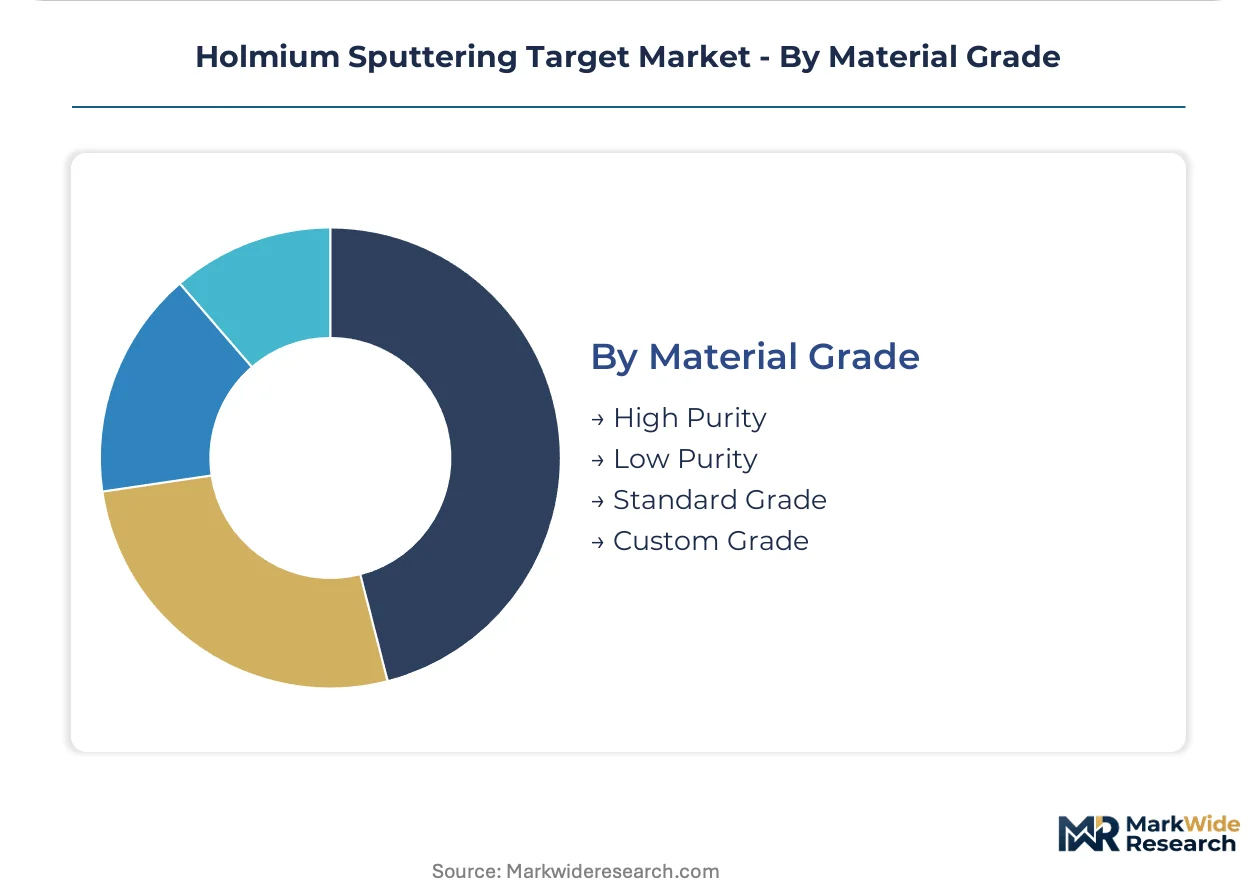
Material Grade:
Supply concentration in high-purity refining creates sourcing bottlenecks, while standard-grade availability through secondary distributors supports price-sensitive coating applications.
- High Purity:99.95%+ holmium refined via solvent extraction and ion exchange commands premium positioning. Chinese export licensing restrictions on rare-earth separation outputs are forcing Japanese magnet manufacturers to qualify Australian and Canadian alternative feedstocks.
- Custom Grade:Client-specified compositions with controlled oxygen and rare-earth co-impurity profiles serve aerospace and medical device certifications. FDA device master file submissions now incorporate target material toxicity profiles.
- Standard Grade:99.5-99.9% purity meets general industrial coating requirements with reduced documentation burdens. Indian domestic refiners are expanding standard-grade output under PLI scheme incentives.
- Low Purity:Technical-grade material for research and development applications where absolute purity is secondary to cost accessibility. University and national laboratory procurement in the United States flows through American Elements and Materion distributor channels.
High purity commands the largest share; custom grade is gaining share fastest as aerospace and medical certification requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT export licensing protocols on rare-earth separation outputs are reshaping procurement patterns across East Asian fabrication clusters. Semiconductor fabs in Taiwan, South Korea, and Japan are accelerating dual-source qualification timelines for refined holmium feedstock.
Taiwan
TSMC and United Microelectronics are expanding 3nm production lines requiring holmium-doped gate dielectrics for threshold voltage control. The island's National Development Council subsidizes critical materials stockpiling under its semiconductor resilience initiative. Hsinchu Science Park anchors target consumption as procurement consortiums negotiate multi-year offtake agreements with integrated rare-earth processors.
South Korea
Samsung Electronics and SK Hynix are qualifying holmium-terbium-iron alloys for heat-assisted magnetic recording media in next-generation data storage. MFDS oversight extends to thin-film deposition equipment used in medical device component manufacturing. Yongin and Icheon clusters dominate bonded target adoption for high-power sputtering chambers with silver-epoxy thermal interfaces.
Japan
Tokyo Electron and Shin-Etsu Chemical are advancing rotatable cylindrical target architectures for continuous magnetic media deposition. METI's critical minerals strategy prioritizes Australian and Canadian alternative feedstock qualification to reduce Chinese import dependency. Osaka prefecture's optical coating specialists specify circular geometries for precision interference filter production.
United States
Intel and GlobalFoundries are reshoring advanced packaging capacity under CHIPS Act incentives, driving demand for high-purity rare-earth sputtering materials. EPA and OSHA frameworks impose occupational exposure limits for pyrophoric powder handling during target machining. Arizona and New Mexico fab clusters are consolidating supplier panels around pre-certified integrated refiners.
Germany
Fraunhofer Institute research programs are advancing multilayer optical designs incorporating holmium oxide layers for aerospace sensor applications. REACH substance registration deadlines and ECHA compliance documentation requirements are filtering demand toward qualified European suppliers. Bavaria's coating houses near Munich are consolidating procurement through distributor networks with full lifecycle toxicity profiles.
Holmium Sputtering Target Market Competitive Landscape
Integrated rare-earth refiners and specialized target fabricators split the market along vertical capability lines. The vendor base concentrates among three strategic archetypes: captive refiners with in-house sputter surface production, independent fabricators sourcing feedstock through long-term contracts, and diversified materials conglomerates extending thin-film portfolios. Competitive positioning hardens around multi-year offtake agreements and predictive technical service contracts for bonded assembly thermal management.
Among North American materials suppliers, American Elements exemplifies the integrated refiner archetype through its rare-earth separation and precision machining capabilities. Materion occupies a position within the diversified conglomerate tier, leveraging thin-film materials expertise across magnetron sputtering applications. Plansee anchors the European fabricator segment through its tungsten-rhenium bonding heritage applied to holmium target assemblies. These three entities represent distinct strategic postures without implying specific market share or operational claims.
| Leading Market Players |
|---|
| American Elements |
| Kurt J. Lesker Company |
| Molybdenum Products, Inc. |
| Plansee |
| Materion |
| H.C. Starck |
| Stanford Advanced Materials |
| Mitsubishi Materials Corporation |
| Linde plc |
| Others |
Pricing and Supply Chain Analysis
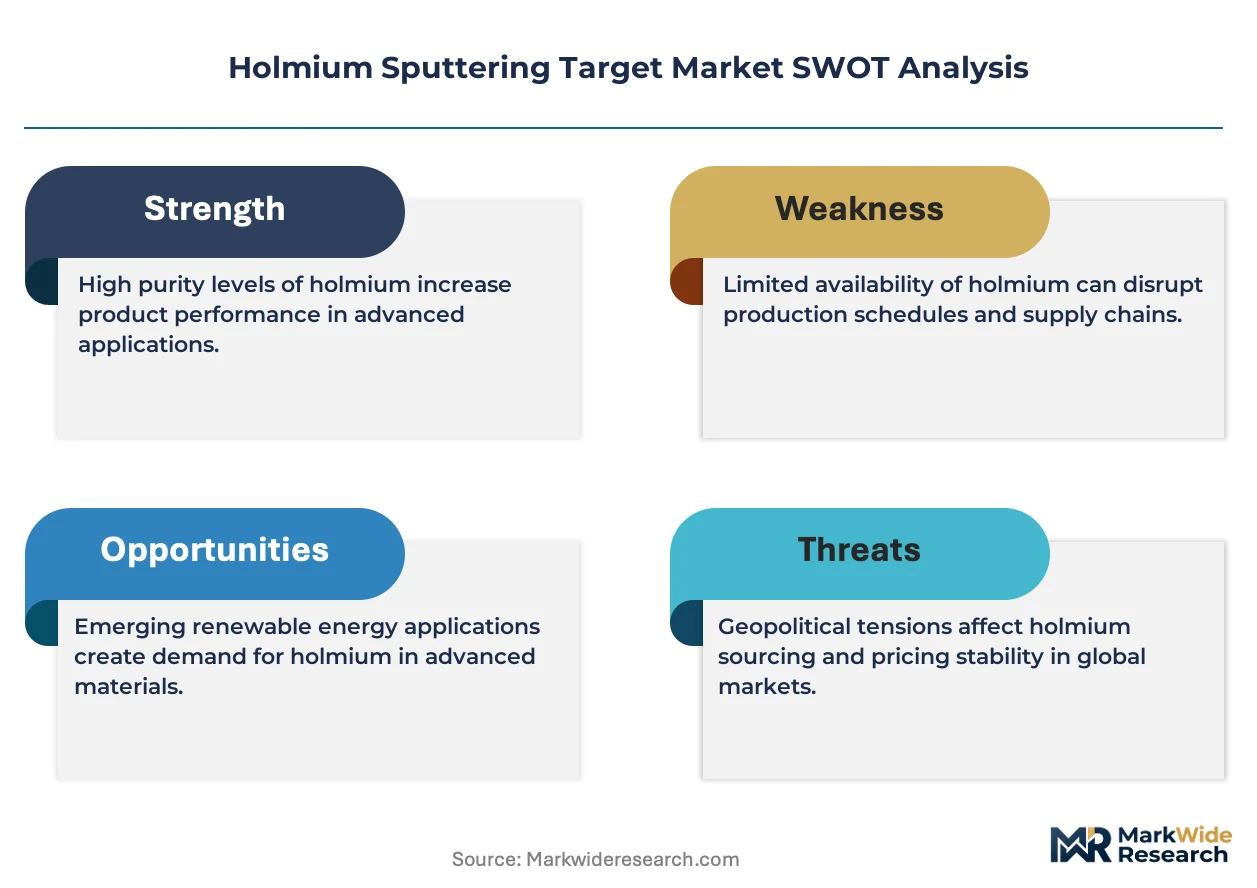
Chinese export licensing restrictions on rare-earth separation outputs determine both pricing tier spreads and supply chain shape by forcing semiconductor fabs into long-term offtake agreements before capacity commitments lock in. This regulatory chokepoint compresses margins for non-integrated target fabricators while elevating premiums for qualified suppliers with captive refining capabilities.
Pricing Analysis
Configured-to-order pricing for bonded target assemblies with silver-epoxy thermal interfaces commands substantial premiums over standard conventional disc formats. Price differentiation rests on certification grade and after-sales service intensity, with REACH-compliant documentation and predictive bonding failure monitoring bundled into premium tiers. Cost compression in standard-grade channels is intensifying because Indian domestic refiners are expanding output under PLI scheme incentives. Coating service bureaus purchasing spot-market material exhibit highest price sensitivity, while semiconductor fabs with multi-year consortium agreements demonstrate lowest sensitivity due to supply security prioritization.
Supply Chain Analysis
Tariff exposure between Chinese separation facilities and East Asian fabrication clusters dominates supply chain risk assessment for refined holmium feedstock. Geographic supply concentrates in China, Australia, and Canada, with downstream target fabrication anchored in Taiwan, South Korea, and Japan. Raw material dependencies center on rare-earth concentrate, solvent extraction reagents, and copper-molybdenum backing plates. Distribution runs through direct refiner contracting for large fabs, compressing specialty distributor margins as procurement consortiums displace spot-market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across the holmium sputtering target market as advanced node expansion and medical device radiotherapy applications create specialized demand niches requiring distinct certification and technical service capabilities.
For Market Incumbents: Insulate market position through backward integration into rare-earth refining and captive bonding technology development. American Elements and Plansee demonstrate the defensive value of controlling pyrophoric powder handling and hot isostatic pressing capabilities in-house. Threats from emerging Indian refiners under PLI incentives warrant preemptive capacity positioning near Gujarat and Tamil Nadu fab clusters. Certification investment in FDA device master file submissions for medical device channels represents a critical margin defense lever. For New Entrants and Emerging Players: Build out technical service capabilities for bonded target thermal management consulting as the most penetrable white-space segment. Indian domestic semiconductor fabrication incentives create geographic entry opportunity with localized machining and bonding facilities. Medical device radiotherapy applications for holmium-166 microspheres offer specialized certification pathways with reduced incumbent saturation. Go-to-market positioning should emphasize predictive maintenance algorithms and field engineering support contracts rather than commodity target supply. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated rare-earth processors with precision machining capabilities over pure-play distributors. Long-term viability across a 5-10 year window rests on securing dual-source feedstock qualification and ECHA pre-certification for European coating channels. Acquisition targets should demonstrate captive rare-earth separation or established bonding expertise with semiconductor fab validation cycles completed. The signal to watch is MIIT export licensing protocol shifts that would accelerate or delay Chinese supply diversification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Refining | Captive holmium separation capacity insulates against Chinese export licensing volatility and secures feedstock priority. |
| Predictive Bonding Failure Monitoring | Technical service contracts for thermal interface optimization differentiate bonded target suppliers in high-power sputtering applications. |
| Dual-Source Feedstock Qualification | Australian and Canadian alternative refiner validation reduces single-source dependency for Japanese magnet manufacturers. |
| Medical Device Certification Investment | FDA device master file submissions for holmium-166 microsphere coatings open premium-margin radiotherapy channels. |
| Local Machining Facility Establishment | India PLI scheme incentives support Gujarat and Tamil Nadu proximity for domestic semiconductor fab supply. |
Research Methodology
A spread of perspectives from semiconductor procurement directors, rare-earth refinery operations managers, magnetron sputtering equipment engineers, and optical coating house technical leads converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC filings of diversified materials conglomerates, ECHA REACH registration databases, MIIT export licensing disclosures, and customs trade data for rare-earth concentrate movements. Bottom-up target consumption estimates from individual fab expansion announcements were triangulated against top-down rare-earth separation capacity assessments across the analysis window.
Demand-supply-balance framing anchored the forecast framework, with segmentation dimensions spanning product architecture, material grade tier, end-use industry, and regional fabrication cluster. CAGRs were derived from installed base growth for physical vapor deposition equipment, node migration timelines for logic and memory fabs, and qualification velocity for alternative feedstock sources. Industry-specific inputs incorporated heat-assisted magnetic recording development schedules at Japanese HDD manufacturers and ECHA substance review timelines for rare-earth oxide classifications.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Australian rare-earth developers or accelerated Indian PLI scheme implementation would shift outcomes. Forecasts reflect assumptions regarding MIIT licensing continuity, REACH registration deadline adherence, and semiconductor fab utilization rates. Material shifts in Chinese rare-earth export policy or ECHA hazardous waste reclassification for machining byproducts would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
North America Atomic Layer Deposition Market
Semiconductor Fabrication
Additive Manufacturing in Semiconductor Market
Semiconductor Fabrication
Semiconductor Etching Cleaner Market
Semiconductor Fabrication
Physical Vapor Deposition (PVD) Market
Semiconductor Fabrication
Global Atomic Layer Deposition Market
Semiconductor Fabrication
Sic Wafer Reclaim Services Market
Semiconductor Fabrication
Global Dry Etching Machine Market
Semiconductor Fabrication
Global Dielectric Etchers Market
Semiconductor Fabrication
Mask Alignment Lithography Market
Semiconductor Fabrication
Deep Reactive Ion Etching (DRIE) Etcher Market
Semiconductor Fabrication
Global Micromachining Market
Semiconductor Fabrication
Semiconductor Logistics Market
Semiconductor Fabrication
Semiconductor Photoresist Polymer Market
Semiconductor Fabrication
Semiconductor Foundry Market
Semiconductor Fabrication
Solar Grade Wafer Market
Semiconductor Fabrication
Etchant for FPD Market