
 Wafer Grinding Machine Market | 2026-2036
Wafer Grinding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Wafer Grinding Machine Market Insights
EU F-Gas Regulation is expanding compliance obligations for coolant systems used in precision grinding equipment, compelling equipment upgrades across European semiconductor fabs. DISCO Corporation leverages its dominance in dicing and grinding system integration across Asian manufacturing corridors. Tokyo Seimitsu Co., Ltd. sustains R&D intensity in ultraprecision metrology-linked grinding platforms. Okamoto Semiconductor Equipment Division anchors geographic presence through localized service networks in Japan and Southeast Asia.
Wafer grinding machines are precision material-removal systems that thin silicon, silicon carbide, or gallium nitride wafers to sub-100-micron thicknesses using diamond-abrasive wheels under controlled coolant delivery, enabling subsequent lithography and packaging steps in semiconductor fabrication. Single-sided grinders dominate current installed base volumes due to their compatibility with existing fab automation, while double-sided grinders capture expanding margin pools as silicon carbide substrate demand rises for power electronics. Wet grinding technology leads technology segment adoption because of superior thermal management during aggressive material removal, though dry grinding platforms are gaining traction in water-stressed manufacturing locations.
FDA oversight of semiconductor equipment in medical device supply chains, EPA emissions standards for coolant fluid handling, and China's MIIT energy-efficiency certification for industrial equipment collectively shape product design requirements and market access conditions for grinding system vendors. ISO 14644 cleanroom compatibility standards and SEMI safety guidelines further constrain equipment architecture decisions. Stakeholders must monitor evolving substrate material transitions from silicon to wide-bandgap compounds and assess how regional carbon-border adjustments reshape equipment sourcing economics.
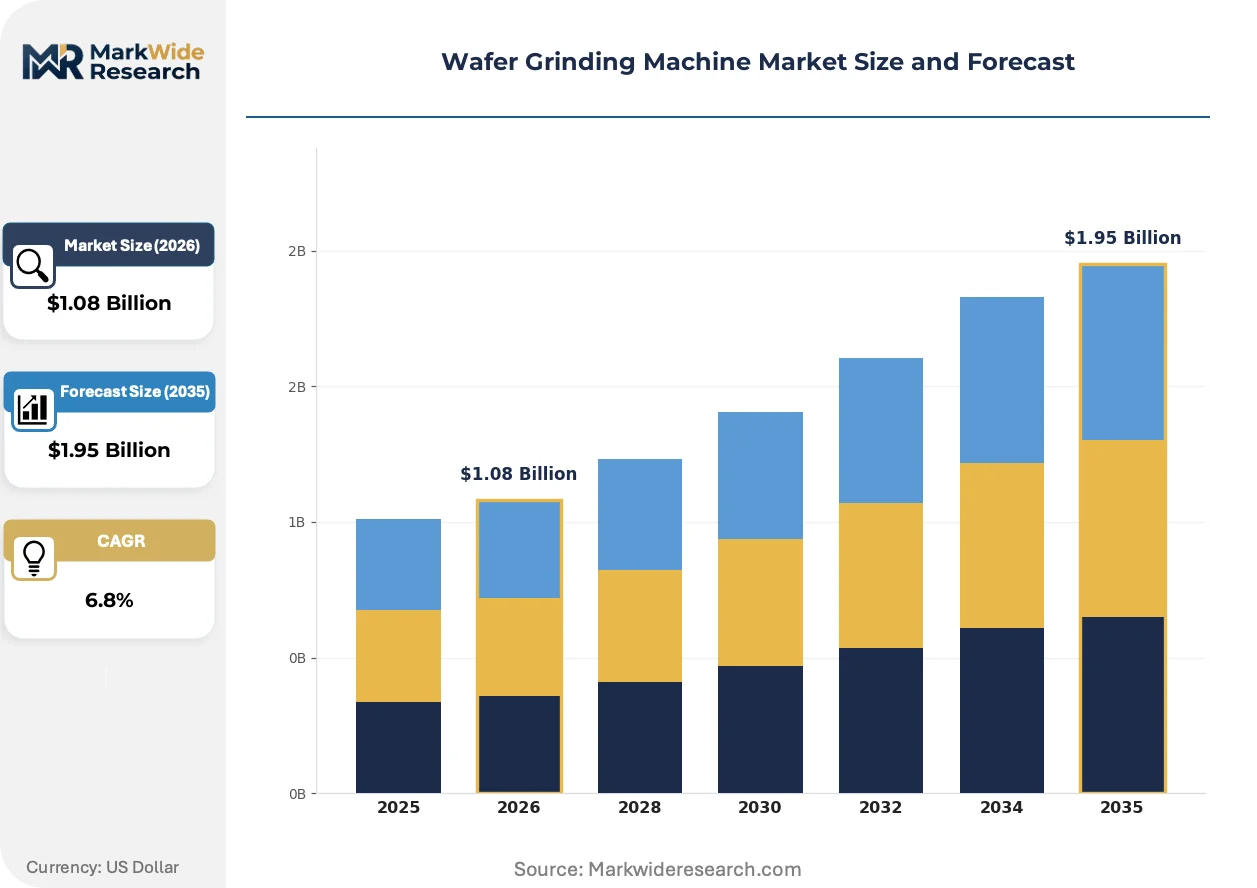
Market Dynamics
Backside thinning capacity expansion for advanced packaging nodes is compressing equipment replacement cycles as fabs prioritize sub-50-micron precision grinding for heterogeneous integration architectures.
Growth Catalysts
- EU F-Gas Regulation:Mandates for low-global-warming-potential coolants in precision grinding systems are accelerating equipment refresh cycles across German and French semiconductor fabrication facilities.
- Silicon carbide substrate demand:Power electronics manufacturers in electric vehicle supply chains are scaling double-sided grinder procurement for 150mm and 200mm SiC wafer processing.
- Hsinchu Science Park cluster:Taiwan's concentrated advanced packaging ecosystem generates sustained demand for integrated dicing-grinding system upgrades.
Market Restraints
- Synthetic diamond abrasive supply:Concentration of high-purity diamond wheel production in specific Asian supply basins creates input cost volatility and lead time uncertainty.
- Technical limitation:Achieving sub-10-micron total thickness variation on gallium nitride wafers remains constrained by thermal damage propagation during aggressive material removal.
- Regulatory friction:China's MIIT energy-efficiency certification requirements for imported industrial equipment extend qualification timelines for non-domestic grinding system vendors.
Strategic Opportunities
- India's semiconductor PLI scheme:Emerging domestic fabrication incentives create first-mover positioning for grinding equipment vendors establishing localized service infrastructure.
- Regulatory tailwind:South Korea's K-Semiconductor Belt initiative subsidizes precision equipment procurement for materials innovation clusters in Pyeongtaek and Yongin.
- Technology convergence:Integration of in-line metrology with grinding platforms enables real-time thickness feedback, reducing downstream yield loss in advanced packaging flows.
Industry Challenges
- Mechatronics engineering scarcity:Specialized talent combining precision mechanical design with closed-loop control systems remains concentrated in established Japanese and German industrial centers.
- Cleanroom certification timelines:ISO 14644 Class 1 compatibility validation for new grinding platforms extends customer qualification periods by six to twelve months.
- Legacy system integration:Retrofitting wet grinding coolant recovery systems into existing fab infrastructure requires substantial piping and environmental control modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wafer Grinding Machine Market |
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $1.95 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided Grinders, Double-Sided Grinders, Belt Grinders, Rotary Grinders, Precision Grinders Technology: Wet Grinding, Dry Grinding, Ultraprecision Grinding, Cryogenic Grinding, Chemical Mechanical Planarization Application: Semiconductor Fabrication, Microelectromechanical Systems, LED Manufacturing, Solar Cell Production, Telecommunications Components End User: Fabless Companies, Equipment Manufacturers, OEMs, Contract Manufacturers, Substrate Suppliers |
| Companies Covered | DISCO Corporation, Tokyo Seimitsu Co., Ltd., Okamoto Semiconductor Equipment Division, ACCRETECH, Komatsu NTC, Revasum, Lapmaster Wolters GmbH, G&N Genauigkeits Maschinenbau Nürnberg GmbH, Strasbaugh, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wafer Grinding Machine Market Trends and Innovations
Equipment architecture is pivoting toward closed-loop process control systems that integrate real-time thickness metrology with adaptive grinding parameters, compressing variation windows for advanced node packaging.
Dry grinding platforms with electrostatic chuck wafer handling are overtaking conventional wet systems in water-stressed manufacturing locations. Semiconductor fabs in Arizona and Singapore are piloting these configurations to eliminate coolant wastewater treatment infrastructure. The shift is overtaking established wet process dominance in regions where municipal water availability constrains fab expansion permits.
China's dual carbon goals and MIIT energy-efficiency certification are mandating regenerative spindle drives and smart power management in new equipment deployments. Grinding system vendors must redesign thermal management architectures to qualify for domestic procurement preferences. Power electronics substrate manufacturers in Jiangsu and Shaanxi provinces are prioritizing certified equipment to secure state-backed capacity expansion subsidies.
Consolidated procurement through semiconductor equipment lessors is displacing direct capital purchases among mid-scale packaging houses. Leasing structures bundle grinding systems with consumables supply and predictive maintenance analytics, transferring obsolescence risk from fab operators to financing entities. This model is gaining traction among outsourced semiconductor assembly and test providers in Malaysia and Vietnam seeking to preserve balance sheet flexibility.
Wafer Grinding Machine Market Segmentation
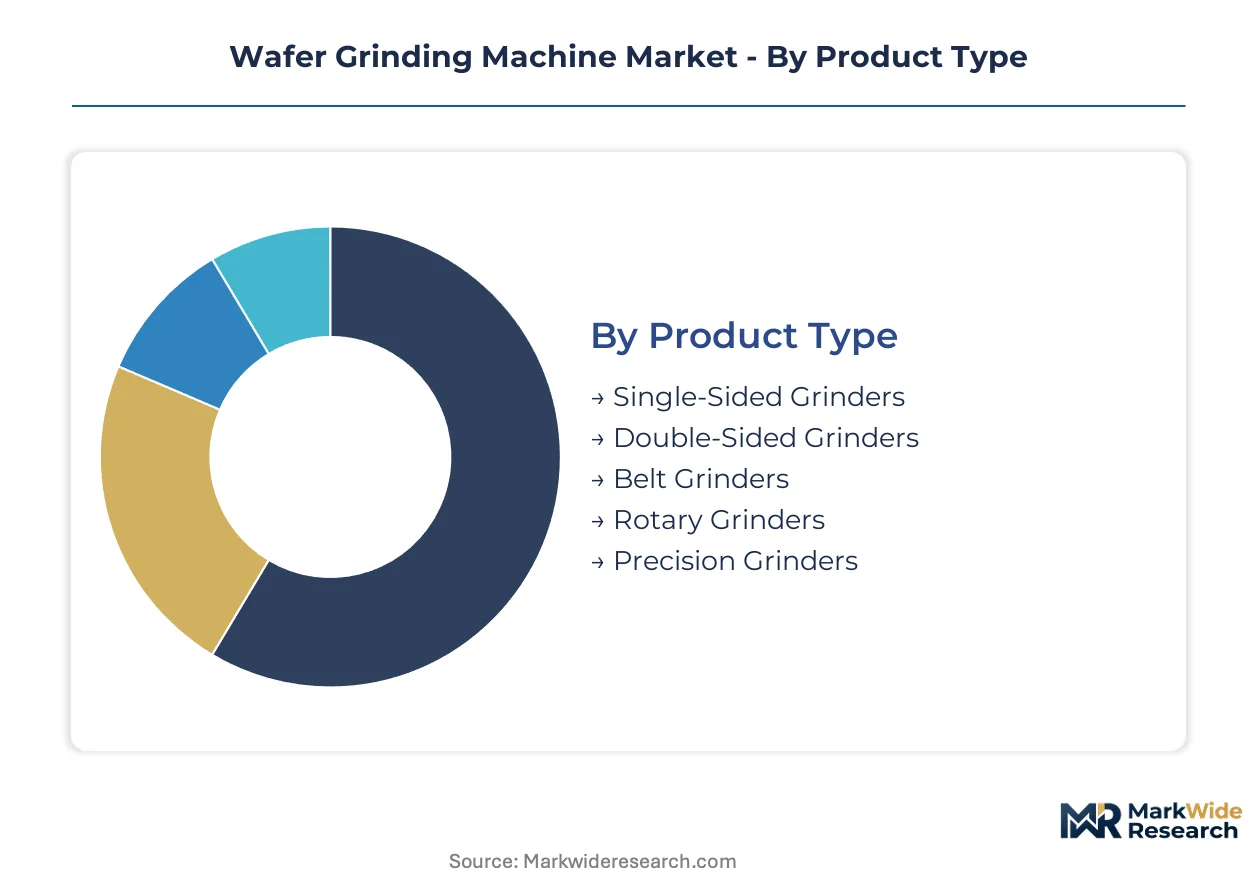
Wafer grinding machine segmentation reflects divergent precision requirements across substrate materials and process nodes. Equipment specifications vary sharply between silicon thinning for advanced packaging and silicon carbide processing for power electronics.
Product Type:
Customization intensity spans from standardized single-sided platforms to highly engineered double-sided systems for exotic substrates.
- Single-Sided Grinders:These systems process one wafer surface at a time using vacuum chuck mounting and diamond wheel abrasion. Taiwan's Hsinchu Science Park fabs deploy these for backside thinning of logic devices where throughput and automation compatibility outweigh absolute precision. Most installed capacity flows through Single-Sided Grinders. Expansion is steepest in Double-Sided Grinders.
- Double-Sided Grinders:Simultaneous material removal from both wafer faces achieves superior thickness uniformity for brittle wide-bandgap materials. South Korean power electronics manufacturers in Pyeongtaek are scaling procurement for 150mm and 200mm SiC wafer production.
- Belt Grinders:Continuous abrasive belt configurations handle edge profiling and coarse material removal in solar wafer manufacturing.
- Rotary Grinders:Platen-based rotary motion systems serve legacy silicon wafer thinning lines with lower capital intensity.
- Precision Grinders:Sub-micron positioning accuracy platforms target gallium nitride substrates for RF device fabrication.
Single-Sided Grinders dominate unit shipments. Double-Sided Grinders command premium pricing and fastest growth.
Technology:
Process architecture divides along thermal management method and environmental footprint, with water availability and coolant regulations driving selection.
- Wet Grinding:Flood coolant delivery suppresses thermal damage during aggressive material removal through controlled lubrication and chip evacuation. The technology anchors installed base volumes across Japanese and Taiwanese fabrication corridors where wastewater treatment infrastructure is mature.
- Dry Grinding:Electrostatic chuck wafer handling eliminates coolant systems entirely, reducing environmental compliance burden. Arizona fabs and Singapore packaging houses are piloting these configurations where municipal water constraints limit expansion permits.
- Ultraprecision Grinding:Nanometer-scale positioning and in-situ metrology enable sub-10-micron total thickness variation for advanced heterogeneous integration.
- Cryogenic Grinding:Liquid nitrogen or CO2 cooling prevents thermal damage in hard-brittle ceramic substrate processing.
- Chemical Mechanical Planarization:Slurry-based material removal combines chemical etching with mechanical abrasion for final thickness tuning.
Wet Grinding retains volume leadership. Dry Grinding is expanding most quickly in water-stressed manufacturing locations.
Application:
End-use requirements fragment by substrate material hardness, target thickness, and downstream packaging complexity.
- Semiconductor Fabrication:Backside thinning for 3D stacking and fan-out wafer-level packaging drives sub-50-micron precision requirements. Taiwan and South Korean advanced packaging clusters generate concentrated demand for integrated grinding-dicing systems.
- Microelectromechanical Systems:Device release and handle wafer removal demand controlled damage penetration into active silicon layers.
- LED Manufacturing:Sapphire substrate thinning for vertical LED structures uses specialized grinding wheels with optimized abrasive bonding.
- Solar Cell Production:Kerf loss reduction and wafer thickness optimization for crystalline silicon photovoltaics.
- Telecommunications Components:RF filter and power amplifier substrate preparation for 5G infrastructure deployment.
Semiconductor Fabrication absorbs the majority of precision grinding capacity. MEMS applications are gaining share fastest as sensor integration accelerates.
End User:
Procurement patterns diverge between captive fabrication and outsourced assembly models, with financing structures adapting to capital intensity constraints.
- Fabless Companies:These design houses specify grinding tolerances but rely on foundry partners for capital equipment deployment, influencing equipment selection through process development agreements rather than direct procurement.
- Equipment Manufacturers:Capital goods producers grinding precision mechanical components for semiconductor tool subassemblies.
- OEMs:Integrated device manufacturers with captive fabrication maintaining direct grinding system ownership and upgrade cycles.
- Contract Manufacturers:OSAT providers in Malaysia and Vietnam are shifting toward equipment leasing structures to preserve balance sheet flexibility amid technology transition risk.
- Substrate Suppliers:Specialized wafer vendors supplying epitaxy-ready silicon carbide and gallium nitride materials to device fabs.
Contract Manufacturers represent the largest equipment installed base. Substrate Suppliers are climbing the fastest as wide-bandgap material demand accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wafer grinding machine manufacturing originated in post-war Japan, where precision toolmaking traditions merged with semiconductor fabrication demands during the 1970s. This heritage established quality benchmarks that persist across contemporary Asian and European production centers. Equipment deployment now concentrates in fabrication corridors shaped by substrate material transitions and packaging node evolution.
Taiwan
Hsinchu Science Park fabs drive integrated dicing-grinding system procurement for advanced packaging nodes. The National Development Council subsidizes precision equipment localization under the Six Core Strategic Industries initiative. Taichung's emerging packaging corridor is absorbing capacity for fan-out wafer-level processing.
South Korea
Pyeongtaek semiconductor manufacturers scale double-sided grinder deployment for silicon carbide power electronics. The K-Semiconductor Belt initiative channels state support toward materials innovation clusters. Yongin's packaging ecosystem is consolidating metrology-integrated grinding platforms for heterogeneous integration.
China
Jiangsu and Shaanxi substrate suppliers prioritize MIIT-certified equipment to secure capacity expansion subsidies under dual carbon goals. The Ministry of Industry and Information Technology mandates regenerative spindle drives and smart power management in new deployments. Shanghai's Zhangjiang Hi-Tech Park is piloting dry grinding configurations to reduce water treatment infrastructure.
Japan
Tokyo and Nagoya industrial centers sustain mechatronics engineering concentration for ultraprecision platform development. METI's semiconductor equipment competitiveness program funds closed-loop process control integration. Kyoto's toolmaking heritage anchors abrasive wheel manufacturing quality for diamond-abrasive applications.
United States
Arizona fabs pilot dry grinding platforms with electrostatic chuck handling to circumvent municipal water constraints on expansion permits. EPA emissions standards for coolant fluid handling shape equipment architecture decisions for new installations. Oregon's semiconductor corridor is evaluating leasing structures to preserve capital flexibility amid technology transition cycles.
Wafer Grinding Machine Market Competitive Landscape
Capital-heavy equipment fabricators compete with asset-light process technology licensors across distinct value capture layers. The vendor base concentrates among Japanese precision machinery conglomerates and specialized German grinding technology houses, with tiered positioning between integrated system suppliers and component specialists. Three archetypes dominate: full-stack platform integrators, abrasive subsystem specialists, and regional service-anchored distributors. Competitive dynamics center on geographic service network density and strategic partnerships with substrate material suppliers.
Within the full-stack integrator tier, DISCO Corporation and Tokyo Seimitsu Co., Ltd. exemplify precision platform development anchored in Japanese industrial centers. Okamoto Semiconductor Equipment Division occupies a position emphasizing localized service infrastructure across Southeast Asian manufacturing corridors. Among European precision fabricators, Lapmaster Wolters GmbH represents abrasive technology specialization, while G&N Genauigkeits Maschinenbau Nürnberg GmbH anchors German engineering heritage in ultraprecision mechanical design. These named entities illustrate how competitive positioning stratifies between geographic proximity advantages and technology specialization depth.
| Leading Market Players |
|---|
| DISCO Corporation |
| Tokyo Seimitsu Co., Ltd. |
| Okamoto Semiconductor Equipment Division |
| ACCRETECH |
| Komatsu NTC |
| Revasum |
| Lapmaster Wolters GmbH |
| G&N Genauigkeits Maschinenbau Nürnberg GmbH |
| Strasbaugh |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation compliance mandates for low-global-warming-potential coolants are forcing equipment refresh decisions across German and French fabs, compelling grinding system vendors to absorb certification costs or pass them through to buyers already facing compressed replacement cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates MIIT-certified platforms with regenerative spindle drives from legacy wet grinding systems and refurbished units. Price differentiation hinges on energy-efficiency certification tier and geographic proximity of service networks. Cost compression in the economy tier is intensifying because substrate suppliers in Jiangsu and Shaanxi prioritize certified equipment to secure state-backed subsidies. Contract manufacturers in Malaysia and Vietnam exhibit highest price sensitivity, while captive OEM fabs in Taiwan and South Korea prioritize precision specifications over unit cost.
Supply Chain Analysis
Regional distribution centers in Tokyo, Nagoya, and Osaka anchor hub-and-spoke patterns serving Southeast Asian manufacturing corridors. Geographic supply concentration centers on Japan for precision mechatronics, Germany for abrasive subsystem engineering, and Taiwan for integrated dicing-grinding platforms. Raw material dependencies draw from high-purity synthetic diamond wheel production, precision spindle bearings, and advanced ceramic components. Single-source vulnerability in diamond abrasive supply basins creates input cost volatility. Distribution runs through semiconductor equipment lessors bundling systems with consumables and predictive maintenance analytics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU F-Gas mandates and China's MIIT certification create sustained equipment replacement demand across multiple geographies.
For Market Incumbents: Extend geographic service network density into India's emerging semiconductor PLI corridors before substrate suppliers finalize vendor qualification decisions. Deepen captive supply of diamond abrasive wheel production to neutralize input cost volatility threatening margin stability in the standard equipment tier. For New Entrants and Emerging Players: The price-point gap between premium MIIT-certified platforms and economy-tier refurbished systems creates entry space for mid-market vendors offering energy-efficient wet grinding configurations without full metrology integration. Target substrate suppliers in Shaanxi and Jiangsu provinces seeking certified equipment for state subsidy eligibility. Lead with localized service infrastructure partnerships rather than direct sales channels. For Investors and Strategic Acquirers: Asymmetric upside sits with precision metrology subsystem specialists capable of integrating real-time thickness feedback into incumbent grinding platforms. Long-term viability favors vendors controlling both equipment architecture and consumables supply over pure hardware fabricators. Watch for inflection signals in dry grinding pilot adoption rates at Arizona and Singapore fabs facing municipal water constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diamond Abrasive Production | Captive supply of grinding wheels neutralizes lead time uncertainty from concentrated Asian supply basins. |
| MIIT Energy-Efficiency Certification Investment | Qualification for China's dual carbon procurement preferences unlocks Jiangsu and Shaanxi substrate supplier demand. |
| Regional Service Network Expansion | Localized maintenance infrastructure in India's PLI corridors accelerates vendor selection for emerging fabrication capacity. |
| In-Line Metrology Platform Integration | Real-time thickness feedback systems reduce downstream yield loss in Taiwan's advanced packaging flows. |
| Dry Grinding Configuration Development | Elimination of coolant systems addresses EPA emissions standards and water constraints at Arizona fabs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fab equipment procurement managers, precision grinding system engineers, substrate supplier operations directors, and semiconductor equipment lessor portfolio managers with secondary validation through SEC filings, customs trade data, SEMI equipment market statistics, and MIIT certification registries. Bottom-up equipment shipment tracking and top-down fabrication capacity expansion analysis provided cross-verification.
Comparable-period anchoring linked projection assumptions to historical replacement cycle patterns and regulatory compliance timelines across the analysis window. Segmentation modeling captured product type, technology architecture, substrate material application, and end-user procurement structure. CAGRs were derived from equipment shipment trajectories weighted against fab capacity buildout schedules and energy-efficiency mandate phase-in dates. Forecast inputs incorporated silicon carbide substrate demand curves and dry grinding pilot adoption indicators.
The model assumes a particular technology adoption path; alternative pathways for electrostatic chuck dry grinding platforms would alter the outlook if municipal water constraints accelerate beyond anticipated permitting timelines. Forecasts reflect assumptions about EU F-Gas implementation consistency and MIIT certification enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Electrostatic Chucks Market
Semiconductor Equipment
Asia-Pacific Aligner Sheet Market
Semiconductor Equipment
SMT Reflow Soldering Equipment Market
Semiconductor Equipment
Semiconductor Photolithography Equipment Market
Semiconductor Equipment
Semiconductor Laser Equipment Market
Semiconductor Equipment
Wire Bonder Equipment Market
Semiconductor Equipment
Europe Semiconductor Etch Equipment Market
Semiconductor Equipment
Pulsed Laser Deposition Systems Market
Semiconductor Equipment
Global Resist Processing Equipment Market
Semiconductor Equipment
Automatic Flip Chip Bonders Market
Semiconductor Equipment
Multi-Touch Equipment Market
Semiconductor Equipment
Semiconductor POD Cleaner Market
Semiconductor Equipment
UV-Based Nanoimprint Lithography (UV-NIL) System Market
Semiconductor Equipment
Vacuum Chambers Market
Semiconductor Equipment
Photolithography Equipment Market
Semiconductor Equipment
Global Cleanroom Technologies Market