
 Porous Silicon Substrates Market | 2026-2036
Porous Silicon Substrates Market Size, Share, and Industry Trends Forecast 2026-2036
Porous Silicon Substrates Market Analytics
Asset-light foundry partnerships is reconfiguring competitive entry barriers for smaller substrate developers. Soitec leverages its engineered substrate expertise to anchor premium wafer supply chains. STMicroelectronics competes through integrated MEMS-silicon capabilities. Shin-Etsu Chemical Co., Ltd. dominates polysilicon feedstock quality, sustaining downstream pricing power.
Porous silicon substrates are nanostructured silicon materials with controlled pore diameters from nanometers to micrometers, fabricated through electrochemical etching in hydrofluoric acid electrolytes to achieve specific surface areas exceeding 500 square meters per gram. These substrates function as tunable platforms for drug encapsulation, optical sensing, and photovoltaic light trapping where bulk silicon performance proves insufficient. Wafer formats command the dominant revenue share due to compatibility with existing semiconductor process equipment, while films represent the fastest-growing category as flexible electronics and wearable biosensors expand. Electrochemical etching retains technology leadership for precise pore architecture control, though laser etching is displacing legacy wet methods in photovoltaic applications requiring rapid throughput.
EMA medical device regulations and REACH substance restrictions in Europe shape biocompatibility certification pathways for healthcare applications. FDA quality system requirements govern U.S. market entry for implantable drug delivery platforms. ISO 10993 biological evaluation standards provide the harmonized testing framework that most manufacturers pursue for multi-jurisdiction product registration. Stakeholders must monitor evolving EU Green Deal material sourcing mandates that could redirect silicon feedstock procurement toward verified low-carbon supply chains.
Market Dynamics
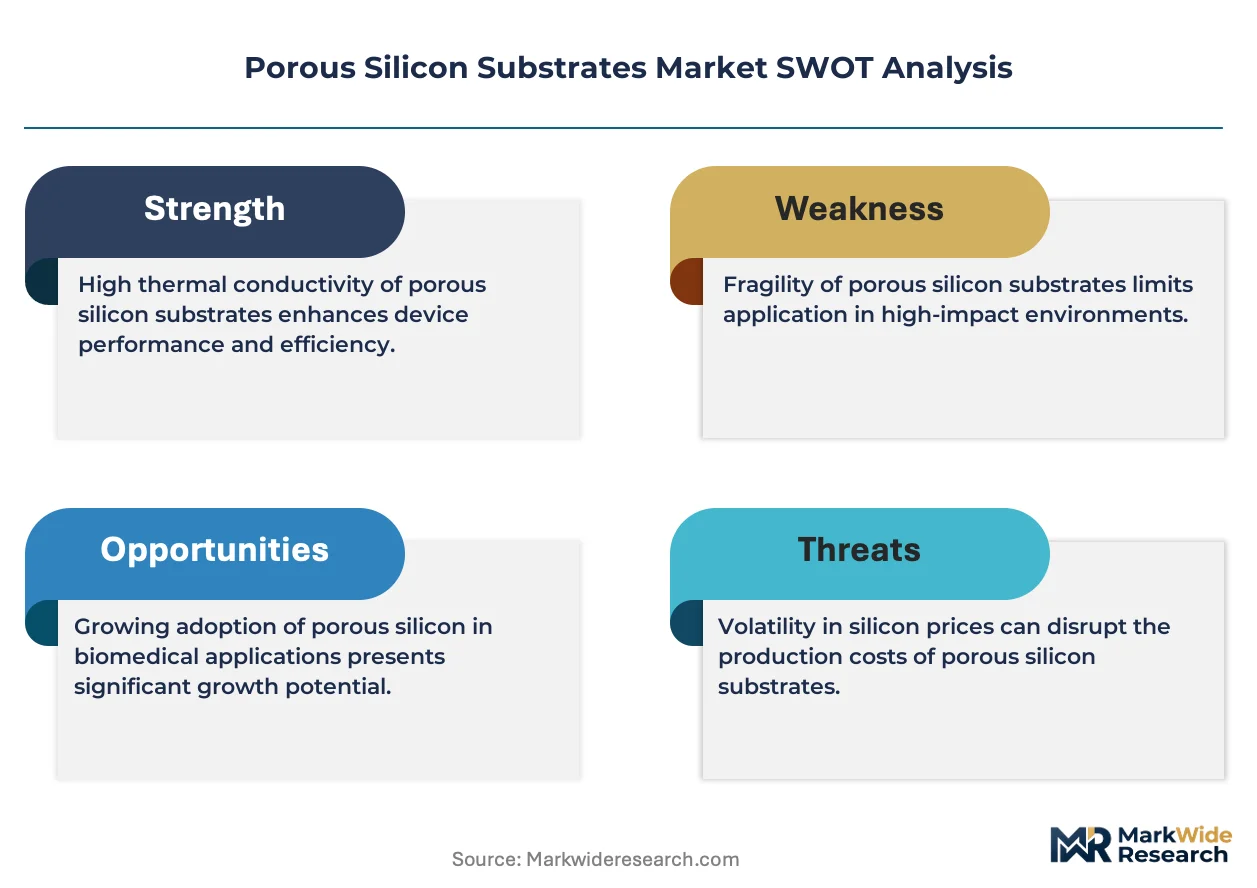
Electrochemical etching precision requirements and REACH substance purity mandates are forcing substrate developers to rebuild process control architectures around verified low-carbon silicon feedstock sourcing.
Growth Catalysts
- Drug delivery platform expansion:Implantable therapeutic systems in cardiovascular and oncology applications require porous silicon's tunable release kinetics and bioresorbable properties.
- EMA medical device regulations:The EU MDR framework creates certification moats that favor established substrate manufacturers with ISO 10993 testing infrastructure already deployed.
- Laser etching throughput gains:Photovoltaic manufacturers in Germany's precision manufacturing corridor are adopting dry etching methods to bypass wet chemistry bottlenecks in high-volume production.
Market Restraints
- Hydrofluoric acid supply volatility:Electrochemical etching depends on semiconductor-grade HF electrolytes concentrated among Chinese and Japanese chemical suppliers, exposing cost structures to export restriction risk.
- Biocompatibility certification timelines:FDA quality system requirements for implantable drug delivery platforms impose 18-36 month validation cycles that freeze working capital and delay revenue recognition.
- Bulk silicon performance improvements:Advanced surface texturing techniques on standard monocrystalline wafers are narrowing the efficiency gap for photovoltaic light trapping applications.
Strategic Opportunities
- Wearable biosensor films:Flexible porous silicon substrates enable conformal integration with skin-mounted glucose and lactate monitors, opening volume markets outside traditional wafer formats.
- EU Green Deal material mandates:Verified low-carbon silicon feedstock procurement requirements will redirect supply contracts toward European polysilicon producers with renewable energy certificates.
- Optical sensing convergence:Integration of porous silicon photonic structures with quantum dot emitters is creating label-free diagnostic platforms for point-of-care pathogen detection.
Industry Challenges
- Electrochemical process engineering talent scarcity:The intersection of semiconductor fabrication and electrochemistry expertise required for pore architecture control concentrates in German and Swiss research clusters, limiting scale-out capacity.
- Multi-jurisdiction certification complexity:Harmonizing FDA quality system documentation with EMA medical device regulations and ISO 10993 biological evaluation standards demands dedicated regulatory affairs functions that strain mid-size developers.
- Legacy semiconductor equipment retrofit costs:Adapting standard CVD and etching tools for porous silicon nanostructure fabrication requires chamber modifications and process recipe redevelopment that consume capex budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Porous Silicon Substrates Market |
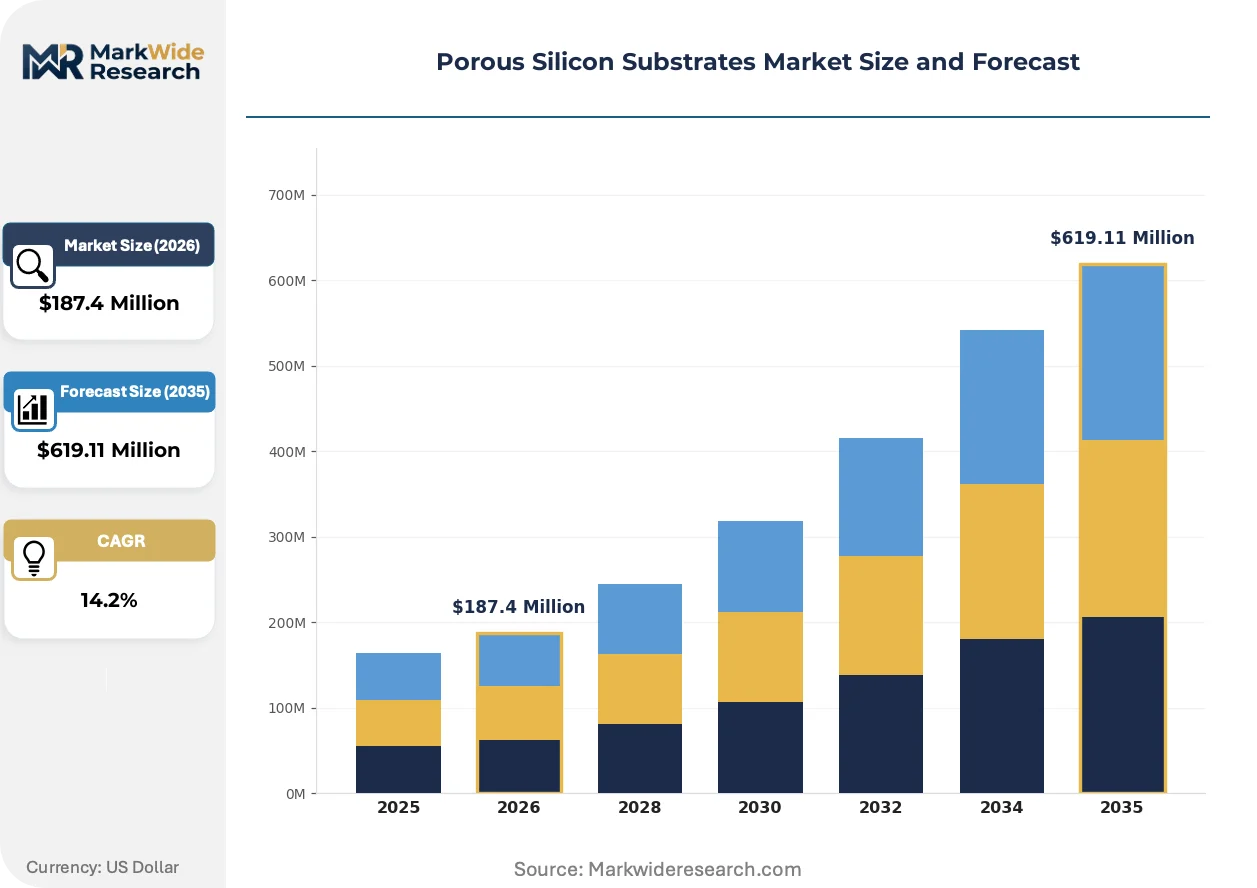
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Plates, Disks, Wafers, Films Application: Semiconductors, Sensors, Photovoltaics, Drug Delivery End User: Electronics, Healthcare, Research Institutions, Renewable Energy Technology: Electrochemical Etching, Laser Etching, Wet Etching, Dry Etching |
| Companies Covered | Applied Materials, STMicroelectronics, Siltronic AG, Intel Corporation, Shin-Etsu Chemical Co., Ltd., SUMCO Corporation, Soitec, GlobalWafers Co., Wolfspeed Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Porous Silicon Substrates Market Evolving Landscape
Process automation and closed-loop etching control systems are compressing the gap between laboratory pore architecture precision and manufacturing repeatability, reshaping competitive entry barriers across substrate formats.
Laser-induced etching is collapsing the throughput advantage that wet chemistry methods held in photovoltaic applications. German solar cell manufacturers now deploy femtosecond laser systems to generate sub-micron surface textures at line speeds exceeding 100 wafers per minute. This dry process eliminates hydrofluoric acid handling infrastructure and enables in-line quality monitoring that wet baths cannot support.
REACH substance restrictions are tightening purity specifications for silicon feedstocks used in implantable medical devices. ECHA enforcement of candidate list substances is forcing substrate developers to document carbon intensity and trace metal content across supply chains. German precision manufacturers are responding by qualifying domestic polysilicon sources with renewable energy certificates to preempt compliance disruption.
Flexible electronics procurement is fragmenting traditional wafer-centric supply relationships. Wearable biosensor developers in the Netherlands and Switzerland now specify film-format porous silicon with roll-to-roll compatibility, bypassing semiconductor foundries entirely. This channel disintermediation is compressing pricing power for established wafer suppliers and opening entry points for specialty chemical coating houses.
Porous Silicon Substrates Market Segmentation
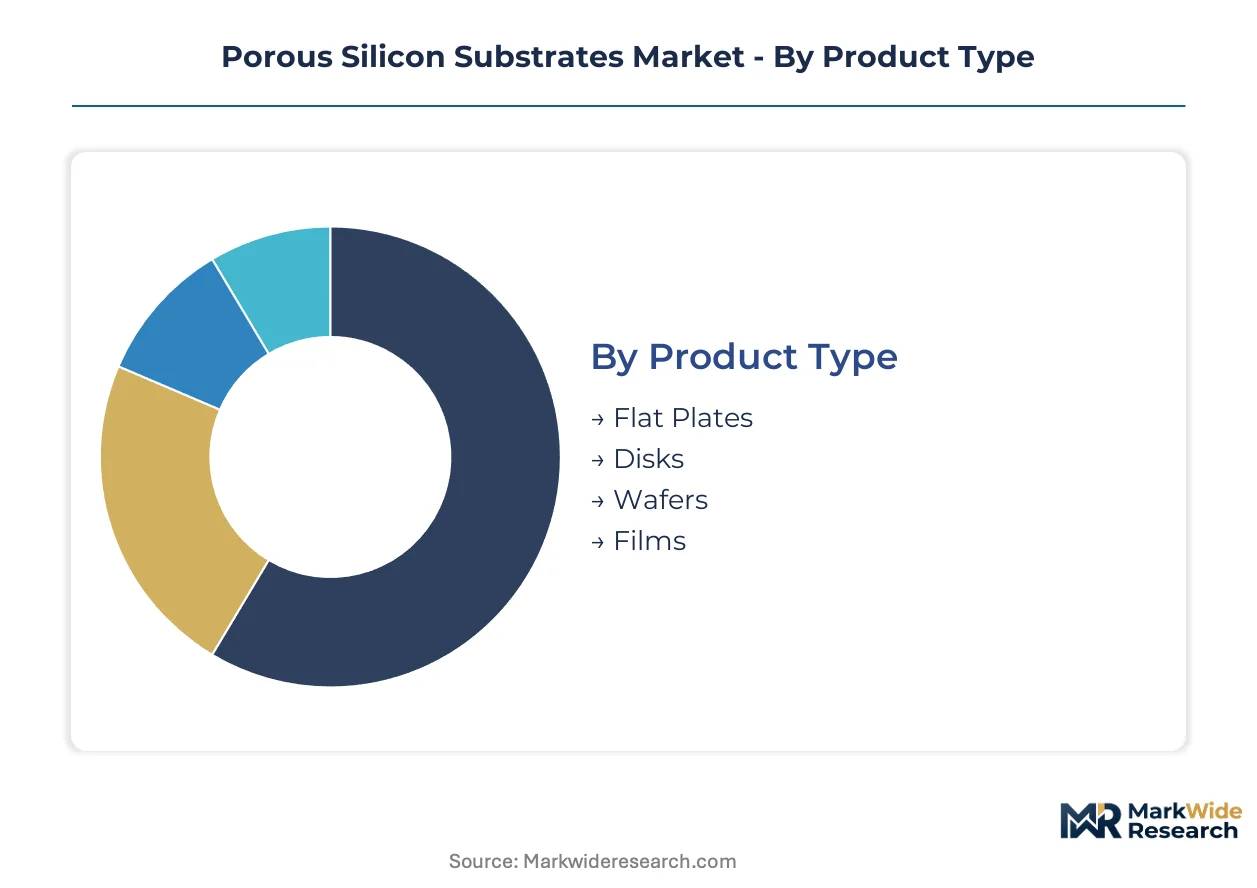
Porous silicon substrates fragment across multiple technical and commercial dimensions. Each segmentation axis reveals distinct procurement patterns, certification requirements, and competitive dynamics that shape supplier positioning.
Product Type:
Volume concentration and process compatibility divide the product landscape into formats with divergent equipment requirements and customer relationships.
- Wafers:Standard semiconductor diameters from 100mm to 300mm dominate current revenue. German precision manufacturers in the automotive sensor supply chain specify 200mm formats for MEMS integration, leveraging existing foundry infrastructure.
- Films:Roll-to-roll compatible formats on polyimide or metal foils enable conformal integration with curved surfaces. Dutch and Swiss wearable biosensor developers drive procurement for glucose monitoring patches, bypassing traditional wafer foundries entirely.
- Flat Plates:Rectangular geometries for optical bench applications and academic research setups.
- Disks:Circular formats for specialized electrochemical cell configurations and filtration membranes.
Wafers command the established base. The steepest expansion runs through films.
Application:
End-use functionality determines pore architecture specifications, biocompatibility certification pathways, and customer technical support intensity.
- Drug Delivery:Implantable therapeutic systems require tunable release kinetics and bioresorbable degradation profiles. FDA quality system requirements and EMA medical device regulations impose parallel 18-36 month validation cycles for cardiovascular and oncology platforms.
- Photovoltaics:Light-trapping surface textures improve conversion efficiency in monocrystalline cells. German solar manufacturers deploy laser etching at line speeds exceeding 100 wafers per minute, eliminating hydrofluoric acid handling infrastructure.
- Semiconductors:MEMS resonators and thermal isolation structures for automotive and consumer electronics.
- Sensors:Optical and electrochemical detection platforms for environmental and industrial monitoring.
Drug delivery commands the established base. Photovoltaics is climbing the fastest.
End User:
Customer type shapes procurement scale, technical specification rigor, and regulatory documentation burden.
- Healthcare:Medical device manufacturers demand ISO 10993 biological evaluation documentation and REACH substance compliance for implantable products. European procurement is concentrating in Germany's precision manufacturing corridor under tightening ECHA enforcement.
- Electronics:Semiconductor and MEMS producers prioritize process compatibility with standard CMOS equipment and supply chain security.
- Renewable Energy:Solar cell manufacturers optimize for throughput and cost per watt in high-volume production environments.
- Research Institutions:Academic and government laboratories drive early-stage pore architecture development with small-batch, high-variability orders.
Healthcare commands the established base. Renewable energy is gaining share fastest.
Technology:
Fabrication method determines pore precision, throughput economics, and environmental compliance exposure.
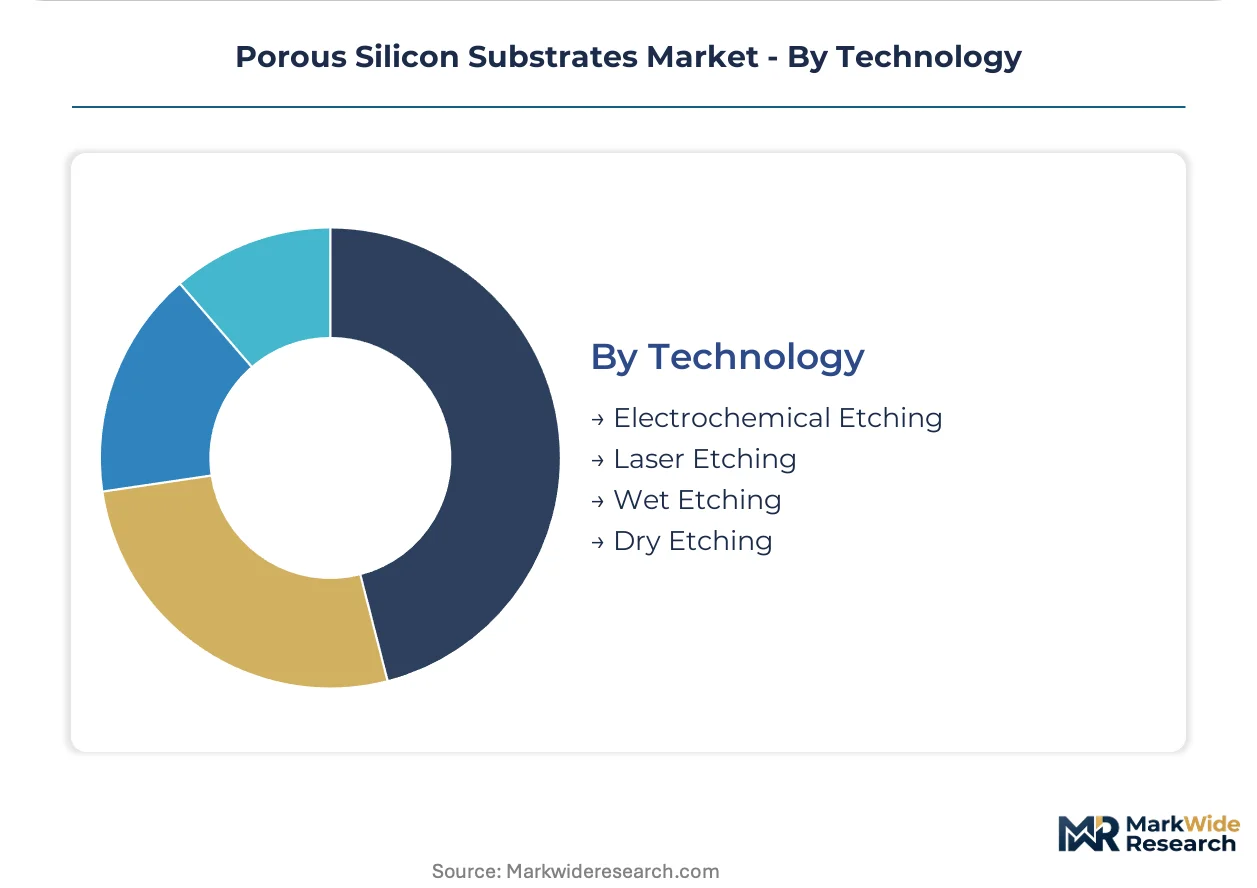
- Electrochemical Etching:Hydrofluoric acid electrolytes enable precise control over pore diameter and depth through current density modulation. German and Swiss research clusters concentrate the specialized electrochemistry-semiconductor fabrication expertise required for scale-out.
- Laser Etching:Femtosecond and nanosecond pulsed systems generate sub-micron textures without wet chemistry. Dry processing eliminates REACH substance handling and enables in-line quality monitoring for photovoltaic applications.
- Wet Etching:Chemical stain etching with nitric acid and hydrofluoric acid mixtures for simpler pore structures.
- Dry Etching:Plasma-based methods for reactive ion etching of silicon in MEMS fabrication flows.
Electrochemical etching commands the established base. Laser etching is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal material mandates and REACH substance restrictions are redirecting silicon feedstock procurement toward verified low-carbon supply chains across major manufacturing economies. National regulators in Germany, the United States, China, Japan, and South Korea are tightening purity specifications for healthcare and photovoltaic applications.
Germany
EMA medical device regulations and ECHA enforcement of candidate list substances dominate compliance planning for implantable drug delivery platforms. The country's precision manufacturing corridor in Baden-Württemberg and Bavaria concentrates electrochemical etching expertise for MEMS-silicon integration. Stuttgart and Munich anchor clusters where substrate developers qualify domestic polysilicon with renewable energy certificates.
United States
FDA quality system requirements impose 18-36 month validation cycles for cardiovascular and oncology therapeutic systems, freezing working capital for mid-size developers. The Inflation Reduction Act's domestic manufacturing incentives are reshaping solar cell production economics. Arizona and Oregon host photovoltaic manufacturers adopting laser etching to bypass wet chemistry infrastructure.
China
MIIT industrial standards and dual carbon goals are pressuring polysilicon producers to document energy intensity across supply chains. Semiconductor-grade hydrofluoric acid concentration among domestic chemical suppliers exposes cost structures to export restriction risk. The Yangtze River Delta anchors wet etching capacity for legacy photovoltaic applications.
Japan
METI technology roadmaps prioritize dry processing methods to eliminate hydrofluoric acid handling in high-volume manufacturing. PMDA pharmaceutical regulations align with ISO 10993 biological evaluation standards for multi-jurisdiction product registration. Kyushu and Tohoku regions concentrate laser etching system deployment for monocrystalline cell texturing.
South Korea
MFDS medical device approval pathways and K-REACH substance registration requirements extend certification timelines for bioresorbable substrates. The Seoul Capital Area dominates MEMS foundry capacity for consumer electronics integration. Busan-Ulsan chemical complexes supply semiconductor-grade electrolytes under tightening carbon disclosure mandates.
Porous Silicon Substrates Market Competitive Landscape
Channel-controlling players compete with product-specialist players across wafer, film, and equipment segments. The vendor base clusters around three strategic archetypes: engineered substrate specialists with premium wafer supply chain anchoring, integrated device manufacturers with captive MEMS-silicon capabilities, and polysilicon feedstock producers with downstream pricing leverage. Dominant competitive moves include asset-light foundry partnerships that reconfigure entry barriers for smaller developers and strategic equipment retrofit collaborations that adapt legacy semiconductor tools for nanostructure fabrication.
Among substrate fabricators, Soitec occupies a position exemplifying engineered substrate expertise, while STMicroelectronics sits within the integrated MEMS-silicon tier. Shin-Etsu Chemical Co., Ltd. anchors the feedstock quality vector that sustains downstream pricing power across electrochemical etching supply chains.
| Leading Market Players |
|---|
| Applied Materials |
| STMicroelectronics |
| Siltronic AG |
| Intel Corporation |
| Shin-Etsu Chemical Co., Ltd. |
| SUMCO Corporation |
| Soitec |
| GlobalWafers Co. |
| Wolfspeed Inc. |
| Others |
Value Network & Pricing Analysis
Hydrofluoric acid supply volatility from Chinese and Japanese chemical suppliers compresses pricing tier spreads while forcing substrate developers toward dual-source qualification and laser etching migration. REACH substance purity mandates and EU Green Deal carbon disclosure requirements simultaneously widen certification-grade premiums and reshape silicon feedstock procurement toward verified low-carbon European polysilicon.
Pricing Analysis
Certification level creates the primary spread between ISO 10993-validated implantable grades and industrial sensor tiers. Three-tier pricing structure across premium, standard, and economy levels reflects FDA quality system documentation burden, EMA medical device regulation compliance depth, and volume scale. Cost compression in standard wafer formats intensifies because bulk silicon surface texturing narrows photovoltaic efficiency gaps. Healthcare buyers show least price sensitivity due to 18-36 month validation cycle lock-in, while renewable energy procurement teams drive hardest bargain on cost-per-watt metrics.
Supply Chain Analysis
Extended payment terms from German precision manufacturers and supply-chain finance facilities from Dutch wearable biosensor developers ease working capital pressure for mid-size substrate fabricators. Polysilicon feedstock concentrates in Germany, Japan, and China. Electrochemical etching draws from semiconductor-grade hydrofluoric acid, renewable energy certificates, and MEMS-compatible wafer handling equipment. Single-source vulnerability runs through Chinese HF electrolyte suppliers. Distribution runs through asset-light foundry partnerships and direct OEM contracts for film-format products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Porous silicon substrates sit in early-cycle expansion as drug delivery platform adoption accelerates cardiovascular and oncology therapeutic deployments. Implantable bioresorbable systems penetration remains below technical potential across European and North American hospital networks.
For Market Incumbents: Harden ISO 10993 testing infrastructure against EMA medical device regulation tightening and FDA quality system documentation expansion. Anchor premium wafer supply chains through backward integration into verified low-carbon polysilicon feedstock to preempt EU Green Deal procurement mandates. Defend against laser etching displacement in photovoltaic segments by retrofitting legacy electrochemical capacity for healthcare-grade pore architecture precision.
For New Entrants and Emerging Players: Build out roll-to-roll film fabrication capability targeting Dutch and Swiss wearable biosensor developers bypassing traditional semiconductor foundries. Penetrate glucose monitoring patch supply chains through conformal substrate integration expertise. Pursue white-label partnerships with precision manufacturing corridor OEMs seeking second-source qualification for MEMS-silicon integration.
For Investors and Strategic Acquirers: EU MDR enforcement reshapes the acquisition landscape toward substrate developers with deployed biological evaluation infrastructure and multi-jurisdiction regulatory affairs functions. Long-term viability centers on healthcare application moats rather than photovoltaic commodity exposure. Target acquisition archetype: mid-cap specialists with ISO 10993 master files and German precision manufacturing corridor customer relationships. Monitor ECHA candidate list substance restrictions as inflection signal for feedstock cost restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon Feedstock | Secures verified low-carbon supply chains against EU Green Deal procurement mandates. |
| Laser Etching Capacity Deployment | Eliminates hydrofluoric acid handling infrastructure for German photovoltaic manufacturers. |
| ISO 10993 Biological Evaluation Infrastructure | Creates certification moats under EMA medical device regulation and FDA quality system requirements. |
| Roll-to-Roll Film Format Development | Captures wearable biosensor procurement from Dutch and Swiss developers outside wafer foundry channels. |
| Asset-Light Foundry Partnership Expansion | Reduces capex burden for pore architecture scale-out while preserving process control. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with substrate fabrication engineers, regulatory affairs directors at medical device OEMs, procurement leads in German precision manufacturing corridors, and electrochemical process specialists; alongside secondary validation through EMA medical device regulation filings, FDA quality system documentation, ECHA REACH substance registrations, and polysilicon producer sustainability disclosures. Bottom-up wafer and film volume estimates triangulated against top-down healthcare and photovoltaic application demand models.
Forecast inputs incorporated electrochemical etching throughput constraints, laser etching adoption curves in German solar manufacturing, and EMA medical device regulation certification timeline distributions across the analysis window. Segmentation dimensions spanned product format, application functionality, fabrication technology, and end-user procurement archetype. CAGRs derived from slope-intercept modeling of adoption S-curves and price elasticity responses to silicon feedstock cost fluctuations.
Sensitivities concentrate around hydrofluoric acid export restriction triggers, EU Green Deal material mandate enforcement timing, and bulk silicon surface texturing efficiency breakthroughs. Forecasts reflect documented assumptions on regulatory compliance cost trajectories and technology substitution thresholds. Macroeconomic contraction, regulatory acceleration, or dry etching cost parity achievement would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Global Foundry Service Market
Semiconductor Fabrication
Semiconductor Etching Cleaner Market
Semiconductor Fabrication
Global Dielectric Etchers Market
Semiconductor Fabrication
Photoresist Removal Market
Semiconductor Fabrication
8-Inch Silicon Carbide (Sic) Wafer Market
Semiconductor Fabrication
Etching Machine Market
Semiconductor Fabrication
Semiconductor Fab Water Reuse Systems Market
Semiconductor Fabrication
Sic Wafer Reclaim Services Market
Semiconductor Fabrication
Epitaxial Wafer Market
Semiconductor Fabrication
Global Spark Plasma Sintering Market
Semiconductor Fabrication
Etchant for FPD Market
Semiconductor Fabrication
Ion Implantation Machine Market
Semiconductor Fabrication
300mm Silicon Wafers Market
Semiconductor Fabrication
Semiconductor Advanced Substrate Market
Semiconductor Fabrication
Additive Manufacturing in Semiconductor Market
Semiconductor Fabrication
Physical Vapor Deposition (PVD) Market