
 Semiconductor Photoresist Polymer Market | 2026-2036
Semiconductor Photoresist Polymer Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Photoresist Polymer Market Insights
Logic foundries are gaining procurement share while memory chip manufacturers moderate capital intensity, so demand is bifurcating between leading-edge and trailing-node buyers. Tokyo Ohka Kogyo leverages its captive supply of high-purity monomers to anchor EUV resist shipments. JSR Corporation dominates ArF immersion formulations through its specialized polymer architecture. DuPont competes in legacy i-line and g-line segments where cost optimization governs purchasing.
Semiconductor photoresist polymers are radiation-sensitive organic compounds formulated with photoacid generators, dissolution inhibitors, and base resins such as polyhydroxystyrene or acrylate derivatives, designed to undergo solubility switching upon exposure to specific wavelengths for precise pattern transfer in integrated circuit fabrication. Chemically amplified photoresist leads value generation due to its catalytic deprotection mechanism enabling sub-7nm resolution. Positive photoresist occupies the largest volume position across mature node foundries and power semiconductor fabs. Lithography technology governs material specification, with EUV resists commanding premium positioning over DUV alternatives.
Japan's METI coordinates domestic supply security for photoresist precursors under export control frameworks, while South Korea's trade ministry accelerates local substitution programs to reduce import dependency. The US CHIPS Act and EPA chemical reporting requirements shape facility investment timelines and material qualification protocols. Stakeholders must monitor regulatory divergence between East Asian supply hubs and Western end markets to calibrate manufacturing footprints and compliance investments.
Market Dynamics
Logic foundries are accelerating EUV resist procurement as memory manufacturers compress capital expenditure, bifurcating demand between leading-edge nodes requiring sub-7nm resolution and trailing-node buyers optimizing for cost.
Growth Catalysts
- Advanced Node Logic:Leading-edge foundries in South Korea's Pyeongtaek cluster are expanding EUV lithography deployment for DRAM and logic fabrication, driving specialized resist formulations.
- F-Gas Regulation:The EU's tightening fluoropolymer supply constraints are accelerating qualification of alternative chemistries in photoresist precursor chains.
- Chemically Amplified Resists:Catalytic deprotection mechanisms enabling sub-7nm patterning are displacing conventional positive-tone systems in high-volume manufacturing.
Market Restraints
- High-Purity Monomer Concentration:Captive supply chains for EUV-grade raw materials concentrate in Japanese chemical producers, creating single-source vulnerability.
- Technical Resolution Limits:Stochastic defect density in EUV resists constrains yield at pitches below 36nm, requiring costly multi-patterning workarounds.
- Regulatory Reporting Burden:EPA chemical disclosure requirements under TSCA Section 8 extend qualification timelines for new resist formulations entering US fabs.
Strategic Opportunities
- South Korean Localization:The trade ministry's import substitution programs are creating openings for domestic resist producers to displace Japanese suppliers in Samsung and SK Hynix qualification pipelines.
- Power Semiconductor Resurgence:Silicon carbide and gallium nitride device fabrication is expanding demand for i-line and g-line resists in automotive and energy applications.
- CHIPS Act Incentives:US domestic fab construction subsidies are accelerating material qualification protocols for resists at new Arizona and Texas manufacturing sites.
Industry Challenges
- EUV Resist Engineer Scarcity:The specialized skill set combining polymer chemistry, photochemical physics, and lithography process integration faces acute talent shortages across all major supply hubs.
- Multi-Year Qualification Cycles:Resist integration with scanner illumination systems and track hardware requires 18-36 month validation timelines that compress product lifecycle returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Photoresist Polymer Market |
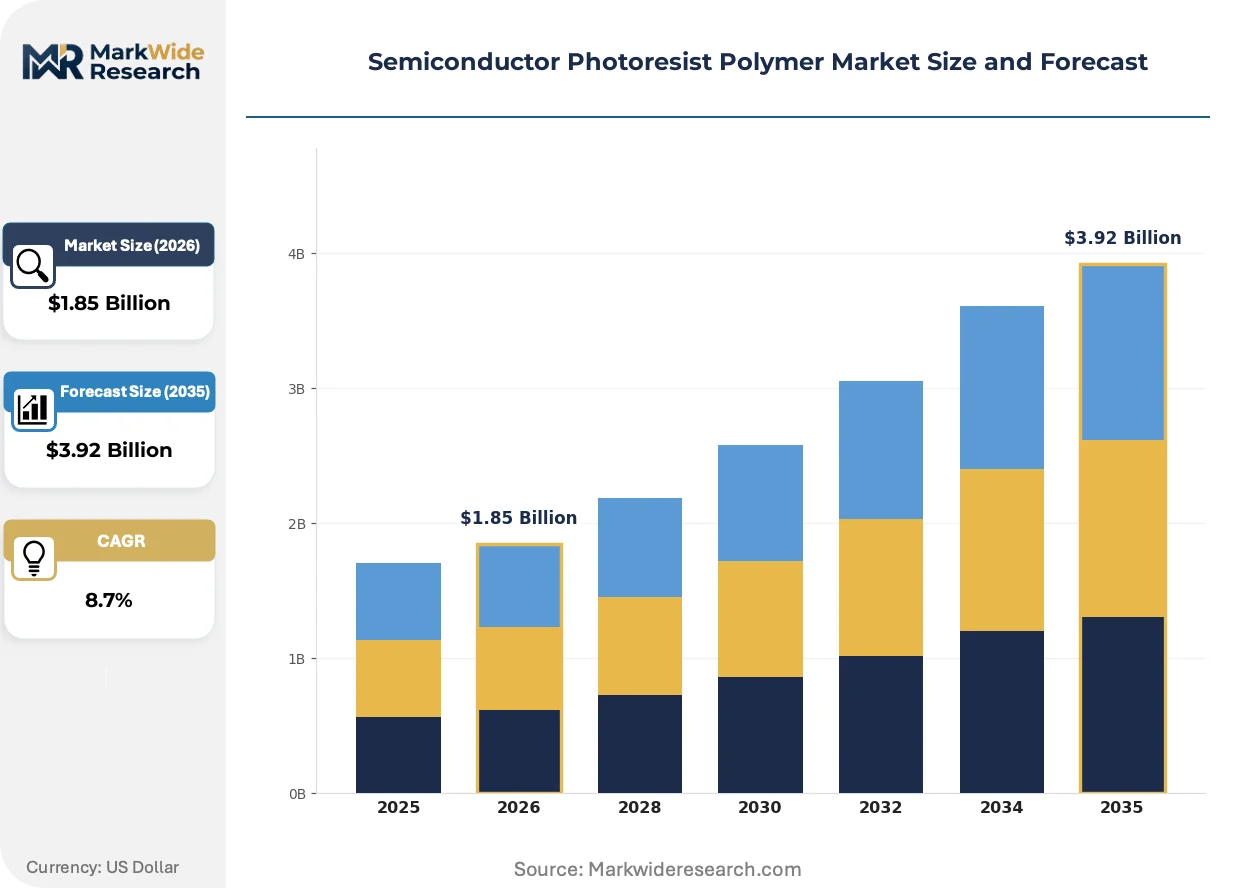
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Positive Photoresist, Negative Photoresist, Chemically Amplified Photoresist, Non-Chemically Amplified Photoresist End User: Microelectronics, Integrated Circuit Manufacturers, Memory Chip Manufacturers, Foundries Technology: Lithography, Etching, Deposition, Doping Application: Nanotechnology, Photovoltaics, Consumer Electronics, Telecommunications |
| Companies Covered | Tokyo Ohka Kogyo Co., Ltd., JSR Corporation, Shin-Etsu Chemical Co., Ltd., FUJIFILM Corporation, DuPont, Sumitomo Chemical Co., Ltd., Dongjin Semichem Co., Ltd., Merck Group, Mitsui Chemicals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Photoresist Polymer Market Trends and Innovations
Photoresist formulation architectures are fragmenting across wavelength-specific requirements, with EUV platforms demanding fundamentally different molecular designs than their DUV predecessors. Three concurrent developments are restructuring competitive positioning.
Metal oxide resists incorporating tin-oxo clusters are decomposing the historical dominance of organic polymer platforms in EUV applications. Leading-edge foundries in South Korea and Taiwan are accelerating adoption for high-NA lithography readiness. The shift is compressing incumbent suppliers' R&D amortization schedules while opening qualification windows for materials-science entrants.
The EU's F-Gas Regulation is restricting perfluorinated compound use in photoresist precursor synthesis, forcing reformulation of fluoropolymer-based dissolution inhibitors. Japanese suppliers are accelerating development of hydrocarbon alternatives to maintain EU market access. Memory fabs are experiencing the tightest formulation constraints due to their dependence on high-fluorine-content etch resistance layers.
Consolidated procurement through foundry-direct contracts is displacing merchant distributor channels for EUV-grade materials. Samsung and TSMC are centralizing resist qualification under captive supply agreements with volume guarantees. South Korea's Pyeongtaek cluster exhibits the most pronounced channel compression, with spot-market availability for leading-edge resists approaching zero.
Semiconductor Photoresist Polymer Market Segmentation
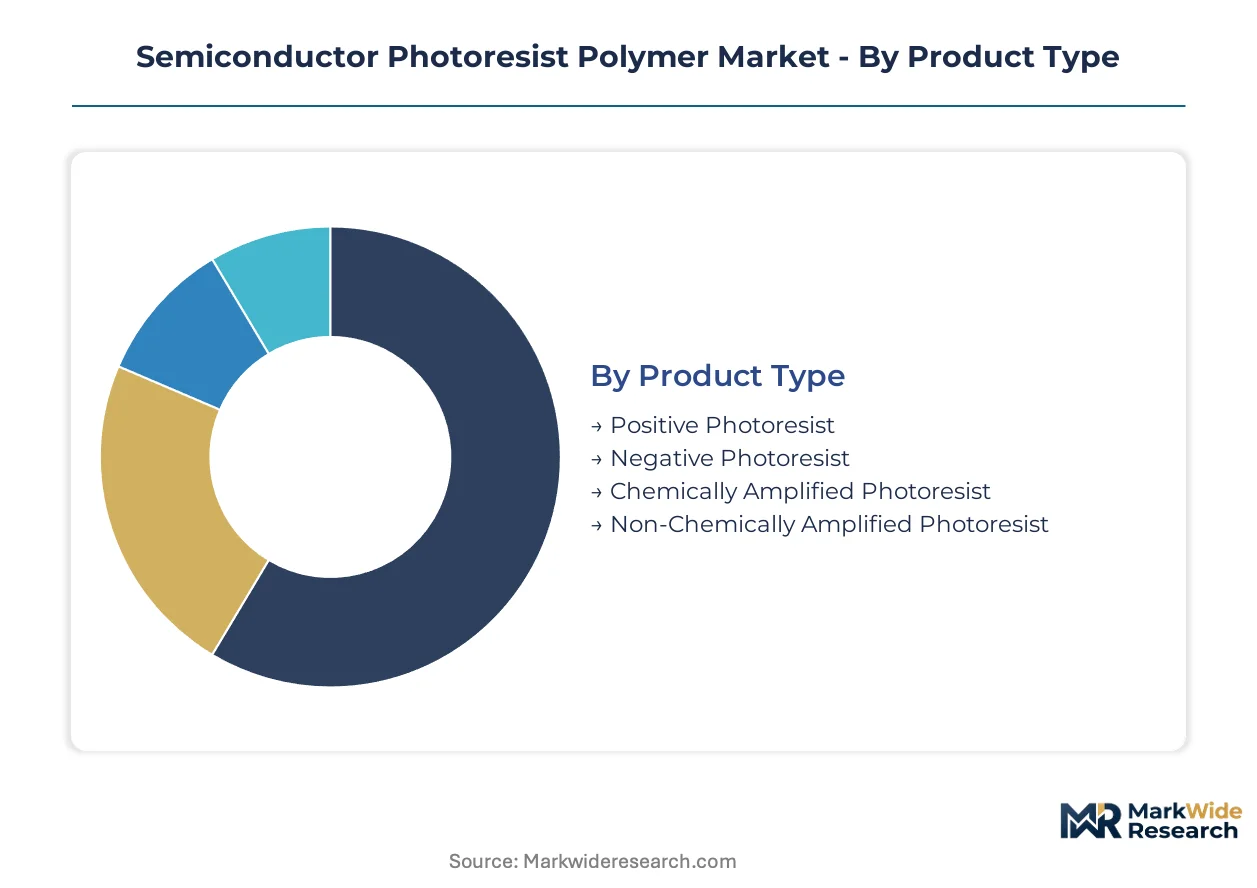
Photoresist polymer specification diverges sharply across lithography wavelengths and device architectures, requiring distinct qualification protocols for each segment. Procurement patterns in South Korea's Pyeongtaek cluster demonstrate how end-use concentration reshapes supplier priorities across these boundaries.
Product Type:
EPA chemical disclosure requirements under TSCA Section 8 impose differentiated compliance burdens across resist chemistries, extending qualification timelines for imported formulations entering US fabs.
- Chemically Amplified Photoresist:Catalytic deprotection mechanisms enable sub-7nm resolution through photoacid generator amplification. Leading-edge foundries in South Korea's Pyeongtaek cluster specify these formulations for EUV lithography deployment, though stochastic defect density constrains yield at pitches below 36nm.
- Positive Photoresist:Polyhydroxystyrene or acrylate derivative base resins undergo solubility switching upon exposure, dominating mature node foundries and power semiconductor fabs. Japan's METI export control frameworks concentrate high-purity monomer supply for these formulations.
- Negative Photoresist:Crosslinking-based insolubilization serves specialty MEMS and packaging applications where thick-film patterning exceeds positive-tone capabilities.
- Non-Chemically Amplified Photoresist:Direct photochemical conversion without acid catalysis persists in i-line and g-line legacy nodes where cost optimization governs purchasing.
Positive photoresist handles the majority of throughput; chemically amplified photoresist is the fastest mover on share.
End User:
Capital intensity bifurcation separates leading-edge procurement from trailing-node optimization, with memory manufacturers compressing expenditure while logic foundries accelerate EUV resist procurement.
- Foundries:Samsung and TSMC centralize resist qualification under captive supply agreements with volume guarantees, compressing spot-market availability for leading-edge materials toward zero.
- Memory Chip Manufacturers:Samsung and SK Hynix in South Korea's Pyeongtaek cluster face tightest formulation constraints from EU F-Gas Regulation due to dependence on high-fluorine-content etch resistance layers.
- Integrated Circuit Manufacturers:IDM facilities balance trailing-node cost efficiency against selective leading-edge migration for high-margin product lines.
- Microelectronics:Discrete device and sensor fabrication relies on mature lithography nodes with resist specifications emphasizing process stability over resolution extremes.
Foundries command the steepest pricing tiers; memory manufacturers are expanding procurement share fastest as DRAM layer counts multiply.
Technology:
Process integration requirements determine resist specification, with lithography governing molecular design while subsequent etching and deposition steps impose thermal and chemical stability demands.
- Lithography:EUV, ArF immersion, and KrF wavelength-specific formulations require distinct polymer architectures and photoacid generator selections.
- Etching:Resist pattern transfer durability depends on fluoropolymer dissolution inhibitor content, now restricted under EU F-Gas Regulation.
- Deposition:Thin-film stack compatibility constrains outgassing profiles during resist cure and patterning sequences.
- Doping:Ion implantation masking applications prioritize resist thickness uniformity and selectivity against implant species.
Lithography consumes the greatest resist volume; etching qualification is climbing the fastest as multi-patterning architectures proliferate.
Application:
End-market semiconductor content drives resist specification across consumer, industrial, and energy transition applications.
- Consumer Electronics:Smartphone and computing device processors demand leading-edge EUV resist for sub-7nm logic fabrication.
- Telecommunications:5G baseband and RF front-end modules require mixed-node resist portfolios spanning trailing-edge power management to advanced digital logic.
- Nanotechnology:Research and prototype fabrication tolerates higher cost-per-wafer resist formulations for exploratory patterning.
- Photovoltaics:Solar cell metallization patterning employs thick-film negative resists for electroplating mold applications.
Consumer electronics anchors volume demand; telecommunications is gaining share fastest from infrastructure buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese suppliers dominate export flows into South Korean and Taiwanese fabs, while US CHIPS Act subsidies redirect procurement patterns toward domestic qualification pipelines. Trade ministry programs in Seoul and Beijing accelerate local substitution efforts. Regulatory divergence between East Asian supply hubs and Western end markets reshapes manufacturing footprints.
Japan
Tokyo Ohka Kogyo and JSR Corporation anchor EUV-grade resist production through captive monomer supply chains. METI coordinates domestic supply security for photoresist precursors under export control frameworks restricting technology transfer. Osaka and Tokyo metropolitan clusters concentrate formulation R&D and high-purity chemical synthesis.
South Korea
Samsung and SK Hynix in Pyeongtaek drive leading-edge EUV resist consumption for DRAM and logic fabrication. The trade ministry accelerates local substitution programs to reduce import dependency on Japanese suppliers. Busan-Ulsan chemical complexes host emerging domestic resist producers targeting qualification pipelines.
United States
CHIPS Act subsidies accelerate material qualification protocols at new Arizona and Texas manufacturing sites. EPA chemical disclosure requirements under TSCA Section 8 extend timelines for imported resist formulations entering domestic fabs. Greater Phoenix and Austin metropolitan areas concentrate fab construction and supplier co-location.
Taiwan
TSMC centralizes resist qualification under captive supply agreements with volume guarantees, compressing spot-market availability. The Hsinchu Science Park anchors foundry demand for ArF immersion and EUV formulations. Kaohsiung industrial zones support chemical precursor distribution infrastructure.
Germany
Merck Group headquarters in Darmstadt coordinates European resist distribution and fluoropolymer precursor development. The EU's F-Gas Regulation tightens fluoropolymer supply chains, forcing reformulation of dissolution inhibitors. Bavaria's chemical corridor hosts specialty polymer R&D for automotive and industrial semiconductor applications.
Semiconductor Photoresist Polymer Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and captive supply arrangements. The vendor base stratifies into three tiers: integrated chemical conglomerates with backward control over monomer production, independent resist formulators dependent on merchant raw material supply, and emerging regional challengers backed by state industrial policy. Strategic moves concentrate on multi-year qualification partnerships with foundry customers and geographic expansion through fab-adjacent formulation facilities.
Within the integrated chemical conglomerate tier, Tokyo Ohka Kogyo Co., Ltd., JSR Corporation, and Shin-Etsu Chemical Co., Ltd. exemplify the archetype of suppliers combining high-purity monomer synthesis with finished resist formulation. These Japan-based entities occupy positions where captive supply chains for EUV-grade raw materials create defensive moats against merchant competitors. Dongjin Semichem Co., Ltd. represents the emerging regional challenger archetype, situating within South Korea's import substitution push to displace incumbent suppliers in Samsung and SK Hynix qualification pipelines.
| Leading Market Players |
|---|
| Tokyo Ohka Kogyo Co., Ltd. |
| JSR Corporation |
| Shin-Etsu Chemical Co., Ltd. |
| FUJIFILM Corporation |
| DuPont |
| Sumitomo Chemical Co., Ltd. |
| Dongjin Semichem Co., Ltd. |
| Merck Group |
| Mitsui Chemicals, Inc. |
| Others |
Pricing and Supply Chain Analysis
EPA chemical disclosure requirements under TSCA Section 8 gate both supply qualification timelines and price differentiation across photoresist tiers, compressing margins for non-compliant imports while amplifying premiums for pre-qualified formulations. Buyers face extended validation cycles that embed regulatory compliance costs into contract structures, separating captive supply agreements from spot-market transactions.
Pricing Analysis
EUV-grade resist formulations command substantial premiums over ArF immersion predecessors, while legacy i-line and g-line segments face cost compression from power semiconductor procurement optimization. Three-tier pricing structure across premium EUV, standard DUV, and economy mature-node levels stratifies by resolution capability and qualification status. Pricing pressure stems from South Korean localization programs accelerating domestic substitution bids. Memory chip manufacturers exhibit highest price sensitivity due to capital expenditure compression, whereas leading-edge foundries prioritize yield stability over unit cost.
Supply Chain Analysis
Inventory buffers for high-purity monomers have tightened to multi-week levels as Japanese suppliers constrain spot-market releases under METI coordination. Raw material supply concentrates in Japan, South Korea, and Germany, drawing from fluoropolymer precursors, photoacid generators, and dissolution inhibitor feedstocks. Single-source vulnerability pervades EUV-grade monomer supply, with Tokyo Ohka Kogyo and JSR Corporation controlling critical precursor synthesis. Distribution runs through foundry-direct captive agreements, displacing merchant channels for leading-edge materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Samsung and TSMC's consolidated procurement, fragmenting supplier negotiating leverage as spot-market access vanishes for EUV-grade materials.
For Market Incumbents: Shield qualification pipelines through accelerated captive capacity expansion in South Korea's Pyeongtaek cluster and Busan-Ulsan chemical corridors. Deepen backward integration into high-purity monomer synthesis to preempt domestic substitution threats from Dongjin Semichem. Secure volume guarantees with foundry partners before localization programs mature. For New Entrants and Emerging Players: Differentiate on fluoropolymer-free formulation architectures that bypass EU F-Gas Regulation constraints affecting Japanese incumbents. Target power semiconductor fabs in automotive and energy applications where i-line and g-line resist specifications emphasize process stability over resolution extremes. Pursue qualification partnerships with IDM facilities balancing trailing-node cost efficiency against selective leading-edge migration. For Investors and Strategic Acquirers: The EU F-Gas Regulation reshapes the acquisition landscape by devaluing fluoropolymer-dependent formulation assets while elevating hydrocarbon-alternative R&D capabilities. Long-term viability centers on materials-science entrants with metal oxide resist platforms for high-NA lithography readiness. Monitor South Korean trade ministry subsidy disbursements as inflection indicator for domestic supplier maturation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Synthesis | Captive supply of high-purity precursors defends against METI export control disruptions and South Korean localization. |
| Fluoropolymer-Free Formulation Development | Hydrocarbon alternatives maintain EU market access under tightening F-Gas Regulation constraints on perfluorinated compounds. |
| Foundry-Direct Captive Supply Agreements | Volume guarantees with Samsung and TSMC preempt spot-market elimination and lock in multi-year revenue visibility. |
| Metal Oxide Resist Platform Investment | Tin-oxo cluster architectures address stochastic defect density limits constraining organic polymer EUV yields below 36nm pitches. |
| South Korean Manufacturing Footprint Expansion | Busan-Ulsan facility proximity accelerates qualification with Samsung and SK Hynix under import substitution programs. |
Research Methodology
Initial hypotheses were tested against primary input from resist formulation chemists, foundry procurement directors, lithography process integration engineers, and semiconductor trade ministry officials, and refined through secondary validation against SEC 10-K filings, customs/trade data, METI export control notifications, and EU regulatory filings. Bottom-up modeling of resist consumption by fab capacity and technology node combined with top-down triangulation against chemical industry revenue disclosures anchored volume estimates.
Variance decomposition across wavelength-specific segments, end-user capital intensity tiers, and regional regulatory clusters structured the analytical framework over the projection horizon. CAGRs derived from segment-level demand elasticity modeling and foundry capex pipeline analysis incorporated EUV scanner deployment schedules, DRAM layer count multiplication trajectories, and power semiconductor substrate transition timelines.
The analysis sits within stated boundaries; outcomes outside sustained leading-edge logic foundry expansion or abrupt fluoropolymer supply disruption would require recalibration. Forecasts reflect documented assumptions regarding qualification timeline durations, regulatory enforcement intensity, and substitution elasticity parameters. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Gan Substrate and Gan Wafer Market
Semiconductor Fabrication
Global Atomic Layer Deposition Market
Semiconductor Fabrication
Etching Machine Market
Semiconductor Fabrication
Deep Reactive Ion Etching (DRIE) Etcher Market
Semiconductor Fabrication
Porous Silicon Substrates Market
Semiconductor Fabrication
Global Dielectric Etchers Market
Semiconductor Fabrication
North America Atomic Layer Deposition Market
Semiconductor Fabrication
Semiconductor Etching Cleaner Market
Semiconductor Fabrication
Thin Layer Deposition Market
Semiconductor Fabrication
Holmium Sputtering Target Market
Semiconductor Fabrication
Semiconductor Foundry Market
Semiconductor Fabrication
Global Spark Plasma Sintering Market
Semiconductor Fabrication
Vapor Deposition Market
Semiconductor Fabrication
Epitaxial Wafer Market
Semiconductor Fabrication
Additive Manufacturing in Semiconductor Market
Semiconductor Fabrication
Global Micromachining Market