
 Additive Manufacturing in Semiconductor Market | 2026-2036
Additive Manufacturing in Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
Additive Manufacturing in Semiconductor Market Insights
REACH chemical authorization is recalibrating the cost-of-entry calculus for European material suppliers serving semiconductor fabs. EOS GmbH leverages its polymer laser sintering expertise to sustain qualification programs for high-purity PEEK compounds in wafer transport applications. GE Additive anchors its position through controlled-atmosphere electron beam melting systems that compete for nickel superalloy showerhead production in advanced node equipment.
Additive manufacturing in semiconductors encompasses the layer-by-layer fabrication of functional components—ranging from 25-micron resolution ceramic fixtures to topology-optimized aluminum gas distribution plates—for process equipment, packaging substrates, and cleanroom tooling. The primary purpose is to merge geometric complexity with material performance, eliminating multi-part assemblies while meeting SEMI-standard surface roughness and outgassing requirements. Materials and services dominate current revenue capture, with ceramics and refractory metal powders commanding premium positioning due to plasma-chamber compatibility demands. Selective laser sintering leads technology deployment for end-use parts, while binder jetting extends fastest in copper heat sink prototyping where sintering furnace throughput determines unit economics.
EPA emissions protocols for perfluorinated compounds in US fabrication facilities are forcing equipment OEMs to redesign chamber components with additive-produced lattice structures that reduce cleaning chemical consumption. Japan's METI semiconductor revitalization framework and China's GB standards for industrial 3D printing equipment collectively shape cross-border qualification timelines for exported tools. Stakeholders must monitor divergence between regional material certification regimes before committing to single-source powder supply agreements.
Market Dynamics
EUV lithography node shrinkage below 3nm is concentrating demand for topology-optimized wafer handling tooling that conventional machining cannot produce at required precision.
Growth Catalysts
- EPA perfluorinated compound protocols:US fabrication facilities face mandated reductions in chamber cleaning chemical consumption, accelerating redesign cycles for lattice-structured gas distribution plates.
- Advanced substrate interposers:East Asian packaging hubs require conformal cooling channels with geometries achievable only through binder-jetted copper heat sinks.
- Taiwan-South Korea foundry expansion:Leading-edge fabs are qualifying 3D-printed ceramic fixtures for plasma chamber compatibility at sub-5nm nodes.
Market Restraints
- High-purity powder supply concentration:Refractory metal feedstock for semiconductor-grade applications sources predominantly from Chinese state-owned refiners, creating single-point vulnerability.
- REACH authorization timelines:European chemical qualification for photopolymer resins extends 18-24 months, freezing material development pipelines for wafer transport applications.
- Surface roughness specification gaps:SEMI-standard Ra 0.4 µm requirements exceed as-printed capabilities of most metal additive systems without secondary finishing.
Strategic Opportunities
- India PLI scheme for semiconductors:Domestic packaging substrate manufacturing incentives create first-mover positioning for additive tooling suppliers establishing local powder processing.
- Copper-silver bimetallic convergence:Hybrid thermal management structures combining binder-jetted copper cores with electroplated silver surfaces address next-generation chiplet packaging thermal density.
- Japan METI revitalization framework:Equipment localization mandates for critical process tools open qualification pathways for domestic additive manufacturers in showerhead and chamber liner segments.
Industry Challenges
- Multi-physics simulation talent scarcity:Topology optimization for thermal-mechanical-electromagnetic coupled performance requires specialized computational design capabilities absent from traditional semiconductor equipment engineering pipelines.
- SEMI S2/S8 certification complexity:Safety and ergonomics compliance for additive-produced vacuum chamber components lacks established precedent, extending validation timelines.
- Legacy ERP integration friction:Digital thread connectivity between additive build management systems and incumbent semiconductor fab MES platforms requires custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Additive Manufacturing in Semiconductor Market |
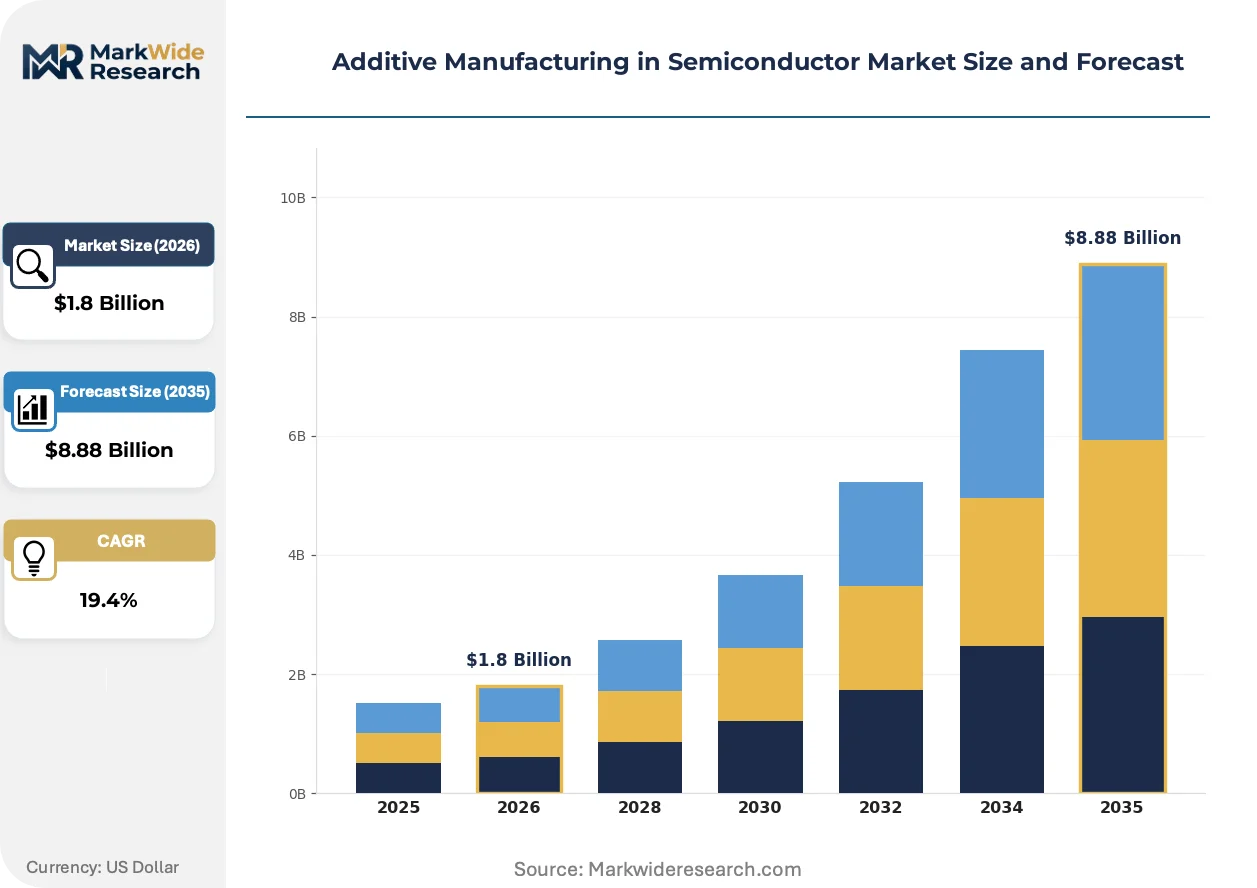
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Printers, Materials, Software, Services Technology: Fused Deposition Modeling, Selective Laser Sintering, Stereolithography, Binder Jetting Application: Prototyping, Tooling, Production Parts, Customization End User: OEMs, Foundries, Research Institutions, Aftermarket Providers |
| Companies Covered | 3D Systems Corporation, GE Additive, EOS GmbH, Stratasys Ltd, Desktop Metal Inc., Materialise NV, Renishaw plc, Optomec Inc., SLM Solutions Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Additive Manufacturing in Semiconductor Market Trends and Innovations
Multi-laser powder bed fusion architectures are compressing build-cycle economics for nickel superalloy showerheads while ceramic stereolithography advances fixture resolution thresholds.
Multi-laser powder bed fusion is decentralizing production economics for complex refractory metal components. Leading equipment OEMs are adopting 16-laser configurations for showerhead prototypes, collapsing lead times from 14 weeks to 72 hours. This capability is decentralizing geographic concentration of high-value chamber component supply away from traditional precision casting centers.
REACH chemical authorization is recalibrating material development priorities across European supply chains. The ECHA's evolving substance of very high concern listings are disqualifying legacy photopolymer formulations from wafer transport applications. German material suppliers are accelerating bio-based resin qualification programs to preempt regulatory displacement.
Direct equipment purchase models are fragmenting into performance-based service arrangements. Foundries in Taiwan are contracting additive tooling on throughput-guaranteed terms rather than capitalizing hardware ownership. This shift is most visible in high-mix, low-volume R&D line environments where utilization uncertainty discourages fixed asset deployment.
Additive Manufacturing in Semiconductor Market Segmentation
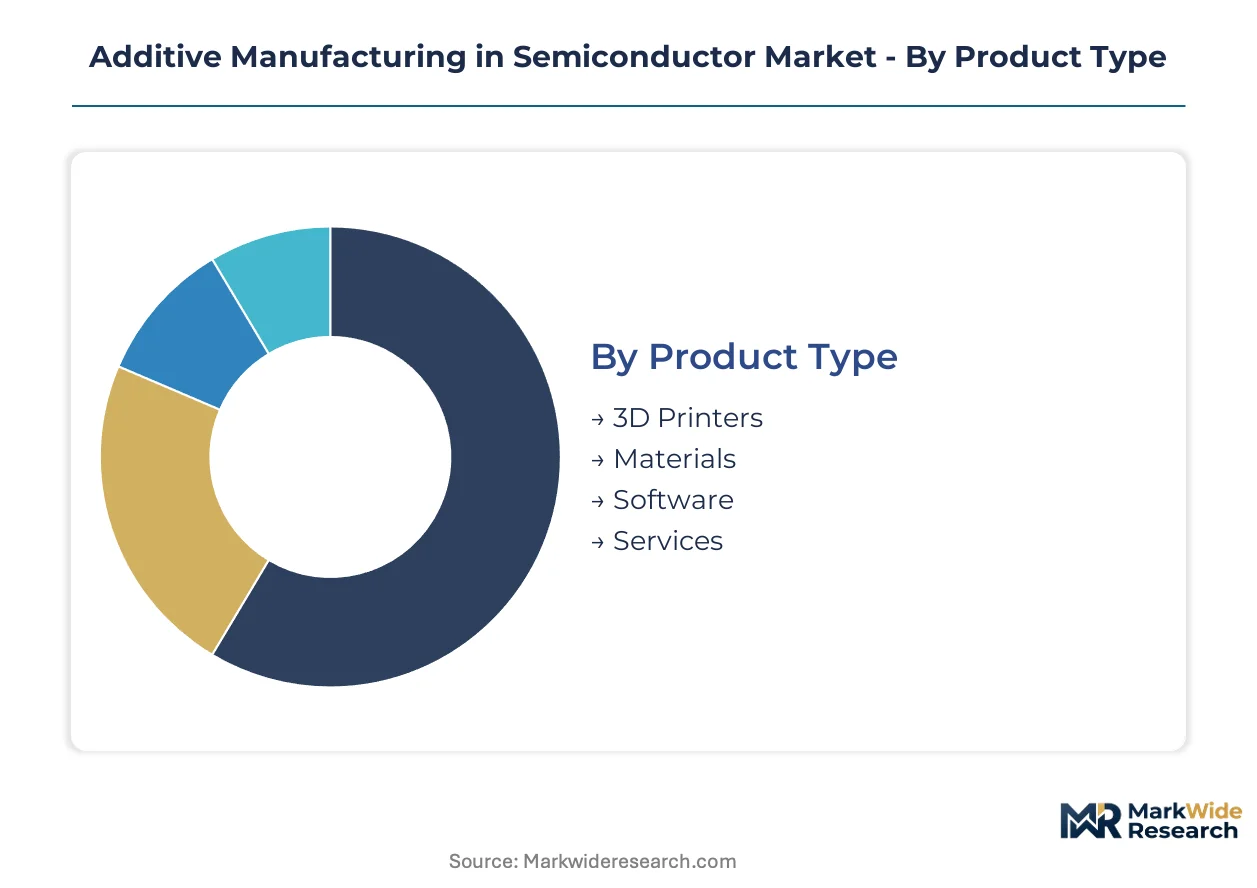
Equipment upgrade cycles in semiconductor fabs determine how additive manufacturing solutions penetrate process tooling, packaging substrates, and cleanroom infrastructure. Segmentation reveals where capital deployment concentrates across hardware, consumables, and value-added services.
Product Type:
Replacement timelines for legacy subtractive equipment accelerate as EUV node transitions demand geometries impossible through conventional machining.
- Materials:High-purity ceramic and refractory metal powders command premium positioning due to plasma-chamber compatibility requirements at sub-5nm nodes. Taiwan and South Korea foundries consume the largest volumes as they expand 3D-printed wafer handling tool qualification programs.
- Services:Contract manufacturing and qualification support capture growing share as foundries shift from capital ownership to throughput-guaranteed arrangements. EOS GmbH and GE Additive anchor their positions through sustained material qualification programs rather than pure hardware sales.
- 3D Printers:Multi-laser powder bed fusion systems target showerhead and gas distribution plate production with 16-laser configurations collapsing lead times from 14 weeks to 72 hours.
- Software:Topology optimization and build management platforms bridge digital thread connectivity gaps with incumbent semiconductor fab MES systems.
Materials sits at the top of the volume ranking, with Services climbing the fastest.
Technology:
Cost tier differentiation separates high-throughput production systems from prototyping platforms serving R&D line environments.
- Selective Laser Sintering:Polymer laser sintering dominates end-use part production for wafer transport applications, with PEEK compounds sustaining qualification against REACH chemical authorization pressures. German material suppliers accelerate bio-based resin programs to preempt regulatory displacement.
- Binder Jetting:Copper heat sink prototyping expands fastest where sintering furnace throughput determines unit economics for conformal cooling channels in advanced substrate interposers. East Asian packaging hubs concentrate demand as thermal density requirements intensify.
- Stereolithography:Ceramic stereolithography advances fixture resolution thresholds for 25-micron precision applications in plasma chamber environments.
- Fused Deposition Modeling:Entry-tier systems serve early-stage design validation before transfer to production-capable platforms.
Selective Laser Sintering holds the largest installed base, though Binder Jetting gains share fastest in thermal management applications.
Application:
Customer maturity curves separate speculative prototyping from qualified production workflows with SEMI-standard surface roughness compliance.
- Production Parts:Topology-optimized aluminum gas distribution plates and nickel superalloy showerheads address EPA-mandated reductions in perfluorinated compound consumption through lattice-structured designs. US fabrication facilities drive redesign cycles as emissions protocols tighten.
- Tooling:Ceramic fixtures and conformal cooling channels for advanced packaging substrates concentrate demand in Taiwan, South Korea, and Japan where METI localization mandates open qualification pathways.
- Prototyping:R&D lines in research institutions and leading-edge foundries validate geometries before production transfer.
- Customization:Low-volume adaptations for specific chamber configurations serve aftermarket providers and specialty equipment OEMs.
Production Parts leads value capture, with Tooling expanding most quickly as packaging complexity intensifies.
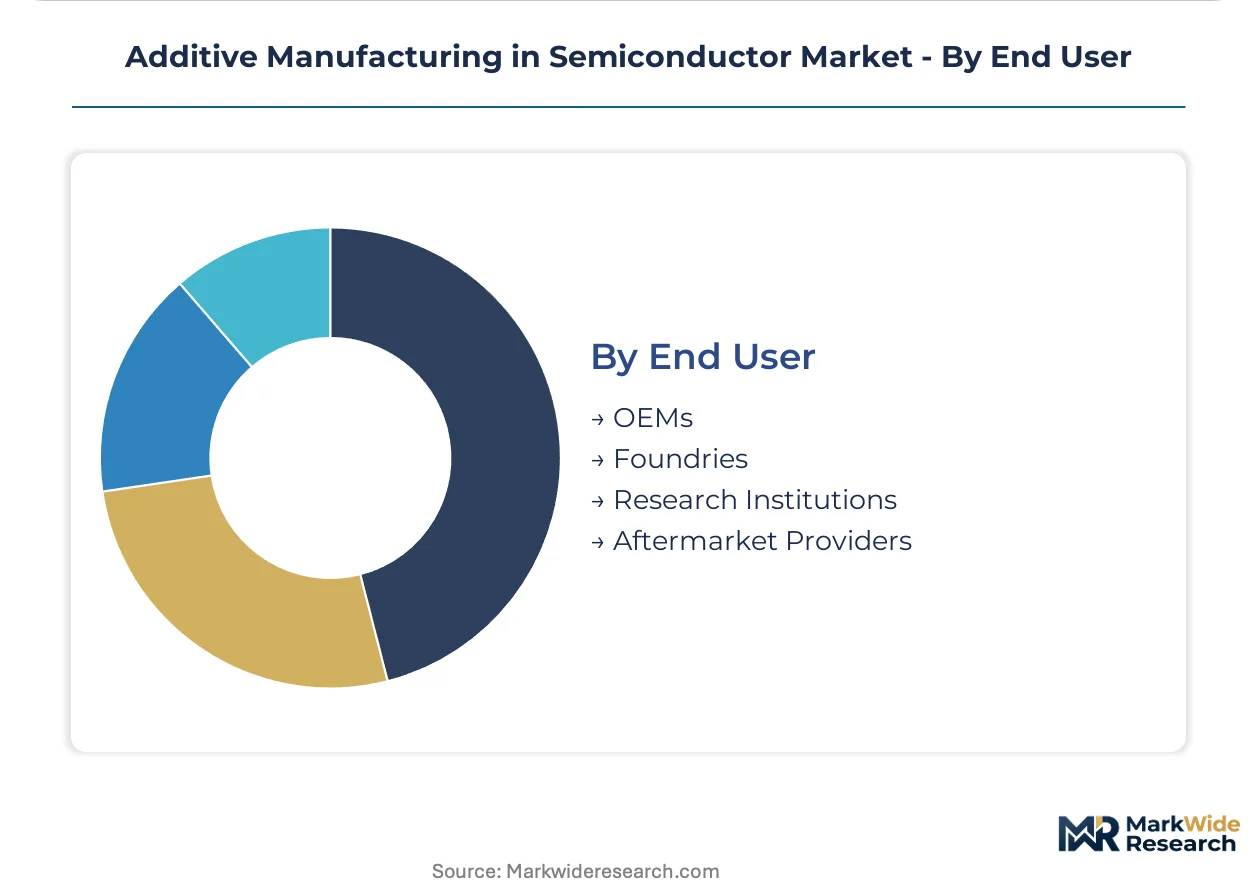
End User:
Procurement authority and technical capability determine whether additive manufacturing deploys through in-house integration or outsourced service models.
- Foundries:Taiwan and South Korea leaders qualify 3D-printed components for EUV lithography nodes below 3nm, contracting additive tooling on throughput-guaranteed terms rather than capitalizing hardware ownership.
- OEMs:Applied Materials and Lam Research anchor demand for chamber components with SEMI S2/S8 certification requirements, though validation timelines lack established precedent for additive-produced vacuum parts.
- Research Institutions:University and national laboratory programs bridge multi-physics simulation talent scarcity through external partnerships.
- Aftermarket Providers:Spare part replacement and legacy equipment retrofit concentrate in regions with established semiconductor manufacturing infrastructure.
Foundries command the largest procurement volumes, while OEMs deepen integration fastest as certification frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized additive manufacturing engineers cluster around established semiconductor ecosystems in Taiwan, South Korea, Germany, Japan, and the United States. These talent concentrations anchor regional capability development for high-purity powder processing and topology optimization workflows. Regulatory divergence across these jurisdictions shapes qualification timelines for exported tooling.
Taiwan
Leading-edge foundries in Hsinchu Science Park qualify 3D-printed ceramic fixtures for EUV lithography nodes below 3nm. The National Science and Technology Council prioritizes domestic additive manufacturing capacity under its semiconductor revitalization programs. Kaohsiung packaging hubs drive conformal cooling channel demand for advanced substrate interposers.
South Korea
Samsung and SK Hynix expand adoption of topology-optimized wafer handling tools as memory process nodes advance. METI-equivalent Korean industrial policy channels funding through the Ministry of Trade, Industry and Energy for equipment localization. Pangyo and Yongin semiconductor clusters concentrate binder jetting qualification programs for copper thermal management components.
Germany
EOS GmbH and specialized material suppliers anchor European laser sintering expertise for high-purity PEEK compounds in wafer transport applications. REACH chemical authorization through ECHA extends 18-24 month timelines for photopolymer resin qualification. Munich and Stuttgart industrial regions host the continent's densest concentration of SEMI-standard certification capabilities.
Japan
Tokyo Electron and domestic equipment OEMs drive showerhead and chamber liner demand under METI semiconductor revitalization framework localization mandates. Nagoya and Kyushu manufacturing belts concentrate electron beam melting system deployments for nickel superalloy components. JIS standards for industrial 3D printing equipment shape cross-border export qualification requirements.
United States
Applied Materials and Lam Research anchor OEM demand for lattice-structured gas distribution plates addressing EPA perfluorinated compound emission reductions. Oregon and Arizona fabrication corridors concentrate multi-laser powder bed fusion adoption for rapid showerhead prototyping. OSHA and SEMI S2/S8 compliance frameworks extend validation timelines for additive-produced vacuum chamber components.
Additive Manufacturing in Semiconductor Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment, materials, and services segments. The vendor structure stratifies into three tiers: integrated industrial conglomerates with captive additive divisions, dedicated hardware manufacturers with materials partnerships, and pure-play service bureaus targeting qualification-heavy semiconductor applications. Dominant competitive moves include strategic partnerships for powder supply security and technology licensing for multi-laser system architectures.
Within the integrated industrial tier, GE Additive and 3D Systems Corporation exemplify scale-driven positioning through controlled-atmosphere electron beam melting and polymer laser sintering platforms respectively. EOS GmbH occupies a specialist position anchored in sustained material qualification programs rather than pure hardware sales. These three entities represent divergent strategic postures: conglomerate-backed vertical integration, diversified technology platform breadth, and focused materials-services hybridization.
| Leading Market Players |
|---|
| 3D Systems Corporation |
| GE Additive |
| EOS GmbH |
| Stratasys Ltd |
| Desktop Metal Inc. |
| Materialise NV |
| Renishaw plc |
| Optomec Inc. |
| SLM Solutions Group AG |
| Others |
Pricing and Supply Chain Analysis
Refractory metal powder spot indices in tungsten and molybdenum cascade through semiconductor-grade supply chains into three distinct pricing tiers: captive foundry programs, qualified service bureau contracts, and spot-market prototyping engagements. REACH compliance costs and EPA emissions retrofit requirements amplify spreads between European and Asian sourcing channels.
Pricing Analysis
Service unbundling separates hardware-as-a-service arrangements from capital equipment sales across Taiwanese and South Korean foundry procurement. Three-tier pricing structure across premium, standard, and economy levels reflects SEMI certification grade, volume commitment scale, and after-sales qualification support. Pricing pressure stems from multi-laser system throughput improvements compressing unit economics for nickel superalloy showerheads. R&D line managers exhibit highest price sensitivity due to utilization uncertainty, while production engineering teams prioritize qualification speed over per-unit cost.
Supply Chain Analysis
Regional distribution centers in Kaohsiung, Yongin, and Stuttgart anchor hub-and-spoke fulfillment for high-purity ceramic and refractory metal powders. Supply concentration in China, Germany, and the United States creates single-source vulnerability for semiconductor-grade tungsten feedstock. Raw material flows draw from Chinese state-owned refiners, German specialty chemical producers, and US domestic powder atomization facilities. Tariff exposure on refractory metal imports from China threatens cost structures for US-based equipment OEMs. Distribution runs through qualified logistics partners with cleanroom-compatible handling capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH authorization timelines in Europe extend 18-24 months against 6-9 month qualification windows in East Asia, creating cost and speed differentials for material suppliers.
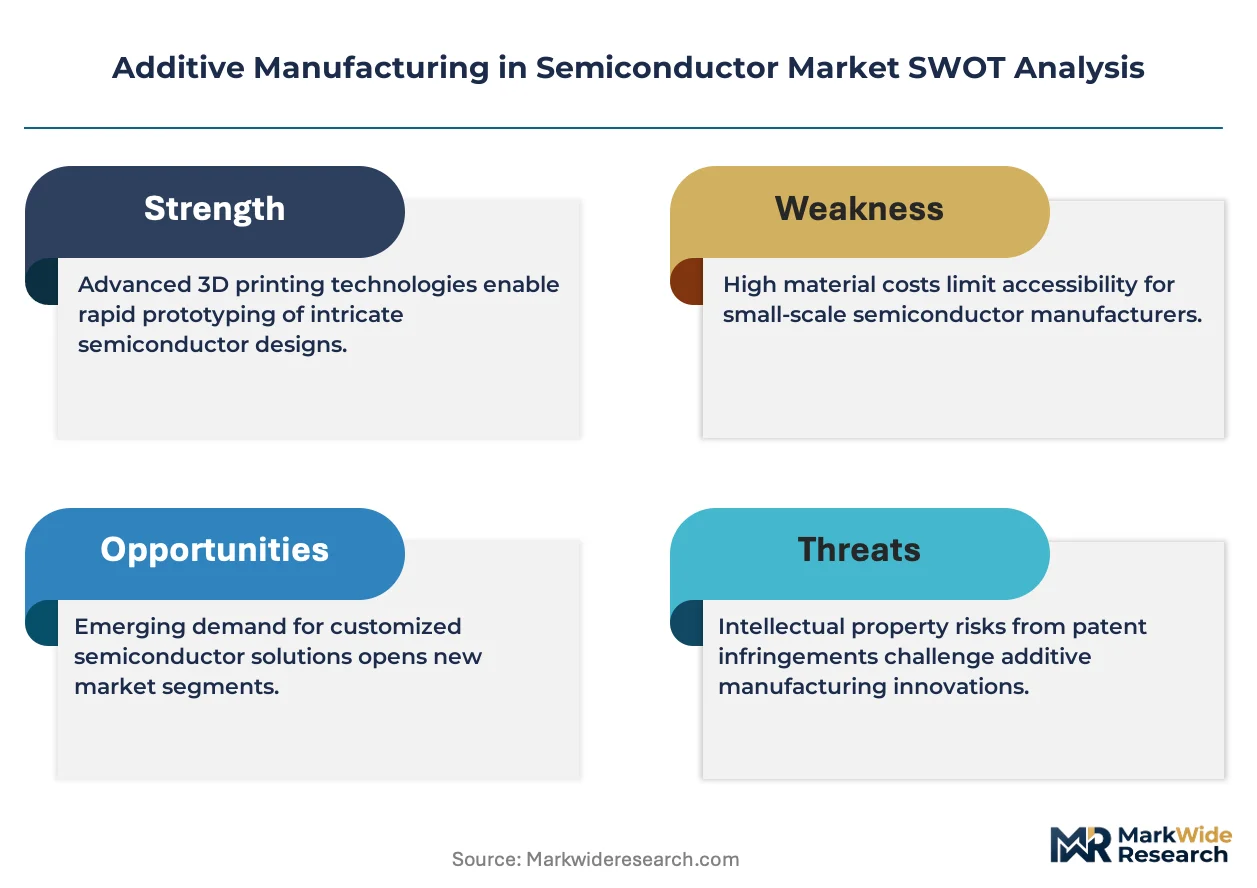
For Market Incumbents: Anchor qualification pipelines through sustained material development programs rather than pure hardware sales to defend against emerging pure-play service bureaus. Deepen backward integration into high-purity powder atomization to secure feedstock against Chinese refiner concentration risk. Prioritize SEMI S2/S8 certification investment to extend validation timelines for additive-produced vacuum components. For New Entrants and Emerging Players: Capture India PLI scheme incentives for domestic packaging substrate manufacturing before incumbent powder processors establish local presence. Target copper-silver bimetallic thermal management structures as the most penetrable segment where hybrid fabrication expertise remains scarce. Pursue throughput-guaranteed service contracts rather than capital sales to bypass foundry CAPEX approval cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized material qualification firms possessing ECHA pre-registration dossiers and SEMI-standard surface roughness capabilities. Five-to-ten year viability hinges on regulatory divergence persisting between REACH and EPA emission protocols. Watch for METI localization mandate acceleration as the inflection signal for Japanese domestic additive manufacturing demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Atomization | Captive tungsten and molybdenum feedstock supply secures margin against Chinese refiner concentration. |
| Multi-Laser System Architecture Licensing | 16-laser configurations collapse showerhead lead times from 14 weeks to 72 hours for foundry customers. |
| Bio-Based Resin Qualification Program | Preemptive ECHA compliance positioning displaces legacy photopolymer formulations under REACH SVHC listings. |
| Throughput-Guaranteed Service Contracts | Performance-based arrangements bypass foundry CAPEX constraints in high-mix R&D line environments. |
| SEMI S2/S8 Certification Precedent Establishment | First-mover safety validation for additive vacuum components extends competitive moats against late entrants. |
Research Methodology
Coverage spans Taiwan, South Korea, Germany, Japan, and the United States, with primary inputs from each region combining foundry process engineering directors, equipment OEM procurement leads, additive manufacturing service bureau operators, and ECHA regulatory affairs specialists. Secondary validation draws from EPA emissions protocol filings, METI semiconductor revitalization framework documents, SEMI standards publications, and customs trade data for refractory metal powder flows. Bottom-up build aggregation and top-down market sizing triangulate volume estimates across the analysis window.
Rate-of-change decomposition separates equipment upgrade cycle timing, node transition acceleration, and regulatory implementation phasing across the projection horizon. Segmentation dimensions include product type, technology platform, application maturity, and end-user procurement authority. CAGRs derive from installed base expansion curves and replacement timeline compression. Forecast inputs incorporate EUV lithography node roadmaps and REACH authorization pipeline visibility.
Node transition delays, REACH SVHC listing acceleration, and powder supply disruption are the dominant revision risks for model outputs. Forecasts reflect documented assumptions regarding regulatory implementation timelines and equipment qualification success rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Global Spark Plasma Sintering Market
Semiconductor Fabrication
Global Dry Etching Machine Market
Semiconductor Fabrication
Global Dielectric Etchers Market
Semiconductor Fabrication
Semiconductor Fab Water Reuse Systems Market
Semiconductor Fabrication
North America Atomic Layer Deposition Market
Semiconductor Fabrication
Global Foundry Service Market
Semiconductor Fabrication
300mm Silicon Wafers Market
Semiconductor Fabrication
Manual Wafer Aligner Market
Semiconductor Fabrication
Vapor Deposition Market
Semiconductor Fabrication
Mask Alignment Lithography Market
Semiconductor Fabrication
Global Atomic Layer Deposition Market
Semiconductor Fabrication
Etchant for FPD Market
Semiconductor Fabrication
Porous Silicon Substrates Market
Semiconductor Fabrication
Global Micromachining Market
Semiconductor Fabrication
Semiconductor Logistics Market
Semiconductor Fabrication
8-Inch Silicon Carbide (Sic) Wafer Market