
 Europe Silicon Carbide Wafers Market | 2026-2036
Europe Silicon Carbide Wafers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Silicon Carbide Wafers Market Foresight
Italy is reshaping regional supply dynamics through expanding SiC substrate fabrication clusters. STMicroelectronics leverages integrated manufacturing from crystal growth to epitaxy near Catania. Infineon Technologies AG anchors German demand with power module packaging tied to domestic wafer sourcing. SiCrystal specializes in high-purity 150mm substrates for premium automotive contracts.
Europe silicon carbide wafers are synthetic crystalline substrates produced via physical vapor deposition or chemical vapor deposition, typically specified by polytype, micropipe density, and diameter for high-temperature, high-frequency power switching. Their primary commercial purpose is to replace silicon in power electronics where breakdown voltage and thermal conductivity requirements exceed conventional semiconductor limits. Round wafers dominate volume production due to equipment compatibility across epitaxial growth and device fabrication lines. Power electronics applications capture the deepest margin pools because automotive and industrial buyers qualify suppliers over multi-year certification cycles. Epitaxial growth technology leads process differentiation as thickness uniformity and defect control determine device yield.
REACH compliance and the EU Green Deal shape material sourcing and energy disclosure obligations for wafer manufacturers operating within Europe. ECHA substance restrictions and CE marking requirements for power modules filter downstream into substrate specifications and traceability systems. Stakeholders must monitor how F-Gas Regulation amendments affect etching chemistry availability and cleanroom process costs across European fabrication sites.
Market Dynamics
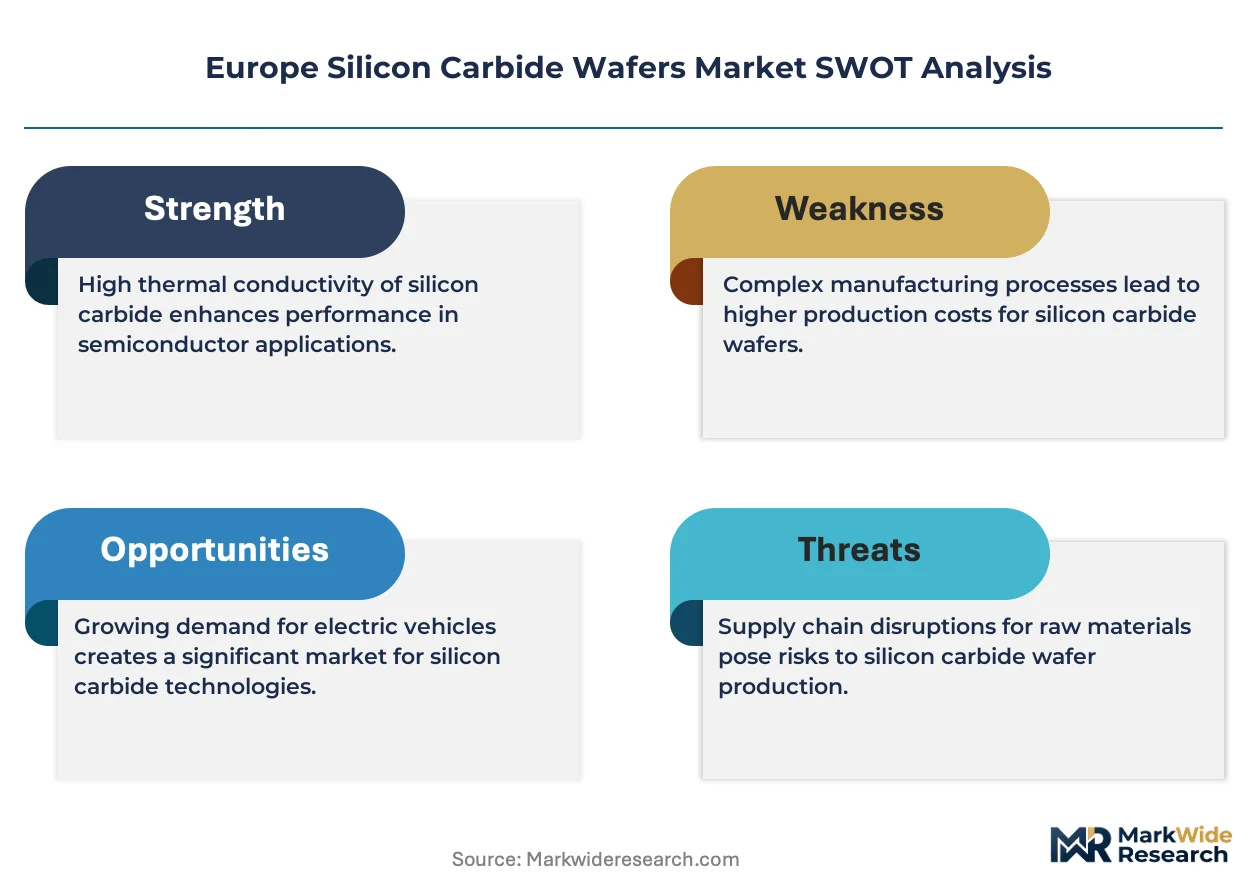
The EU Green Deal and F-Gas Regulation are compressing qualification timelines for wide-bandgap semiconductors, forcing automotive OEMs to lock in SiC substrate supply chains ahead of silicon IGBT phase-outs. This regulatory pressure is concentrating procurement power among Tier-1 suppliers with established European wafer partnerships.
Growth Catalysts
- EU Green Deal carbon mandates:The framework's 2050 climate neutrality target accelerates powertrain electrification, pulling SiC wafer demand into high-voltage inverter and onboard charger applications.
- Automotive 800V architectures:Premium EV platforms specify SiC MOSFETs for efficiency gains, creating dedicated substrate demand that silicon cannot satisfy.
- German OEM supplier density:Concentrated engineering resources in Stuttgart and Munich enable rapid co-development cycles between wafer growers and power module packagers.
Market Restraints
- High-purity silicon feedstock volatility:Polysilicon price swings and energy-intensive purification constrain substrate cost reduction trajectories.
- 150mm substrate supply concentration:Limited qualified European crystal growth capacity creates allocation risk for automotive qualification programs.
- Physical vapor transport yield ceilings:Micropipe density reduction hits diminishing returns, capping usable area per boule and inflating effective wafer cost.
Strategic Opportunities
- Eastern European fabrication greenfield:Greenfield sites in Romania and Czechia offer lower energy costs and proximity to German automotive clusters for epitaxy expansion.
- Renewable energy inverters:Offshore wind and solar string inverter deployments create parallel demand for high-voltage SiC devices outside automotive.
- CE marking pre-certification services:Wafer suppliers bundling traceability documentation and REACH compliance data capture margin from risk-averse industrial buyers.
Industry Challenges
- Crystal growth technician scarcity:Europe lacks training pipelines for physical vapor transport operators, constraining capacity expansion at existing facilities.
- Automotive AQAP-2120 qualification timelines:Multi-year device validation cycles lock working capital and demand forecasting accuracy from wafer suppliers.
- Epitaxy-to-device fabrication handoff complexity:Defect propagation across the substrate-epi-device stack requires coordinated yield management that few supply chains have mastered.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Silicon Carbide Wafers Market |
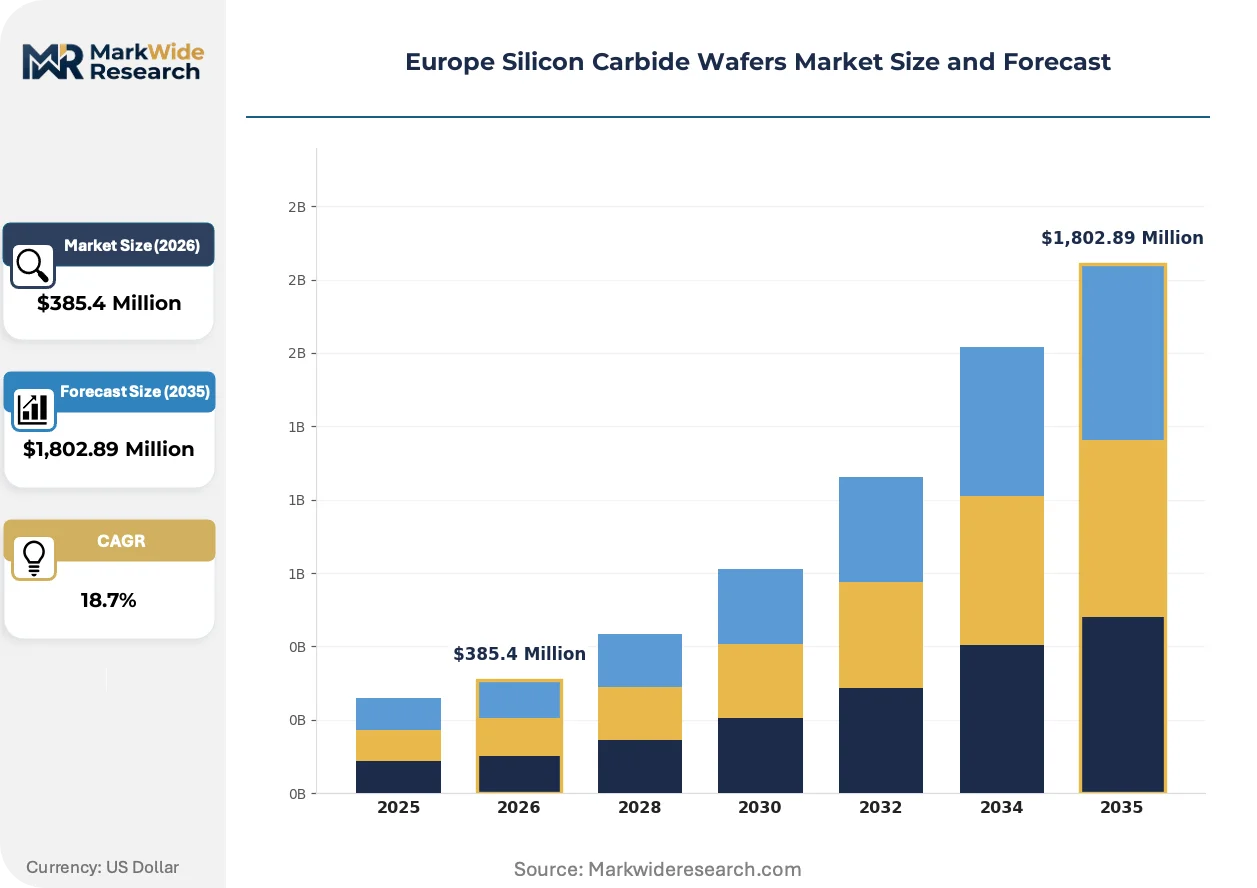
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,802.89 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round Wafer, Square Wafer, Rectangular Wafer, Custom Shaped Wafer Application: Power Electronics, Electric Vehicles, Wireless Communication, Lighting End User: Industrial, Consumer Electronics, Automotive, Telecommunications Technology: Chopped Silicon Carbide, Epitaxial Growth, Chemical Vapor Deposition, Physical Vapor Deposition |
| Companies Covered | Wolfspeed, Inc., Infineon Technologies AG, STMicroelectronics, Coherent Corp., ROHM Co., Ltd., Showa Denko K.K., SiCrystal, II-VI Incorporated, SK Siltron Co., Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Silicon Carbide Wafers Market Shifts & Advancements
European SiC wafer production is pivoting toward larger diameters and tighter defect specifications as automotive buyers consolidate supply relationships. Process innovation and regulatory disclosure requirements are reshaping competitive differentiation.
Hot-wall chemical vapor deposition for epitaxial growth is rendering obsolete legacy cold-wall reactor designs across European fabrication lines. BMW and Volkswagen procurement teams now specify epi thickness uniformity below 3% variation for 800V inverter programs. This technical threshold is compressing the qualified supplier base to three European epitaxy houses with proven hot-wall capability.
The F-Gas Regulation's phasedown of hydrofluorocarbon etching gases is forcing cleanroom chemistry transitions at substrate fabrication facilities. ECHA substance restriction notifications now cover sulfur hexafluoride alternatives, adding process validation overhead. German wafer manufacturers are responding with closed-loop etching gas recovery systems that reduce regulatory exposure and input cost volatility.
Automotive buyers are consolidating wafer procurement under multi-year take-or-pay contracts rather than spot-market purchasing. Tier-1 power module suppliers now demand five-year substrate allocation guarantees with quarterly price adjustment mechanisms. This contracting shift is most visible in Germany, where Infineon and Bosch have locked 150mm supply through 2028.
Europe Silicon Carbide Wafers Market Segmentation
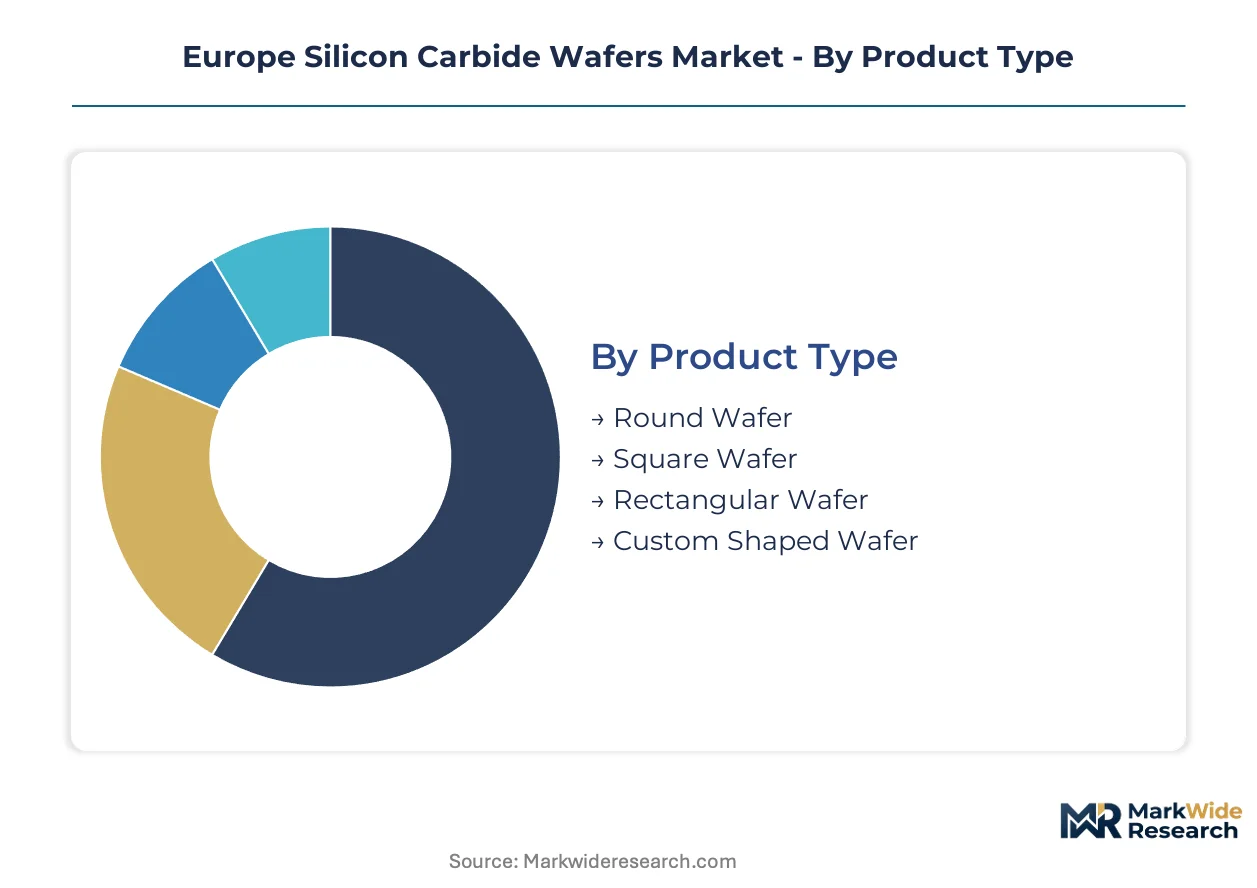
Segmentation in the Europe silicon carbide wafers market exposes how substrate geometry, device application, and manufacturing technology intersect with automotive qualification cycles and cleanroom chemistry transitions. Buyers segment procurement strategies across these dimensions to manage allocation risk and lock in supply for multi-year power module programs.
Product Type:
Cycle times vary sharply by wafer geometry, with round formats turning through epitaxy and device fabrication lines fastest due to equipment compatibility, while custom shapes face longest validation timelines for specialized power module footprints.
- Round Wafer:Dominant 150mm and 200mm circular substrates compatible with standard epitaxial growth reactors and lithography equipment across European fabrication lines. German automotive power module suppliers specify round wafers exclusively for 800V inverter programs, locking procurement under multi-year take-or-pay contracts that compress spot market availability.
- Square Wafer:Rectilinear substrates optimized for die-per-wafer efficiency in high-current power modules, requiring specialized handling equipment that extends qualification timelines. Italian substrate fabricators near Catania are developing square formats for integrated manufacturing from crystal growth through epitaxy, targeting premium automotive contracts with thickness uniformity below 3% variation.
- Rectangular Wafer:Elongated substrates for specific power module form factors with intermediate tooling requirements.
- Custom Shaped Wafer:Application-specific geometries for specialized RF and aerospace components with longest development cycles.
Round wafers anchor the volume base while square wafers gain share at the steepest rate as die-per-wafer efficiency drives automotive procurement consolidation.
Application:
Margin pools stratify across application segments, with power electronics commanding premium pricing for high-voltage switching and electric vehicles absorbing the deepest substrate volumes through inverter and onboard charger demand.
- Power Electronics:High-voltage switching devices for industrial motor drives, renewable energy inverters, and grid infrastructure requiring breakdown voltage specifications above silicon limits. Offshore wind deployments in the North Sea and solar string inverter manufacturing in Eastern Europe create parallel demand channels outside automotive supply chains.
- Electric Vehicles:SiC MOSFETs for 800V traction inverters, DC-DC converters, and onboard chargers where efficiency gains justify substrate cost premiums. BMW and Volkswagen procurement teams now specify epi thickness uniformity thresholds that compress the qualified European supplier base to three epitaxy houses with proven hot-wall chemical vapor deposition capability.
- Wireless Communication:RF power amplifiers and base station infrastructure with moderate volume requirements.
- Lighting:UV-C and high-power LED applications with specialized wavelength specifications.
Power electronics commands the deepest margin pools while electric vehicles climbs the fastest as OEMs accelerate silicon IGBT phase-outs under EU Green Deal carbon mandates.
End User:
Customer concentration shapes procurement power, with automotive buyers consolidating supply relationships under long-term contracts while industrial purchasers fragment across equipment OEMs with varying technical specifications.
- Automotive:Tier-1 power module suppliers and OEM in-house packaging operations driving the steepest demand trajectory for 150mm substrates. Infineon and Bosch have locked European wafer supply through multi-year allocation guarantees with quarterly price adjustment mechanisms, concentrating procurement power among established partnerships.
- Industrial:Motor drive manufacturers, welding equipment producers, and uninterruptible power supply vendors with fragmented demand across performance tiers. REACH compliance documentation and CE marking traceability requirements filter downstream into substrate specifications, creating margin capture opportunities for suppliers bundling regulatory disclosure services.
- Consumer Electronics:Premium laptop adapters and mobile fast-charging infrastructure with high-volume, price-sensitive procurement patterns.
- Telecommunications:5G base station power amplifiers and data center power supplies with emerging SiC adoption curves.
Automotive anchors the volume base while industrial gains share at the steepest rate as equipment OEMs qualify SiC for motor drive retrofits and renewable energy integration.
Technology:
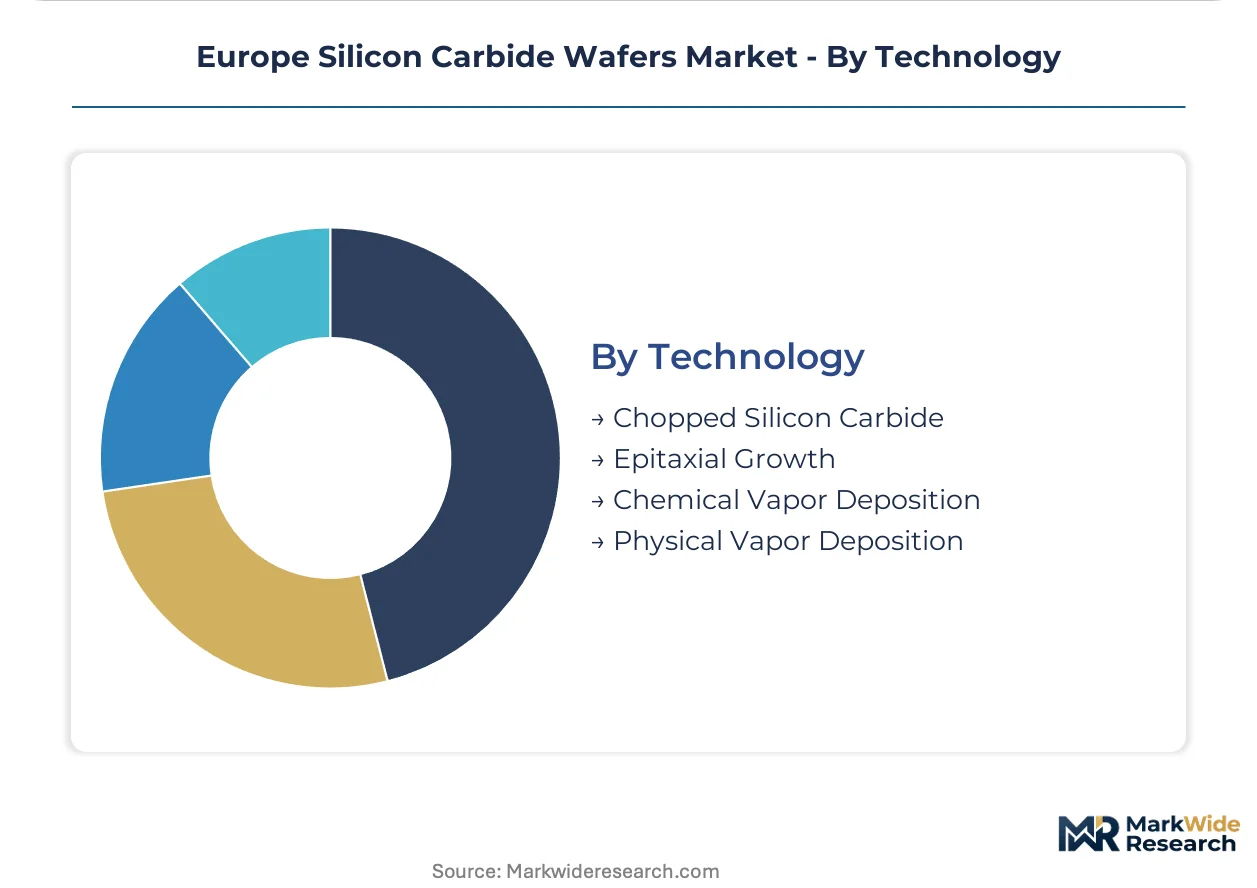
Process maturity determines yield economics, with physical vapor transport dominating crystal growth for substrate blanks while epitaxial growth technology separates qualified suppliers in the device-ready wafer tier.
- Epitaxial Growth:Hot-wall chemical vapor deposition processes rendering obsolete legacy cold-wall reactor designs across European fabrication lines. Thickness uniformity below 3% variation and defect control determine device yield, compressing the qualified supplier base to three European epitaxy houses serving BMW and Volkswagen 800V inverter programs.
- Physical Vapor Deposition:Physical vapor transport for high-purity boule growth with micropipe density reduction hitting diminishing returns that cap usable area per boule. SiCrystal specializes in 150mm substrates for premium automotive contracts, while Europe lacks training pipelines for PVT operators that constrain capacity expansion at existing facilities.
- Chopped Silicon Carbide:Mechanical processing for abrasive and refractory applications outside semiconductor-grade specifications.
- Chemical Vapor Deposition:Alternative deposition approaches for specialized layer structures with limited commercial penetration.
Physical vapor deposition anchors the volume base while epitaxial growth gains share at the steepest rate as automotive buyers consolidate procurement under technical thresholds that exclude legacy process capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across European SiC wafer markets diverge sharply by end-use intensity. German automotive clusters absorb the deepest substrate volumes for 800V traction inverters, while Italian fabrication centers concentrate upstream crystal growth and epitaxy capacity for export supply.
Germany
Stuttgart and Munich engineering corridors drive concentrated demand for 150mm substrates through dense OEM and Tier-1 supplier ecosystems. The EU Green Deal carbon neutrality mandates compress silicon IGBT phase-out timelines, locking procurement power with established wafer partnerships. Bavarian fabrication sites anchor power module packaging operations tied to domestic substrate sourcing.
Italy
STMicroelectronics operates integrated manufacturing from crystal growth through epitaxy near Catania, reshaping regional supply dynamics for premium automotive contracts. REACH compliance documentation requirements filter into substrate traceability systems for export markets. Sicilian substrate clusters specialize in high-purity boule production with thickness uniformity specifications below 3% variation.
France
Paris-Saclay semiconductor research corridors feed qualification protocols for automotive power module suppliers. ECHA substance restriction notifications on sulfur hexafluoride alternatives add process validation overhead for cleanroom etching transitions. Auvergne-Rhône-Alpes industrial zones host motor drive manufacturers creating parallel demand outside automotive supply chains.
United Kingdom
Cambridge and Bristol electronics clusters concentrate design engineering for RF power amplifiers with moderate SiC substrate requirements. CE marking pre-certification services capture margin from risk-averse industrial buyers bundling traceability documentation. Midlands manufacturing corridors face allocation pressure from limited qualified European crystal growth capacity.
Netherlands
Eindhoven Brainport corridors concentrate power electronics R&D for renewable energy inverter applications. F-Gas Regulation phasedown of hydrofluorocarbon etching gases forces cleanroom chemistry transitions at equipment suppliers serving wafer fabrication lines. Randstad logistics hubs coordinate substrate distribution across German automotive clusters and Italian growth facilities.
Europe Silicon Carbide Wafers Market Competitive Landscape
Capability concentration sits with specialized crystal growth and epitaxy houses; scale advantage sits with diversified semiconductor conglomerates with captive module packaging. The vendor base stratifies across three tiers: integrated substrate-to-device fabricators, pure-play wafer growers, and materials-science conglomerates with SiC divisions. Dominant competitive moves include multi-year take-or-pay contracting with automotive Tier-1s and geographic expansion into Eastern European greenfield fabrication sites.
Among European-anchored suppliers, STMicroelectronics and Infineon Technologies AG exemplify the integrated-device-manufacturer archetype with captive substrate sourcing and power module packaging. SiCrystal occupies a position within the pure-play wafer growth tier, specializing in high-purity 150mm substrates for premium automotive qualification programs. Wolfspeed, Inc. represents the transatlantic scale-driven competitor with established European customer relationships through its substrate supply agreements.
| Leading Market Players |
|---|
| Wolfspeed, Inc. |
| Infineon Technologies AG |
| STMicroelectronics |
| Coherent Corp. |
| ROHM Co., Ltd. |
| Showa Denko K.K. |
| SiCrystal |
| II-VI Incorporated |
| SK Siltron Co., Ltd. |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp corridor freight costs amplify pricing power for German automotive clusters while compressing margins for peripheral substrate fabricators. This logistics chokepoint concentrates procurement leverage with Bavarian OEMs who negotiate multi-year offtake terms, forcing Italian and Eastern European suppliers to absorb transport premiums or sacrifice volume allocation.
Pricing Analysis
Long-term offtake contracts dominate procurement, with BMW and Volkswagen locking five-year substrate allocation guarantees that exclude spot-market participation. Price differentiation hinges on epi thickness uniformity certification and REACH compliance documentation bundling. Cost compression in standard-grade 150mm substrates intensifies as SiCrystal and STMicroelectronics expand boule capacity. Industrial motor drive manufacturers exhibit highest price sensitivity, while automotive Tier-1s prioritize supply security over unit cost.
Supply Chain Analysis
X-FAB and GlobalFoundries hold concentrated foundry capacity for SiC device fabrication serving European power module packagers. High-purity polysilicon feedstock draws from Germany, Norway, and the United States, while graphite crucibles and argon gas rest on Chinese and Russian supply origins. Single-source vulnerability in qualified 150mm substrate growth constrains automotive qualification timelines. Distribution runs through Randstad logistics hubs coordinating just-in-time delivery to Stuttgart and Munich assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe silicon carbide wafers are cycling through a capacity-led recovery as automotive 800V platform ramps absorb constrained substrate supply. Polysilicon purification energy costs and crystal growth technician scarcity constitute the cyclical tension governing margin restoration.
For Market Incumbents: Build process IP moats around hot-wall epitaxy defect control protocols that automotive buyers now mandate. Infineon and Bosch procurement teams are consolidating supply relationships under technical thresholds that exclude legacy cold-wall capabilities. Captive polysilicon purification capacity in Norway or hydro-powered regions hedges energy cost volatility that threatens margin structures. For New Entrants and Emerging Players: Pursue Eastern European greenfield epitaxy expansion in Romania and Czechia, where lower energy costs and proximity to German automotive clusters offset qualification timeline disadvantages. Renewable energy inverter manufacturers present the most penetrable demand segment outside automotive, with less stringent AQAP-2120 validation requirements. CE marking pre-certification bundling captures margin from risk-averse industrial buyers seeking regulatory disclosure shortcuts. For Investors and Strategic Acquirers: Pure-play epitaxy houses with proven hot-wall chemical vapor deposition capability and automotive qualification track records represent the highest-conviction acquisition archetype. Long-term viability centers on five-to-ten year automotive platform electrification commitments that outlast silicon IGBT phase-out cycles. Quarterly monitoring of F-Gas Regulation amendment timelines and ECHA substance restriction notifications detects process chemistry transition costs that could compress epitaxy house margins.| Strategic Initiative | Industry Significance |
|---|---|
| Hot-Wall Epitaxy Capacity Expansion | BMW and Volkswagen procurement teams now mandate thickness uniformity below 3% variation for 800V inverter qualification. |
| Backward Integration into Polysilicon Purification | Hydro-powered Norwegian feedstock operations hedge energy cost volatility constraining substrate cost reduction trajectories. |
| CE Marking Pre-Certification Services | REACH compliance documentation bundling captures margin from industrial buyers facing ECHA substance restriction validation overhead. |
| Eastern European Greenfield Fabrication | Romania and Czechia sites offer lower energy costs and proximity to German automotive clusters for epitaxy expansion. |
| Closed-Loop Etching Gas Recovery Systems | German wafer manufacturers reduce F-Gas Regulation exposure and sulfur hexafluoride alternative process validation costs. |
Research Methodology
Initial hypotheses were tested against primary input from crystal growth technicians, automotive Tier-1 procurement directors, epitaxy process engineers, and power module packaging operations managers, then refined against secondary validation. SEC filings from Infineon Technologies AG and STMicroelectronics, ECHA substance restriction notifications, EU Green Deal implementation documents, and customs trade data for polysilicon and graphite crucible imports furnished triangulation anchors. Bottom-up wafer demand modeling from automotive platform electrification timelines converged with top-down semiconductor materials market sizing.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeled by wafer geometry, device application, manufacturing technology, and end-user concentration. CAGRs were derived from installed base growth in 800V traction inverters and renewable energy inverter deployments. Forecast inputs incorporated physical vapor transport yield ceilings and automotive AQAP-2120 qualification timeline constraints.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese substrate growers or breakthroughs in alternative wide-bandgap materials would shift outcomes. Quarterly review of automotive platform electrification announcements, F-Gas Regulation amendment progress, and polysilicon spot price movements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Die Spacer Market
Semiconductor Devices
APAC Semiconductor Device for Industrial Applications Market
Semiconductor Devices
Global Transistor Market
Semiconductor Devices
Gallium Oxide Transistor Market
Semiconductor Devices
Monocrystalline Half-Chip Module Market
Semiconductor Devices
Ram BOP Market
Semiconductor Devices
APAC Semiconductor Device in Aerospace and Defense Market
Semiconductor Devices
Gan Transistor Market
Semiconductor Devices
Embedded Multimedia Card Market
Semiconductor Devices
Gan-On-Silicon Market
Semiconductor Devices
DNA Chromatography Chip Market
Semiconductor Devices
Micro and Nano PLC Market
Semiconductor Devices
High Resistivity Silicon Wafers Market
Semiconductor Devices
Semiconductor Device in Aerospace and Defense Industry Market
Semiconductor Devices
China Semiconductor Diode Market
Semiconductor Devices
Advanced IC Substrates Market