
 Diamond Semiconductor Substrates Market | 2026-2036
Diamond Semiconductor Substrates Market Size, Share, and Industry Trends Forecast 2026-2036
Diamond Semiconductor Substrates Market Analysis
Japan is narrowing the supply gap for high-purity single-crystal diamond wafers through dedicated foundry investments near Nagoya. Element Six leverages its synthetic diamond heritage to dominate substrate quality benchmarks. Sumitomo Electric Industries anchors Japanese domestic supply with integrated epitaxial growth capabilities. Advanced Diamond Technologies specializes in thin-film diamond coatings for thermal management applications.
Diamond semiconductor substrates consist of synthetically grown crystalline carbon layers engineered for bandgap properties exceeding five electron volts, manufactured primarily through microwave plasma chemical vapor deposition to achieve thermal conductivity above 2,000 watts per meter-kelvin. These substrates serve critical heat-spreading and high-voltage switching functions in power electronics and high-frequency devices where silicon carbide and gallium nitride face thermal limitations. Single crystal substrates command premium positioning due to defect density requirements in radio-frequency amplifiers. Polycrystalline variants compete aggressively on cost in thermal management applications where optical clarity is secondary. Epitaxial growth technology leads investment intensity as device makers demand thicker active layers for power electronics.
The US FDA and FCC jointly shape device qualification pathways for diamond substrates in medical imaging and telecommunications hardware. Japan's METI coordinates national R&D consortia targeting substrate diameter scaling through JIS standards alignment. REACH compliance in Europe restricts certain chemical precursors in chemical vapor deposition processes, redirecting supply chain qualification efforts. Stakeholders must monitor foundry yield improvements against substrate diameter roadmaps to time capacity commitments.
Market Dynamics
Microwave plasma chemical vapor deposition scaling is compressing single-crystal diamond wafer production timelines while METI semiconductor revitalization policies redirect capital toward substrate fabrication clusters near Nagoya and Osaka.
Growth Catalysts
- Power electronics thermal limits:Aerospace manufacturers accelerate synthetic diamond adoption for heat-spreading functions where silicon carbide substrates fail. Radio-frequency amplifiers in defense communications drive defect-density specifications.
- METI semiconductor subsidies:Japan's national R&D consortia fund diameter scaling roadmaps through JIS standards alignment, tightening domestic supply chains around Tokyo industrial clusters.
- Epitaxial growth advances:Thicker active layer deposition enables high-voltage switching applications, expanding addressable device categories beyond thermal management into power electronics.
Market Restraints
- High-purity methane precursor costs:Chemical vapor deposition feedstock price volatility constrains foundry margin expansion and capacity planning.
- Japanese supply concentration:Substrate fabrication expertise clusters around Osaka and Tokyo, creating geographic vulnerability to regional disruption.
- Polycrystalline diamond substitution:Lower-cost thermal management alternatives capture volume in applications where optical clarity and defect density are secondary.
Strategic Opportunities
- Medical imaging device qualification:FDA pathways for diamond substrates in radiation-hardened detectors open diagnostic hardware penetration.
- Telecommunications hardware certification:FCC device qualification creates regulatory tailwind for radio-frequency amplifier substrates in base station infrastructure.
- Gallium nitride convergence:Diamond-on-GaN heterostructure integration enables next-generation high-electron-mobility transistors for millimeter-wave systems.
Industry Challenges
- Crystallography specialist scarcity:Microwave plasma reactor operation and defect characterization expertise concentrates in Japanese industrial clusters, constraining global talent pipelines.
- Substrate-wafer bonding certification:Extended qualification timelines for epitaxial layer transfer processes delay device maker volume commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diamond Semiconductor Substrates Market |
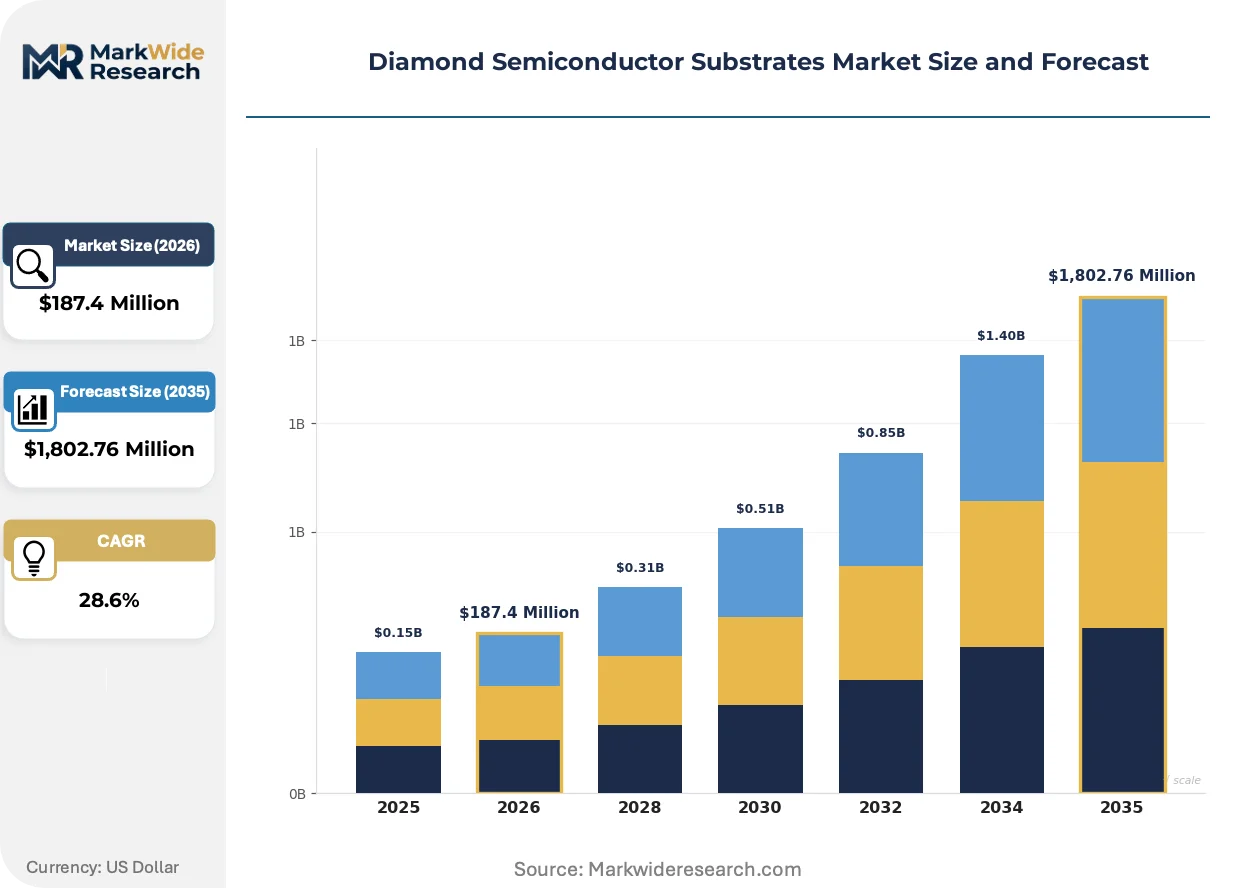
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,802.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Crystal, Polycrystalline, Chemical Vapor Deposited, High-Purity Technology: Substrate Fabrication, Epitaxial Growth, Slicing, Polishing End Use Industry: Aerospace, Electronics, Telecommunications, Defense Application: Power Electronics, High-Frequency Devices, Optoelectronics, Thermal Management |
| Companies Covered | Element Six, Blue Wave Semiconductors, Sumitomo Electric Industries, Advanced Diamond Technologies, IIa Technologies, Crystallume, NeoCoat, Carat Systems, AKHAN Semiconductor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diamond Semiconductor Substrates Market Emerging Trajectories
Computational materials modeling and reactor automation are compressing single-crystal growth cycle times while regulatory alignment across FDA, FCC, and METI frameworks accelerates device qualification standardization.
Homoepitaxial diamond growth on single-crystal seeds is virtualizing traditional heteroepitaxial approaches by enabling thicker active layers with lower defect density. Power electronics device makers in Japanese aerospace supply chains adopt this platform fastest. The technology is virtualizing competitive differentiation around thermal conductivity benchmarks previously dominated by substrate sourcing relationships.
REACH compliance in Europe restricts certain chemical precursors in chemical vapor deposition processes, redirecting supply chain qualification efforts toward alternative feedstock chemistries. Foundries serving EU medical imaging and telecommunications hardware markets reformulate deposition recipes. Japanese exporters face additional documentation burdens for polycrystalline diamond thermal management substrates.
Device makers unbundle substrate procurement from epitaxial growth services, creating direct purchasing relationships with foundries. Traditional vertically integrated semiconductor houses lose captive supply advantages. Japanese power electronics manufacturers lead this pattern, negotiating separate contracts for single-crystal wafers and active layer deposition.
Diamond Semiconductor Substrates Market Segmentation
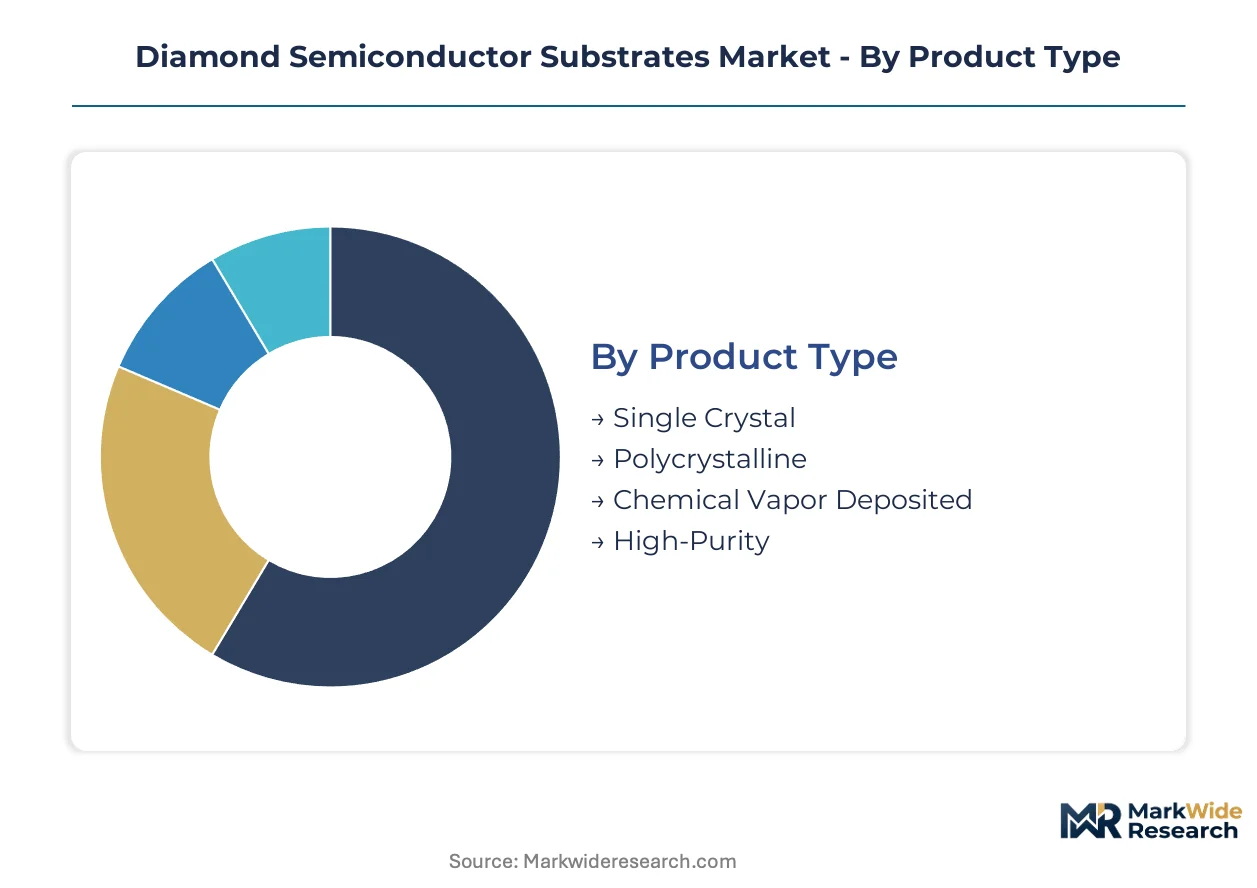
Diamond semiconductor substrates fragment across crystalline structure, manufacturing process, and thermal-electrical performance requirements. Each segmentation axis reveals distinct margin profiles and customer procurement patterns that shape competitive positioning.
Product Type:
Cost tier separates premium single-crystal grades from volume-oriented polycrystalline alternatives, with purity specifications driving foundry yield economics.
- Single Crystal:Engineered from high-purity synthetic diamond seeds with defect densities below 10^3 cm^-2, these substrates enable radio-frequency amplifiers in Japanese aerospace supply chains where thermal conductivity above 2,000 W/m-K is mandatory. METI-funded diameter scaling roadmaps target 2-inch wafer commercialization.
- Polycrystalline:Aggregated diamond grain structures manufactured without single-crystal seeding achieve 80% of thermal performance at 40% of substrate cost. Demand concentrates in industrial heat-spreading applications across Osaka industrial clusters where optical clarity requirements are absent.
- Chemical Vapor Deposited:Microwave plasma reactors deposit carbon layers onto sacrificial substrates, enabling custom geometries for medical imaging detector housings.
- High-Purity:Sub-ppb nitrogen content grades serve quantum sensing applications requiring spin coherence preservation.
Single Crystal commands the established base. The steepest expansion runs through Polycrystalline.
Technology:
Application requirements across power electronics and telecommunications hardware dictate which processing stages receive capital allocation.
- Substrate Fabrication:Microwave plasma chemical vapor deposition reactors operating at 900°C and 150 Torr grow bulk diamond crystals over 500-hour cycles. Japanese foundries near Nagoya achieve the highest reproducibility rates for 1-inch diameter wafers.
- Epitaxial Growth:Homoepitaxial deposition on single-crystal seeds builds active layers exceeding 100 microns thickness for high-voltage switching devices. Thicker deposition cycles enable vertical power transistor architectures previously constrained by gallium nitride thermal limits.
- Slicing:Laser-assisted wafering reduces kerf loss below 150 microns versus mechanical sawing.
- Polishing:Chemo-mechanical planarization achieves atomic-scale surface roughness for heterostructure bonding.
Epitaxial Growth attracts the most capital intensity. Slicing gains share fastest as diameter roadmaps accelerate.
End Use Industry:
Customer type diversity spans defense procurement cycles, commercial electronics velocity, and aerospace qualification timelines.
- Aerospace:Satellite power conditioning systems and radar cooling assemblies specify diamond substrates for radiation hardness and thermal shock resistance. Japanese manufacturers in Tokyo industrial clusters lead qualification programs for next-generation geostationary platforms.
- Electronics:Consumer power supply modules and data center cooling solutions drive polycrystalline diamond volume where unit cost thresholds dominate specification decisions.
- Telecommunications:Base station power amplifiers and millimeter-wave backhaul equipment demand low-defect single-crystal substrates for gallium nitride heterointegration.
- Defense:Classified programs for electronic warfare systems sustain premium pricing for ultra-high-purity grades with documented chain-of-custody.
Electronics provides the volume foundation. Aerospace delivers the margin expansion.
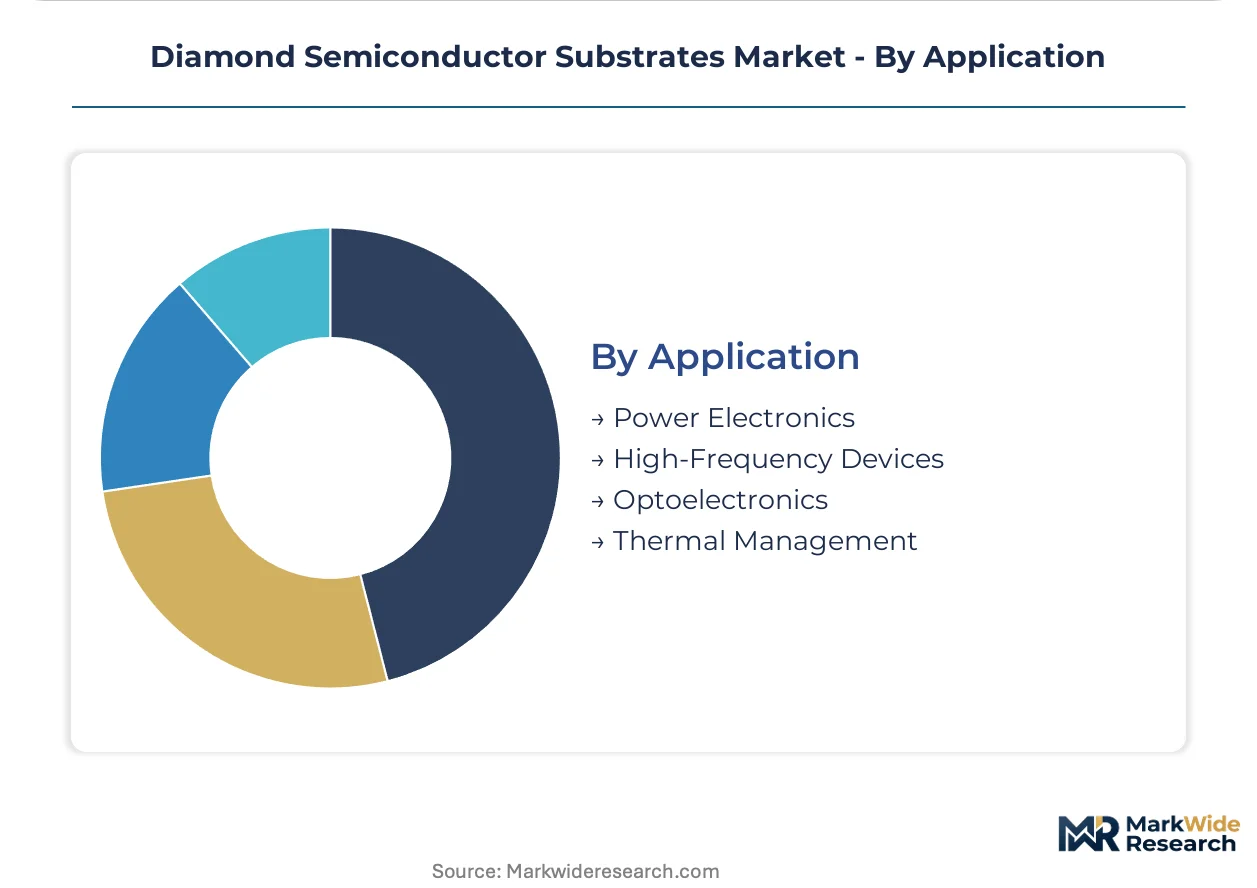
Application:
Performance tier stratification matches thermal conductivity and electrical insulation requirements to device operating conditions.
- Power Electronics:Insulated-gate bipolar transistors and silicon carbide power modules integrate diamond heat spreaders to manage junction temperatures above 200°C. Thicker epitaxial layers enable vertical device architectures that displace silicon carbide in 1,200V+ switching applications.
- Thermal Management:Heat sink substrates and thermal interface materials exploit diamond's isotropic conductivity for laser diode arrays and high-brightness LEDs. Polycrystalline grades capture this segment through aggressive cost positioning against copper-molybdenum alternatives.
- High-Frequency Devices:Radio-frequency monolithic microwave integrated circuits require single-crystal substrates with surface roughness below 0.5 nm RMS.
- Optoelectronics:Ultraviolet light-emitting diodes and diamond-based photodetectors leverage wide bandgap properties for deep-UV emission.
Thermal Management anchors current revenue. Power Electronics is climbing the fastest toward commercial scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Substrate fabrication expertise clusters heavily in Japan, where microwave plasma chemical vapor deposition capacity has accumulated around Nagoya and Osaka. This concentration creates geographic vulnerability while METI subsidies accelerate diameter scaling roadmaps.
Japan
Aerospace power electronics manufacturers in Tokyo industrial clusters drive single-crystal diamond demand for satellite thermal management. METI semiconductor revitalization policies fund JIS standards alignment for substrate diameter scaling. Foundries near Nagoya achieve the highest reproducibility rates for 1-inch wafers through integrated epitaxial growth capabilities.
United States
Defense communications programs sustain premium demand for ultra-high-purity grades with documented chain-of-custody requirements. The FDA and FCC jointly shape device qualification pathways for medical imaging detectors and telecommunications hardware. Research corridors in California and Massachusetts host reactor automation development for compressing single-crystal growth cycle times.
Germany
Industrial laser manufacturers specify polycrystalline diamond heat spreaders for high-brightness diode arrays. REACH compliance restricts certain chemical precursors in chemical vapor deposition processes, redirecting supply chain qualification toward alternative feedstock chemistries. The Eindhoven-Dortmund corridor anchors European thermal management substrate distribution.
China
Domestic gallium nitride device makers explore diamond-on-GaN heterostructure integration for millimeter-wave base station amplifiers. MIIT semiconductor self-sufficiency targets redirect capital toward microwave plasma reactor capacity expansion. Yangtze River Delta industrial zones concentrate polycrystalline diamond volume production for consumer electronics cooling modules.
South Korea
Memory semiconductor manufacturers evaluate diamond thermal interface materials for high-bandwidth packaging applications. MFDS medical device regulations create parallel qualification frameworks for radiation-hardened detector substrates. Seoul Capital Area foundries develop laser-assisted wafering to reduce kerf loss below mechanical sawing benchmarks.
Diamond Semiconductor Substrates Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream controlling substrate quality benchmarks and epitaxial growth capabilities. The vendor base separates into three strategic archetypes: synthetic diamond heritage players with integrated seed-to-wafer operations, thin-film coating specialists focused on thermal management applications, and emerging foundries unbundling substrate procurement from active layer deposition. Dominant competitive moves include backward integration into high-purity methane precursor supply and technology licensing agreements spanning reactor design automation.
Among heritage synthetic diamond producers, Element Six leverages its industrial materials legacy to anchor premium-tier positioning, while Sumitomo Electric Industries exemplifies integrated Japanese fabrication capabilities spanning substrate growth through epitaxial layer deposition. Advanced Diamond Technologies occupies a specialist position in thin-film diamond coatings, representing the coating-focused archetype targeting thermal management applications where volume cost thresholds dominate procurement decisions.
| Leading Market Players |
|---|
| Element Six |
| Blue Wave Semiconductors |
| Sumitomo Electric Industries |
| Advanced Diamond Technologies |
| IIa Technologies |
| Crystallume |
| NeoCoat |
| Carat Systems |
| AKHAN Semiconductor |
| Others |
Supply Flow & Price Mechanics
The Osaka-Nagoya freight corridor carries high-purity methane precursors and finished single-crystal wafers between Japanese fabrication clusters, with logistics costs amplifying the pricing power of concentrated substrate foundries while downstream buyers face tiered cost structures based on defect density certification.
Pricing Analysis
REACH compliance dictates the pricing tier structure across European markets, with three-tier pricing separating ultra-high-purity quantum grades from standard thermal management substrates and economy polycrystalline alternatives. Price differentiation hinges on nitrogen content certification and JIS diameter specifications, with single-crystal grades commanding substantial premiums. Cost compression in polycrystalline segments is intensifying because Chinese volume producers are scaling microwave plasma capacity. Aerospace procurement teams show the least price sensitivity due to radiation-hardening requirements, while consumer electronics buyers drive aggressive cost negotiations.
Supply Chain Analysis
High-purity methane feedstock anchors the upstream cost structure, with Japanese foundries drawing from domestic gas suppliers and European competitors sourcing from Norwegian and Qatari producers. Substrate fabrication concentrates in Japan, the United States, and Germany, with reactor components resting on specialized ceramic and precision gas handling systems. Single-source vulnerability runs through Japanese epitaxial growth equipment manufacturers. Distribution runs through direct foundry relationships with power electronics OEMs, bypassing traditional semiconductor distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized crystallography expertise for microwave plasma reactor operation represents the binding constraint on capacity expansion, with fewer than two hundred qualified engineers globally capable of optimizing defect density in single-crystal growth cycles.
For Market Incumbents: Entrench through backward integration into high-purity methane precursor supply and captive epitaxial growth capacity additions near Nagoya. Polycrystalline substitution from Chinese entrants threatens thermal management margins, requiring certification investment in quantum-grade purity tiers to defend positioning. For New Entrants and Emerging Players: Build out laser-assisted wafering capabilities to reduce kerf loss below mechanical sawing benchmarks, targeting South Korean memory semiconductor packaging applications where thermal interface materials remain underpenetrated. Partner with gallium nitride device makers for diamond-on-GaN heterostructure co-development. For Investors and Strategic Acquirers: Thin-film coating specialists with proprietary microwave plasma recipes and established FDA documentation pathways represent the most defensible acquisition profile. Long-term viability rests on medical imaging detector qualification timelines and telecommunications hardware certification velocity. Watch for METI subsidy announcements signaling diameter scaling inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methane Feedstock | Secures supply chain resilience against REACH precursor restrictions and price volatility. |
| Homoepitaxial Growth Capacity Expansion | Enables thicker active layers for 1,200V+ power electronics displacing silicon carbide. |
| FDA Medical Device Qualification Pathway | Opens radiation-hardened detector substrates for diagnostic hardware penetration. |
| Laser-Assisted Wafering Technology Deployment | Reduces material loss below 150 microns versus mechanical sawing benchmarks. |
| Diamond-on-GaN Heterostructure Joint Development | Accelerates millimeter-wave transistor integration for telecommunications base stations. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interviews with microwave plasma reactor engineers, epitaxial growth specialists, aerospace procurement directors, and medical imaging device regulators. Secondary validation drew from METI semiconductor policy filings, FDA 510(k) submission databases, JIS standards documentation, and customs trade records for high-purity methane imports. Bottom-up wafer production estimates and top-down power electronics market sizing were triangulated to anchor volume projections.
Calibration against historical diameter scaling roadmaps and foundry yield improvement curves shaped the analytical framework across the analysis window. Segmentation modeling captured crystalline structure tiers, manufacturing process stages, thermal-electrical performance thresholds, and end-use industry procurement patterns. CAGRs were derived from supply elasticity assessments and device maker adoption curve analysis, with particular weighting on aerospace qualification timelines and telecommunications hardware certification cycles.
Sensitivities concentrate around METI subsidy disbursement timing, REACH precursor restriction scope expansion, and polycrystalline Chinese import pricing. Forecasts reflect assumptions on reactor automation deployment rates and epitaxial layer transfer process qualification timelines. Cross-checking against SEMI semiconductor equipment spending benchmarks and aerospace platform procurement announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Global Micromachining Market
Semiconductor Fabrication
Semiconductor Logistics Market
Semiconductor Fabrication
Semiconductor Photoresist Polymer Market
Semiconductor Fabrication
Physical Vapor Deposition (PVD) Market
Semiconductor Fabrication
Global Dielectric Etchers Market
Semiconductor Fabrication
Sic Wafer Reclaim Services Market
Semiconductor Fabrication
8-Inch Silicon Carbide (Sic) Wafer Market
Semiconductor Fabrication
Etching Machine Market
Semiconductor Fabrication
Photoresist Removal Market
Semiconductor Fabrication
Semiconductor Advanced Substrate Market
Semiconductor Fabrication
Deep Reactive Ion Etching (DRIE) Etcher Market
Semiconductor Fabrication
Additive Manufacturing in Semiconductor Market
Semiconductor Fabrication
Solar Ingot Wafer Market
Semiconductor Fabrication
Semiconductor Foundry Market
Semiconductor Fabrication
Ion Implantation Machine Market
Semiconductor Fabrication
Global Dry Etching Machine Market