
 Manual Wafer Aligner Market | 2026-2036
Manual Wafer Aligner Market Size, Share, and Industry Trends Forecast 2026-2036
Manual Wafer Aligner Market Insights
Equipment leasing programs for lithography tools is reconfiguring how mid-size foundries access manual wafer aligners without capital-heavy balance sheets. SUSS MicroTec leverages its European installed base to sustain service revenue streams alongside hardware placements. EV Group anchors its position through specialized bond-alignment systems for MEMS fabs. HIWIN competes on precision motion components that OEMs integrate into aligner subsystems.
A manual wafer aligner positions a photomask relative to a coated substrate using mechanical micrometers and optical fiducial recognition, achieving overlay accuracy typically within one to three micrometers for research and low-volume production. The tool serves semiconductor prototyping, MEMS development, and educational fabrication lines where automated stepper throughput is economically unjustified. Mask aligners occupy the largest product category as universities and government labs maintain steady replacement cycles for aging contact-printing equipment. Optical alignment technology leads the technology dimension due to its lower cost and established maintenance infrastructure, though laser alignment systems are gaining share in compound semiconductor applications requiring tighter overlay control.
ISO 14644 cleanroom classification standards and SEMI S2 safety guidelines shape equipment design requirements for manual aligner vendors selling into regulated fabs. The EPA and OSHA impose ventilation and ergonomic constraints on equipment operated by technicians in US-based research facilities. Buyers should monitor how REACH substance restrictions and evolving EU semiconductor subsidies alter equipment qualification timelines and supplier certification burdens.
Market Dynamics
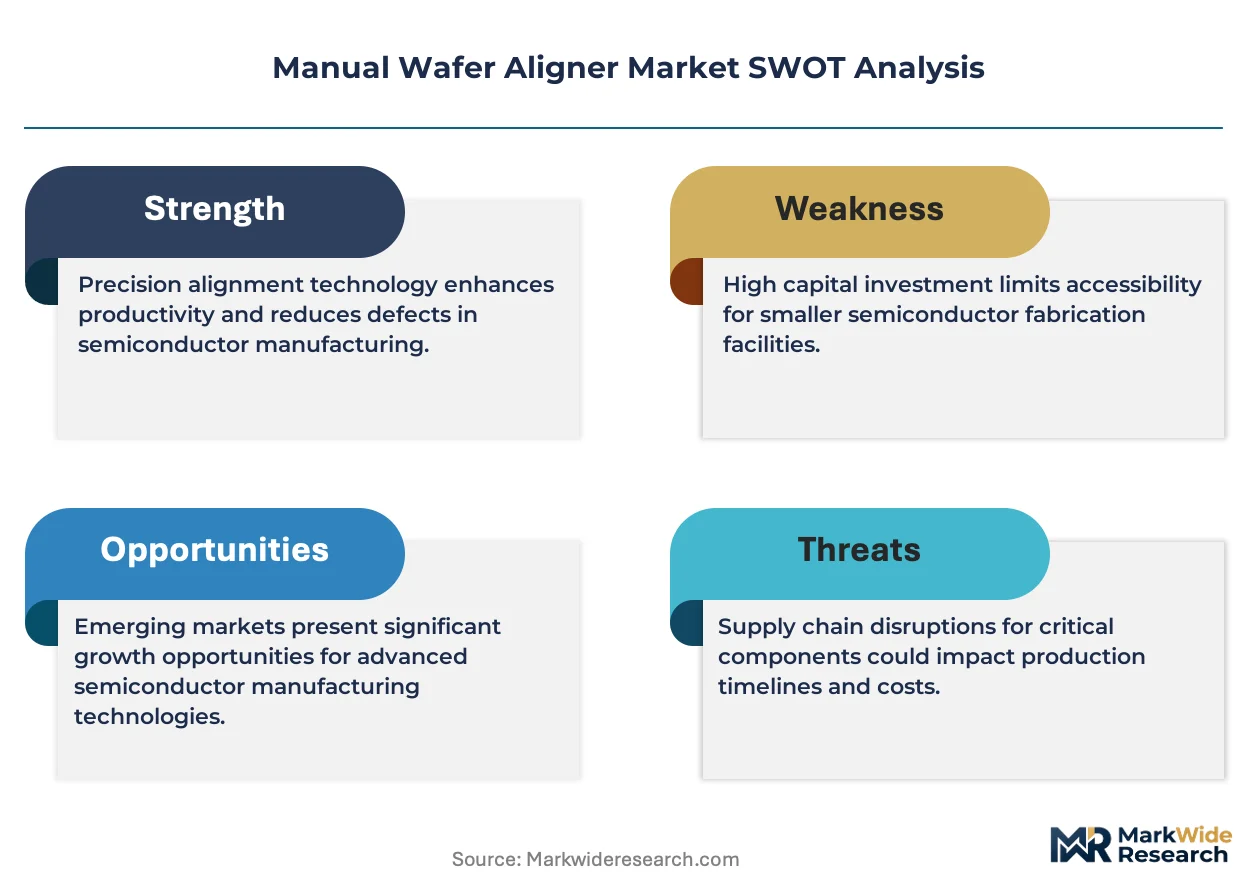
Equipment leasing programs for lithography tools are reconfiguring how mid-size foundries access manual wafer aligners without capital-heavy balance sheets, compressing ownership cycles and expanding the addressable buyer base.
Growth Catalysts
- EU Chips Act traceability mandates:European automotive chip demand is tightening equipment qualification requirements, forcing fabs to upgrade aging manual aligners with certified units that meet component-level tracking standards.
- Mature-node foundry expansion:Semiconductor foundries in Taiwan and South Korea are expanding manual aligner procurement for 200mm legacy production lines where automated steppers remain economically unjustified.
- MEMS prototyping surge:Universities and government labs maintain steady replacement cycles for contact-printing equipment, sustaining demand for mask aligners in research fabrication environments.
Market Restraints
- Precision component supply concentration:Critical motion control subsystems rely on specialized suppliers concentrated in Germany and Japan, exposing lead times to geopolitical friction and export control variability.
- Automated stepper substitution:Low-volume production lines face mounting pressure to migrate to semi-automated alignment systems as unit economics of manual operation deteriorate at scale thresholds.
- REACH substance compliance burdens:Evolving EU chemical restrictions on coating materials and lubricants extend equipment qualification timelines, delaying revenue recognition for vendors serving European research facilities.
Strategic Opportunities
- Indian packaging house penetration:Domestic semiconductor assembly and test facilities under the PLI scheme represent underdeveloped demand for legacy 200mm alignment equipment as capacity expands.
- Laser-optical convergence:Integration of laser interferometry with conventional optical fiducial recognition enables sub-micron overlay accuracy for compound semiconductor applications without full stepper investment.
- Educational leasing channels:Equipment-as-a-service models targeting university cleanrooms reduce upfront capital barriers and create recurring revenue streams through maintenance and upgrade contracts.
Industry Challenges
- Specialized technician scarcity:Manual aligner operation demands expertise in photomask handling and overlay metrology that fabrication training programs have deprioritized in favor of automated tool proficiency.
- Legacy system integration complexity:New aligner installations must interface with decades-old contact printers and wet benches, requiring custom mechanical adapters and control software bridges.
- ISO 14644 certification timelines:Cleanroom classification verification for equipment upgrades consumes 4-6 months of project schedules, compressing installation windows for academic facilities with fixed grant cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manual Wafer Aligner Market |
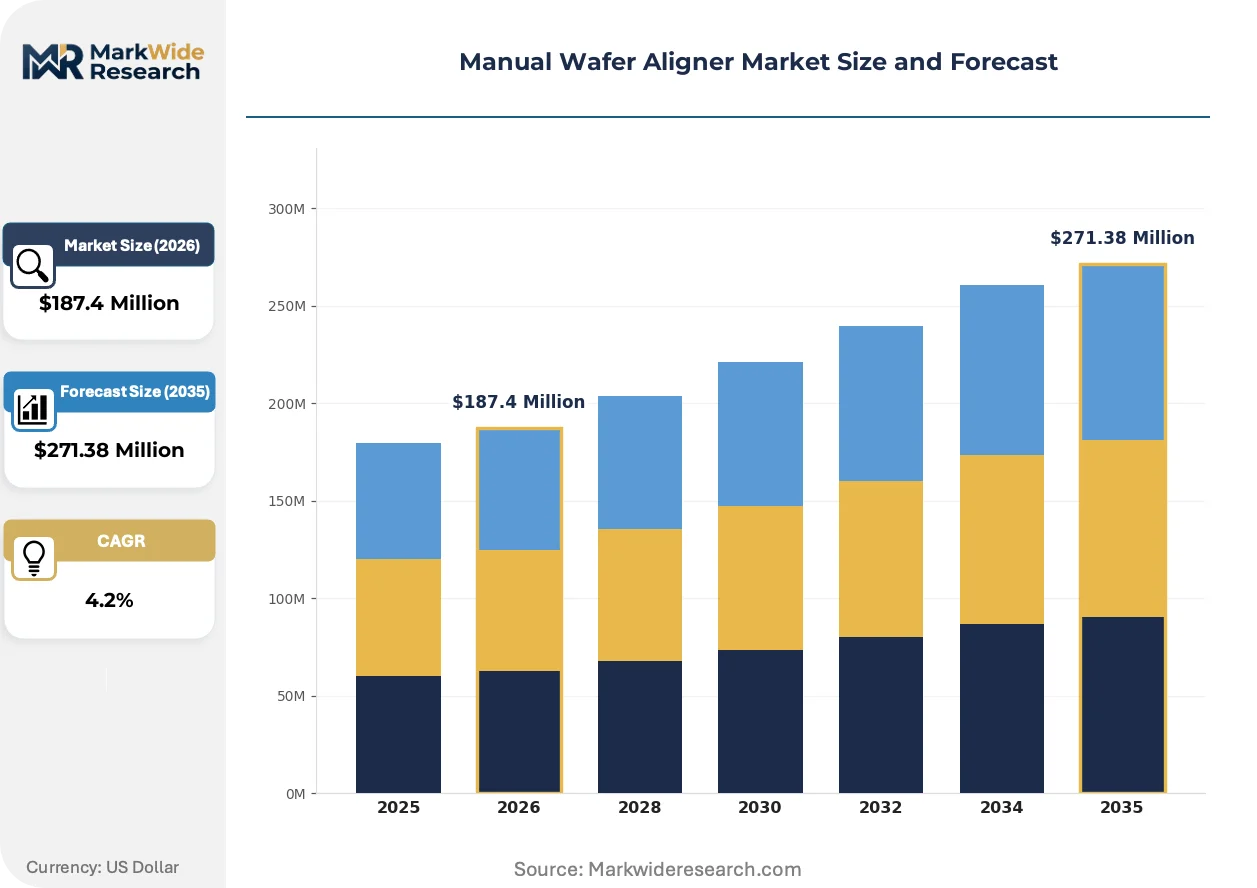
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $271.38 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mask Aligner, Contact Aligner, Proximity Aligner, Projection Aligner, Stepper, Stitch Aligner Technology: Optical Alignment, Electron Beam Alignment, Infrared Alignment, Laser Alignment, Magnetic Alignment Application: Semiconductor Fabrication, MEMS Production, Photovoltaic Cell Manufacturing, Printed Circuit Board Assembly, Sensor Fabrication End User: Foundries, Integrated Device Manufacturers, Research Laboratories, Packaging Houses, Assembly Lines |
| Companies Covered | HIWIN, Burgeon Instrument, Hamamatsu Photonics, Chung King Enterprise, Applied Microengineering, EMU Technologies, EV Group, OAI, SUSS MicroTec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manual Wafer Aligner Market Trends and Innovations
Manual wafer aligner technology is fragmenting along application-specific performance tiers, with vendors developing divergent architectures for research prototyping versus production packaging environments.
Laser alignment systems are migrating from specialized compound semiconductor fabs into mainstream MEMS development lines. These systems deliver sub-micron overlay accuracy through interferometric position feedback. Research institutions in Germany and Japan are adopting them for GaN and SiC device prototyping. The technology is migrating from premium niche applications toward mid-tier educational and government labs as component costs decline.
REACH substance restrictions are forcing equipment redesigns across the European supply base. ECHA's evolving candidate list now impacts photoresist handling components and vacuum seal materials. Vendors serving European automotive chip fabs are accelerating qualification of alternative chemistries to maintain CE marking compliance without disrupting installed base service contracts.
Leasing structures are displacing outright purchase for mid-size foundry procurement. Equipment finance firms now structure operating leases with bundled maintenance for 200mm legacy lines. This model is most visible in Taiwanese packaging houses seeking to preserve balance sheet flexibility during node transition uncertainty.
Manual Wafer Aligner Market Segmentation
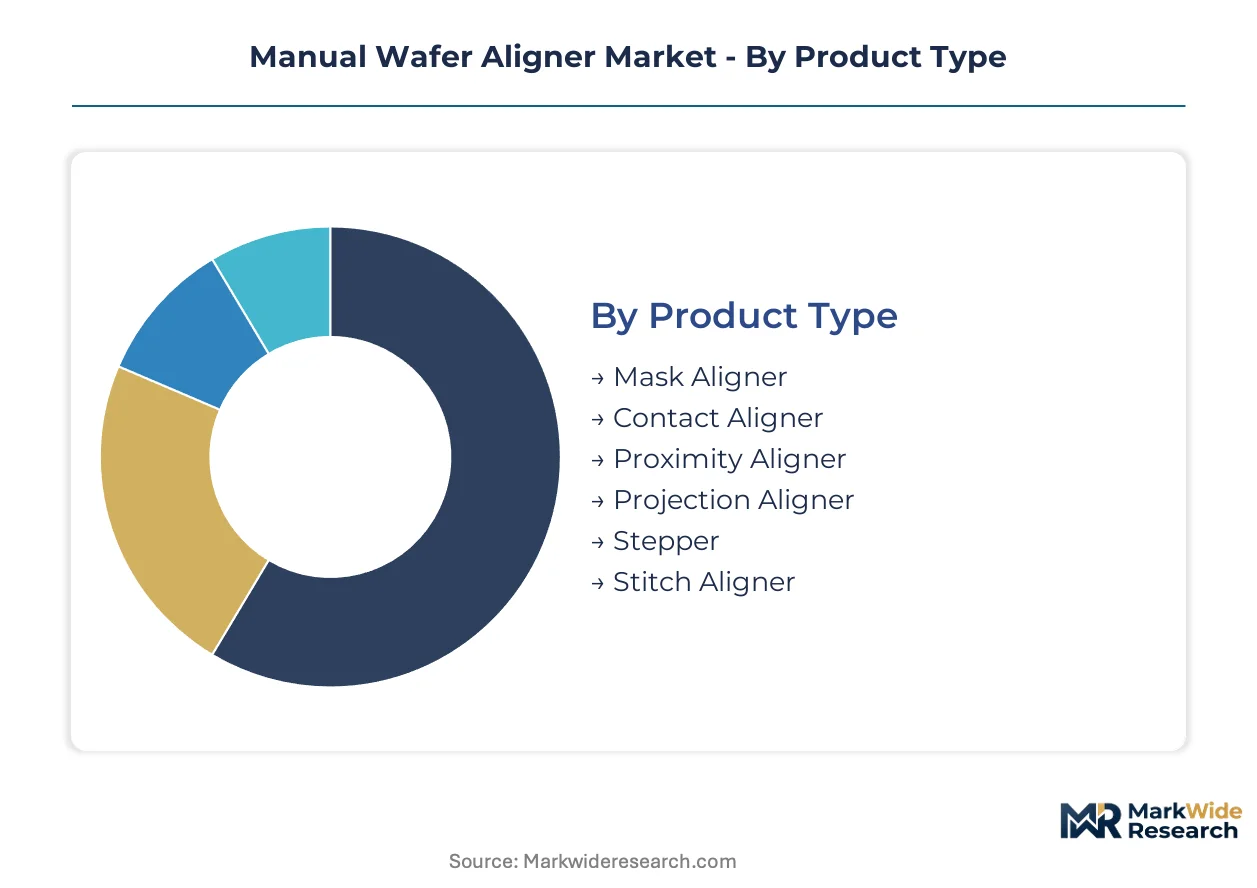
Manual wafer aligner procurement patterns diverge sharply across equipment configurations and operational environments. Understanding these fault lines reveals where capital deployment concentrates and which technology trajectories command R&D investment priority.
Product Type:
Equipment cost tier and throughput requirements determine which aligner architecture dominates specific fabrication settings.
- Mask Aligner:Contact-printing systems position photomasks directly against resist-coated wafers using mechanical micrometers. Universities and government labs in Taiwan and South Korea sustain replacement cycles for aging equipment as legacy 200mm lines persist.
- Contact Aligner:Direct substrate-to-mask contact delivers sub-micron resolution for research prototyping. MEMS development facilities in Germany are rotating up procurement volumes for bond-alignment applications requiring tight overlay control.
- Proximity Aligner:Near-contact gap control reduces mask wear while maintaining pattern fidelity. Packaging houses running mature-node production favor these units for cost-sensitive volume operations.
- Projection Aligner:Reduced-image optics extend mask lifetime through non-contact exposure. Compound semiconductor fabs processing GaN and SiC substrates specify these for reduced defect rates.
- Stepper:Reduced-pattern scanning delivers superior overlay accuracy at the expense of manual throughput. Research institutions with grant-funded precision requirements represent the primary demand pool.
- Stitch Aligner:Field-stitching capability enables large-area patterning beyond single-exposure limits. Specialty sensor manufacturers in Japan integrate these for unconventional substrate formats.
Mask Aligner holds installed capacity. Contact Aligner is rotating up the share rankings.
Technology:
Alignment precision specifications and maintenance infrastructure availability shape technology adoption curves across end-user categories.
- Optical Alignment:Conventional fiducial recognition using visible-light microscopy achieves one-to-three micrometer overlay accuracy. Mature maintenance networks and lower capital costs sustain dominance in educational fabrication lines.
- Laser Alignment:Interferometric position feedback delivers sub-micron precision for compound semiconductor applications. Research institutions in Germany and Japan are expanding adoption as component costs decline.
- Electron Beam Alignment:Direct-write patterning eliminates photomask requirements for prototype iterations. Specialized MEMS development facilities specify these for rapid design validation cycles.
- Infrared Alignment:Non-visible wavelength inspection enables alignment through opaque substrate layers. Silicon carbide device manufacturers leverage this for backside processing operations.
- Magnetic Alignment:Ferromagnetic fiducial detection accommodates non-standard substrate materials. Niche sensor fabrication applications in Japanese government labs represent primary demand.
Optical Alignment maintains volume leadership. Laser Alignment is climbing the fastest among precision-demanding segments.
Application:
Process maturity and automation economics determine where manual aligners retain competitive positioning against stepper alternatives.
- Semiconductor Fabrication:Mature-node production lines at 200mm and below continue manual aligner deployment where automated stepper throughput remains economically unjustified. Taiwanese foundries expanding legacy capacity drive procurement concentration.
- MEMS Production:Multi-layer mechanical structures require specialized bond-alignment capabilities. Packaging houses in South Korea are increasing specifications for precision motion subsystems.
- Photovoltaic Cell Manufacturing:Large-area substrate handling favors proximity aligner architectures. Research-scale perovskite development lines represent emerging demand.
- Printed Circuit Board Assembly:Panel-scale exposure requirements push equipment toward modified aligner configurations. Domestic Indian facilities under PLI scheme incentives are evaluating legacy equipment imports.
- Sensor Fabrication:Non-standard substrate geometries and materials demand flexible alignment solutions. Automotive chip suppliers serving European OEMs face EU Chips Act traceability mandates.
Semiconductor Fabrication anchors revenue concentration. MEMS Production is gaining share fastest as prototyping activity intensifies.
End User:
Capital availability and operational expertise availability create distinct purchasing patterns across organizational types.
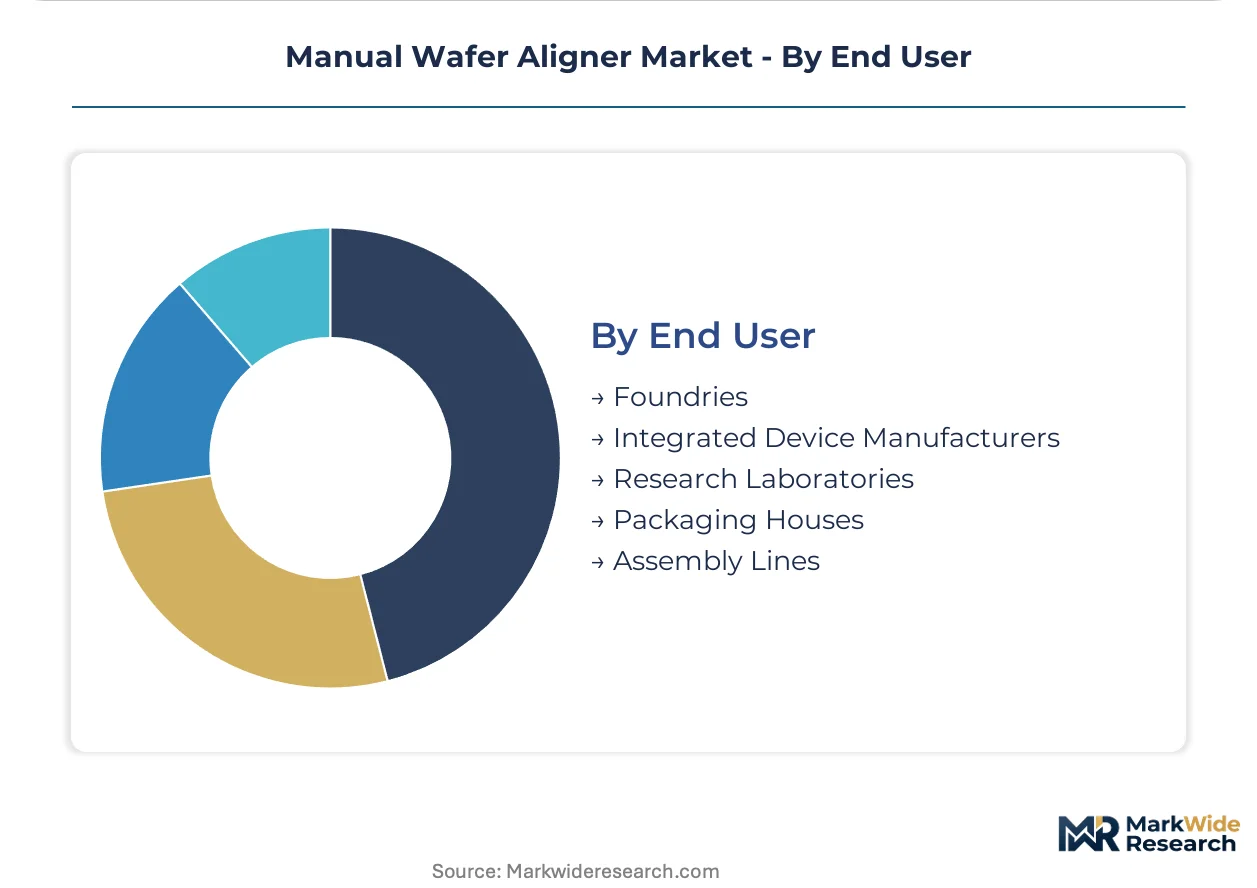
- Foundries:Merchant silicon manufacturers balance equipment utilization rates across mixed-node portfolios. Taiwanese and South Korean operators are expanding manual aligner fleets for 200mm legacy lines.
- Research Laboratories:University and government cleanrooms prioritize flexibility over throughput. Equipment leasing programs are compressing ownership cycles and expanding addressable procurement.
- Integrated Device Manufacturers:Captive fabrication facilities maintain manual aligners for process development and low-volume specialty production. REACH compliance timelines extend European qualification schedules.
- Packaging Houses:Assembly and test operations require alignment for interconnect and MEMS integration. Indian domestic facilities represent underdeveloped demand as PLI scheme capacity expands.
- Assembly Lines:Final manufacturing stages apply aligners for module-level optical and sensor integration. Automotive chip suppliers face tightening component traceability requirements.
Foundries command the largest equipment installed base. Research Laboratories are expanding most quickly through leasing channel adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment trade flows for manual wafer aligners tilt heavily toward export-dependent manufacturing economies, with import demand concentrated in emerging packaging hubs and research-intensive economies building domestic semiconductor capabilities.
Taiwan
Semiconductor foundries in Hsinchu and Tainan are expanding manual aligner fleets for mature-node 200mm production lines where automated steppers remain economically unjustified. The National Development Council's chip industry incentives reinforce equipment procurement timelines for legacy capacity extensions. Packaging houses in Taichung are rotating up proximity aligner specifications for cost-sensitive volume operations.
South Korea
Memory and logic foundries in Yongin and Pyeongtaek are balancing mixed-node portfolios with expanded manual aligner deployment for specialty production. The Ministry of Trade, Industry and Energy's K-Semiconductor Belt program channels subsidies toward domestic equipment qualification. MEMS development facilities in Suwon are increasing bond-alignment system specifications for multi-layer mechanical structures.
Germany
Research institutions in Dresden and Munich are adopting laser alignment systems for GaN and SiC device prototyping as component costs decline. ECHA's evolving REACH substance restrictions are accelerating equipment redesigns for photoresist handling components and vacuum seal materials. Precision motion subsystem suppliers in Baden-Württemberg are anchoring regional supply chain concentration for critical aligner components.
United States
University cleanrooms in California and Massachusetts are compressing ownership cycles through equipment leasing programs that reduce upfront capital barriers. The EPA and OSHA impose ventilation and ergonomic constraints on equipment operated by technicians in research facilities. Government labs in New Mexico are maintaining steady replacement cycles for aging contact-printing equipment in educational fabrication environments.
India
Domestic packaging houses under the PLI scheme are evaluating legacy 200mm alignment equipment imports as assembly and test capacity expands. The Central Electricity Authority and BIS certification requirements shape equipment qualification timelines for imported semiconductor tools. Facilities in Gujarat and Karnataka represent underdeveloped demand concentrations as domestic semiconductor assembly infrastructure scales.
Manual Wafer Aligner Market Competitive Landscape
On the supply side, the industry is tiered between precision motion specialists, lithography system integrators, and regional component fabricators. European and Japanese vendors anchor the premium tier through established service networks and cleanroom certification expertise. Mid-tier competition centers on bond-alignment specialization for MEMS applications and educational market leasing structures. Dominant competitive moves include geographic expansion through local distributor partnerships and technology licensing agreements for laser-interferometric subsystems.
Within the precision motion tier, HIWIN and Hamamatsu Photonics occupy positions anchored by component supply relationships with aligner OEMs. SUSS MicroTec exemplifies the European integrated-system archetype through sustained service revenue alongside hardware placements. EV Group sits within the bond-alignment specialization segment, serving MEMS fabrication requirements with differentiated motion control architectures. These three patterns—component supply, integrated-system service, and application-specific specialization—structure competitive positioning across procurement segments.
| Leading Market Players |
|---|
| HIWIN |
| Burgeon Instrument |
| Hamamatsu Photonics |
| Chung King Enterprise |
| Applied Microengineering |
| EMU Technologies |
| EV Group |
| OAI |
| SUSS MicroTec |
| Others |
Pricing and Supply Chain Analysis
Export control variability on precision motion subsystems from Germany and Japan determines both pricing tier spreads and supply chain shape, forcing buyers to absorb lead-time premiums or qualify secondary sources. Foundries in Taiwan and South Korea face divergent cost structures depending on their exposure to these concentrated component flows.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by ISO 14644 cleanroom certification grade and bundled after-sales service intensity. Premium tiers command substantial markups for laser-interferometric systems with sub-micron accuracy guarantees, while economy positioning targets educational leasing channels with stripped-down optical configurations. Pricing pressure stems from automated stepper substitution threats at volume thresholds, compressing margins in mid-tier standard offerings. University cleanrooms exhibit highest price sensitivity due to fixed grant cycles, whereas automotive chip suppliers serving European OEMs prioritize traceability compliance over unit cost.
Supply Chain Analysis
Export control regimes restricting precision motion technology flows from Germany and Japan fragment component availability across procurement tiers. Critical granite air-bearing stages and interferometric encoders draw from specialized suppliers concentrated in Baden-Württemberg and Hamamatsu production clusters. Supply chain risk centers on single-source vulnerability for vacuum-compatible linear motors, with no qualified alternatives meeting SEMI S2 safety guidelines. Distribution runs through lithography system integrators with captive service networks, limiting direct component access for end-user fabs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manual wafer aligner procurement is restructuring around service-attach revenue, with maintenance and upgrade contracts expanding faster than hardware placements as leasing models displace outright purchase.
For Market Incumbents: Pre-empt automated stepper substitution by embedding predictive maintenance telemetry into legacy aligner fleets, locking in recurring revenue before semi-automated alternatives capture volume thresholds. Consolidate position through backward integration into precision granite substrate machining, reducing exposure to German component lead-time volatility. Prioritize EU Chips Act certification pre-qualification to capture European automotive chip demand before traceability mandates harden procurement requirements. For New Entrants and Emerging Players: Indian packaging house underpenetration offers the most accessible white-space target, with PLI scheme capacity expansion creating immediate demand for legacy 200mm alignment equipment without entrenched incumbent relationships. MEMS prototyping surge in German and Japanese research institutions represents a secondary entry vector for laser-optical convergence systems. Pursue equipment-as-a-service go-to-market structures that reduce upfront capital barriers for university cleanrooms while capturing long-term maintenance contracts. For Investors and Strategic Acquirers: EU Chips Act traceability mandates reshape the acquisition landscape toward vendors with pre-qualified component-level tracking infrastructure. Long-term viability hinges on service revenue attachment rates exceeding hardware replacement cycles. Target precision motion subsystem specialists with established SEMI S2 certification pathways. Monitor REACH substance restriction evolution as the critical inflection signal—accelerated ECHA candidate list expansion would force portfolio-wide equipment redesigns and consolidation pressure on undercapitalized vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Service Revenue Attachment | Bundled maintenance contracts with university cleanrooms create recurring revenue streams that outlast hardware depreciation cycles. |
| Precision Component Backward Integration | In-house production of granite air-bearing stages insulates lead times from German export control variability. |
| Laser-Optical Convergence Development | Sub-micron interferometric systems capture compound semiconductor prototyping demand from GaN and SiC device manufacturers. |
| Educational Leasing Channel Expansion | Equipment-as-a-service models reduce grant-cycle friction for research laboratories while locking in upgrade pathways. |
| EU Chips Act Pre-Qualification | Component-level traceability certification opens European automotive chip fab procurement before mandates fully harden. |
Research Methodology
Operator-level perspectives from fab equipment procurement managers, cleanroom facility directors, precision motion subsystem engineers, and lithography tool maintenance heads anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through SEMI industry association filings, customs trade data for lithography equipment imports, SEC 10-K disclosures from listed semiconductor capital equipment vendors, and ISO 14644 certification registry records. Bottom-up equipment shipment tallies triangulated against top-down foundry capex allocation surveys to constrain volume estimates.
Scenario-bracketing around EU subsidy disbursement timelines and REACH compliance acceleration informed projection boundaries across the modeling period. Segmentation dimensions included aligner architecture type, alignment technology tier, end-use application maturity, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and foundry capacity expansion announcements, with cross-checks against university grant funding trajectories and packaging house PLI scheme utilization rates.
Practitioners should monitor export control list revisions and ECHA candidate list expansion for early signals of supply disruption or qualification timeline extension. Forecasts reflect assumptions on leasing model penetration rates and mature-node foundry capacity persistence. Material shifts in EU automotive chip demand trajectories or automated stepper cost curves would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Global Dry Etching Machine Market
Semiconductor Fabrication
Semiconductor Etching Cleaner Market
Semiconductor Fabrication
Diamond Semiconductor Substrates Market
Semiconductor Fabrication
Thin Layer Deposition Market
Semiconductor Fabrication
Global Atomic Layer Deposition Market
Semiconductor Fabrication
300mm Silicon Wafers Market
Semiconductor Fabrication
Physical Vapor Deposition (PVD) Market
Semiconductor Fabrication
Global Micromachining Market
Semiconductor Fabrication
Deep Reactive Ion Etching (DRIE) Etcher Market
Semiconductor Fabrication
Additive Manufacturing in Semiconductor Market
Semiconductor Fabrication
Ion Implantation Machine Market
Semiconductor Fabrication
Semiconductor Photoresist Polymer Market
Semiconductor Fabrication
8-Inch Silicon Carbide (Sic) Wafer Market
Semiconductor Fabrication
Photoresist Removal Market
Semiconductor Fabrication
Sic Wafer Reclaim Services Market
Semiconductor Fabrication
Semiconductor Foundry Market