
 Thin Layer Deposition Market | 2026-2036
Thin Layer Deposition Market Size, Share, and Industry Trends Forecast 2026-2036
Thin Layer Deposition Market Analytics
Buyer concentration in semiconductor fabrication is shifting toward integrated device manufacturers and foundries operating at advanced nodes. Applied Materials Inc. leverages its broad process equipment portfolio to serve these consolidated buyers. Lam Research Corporation anchors its position through etch and deposition technology leadership. Tokyo Electron Limited competes across multiple deposition modalities with strong presence in Asian manufacturing hubs.
Thin layer deposition encompasses controlled processes that deposit material films ranging from angstroms to micrometers onto substrates, utilizing vacuum environments, plasma activation, or thermal energy to achieve precise thickness and uniformity for functional surface modification. Atomic layer deposition commands premium positioning due to its angstrom-level precision in advanced semiconductor nodes, while chemical vapor deposition sustains volume leadership across mature logic and memory production. Physical vapor deposition occupies established positions in hard disk drive and legacy semiconductor applications where cost efficiency outweighs atomic-scale precision requirements.
EPA air emission standards and OSHA workplace exposure limits constrain process chemistry selection and abatement system design in US manufacturing facilities, while REACH registration requirements govern precursor chemical usage across European operations. China's MEE enforces escalating discharge standards that affect deposition equipment configuration for domestic fabs. Stakeholders must evaluate regulatory trajectory divergence when siting new deposition capacity or qualifying alternative precursor chemistries.
Market Dynamics
Semiconductor node shrinkage below 3nm is forcing deposition equipment makers to deliver angstrom-level precision at throughput levels previously associated with nanometer-scale processes, compressing development cycles and tightening qualification protocols across the supply base.
Growth Catalysts
- Advanced Node Proliferation:Logic and memory fabs in South Korea and Taiwan are scaling atomic layer deposition for gate-all-around transistor architectures, pulling equipment spend forward.
- EPA Air Emission Standards:US OSHA workplace exposure limits for metal-organic precursors are accelerating abatement system upgrades, creating replacement demand for compliant deposition tools.
- Power Device Expansion:Silicon carbide and gallium nitride epitaxy for electric vehicle traction inverters is diversifying chemical vapor deposition demand beyond traditional semiconductor applications.
Market Restraints
- Precursor Supply Concentration:High-purity metal-organic precursor synthesis concentrates among German and Japanese specialty chemical suppliers, exposing deposition tool makers to input bottlenecks.
- Technical Throughput Ceiling:Atomic layer deposition's sequential reactant pulsing imposes fundamental cycle time limits that constrain cost economics for commodity memory layers.
- EU REACH Registration Burden:ECHA chemical authorization timelines for novel precursor molecules extend 18-36 months, delaying process qualification for European fabs.
Strategic Opportunities
- India Semiconductor Mission:PLI scheme incentives for domestic fab construction are creating first-mover positioning for deposition equipment vendors establishing local service infrastructure.
- Photonics Integration:Silicon photonics foundries are adopting plasma-enhanced chemical vapor deposition for waveguide cladding, opening non-traditional demand channels.
- Advanced Packaging Redistribution Layers:Fan-out wafer-level packaging is displacing traditional interconnect methods, requiring conformal dielectric deposition at panel-scale formats.
Industry Challenges
- Process Engineer Scarcity:Atomic layer deposition recipe development demands rare combinations of surface chemistry expertise and vacuum system operation experience, constraining fab ramp timelines.
- Qualification Cycle Compression:Leading-edge node introductions now require simultaneous precursor, equipment, and process qualification, stretching supplier engineering resources across multiple workstreams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin Layer Deposition Market |
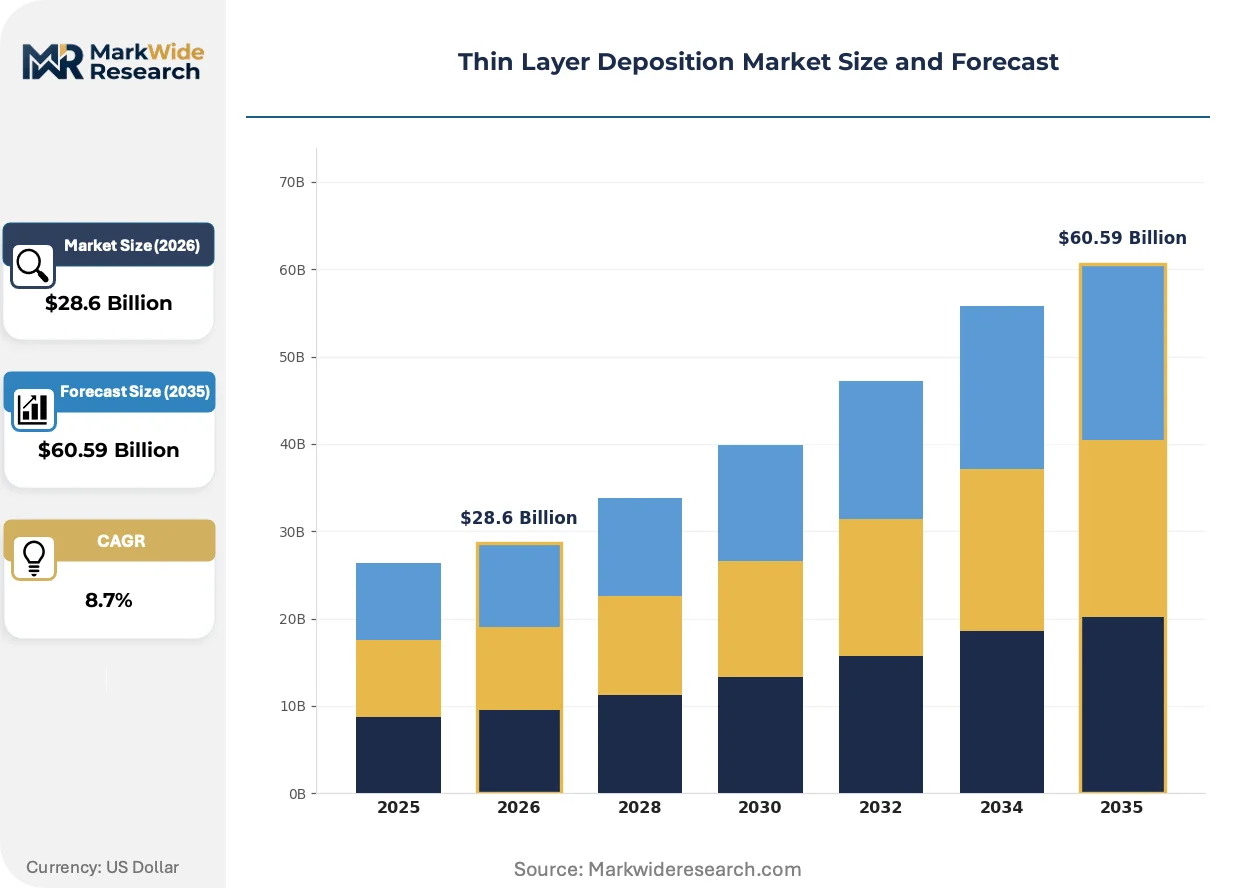
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Physical Vapor Deposition, Chemical Vapor Deposition, Atomic Layer Deposition, Sputtering Technology: Vacuum, Plasma, Laser, Thermal End User: Electronics, Aerospace, Automotive, Medical Application: Coatings, Semiconductor Fabrication, Optoelectronics, Thin-Film Solar Cells |
| Companies Covered | Applied Materials Inc., Lam Research Corporation, Tokyo Electron Limited, ASM International NV, Veeco Instruments Inc., Aixtron SE, Advanced Micro-Fabrication Equipment Inc., Oxford Instruments plc, ULVAC Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin Layer Deposition Market Evolving Landscape
Deposition technology evolution is bifurcating between precision-first atomic layer methods and throughput-optimized spatial variants, with regulatory chemistry constraints and end-use diversification forcing parallel innovation tracks rather than sequential replacement.
Spatial atomic layer deposition is expanding into high-volume memory manufacturing by decoupling precursor exposure from wafer motion, enabling continuous substrate transport through segregated reaction zones. NAND flash producers in South Korea are piloting these systems for 3D stack dielectric deposition, compressing cost-per-wafer toward chemical vapor deposition parity while maintaining atomic-scale thickness control.
China's MEE is enforcing escalating discharge standards for perfluorinated compound emissions from plasma etch and deposition processes, compelling domestic fabs to retrofit abatement systems or qualify fluorine-free chemistries. Equipment vendors are responding with integrated thermal scrubber architectures that capture unreacted precursors at source, particularly affecting tungsten chemical vapor deposition tool configurations for logic contact fill applications.
Integrated device manufacturers are consolidating deposition equipment procurement under multi-year strategic supply agreements that bundle preventive maintenance, consumables, and process optimization services. This unbundles traditional capital-only transactions and shifts supplier relationships toward performance-guaranteed partnerships, with the most pronounced adoption visible among US memory producers seeking to lock capacity during supply-constrained periods.
Thin Layer Deposition Market Segmentation
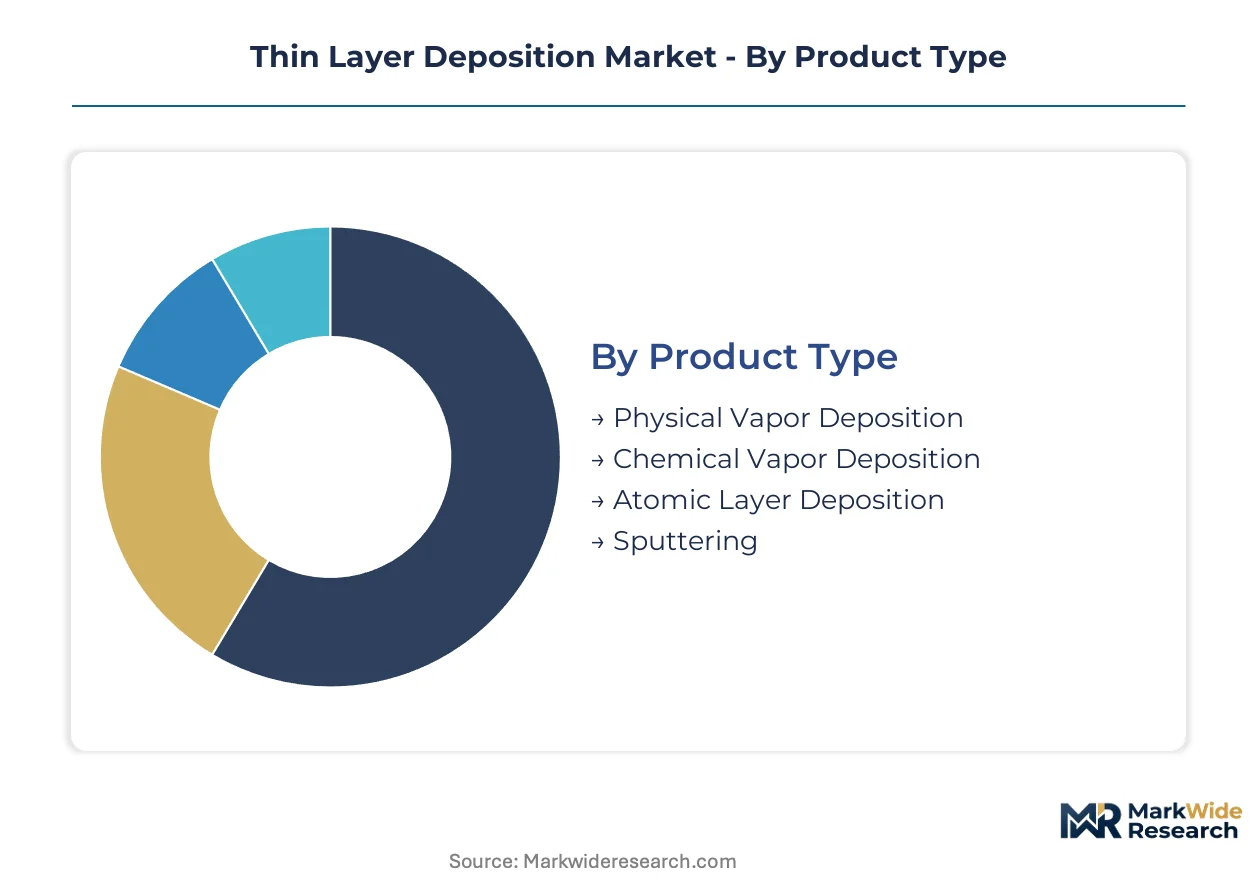
Thin layer deposition equipment and materials exhibit divergent performance characteristics across process modalities and end-use requirements. Segmentation reveals where angstrom-scale precision commands premium positioning versus throughput-optimized configurations.
Product Type:
Chemical vapor deposition systems function as standalone production units in high-volume fabs, while atomic layer deposition often integrates into multi-process cluster tools alongside etch and metrology modules.
- Chemical Vapor Deposition:Delivers conformal films through gas-phase precursor reactions at elevated temperatures, sustaining volume leadership across mature logic and memory production. South Korea's Pyeongtaek cluster deploys tungsten CVD for contact fill at advanced nodes. Tool configurations must accommodate China's MEE discharge standards for perfluorinated compound emissions.
- Atomic Layer Deposition:Achieves angstrom-level thickness control through sequential self-limiting surface reactions, commanding premium positioning for gate-all-around transistor architectures. Taiwan's Hsinchu Science Park scales ALD for high-k dielectric and metal gate stacks. Sequential reactant pulsing imposes fundamental throughput constraints that limit commodity memory applications.
- Physical Vapor Deposition:Evaporates or sputters solid source materials in vacuum environments for metal interconnect and barrier layers.
- Sputtering:Ionizes inert gas to eject target material onto substrates, dominating hard disk drive magnetic media and legacy semiconductor metallization.
Chemical vapor deposition leads volumes today; atomic layer deposition is gaining share fastest.
Technology:
Cost tiers separate vacuum-based batch systems from plasma-enhanced single-wafer platforms requiring radio-frequency power delivery and chamber-matched impedance tuning.
- Plasma:Generates ionized species through RF or DC excitation to enable low-temperature deposition with enhanced film density. Silicon photonics foundries adopt plasma-enhanced CVD for waveguide cladding at temperatures compatible with pre-patterned substrates. Process uniformity depends on chamber design and gas flow dynamics.
- Vacuum:Maintains sub-atmospheric pressure to eliminate gas-phase reactions and enable controlled mean free paths for evaporated species. Thermal evaporation systems serve optical coating and decorative applications where thickness precision exceeds purity requirements. Pump-down cycle time constrains batch throughput economics.
- Thermal:Activates surface reactions through substrate heating without plasma enhancement, sustaining positions in epitaxial silicon and compound semiconductor growth.
- Laser:Delivers localized energy for pulsed laser deposition of complex oxide films and superlattice structures in research and specialty production.
Vacuum technology anchors the largest installed base; plasma configurations show the steepest expansion trajectory.
End User:
Customer type segmentation distinguishes captive fabs with internal process development from merchant foundries purchasing turnkey deposition solutions.
- Electronics:Encompasses integrated device manufacturers and pure-play foundries fabricating logic, memory, and power devices. India's Semiconductor Mission PLI incentives are attracting deposition equipment vendors to establish local service infrastructure for projected domestic fab construction. Qualification cycles compress as leading-edge nodes require simultaneous precursor, equipment, and process validation.
- Automotive:Demands silicon carbide and gallium nitride epitaxy for electric vehicle traction inverters, diversifying CVD demand beyond traditional semiconductor applications. Power device producers qualify deposition tools for 150mm and 200mm SiC substrates with defect density requirements distinct from silicon logic. Thermal budget constraints from SiC crystal quality limit process temperature windows.
- Aerospace:Utilizes erosion-resistant coatings and thermal barrier systems on turbine components.
- Medical:Applies biocompatible coatings to implants and drug-eluting surfaces requiring sterilization stability.
Electronics dominates current procurement; automotive is climbing the fastest as electrification accelerates.
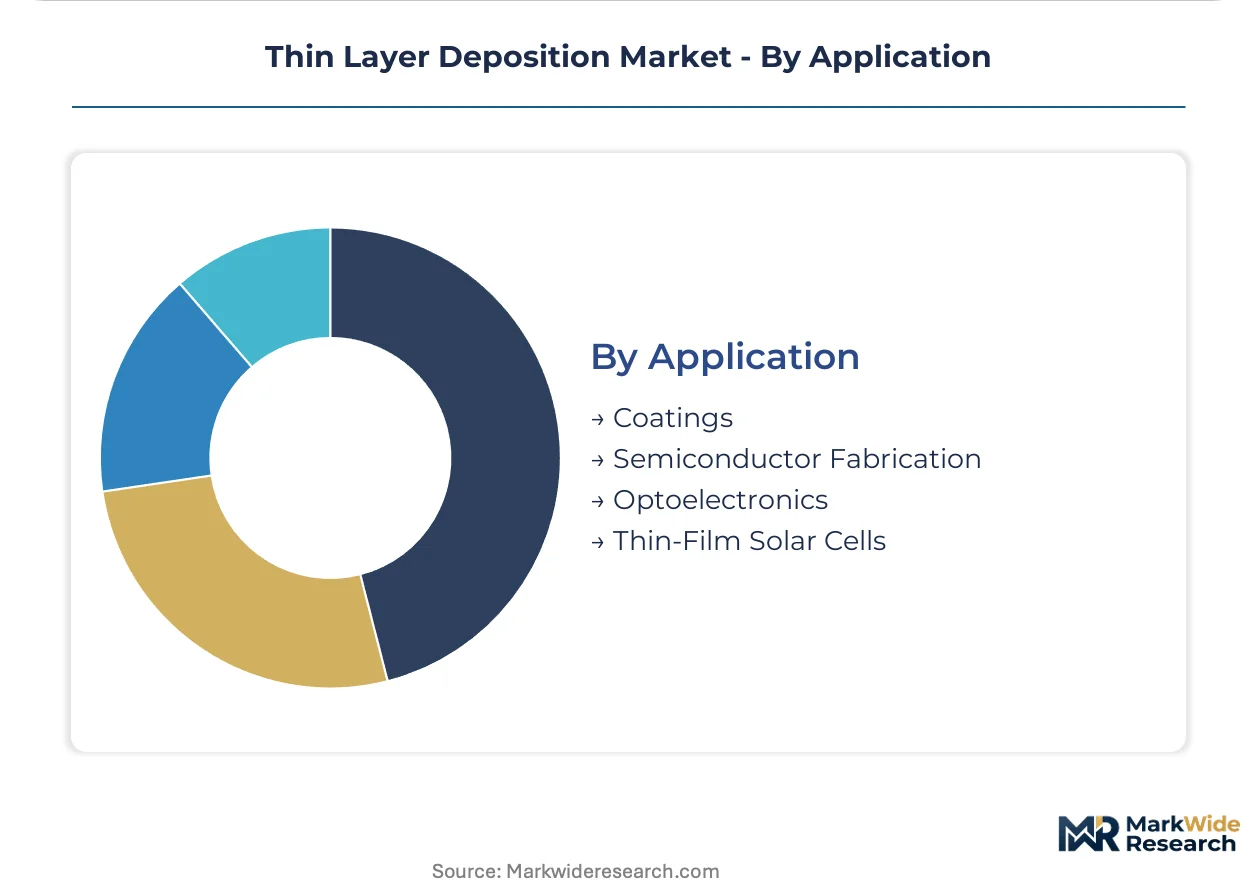
Application:
Application maturity varies from volume-proven semiconductor fabrication to emerging panel-scale advanced packaging formats.
- Semiconductor Fabrication:Constitutes the primary demand driver with deposition serving front-end-of-line transistor formation and back-end-of-line interconnect build. EU REACH registration timelines of 18-36 months for novel precursors delay process qualification for European fabs. Node shrinkage below 3nm forces equipment makers to deliver angstrom precision at throughput levels previously associated with nanometer processes.
- Coatings:Spans decorative, protective, and functional surface modifications across industrial and consumer goods. Tool architectures prioritize deposition rate and substrate size flexibility over atomic-scale thickness control. OSHA workplace exposure limits for metal-organic precursors accelerate abatement system upgrades in US manufacturing facilities.
- Optoelectronics:Requires precise refractive index control for LED, laser, and photodetector structures.
- Thin-Film Solar Cells:Deposits photovoltaic absorber and transparent conductive oxide layers on glass or flexible substrates.
Semiconductor fabrication leads volumes today; coatings applications are expanding most quickly in industrial diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Process engineers with atomic layer deposition expertise cluster disproportionately in South Korea, Taiwan, and Japan, creating talent scarcity that constrains fab ramp timelines in emerging manufacturing regions.
United States
Memory producers in Idaho and California are consolidating equipment procurement under multi-year strategic supply agreements that bundle preventive maintenance with process optimization services. EPA air emission standards and OSHA workplace exposure limits for metal-organic precursors accelerate abatement system upgrades across domestic fabs. Austin and Phoenix manufacturing corridors attract deposition equipment vendors establishing localized service infrastructure.
South Korea
Logic and memory fabs in Pyeongtaek scale atomic layer deposition for gate-all-around transistor architectures below 3nm, pulling equipment spend forward from planned timelines. The Ministry of Environment enforces escalating discharge standards for perfluorinated compound emissions from plasma processes. Samsung and SK Hynix operations in the Seoul Capital Area dominate global NAND flash deposition demand.
Taiwan
TSMC and UMC foundries in Hsinchu Science Park deploy ALD for high-k dielectric and metal gate stacks at advanced nodes, compressing qualification cycles across supplier engineering resources. The island's national semiconductor strategy prioritizes domestic deposition technology development. Tainan and Taichung science parks expand specialty chemical precursor storage capacity.
China
Domestic fabs retrofit abatement systems to comply with MEE escalating discharge standards for unreacted precursors from tungsten chemical vapor deposition tools. The dual carbon goals tighten energy efficiency requirements for deposition equipment configuration. Yangtze River Delta and Beijing-Tianjin-Hebei clusters concentrate state-backed memory and logic construction.
Japan
Specialty chemical suppliers in Osaka and Tokyo prefectures concentrate high-purity metal-organic precursor synthesis, exposing deposition tool makers to input bottlenecks. METI industrial policy supports domestic equipment vendor competitiveness in atomic layer deposition modalities. Kyushu semiconductor material suppliers qualify novel chemistries under extended ECHA-equivalent timelines.
Thin Layer Deposition Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deposition modalities, creating a tiered structure where broad process equipment portfolios anchor against targeted technology leadership positions. The vendor base organizes around equipment scale, precursor chemistry integration depth, and geographic proximity to Asian manufacturing hubs. Three archetypes dominate: diversified process equipment conglomerates, deposition-technology pure-plays, and specialty chemical precursor suppliers. Competitive moves concentrate on strategic partnerships for precursor co-development and geographic expansion into emerging fab construction zones.
Within the diversified equipment tier, Applied Materials Inc. and Lam Research Corporation represent integrated process platform vendors competing across etch, deposition, and metrology modules. Tokyo Electron Limited occupies a position bridging multi-modality equipment supply with strong presence in Asian manufacturing hubs. ASM International NV exemplifies the deposition-technology pure-play archetype with focused atomic layer deposition specialization.
| Leading Market Players |
|---|
| Applied Materials Inc. |
| Lam Research Corporation |
| Tokyo Electron Limited |
| ASM International NV |
| Veeco Instruments Inc. |
| Aixtron SE |
| Advanced Micro-Fabrication Equipment Inc. |
| Oxford Instruments plc |
| ULVAC Inc. |
| Others |
Value Network & Pricing Analysis
Captive precursor synthesis by Japanese and German specialty chemical suppliers anchors both supply security and pricing power for deposition equipment vendors serving advanced node fabs. This backward integration into high-purity metal-organic chemistry insulates qualified suppliers from spot market volatility while exposing non-integrated tool makers to input cost pass-through.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for atomic layer deposition systems as Samsung and SK Hynix consolidate procurement under multi-year strategic supply agreements. Three-tier pricing structure across premium, standard, and economy levels separates angstrom-precision ALD platforms from throughput-optimized CVD tools and legacy PVD equipment. Cost compression in commodity memory deposition is intensifying because spatial ALD variants approach CVD economics. Merchant foundries exhibit highest price sensitivity; integrated device manufacturers prioritize performance guarantees over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from leading-edge fabs mandate multi-supplier qualification for metal-organic precursors, forcing equipment vendors to maintain redundant chemical partnerships. Geographic supply concentration centers on Japan, Germany, and the United States for precursor synthesis, with South Korea and Taiwan dominating fab operations. Raw material dependencies include high-purity tungsten hexafluoride, trimethylaluminum, and hafnium precursors. Single-source vulnerability concentrates among German specialty chemical suppliers for novel gate dielectric molecules. Distribution runs through direct equipment sales with bundled service contracts rather than channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EPA air emission standards and OSHA workplace exposure limits for metal-organic precursors continuously pull replacement demand for compliant abatement-integrated deposition tools.
For Market Incumbents: Deepen precursor co-development partnerships with Japanese and German specialty chemical suppliers to lock qualified chemistries ahead of REACH registration timelines. Anchor service infrastructure in India's emerging fab corridors under PLI scheme incentives. Defend against spatial ALD entrants by accelerating throughput improvements in conventional atomic layer platforms. For New Entrants and Emerging Players: China's MEE escalating discharge standards for perfluorinated compounds open a window for fluorine-free chemistry specialists to qualify with domestic fabs retrofitting tungsten CVD tools. Target silicon photonics foundries adopting plasma-enhanced CVD for waveguide cladding as the most penetrable non-traditional demand channel. Lead with integrated thermal scrubber architectures as the go-to-market differentiator. For Investors and Strategic Acquirers: Roll-up economics work for deposition-technology pure-plays because equipment vendor fragmentation across ALD, CVD, and PVD modalities creates multiple bite-sized targets with complementary customer relationships. Five-to-ten-year viability hinges on exposure to advanced node capital cycles rather than commodity memory replacement demand. Watch for qualification cycle compression at sub-3nm nodes as the inflection signal for supplier engineering resource constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Precursor Co-Development Partnership | Locks qualified chemistries ahead of ECHA authorization timelines for European fabs. |
| Spatial ALD Platform Launch | Enables NAND flash producers to compress cost-per-wafer toward CVD parity. |
| Integrated Abatement Retrofit | Addresses China's MEE discharge standards for domestic tungsten CVD tool configurations. |
| India Service Infrastructure Buildout | Positions vendors for Semiconductor Mission PLI-driven domestic fab construction. |
| Silicon Photonics Foundry Qualification | Opens plasma-enhanced CVD demand for waveguide cladding beyond traditional semiconductors. |
Research Methodology
Coverage spans South Korea, Taiwan, Japan, the United States, and China, with primary inputs from each major deposition equipment demand cluster. Process engineering directors at leading-edge fabs, specialty chemical procurement leads, and deposition equipment sales executives provided qualitative inputs. Secondary validation drew from SEC 10-K filings, ECHA registration databases, and customs trade data for precursor chemicals. Bottom-up equipment shipment tallies triangulated against top-down fab capital expenditure disclosures.
Rate-of-change decomposition anchored the analytical framework across the projection horizon, separating volume effects from mix shifts toward higher-precision ALD platforms. Segmentation dimensions modeled include deposition modality, technology activation mechanism, end-use industry, and regional regulatory cluster. CAGRs derived from equipment spend trajectories at named fabs and precursor consumption patterns. Industry-specific inputs incorporated EU REACH registration timelines and China's dual carbon energy efficiency mandates.
Revisions become necessary when semiconductor node transition schedules accelerate or stall, when precursor supply disruptions emerge from German or Japanese chemical suppliers, or when India's PLI scheme incentives shift domestic fab construction timelines. Deviation in EPA or MEE regulatory enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Solar Grade Wafer Market
Semiconductor Fabrication
Global Dry Etching Machine Market
Semiconductor Fabrication
Epitaxial Wafer Market
Semiconductor Fabrication
Porous Silicon Substrates Market
Semiconductor Fabrication
Semiconductor Advanced Substrate Market
Semiconductor Fabrication
Manual Wafer Aligner Market
Semiconductor Fabrication
Ion Implanter Market
Semiconductor Fabrication
Physical Vapor Deposition (PVD) Market
Semiconductor Fabrication
Semiconductor Photoresist Polymer Market
Semiconductor Fabrication
Holmium Sputtering Target Market
Semiconductor Fabrication
Etchant for FPD Market
Semiconductor Fabrication
Deep Reactive Ion Etching (DRIE) Etcher Market
Semiconductor Fabrication
Global Micromachining Market
Semiconductor Fabrication
8-Inch Silicon Carbide (Sic) Wafer Market
Semiconductor Fabrication
Global Atomic Layer Deposition Market
Semiconductor Fabrication
Semiconductor Logistics Market