
 Global Silicon Carbide (SIC) Market | 2026-2036
Global Silicon Carbide (SIC) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Silicon Carbide (SIC) Market Foresight
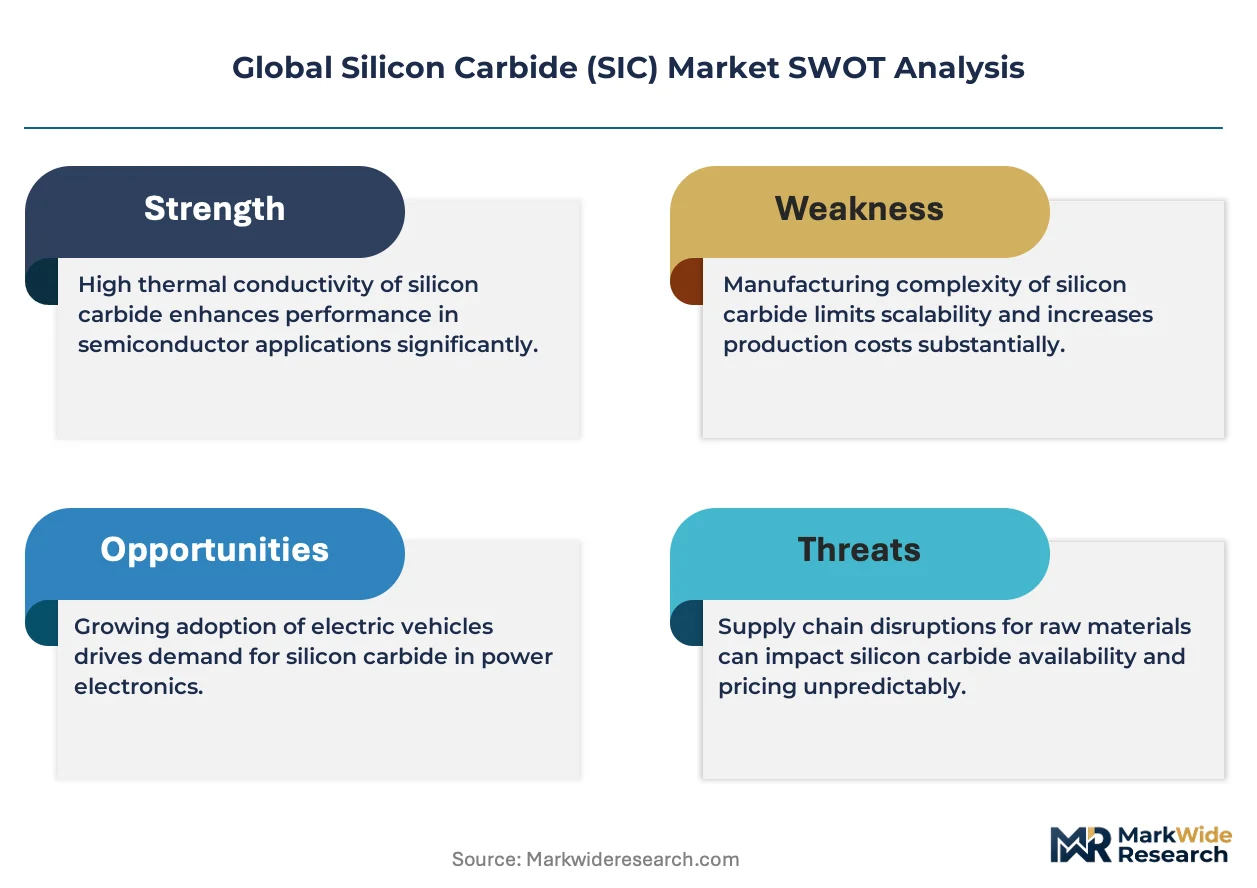
Subscription-based wafer supply agreements is repositioning how semiconductor manufacturers secure SiC substrate access. Wolfspeed leverages captive crystal growth facilities in North Carolina to control upstream material flows. Infineon Technologies AG anchors European automotive qualification pipelines through its Dresden fabrication complex. STMicroelectronics N.V. competes across integrated device manufacturing with SiC MOSFET lines serving multiple Tier-1 suppliers.
Silicon carbide is a wide-bandgap semiconductor compound of silicon and carbon atoms, synthesized through physical vapor transport or chemical vapor deposition at temperatures exceeding 2,200°C, delivering breakdown electric fields roughly ten times higher than silicon. Its primary purpose centers on high-voltage power switching where thermal conductivity above 490 W/mK enables compact inverter and converter architectures. SiC wafers command premium positioning due to defect density challenges and limited 150mm substrate availability, while SiC epitaxial layers capture expanding value as device architectures shift toward thinner, higher-performance stacks. Power Electronics applications lead current volume absorption, though Renewable Energy Systems represent the fastest structural expansion with utility-scale inverters and energy storage interfaces.
EPA tailpipe standards and the EU Green Deal's industrial decarbonization framework are mandating higher-efficiency power conversion, directly expanding qualified SiC component procurement pools. China's GB standards for new energy vehicles and NMPA semiconductor quality protocols are creating dual compliance pathways for suppliers seeking access across Western and Chinese EV supply chains. Stakeholders must monitor substrate diameter transitions from 150mm to 200mm and evolving automotive qualification timelines as determinants of competitive positioning.
Market Dynamics
Automotive electrification mandates across China, the United States, and the European Union are compressing SiC qualification timelines and forcing substrate suppliers to lock in multi-year wafer agreements before 200mm capacity ramps mature.
Growth Catalysts
- EPA Vehicle Emissions Standards:Tightening tailpipe regulations in the United States mandate higher-efficiency powertrains, expanding qualified SiC inverter procurement pools for domestic EV manufacturers.
- EU Green Deal Industrial Decarbonization:The framework's binding carbon reduction targets accelerate SiC deployment in heavy-duty transport and renewable energy conversion systems across member states.
- China EV Manufacturing Corridor:Concentrated production spanning Shanghai and Shenzhen generates concentrated substrate demand that pulls capacity allocation decisions eastward.
Market Restraints
- Substrate Cost Volatility:Limited 150mm wafer availability and defect density challenges maintain premium pricing that constrains adoption in cost-sensitive power applications.
- Upstream Supply Concentration:Physical vapor transport crystal growth capacity clusters in North Carolina and select Asian facilities, creating geographic chokepoints for substrate access.
- Technical Limitation:Basal plane dislocation defects in epitaxial layers continue to constrain device yield rates for high-voltage automotive qualification tiers.
Strategic Opportunities
- Utility-Scale Renewable Integration:Energy storage interfaces and grid-tied inverters represent underpenetrated demand verticals where SiC thermal performance justifies premium positioning.
- 200mm Substrate Transition:Wafer diameter expansion from 150mm to 200mm promises die-cost reduction for power module manufacturers qualifying next-generation EV platforms.
- Dual Compliance Pathways:China's GB standards for new energy vehicles create regulatory frameworks that suppliers can leverage for simultaneous Western and Chinese market access.
Industry Challenges
- Crystal Growth Talent Scarcity:The specialized thermal engineering expertise required for physical vapor transport operation remains concentrated among a limited pool of experienced practitioners.
- Automotive Qualification Timelines:AEC-Q101 certification cycles spanning 18-24 months compress revenue realization windows for new device architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Silicon Carbide (SIC) Market |
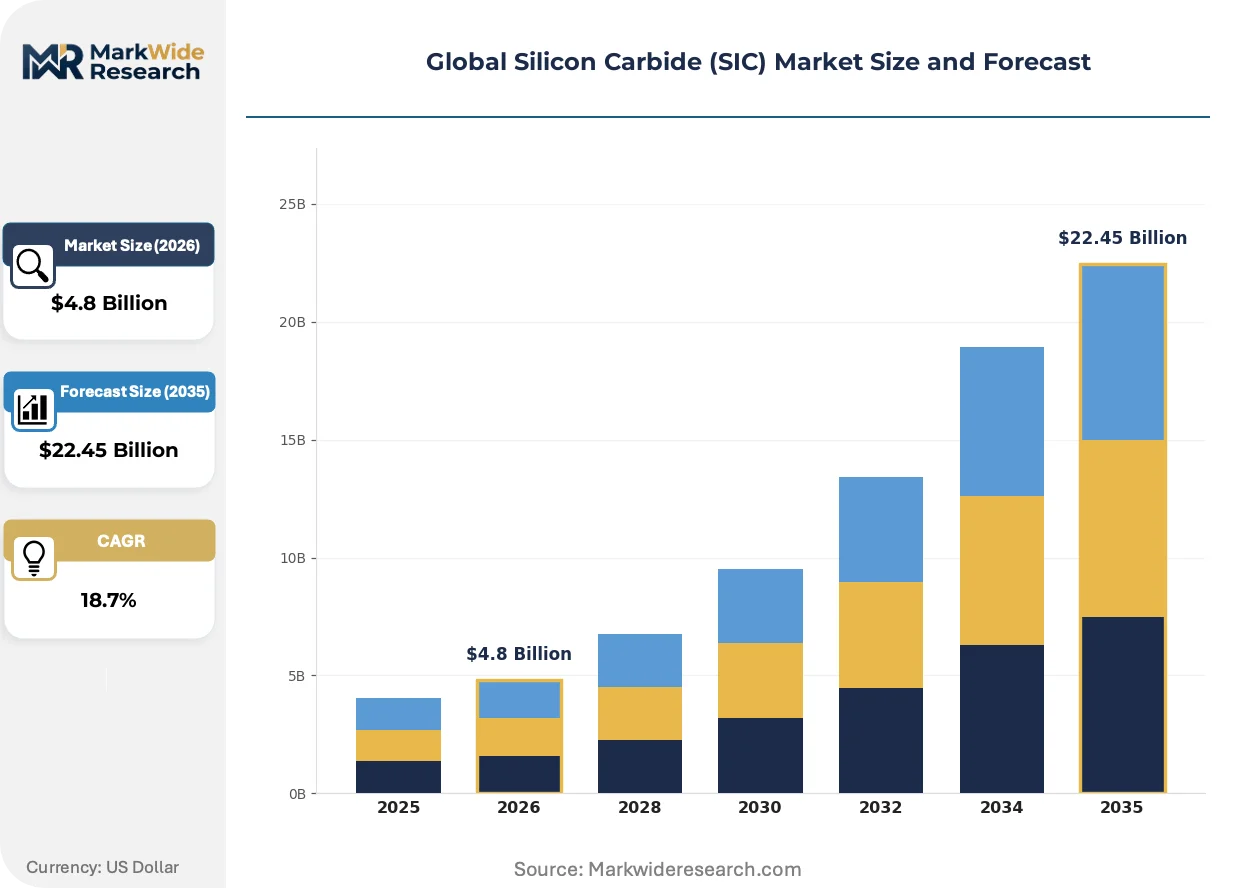
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SiC Wafers, SiC Powders, SiC Epitaxial Layers, SiC Substrates Technology: Metal Oxide Semiconductor Field Effect Transistor, Schottky Diodes, PiN Diodes, MOSFETs Application: Power Electronics, Renewable Energy Systems, Consumer Electronics, Aerospace & Defense End User: Semiconductor Manufacturers, Electronic Equipment Makers, Research Institutes, Automotive Tier-1 Suppliers |
| Companies Covered | Wolfspeed, Inc., Infineon Technologies AG, STMicroelectronics N.V., ROHM Co., Ltd., Semiconductor Components Industries, LLC, Toshiba Corporation, Mitsubishi Electric Corporation, ON Semiconductor Corporation, Microchip Technology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Silicon Carbide (SIC) Market Shifts & Advancements
SiC device architectures are thinning epitaxial stacks while expanding voltage ratings, compressing the traditional trade-off between performance and cost that has governed power semiconductor selection.
Thinner epitaxial layer designs are converging with trench-gate MOSFET architectures to reduce on-resistance without expanding wafer area requirements. Tier-1 automotive suppliers in Germany and the United States are accelerating qualification of these stacked configurations for 800V EV platforms. The structural consequence is converging with cost parity targets against silicon IGBTs in mid-power traction applications.
The EU Green Deal's F-Gas Regulation is phasing down fluorinated greenhouse gases used in semiconductor etching processes, forcing SiC manufacturers to retool cleaning and patterning workflows. Industrial consequence includes accelerated capital deployment toward dry etch alternatives and plasma-based surface preparation. European fabrication complexes in Dresden and Catania are most affected, with qualification pipelines extending to meet new environmental compliance tiers.
Subscription-based wafer supply agreements are displacing spot-market substrate purchases among integrated device manufacturers seeking volume certainty. Direct contracting with crystal growth facilities is replacing distributor-mediated procurement for automotive-qualified material tiers. This pattern is most visible in China, where NMPA semiconductor quality protocols add compliance layers that favor long-term supplier relationships over transactional sourcing.
Global Silicon Carbide (SIC) Market Segmentation
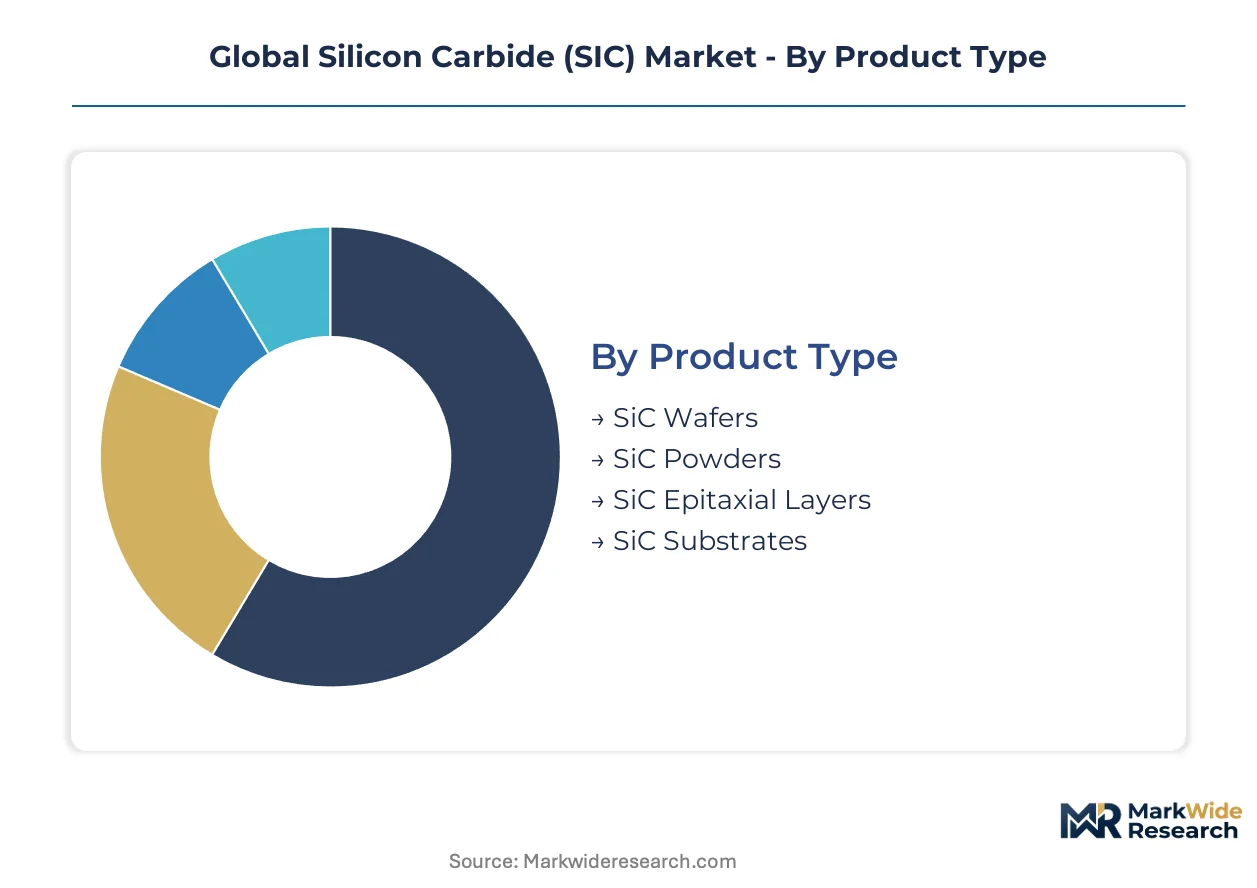
SiC market segmentation reveals distinct value capture patterns across the supply chain, from raw material conversion through device integration. Understanding how product form factors, device architectures, and end-use requirements intersect determines procurement strategy and margin positioning for stakeholders.
Product Type:
Standalone wafer products serve merchant markets and captive fabrication lines, while embedded substrate-epitaxy stacks integrate directly into device manufacturing workflows.
- SiC Wafers:These bulk crystalline discs form the foundational substrate for power semiconductor fabrication, with 150mm diameter specifications currently dominating automotive qualification pipelines. Demand concentrates in China's EV manufacturing corridor spanning Shanghai and Shenzhen, where NMPA semiconductor quality protocols enforce stringent defect density thresholds that constrain qualified supply.
- SiC Epitaxial Layers:Thin crystalline films deposited atop substrates determine device voltage ratings and switching performance through controlled doping profiles. Tier-1 automotive suppliers in Germany and the United States are accelerating qualification of thinner epitaxial stacks for 800V EV platforms, compressing the traditional performance-cost trade-off that governed power semiconductor selection.
- SiC Powders:Abrasive and ceramic-grade material feed industrial applications outside semiconductor device manufacturing.
- SiC Substrates:Finished wafer products with polished surfaces and specified orientation for direct epitaxial growth or device processing.
Volume placements concentrate in SiC Wafers; the faster expansion belongs to SiC Epitaxial Layers.
Technology:
Discrete device categories span unipolar and bipolar conduction mechanisms, with each architecture commanding distinct voltage-current operating envelopes and switching frequency suitability.
- MOSFETs:Unipolar switching devices leveraging trench-gate architectures to minimize on-resistance while maintaining high-voltage blocking capability. 800V EV traction inverters across China's new energy vehicle sector and European heavy-duty transport applications are pulling capacity allocation toward these structures.
- Schottky Diodes:Majority-carrier rectifiers eliminating reverse recovery losses that plague silicon alternatives, enabling higher-frequency converter designs. Renewable energy inverters in utility-scale deployments across the United States and EU member states under Green Deal decarbonization mandates are absorbing volume as designers prioritize efficiency over upfront component cost.
- Metal Oxide Semiconductor Field Effect Transistor:Planar-gate variants retaining relevance in cost-optimized industrial drives and consumer power supplies.
- PiN Diodes:Bipolar structures with conductivity modulation for ultra-high voltage applications beyond unipolar device limits.
Revenue concentration sits with MOSFETs; Schottky Diodes are climbing the fastest as renewable energy conversion scales.
Application:
Power density requirements and thermal management constraints differentiate deployment contexts, with some applications tolerating silicon alternatives while others mandate wide-bandgap performance.
- Power Electronics:Motor drives, converters, and inverters across industrial and transportation sectors where efficiency gains justify premium component positioning. EPA tailpipe standards tightening in the United States and China's GB standards for new energy vehicles are mandating higher-efficiency powertrains that expand qualified SiC component procurement pools.
- Renewable Energy Systems:Grid-tied inverters, energy storage interfaces, and photovoltaic power optimizers where thermal performance enables compact architectures. Utility-scale deployments across Germany, Spain, and the southwestern United States are gaining share fastest as project developers prioritize levelized cost of energy over capital expenditure minimization.
- Consumer Electronics:Compact adapters and charging infrastructure where form factor constraints override efficiency optimization.
- Aerospace & Defense:Radiation-hardened and high-reliability applications with extended qualification timelines and limited volume absorption.
Current volume absorption leads in Power Electronics; Renewable Energy Systems show the steepest expansion trajectory.
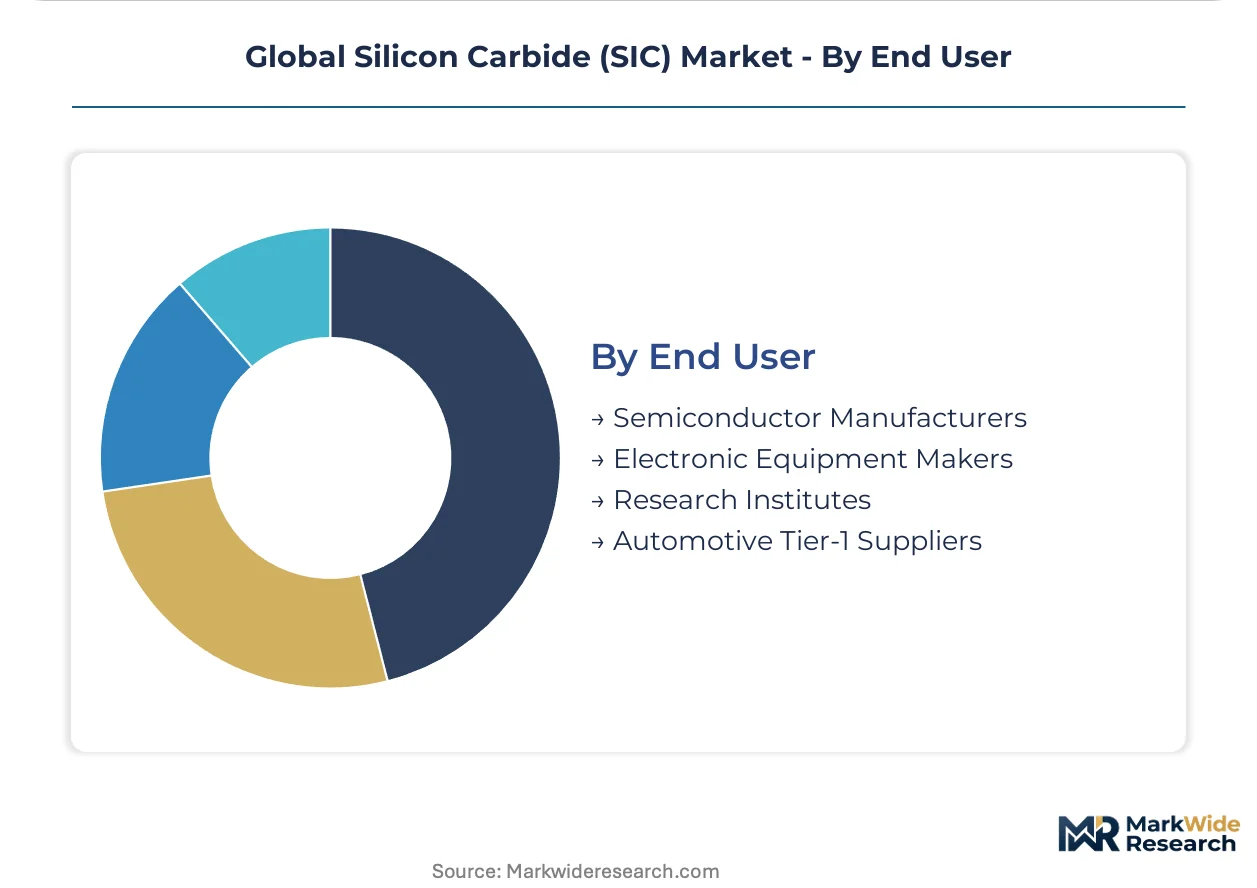
End User:
Integration depth varies dramatically across customer categories, from fully captive device manufacturing to merchant procurement of qualified components.
- Automotive Tier-1 Suppliers:Integrated module manufacturers qualifying SiC devices for 800V traction inverters, onboard chargers, and DC-DC converters. Multi-year wafer supply agreements with crystal growth facilities in North Carolina and Asian locations are displacing spot-market purchases as these suppliers secure volume certainty ahead of 200mm capacity ramps.
- Semiconductor Manufacturers:Integrated device manufacturers and foundries fabricating SiC devices for merchant sale or captive consumption. Dresden fabrication complexes and Catania facilities are anchoring European automotive qualification pipelines, with EU F-Gas Regulation compliance adding capital deployment requirements for dry etch alternatives.
- Electronic Equipment Makers:System integrators procuring qualified power modules for end-product assembly.
- Research Institutes:Pre-commercial volume for device physics research and next-generation architecture development.
Procurement scale concentrates with Automotive Tier-1 Suppliers; Semiconductor Manufacturers are expanding most quickly as merchant device supply matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Crystal growth capacity clusters in North Carolina while device fabrication concentrates in Germany and China, creating a geographic mismatch between substrate supply and downstream demand centers.
United States
EPA tailpipe standards mandate higher-efficiency powertrains that expand qualified SiC inverter procurement pools for domestic EV manufacturers. The Inflation Reduction Act's clean vehicle tax credits accelerate 800V platform adoption. Wolfspeed's captive crystal growth facilities in North Carolina anchor upstream material flows for automotive Tier-1 suppliers.
Germany
Heavy-duty transport electrification under EU Green Deal decarbonization mandates pulls capacity toward high-voltage automotive qualification. The EU F-Gas Regulation forces retooling of cleaning and patterning workflows in Dresden fabrication complexes. Infineon Technologies AG anchors European automotive qualification pipelines through its fabrication complex.
China
GB standards for new energy vehicles create dual compliance pathways for suppliers seeking Western and Chinese market access. NMPA semiconductor quality protocols enforce stringent defect density thresholds. The EV manufacturing corridor spanning Shanghai and Shenzhen generates concentrated substrate demand that pulls capacity allocation decisions eastward.
Japan
METI industrial decarbonization roadmaps accelerate SiC deployment in renewable energy conversion systems. JIS standards govern power semiconductor quality tiers for automotive and industrial applications. Toshiba Corporation and Mitsubishi Electric Corporation anchor domestic device fabrication for regional supply chains.
South Korea
MFDS-equivalent semiconductor quality frameworks support automotive qualification pipelines for export-oriented manufacturers. Government battery-EV industrial policy concentrates demand in Seoul Capital Area module assembly operations. Domestic power electronics specialists compete for substrate allocation against Chinese and Japanese buyers.
Global Silicon Carbide (SIC) Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a market structure that rewards captive crystal growth and long-term wafer supply agreements. Integrated device manufacturers with in-house fabrication capabilities hold procurement advantages over merchant foundry customers. Two strategic archetypes dominate: vertically integrated substrate-to-device producers and specialized epitaxial layer suppliers. Competitive moves center on multi-year wafer contracting and 200mm substrate qualification timelines.
Among integrated device manufacturers, Wolfspeed, Inc., Infineon Technologies AG, and STMicroelectronics N.V. exemplify the capital-intensive archetype that combines upstream crystal growth with downstream device fabrication. These entities occupy positions where captive material flows insulate against substrate cost volatility. Asset-light designers without crystal growth capabilities face procurement constraints as subscription-based wafer agreements displace spot-market purchases.
| Leading Market Players |
|---|
| Wolfspeed, Inc. |
| Infineon Technologies AG |
| STMicroelectronics N.V. |
| ROHM Co., Ltd. |
| Semiconductor Components Industries, LLC |
| Toshiba Corporation |
| Mitsubishi Electric Corporation |
| ON Semiconductor Corporation |
| Microchip Technology Inc. |
| Others |
Supply & Pricing Matrix
200mm substrate qualification timelines are compressing cost economics while simultaneously concentrating supply control among crystal growth specialists with captive North Carolina facilities. This diameter transition forces device manufacturers into multi-year wafer agreements that lock in pricing before economies of scale materialize.
Pricing Analysis
Margin tightening in automotive-qualified epitaxial layers reflects defect density premiums and AEC-Q101 certification overhead. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade tiers separates qualified supply from merchant spot markets. Cost-down pressure on 150mm substrates accelerates because 200mm ramp delays maintain scarcity premiums. Automotive Tier-1 suppliers show least price sensitivity; consumer power supply integrators face acute budget constraints.
Supply Chain Analysis
Freight costs for SiC substrates from North Carolina fabrication complexes to German automotive module plants add geographic premiums to landed costs. Physical vapor transport crystal growth capacity clusters in the United States, China, and Japan, drawing from high-purity silicon feedstock and graphite crucible components. Single-source vulnerability concentrates in 150mm substrate supply as 200mm qualification timelines extend. Distribution runs through direct long-term contracts rather than distributor-mediated spot purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trench-gate MOSFET architectures are displacing planar-gate silicon IGBTs in 800V EV platforms, compressing qualification windows for legacy technology suppliers.
For Market Incumbents: Extend captive crystal growth capacity in North Carolina ahead of 200mm substrate ramps to defend against merchant foundry competitors. Lock multi-year wafer agreements with automotive Tier-1 suppliers before Chinese GB standards compliance requirements harden procurement preferences. Prioritize AEC-Q101 certification pipeline investment as EPA tailpipe standards tighten qualification timelines. For New Entrants and Emerging Players: Enter via utility-scale renewable energy inverter segments where SiC thermal performance justifies premium positioning against silicon alternatives. Target energy storage interface applications in Germany and the southwestern United States where project developers prioritize efficiency over capital expenditure minimization. Pursue NMPA semiconductor quality protocol certification for simultaneous Western and Chinese market access. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of specialized epitaxial layer suppliers with established automotive qualification pipelines. Five-to-ten year viability hinges on 200mm substrate transition execution and EU F-Gas Regulation compliance capital deployment. Monitor AEC-Q101 certification backlog as inflection indicator for revenue realization capacity.| Strategic Initiative | Industry Significance |
|---|---|
| 200mm Substrate Qualification | Die-cost reduction for power module manufacturers accelerates 800V EV platform adoption. |
| Multi-Year Wafer Supply Agreement | Volume certainty for automotive Tier-1 suppliers displaces spot-market substrate purchases. |
| EU F-Gas Regulation Compliance | Dry etch retooling in Dresden fabrication complexes extends qualification pipelines. |
| Trench-Gate MOSFET Architecture | Thinner epitaxial stacks reduce on-resistance without expanding wafer area requirements. |
| NMPA Quality Protocol Certification | Dual compliance pathways enable simultaneous Western and Chinese EV supply chain access. |
Research Methodology
Independent corroboration across primary interviews with crystal growth engineers, automotive Tier-1 procurement directors, and power electronics design leads underwrites the qualitative findings. Secondary validation draws from EPA regulatory filings, EU Green Deal implementation documents, NMPA semiconductor quality protocols, and customs trade data for SiC substrate imports. Bottom-up device demand modeling triangulates against top-down substrate capacity assessments.
Comparable-period anchoring to historical 150mm substrate ramp curves informs projection assumptions across the analysis window. Segmentation dimensions include product type, device architecture, application voltage tier, and regional regulatory cluster. CAGRs derive from installed base growth in EV powertrains and renewable energy inverters. Forecast inputs incorporate automotive qualification timeline distributions and crystal growth yield improvement trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under 200mm substrate ramp delays or basal plane dislocation defect persistence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Chromium Oxide Market
Semiconductor Material
India Liquid Silicon Rubber Market
Semiconductor Material
Organic Silicon Coating Market
Semiconductor Material
Electronic Circuit Board Level Underfill Material Market
Semiconductor Material
Synthetic Single Crystal Diamond Market
Semiconductor Material
Middle East Silicon Carbide (Sic) Market
Semiconductor Material
Silicon Tetrachloride Market
Semiconductor Material
Semiconductor Film Market
Semiconductor Material
Polysilicon for Solar Semiconductor Market
Semiconductor Material
Global Silicon Alloys Market
Semiconductor Material
EV Capacitor Films Market
Semiconductor Material
Hafnium Market
Semiconductor Material
Terbium Oxide Market
Semiconductor Material
Synthetic Sapphire Market
Semiconductor Material
Silicon Metal Market
Semiconductor Material
Semiconductor PI Film Market