
 Ship Repair and Maintenance Services Market | 2026-2036
Ship Repair and Maintenance Services Market Size, Share, and Industry Trends Forecast 2026-2036
Ship Repair and Maintenance Services Market Intelligence
ISO 9001 and IACS member society certifications is bifurcating the competitive landscape between accredited full-service yards and localized repair shops. Huntington Ingalls Industries dominates nuclear-capable naval maintenance on the US East Coast. Cochin Shipyard Limited anchors India's indigenous carrier and submarine refit programs. BAE Systems Ship Repair leverages its Portsmouth and San Diego facilities to sustain Royal Navy and US Navy contracts simultaneously.
Ship repair and maintenance services encompass hull steel renewal, machinery overhaul, and electrical system restoration performed in dry dock or afloat conditions, typically governed by classification society rules and statutory flag-state requirements. The primary purpose is extending vessel operational life while preserving seaworthiness and regulatory compliance. Hull maintenance and dry docking represent the mature revenue base where pricing pressure from shipping companies squeezes margins, while predictive maintenance and automated inspection systems capture expanding budgets from offshore operators seeking to minimize unplanned downtime. Engine overhaul work concentrates around major port hubs with deepwater access and crane capacity.
The International Maritime Organization enforces Energy Efficiency Existing Ship Index mandates that compel owners to schedule hull cleaning and propeller polishing during mandatory dry-docking windows. Classification societies including Lloyd's Register and DNV execute statutory surveys that determine repair scope and yard selection criteria. Stakeholders must monitor how EU Green Deal-aligned fuel-transition deadlines reshape engine retrofit demand across European-flagged fleets.
Market Dynamics
The International Maritime Organization's Energy Efficiency Existing Ship Index is compressing dry-docking cycles and forcing simultaneous hull coating upgrades with engine retrofits, restructuring yard scheduling and capacity allocation worldwide.
Growth Catalysts
- IMO Carbon Intensity Regulations:Mandatory Energy Efficiency Existing Ship Index compliance is compelling vessel operators to bundle hull cleaning, propeller polishing, and engine system upgrades during statutory dry-docking windows, expanding repair scope per vessel.
- Naval Fleet Modernization:Nuclear-capable and conventional naval forces in the United States, United Kingdom, India, and South Korea are accelerating submarine and aircraft carrier refit programs, creating sustained demand for specialized defense-grade maintenance capacity.
- Predictive Maintenance Technologies:Automated inspection systems and condition-monitoring sensors are supplanting calendar-based maintenance schedules among offshore operators seeking to minimize unplanned downtime and optimize asset utilization.
Market Restraints
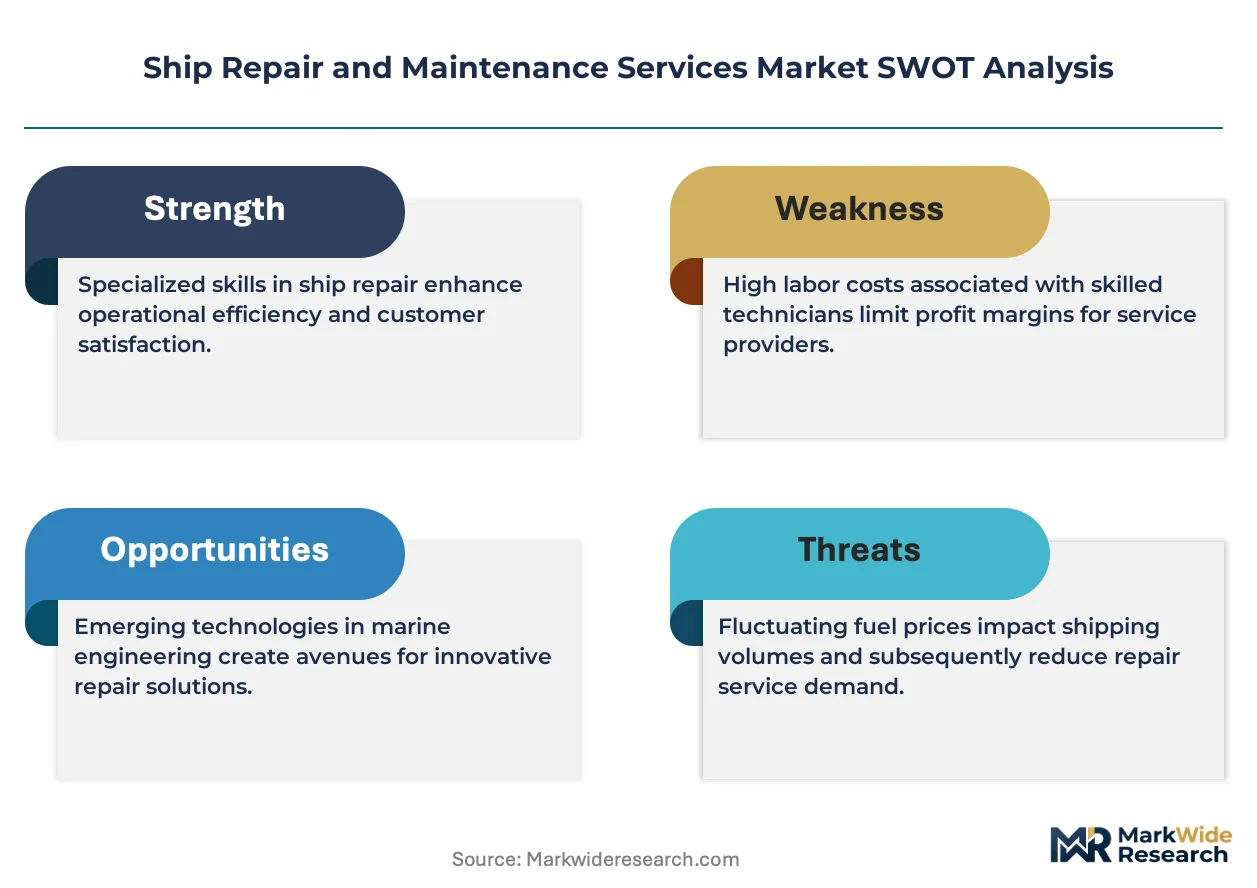
- Skilled Labor Scarcity:Certified welders, marine engineers, and nuclear-qualified technicians concentrate in legacy shipyard clusters, constraining capacity expansion and inflating wage costs in Singapore, South Korea, and the US East Coast.
- Steel and Coating Input Volatility:Specialized marine-grade steel plate and low-friction hull coating formulations face supply concentration among a limited supplier base, exposing repair yards to raw material price swings and delivery delays.
- Classification Society Fragmentation:Divergent interpretation of Lloyd's Register, DNV, and American Bureau of Shipping rules across flag-state jurisdictions creates compliance friction, extending quotation timelines and repair scope disputes.
Strategic Opportunities
- Alternative Fuel Retrofit Demand:EU Green Deal-aligned fuel-transition deadlines for methanol, ammonia, and LNG propulsion systems are reshaping engine overhaul demand across European-flagged fleets, creating specialized conversion capacity requirements.
- Underpenetrated Indian Ocean Basin:Sri Lanka, Oman, and Djibouti lack deepwater repair infrastructure relative to transshipment volume growth, presenting greenfield yard development opportunities for regional operators.
- Digital Twin Integration:Convergence of hull laser scanning, finite element analysis, and real-time operational data is enabling remote survey pre-qualification and repair scope optimization, reducing dry-docking duration.
Industry Challenges
- Certification Timeline Compression:ISO 9001 and IACS member society accreditation processes require 12-18 month validation cycles, delaying new yard market entry and limiting competitive response to demand surges.
- Legacy Vessel Documentation Gaps:Pre-digital-era construction records and modification histories impede accurate repair scoping for vessels over 25 years old, inflating contingency allowances and dispute frequency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ship Repair and Maintenance Services Market |
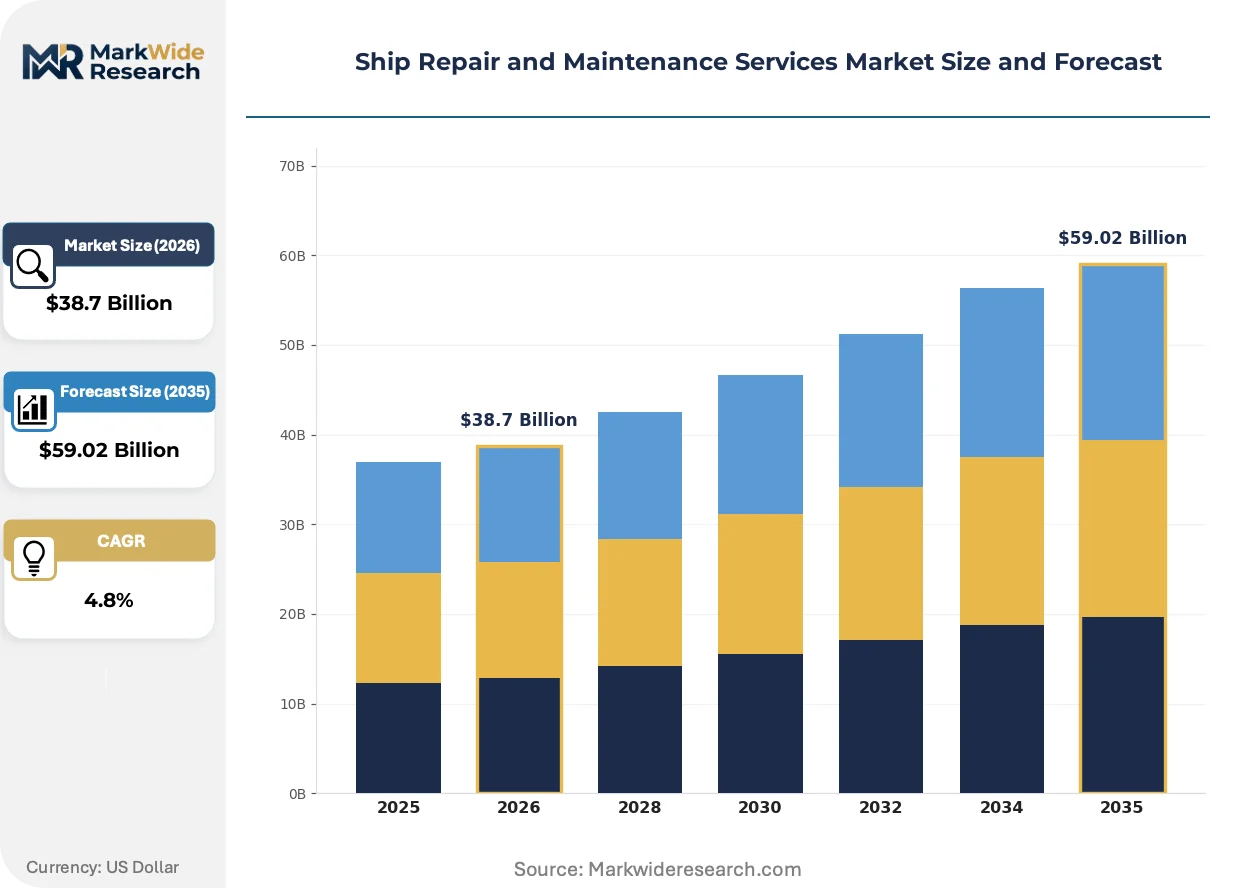
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dry Docking, Hull Maintenance, Engine Overhaul, Electrical Repairs End User: Shipping Companies, Naval Forces, Offshore Operators, Charter Services Technology: Manual Repair, Automated Systems, Inspection Technologies, Predictive Maintenance Inspection Type: Classification Surveys, Condition Surveys, Safety Checks, Routine Inspections |
| Companies Covered | Huntington Ingalls Industries, Cochin Shipyard Limited, Vigor Marine Group, Continental Maritime of San Diego, MHI Ship Repair & Services, BAE Systems Ship Repair, Fincantieri, Colonna's Shipyard, General Dynamics NASSCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ship Repair and Maintenance Services Market Strategic Shifts & Innovations
Digitalization of vessel condition assessment and regulatory compliance documentation is restructuring how shipyards qualify repair scope, price contracts, and execute work packages across global port networks.
Robotic hull cleaning and propeller polishing systems are supplanting manual diver-based maintenance for in-water operations. Offshore operators and cruise lines are deploying these systems at 40-60 day intervals between statutory dry-dockings. This technology is compressing the addressable market for traditional underwater service contractors while expanding recurring revenue streams for equipment OEMs.
The European Union's Green Deal and FuelEU Maritime regulations are mandating progressive carbon intensity reductions for vessels calling at EU ports. Shipowners must now schedule engine retrofits and alternative fuel system installations during already-mandated dry-docking windows. Container lines and ro-ro operators with dense EU port rotations are accelerating methanol-ready engine contracts to secure yard slots.
Condition-based service agreements are displacing fixed-price repair contracts among major tanker and bulker fleets. Shipowners now compensate yards based on achieved vessel performance improvements rather than labor hours consumed. This model is most visible in Singapore and Rotterdam, where integrated ship management groups negotiate multi-vessel framework agreements with outcome-linked payment terms.
Ship Repair and Maintenance Services Market Segmentation
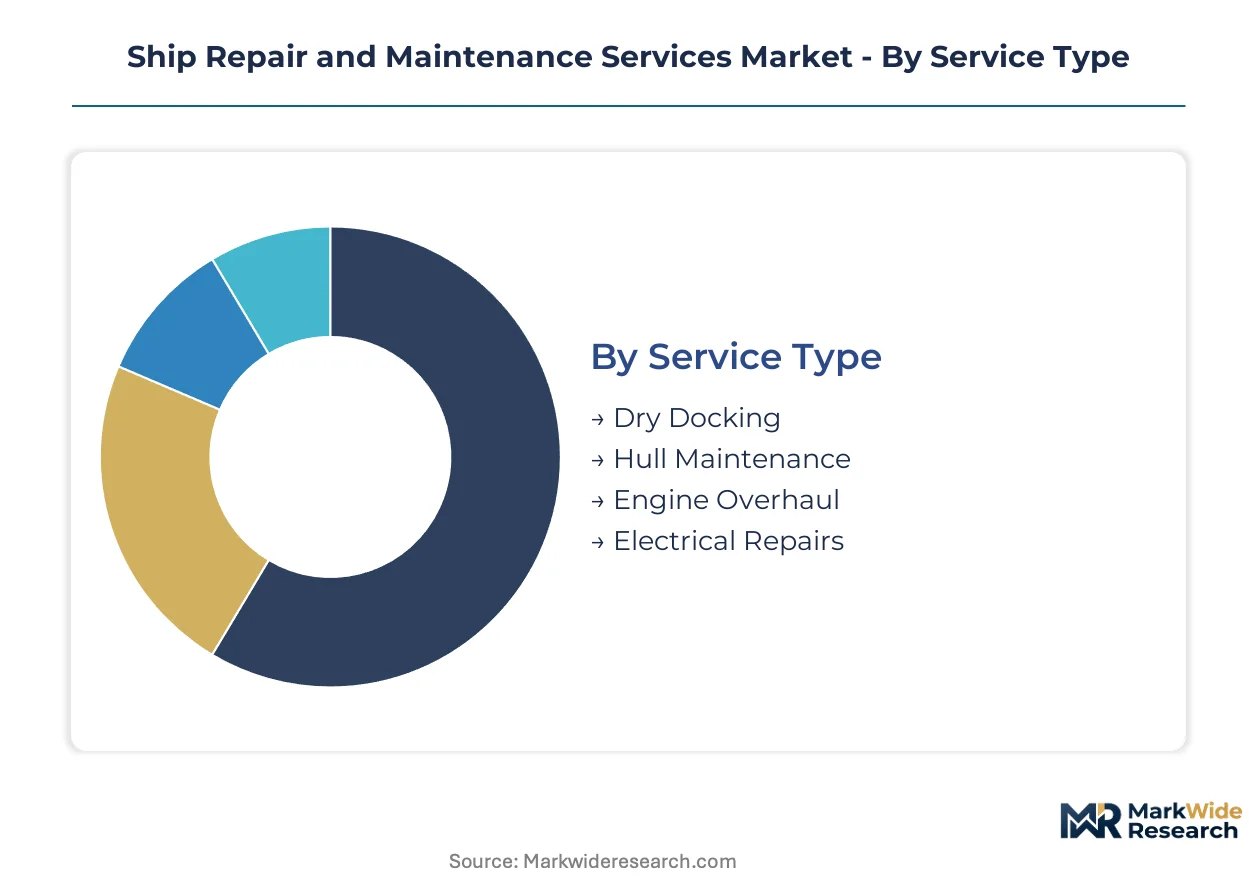
Ship repair and maintenance services fragment across service capabilities, customer risk profiles, and technology intensity. Segmentation reveals where pricing power concentrates and which capability investments yield competitive separation.
Service Type:
Dry docking commands premium rates in East Asian clusters where Singapore and South Korean yards serve export-led demand, while hull maintenance and electrical repairs sustain localized coastal operations.
- Dry Docking:Comprehensive vessel haul-out operations encompassing bottom inspection, steel renewal, and coating application in controlled environments. Singapore's Sembcorp Marine and South Korea's DSME anchor regional capacity; IMO carbon regulations compress scheduling cycles and expand bundled retrofit scopes.
- Hull Maintenance:Steel plate replacement, structural reinforcement, and corrosion management governed by classification society thickness standards. Demand concentrates among aging bulk carrier fleets operating under Marshall Islands and Liberian flags; coating specification upgrades now dominate scope negotiations.
- Engine Overhaul:Diesel and dual-fuel propulsion system restoration performed in deepwater facilities with heavy-lift capacity.
- Electrical Repairs:Switchboard modernization, automation system integration, and cable replacement for vessels upgrading to shore-power compatibility.
Dry docking holds the largest share; momentum sits with engine overhaul as alternative fuel retrofits accelerate.
End User:
Customer type determines contract structure, with naval forces locking in multi-year sustainment agreements while commercial operators negotiate spot-market availability.
- Shipping Companies:Container lines, tanker operators, and dry bulk owners purchasing statutory maintenance to preserve class certification and charter eligibility. Cost pressure from freight rate volatility squeezes margin; integrated ship managers in Rotterdam and Singapore consolidate procurement through framework agreements.
- Naval Forces:Nuclear and conventional military vessel refit programs requiring security-cleared facilities and specialized technical labor. Huntington Ingalls Industries sustains US Navy nuclear submarine maintenance; Cochin Shipyard Limited executes India's indigenous carrier programs under Ministry of Defence contracts.
- Offshore Operators:Oil and gas platform supply vessels and floating production units demanding minimized downtime through condition-based scheduling.
- Charter Services:Cruise lines and ferry operators with seasonal maintenance windows and passenger-safety compliance priorities.
Shipping companies generate the highest volume; naval forces capture the steepest expansion trajectory as Indo-Pacific fleet modernization accelerates.
Technology:
Technology intensity separates premium-priced integrated offerings from labor-dependent commodity services, with predictive systems capturing expanding offshore budgets.
- Manual Repair:Welder-dependent steelwork, pipefitting, and mechanical restoration performed by certified marine trades. Labor scarcity in Singapore and South Korea inflates wage costs; training pipeline gaps constrain capacity expansion.
- Automated Systems:Robotic hull cleaning, automated welding stations, and CNC plasma cutting reducing dry-docking duration. Cruise operators and container lines deploy in-water robotic systems at 40-60 day intervals between statutory dockings.
- Inspection Technologies:Laser scanning, ultrasonic thickness measurement, and drone-based structural survey accelerating damage assessment.
- Predictive Maintenance:Sensor networks and digital twin platforms enabling condition-based intervention before failure.
Manual repair retains volume dominance; predictive maintenance is gaining share fastest among offshore operators optimizing asset utilization.
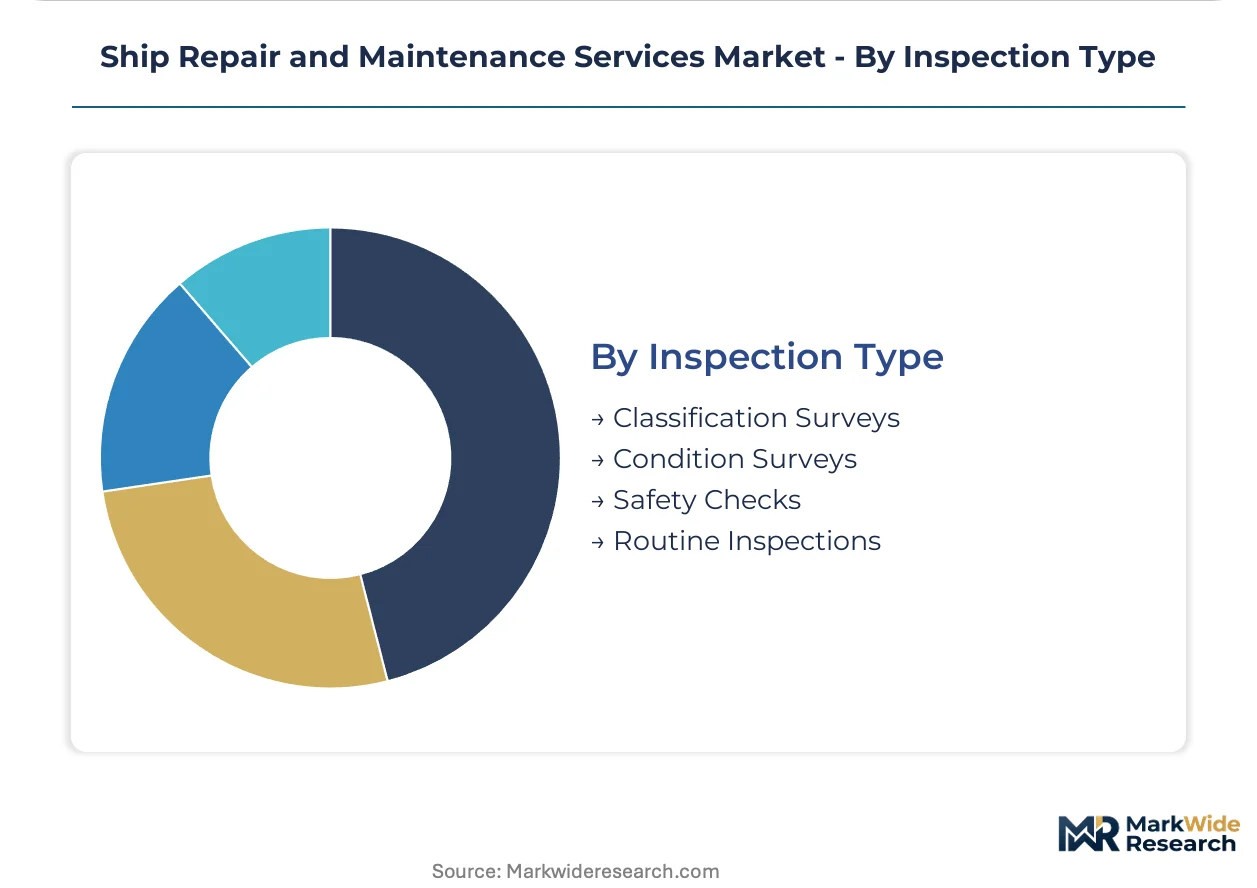
Inspection Type:
Inspection category determines yard selection criteria and repair scope authority, with classification surveys commanding highest compliance stakes.
- Classification Surveys:Statutory examinations by Lloyd's Register, DNV, or American Bureau of Shipping validating structural integrity and machinery condition for certificate renewal. Survey findings directly mandate repair scope; divergent rule interpretation across flag states extends quotation timelines.
- Condition Surveys:Buyer-commissioned pre-purchase or pre-charter assessments documenting vessel state for transaction risk allocation. Secondary market activity in Singapore and Hamburg drives demand; surveyor availability constrains peak-season throughput.
- Safety Checks:Port state control and flag state examinations verifying lifesaving equipment, fire suppression, and pollution prevention compliance.
- Routine Inspections:Operator-scheduled maintenance rounds and Planned Maintenance System verification.
Classification surveys represent the largest revenue category; condition surveys are climbing the fastest as secondhand vessel transactions recover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon intensity regulations and naval modernization programs are redistributing ship repair demand across port clusters with deepwater access and certified defense capacity.
United States
Nuclear submarine refit programs and Jones Act compliance sustain demand for security-cleared facilities. The US Navy's ship maintenance backlog drives multi-year sustainment contracts toward the East and Gulf Coasts. Norfolk, Virginia and San Diego, California anchor the largest naval repair concentrations.
Singapore
Sembcorp Marine and Keppel FELS execute statutory dry-docking for container lines and tanker operators under compressed IMO scheduling cycles. The Maritime and Port Authority of Singapore enforces environmental standards that accelerate hull coating upgrades. Tuas Yard expansion adds capacity for alternative fuel retrofits.
South Korea
DSME and Hyundai Heavy Industries leverage heavy-lift infrastructure for engine overhauls and dual-fuel conversions. The Ministry of Oceans and Fisheries supports yard digitalization through smart shipbuilding initiatives. Busan and Geoje Island concentrate defense and commercial repair capacity.
India
Cochin Shipyard Limited and Mazagon Dock execute indigenous carrier and submarine programs under Ministry of Defence contracts. The Make in India initiative prioritizes local content requirements for naval refits. Mumbai and Kochi host the primary defense-grade facilities.
United Kingdom
BAE Systems Ship Repair sustains Royal Navy surface fleet availability through Portsmouth facilities. The UK Shipbuilding Strategy commits public procurement toward domestic yard retention. Rosyth in Scotland and Devonport in Plymouth handle nuclear and conventional vessel maintenance.
Ship Repair and Maintenance Services Market Key Industry Players
Player mix skews toward defense-anchored full-service yards with nuclear certification and classification-accredited commercial operators. The market exhibits tiered concentration: a premium tier holds nuclear-capable naval contracts, a mid-tier captures statutory commercial dry-docking, and a regional tier serves localized coastal fleets. Strategic moves center on M&A for defense capability acquisition and greenfield capacity for alternative fuel retrofit demand.
Within the defense-anchored tier, Huntington Ingalls Industries, BAE Systems Ship Repair, and General Dynamics NASSCO occupy positions sustained by multi-year naval sustainment agreements. These entities exemplify the certification-intensive archetype where security clearance and nuclear-qualified labor create structural barriers to competitive entry.
| Leading Market Players |
|---|
| Huntington Ingalls Industries |
| Cochin Shipyard Limited |
| Vigor Marine Group |
| Continental Maritime of San Diego |
| MHI Ship Repair & Services |
| BAE Systems Ship Repair |
| Fincantieri |
| Colonna's Shipyard |
| General Dynamics NASSCO |
| Others |
Cost & Logistics Intelligence
Low-friction hull coating formulations replacing conventional anti-fouling paints are redrawing supplier geography toward South Korean and Japanese chemical producers while compressing margin structures for repair yards locked into legacy procurement contracts. This substitution dynamic simultaneously elevates input costs for European and North American operators and concentrates pricing power among yards with direct coating manufacturer partnerships.
Pricing Analysis
Certification level creates the primary spread across IACS-accredited full-service yards, ISO 9001-compliant mid-tier operators, and uncertified local repair shops. Project-based contracting dominates, with naval sustainment agreements commanding premium rates while commercial dry-docking faces cost compression from consolidated shipping company procurement. Price differentiation hinges on security clearance status and nuclear-qualified labor availability. Margins are tightening in the commercial hull maintenance segment as freight rate volatility intensifies buyer negotiation leverage. Integrated ship managers in Singapore and Rotterdam exhibit lowest price sensitivity due to outcome-linked payment structures, while independent bulk carrier operators show highest sensitivity to labor hour rates.
Supply Chain Analysis
Strategic stockpiling of marine-grade steel plate and specialized welding consumables prevails among defense-anchored yards facing nuclear-qualified labor scarcity, while commercial operators maintain just-in-time inventory exposed to delivery volatility. Supply concentrates in South Korea, Japan, and Germany for high-tensile steel plate, with China dominating standard-grade structural inputs. Raw material dependencies encompass nickel-alloy welding wire, copper-nickel piping systems, and low-VOC coating formulations. Single-source vulnerability runs through Japanese and South Korean coating chemical suppliers following consolidation in the marine chemicals sector. Distribution feeds from mill-direct arrangements for naval programs and through regional distributors for commercial yards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers and geographic capability gaps creates niche entry points as IMO carbon regulations force bundled retrofit demand that incumbent capacity cannot fully absorb.
For Market Incumbents: Compound defensive positioning through captive supply arrangements with coating chemical manufacturers and accelerated certification of secondary facilities in India. Huntington Ingalls Industries and BAE Systems Ship Repair demonstrate how nuclear-qualified labor pipelines and security-cleared infrastructure create structural barriers against emerging competitors. Capacity expansion in alternative fuel retrofit bays at existing deepwater sites captures engine overhaul demand migration. For New Entrants and Emerging Players: Predictive maintenance technology deployment represents the most penetrable service layer where incumbent yards under-invest in sensor networks and digital twin platforms. Offshore operators in the North Sea and Gulf of Mexico present concentrated demand for condition-based intervention contracts outside traditional dry-docking cycles. A go-to-market angle anchored to guaranteed uptime performance rather than labor-hour billing distinguishes new entrants from established pricing models. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors acquisition of mid-tier commercial yards with IACS accreditation and available waterfront expansion capacity. Long-term viability hinges on positioning for naval fleet modernization sustainment agreements and alternative fuel conversion demand. The signal to watch is Ministry of Defence contract award velocity in India and South Korea as indicators of defense-anchored capacity scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Fuel Retrofit Capacity Buildout | Methanol-ready engine bays at Singapore's Tuas Yard capture EU Green Deal-aligned container line demand. |
| Nuclear-Qualified Labor Pipeline Investment | Security-cleared technician training programs at US East Coast facilities sustain Huntington Ingalls Industries' submarine refit dominance. |
| Digital Twin Platform Integration | Hull laser scanning convergence with finite element analysis reduces dry-docking duration for offshore operators. |
| Strategic Coating Chemical Partnership | Direct manufacturer relationships insulate South Korean yards from marine-grade input price volatility. |
| Greenfield Yard Development | Deepwater facility construction in Sri Lanka and Oman addresses Indian Ocean Basin infrastructure underpenetration. |
Research Approach
A standing panel of shipyard operations directors, naval program managers at Ministry of Defence procurement divisions, classification society surveyors, and integrated ship management procurement heads provided ongoing calibration across primary interview cycles. Secondary validation drew from Lloyd's Register and DNV statutory survey filings, International Maritime Organization regulatory circulars, customs trade data on marine steel plate imports, and SEC 10-K disclosures from publicly traded repair yard operators. Bottom-up vessel dry-docking frequency modeling and top-down fleet age structure analysis were triangulated against capacity utilization rates at major port clusters.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across service type, end user risk profile, technology intensity, and inspection category, with additional dimensioning by flag-state regulatory cluster and vessel age cohort. CAGRs were derived from regression analysis of historical dry-docking cycle compression and projected alternative fuel retrofit adoption curves. Forecast inputs incorporated IMO Energy Efficiency Existing Ship Index compliance timelines and naval fleet modernization program announcements.
Underlying assumptions cover sustained enforcement of carbon intensity regulations and continued concentration of deepwater repair capacity in East Asian clusters, with deviation risk concentrated in trade policy shifts affecting steel plate tariffs and accelerated automation adoption compressing manual repair demand. Revision becomes warranted when classification society rule harmonization crosses thresholds that alter yard selection criteria or when alternative fuel technology standardization accelerates beyond current projection bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Integrated Bridge Systems (IBS) Market
Maritime Equipment
Tugboat Operation Market
Maritime Equipment
Maritime Communication System Market
Maritime Equipment
Liquefied Natural Gas (LNG) Carrier Market
Maritime Equipment
LNG Carrier Market
Maritime Equipment
Asia-Pacific Digital Shipyard Market
Maritime Equipment
Persian Gulf Offshore Support Vessels (OSV) Market
Maritime Equipment
Ship Breaking Market
Maritime Equipment
Barge Transportation Market
Maritime Equipment
Asia-Pacific Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Global Maritime Market
Maritime Equipment
China Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Integrated Marine Automation System Market
Maritime Equipment
North America Offshore Support Vessels Market
Maritime Equipment
North America Container Terminal Operations Market
Maritime Equipment
Isolated Danger Marks Beacon Buoys Market