
 Global Electric Light Commercial Vehicles Market | 2026-2036
Global Electric Light Commercial Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electric Light Commercial Vehicles Market Foresight
Powertrain electrification is fragmenting the traditional light commercial vehicle supply chain as dedicated EV platforms displace adapted internal combustion architectures. BYD Company Limited leverages its in-house battery cell production to control costs across cargo van and box truck variants. Ford Motor Company anchors its commercial strategy in the North American fleet segment with purpose-built electric chassis. Rivian Automotive Inc. differentiates through software-integrated delivery vans designed exclusively for e-commerce logistics partners.
Electric light commercial vehicles are zero-emission road transport vehicles with gross vehicle weight ratings typically below 3.5 tonnes, propelled by battery-electric or fuel-cell electric drivetrains and engineered for freight carriage, trade services, or passenger shuttle duties. Cargo vans dominate current production volumes due to their suitability for dense urban last-mile routes where regenerative braking and low-speed torque maximize operational efficiency. Solid-state battery chemistry represents the fastest-advancing technology segment, promising energy density gains that would extend flatbed truck range without payload compromise. Last-mile delivery applications attract the deepest margin pools as logistics providers prioritize total cost of ownership over upfront vehicle expenditure.
The EU Green Deal and F-Gas Regulation shape European product standards by accelerating diesel phase-out timelines and mandating refrigerant specifications for temperature-controlled vans. EPA tailpipe rules and NHTSA fuel economy standards in the United States force domestic manufacturers to electrify light truck portfolios or face fleet-average penalties. China's MIIT administers dual carbon goals through GB standards that dictate battery performance thresholds and vehicle efficiency metrics for domestic producers. Stakeholders must monitor how divergent certification timelines across Brussels, Washington, and Beijing fragment platform development budgets and supplier qualification requirements.
Market Dynamics
Powertrain electrification is forcing a complete reconstitution of light commercial vehicle manufacturing economics as dedicated EV platforms render adapted combustion architectures obsolete. Battery cell supply concentration and thermal management integration now determine competitive viability more than traditional stamping or assembly scale.
Growth Catalysts
- EU Green Deal diesel phase-out mandates:Fleet operators across Germany, France, and the Netherlands face binding zero-emission zone entry restrictions that compel vehicle replacement regardless of depreciation schedules.
- Last-mile logistics densification:E-commerce fulfillment networks prioritize electric cargo vans for urban route efficiency where regenerative braking and low-speed torque maximize daily cycle capacity.
- Solid-state battery chemistry maturation:Energy density improvements promise extended flatbed truck range without payload compromise, unlocking inter-urban freight applications previously reserved for diesel.
Market Restraints
- Lithium-ion cell supply concentration:Cathode material processing and cell manufacturing capacity clusters in China, creating geopolitical exposure for European and North American chassis assemblers.
- Charging infrastructure gap:Depot installation costs and grid connection timelines delay fleet electrification for small and mid-size operators lacking capital reserves.
- Thermal management complexity:Battery conditioning demands in temperature-extreme climates reduce effective range and accelerate cell degradation, limiting addressable markets.
Strategic Opportunities
- Software-defined vehicle platforms:Over-the-air update capability and fleet telematics integration enable recurring revenue streams from logistics providers managing multi-van operations.
- Vehicle-to-grid bidirectional charging:Energy storage arbitrage opportunities allow fleet operators to monetize idle battery capacity during peak demand periods.
- India commercial EV incentives:The PLI scheme for automotive manufacturing offers production-linked subsidies that reduce effective platform development costs for domestic and joint-venture producers.
Industry Challenges
- Battery engineering talent scarcity:Electrochemical systems expertise and thermal simulation capability command premium compensation, constraining development velocity for second-tier manufacturers.
- Multi-jurisdiction type approval fragmentation:Divergent crash-testing protocols and electromagnetic compatibility standards between Brussels, Washington, and Beijing extend platform validation timelines and inflate certification budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electric Light Commercial Vehicles Market |
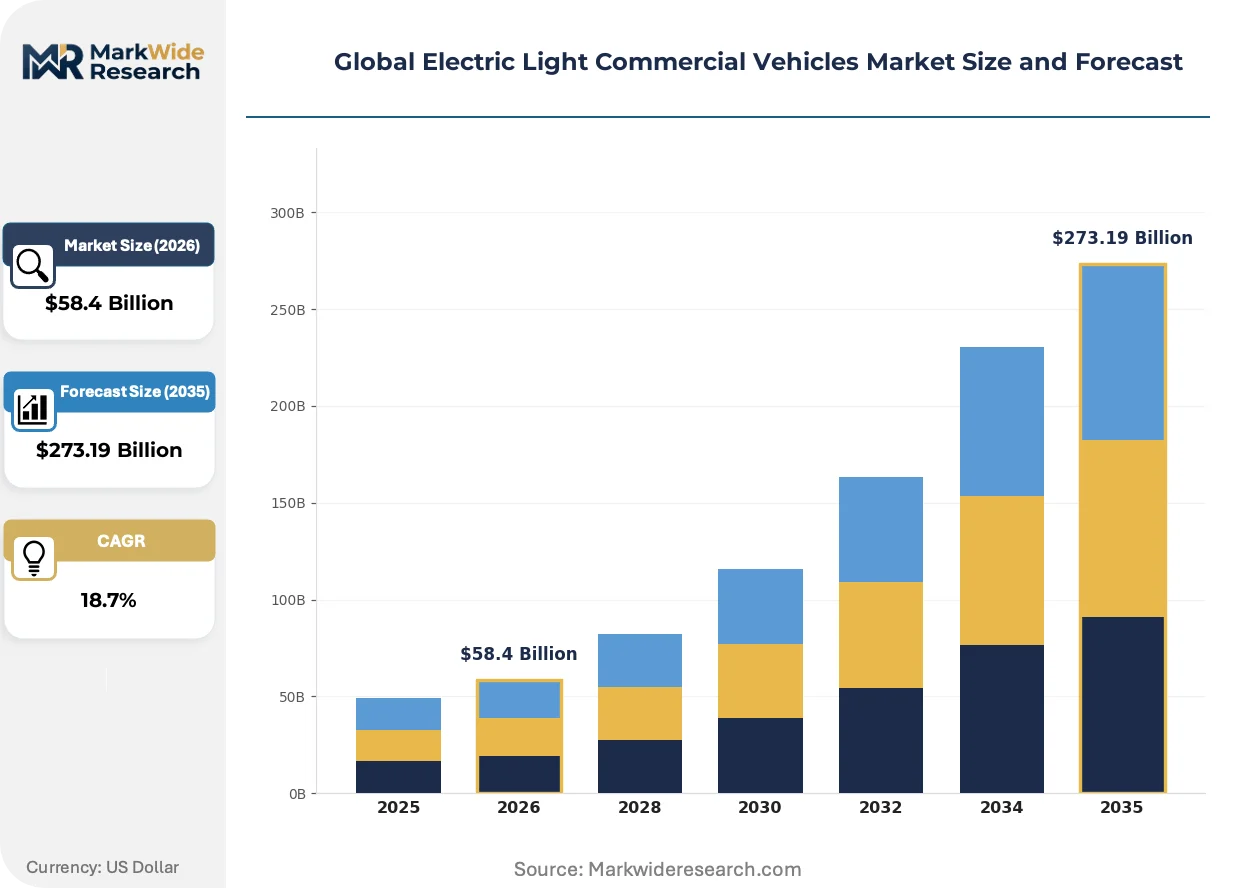
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $273.19 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Cargo Vans, Box Trucks, Flatbed Trucks, Refrigerated Vans, Passenger Vans Battery Technology: Lithium-Ion, Solid-State, Nickel-Metal Hydride, Lead-Acid, Zinc-Air Use Case: Last-Mile Delivery, Mobile Workshops, Postal Services, Food & Beverage Distribution, Service & Maintenance End User: Logistics Providers, Courier Firms, Municipal Services, Rental Agencies, Small Scale Entrepreneurs |
| Companies Covered | General Motors Company, SAIC Motor Corporation Limited, Volkswagen AG, Nissan Motor Co. Ltd., Daimler AG, Stellantis N.V., BYD Company Limited, Rivian Automotive Inc., Ford Motor Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electric Light Commercial Vehicles Market Shifts & Advancements
Telematics integration and predictive energy management are compressing total cost of ownership calculations and reshaping how fleet managers evaluate vehicle procurement. These developments favor integrated platform providers over component assemblers.
Digital twin simulation is digitizing vehicle development workflows by enabling virtual thermal and structural validation before physical prototyping. Tier 1 suppliers and captive OEM engineering teams deploy these tools to compress platform launch timelines from forty-eight to thirty-six months. The consequence is digitizing competitive advantage toward vertically integrated manufacturers with proprietary software stacks.
EPA tailpipe rules and NHTSA fuel economy standards are tightening fleet-average emissions requirements that force domestic manufacturers to electrify light truck portfolios or absorb penalty payments. The industrial consequence is accelerated R&D reallocation from internal combustion refinement to battery-electric architecture. Light-duty cargo van segments face the most immediate compliance pressure due to their high-volume, price-sensitive fleet customer base.
Logistics providers are consolidating vendor relationships and demanding outcome-based fleet performance guarantees rather than per-vehicle transactions. This procurement compression favors chassis manufacturers with captive service networks and real-time diagnostic capability. The shift is most visible in Germany and the United States where large e-commerce fulfillment operators negotiate multi-year total cost contracts spanning vehicles, charging infrastructure, and maintenance.
Global Electric Light Commercial Vehicles Market Segmentation
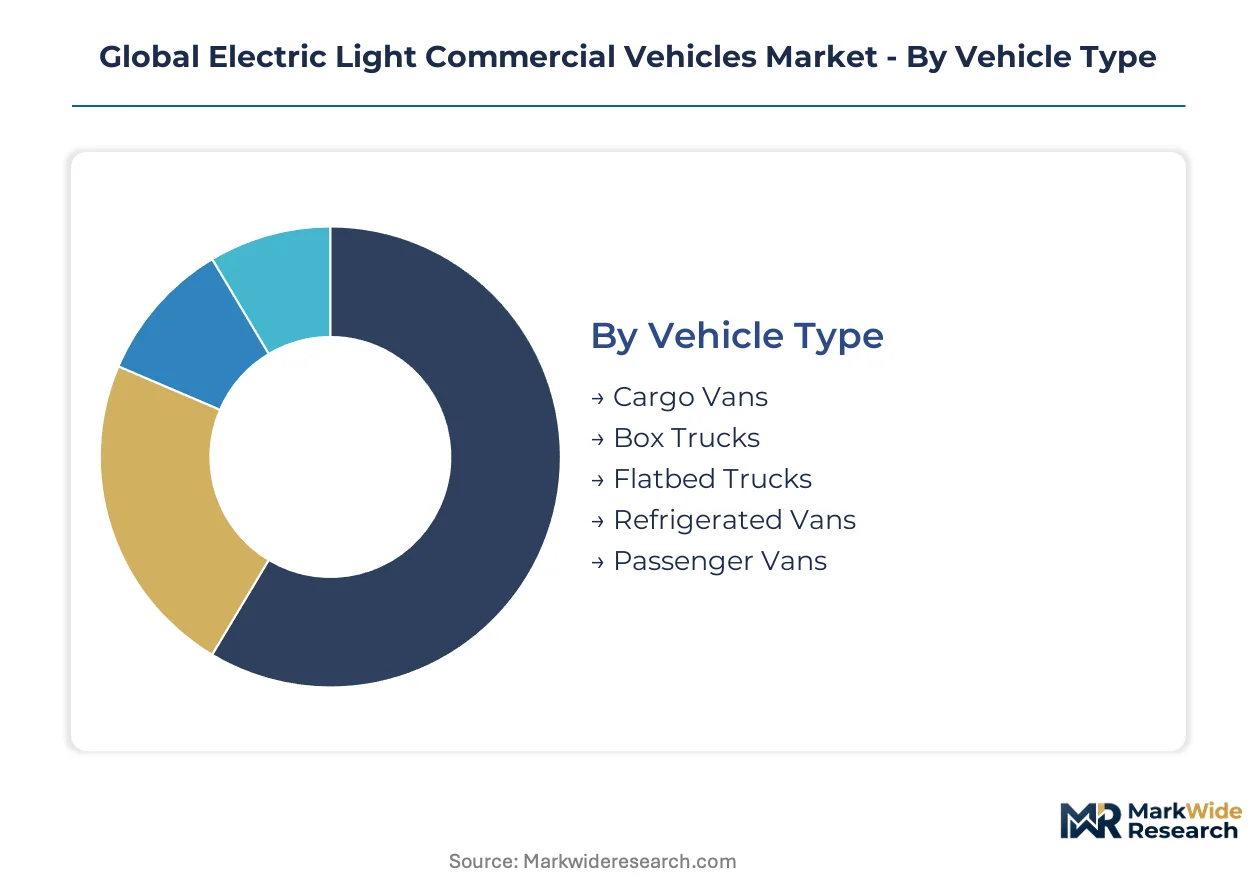
Segmentation in the electric light commercial vehicle market reveals how powertrain electrification fragments across duty cycles, battery chemistries, and fleet procurement models. Each dimension exposes distinct margin structures and regulatory exposure that determine competitive viability.
Vehicle Type:
Mature urban freight formats dominate current production, while emerging architectures target temperature-controlled and inter-urban applications.
- Cargo Vans:Enclosed-body vehicles with gross vehicle weight ratings below 3.5 tonnes engineered for parcel consolidation and dense urban route optimization. German and Dutch fleet operators deploy these for last-mile e-commerce fulfillment where regenerative braking and low-speed torque maximize daily cycle capacity. EU Green Deal zero-emission zone mandates in Berlin, Amsterdam, and Paris accelerate diesel replacement regardless of depreciation schedules.
- Box Trucks:Rigid chassis with enclosed cubic cargo compartments designed for palletized freight and intermediate distribution legs. Logistics providers in the United States concentrate order volumes here for suburban fulfillment center routes where payload density outweighs maneuverability constraints. NHTSA fuel economy standards impose fleet-average penalties that force electrification of this high-volume segment.
- Flatbed Trucks:Open-deck configurations for irregular dimensional freight and construction material transport.
- Refrigerated Vans:Temperature-controlled cargo compartments with integrated electric compressor systems for cold chain logistics.
- Passenger Vans:Multi-seat configurations for shuttle services, corporate transport, and municipal mobility contracts.
Cargo vans retain volume leadership; refrigerated vans hold the steepest expansion curve.
Battery Technology:
Cost tier differentiation separates established lithium-ion deployments from emerging solid-state architectures promising energy density breakthroughs.
- Lithium-Ion:Nickel-manganese-cobalt and lithium-iron-phosphate cell chemistries constituting the dominant installed base across current production. China's MIIT administers GB standards that dictate performance thresholds and efficiency metrics for domestic producers utilizing these cells. Cathode material processing concentration creates geopolitical exposure for European and North American chassis assemblers.
- Solid-State:Electrolyte-substituted architectures eliminating liquid components to enable higher energy density and improved thermal stability. South Korean and Japanese manufacturers lead pilot production for flatbed truck applications where extended range unlocks inter-urban freight previously reserved for diesel. Cell manufacturing scale-up timelines determine commercialization velocity.
- Nickel-Metal Hydride:Mature chemistry retained for cost-sensitive municipal service vehicles with moderate range requirements.
- Lead-Acid:Legacy technology confined to auxiliary power and low-speed commercial applications in price-constrained markets.
- Zinc-Air:Metal-air chemistry under development for theoretical energy density advantages in long-haul commercial configurations.
Lithium-ion retains volume leadership; solid-state holds the steepest expansion curve.
Use Case:
Application-specific duty cycles determine thermal management requirements and charging infrastructure deployment patterns.
- Last-Mile Delivery:Urban parcel distribution characterized by high-stop-frequency routes with regenerative braking recovery potential. E-commerce fulfillment networks in Germany and the United States prioritize electric cargo vans here for operational efficiency where total cost of ownership outweighs upfront vehicle expenditure. Logistics providers negotiate multi-year performance guarantees spanning vehicles, charging infrastructure, and maintenance.
- Mobile Workshops:Service vehicles equipped with onboard power tools and equipment requiring auxiliary electrical supply.
- Postal Services:Scheduled route operations with predictable daily mileage and depot-based overnight charging.
- Food & Beverage Distribution:Temperature-controlled transport with integrated refrigeration loads that reduce effective battery range.
- Service & Maintenance:Trade-specific vehicles for technician dispatch with variable route patterns and intermittent vehicle idle periods.
Last-mile delivery retains volume leadership; mobile workshops hold the steepest expansion curve.
End User:
Customer type segmentation exposes divergent procurement sophistication and capital availability across fleet scale categories.
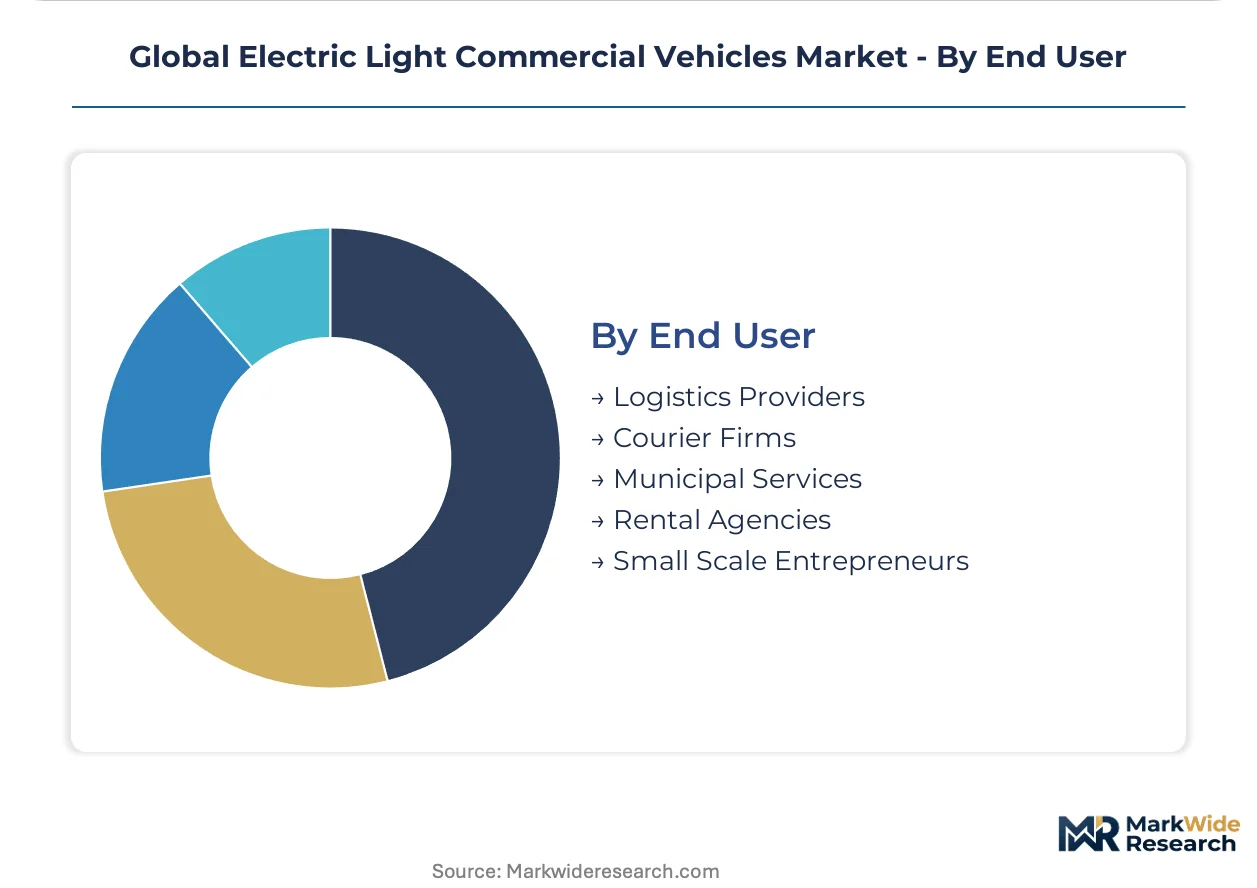
- Logistics Providers:Large-scale fleet operators managing multi-van operations with integrated telematics and predictive energy management systems. These stakeholders consolidate vendor relationships and demand outcome-based performance guarantees rather than per-vehicle transactions. Software-defined vehicle platforms with over-the-air update capability enable recurring revenue streams from this segment.
- Courier Firms:Express delivery specialists with high-utilization route density and time-definite service commitments.
- Municipal Services:Government fleet operators with regulated procurement timelines and sustainability mandates.
- Rental Agencies:Short-term vehicle providers with utilization optimization requirements and diverse customer training needs.
- Small Scale Entrepreneurs:Individual operators and micro-fleets with constrained capital reserves and limited charging infrastructure access.
Logistics providers retain volume leadership; small scale entrepreneurs hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Logistics providers and fleet operators in China, Germany, and the United States account for the heaviest order volumes, with municipal zero-emission mandates accelerating replacement cycles across dense urban corridors. National regulatory frameworks and industrial clustering patterns determine platform development priorities and supplier qualification requirements.
China
Domestic logistics giants and municipal fleet operators drive procurement of battery-electric cargo vans for last-mile delivery networks in Shanghai, Beijing, and Shenzhen. MIIT administers GB standards that dictate battery performance thresholds and vehicle efficiency metrics for domestic producers. The Yangtze River Delta manufacturing corridor concentrates cathode material processing and cell assembly capacity, creating captive supply advantages for chassis assemblers headquartered in the region.
Germany
Parcel consolidation specialists and trade service fleets dominate electric van adoption in Berlin, Hamburg, and the Rhine-Ruhr industrial belt. The EU Green Deal and KBA type-approval protocols enforce diesel phase-out timelines and zero-emission zone entry restrictions that compel vehicle replacement. Bavaria and Baden-Württemberg host engineering clusters developing thermal management systems for temperature-controlled electric freight applications.
United States
E-commerce fulfillment operators and utility fleet managers anchor demand for electric box trucks and cargo vans across California, Texas, and the Northeast Corridor. EPA tailpipe rules and NHTSA fuel economy standards impose fleet-average penalties that force electrification of light truck portfolios. Michigan and the Pacific Northwest concentrate battery pack assembly and electric drivetrain engineering talent pools.
India
Last-mile delivery startups and small-scale entrepreneurs in Maharashtra, Gujarat, and Karnataka represent emerging demand for cost-optimized electric commercial vehicles. The PLI scheme for automotive manufacturing offers production-linked subsidies that reduce effective platform development costs for domestic and joint-venture producers. The Delhi-NCR corridor and Bangalore-Tamil Nadu industrial belt attract component suppliers establishing localized battery assembly operations.
Japan
Postal services and corporate shuttle operators in Tokyo, Osaka, and Nagoya sustain demand for compact electric vans with moderate range requirements. METI directs industrial policy toward solid-state battery commercialization and vehicle-to-grid integration standards. The Kanto and Kansai regions concentrate electronics suppliers transitioning into power electronics and thermal management component production for electric commercial platforms.
Global Electric Light Commercial Vehicles Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around vertically integrated battery producers and legacy chassis manufacturers with captive fleet relationships. The competitive terrain splits between scale-driven platform developers and software-integrated specialists. Dominant moves include strategic partnerships for charging infrastructure deployment and backward integration into cell manufacturing to secure supply.
Within the integrated battery-tier, BYD Company Limited and SAIC Motor Corporation Limited exemplify manufacturers leveraging in-house cell production to control costs across cargo van and box truck variants. Ford Motor Company anchors the North American fleet segment with purpose-built electric chassis designed for high-volume logistics contracts. These three players occupy positions spanning the premium platform and mass-market fleet tiers, with competitive differentiation concentrating on thermal management integration and telematics capability rather than traditional stamping scale.
| Leading Market Players |
|---|
| General Motors Company |
| SAIC Motor Corporation Limited |
| Volkswagen AG |
| Nissan Motor Co. Ltd. |
| Daimler AG |
| Stellantis N.V. |
| BYD Company Limited |
| Rivian Automotive Inc. |
| Ford Motor Company |
| Others |
Supply & Pricing Matrix
The Rhine-Ruhr freight corridor exposes how cathode material concentration in China's Yangtze River Delta compresses chassis assembler margins while enabling three-tier pricing stratification across premium telematics-integrated, standard fleet-spec, and economy depot-only configurations.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate fleet procurement agreements. Three-tier pricing structure across premium, standard, and economy levels reflects thermal management sophistication and telematics bundling. Pricing pressure stems from cathode material volatility and logistics provider consolidation demanding outcome-based guarantees. Small-scale entrepreneurs exhibit highest price sensitivity; logistics providers with captive charging infrastructure show lowest.
Supply Chain Analysis
Export control regimes restricting semiconductor and battery technology flows fragment supplier qualification timelines across jurisdictions. Cell manufacturing concentrates in China, South Korea, and Japan; chassis assembly draws from Germany, the United States, and Mexico. Nickel, cobalt, and lithium hydroxide feed cathode production. Single-source vulnerability in solid-state electrolyte pilot lines threatens scale-up timelines. Distribution runs through OEM captive networks and specialized commercial vehicle dealers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward consolidated logistics providers negotiating multi-year total cost contracts, fragmenting procurement relationships previously managed through per-vehicle transactions.
For Market Incumbents: Build switching-cost moats through embedded telematics and charging infrastructure bundling. Secure captive cell supply through joint ventures with South Korean or Chinese producers. Defend against software-native entrants by accelerating over-the-air capability deployment.
For New Entrants and Emerging Players: Establish a beachhead in refrigerated van segments where thermal management complexity deters commodity competition. Target India's PLI-subsidized production corridor for cost-optimized platform development. Lead with vehicle-to-grid integration as a differentiated fleet revenue stream.
For Investors and Strategic Acquirers: Solid-state battery engineering boutiques with pilot production lines represent priority acquisition targets. Five-to-ten-year viability hinges on thermal management IP and OEM qualification timelines. Watch for MIIT GB standard revisions accelerating domestic Chinese consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cathode offtake contracts with Chinese or South Korean producers secure cost visibility for chassis assemblers. |
| Software-Defined Vehicle Investment | Over-the-air update architecture enables recurring revenue from logistics providers managing multi-van operations. |
| Charging Infrastructure Partnership | Depot installation and grid integration bundling differentiates fleet offerings in Germany and the United States. |
| Geographic Manufacturing Footprint | Localized assembly in India or Mexico reduces tariff exposure and logistics provider total cost of ownership. |
| Platform Standardization | Shared thermal management and battery pack architectures compress development timelines across cargo van and box truck variants. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet operations directors, and charging infrastructure developers; and secondary validation against vehicle production databases, MIIT GB standard filings, EPA certification records, and IHS Markit registration data. Bottom-up segment sizing triangulated with top-down macroeconomic drivers.
Forecast inputs span vehicle class, propulsion architecture, battery chemistry tier, and regional production cluster across the analysis window. CAGRs derive from segment-level adoption curves, regulatory mandate timelines, and fleet replacement cycle modeling. Solid-state battery commercialization trajectories and EU Green Deal enforcement intensity shape scenario boundaries.
Stress conditions across lithium price volatility, charging infrastructure deployment rates, and zero-emission zone expansion timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions documented in the segmentation framework. Material shifts in export control regime stringency or solid-state cell manufacturing yields would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Nordic E-Bike Market
Electric Vehicles
Asia-Pacific Electric Vehicle Market
Electric Vehicles
ASEAN Countries Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
UK Electric Vehicle Market
Electric Vehicles
Electric Vehicle (EV) Battery Housing Market
Electric Vehicles
Electric Three Wheeler Market
Electric Vehicles
Automotive Intelligent Battery Sensor Market
Electric Vehicles
Fuel Cell Electric Vehicle (FCEV) Market
Electric Vehicles
Electric Vehicle Cold Plates Market
Electric Vehicles
Scooter Market
Electric Vehicles
Vietnam E-Bike Market
Electric Vehicles
Mexico Automotive Electric Bus Market
Electric Vehicles
Global Electric All Wheel Drive (AWD) Market
Electric Vehicles
China Electric Vehicle Market
Electric Vehicles
Electric Vehicle Power Control Unit Market
Electric Vehicles
Electric Utility Vehicle Market