
 Electric Boat and Ship Market | 2026-2036
Electric Boat and Ship Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Boat and Ship Market Intelligence
Ferry procurement across European public transport authorities is decoupling from traditional diesel vessel contracts, fragmenting demand across municipal operators and private tourism concessionaires. Torqeedo anchors the outboard and inboard electric propulsion segment through its integrated battery-motor systems for leisure and light commercial craft. Brunswick Corporation leverages its parts distribution network to extend electric powertrain availability through dealer channels across North American marinas. Greenline specializes in hybrid-electric yacht architecture, occupying a distinctive position in the 35- to 65-foot cruising segment.
Electric boats and ships are watercraft propelled by electric motors drawing power from batteries, fuel cells, or hybrid configurations, with energy storage capacities typically ranging from 20 kWh for small leisure craft to multi-megawatt systems for commercial ferries. These vessels eliminate direct exhaust emissions during operation, serving regulatory compliance and noise-sensitive applications in harbors, inland waterways, and marine protected zones. Ferries dominate current order books because fixed routes and predictable duty cycles match battery range constraints while enabling shore-side charging infrastructure amortization. Fuel cells are gaining traction in cargo ship conceptual designs where battery energy density proves insufficient for transoceanic distances. Recreational buyers gravitate toward hybrid systems that preserve range flexibility during extended cruising.
The International Maritime Organization enforces progressively stricter carbon intensity indicators for vessels over 400 gross tonnes, compelling commercial operators to evaluate electric alternatives for short-sea shipping. The EU Green Deal channels infrastructure funding through the Connecting Europe Facility to port electrification projects in Denmark, the Netherlands, and Greece. Norway's NOx fund provides direct grants covering up to 80 percent of cost premiums for electric ferry conversions, establishing the most aggressive subsidy mechanism worldwide. Stakeholders must monitor how battery safety standards evolve under IEC 62619 and whether fuel cell certification timelines align with shipyard construction schedules for committed orders.
Market Dynamics
Maritime electrification momentum is accelerating as shore-side charging infrastructure amortization economics improve and battery energy density thresholds cross commercial viability for fixed-route operations. The collision between tightening emission mandates and vessel replacement cycles is forcing fleet operators toward capital-intensive propulsion transitions.
Growth Catalysts
- EU Green Deal infrastructure funding:The Connecting Europe Facility channels capital into port electrification projects across Denmark, the Netherlands, and Greece, reducing charging infrastructure deployment risk for ferry operators.
- Norway's NOx fund subsidy mechanism:Direct grants covering up to 80 percent of electric ferry conversion cost premiums establish the world's most aggressive fiscal support for maritime battery adoption.
- IMO carbon intensity indicators:Progressive enforcement for vessels over 400 gross tonnes compels commercial operators to evaluate electric alternatives for short-sea shipping routes.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack production relies on cathode material processing concentrated in East Asian supply chains, exposing European shipyards to input cost volatility and geopolitical disruption risk.
- Energy density ceiling for transoceanic cargo:Current lithium-ion configurations cannot achieve the multi-megawatt-hour capacities required for long-haul container shipping without prohibitive weight penalties.
- IEC 62619 certification timeline friction:Evolving safety standards for marine battery systems create regulatory uncertainty that misaligns with shipyard construction schedules for committed vessel orders.
Strategic Opportunities
- Fuel cell-battery hybrid architectures:Hydrogen fuel cells are gaining traction in cargo ship conceptual designs where pure battery energy density proves insufficient for extended-range operations.
- Greek island ferry electrification:Short inter-island routes with predictable duty cycles and established port infrastructure present underpenetrated deployment potential within EU-supported maritime corridors.
- Hybrid-electric recreational cruising:Extended-range flexibility requirements among yacht buyers create demand for dual-mode propulsion systems that preserve diesel backup for ocean passages.
Industry Challenges
- Marine electrical engineering talent scarcity:Shipyards face acute shortages of technicians qualified to integrate high-voltage battery systems with vessel safety management protocols.
- Fuel cell certification alignment gaps:Hydrogen propulsion approval timelines lag behind shipyard construction schedules, forcing project delays or technology downgrades for committed orders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Boat and Ship Market |
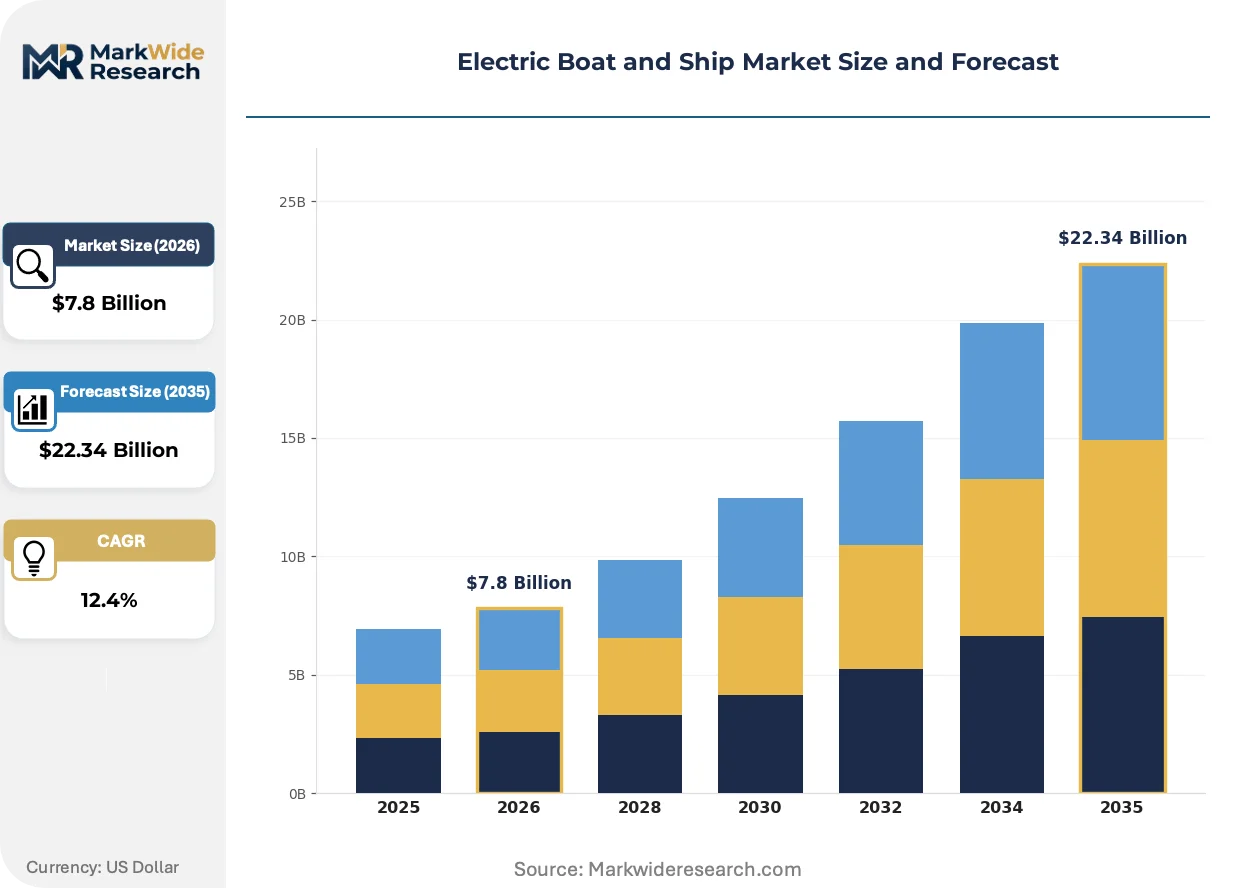
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $22.34 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Ferries, Yachts, Cargo Ships, Patrol Boats Power Source: Batteries, Fuel Cells, Hybrid Systems, Solar Power End User: Commercial, Government, Recreational, Research Deployment Model: Onshore, Offshore, Inland Waterways, Coastal |
| Companies Covered | VETUS, Incat Tasmania, Electric Boat, Azimut Benetti, Brunswick Corporation, Torqeedo, Greenline, Dufour Yachts, ePropulsion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Boat and Ship Market Strategic Shifts & Innovations
Propulsion system architecture is converging toward modular battery-fuel cell configurations that extend operational range while preserving zero-emission harbor operations. This technological pivot is reshaping shipyard design practices and supplier qualification criteria.
Silicon carbide power electronics are integrating into marine motor controllers to reduce switching losses and improve thermal efficiency in high-power electric propulsion systems. Ferry operators in Norway and Denmark are adopting these components to maximize battery range on fixed routes. The technology is integrating vessel automation systems with predictive energy management algorithms that optimize power draw against arrival schedules and charging windows.
The EU Green Deal's maritime corridor designation is channeling infrastructure investment toward prioritized short-sea shipping lanes connecting Baltic and North Sea ports. Ship operators on these routes gain preferential access to shore power and reduced port fee structures. Danish and Swedish ferry concessionaires are restructuring procurement contracts to mandate electric propulsion for renewal tenders, locking in technology commitments through 2040 service agreements.
Public transport authorities are fragmenting vessel procurement across municipal operators and private tourism concessionaires, displacing consolidated national fleet purchasing. Municipal harbor authorities in Bergen, Stavanger, and Tromsø now issue independent electric ferry tenders with customized route specifications. This pattern is concentrating most visibly in Norwegian fjord tourism clusters where local environmental permitting accelerates zero-emission mandates beyond national timelines.
Electric Boat and Ship Market Segmentation
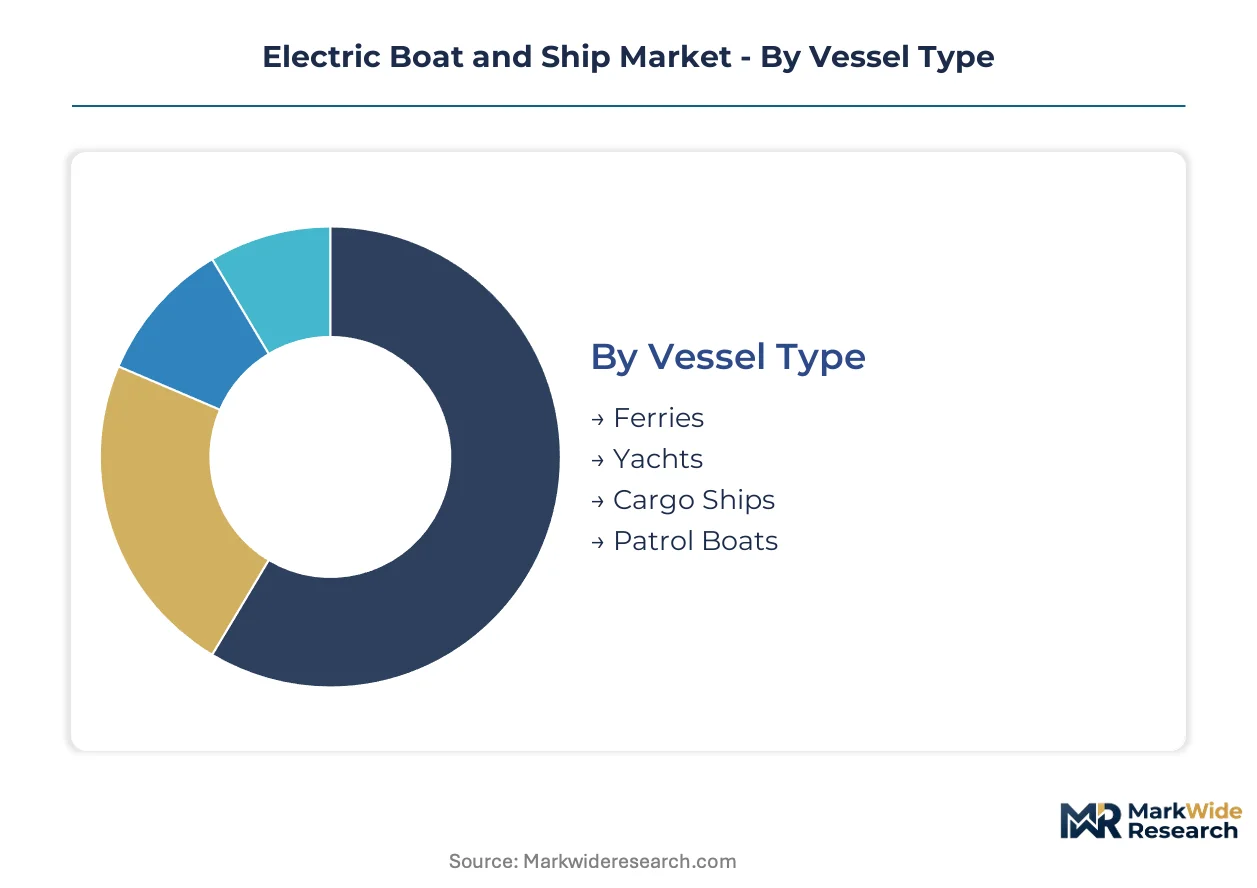
Segmentation in electric maritime propulsion reveals how battery energy density constraints and route predictability shape viable deployment models. Fixed-route operators prioritize different power architectures than ocean-going fleets, while regulatory pressure varies sharply across coastal, inland, and offshore operating zones.
Vessel Type:
Ferries dominate volume procurement through municipal tendering, while yachts command premium pricing through hybrid-electric customization.
- Ferries:Battery-electric configurations with 1-10 MWh storage capacity serve fixed routes under 50 nautical miles. Norwegian public transport authorities and Danish municipal operators concentrate current order books, driven by EU Green Deal infrastructure subsidies and shore-side charging amortization on predictable duty cycles.
- Yachts:Hybrid-electric architectures in the 35- to 65-foot segment preserve diesel range extension for ocean passages. Greenline and Northern European shipyards specialize in this configuration, responding to recreational buyers who demand zero-emission harbor maneuvering without sacrificing cruising autonomy.
- Cargo Ships:Pure battery propulsion remains confined to short-sea container feeders and coastal bulk carriers under 400 gross tonnes. Fuel cell-battery hybrids are gaining conceptual traction for transoceanic routes where lithium-ion energy density imposes prohibitive weight penalties.
- Patrol Boats:Coastal enforcement and harbor security craft utilize compact battery systems for silent operation during surveillance missions. Maritime police agencies in Norway and the Netherlands specify electric propulsion for noise-sensitive marine protected zone patrols.
Mature deployment sits with ferries. Newer deployment is concentrated in cargo ship fuel cell conceptual designs.
Power Source:
Cost tiering separates fully electric systems from hybrid architectures, with fuel cells occupying an emerging premium position for extended-range applications.
- Batteries:Lithium-ion NMC and LFP chemistries power the operating fleet, with pack capacities scaling from 20 kWh for leisure craft to 4 MWh for commuter ferries. Norwegian operators leverage 80 percent cost premium subsidies through the NOx fund, accelerating adoption beyond commercial viability thresholds in other geographies.
- Fuel Cells:Proton exchange membrane hydrogen systems are advancing from pilot demonstrations to commercial orders in cargo ship designs. Stakeholders face certification timeline misalignment with shipyard construction schedules, forcing technology downgrades for committed orders.
- Hybrid Systems:Dual-mode diesel-electric or battery-diesel configurations preserve operational flexibility for yacht owners and expedition cruise operators. This architecture dominates recreational segments where range anxiety and charging infrastructure gaps persist.
- Solar Power:Photovoltaic deck installations supplement auxiliary loads and extend battery range for small leisure craft and research vessels. Limited surface area constraints commercial scalability beyond demonstration projects in Mediterranean and Caribbean charter fleets.
Battery systems anchor current revenue. Fuel cells are gaining share fastest in cargo ship engineering studies.
End User:
Procurement authority fragmentation distinguishes commercial fleet operators from recreational buyers, with government mandates driving standardization.
- Commercial:Freight operators and ferry concessionaires evaluate total cost of ownership against IMO carbon intensity compliance deadlines. Danish and Swedish operators now mandate electric propulsion in renewal tenders through 2040 service agreements.
- Government:Naval, coast guard, and maritime police procurement prioritizes silent operation and emission compliance in territorial waters. Norway's defense procurement agency specifies battery-electric patrol craft for fjord and archipelago operations.
- Recreational:Individual buyers and charter fleet owners balance environmental preferences against infrastructure availability. Mediterranean marina electrification lags Nordic networks, constraining pure electric adoption in high-volume cruising grounds.
- Research:Oceanographic institutes specify low-noise electric propulsion for acoustic survey missions. University-operated vessels in the North Sea and Baltic prioritize zero-emission access to marine protected zones.
Government tenders established early standards. Commercial procurement is now scaling fastest through municipal ferry electrification.
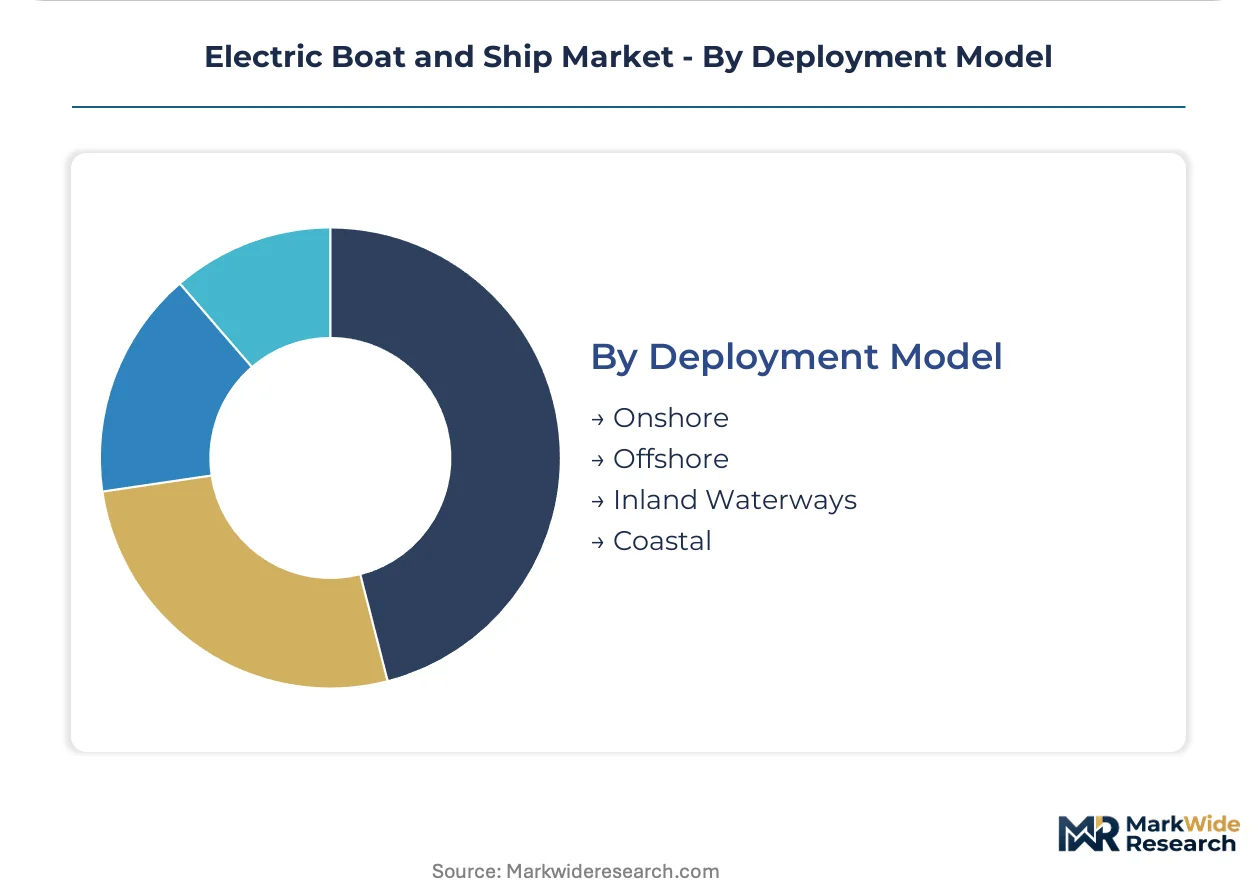
Deployment Model:
Geographic operating zone determines charging infrastructure feasibility and regulatory pressure intensity.
- Onshore:Harbor-based vessels including tugs, pilot boats, and port service craft utilize continuous shore power connection. Port authorities in Rotterdam and Antwerp mandate electrification for harbor fleet renewal under EU Green Deal corridor designations.
- Offshore:Platform supply vessels and wind farm service craft face severe battery range constraints in North Sea operations. Hybrid diesel-electric systems dominate pending fuel cell certification for extended offshore endurance.
- Inland Waterways:River barges and canal boats operate on predictable routes with established shore power infrastructure. Dutch and German Rhine fleet operators evaluate battery conversion against draft and cargo capacity trade-offs.
- Coastal:Short-sea shipping and inter-island ferry routes match battery range capabilities with shore-side charging at both termini. Greek island clusters present underpenetrated potential within EU-supported maritime corridors.
Inland waterway deployment matured earliest through European canal networks. Coastal routes are expanding fastest through Nordic and Mediterranean ferry electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium-ion cell processing capacity in East Asia anchors battery pack supply for electric vessel builders, while Nordic coastal infrastructure and Mediterranean tourism routes concentrate deployment demand.
Norway
Fjord tourism operators and municipal ferry authorities drive vessel procurement at the world's densest concentration of battery-electric operations. The NOx fund delivers grants covering up to 80 percent of electric ferry conversion cost premiums, establishing the most aggressive subsidy mechanism globally. Bergen, Stavanger, and Tromsø harbor authorities now issue independent tenders with route-specific zero-emission mandates that accelerate beyond national timelines.
Denmark
Municipal ferry concessionaires and short-sea shipping operators evaluate battery propulsion against fixed-route economics. The EU Green Deal's Connecting Europe Facility channels infrastructure capital into port electrification projects across Danish terminals. Copenhagen and Aarhus ferry operators restructure procurement contracts to mandate electric propulsion through 2040 service agreements, locking in technology commitments.
Netherlands
Rhine fleet operators and port service authorities confront draft and cargo capacity trade-offs in inland waterway battery conversions. Rotterdam and Antwerp port authorities mandate electrification for harbor fleet renewal under EU Green Deal corridor designations. Dutch shipyards specialize in modular battery integration for river barges operating predictable routes with established shore power infrastructure.
Greece
Island ferry operators and coastal tourism fleets present underpenetrated deployment potential for short inter-island routes. EU-supported maritime corridors prioritize infrastructure investment connecting Aegean and Ionian port clusters. Piraeus and island harbor authorities evaluate shore-side charging amortization against diesel replacement economics for established ferry termini.
United States
Recreational boat builders and marina operators extend electric powertrain availability through established dealer networks. The EPA enforces emission standards for marine engines that tighten compliance pressure on coastal vessel operators. Pacific Northwest and Northeast coastal clusters concentrate early adoption among harbor service craft and tourism concessionaires.
Electric Boat and Ship Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue integrated battery-motor systems and hybrid-electric architectures. The market structures around three maturity tiers: legacy marine propulsion suppliers diversifying into electrification, pure-play electric motor specialists, and hybrid yacht builders. Consolidation pressure concentrates among European shipyards with established ferry relationships and Asian battery system integrators. Competitive moves center on strategic partnerships between vessel builders and cell suppliers, plus geographic expansion through port authority concession bidding.
Within the integrated propulsion tier, Torqeedo and ePropulsion represent pure-play specialists anchoring outboard and inboard electric motor supply for leisure and light commercial applications. Brunswick Corporation exemplifies legacy marine conglomerate diversification, leveraging parts distribution networks to extend electric powertrain reach through North American dealer channels. Greenline occupies a distinctive position among hybrid-electric yacht architects, specializing in dual-mode configurations that preserve diesel range extension for ocean passages.
| Leading Market Players |
|---|
| VETUS |
| Incat Tasmania |
| Electric Boat |
| Azimut Benetti |
| Brunswick Corporation |
| Torqeedo |
| Greenline |
| Dufour Yachts |
| ePropulsion |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's emission compliance deadlines gate both qualified battery system suppliers and premium-tier vessel pricing access, concentrating procurement leverage among shipyards with IEC 62619-certified integration capabilities. Buyers lacking shore-side charging infrastructure face cost premiums that compound across vessel lifetime, while subsidy-dependent operators in Norway capture price advantages through the NOx fund's 80 percent cost coverage mechanism.
Pricing Analysis
Volume procurement concentrates with municipal ferry authorities, while margin capture sits with hybrid-electric yacht builders serving discretionary buyers. Three-tier pricing structure across premium, standard, and economy levels separates fully electric ferries from hybrid configurations and conventional diesel retrofits. Price differentiation hinges on battery energy density certification and after-sales service bundling. Cost compression in standard-tier commuter ferries is intensifying because lithium-ion cell supply volatility transmits directly into pack pricing. Commercial fleet operators exhibit highest price sensitivity; luxury yacht buyers demonstrate lowest sensitivity due to environmental preference premiums.
Supply Chain Analysis
Domestic-content mandates in South Korea and Japan are reshaping sourcing patterns for European shipyards seeking cathode material supply security. Cell manufacturing concentrates in China, South Korea, and Japan, with pack assembly gravitating toward Nordic maritime clusters. Raw material dependencies center on lithium carbonate, nickel sulfate, and cobalt hydroxide refined through East Asian processing networks. Single-source vulnerability in cathode precursor supply exposes vessel builders to geopolitical disruption risk. Distribution runs through shipyard direct procurement contracts and Tier 1 marine system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery cell production capacity constraints prop pricing power for qualified system integrators, sustaining premium capture through the analysis window. Shipyards with captive cell supply agreements command procurement preference from risk-averse ferry operators.
For Market Incumbents: To counter emerging Asian battery system integrators, European shipyards should deepen backward integration into pack assembly and secure long-term offtake agreements with South Korean cathode suppliers. Certification investment in IEC 62619 marine battery safety standards creates switching costs that lock in municipal ferry procurement relationships. For New Entrants and Emerging Players: Begin with Greek island ferry routes where EU Green Deal corridor funding reduces infrastructure deployment risk and incumbent relationships remain underdeveloped. Target hybrid-electric retrofit services for Mediterranean charter fleets as the most penetrable segment. Pursue port authority concession partnerships rather than direct vessel sales to accelerate reference account accumulation. For Investors and Strategic Acquirers: Norwegian NOx fund disbursement acceleration is the leading indicator that subsidy-dependent demand is converting to structural procurement preference. Position for 5-10 year horizon viability through acquisition of marine electrical engineering specialists with high-voltage integration capabilities. Monitor fuel cell certification timeline alignment with shipyard construction schedules as the critical inflection signal for technology pivot risk.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Pack Capacity Expansion | Captures NOx fund subsidy flows in Norway and Denmark municipal tenders. |
| Fuel Cell Certification Investment | Aligns hydrogen propulsion timelines with IMO carbon intensity enforcement windows. |
| Shore-Side Charging Partnership | Locks in EU Green Deal infrastructure funding through Connecting Europe Facility channels. |
| Hybrid System Architecture R&D | Preserves range flexibility for yacht buyers in Mediterranean and Caribbean cruising grounds. |
| Marine Electrical Engineering Acquisition | Addresses acute technician scarcity constraining high-voltage vessel integration. |
Research Approach
Independent corroboration across ferry operator procurement directors, shipyard project managers, and port authority infrastructure planners underwrites the qualitative findings. Primary fieldwork with marine battery system integrators, maritime regulatory consultants, and EU funding program administrators combined with secondary validation from IMO emission enforcement documentation, EU Green Deal corridor investment disclosures, and Norwegian NOx fund disbursement records. Bottom-up vessel order book analysis triangulates against top-down maritime electrification spending projections.
Rate-of-change decomposition across vessel type, power source architecture, and geographic deployment zone structures the analytical framework over the projection horizon. Segmentation modeling incorporates ferry route predictability, battery energy density thresholds, and shore-side charging infrastructure maturity as industry-specific forecast inputs. CAGRs derive from installed base replacement cycles against regulatory compliance deadline clustering.
Underlying measurement precision varies by segment; Norwegian ferry procurement data carries tighter precision than emerging market conceptual designs. Forecasts reflect assumptions regarding subsidy continuity, certification timeline adherence, and cell supply chain stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Auxiliary Engine Market
Marine
Jack-Up Vessels Market
Marine
Marine Asset Integrity Services Market
Marine
Electric Outboard Engines Market
Marine
Offshore AUV and ROV Market
Marine
Electric Boat Market
Marine
Ship Rudders Market
Marine
Freighter Conversions Market
Marine
Marine Exhaust Systems Market
Marine
Tele-Operated Marine Drone Market
Marine
Passenger Vessel Propeller Market
Marine
Furnace Boats Market
Marine
Autonomous Ships Market
Marine
Marine Interiors Market
Marine
Dynamic Positioning System Market
Marine
Ballast Water Management Market